
 North America Photographic Services Market | 2026-2036
North America Photographic Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Photographic Services Market Outlook
A shortage of certified drone pilots is unwinding capacity constraints across aerial photography segments. Getty Images Holdings Inc. leverages its archival depth to dominate commercial licensing workflows. Shutterfly LLC anchors consumer-oriented portrait and event photography through integrated print fulfillment. Snappr Inc. competes on gig-economy speed, matching corporate clients with vetted photographers inside forty-eight hours.
Photographic services encompass image capture, post-production editing, and rights-managed licensing for commercial, editorial, and personal use, typically delivered through digital workflows with RAW file formats exceeding 25 megapixels for professional applications. Wedding photography and commercial photography generate the steadiest revenue streams, while drone and 360-degree technologies attract the fastest investment as real estate and e-commerce verticals demand immersive visual assets. Film photography persists as a premium niche, sustaining higher per-session margins among specialty portrait studios.
The FAA governs commercial drone operations through Part 107 certification, while Canada's Transport Aviation issues equivalent RPAS pilot credentials; both frameworks restrict altitude, airspace, and equipment standards. The U.S. Copyright Office and Canadian Intellectual Property Office shape licensing enforceability, directly affecting how Getty Images and Shutterstock structure rights agreements. Stakeholders must monitor how generative AI tools alter client expectations around image origination, customization speed, and per-asset pricing.
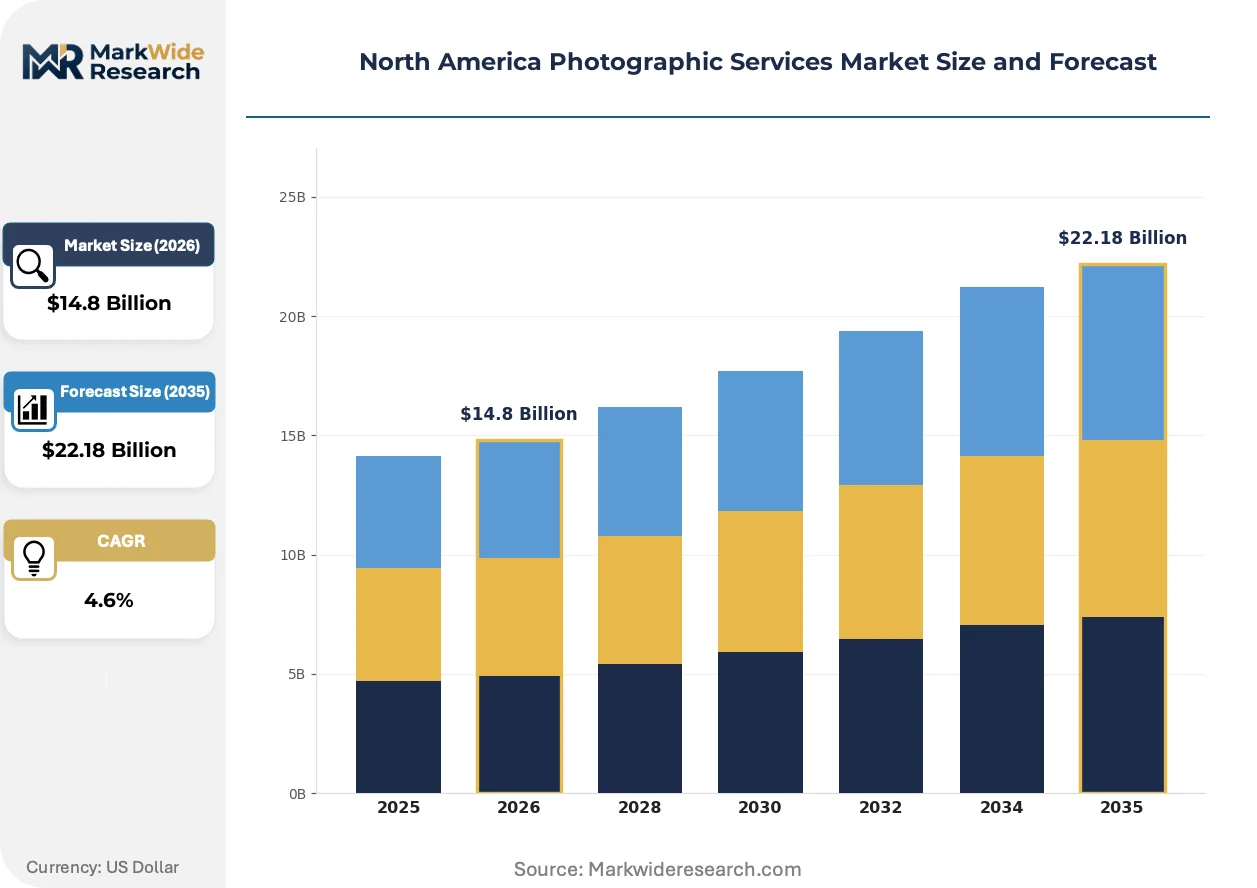
Market Dynamics
Visual content pipelines are fragmenting as generative AI tools compress production timelines from days to hours, forcing traditional photographic services to reposition around authenticity guarantees and licensed archival depth.
Growth Catalysts
- Part 107 Expansion:The FAA's evolving drone certification framework is unlocking commercial airspace access across the United States, enabling real estate developers and infrastructure inspectors to commission aerial capture at scale.
- E-commerce Visual Demands:Online retailers require immersive 360-degree product photography and lifestyle imagery, driving studio bookings for apparel and consumer electronics verticals.
- California Production Clustering:Entertainment and technology headquarters concentration around Los Angeles and San Francisco generates sustained demand for commercial photography, corporate headshots, and marketing campaign production.
Market Restraints
- Drone Pilot Scarcity:Certified RPAS operator shortages under Transport Canada's framework and FAA Part 107 bottlenecks limit aerial photography capacity expansion despite rising client inquiries.
- Equipment Depreciation Cycles:Professional camera bodies and lens systems require replacement every 36-48 months to maintain competitive resolution and low-light performance, straining independent operator cash flows.
- Generative Substitution:Text-to-image platforms from Midjourney and DALL-E variants are capturing budget share for conceptual advertising and stock imagery applications previously served by commissioned shoots.
Strategic Opportunities
- Canadian Prairie Markets:Agricultural drone imaging for crop monitoring and insurance documentation remains underpenetrated across Manitoba and Saskatchewan, offering first-mover positioning for certified operators.
- AI-Assisted Post-Production:Machine learning tools for automated culling, color grading, and background replacement are converging with traditional editing workflows, compressing delivery timelines and expanding per-photographer throughput.
- Heritage Digitization Mandates:Library and museum archive preservation initiatives across the United States and Canada are funding large-scale film negative and print digitization contracts.
Industry Challenges
- Copyright Enforcement Complexity:The U.S. Copyright Office and Canadian Intellectual Property Office registration processes create friction when pursuing infringement claims against unauthorized social media reposting, particularly for wedding and event photographers.
- Legacy File Format Migration:Studios maintaining archives spanning multiple decades face technical debt from proprietary RAW formats and obsolete storage media, requiring capital investment for accessibility preservation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Photographic Services Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wedding Photography, Commercial Photography, Portrait Photography, Event Photography Technology: Digital, Film, Drone, 360-Degree Industry Vertical: Advertising, Media, E-Commerce, Real Estate Customer Type: Individuals, Corporations, Non-profits, Government |
| Companies Covered | Shutterfly LLC, Lifetouch Inc., Getty Images Holdings Inc., Shutterstock Inc., Snappr Inc., Cherry Hill Programs, Bella Baby Photography, GradImages, Jostens Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Photographic Services Market Strategic Shifts
Computational photography and automated editing pipelines are compressing the value chain between capture and delivery, forcing service providers to differentiate through creative direction and client experience rather than technical execution alone.
Computational capture systems integrating multiple exposures, focus stacking, and real-time HDR processing are decomposing the traditional separation between in-camera technique and post-production correction. Real estate marketing departments and e-commerce catalog teams are adopting these tools to reduce per-image editing hours. The result is collapsing pricing power for basic retouching services as software automates what previously required skilled labor.
The FAA's Remote ID mandate for commercial drone operations is tightening airspace accountability across the United States, requiring broadcast equipment upgrades for existing Part 107 certificate holders. Transport Canada is advancing equivalent Remote Piloted Aircraft System traceability rules, creating compliance costs for cross-border operators. Aerial photography fleets serving construction and energy infrastructure are absorbing these capital requirements fastest, passing costs through to project budgets.
Enterprise marketing teams are unbundling photography procurement from bundled agency retainers, establishing direct relationships with specialized studios and gig-platform talent marketplaces. Consumer brands in apparel and food verticals are piloting this model to accelerate campaign turnaround. The shift is most visible in New York and Los Angeles, where in-house creative directors now source photographers through portfolio platforms rather than traditional representation.
North America Photographic Services Market Segmentation
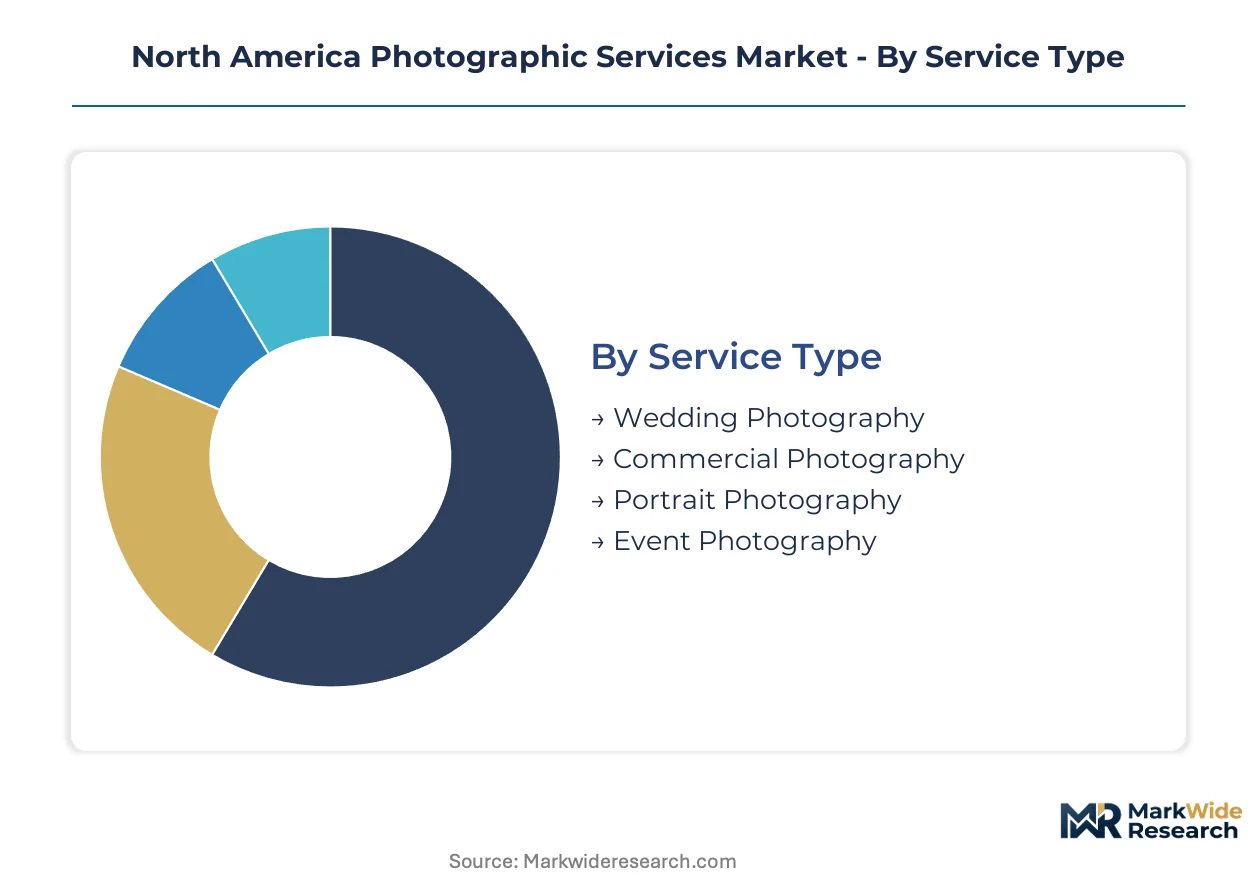
Photographic services fragment across four distinct dimensions, each revealing where pricing power concentrates and where commoditization pressures mount. Service type and technology splits determine margin structure, while vertical and customer segmentation governs contract duration and payment reliability.
Service Type:
Wedding and commercial photography command the widest margin spreads, with premium packages sustaining 60-70% gross margins against standardized event coverage.
- Wedding Photography:Multi-session packages spanning engagement shoots, ceremony coverage, and album production generate recurring referral networks. California's entertainment corridor and Texas's metropolitan clusters sustain the highest per-booking averages due to destination wedding demand and vendor ecosystem density.
- Commercial Photography:Campaign assets for advertising and corporate communications require rights-managed licensing frameworks. Los Angeles and New York studios dominate volume, though Toronto's production sector is capturing mid-market brand work through favorable exchange rates and provincial tax incentives.
- Portrait Photography:Headshot and family session work concentrates in suburban retail corridors with high foot traffic.
- Event Photography:Corporate gatherings and milestone celebrations operate on tighter margins with faster turnaround expectations.
The dominant share belongs to commercial photography, while wedding photography is closing the gap fastest through premium package tiering.
Technology:
Digital capture underpins volume economics, though specialized formats extract scarcity premiums in saturated markets.
- Digital:RAW workflows exceeding 25 megapixels dominate professional applications. E-commerce catalog teams and real estate marketers drive equipment refresh cycles, with California studios upgrading most aggressively to maintain competitive resolution benchmarks.
- Drone:FAA Part 107 certification requirements create supply bottlenecks that sustain pricing power. Infrastructure inspection and agricultural imaging across the Canadian Prairies and American Midwest are absorbing available pilot capacity fastest.
- Film:Analog capture persists as a premium niche with higher per-session margins.
- 360-Degree:Immersive capture formats attract investment from property technology platforms and virtual tour providers.
Digital capture holds the installed base advantage, though drone services are expanding most quickly through regulatory unlocking of commercial airspace.
Industry Vertical:
Advertising and e-commerce verticals concentrate procurement budgets, while real estate cycles drive volatile demand spikes.
- Advertising:Campaign production houses commission high-production-value shoots with extended post-production timelines. New York and Los Angeles agencies maintain direct studio relationships, bypassing traditional representation models.
- E-Commerce:Apparel and consumer electronics retailers require volume photography with rapid turnaround. Vancouver and Seattle technology corridors are piloting automated capture systems to compress per-image costs.
- Media:Editorial workflows prioritize speed over production value with compressed licensing terms.
- Real Estate:Property marketing demands fluctuate with transaction velocity and mortgage rate sensitivity.
Advertising commands the largest contract values, while e-commerce is gaining share fastest through catalog expansion and marketplace seller onboarding.
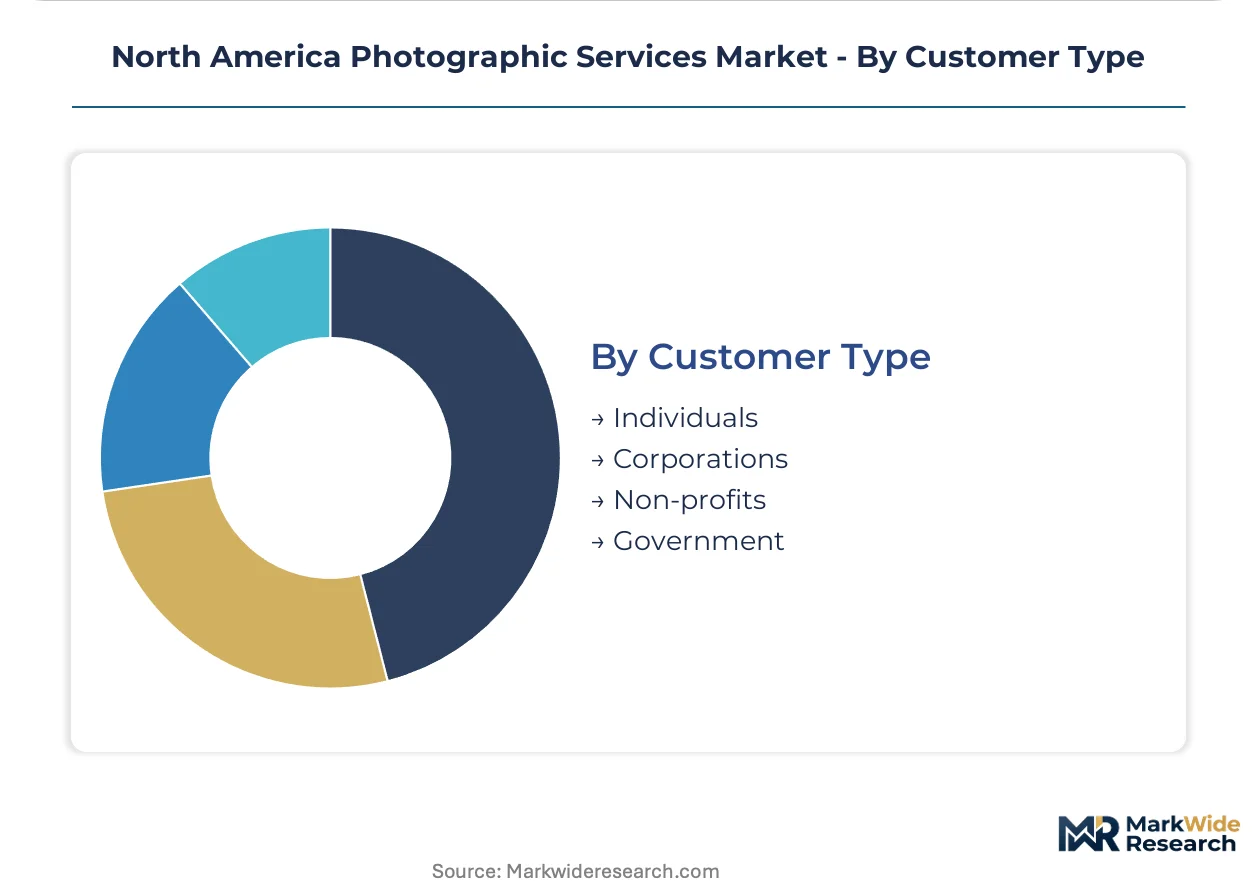
Customer Type:
Corporate accounts deliver payment reliability and repeat business, though individual consumers sustain higher per-transaction margins.
- Corporations:Marketing departments and human resources teams commission headshots, product photography, and campaign assets. Fortune 500 concentration in Illinois and Texas generates steady RFP volume with 30-60 day payment terms.
- Individuals:Personal milestone events and family portraiture accept premium pricing for emotional significance. Florida's retirement corridors and Arizona's resort communities sustain seasonal booking peaks.
- Non-profits:Fundraising documentation and annual report imagery operate on constrained budgets with mission-driven negotiation.
- Government:Municipal documentation and infrastructure imaging follow rigid procurement protocols with extended award timelines.
Corporate customers anchor revenue stability, while individual clients are climbing fastest through experience-economy spending prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California's entertainment corridor while Texas and Florida markets compete on volume throughput. The United States dominates absolute expenditure, though Canadian operators capture premium margins in agricultural imaging and heritage digitization. Mexico's border manufacturing zones and tourism corridors sustain growing commercial photography demand.
United States
Corporate marketing departments and entertainment studios drive sustained demand across Los Angeles, New York, and Chicago metropolitan clusters. FAA Part 107 certification requirements and Remote ID mandates shape aerial photography compliance costs. California's Silicon Valley and Hollywood production ecosystems generate the highest per-session commercial rates through integrated campaign production workflows.
Canada
Transport Canada's RPAS pilot certification framework restricts aerial photography capacity expansion despite rising agricultural and infrastructure inspection inquiries. Provincial tax incentives in Ontario and British Columbia attract mid-market brand production from US clients. Toronto's commercial studios and Vancouver's technology corridor concentrate the majority of national contract volume.
Mexico
Maquiladora manufacturing zones near Tijuana and Ciudad Juárez generate industrial documentation and corporate headshot demand from multinational subsidiaries. Mexico's federal consumer protection agency enforces advertising photography standards for cross-border e-commerce listings. Mexico City's metropolitan area and Cancún's tourism corridor anchor premium wedding and hospitality photography bookings.
Texas
Fortune 500 energy and technology headquarters in Houston and Dallas-Fort Worth sustain steady corporate photography RFP volume. The state's absence of income tax attracts independent photographers relocating from higher-cost coastal markets. Austin's technology startup density and San Antonio's military contracting ecosystem diversify demand beyond traditional oil and gas verticals.
Florida
Retirement corridor demographics and seasonal tourism sustain portrait and event photography booking peaks across Tampa, Orlando, and Miami metropolitan areas. Florida's homestead exemption and warm climate attract destination wedding planners and snowbird family portrait sessions. The state's film production incentive program, though reduced, continues drawing commercial shoots from northeastern markets.
North America Photographic Services Market Competitive Environment
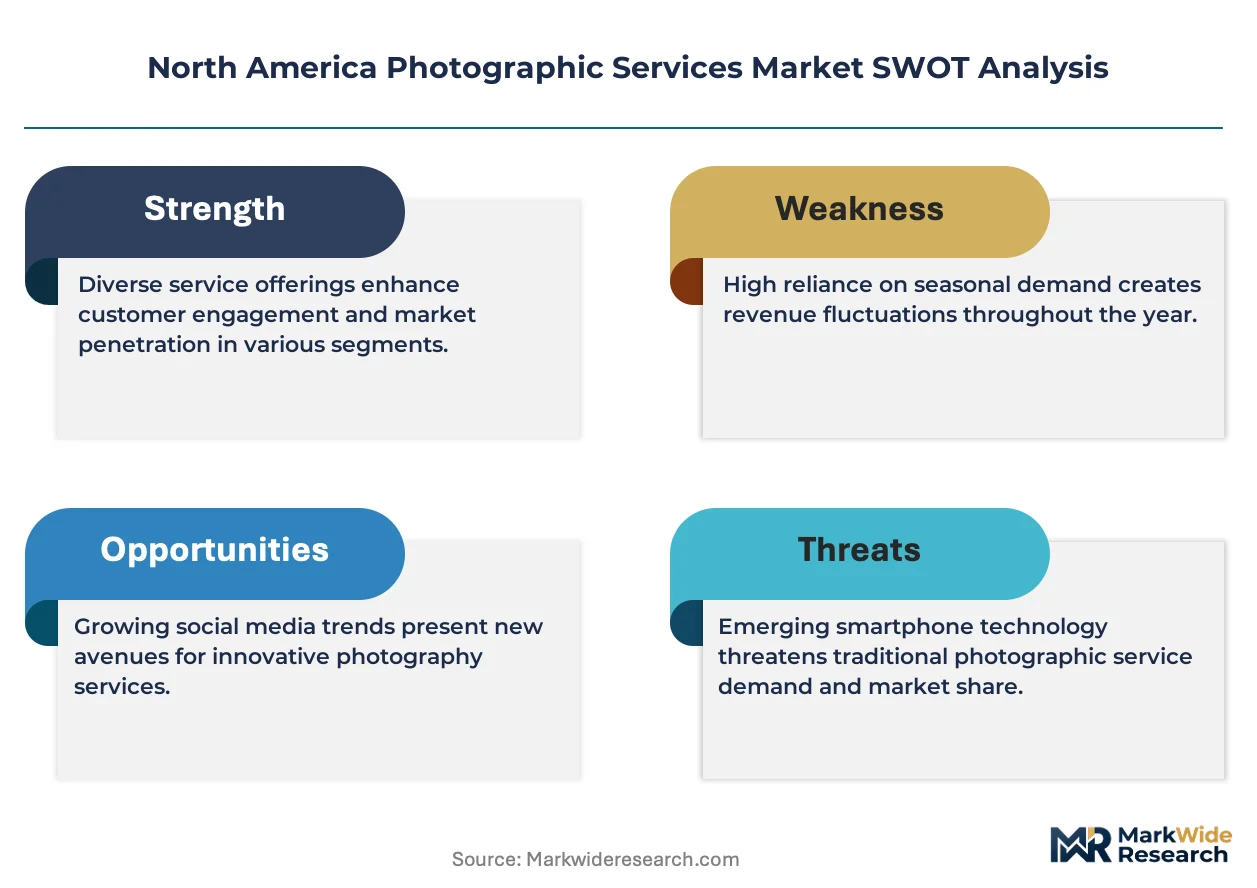
Technology leadership and cost leadership are held by different player archetypes across the North America Photographic Services Market. Archival depth and algorithmic distribution platforms define one strategic cluster, while gig-economy speed and integrated print fulfillment define another. The competitive terrain separates into three archetypes: licensed content aggregators, vertically integrated consumer studios, and on-demand marketplace platforms. Consolidation pressures favor acquisition of regional studios by national platforms, while technology licensing partnerships proliferate between software vendors and service providers.
Within the licensed content tier, Getty Images Holdings Inc. and Shutterstock Inc. occupy positions anchored by decades of archival accumulation and enterprise sales infrastructure. Shutterfly LLC exemplifies the vertically integrated consumer archetype through captive print fulfillment and seasonal portrait studio operations. Snappr Inc. represents the gig-economy velocity model, matching corporate procurement teams with vetted photographers through algorithmic dispatch systems.
| Leading Market Players |
|---|
| Shutterfly LLC |
| Lifetouch Inc. |
| Getty Images Holdings Inc. |
| Shutterstock Inc. |
| Snappr Inc. |
| Cherry Hill Programs |
| Bella Baby Photography |
| GradImages |
| Jostens Inc. |
| Others |
Value Chain & Pricing Dynamics
FAA Part 107 certification requirements gate both pilot qualification and aerial photography rate premiums simultaneously, creating a dual-track market where certified operators command project-based fees that uncertified competitors cannot access while equipment depreciation cycles compress margins across digital capture tiers.
Pricing Analysis
Configured-to-order pricing for custom commercial shoots sustains substantial premiums over standardized event packages. Three-tier pricing structure across premium, standard, and economy levels separates rights-managed campaign assets from rapid-turnaround editorial work and commodity stock licensing. Cost compression in basic retouching services is intensifying because computational photography tools automate exposure blending and background removal. Corporate marketing departments show least price sensitivity for integrated campaign production, while independent event photographers face acute margin pressure from gig-platform competition.
Supply Chain Analysis
Japan and Germany anchor precision optics manufacturing for professional lens systems, while Taiwan and South Korea dominate sensor fabrication for camera bodies. Professional equipment supply draws from specialized glass foundries, semiconductor fabs, and precision machining operations concentrated in East Asian industrial clusters. Single-source vulnerability persists for high-resolution CMOS sensors from Sony and Canon fabrication networks. Distribution runs through authorized dealer networks and direct-to-studio e-commerce channels, with regional service centers managing warranty repair workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America photographic services sit in early-cycle expansion as enterprise marketing teams unbundle agency retainers and establish direct procurement relationships with specialized studios, accelerating platform adoption for on-demand talent matching.
For Market Incumbents: Consolidate regional studio networks to capture enterprise RFP volume and defend against generative AI substitution in conceptual advertising workflows. Acquire certified drone operations in underserved agricultural corridors to lock in infrastructure inspection contracts. Prioritize archival depth investments that licensing platforms cannot replicate through synthetic image generation.
For New Entrants and Emerging Players: FAA Part 107 fast-track programs offer accelerated path to aerial photography rate premiums in real estate and energy verticals. Target Canadian Prairie agricultural imaging where Transport Canada RPAS bottlenecks limit incumbent capacity expansion. Pursue white-label partnerships with property technology platforms requiring immersive 360-degree capture for virtual tour deployments.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy portrait studio chains with captive print fulfillment infrastructure and seasonal booking density. Long-term viability hinges on differentiation through creative direction rather than technical execution as software automates post-production workflows. Monitor Remote ID mandate compliance costs as inflection indicator for aerial fleet operator consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Part 107 Certification Investment | FAA compliance unlocks commercial airspace access for real estate and infrastructure verticals. |
| AI-Assisted Post-Production Integration | Machine learning tools compress delivery timelines and expand per-photographer throughput capacity. |
| Archival Digitization Partnership | Museum and library mandates fund large-scale film negative preservation contracts across federal agencies. |
| Direct Enterprise Procurement Channel | Bypassing agency retainers accelerates campaign turnaround for apparel and food brand marketers. |
| Cross-Border RPAS Operator Network | Dual FAA and Transport Canada certification captures agricultural imaging demand across prairie provinces. |
Study Parameters
Desk research of equipment manufacturer technical specifications, FAA regulatory filings, and commercial licensing databases preceded structured interviews with studio operations directors, corporate procurement managers, certified drone pilots, and archival digitization contractors. Primary fieldwork across Los Angeles, Toronto, and New York metropolitan clusters validated secondary data from U.S. Copyright Office registration statistics and Canadian Intellectual Property Office licensing records. Bottom-up service provider revenue estimates triangulated against top-down corporate marketing expenditure surveys.
Variance decomposition across service type, technology platform, and customer segment dimensions shaped projection outputs over the forecast period. Modeled segmentation captured wedding, commercial, portrait, and event service categories alongside digital, drone, film, and 360-degree capture technologies. CAGRs derived from equipment refresh cycle analysis and regulatory unlocking timelines for commercial airspace access. Forecast inputs incorporated generative AI adoption curves and enterprise procurement unbundling velocity.
Underlying assumptions cover sustained FAA Part 107 certification growth and stable corporate marketing budget allocation, with deviation risk concentrated in generative AI substitution rates for stock imagery applications. Forecasts reflect these documented conditions with sensitivity to Remote ID mandate compliance cost pass-through and cross-border operator certification reciprocity developments. Recalibration cycles align with material shifts in FAA regulatory frameworks and enterprise sourcing platform adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Digital Media Switchers Market
Digital Media
Anime Merchandising Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Global Location-Based Entertainment Market
Digital Media
Manga Market
Digital Media
Global Streaming Media Device Market
Digital Media
Blockchain in Media and Entertainment Market
Digital Media
APAC Media and Entertainment Market
Digital Media
Photography Services Market
Digital Media
South Korea Webtoons Market
Digital Media
Sound Effects Services Market
Digital Media
Stock Music Software Market
Digital Media
3D Anaglyph Glasses Market
Digital Media
APAC DOOH Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
Playout Solutions Market