
 Digital String Encoder Market | 2026-2036
Digital String Encoder Market Size, Share, and Industry Trends Forecast 2026-2036
Digital String Encoder Market Outlook
Direct sales partnerships between encoder manufacturers and industrial automation integrators is reshaping how Digital String Encoder products reach end-users. HEIDENHAIN leverages its captive distribution network to dominate precision positioning applications in European machine tool markets. Sensata Technologies competes through backward integration into sensor packaging, securing cost advantages in high-volume automotive contracts. Texas Instruments anchors the component layer with integrated signal conditioning chips that reduce peripheral circuitry for encoder designers.
A digital string encoder converts linear or rotational displacement into digital pulse streams through photoelectric or magnetic sensing elements, typically achieving resolutions below one micrometer for closed-loop motion control systems. The device serves primarily to deliver position feedback to CNC machines, robotic arms, and automated guided vehicles with deterministic latency requirements. Integrated Systems command the largest revenue share as OEMs favor encoder-amplifier-controller bundles that slash commissioning time on factory floors. High-Speed Encoders represent the fastest-expanding product category, driven by semiconductor wafer handling equipment and lithium-ion battery winding lines that demand sub-microsecond response loops. Optical Encoding technology leads in absolute positioning accuracy, though Serial Communication interfaces are displacing parallel bus architectures across new industrial Ethernet deployments.
The IEC 61158 fieldbus standard and ISO 13849 machinery safety framework govern encoder interoperability and fault tolerance in automated systems across European and Asian manufacturing jurisdictions. The US OSHA machinery directive and China's GB/T industrial automation standards further shape product certification requirements for market access. Buyers must monitor how encoder vendors align their communication protocols with evolving Time-Sensitive Networking specifications to avoid stranded investments in legacy fieldbus infrastructure.
Market Dynamics
The IEC 61158 industrial Ethernet standard is compressing fieldbus protocol diversity, forcing encoder vendors to consolidate communication architectures around Time-Sensitive Networking while semiconductor fabs and battery winding lines demand sub-microsecond position feedback loops.
Growth Catalysts
- IEC 61158 Standardization:The industrial Ethernet protocol mandate across European and Asian manufacturing jurisdictions is eliminating proprietary fieldbus islands. Machine builders in Germany and Japan now specify interoperable digital interfaces as default.
- Semiconductor Wafer Handling:China's fabrication corridors are deploying high-speed encoders for vacuum chamber positioning systems. Sub-micron repeatability requirements in 300mm wafer transport are pulling optical encoding technology into cleanroom environments.
- Lithium-Ion Battery Manufacturing:Electrode winding lines in automotive assembly belts require closed-loop tension control with deterministic latency. Digital string encoders are replacing analog potentiometric sensors in calendering and slitting stations.
Market Restraints
- Rare Earth Magnet Supply Concentration:Magnetic sensing elements depend on neodymium and dysprosium processed primarily through Chinese supply chains. Geopolitical friction is injecting price volatility into encoder bill-of-materials.
- Optical Component Lead Times:Precision glass scales and LED sources face 26-week procurement cycles from specialized Japanese and German suppliers. OEMs cannot buffer inventory for custom stroke lengths.
- Functional Safety Certification Burden:ISO 13849 PLd/PLe compliance for machinery safety demands redundant channel architectures. Dual-encoder systems inflate unit costs by 40-60% versus single-channel alternatives.
Strategic Opportunities
- Time-Sensitive Networking Convergence:The IEEE 802.1AS time synchronization standard enables encoder-amplifier-controller bundles to share deterministic Ethernet backbones. Vendors can displace legacy fieldbus gateways with single-cable architectures.
- Automotive Assembly Belt Expansion:Electric vehicle powertrain lines in China's Yangtze River Delta and Germany's Baden-Württemberg region are retrofitting servo presses with absolute encoders for tool positioning.
- Integrated Signal Conditioning:Silicon vendors are embedding interpolation and error compensation into encoder interface chips. This convergence reduces peripheral component count for encoder designers targeting cost-sensitive robotic joint applications.
Industry Challenges
- Mechatronics Talent Scarcity:Commissioning encoder-amplifier-controller bundles requires fluency in both motion control theory and industrial Ethernet diagnostics. System integrators in Germany and Japan report 18-month hiring cycles for qualified application engineers.
- Legacy Fieldbus Stranded Assets:Machine retrofits must bridge SSI, BiSS, and proprietary protocols to TSN-compatible interfaces. End-users face write-downs on existing cabling infrastructure when upgrading to deterministic Ethernet.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital String Encoder Market |
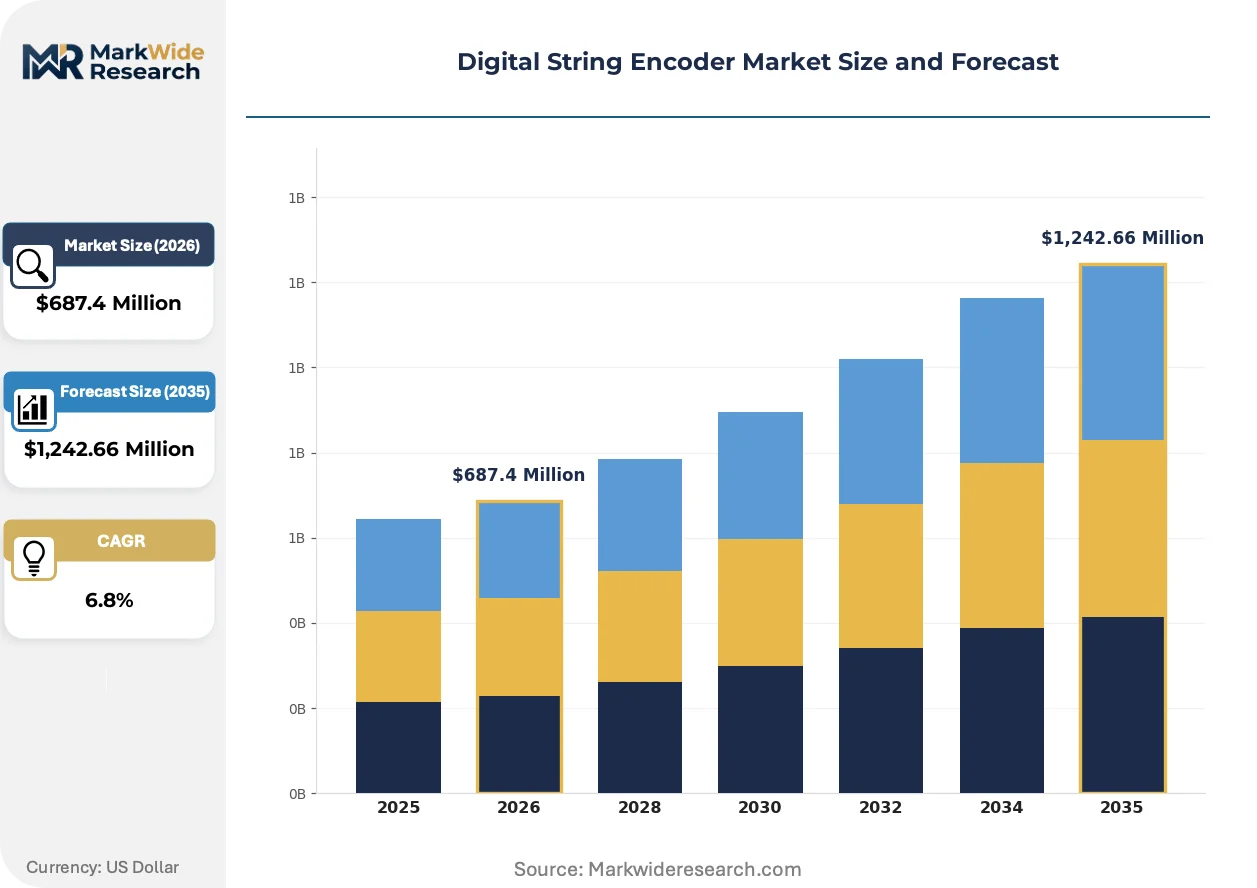
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,242.66 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Encoders, Integrated Systems, Software Solutions, High-Speed Encoders End User: Manufacturing, Telecommunications, Broadcasting, Automotive Technology: Digital Signal Processing, Analog Signal Processing, Optical Encoding, Serial Communication Functionality: Real-Time Encoding, Batch Encoding, Multi-Channel Encoding, Data Compression |
| Companies Covered | Sensata Technologies, HEIDENHAIN, Fortive (Dynapar), Renishaw plc, Mitutoyo Corporation, FRABA B.V., Texas Instruments, Analog Devices, Micro-Epsilon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital String Encoder Market Strategic Shifts
Photoelectric sensing architectures are yielding to magnetic and capacitive alternatives as semiconductor integration redefines encoder signal chains. Vendors are compressing form factors while embedding intelligence at the sensing edge.
Single-chip magnetic encoder solutions with integrated 24-bit interpolation are rendering obsolete discrete optical code disc assemblies in medium-precision positioning applications. Collaborative robot joint manufacturers in Germany are adopting these monolithic devices to shrink motor-encoder packages below 40mm diameter. The elimination of glass scales and precision alignment fixtures is collapsing encoder subsystem costs by half for 10-micron accuracy class applications.
The EU Machinery Regulation 2023/1230 is mandating digital product passports for safety-critical components including position feedback devices. Encoder vendors must now embed traceability data covering conflict minerals, carbon footprint, and end-of-life recyclability. European machine tool OEMs are prioritizing suppliers with pre-certified documentation packages to compress CE marking timelines for their own export shipments.
Automotive tier-one suppliers are unbundling encoder specification from captive amplifier-controller sourcing. Procurement teams at battery winding equipment builders now issue separate RFQs for sensing elements, signal conditioning electronics, and communication interfaces. This disaggregation is fragmenting vendor relationships in China's Jiangsu province, where integrators previously accepted bundled solutions from Japanese motion control specialists.
Digital String Encoder Market Segmentation
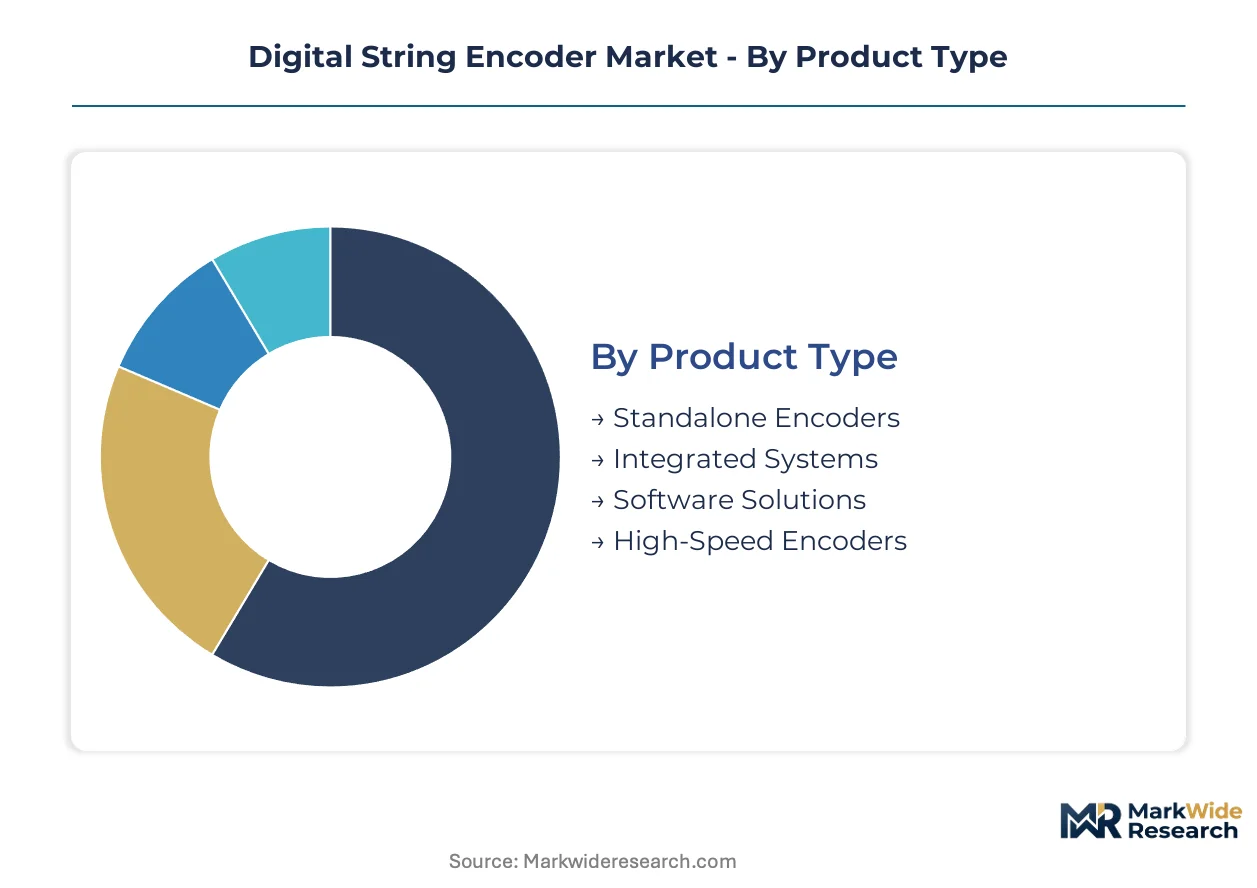
Digital string encoder procurement decisions pivot on four intersecting dimensions: product architecture, end-use environment, sensing technology, and operational functionality. Each axis carries distinct cost-performance tradeoffs that shape vendor selection across semiconductor fabrication, automotive assembly, and industrial automation corridors.
Product Type:
Use-case spectrum spans discrete sensing elements through complete motion subsystems, with integration depth determining commissioning complexity and total installed cost.
- Integrated Systems:Encoder-amplifier-controller bundles consolidate position feedback, signal conditioning, and motion control logic into factory-preconfigured assemblies. OEMs in Germany's machine tool sector favor these packages to compress commissioning timelines on CNC retrofit lines.
- High-Speed Encoders:Sub-microsecond response loops serve lithium-ion battery winding equipment and semiconductor wafer handling robots. China's Yangtze River Delta fabrication corridors are pulling these devices into cleanroom vacuum chamber positioning systems.
- Standalone Encoders:Discrete sensing heads with separate electronics enclosures suit legacy machine retrofits where amplifier-controller hardware remains serviceable.
- Software Solutions:Encoder configuration tools and diagnostic suites enable remote parameterization of distributed motion networks.
Established volume favors Integrated Systems; emerging adoption favors High-Speed Encoders.
End User:
Cost tier stratification separates capital-intensive precision manufacturing from price-sensitive volume applications.
- Manufacturing:CNC machine tools, robotic arms, and automated guided vehicles demand deterministic latency below one millisecond. Japanese automotive component suppliers specify redundant channel architectures to satisfy ISO 13849 machinery safety mandates.
- Automotive:Electric vehicle powertrain lines in Germany's Baden-Württemberg region retrofit servo presses with absolute encoders for tool positioning accuracy.
- Telecommunications:Antenna positioning systems and satellite tracking equipment require moderate precision at extended temperature ranges.
- Broadcasting:Camera robotics and motion control rigs prioritize smooth velocity profiling over absolute positioning accuracy.
Margin concentration sits with Manufacturing; volume scaling favors Automotive.
Technology:
Application requirements dictate sensing modality selection across photoelectric, magnetic, and electronic signal processing alternatives.
- Optical Encoding:Photoelectric architectures with glass scale interferometry achieve sub-micron resolution for semiconductor lithography stages. Japanese suppliers dominate precision glass scale fabrication, creating 26-week procurement bottlenecks for custom stroke lengths.
- Serial Communication:Industrial Ethernet interfaces displace parallel bus architectures as IEC 61158 standardization compresses fieldbus protocol diversity across European and Asian manufacturing jurisdictions.
- Digital Signal Processing:Integrated interpolation algorithms embed error compensation and noise filtering directly at the sensing edge.
- Analog Signal Processing:Legacy sine-cosine outputs persist in retrofit applications where controller hardware predates digital interface adoption.
Technology leadership resides with Optical Encoding; interface transition favors Serial Communication.
Functionality:
Operational mode selection reflects throughput requirements versus processing latency constraints in automated production environments.
- Real-Time Encoding:Continuous position streaming with deterministic latency serves closed-loop servo control in robotic joint applications. Collaborative robot manufacturers in Germany specify these devices for force-limited human-machine interaction.
- Multi-Channel Encoding:Synchronized feedback from multiple axes enables coordinated motion in gantry systems and parallel kinematic machines.
- Batch Encoding:Buffered position capture suits quality inspection stations where post-process analysis replaces immediate control response.
- Data Compression:Delta-encoding schemes reduce bandwidth requirements for long-stroke linear applications with incremental position reporting.
Performance premiums attach to Real-Time Encoding; architectural flexibility favors Multi-Channel Encoding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial policy incentives across Germany, China, Japan, and the United States are accelerating encoder deployment in precision manufacturing corridors. Subsidies for semiconductor fabrication and electric vehicle production are reshaping procurement patterns in each jurisdiction.
Germany
The EU Green Deal industrial transformation funding is channeling investment into Baden-Württemberg's machine tool sector. CE marking under the EU Machinery Regulation 2023/1230 mandates digital product passports for safety-critical components. Stuttgart-based OEMs are retrofitting servo presses with absolute encoders for tool positioning accuracy.
China
Dual carbon goals and domestic semiconductor self-sufficiency targets are driving encoder demand in Yangtze River Delta fabrication corridors. GB/T industrial automation standards govern product certification for market access. Shanghai and Suzhou cleanrooms are deploying high-speed encoders for 300mm wafer transport systems.
Japan
METI's semiconductor back-end equipment subsidy program is expanding encoder procurement for lithography stages. JIS standards and PMDA-equivalent industrial safety frameworks shape certification requirements. Nagoya automotive component suppliers specify redundant channel architectures to satisfy ISO 13849 machinery safety mandates.
United States
OSHA machinery directives and CHIPS Act semiconductor manufacturing incentives are converging on encoder specifications. The IRA clean energy tax credits are pulling encoders into battery winding equipment for domestic EV supply chains. Michigan and Texas automotive assembly belts are retrofitting calendering stations with closed-loop tension control systems.
South Korea
K-Semiconductor Belt subsidies under the national semiconductor strategy are accelerating encoder deployment in Pyeongtaek and Hwaseong fabrication complexes. MFDS-equivalent industrial safety regulations and KOSHA machinery standards govern fault-tolerant system architectures. Seoul Capital Area battery manufacturers are replacing analog potentiometric sensors in electrode winding lines.
Digital String Encoder Market Competitive Environment
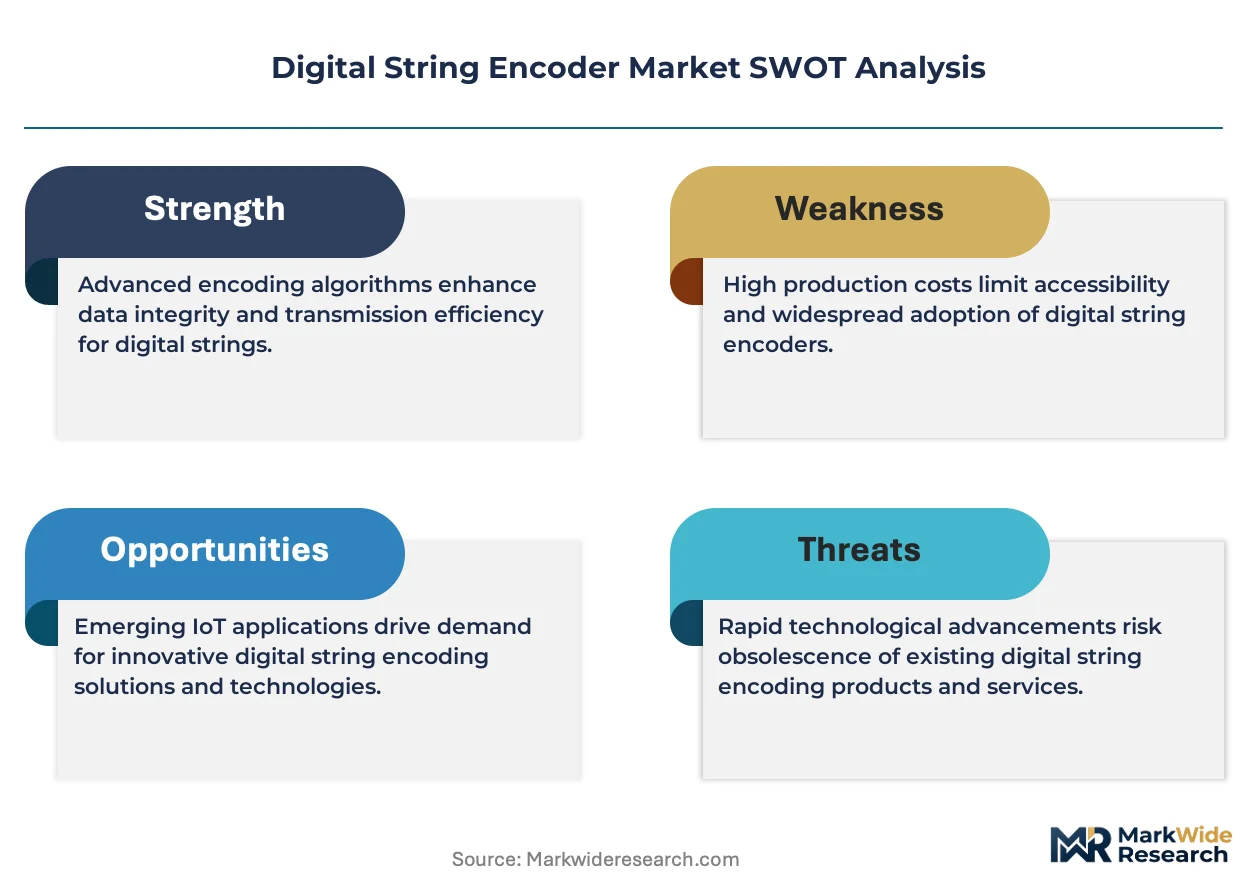
On the supply side, the industry is consolidating around three distinct strategic tiers: precision positioning specialists with captive distribution networks, component-layer silicon vendors with integrated signal conditioning capabilities, and high-volume automotive suppliers with backward integration into sensor packaging. The dominant competitive moves involve M&A to secure rare earth magnet supply chains and strategic partnerships to align communication protocols with Time-Sensitive Networking specifications.
Within the precision positioning tier, HEIDENHAIN represents the European captive-distribution archetype, while Sensata Technologies occupies a position exemplifying automotive-scale backward integration. Texas Instruments anchors the component-layer vector with integrated signal conditioning chips that reduce peripheral circuitry for encoder designers. These three entities collectively illustrate how vendor specialization across sensing, signal processing, and system integration is reshaping competitive positioning in precision motion control markets.
| Leading Market Players |
|---|
| Sensata Technologies |
| HEIDENHAIN |
| Fortive (Dynapar) |
| Renishaw plc |
| Mitutoyo Corporation |
| FRABA B.V. |
| Texas Instruments |
| Analog Devices |
| Micro-Epsilon |
| Others |
Value Chain & Pricing Dynamics
Rare earth magnet supply concentration through Chinese processing corridors determines both pricing tier spreads and supply chain shape for digital string encoder procurement. Geopolitical friction injects volatility into bill-of-materials while OEMs buffer against stranded fieldbus investments.
Pricing Analysis
Certification level creates the primary spread across encoder pricing tiers, with ISO 13849 PLd/PLe redundant channel architectures commanding 40-60% premiums over single-channel alternatives. Three-tier pricing structure separates premium optical encoding systems with sub-micron resolution from standard magnetic devices and economy-grade analog replacements. Cost compression in the mid-tier magnetic segment is intensifying because single-chip integrated solutions from silicon vendors collapse peripheral component counts. Automotive battery winding equipment builders exhibit highest price sensitivity due to unbundled procurement practices, while semiconductor lithography OEMs absorb premium tiers for vacuum-compatible precision.
Supply Chain Analysis
Neodymium and dysprosium feedstock draws from Chinese rare earth processing corridors, while precision glass scales and LED sources hinge on specialized Japanese and German suppliers. Magnetic sensing elements rest on neodymium-dysprosium supply chains concentrated in Chinese refining operations, and optical code discs feed from Hoya and Schott glass fabrication facilities. Single-source vulnerability concentrates in 300mm wafer transport encoder procurement for Yangtze River Delta cleanrooms. Distribution runs through captive networks for precision positioning specialists and direct OEM contracts for high-volume automotive suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Time-Sensitive Networking convergence is shifting this market toward platform-economics dynamics where interoperability determines vendor viability. IEC 61158 standardization rewards early protocol alignment while penalizing proprietary fieldbus islands.
For Market Incumbents: Pre-empt stranded asset risk by accelerating TSN-compatible interface roadmaps before OEMs complete machine tool retrofit cycles. Consolidate rare earth magnet supply through captive offtake agreements with Chinese processors to defend against price volatility. Certification pre-investment in EU Machinery Regulation 2023/1230 digital product passports compresses CE marking timelines for European machine tool OEMs.
For New Entrants and Emerging Players: Mid-market robotic joint applications in China's Jiangsu province represent the most penetrable entry point given disaggregation of encoder specification from bundled motion control systems. Collaborative robot manufacturers in Germany sourcing sub-40mm motor-encoder packages present secondary white-space opportunity. Go-to-market positioning through silicon vendor reference designs reduces R&D barriers for magnetic encoder signal conditioning integration.
For Investors and Strategic Acquirers: The market sits at a standardization-inflection phase that favors component-layer specialists with integrated interpolation capabilities over discrete optical assembly vendors. Long-term viability across the analysis window rests on backward integration into rare earth magnet sourcing and forward integration into TSN protocol stacks. Watch IEEE 802.1AS adoption velocity in German automotive assembly belts as inflection indicator for single-cable architecture displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| TSN Protocol Stack Integration | Eliminates legacy fieldbus gateways for German machine tool OEMs deploying IEC 61158. |
| Rare Earth Magnet Supply Agreement | Secures neodymium-dysprosium feedstock against Chinese export restriction scenarios. |
| Digital Product Passport Certification | Compresses EU Machinery Regulation 2023/1230 compliance timelines for CE marking. |
| Single-Chip Magnetic Encoder Launch | Collapses subsystem costs for collaborative robot joints below 40mm diameter targets. |
| Automotive Assembly Belt Partnership | Captures EV powertrain retrofit demand in Baden-Württemberg servo press installations. |
Study Parameters
Operator-level perspectives from plant engineers at CNC retrofit facilities, procurement leads at automotive battery equipment builders, and motion control specialists at German machine tool OEMs anchored the qualitative base. Secondary validation drew from IEC 61158 standard documentation, SEC filings of listed component vendors, METI subsidy program disclosures, and EU Machinery Regulation implementation guidance. Bottom-up encoder shipment estimates by product architecture and sensing technology triangulated against top-down industrial automation capital expenditure projections across semiconductor and automotive verticals.
Scenario-bracketing across TSN adoption velocity, rare earth price volatility bands, and machinery safety certification timelines shaped the analytical framework. Segmentation dimensions modeled include product integration depth, sensing modality, end-use environment, and communication interface type alongside regional regulatory cluster differentiation. CAGRs were derived from installed base growth in precision motion control applications and replacement cycle acceleration in legacy fieldbus retrofit programs.
Stress conditions across neodymium supply disruption, IEEE 802.1AS implementation delays, and ISO 13849 certification backlog scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about industrial Ethernet protocol consolidation and machinery safety mandate enforcement. Cross-checking against IEC standard adoption metrics reported by fieldbus consortiums is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Virtual Closet Market
Digital Solutions
EHS Software Market
Digital Solutions
Multicarrier Parcel Management Solutions Software Market
Digital Solutions
Cinema Point of Sale (POS) Solutions Market
Digital Solutions
Hyperlocal Services Market
Digital Solutions
Digital Shelf Market
Digital Solutions
Digital Experience Technology Market
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
Global Application Container Market
Digital Solutions
Online Dating Market
Digital Solutions
Digital User Experience Solutions Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
Data Classification Tool Market
Digital Solutions
Container Orchestration Market
Digital Solutions
Enterprise Manufacturing Intelligence Market
Digital Solutions
Real-Time (Graphics and Video) Rendering Solutions Market