
 Global Application Container Market | 2026-2036
Global Application Container Market Size, Share, and Industry Trends Forecast 2026-2036
Global Application Container Market Intelligence
Subscription-based access to container orchestration and management platforms is expanding the total addressable market beyond simple runtime environments. This shift favors large-scale cloud providers who can bundle container services with other cloud offerings. Google Cloud leverages its deep expertise in Kubernetes, which it originally developed. Red Hat differentiates through its enterprise-focused OpenShift platform, offering security and support for hybrid cloud deployments, while Microsoft Azure positions its Azure Kubernetes Service as a core component of its broader cloud ecosystem.
Application containers are lightweight, executable software packages containing an application's code, runtime, and system dependencies. This self-contained structure ensures consistent performance across different computing environments, from development to production. The primary purpose is to streamline software delivery and improve operational efficiency. The public cloud deployment model dominates new projects, while the microservices application segment is the primary driver of new container adoption, breaking down monolithic applications into smaller, manageable services.
Regulatory frameworks significantly influence container security and data management strategies. Europe's GDPR mandates strict controls over personal data, affecting where containerized workloads can run and how data is processed. In the United States, guidelines from NIST provide benchmarks for securing container images and runtime environments. Consequently, enterprises must navigate a complex landscape of compliance requirements when architecting their container strategies.
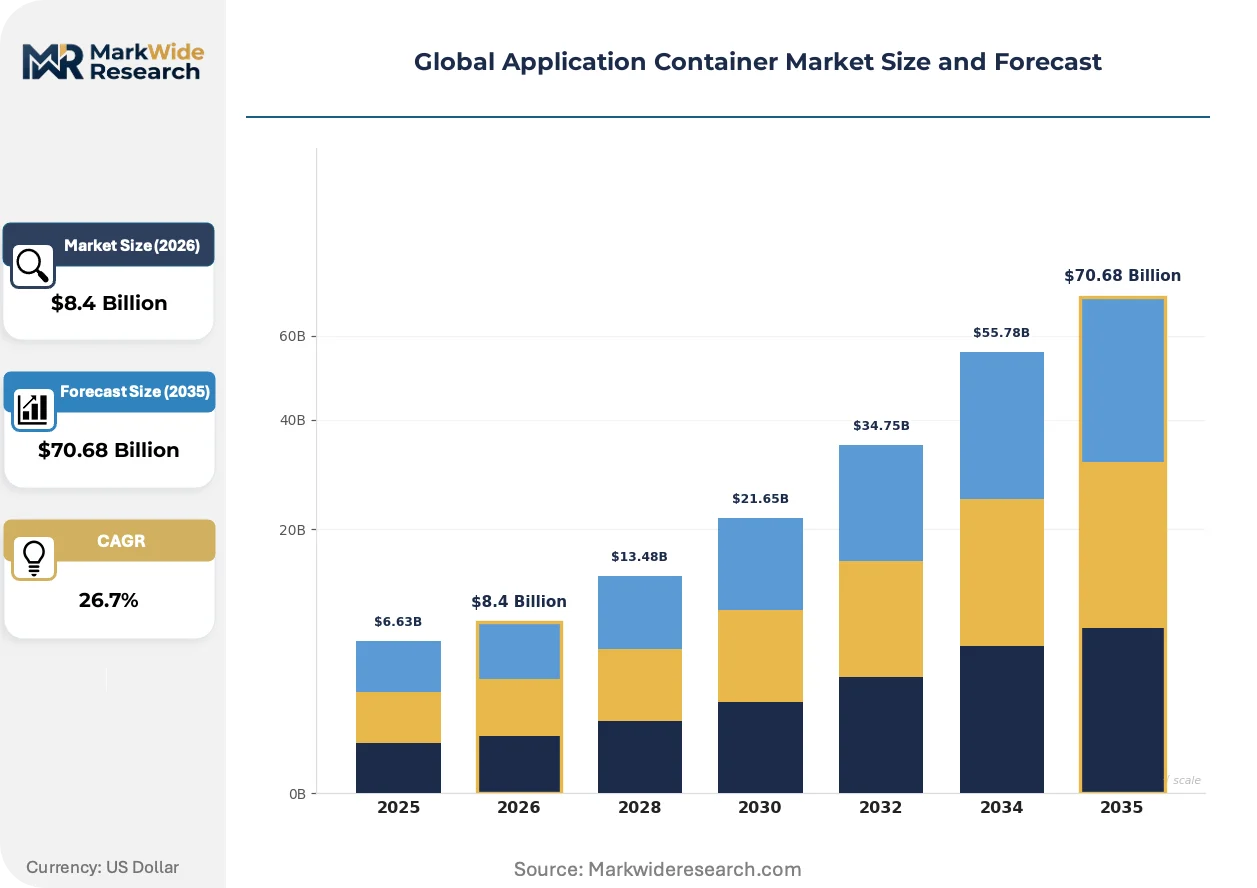
Market Dynamics
The fundamental shift from monolithic application architectures to distributed microservices is the central force shaping the application container market. This architectural evolution makes containerization a necessity for managing deployment complexity, improving scalability, and enabling agile development lifecycles across enterprises.
Growth Catalysts
- DevOps Automation:The widespread adoption of continuous integration and continuous delivery (CI/CD) pipelines directly drives container usage, as containers provide the consistent, immutable artifacts needed to automate software delivery from development to production environments.
- Telecommunications Modernization:Network operators are containerizing network functions (CNFs) to build more agile, scalable, and cost-effective 5G networks, replacing traditional hardware-based virtual network functions (VNFs) and creating significant demand for container orchestration.
- Software Development Hubs:Demand is concentrating in technology clusters like Silicon Valley in the United States and Bangalore in India, where a high density of software companies and skilled engineers accelerates the adoption and innovation of container-native technologies.
Market Restraints
- Stateful Application Complexity:Managing persistent data and stateful applications, such as databases, within containerized environments remains a significant technical hurdle, often requiring complex storage orchestration solutions that add operational overhead.
- Security Vulnerabilities:The shared kernel architecture inherent to containers creates a distinct attack surface. Securing the container supply chain from image creation to runtime requires specialized tools and expertise, which can slow down adoption for security-conscious organizations.
- Orchestration Platform Lock-in:While Kubernetes is open-source, deep integration with a specific cloud provider's managed service (like GKE or EKS) creates a risk of ecosystem lock-in, making future migrations to other clouds or on-premises environments costly and complex.
Strategic Opportunities
- Edge Computing Workloads:The expansion of IoT and industrial automation creates a significant opportunity for lightweight containers at the network edge, where low-latency processing is critical and traditional virtual machines are too resource-intensive.
- Serverless Container Convergence:The fusion of serverless platforms with container technology, through services like AWS Fargate and Azure Container Apps, offers a simplified operational model that abstracts away server management, appealing to organizations without deep Kubernetes expertise.
- Public Sector Adoption:Government agencies in Europe and North America are beginning to adopt container strategies to modernize legacy applications and improve service delivery, creating new revenue streams for vendors offering compliant and secure platforms.
Industry Challenges
- Kubernetes Skills Gap:A persistent shortage of DevOps engineers and site reliability engineers (SREs) with advanced skills in Kubernetes, service mesh, and container security is a primary operational bottleneck for many enterprises.
- Legacy System Integration:Integrating containerized microservices with existing monolithic applications and legacy data stores presents a major architectural challenge, often leading to complex hybrid environments that are difficult to manage and secure.
- Multi-Cluster Management:As container adoption scales, organizations face increasing complexity in managing, securing, and ensuring consistent policies across multiple Kubernetes clusters that may span different clouds and on-premises data centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Application Container Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $70.68 Billion |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Docker, Kubernetes, LXC, rkt, Apache Mesos, OpenVZ Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-premises Application: Microservices, Web Applications, Big Data Analytics, IoT, DevOps Automation End User Industry: Telecommunications, Media & Entertainment, Government, Education, Manufacturing |
| Companies Covered | Docker, Inc., Amazon Web Services, Google Cloud, Microsoft Azure, IBM, Red Hat, Oracle, VMware, Mirantis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Application Container Market Strategic Shifts & Innovations
The container ecosystem is maturing beyond core orchestration, with innovation now focused on enhancing security, simplifying developer experience, and enabling new application architectures. This evolution is reshaping competitive positioning from pure runtime providers to comprehensive enterprise platform vendors.
WebAssembly (Wasm) provides a sandboxed, high-performance runtime environment for code execution. Technology firms and financial services companies are actively experimenting with Wasm for its security and portability benefits. The technology is integrating with container runtimes to offer a faster, more secure alternative for running specific functions and microservices, especially in edge computing scenarios.
Regulatory frameworks are solidifying best practices for container security. For instance, guidelines from the U.S. National Institute of Standards and Technology (NIST) provide authoritative benchmarks for securing the software supply chain, which is forcing enterprises to formalize image scanning and vulnerability management. The defense and financial sectors are most affected, embedding these security controls directly into their automated deployment pipelines.
Enterprise buying behavior is evolving from adopting individual open-source tools to procuring fully integrated and supported container platforms. This change disrupts the do-it-yourself approach, favoring vendors that offer unified solutions for orchestration, security, storage, and networking. This pattern is most prominent in regulated industries like healthcare and banking, where vendor support and a clear compliance posture are critical procurement criteria.
Global Application Container Market Segmentation
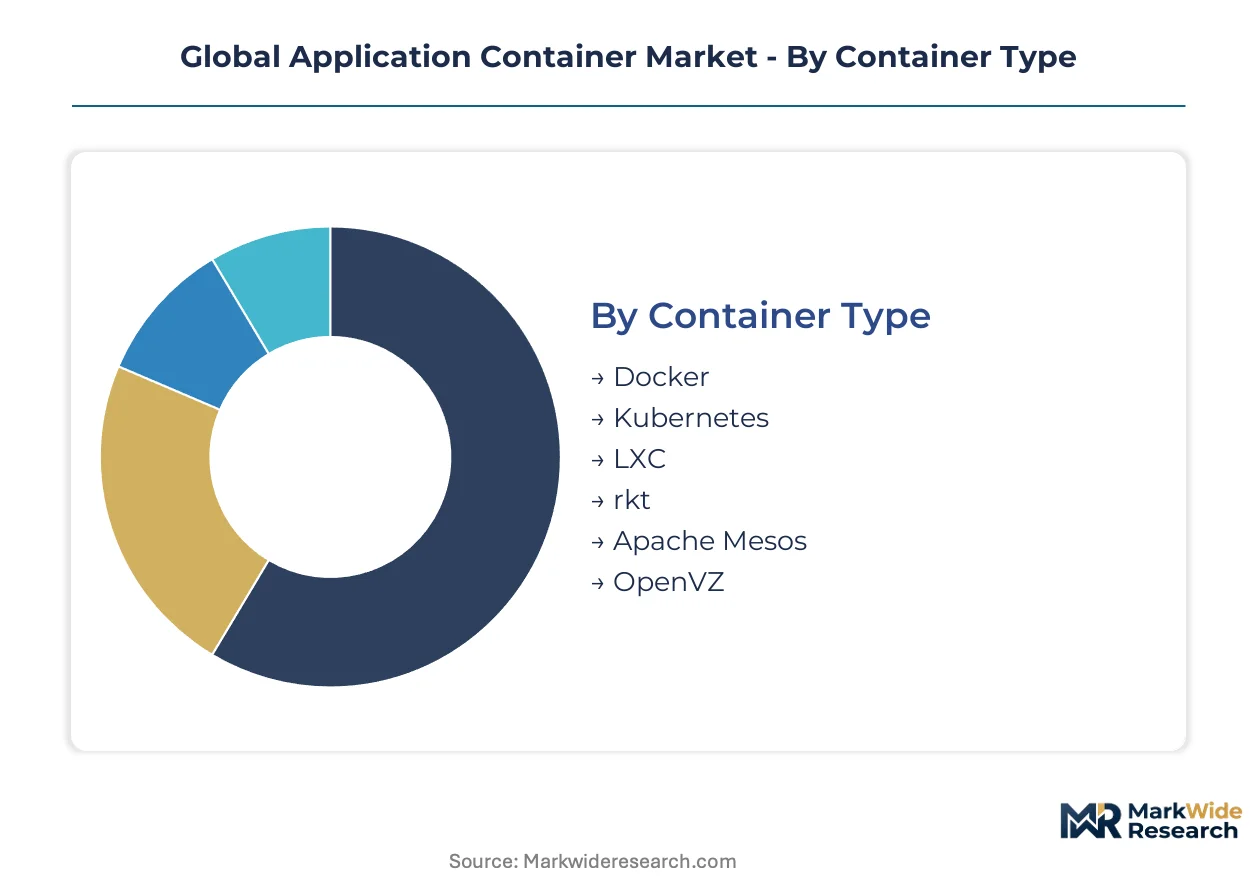
Understanding the Global Application Container Market through segmentation reveals how diverse technological requirements and deployment preferences shape adoption. This granular view helps stakeholders identify areas of concentrated demand and emerging opportunities across various operational environments.
Container Type:
Capital investment in container orchestration platforms and runtime environments often dictates the choice of container type, influencing operational complexity and scalability for enterprises.
- Kubernetes:This open-source system automates deployment, scaling, and management of containerized applications, serving as the de facto standard for orchestration. Demand concentrates heavily in telecommunications for 5G network function virtualization and in major software development hubs like Silicon Valley, driven by the need for advanced workload management.
- Docker:As a foundational platform, Docker packages applications into standardized units called containers, ensuring consistent execution across environments. Software development teams widely adopt Docker for streamlining CI/CD pipelines, particularly within agile development practices.
- LXC:Linux Containers provide operating-system-level virtualization, allowing multiple isolated Linux systems to run on a single host.
- rkt:An open-source container runtime, rkt focuses on security and composability, often used in environments prioritizing stringent isolation.
- Apache Mesos:This distributed systems kernel manages computer clusters, abstracting CPU, memory, storage, and other compute resources away from machines.
- OpenVZ:An operating system-level virtualization technology, OpenVZ creates isolated, secure Linux containers on a single physical server.
Most installed capacity flows through Kubernetes for orchestration. Expansion is steepest in Docker for developer adoption.
Deployment Model:
Deployment models dictate where containerized workloads reside and how they are managed at scale, impacting data sovereignty and infrastructure costs for organizations.
- Public Cloud:Cloud providers host container services, offering scalability, reduced operational overhead, and pay-as-you-go pricing. New projects in software development and data analytics predominantly favor public cloud deployments due to their immediate resource availability and elastic scaling capabilities.
- Hybrid Cloud:This model combines public and private cloud environments, allowing data and applications to move between them. Enterprises in regulated industries, such as financial services, utilize hybrid cloud to maintain compliance while leveraging public cloud agility for non-sensitive workloads.
- Private Cloud:Dedicated infrastructure within a company's data center provides enhanced security and control over containerized applications.
- On-premises:Containers run on local servers within an organization's physical infrastructure, offering maximum control and minimal reliance on external providers.
Public cloud deployments currently lead in new project volume. Hybrid cloud models are gaining traction for their balanced approach to data residency and operational flexibility.
Application:
Specific application types define the operational requirements and architectural patterns for container adoption, driving specialized tooling and management strategies.
- Microservices:This architectural approach structures an application as a collection of loosely coupled services, making containers a natural fit for their deployment and management. Software development firms widely adopt microservices to enhance agility and independent scaling of application components.
- DevOps Automation:Containers provide consistent, immutable environments essential for continuous integration and continuous delivery (CI/CD) pipelines. Technology companies in Bangalore leverage containerization extensively to automate software releases and ensure environmental parity from development to production.
- Web Applications:Containers encapsulate web application code and dependencies, simplifying deployment and ensuring consistent performance across various servers.
- Big Data Analytics:Containerization supports the deployment of distributed data processing frameworks, enabling scalable analytics workloads.
- IoT:Lightweight containers are suitable for edge computing scenarios, allowing low-latency processing of data from Internet of Things devices.
Microservices architectures are the primary catalyst for new container deployments. DevOps automation platforms integrate containers for consistent software delivery.
End User Industry:
End-user industries exhibit varying levels of container adoption maturity and regulatory scrutiny, influencing deployment strategies and vendor requirements.
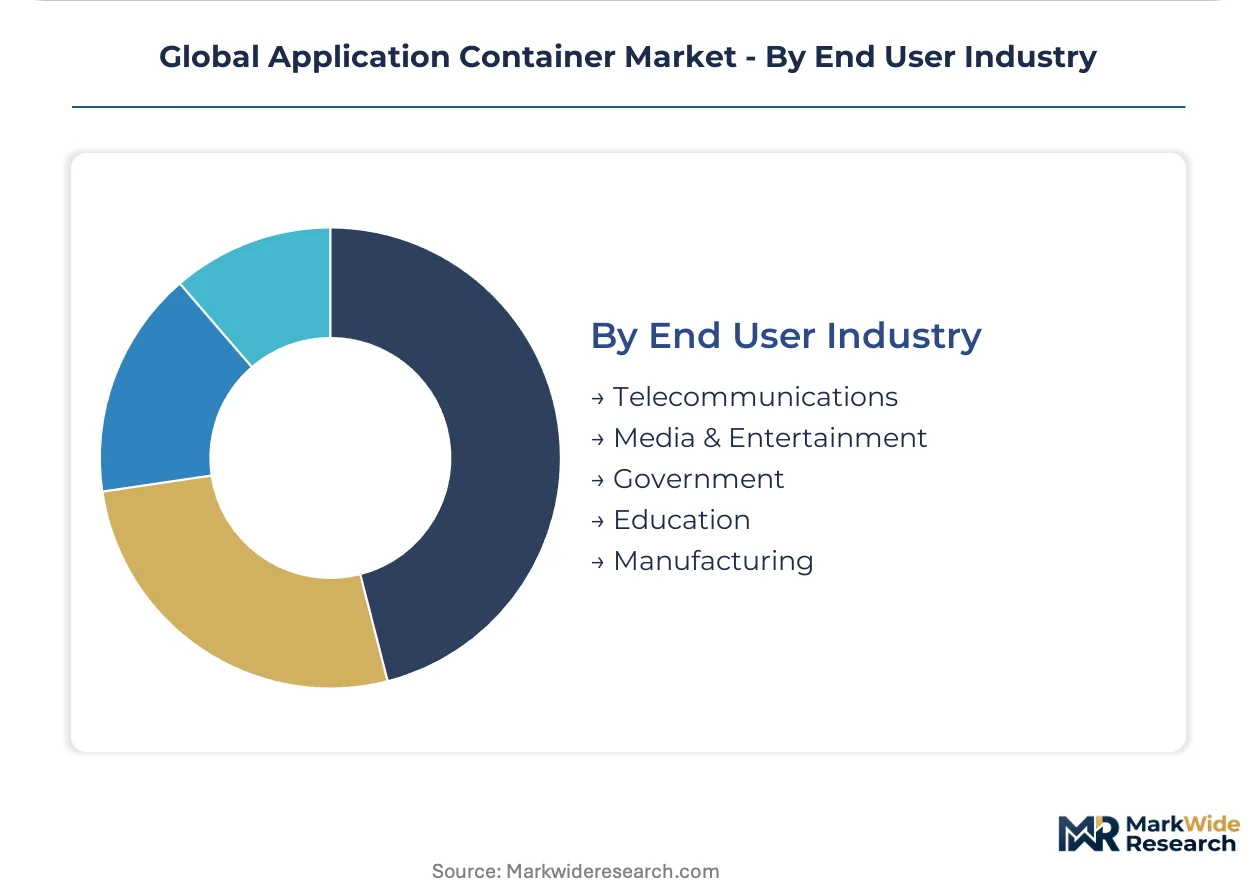
- Telecommunications:Network operators containerize network functions (CNFs) to modernize infrastructure, enabling more agile and cost-effective 5G networks. This sector represents a significant growth area for container orchestration, displacing traditional hardware-based solutions.
- Government:Public sector agencies are increasingly adopting container strategies to modernize legacy applications and improve service delivery, requiring compliant and secure platforms. Regulatory guidelines from NIST influence container security benchmarks for government deployments in the United States.
- Media & Entertainment:Companies in this sector utilize containers for scalable content delivery, streaming services, and rendering farms.
- Education:Educational institutions deploy containers for consistent development environments, research computing, and online learning platforms.
- Manufacturing:Manufacturers employ containers for industrial IoT applications, factory automation, and managing operational technology workloads at the edge.
Telecommunications leads in large-scale infrastructure modernization through containerization. Government agencies are increasing their container strategies for secure application delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States drives innovation in container-native technologies, India rapidly scales adoption through extensive software development. Both countries demonstrate significant demand for application container solutions. This global market sees varied regional growth patterns influenced by regulatory environments and industry modernization efforts.
United States
Demand for application containers in the United States stems from its robust software development hubs and significant public cloud adoption. NIST guidelines for securing container images and runtime environments influence enterprise strategies. Silicon Valley remains a primary center for accelerating container-native technology adoption and innovation.
India
India's application container market expands rapidly, driven by pervasive DevOps automation and telecommunications modernization initiatives. The country's data privacy regulations shape how containerized workloads are deployed and managed. Bangalore serves as a key technology cluster, extensively leveraging containerization to automate software releases.
Germany
Germany exhibits strong demand for hybrid cloud deployments and containerization within its regulated industries, such as financial services. Europe's GDPR mandates strict controls over personal data, affecting containerized workload placement. Munich emerges as an innovation hub for enterprise container platforms, focusing on secure and compliant solutions.
United Kingdom
The United Kingdom's market for application containers is propelled by modernization efforts in financial services and government sectors. The UK's Data Protection Act influences data management strategies for containerized applications. London's vibrant fintech sector drives the need for secure and scalable container deployments.
China
China's application container market grows significantly through 5G network buildouts and widespread cloud service adoption. Policies from the Ministry of Industry and Information Technology (MIIT) promote advanced cloud infrastructure development. Shenzhen leads in the rapid adoption of container technologies within its high-tech manufacturing base.
Global Application Container Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining the market's competitive structure. The application container market features a tiered landscape with large cloud providers, specialized enterprise software vendors, and open-source contributors. Strategic partnerships and portfolio diversification are dominant competitive moves among these players.
Large-scale cloud providers and enterprise software specialists define distinct competitive vectors. Google Cloud leverages its deep expertise in Kubernetes, which it originally developed, to anchor its cloud offerings. Red Hat differentiates through its enterprise-focused OpenShift platform, exemplifying a hybrid cloud strategy. Microsoft Azure positions its Azure Kubernetes Service as a core component of its broader cloud ecosystem, representing a comprehensive platform approach.
| Leading Market Players |
|---|
| Docker, Inc. |
| Amazon Web Services |
| Google Cloud |
| Microsoft Azure |
| IBM |
| Red Hat |
| Oracle |
| VMware |
| Mirantis |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure costs significantly influence the pricing of managed container services, as hyperscalers bundle these offerings with other platform services. This upstream cost component directly impacts downstream subscription models for enterprises.
Pricing Analysis
Capacity additions in public cloud regions are reshaping price floors for managed container services, intensifying competition among hyperscalers. The dominant pricing model is subscription-based, offering tiered access to orchestration and management platforms. Price differentiation stems from enhanced security features, robust hybrid cloud support, and deep integration with broader cloud ecosystems. Pricing pressure arises from the availability of open-source Kubernetes and the need to attract new projects, making smaller software development firms highly price-sensitive compared to large enterprises requiring extensive compliance and support.
Supply Chain Analysis
Dual-sourcing requirements often emerge for critical container components, driven by enterprises seeking to mitigate vendor lock-in with specific cloud providers. Geographic supply for container innovation concentrates in technology hubs like Silicon Valley and Bangalore, while cloud infrastructure deployment spans global regions. The supply chain relies on open-source software contributions and robust cloud hardware. Orchestration platform lock-in presents a structural risk, as deep integration with one cloud ecosystem can complicate migration. Distribution runs through direct offerings from hyperscalers and specialized enterprise software vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The application container market presents a geographic-arbitrage opportunity, where lower operational costs in regions like India enable cost-effective software development compared to higher-cost Western hubs. This differential drives strategic investment decisions for container-native solutions.
For Market Incumbents:Acquire specialized container security firms to integrate advanced threat detection and vulnerability management capabilities into existing platforms. Large cloud providers must also expand their hybrid cloud support, especially for regulated industries facing data residency requirements, countering the threat of ecosystem lock-in. Investing in R&D for WebAssembly integration can future-proof runtime environments, addressing emerging performance and security demands. Focus R&D on simplifying multi-cluster management to reduce operational complexity for large enterprise clients.
For New Entrants and Emerging Players:Small to medium enterprises (SMEs) without extensive Kubernetes expertise represent an underserved buyer archetype for simplified container management solutions. Target edge computing workloads where lightweight containers offer critical low-latency processing, especially in industrial automation. Focus on serverless container convergence platforms, abstracting away infrastructure complexity for developers. A go-to-market strategy emphasizing compliance-as-a-service and ease of integration can attract public sector agencies in Europe and North America.
For Investors and Strategic Acquirers:Consolidation pressure builds where specialized container security and compliance capabilities become critical differentiators for platform completeness. Long-term viability in this market depends on continued enterprise migration to microservices architectures and demand for hybrid cloud solutions. Investors should seek acquisition targets specializing in container security, multi-cluster management, or WebAssembly integration. The signal to watch is a significant increase in government and financial sector mandates for end-to-end container supply chain security, indicating a shift towards regulated, integrated platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Google Cloud deepens its Kubernetes offerings by integrating advanced security and AI/ML services. |
| Strategic Partnership | Red Hat partners with telecommunications providers to deploy OpenShift for 5G network function virtualization. |
| Acquisition of Specialist Firm | Microsoft Azure acquires a container security startup to bolster its Azure Kubernetes Service defenses. |
| Geographic Expansion | Major cloud providers expand data center presence in India to support local DevOps automation demand. |
| Product Launch | Vendors introduce serverless container platforms to simplify operations for developers lacking Kubernetes expertise. |
Research Approach
Bottom-up end-user adoption modeling reconciled against top-down cloud provider revenue tracking forms the analytical core of this study. Primary interviews with CTOs, DevOps engineers, and IT procurement officers provided qualitative insights. Secondary validation drew from public cloud provider reports, open-source project documentation, and NIST guidelines. This triangulation approach ensured a robust understanding of market dynamics.
Historical trendline analysis established foundational growth trajectories for various container technologies and deployment models across the analysis window. The quantitative model segmented the market by container type, deployment model, application, and end-user industry. Compound Annual Growth Rates were derived from an assessment of growth catalysts and market restraints. Microservices adoption rates and 5G network buildout schedules served as critical industry-specific forecast inputs.
Underlying measurement precision varies by segment; public cloud deployments carry tighter precision than emerging edge computing applications. Forecasts reflect assumptions regarding regulatory stability and continued enterprise digital transformation. Deviation in widespread open-source security vulnerabilities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
IT Asset Management Market
Digital Solutions
Global Content Moderation Solutions Market
Digital Solutions
Online Classified Ad Platform Market
Digital Solutions
US Digital Signage Market
Digital Solutions
Hiking Apps Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Asia Pacific B2C Legal Services Market
Digital Solutions
Morocco ICT Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
Governed Enterprise Architecture Scenario Sandbox Market
Digital Solutions
Correspondence Management Solution Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Global Assistive Technologies for Visually Impaired Market
Digital Solutions
Global Digital Experience Management Market
Digital Solutions
Global Referral Management Market