
 Real-Time (Graphics and Video) Rendering Solutions Market | 2026-2036
Real-Time (Graphics and Video) Rendering Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Real-Time (Graphics and Video) Rendering Solutions Market Analytics
The EU AI Act is realigning compliance costs for real-time rendering vendors serving European media clients. NVIDIA leverages its CUDA ecosystem to dominate datacenter GPU deployments for path tracing workloads. Epic Games anchors its position through Unreal Engine's penetration of virtual production stages across major film studios. Autodesk differentiates via deep integration between Maya and emerging real-time pipelines.
Real-time (graphics and video) rendering solutions comprise software and hardware systems that generate photorealistic or stylized imagery within milliseconds using parallel GPU architectures, with latency thresholds typically below 33 milliseconds for 30 frames-per-second playback. These systems serve film production, interactive entertainment, architectural visualization, and live broadcast graphics by replacing offline batch rendering with immediate visual feedback. Video game engines capture the largest revenue pool due to their extensibility into non-gaming verticals, while ray tracing represents the fastest-expanding technology segment as hardware-accelerated RT cores reach mainstream price points. Cloud-based deployment is displacing on-premises render farms among mid-sized film studios seeking elastic compute for peak production cycles.
The Federal Communications Commission shapes broadcast graphics standards in the United States, while the European Union's CSRD mandates sustainability disclosures from rendering datacenter operators. China's MIIT enforces GB standards for graphics processing hardware imported for media infrastructure. Stakeholders must monitor divergence between regional AI content labeling regimes as synthetic media capabilities embed deeper into real-time toolchains.
Market Dynamics
Hardware-accelerated ray tracing is compressing production timelines across film and broadcast verticals, forcing vendors to recalibrate software licensing models around GPU core counts rather than seat-based pricing.
Growth Catalysts
- Virtual production stages:LED volume technology enables in-camera visual effects that eliminate green-screen post-production, pulling demand from Los Angeles and London studio complexes.
- EU AI Act:Synthetic media disclosure mandates create compliance software attach rates for European broadcasters deploying real-time character animation.
- Path tracing hardware:Dedicated RT cores in consumer-grade GPUs democratize photorealistic rendering for mid-sized architectural visualization firms.
Market Restraints
- Datacenter power density:Training-grade GPU clusters face 40-60 kW per rack thermal limits, constraining cloud render farm expansion in Singapore and Frankfurt.
- Foundry concentration:Advanced node semiconductor fabrication concentrates in Taiwan, exposing hardware supply to geopolitical disruption risk.
- Latency physics:Sub-16 millisecond frame generation for 60 fps broadcast graphics requires edge compute placement within 50 kilometers of production facilities.
Strategic Opportunities
- India post-production hubs:Mumbai and Hyderabad facilities seek real-time pipelines to capture overflow work from saturated Los Angeles and London markets.
- Live sports graphics:Augmented reality overlay systems for real-time player tracking open broadcast contracts outside traditional entertainment verticals.
- GB standards alignment:China's MIIT certification requirements for imported broadcast infrastructure create first-mover advantage for vendors achieving dual EU-China compliance.
Industry Challenges
- Pipeline engineering talent:Shortage of technical artists capable of bridging Unreal Engine blueprints with proprietary studio tools extends onboarding cycles to 6-9 months.
- Legacy DCC integration:Real-time workflows must interoperate with decades of Maya and Houdini asset libraries without full scene reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real-Time (Graphics and Video) Rendering Solutions Market |
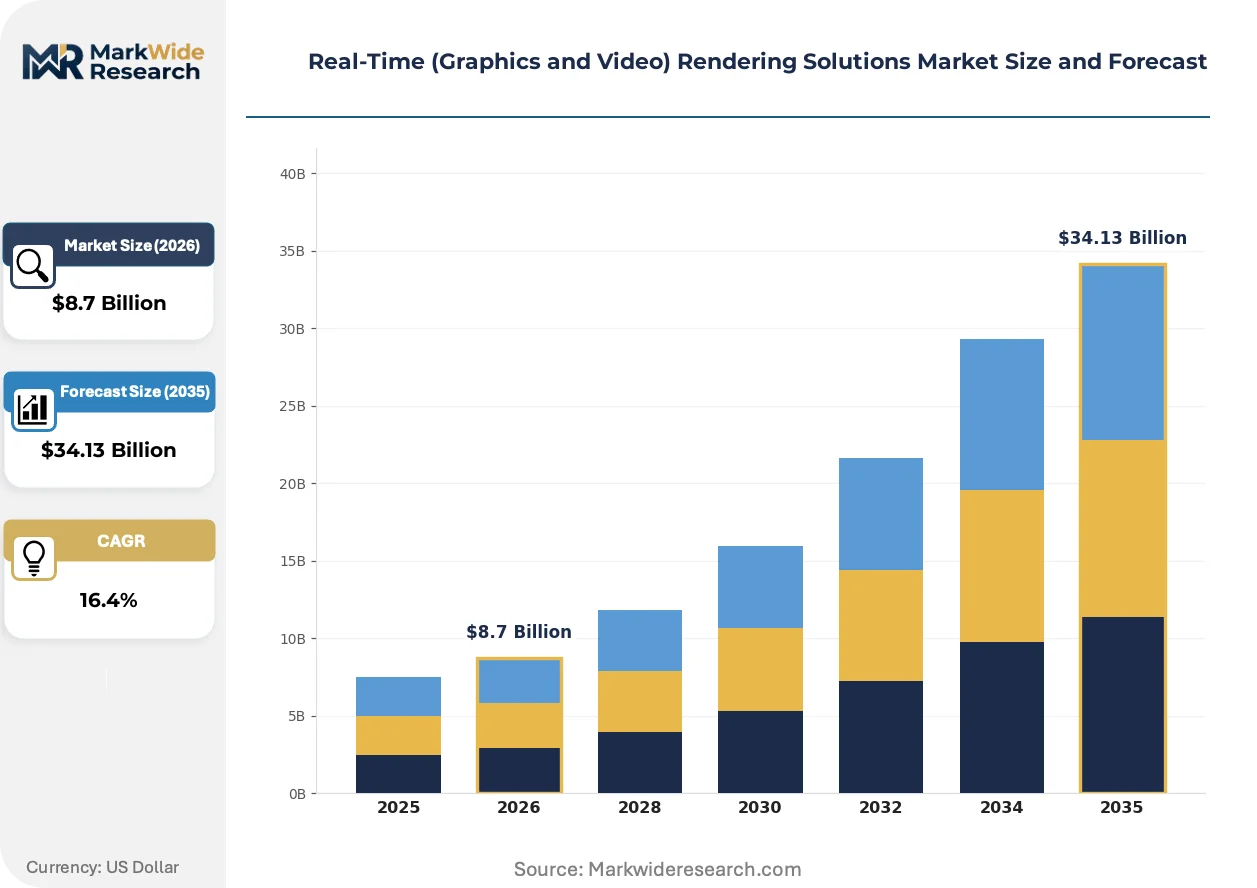
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Game Engines, 3D Rendering Software, Visual Effects Tools, Animation Software End User: Gamers, Film Studios, Advertising Agencies, Educational Institutions Technology: Rasterization, Ray Tracing, Hybrid Rendering, Path Tracing Deployment: Cloud-Based, On-Premises, Hybrid, Mobile |
| Companies Covered | NVIDIA, AMD, Intel, Unity Technologies, Epic Games, Autodesk, Adobe, Maxon, Avid Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real-Time (Graphics and Video) Rendering Solutions Market Evolving Landscape
Neural rendering techniques are collapsing the boundary between pre-rendered cinematic quality and interactive frame rates, forcing infrastructure investments that favor cloud-distributed GPU architectures over on-premises render farms.
Neural radiance fields (NeRF) and 3D Gaussian splatting are electrifying volumetric scene reconstruction for virtual production. Film studios in Los Angeles deploy these techniques to generate photorealistic backgrounds from sparse camera arrays within minutes rather than weeks. The compression of asset creation timelines is electrifying competitive pressure on traditional photogrammetry service providers.
The EU AI Act's synthetic media labeling requirements are reshaping compliance architecture for European broadcasters. Real-time rendering pipelines must now embed provenance metadata at the frame level, adding 8-12% computational overhead to live graphics engines. French and German public broadcasters are piloting blockchain-anchored watermarking systems to satisfy CSRD-aligned transparency mandates.
Subscription-based engine licensing is displacing perpetual seat sales across mid-market visualization studios. Per-project billing tied to render-minute consumption replaces upfront capital expenditure, particularly among Austin and Vancouver architectural firms with irregular project pipelines. This consumption model is most visible in North American markets where cloud infrastructure density supports elastic scaling.
Real-Time (Graphics and Video) Rendering Solutions Market Segmentation
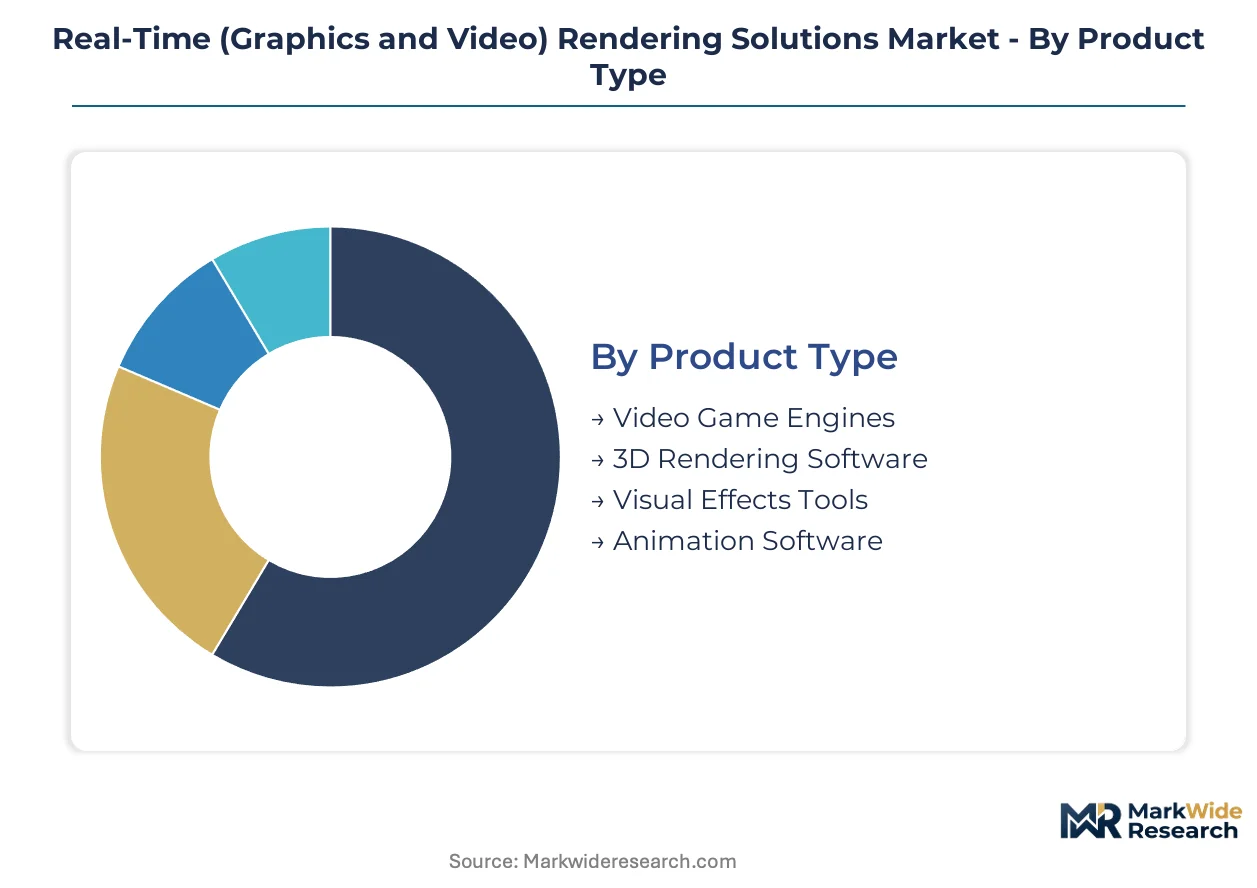
Segmentation in real-time rendering reveals how GPU architecture specialization and workflow integration requirements split purchasing decisions across divergent technical specifications. Product type and deployment mode particularly expose fault lines between elastic cloud consumption and fixed-capital on-premises investment.
Product Type:
Supply concentration in CUDA-optimized toolchains tilts commercial leverage toward engine vendors with datacenter-scale hardware partnerships.
- Video Game Engines:Extensible runtime architectures built on component-based scripting systems serve as the dominant integration layer for virtual production stages. Los Angeles and London film studios drive demand for engine licenses that bridge interactive frame rates with cinematic output pipelines.
- 3D Rendering Software:Standalone photorealistic renderers with proprietary sampling algorithms target architectural visualization firms requiring material accuracy certification. Austin and Vancouver mid-sized studios concentrate demand for subscription-priced GPU renderers that displace perpetual-license CPU farms.
- Visual Effects Tools:Node-based compositing systems with real-time preview capabilities integrate with LED volume workflows.
- Animation Software:Character rigging and motion capture pipelines with live retargeting serve broadcast graphics and live performance capture.
Video game engines absorb the bulk of installed capacity; 3D rendering software is expanding most quickly among architectural visualization specialists.
End User:
Cost tier stratification separates enterprise-grade virtual production deployments from individual creator subscriptions.
- Film Studios:LED volume operators and virtual production departments with dedicated technical artists and on-set visualization supervisors. Los Angeles production clusters anchor enterprise licensing volumes for Unreal Engine and proprietary real-time pipelines.
- Gamers:Individual consumers and esports broadcasters leveraging consumer-grade GPU hardware for content creation and streaming overlays. Twitch and YouTube creators in Austin drive attach rates for engine marketplace assets and plugin subscriptions.
- Advertising Agencies:Brand visualization teams producing real-time configurators and interactive campaign experiences.
- Educational Institutions:University media programs and vocational training centers building curriculum around accessible engine licensing.
Film studios command the highest per-seat pricing; gamers represent the steepest expansion trajectory in absolute license volume.
Technology:
Application requirements dictate trade-offs between frame rate guarantees and visual fidelity thresholds.
- Ray Tracing:Hardware-accelerated intersection tests on dedicated RT cores deliver photorealistic reflections and global illumination at 30-60 fps. Broadcast graphics vendors in Germany and France pilot ray-traced virtual sets to satisfy EU AI Act transparency requirements for synthetic media disclosure.
- Path Tracing:Unbiased light transport simulation converging to physically accurate imagery for final-pixel virtual production. Architectural visualization firms in Mumbai and Hyderabad adopt path tracing to compete with London and Los Angeles quality benchmarks.
- Rasterization:Traditional triangle pipeline with shader-based approximations for maximum frame rate in competitive gaming.
- Hybrid Rendering:Selective ray tracing for primary visibility combined with rasterized effects for performance-critical passes.
Ray tracing dominates current hardware shipments; path tracing is gaining share fastest among premium virtual production deployments.
Deployment:
Customer type and project pipeline volatility determine infrastructure ownership versus operational expenditure preferences.
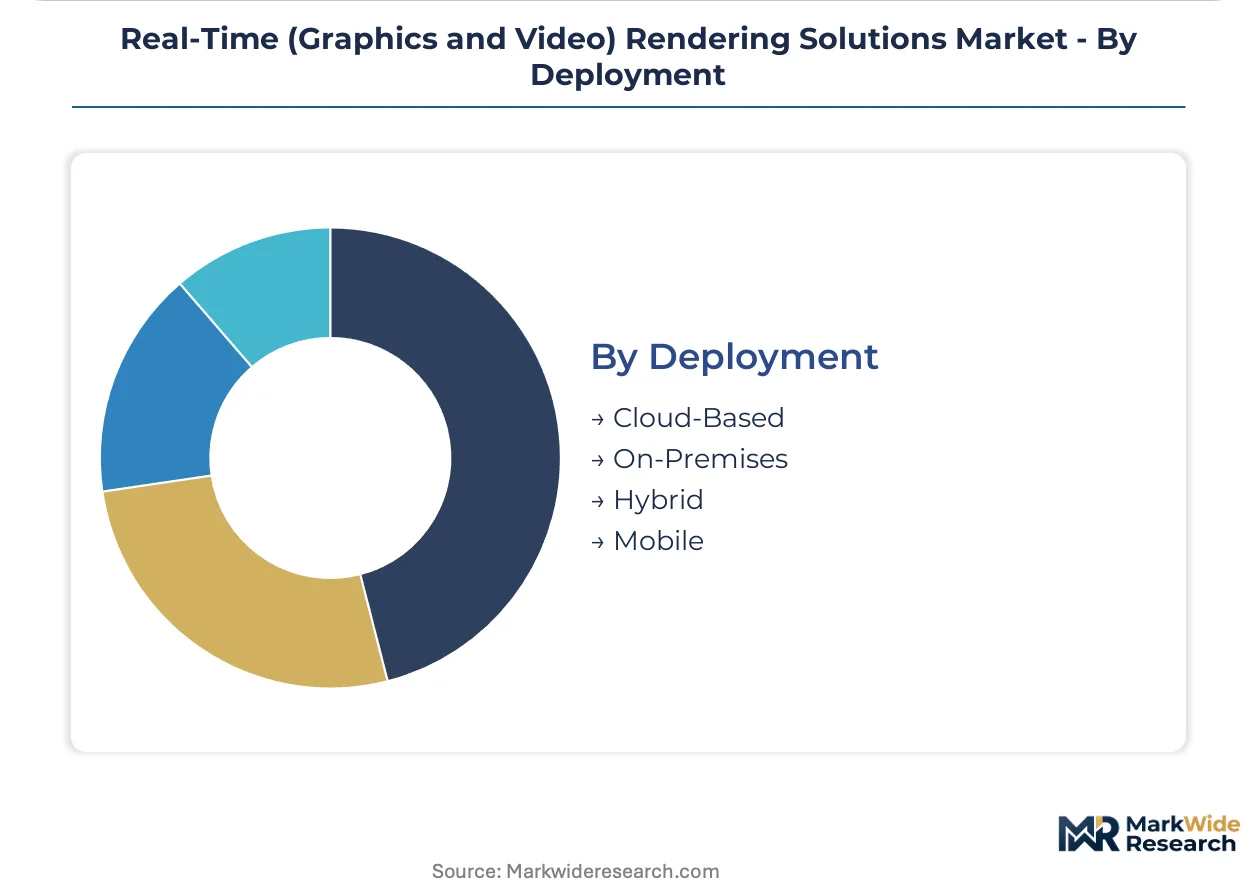
- Cloud-Based:Elastic GPU clusters accessed via render-minute billing models eliminate capital intensity for peak production cycles. Mid-sized film studios in Vancouver and Austin displace on-premises render farms for overflow work from saturated Los Angeles facilities.
- On-Premises:Dedicated server rooms with fixed GPU density serving security-sensitive intellectual property and sub-16ms latency requirements. Major film studios in Los Angeles maintain on-premises LED volume control systems to guarantee frame synchronization.
- Hybrid:Split workflows with asset creation on local workstations and final rendering burst to cloud infrastructure.
- Mobile:Tablet and smartphone-optimized renderers for location scouting and client presentation workflows.
Cloud-based deployment captures the majority of new contract value; hybrid architectures are climbing the fastest among established studios transitioning from capital-intensive infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for real-time rendering solutions clusters in three production corridors where film studios and broadcast infrastructure overlap. Los Angeles, London, and Mumbai anchor distinct supply tiers shaped by regulatory divergence and talent pool depth.
United States
LED volume stages in Los Angeles and Austin drive enterprise engine licensing for virtual production workflows. The FCC maintains broadcast graphics standards that shape real-time overlay requirements for live sports networks. Texas production clusters attract overflow architectural visualization work from saturated California facilities.
United Kingdom
London studio complexes compete for European virtual production contracts against German and French facilities. The UK Information Commissioner's Office enforces GDPR-aligned data handling for cloud-rendered broadcast content. Manchester post-production hubs expand real-time capacity to capture continental overflow work.
Germany
Public broadcasters in Berlin and Munich pilot blockchain-anchored watermarking for EU AI Act synthetic media compliance. The KBA regulates automotive visualization software used in real-time configurators for premium vehicle brands. Bavarian media technology clusters integrate path tracing pipelines for industrial design validation.
China
MIIT enforces GB standards for graphics processing hardware imported for media infrastructure projects. Shenzhen and Beijing production centers develop domestic engine alternatives to reduce dependency on Western software licensing. Shanghai studio complexes deploy hybrid cloud-local architectures to satisfy data sovereignty requirements.
India
Mumbai and Hyderabad post-production facilities adopt real-time pipelines to compete with London and Los Angeles quality benchmarks. BIS certification requirements shape procurement decisions for imported GPU hardware. Karnataka technology corridors attract architectural visualization firms seeking cost-advantaged path tracing services.
Real-Time (Graphics and Video) Rendering Solutions Market Competitive Landscape
United States producers anchor the premium engine tier; European and Asian specialists hold differentiated positions in hardware acceleration and middleware integration. Market structure tilts toward consolidated control at the GPU layer with fragmented competition among engine and tool vendors. Three archetypes dominate: semiconductor designers with datacenter-scale ecosystems, game engine developers extending into film workflows, and legacy DCC vendors bridging real-time and offline pipelines. Capacity expansion and strategic licensing partnerships constitute the primary competitive vectors.
Within the semiconductor archetype, NVIDIA Corporation and Intel Corporation occupy positions reflecting divergent ecosystem strategies. Among engine developers, Epic Games, Inc. exemplifies the virtual production pivot. Autodesk, Inc. represents legacy DCC vendors integrating real-time capabilities. These three anchors illustrate how hardware-software coupling, production workflow penetration, and asset library migration define competitive positioning.
| Leading Market Players |
|---|
| NVIDIA |
| AMD |
| Intel |
| Unity Technologies |
| Epic Games |
| Autodesk |
| Adobe |
| Maxon |
| Avid Technology |
| Others |
Value Network & Pricing Analysis
Technical artist scarcity in Los Angeles and London production clusters widens pricing spreads between premium virtual production deployments and mid-market visualization subscriptions. Labor-cost differentials between these talent hubs and emerging Mumbai and Hyderabad facilities compress margins for standardized rendering services while preserving premium tiers for LED volume operators with proprietary pipeline expertise.
Pricing Analysis
Volume-versus-margin splits separate enterprise virtual production licenses from mass-market engine subscriptions. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service intensity. Cost compression in mid-market GPU renderers intensifies because cloud infrastructure commoditizes peak-load capacity. Individual creators and small Austin studios exhibit highest price sensitivity; Los Angeles film studios demonstrate lowest sensitivity due to timeline premiums.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan's advanced node semiconductor fabrication for RT-core GPUs. Hardware supply draws from Taiwan, South Korea, and the United States for datacenter accelerators, while specialized memory components rest on South Korean and Japanese sources. Raw material dependencies include silicon wafers, high-bandwidth memory stacks, and advanced packaging substrates. Tariff exposure on imported Chinese-assembled consumer GPUs threatens cost structures for mid-market visualization firms. Distribution runs through direct OEM partnerships with cloud hyperscalers and authorized reseller networks serving film studio procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: foundry capacity bottlenecks for 4nm and below GPU architectures prop pricing power for semiconductor vendors with secured wafer allocations.
For Market Incumbents: Deepen CUDA ecosystem lock-in by accelerating middleware partnerships with LED volume control system vendors. Expand captive supply of HBM3 memory through long-term foundry contracts to neutralize emerging AMD ROCm competitive threats. Prioritize certification investment for EU AI Act compliance software attach rates among French and German public broadcasters. For New Entrants and Emerging Players: Enter via India's post-production corridor, where Mumbai and Hyderabad facilities seek cost-advantaged real-time pipelines for London and Los Angeles overflow work. Target live sports augmented reality graphics as the most penetrable broadcast vertical outside saturated entertainment markets. Pursue white-label engine licensing to architectural visualization firms with irregular project pipelines. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid cloud-local infrastructure providers given the EU CSRD's sustainability disclosure mandates for datacenter operators. Long-term viability favors vendors with backward integration into edge compute placement within 50 kilometers of production facilities. Watch blockchain-anchored watermarking pilot adoption among German public broadcasters as inflection signal for compliance software attach rates.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unreal Engine penetration of LED volume workflows locks in Los Angeles studio procurement cycles. |
| Strategic Partnership | NVIDIA's CUDA partnerships with cloud hyperscalers secure datacenter GPU deployment dominance. |
| Acquisition of Specialist Firm | NeRF and 3D Gaussian splatting startups accelerate volumetric scene reconstruction capabilities. |
| Geographic Expansion | Mumbai and Hyderabad facilities capture architectural visualization work from saturated Western markets. |
| Product Launch | Path tracing hardware in consumer-grade GPUs democratizes photorealistic rendering for mid-sized firms. |
Research Methodology
Independent corroboration across virtual production supervisors, broadcast graphics engineers, and datacenter infrastructure planners underwrites the qualitative findings. Primary interviews with technical artists, LED volume operators, and GPU procurement officers at film studios combined with secondary validation from SEC hyperscaler capex disclosures, FCC broadcast standards filings, and EU AI Act regulatory texts. Bottom-up and top-down triangulation cross-checks engine licensing volumes against foundry wafer allocation data.
Comparable-period anchoring to historical virtual production adoption curves and cloud render-farm deployment cycles shapes the forecast window. Segmentation dimensions modeled include deployment mode, end-user scale tier, technology type, and regional regulatory cluster. CAGRs derive from GPU shipment trajectories and engine license attach rates across the projection horizon. Path tracing hardware penetration and EU synthetic media compliance software adoption constitute industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical disruption to Taiwan foundry operations and divergence in regional AI content labeling regimes. Forecasts reflect assumptions about elastic cloud infrastructure density and LED volume stage deployment timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
North America Managed Mobility Service Market
Digital Solutions
AQI App Market
Digital Solutions
Human Resource (HR) Technology Market
Digital Solutions
Kenya ICT Market
Digital Solutions
Self-Service Kiosk Market
Digital Solutions
Business Process Management As a Service Market
Digital Solutions
Laser Page-Turning Pen Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
Mexico Digital Showers Market
Digital Solutions
US Digital Signage Market
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Data Monetization Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Webrtc Market
Digital Solutions
Change Management Software Market
Digital Solutions
Digital Twin in Construction Market