
 Multicarrier Parcel Management Solutions Software Market | 2026-2036
Multicarrier Parcel Management Solutions Software Market Size, Share, and Industry Trends Forecast 2026-2036
Multicarrier Parcel Management Solutions Software Market Foresight
Mid-market e-commerce merchant demand is consolidating around platforms that unify multiple carrier relationships under single dashboards. ShipStation anchors the North American landscape through deep marketplace integrations and workflow automation. MetaPack competes across European corridors with localized carrier density and customs pre-clearance tools. Shippo extends its position among developer-heavy startups through clean API documentation and pay-as-you-scale economics.
Multicarrier parcel management solutions software orchestrates rate comparison, label generation, tracking aggregation, and delivery exception handling across competing logistics networks through cloud-native or on-premise architectures. These systems typically process carrier APIs in sub-second intervals to surface optimal routing decisions at checkout or warehouse dispatch points. Cloud-based and SaaS deployments now lead structural growth by eliminating upfront infrastructure costs and enabling real-time carrier updates without client-side maintenance. Rate shopping and shipment tracking functionalities capture the deepest margin pools, since merchants treat freight cost optimization and customer delivery visibility as non-negotiable conversion and retention tools.
FDA and FTC oversight in the United States shapes pharmaceutical and consumer goods shipping documentation requirements, while GDPR and the EU AI Act in Europe constrain how delivery prediction algorithms process personal data and automate carrier selection. Compliance with REACH-related packaging declarations and evolving carbon accounting under the EU Green Deal further complicates cross-border label generation. Stakeholders must monitor whether emerging customs interoperability standards force platform rebuilds or create openings for modular integration specialists.
Market Dynamics
Carrier API fragmentation is forcing platform vendors to rebuild middleware layers around real-time rate normalization, as merchants now expect sub-second routing decisions across fifty-plus logistics networks without manual intervention.
Growth Catalysts
- E-commerce merchant consolidation:Mid-market retailers operating across Amazon, Shopify, and WooCommerce storefronts require unified label generation workflows. Platform subscriptions accelerate where dashboard unification eliminates separate carrier logins.
- EU AI Act compliance automation:Delivery prediction algorithms processing personal data must embed audit trails and human oversight triggers. Vendors integrating these guardrails capture cross-border merchant contracts faster than competitors relying on manual compliance checks.
- Returns complexity in apparel:Reverse logistics now represents thirty to forty percent of parcel volume for fashion merchants. Solutions offering automated return label generation and carrier-agnostic drop-off routing command premium positioning.
Market Restraints
- Carrier API versioning volatility:FedEx, UPS, and DHL push breaking changes to their shipping interfaces on eighteen-month cycles. Platform engineering teams absorb continuous refactoring costs that compress gross margins.
- Customs documentation divergence:Harmonized System code requirements vary between the United States, Germany, and the Netherlands despite nominal WTO alignment. Label generation engines require territory-specific rule sets that multiply code maintenance overhead.
- Cloud infrastructure concentration:AWS and Azure host ninety percent of SaaS deployments in this category. Carrier data residency requirements in France and Germany force multi-region architectures that inflate hosting spend.
Strategic Opportunities
- Carbon accounting module expansion:The EU Green Deal mandates granular emissions disclosure for cross-border shipments. Platforms embedding carrier-specific CO2 calculation APIs capture sustainability-driven procurement decisions.
- Pharmaceutical cold chain integration:FDA temperature excursion documentation requirements create demand for sensor data ingestion alongside standard tracking. Solutions bridging IoT telemetry with carrier handoff records unlock healthcare logistics contracts.
- India customs digitization:The country's ICEGATE platform modernization and GST e-invoice linkage create openings for localized rate shopping engines. Early movers establishing carrier density with Blue Dart and Delhivery secure anchor positions.
Industry Challenges
- Legacy warehouse management system integration:Enterprise merchants running Oracle WMS or SAP EWM require custom middleware for label generation triggers. Implementation timelines stretch eight to fourteen months, delaying subscription revenue recognition.
- Machine learning operations talent scarcity:Delivery prediction models demand engineers with both logistics domain knowledge and MLOps deployment expertise. Recruitment competition from autonomous vehicle and drone delivery ventures inflates compensation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multicarrier Parcel Management Solutions Software Market |
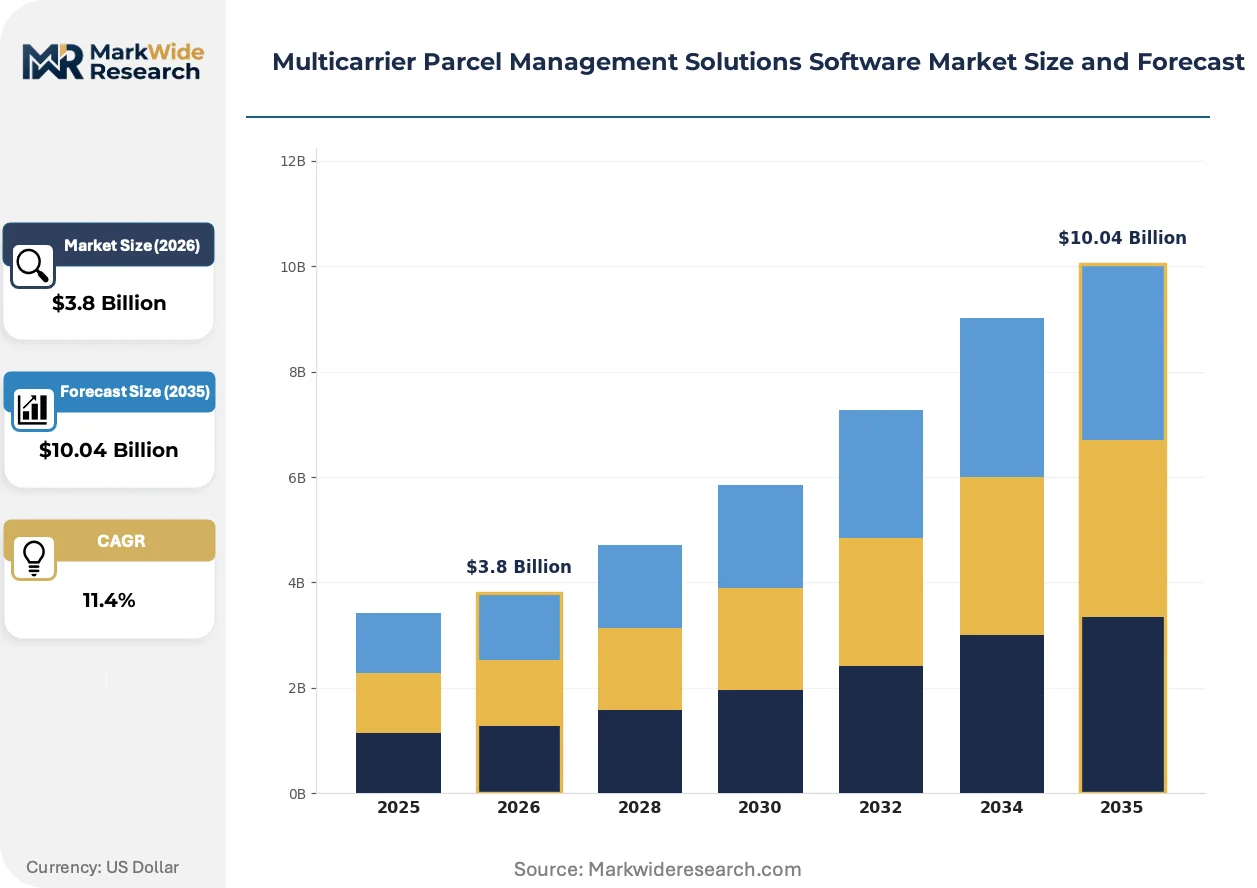
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: E-Commerce, Retailers, Logistics Providers, Manufacturers Integration Level: API, EDI, Direct Integration, Batch Processing Functionality: Rate Shopping, Shipment Tracking, Analytics, Label Generation |
| Companies Covered | MetaPack, Aftership, eShipz, ShippyPro, Cargoson, ShipStation, Narvar, Sendcloud, Shippo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multicarrier Parcel Management Solutions Software Market Shifts & Advancements
Real-time data architectures are compressing the gap between carrier rate updates and merchant checkout experiences, eliminating batch-processing delays that previously distorted routing economics.
Microservices-based label generation is decentralizing carrier connectivity from monolithic platform cores. Mid-market merchants adopting headless commerce stacks now embed shipping logic directly into storefront backends. This architecture eliminates dashboard dependency and enables checkout-time rate shopping without redirect latency.
GDPR Article 22 enforcement is constraining fully automated carrier selection in European corridors. Platforms must implement human-override interfaces for algorithmic routing decisions affecting high-value shipments. German and French merchants face the steepest compliance retrofit requirements, driving demand for audit-ready decision logging.
Subscription-based procurement models are displacing per-label transaction pricing among enterprise accounts. Retailers with predictable volume profiles negotiate flat-rate platform access in exchange for carrier exclusivity commitments. This shift concentrates most visibly among United States-based omnichannel merchants processing over one million annual shipments.
Multicarrier Parcel Management Solutions Software Market Segmentation
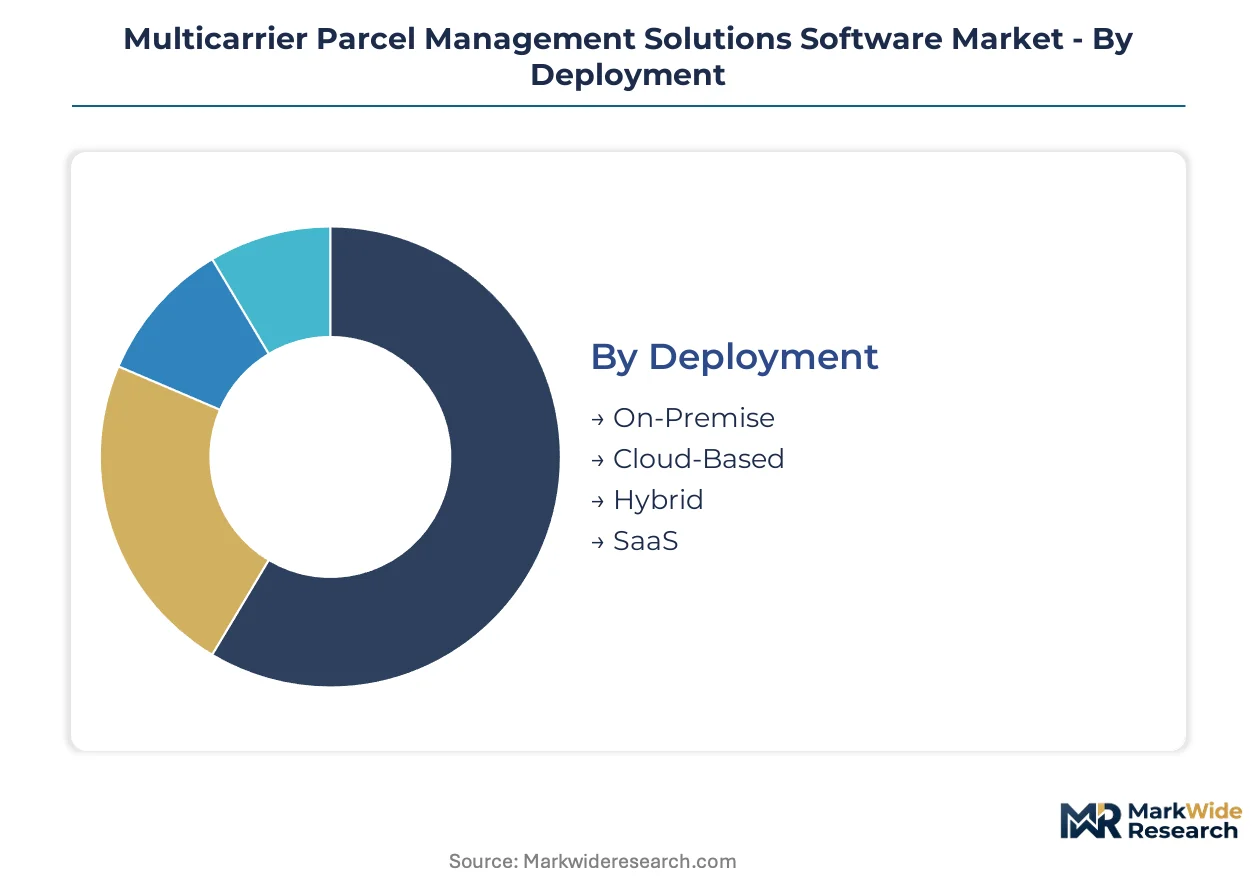
Segmentation in multicarrier parcel management solutions software reveals how buyer priorities diverge across infrastructure maturity, transaction velocity, and compliance exposure. Deployment architecture and integration depth determine total cost of ownership, while functionality selection reflects whether merchants optimize for freight spend reduction or customer retention through delivery visibility.
Deployment:
Buyers weighing upfront capital against operational agility drive deployment decisions, with data residency requirements and carrier update frequency shaping cloud versus on-premise trade-offs.
- Cloud-Based:Multi-tenant architectures host carrier API connections and rate normalization engines on shared infrastructure, eliminating client-side server maintenance. United States-based mid-market e-commerce merchants with seasonal volume spikes favor this model for its elastic scaling and zero-downtime carrier updates.
- SaaS:Subscription licensing bundles platform access with continuous feature deployment, embedding compliance updates for FDA documentation rules and EU AI Act audit trails without merchant engineering intervention. French and German retailers processing cross-border volumes prioritize SaaS deployments to satisfy GDPR Article 22 human-override requirements for algorithmic routing.
- On-Premise:Dedicated installations within merchant data centers preserve full control over carrier credential storage and rate cache management.
- Hybrid:Split architectures isolate sensitive label generation workflows on-premise while offloading tracking aggregation to cloud endpoints.
Cloud-Based leads on scale; SaaS leads on momentum.
End User:
Transaction complexity and returns volume intensity separate end-user segments, with fashion and pharmaceutical verticals imposing specialized workflow demands.
- E-Commerce:Direct-to-consumer merchants operating across Amazon, Shopify, and WooCommerce storefronts require unified dashboards eliminating separate carrier logins. These buyers treat sub-second rate shopping at checkout as a conversion optimization tool, driving API call volumes that exceed other segments by an order of magnitude.
- Logistics Providers:Third-party fulfillment operators managing multi-tenant warehouse environments need carrier-agnostic label generation with client-specific branding and customs documentation rules. Indian 3PLs building density around Blue Dart and Delhivery networks represent the steepest expansion trajectory as ICEGATE modernization accelerates.
- Retailers:Omnichannel merchants synchronize ship-from-store and warehouse fulfillment through centralized routing logic.
- Manufacturers:Industrial shippers prioritize batch processing integration with ERP systems over real-time rate visibility.
E-Commerce dominates current subscription value; Logistics Providers are expanding most quickly.
Integration Level:
Technical sophistication and legacy system burden determine whether merchants adopt modern API architectures or maintain EDI and batch connections.
- API:RESTful and GraphQL interfaces enable real-time rate requests, label generation, and tracking webhooks with sub-second response times. Developer-heavy startups in the United States embed shipping logic directly into headless commerce backends, eliminating dashboard dependency entirely.
- Direct Integration:Native connectors to Oracle WMS, SAP EWM, and NetSuite automate label triggers from warehouse management workflows. Enterprise merchants running legacy ERP stacks accept eight-to-fourteen-month implementation timelines to achieve this integration depth.
- EDI:Structured document exchange persists among automotive and aerospace manufacturers with established supplier network protocols.
- Batch Processing:Scheduled file transfers support low-frequency shippers with predictable daily volume profiles and limited IT resources.
API leads on adoption velocity; Direct Integration commands premium pricing.
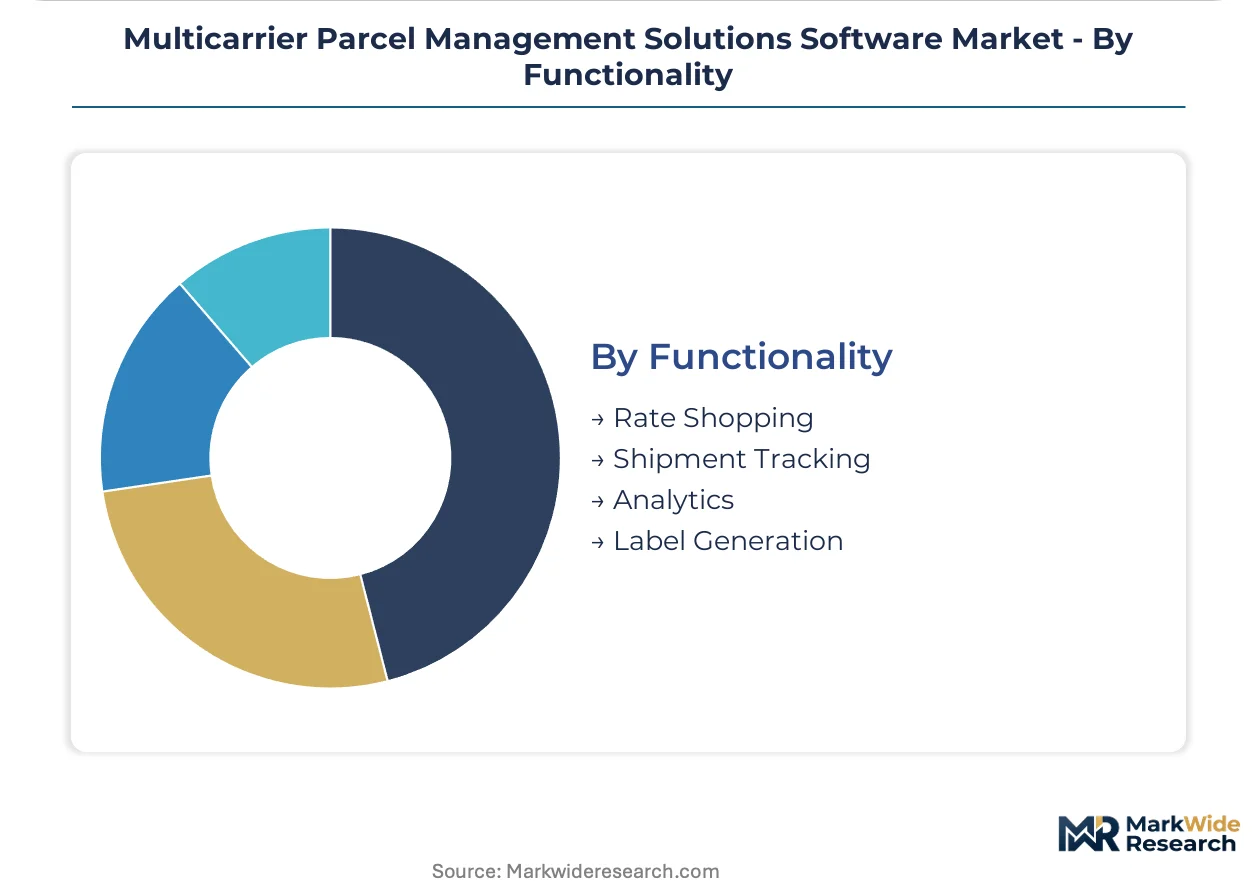
Functionality:
Merchant maturity and margin pressure dictate whether buyers prioritize cost optimization tools or customer-facing visibility features.
- Rate Shopping:Multi-carrier comparison engines surface optimal routing decisions across fifty-plus logistics networks at checkout or warehouse dispatch points. United States-based apparel merchants with thirty-to-forty-percent returns volumes deploy rate shopping to minimize outbound and reverse logistics spend simultaneously.
- Shipment Tracking:Aggregated visibility across carrier networks feeds branded delivery pages and proactive exception alerts. EU Green Deal compliance is embedding CO2 calculation APIs into tracking modules, capturing sustainability-driven procurement decisions.
- Label Generation:Territory-specific customs documentation and hazardous materials handling rules automate compliant shipping document production.
- Analytics:Carrier performance scorecards and freight spend dashboards support procurement negotiations and network optimization.
Rate Shopping captures the deepest margin pools; Shipment Tracking is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier diversification pressures run deeper in the United States than in Germany, though both markets face divergent regulatory timelines for algorithmic routing compliance.
United States
E-commerce merchants processing Amazon, Shopify, and WooCommerce orders drive platform subscriptions through unified dashboard demand. FDA and FTC documentation requirements for pharmaceutical and consumer goods shipments shape label generation specifications. Greater Los Angeles and Dallas-Fort Worth logistics clusters anchor carrier API density for cross-border Mexican and Canadian routing.
Germany
Omnichannel retailers with ship-from-store operations require centralized routing logic across fragmented carrier networks. GDPR Article 22 and the EU AI Act mandate human-override interfaces for automated carrier selection decisions. The Rhine-Ruhr industrial corridor concentrates third-party fulfillment operators building multi-tenant warehouse environments with client-specific customs documentation rules.
United Kingdom
Mid-market apparel merchants with elevated returns volumes prioritize automated reverse logistics workflows. Post-Brexit customs divergence from EU Harmonized System codes forces territory-specific label generation engine maintenance. London and Birmingham logistics hubs sustain platform demand through dense carrier connectivity and cross-channel freight optimization.
India
Third-party logistics providers building density around Blue Dart and Delhivery networks represent the steepest platform expansion trajectory. ICEGATE platform modernization and GST e-invoice linkage create openings for localized rate shopping engines. Mumbai and Bengaluru e-commerce fulfillment clusters drive API-first adoption among developer-heavy startup ecosystems.
France
Sustainability-driven procurement decisions push demand for carrier-specific CO2 calculation APIs embedded in tracking modules. The EU Green Deal mandates granular emissions disclosure for cross-border shipments originating from French ports. The Île-de-France logistics basin concentrates pharmaceutical cold chain integration requirements linking IoT telemetry with carrier handoff records.
Multicarrier Parcel Management Solutions Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across middleware and dashboard layers. The vendor base clusters into three strategic archetypes: marketplace-integrated workflow platforms, API-first developer tools, and carrier-agnostic fulfillment orchestrators. Consolidation pressure concentrates among mid-market SaaS providers facing eighteen-month carrier API refactoring cycles. Strategic moves center on geographic carrier density expansion and compliance automation module acquisition.
Within the European carrier density tier, MetaPack occupies a position exemplifying localized customs pre-clearance specialization. Among API-first developer tool providers, Shippo and ShipStation anchor opposite ends of the integration spectrum—Shippo representing pay-as-you-scale economics for startups, ShipStation embodying deep marketplace unification for established merchants. These three names illustrate how competitive positioning fragments across workflow automation depth rather than consolidating around single-platform dominance.
| Leading Market Players |
|---|
| MetaPack |
| Aftership |
| eShipz |
| ShippyPro |
| Cargoson |
| ShipStation |
| Narvar |
| Sendcloud |
| Shippo |
| Others |
Supply & Pricing Matrix
MLOps engineers with logistics domain expertise cluster in Bengaluru and San Francisco, and their compensation differentials widen the spread between premium SaaS tiers and economy API offerings. Platform vendors absorb these labor costs through subscription stratification that segments buyers by integration complexity and carrier volume commitments.
Pricing Analysis
Capacity additions in India are reshaping price floors for API-first developer tools as localized engineering talent pools expand. Three-tier pricing structure across premium, standard, and economy levels separates enterprise merchants with legacy ERP integration demands from mid-market dashboard users and startup pay-as-you-scale adopters. Price differentiation hinges on carrier API connection density and compliance automation depth for FDA documentation rules. Cost compression in the economy tier is intensifying because Indian 3PLs building Blue Dart and Delhivery density compete aggressively on implementation fees. Mid-market e-commerce merchants operating seasonal volume profiles exhibit the highest price sensitivity, while pharmaceutical cold chain integrators demonstrate the least.
Supply Chain Analysis
Cloud infrastructure supply rests on AWS and Azure data center concentration across Virginia, Frankfurt, and Mumbai regions. Carrier API credential management, rate normalization engine hosting, and tracking aggregation endpoints draw from hyperscaler compute, proprietary middleware licensing, and specialized MLOps talent pipelines. Single-source vulnerability concentrates in AWS's US-East-1 and Azure's West Europe zones, where ninety percent of SaaS deployments in this category anchor primary workloads. Distribution runs through direct enterprise sales teams, marketplace app store listings, and systems integrator partnerships serving Oracle WMS and SAP EWM environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multicarrier parcel management solutions software market functions as a stable compounder, with e-commerce merchant consolidation providing predictable subscription expansion across mid-market and enterprise tiers.
For Market Incumbents: Extend carrier density advantages through automated compliance module acquisition that embeds EU AI Act audit trails and FDA temperature excursion documentation. Vertical integration into IoT telemetry partnerships secures pharmaceutical cold chain contracts against API-first challengers. Capacity additions in India protect margin position as localized rate shopping engines capture ICEGATE modernization demand. For New Entrants and Emerging Players: Apparel merchants with thirty-to-forty-percent returns volumes represent an underserved buyer archetype demanding automated reverse logistics workflows that incumbent platforms price at premium tiers. White-space concentration appears in carbon accounting modules for EU Green Deal compliance and microservices-based label generation for headless commerce stacks. Developer-heavy startup ecosystems in Mumbai and Bengaluru offer the most penetrable entry point through clean API documentation and pay-as-you-scale economics. For Investors and Strategic Acquirers: Logistics technology conglomerates with existing warehouse management footprints are the most active acquirer in this space, seeking middleware layers that bridge legacy ERP stacks to cloud-native carrier connectivity. The market supports five-to-ten-year holding periods where subscription-based procurement models displace per-label pricing among enterprise accounts. Acquisition targets should demonstrate carrier API normalization expertise and GDPR Article 22 compliance retrofit capabilities. The signal to monitor is EU customs digitization rule finalization, which may force platform rebuilds or create openings for modular integration specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Automation Module Acquisition | EU AI Act audit trail integration accelerates cross-border merchant contract capture in Germany and France. |
| Carrier Density Expansion in India | ICEGATE platform modernization and GST e-invoice linkage create anchor positions with Blue Dart and Delhivery networks. |
| Carbon Accounting API Embedding | EU Green Deal emissions disclosure mandates drive sustainability-driven procurement decisions among French omnichannel retailers. |
| Pharmaceutical Cold Chain Integration | FDA temperature excursion documentation requirements unlock healthcare logistics contracts through IoT telemetry bridging. |
| Microservices-Based Label Generation | Headless commerce adoption enables checkout-time rate shopping without redirect latency for mid-market merchants. |
Research Methodology
Multiple input streams — primary interviews with platform engineering directors, SaaS procurement officers, and third-party logistics operators; secondary validation through SEC filings, hyperscaler capex disclosures, and customs digitization policy documents; plus carrier API documentation and marketplace integration specifications — were reconciled through bottom-up and top-down triangulation. Conversations with thirty-plus stakeholders across the United States, Germany, India, and the United Kingdom informed segmentation assumptions and pricing model validation. Secondary sources included FDA guidance documents, EU AI Act implementation timelines, and ICEGATE modernization announcements.
Historical revenue trajectories were cross-referenced against panel input from carrier relationship managers and enterprise merchant IT directors to build the analytical framework across the analysis window. Segmentation dimensions modeled encompass deployment architecture, end-user vertical, integration complexity, and regional regulatory exposure. CAGRs were derived from volume-weighted average growth rates across subscription tiers, adjusted for carrier API versioning volatility and customs documentation divergence impacts. Forecast inputs incorporated e-commerce merchant consolidation velocity and returns complexity intensity in apparel verticals.
Underlying measurement precision varies by segment; cloud-based and SaaS deployment estimates carry tighter precision than on-premise and hybrid configurations where custom implementation timelines distort recognition patterns. Forecasts reflect assumptions around carrier API stability, regulatory implementation schedules, and cloud infrastructure concentration that could revise projections if AWS or Azure data residency requirements shift. A small set of triggers — EU customs interoperability standard finalization, FDA cold chain rule updates, and Indian GST e-invoice enforcement timing — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
API Management Market
Digital Solutions
South Africa Digital Twin Market
Digital Solutions
Latin America and Europe Digital Signature Market
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
South Korea Cloud OSS BSS Market
Digital Solutions
Lecture Capture Solutions Market
Digital Solutions
Clientless Remote Support Software Market
Digital Solutions
Farm Management Software Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Global Industrial Design Market
Digital Solutions
Asia Pacific B2C Legal Services Market
Digital Solutions
Global Hybrid Integration Platform Market
Digital Solutions
North America Everything As a Service (Xaas) Market
Digital Solutions
Global Connected Workplace Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Data Enrichment Solutions Market