
 EHS Software Market | 2026-2036
EHS Software Market Size, Share, and Industry Trends Forecast 2026-2036
EHS Software Market Analysis
Market Context
A shortage of certified EHS data analysts is reorganizing how enterprises select software partners, pushing buyers toward platforms with embedded analytics and automated reporting. VelocityEHS leverages cloud-native architecture to capture mid-market manufacturers seeking rapid deployment without dedicated IT staff. Sphera anchors its position through deep chemical industry expertise and process safety integration. Intelex competes on configurability, allowing large industrials to tailor incident management workflows across multinational operations.
Technical Definition and Segment Structure
EHS software encompasses integrated digital platforms that collect, analyze, and report environmental emissions data, occupational health records, safety incident logs, and regulatory compliance documentation through standardized dashboards and automated workflows. These systems typically integrate IoT sensor feeds, mobile inspection tools, and API-connected ERP modules to enable real-time hazard detection and audit trail generation. Cloud-based deployment leads the market as energy and chemical buyers prioritize remote accessibility and reduced infrastructure overhead, while on-premises solutions retain share among defense contractors and critical infrastructure operators with air-gapped security requirements. Compliance Management commands the largest revenue pool due to the complexity of multi-jurisdictional reporting, though Safety Management represents the fastest expansion trajectory as construction and transportation end users mandate near-miss tracking and predictive risk modeling.
Regulatory Framework and Outlook
OSHA recordkeeping rules, EPA Clean Air Act reporting mandates, and EU REACH compliance deadlines shape software feature roadmaps and sales cycles across North America and Europe. The SEC climate disclosure requirements and CSRD sustainability reporting standards are forcing cross-functional integration between EHS platforms and financial reporting systems. Stakeholders must monitor how emerging AI audit capabilities reshape regulatory expectations for data accuracy and response velocity.
Market Dynamics
Regulatory enforcement intensification across the United States, Germany, and China is compressing enterprise software procurement cycles as compliance deadlines force rapid platform selection. Buyers now prioritize embedded analytics and automated reporting capabilities over customization depth.
Growth Catalysts
- OSHA Recordkeeping Modernization:Revised electronic submission requirements for injury and illness data are mandating real-time dashboard capabilities across manufacturing and construction sectors.
- Energy Sector Carbon Tracking:Oil and gas operators are deploying integrated EHS platforms to unify emissions monitoring with operational safety systems ahead of tightening EPA methane rules.
- Cloud-Native Architecture Adoption:Mid-market manufacturers without dedicated IT staff are accelerating SaaS deployments to achieve rapid implementation and remote accessibility.
Market Restraints
- Certified EHS Data Analyst Shortage:The scarcity of qualified professionals capable of configuring analytics modules is extending implementation timelines and inflating professional services costs.
- On-Premises Infrastructure Lock-In:Defense contractors and critical infrastructure operators with air-gapped security requirements face high switching costs when migrating to cloud architectures.
- Multi-Jurisdictional Reporting Complexity:Divergent state-level OSHA plan variations and EU member state REACH implementations create persistent compliance friction for multinational deployments.
Strategic Opportunities
- CSRD Sustainability Integration:The EU Corporate Sustainability Reporting Directive is creating demand for EHS platforms that feed directly into financial disclosure systems.
- Predictive Risk Modeling:Construction and transportation end-users are expanding near-miss tracking capabilities into AI-driven hazard prediction modules.
- IoT Sensor Convergence:Integration between wearable safety devices and environmental monitoring hardware is opening new subscription revenue streams for platform vendors.
Industry Challenges
- Legacy ERP Integration Complexity:Large industrials struggle to synchronize incident management workflows with decades-old SAP and Oracle systems without custom API development.
- Mobile Inspection Tool Standardization:Field teams using heterogeneous device ecosystems create data quality inconsistencies that undermine audit trail integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EHS Software Market |
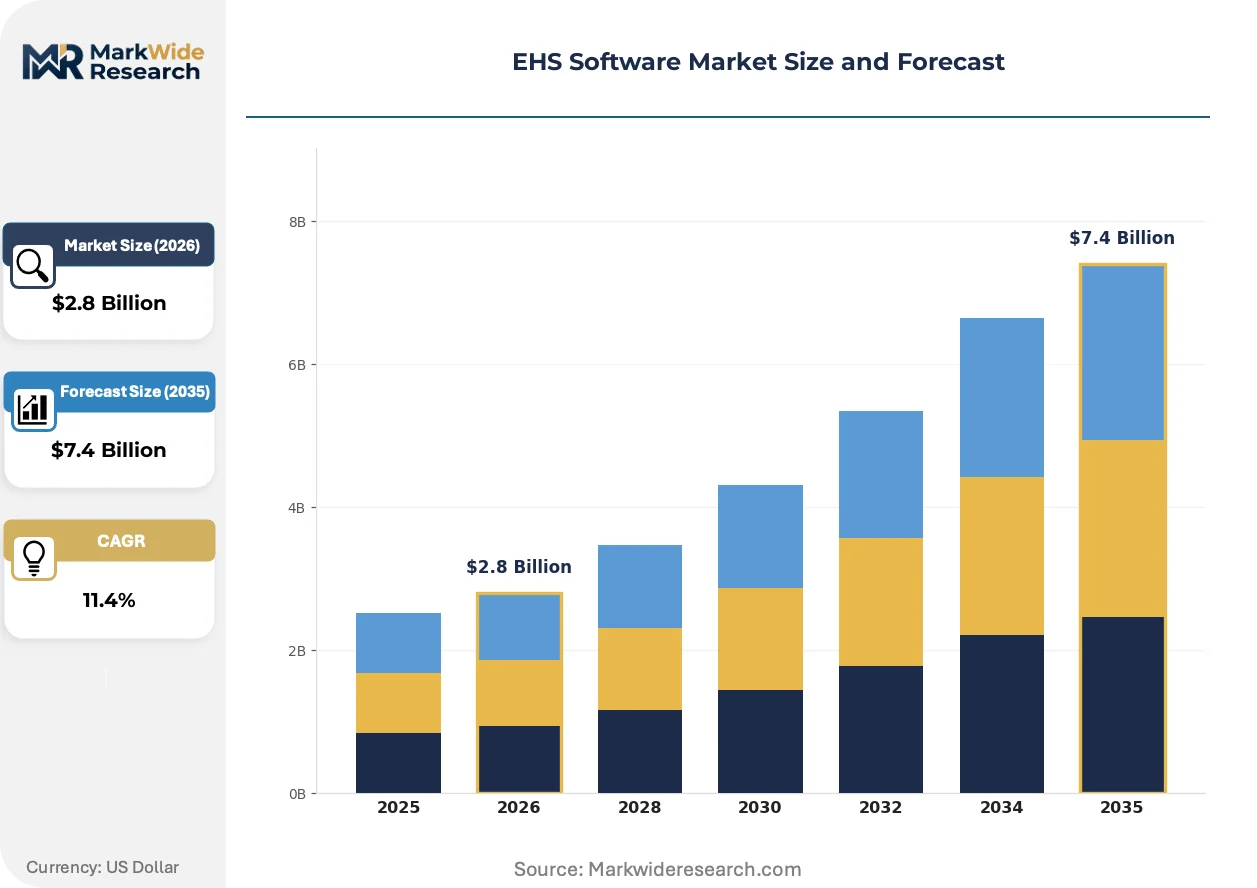
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Environmental Management, Health Management, Safety Management, Compliance Management Deployment: Cloud-based, On-premises, Hybrid, SaaS End User: Manufacturing, Construction, Energy, Transportation Industry Vertical: F&B, Chemicals, Pharmaceuticals, Utilities |
| Companies Covered | Enablon, Gensuite, VelocityEHS, KPA EHS, ETQ Reliance, Intelex, EcoOnline, Sphera, Cority, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EHS Software Market Emerging Trajectories
Artificial intelligence capabilities are compressing the gap between data collection and actionable safety interventions across industrial workflows. Platform vendors are racing to embed predictive models that anticipate regulatory violations before they trigger penalties.
Edge computing architectures for industrial IoT are miniaturizing the hardware footprint required for real-time environmental monitoring. Chemical plant operators in Texas and Louisiana are deploying compact sensor arrays that stream directly to cloud dashboards without on-site server infrastructure. This is miniaturizing the capital barrier to entry for continuous emissions monitoring and displacing periodic manual sampling regimes.
The SEC climate disclosure requirements are forcing cross-functional collaboration between EHS and finance departments. Publicly traded manufacturers must now source Scope 1 and Scope 2 emissions data through auditable software trails rather than spreadsheet estimates. Energy sector buyers in the United States are responding by mandating API connectivity between EHS platforms and ERP general ledger modules.
Enterprise buying committees are consolidating vendor relationships to reduce integration overhead. Procurement teams at multinational industrials now require single-platform coverage across environmental, safety, and occupational health functions. This consolidation pattern is most visible in Germany's automotive supply chain, where Tier 1 suppliers are phasing out point solutions in favor of unified compliance suites.
EHS Software Market Segmentation
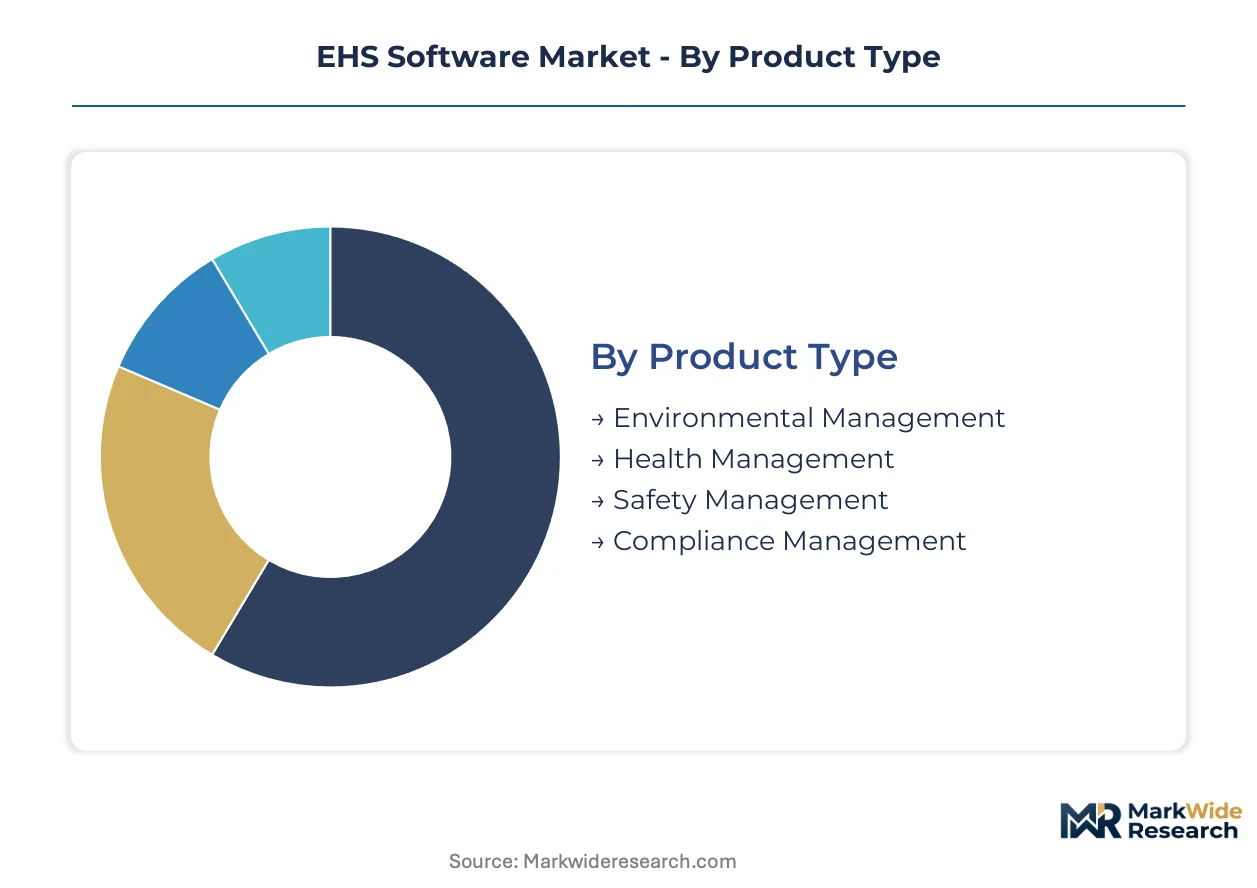
Segmentation in EHS software reveals how procurement priorities diverge across operational contexts. Buyers select platforms based on regulatory exposure, IT infrastructure constraints, and the specific hazards governing their physical operations.
Product Type:
Margin pools concentrate in modules that reduce regulatory penalty exposure and audit preparation labor.
- Compliance Management:Platforms automate multi-jurisdictional reporting workflows for OSHA, EPA, and EU REACH obligations. Energy sector buyers in Texas and Louisiana prioritize these modules to preempt methane rule violations and streamline audit documentation.
- Safety Management:Systems capture near-miss incidents, conduct job hazard analyses, and trigger corrective action workflows. Construction firms across Germany's industrial belt are mandating predictive risk modeling capabilities to reduce lost-time injury rates on complex infrastructure projects.
- Environmental Management:Modules track emissions inventories, waste streams, and water discharge permits with sensor-fed data validation.
- Health Management:Platforms manage occupational exposure records, medical surveillance schedules, and industrial hygiene sampling results.
The dominant share belongs to Compliance Management, while Safety Management is closing the gap fastest.
Deployment:
Architecture choices reflect IT staffing levels and data sovereignty requirements rather than feature differentiation.
- Cloud-based:SaaS architectures eliminate server maintenance burdens and enable remote access for distributed workforces. Mid-market manufacturers in China's Pearl River Delta are adopting these deployments to bypass dedicated IT hiring.
- SaaS:Subscription models bundle automatic updates and security patching into predictable operating expenditures. Chemical processors in Germany's Ruhr region favor SaaS for rapid implementation across acquired facilities.
- On-premises:Air-gapped installations serve defense contractors and critical infrastructure operators with classified or isolated network requirements.
- Hybrid:Configurations split sensitive data storage locally while pushing analytics processing to cloud environments.
Cloud-based deployments command the installed base, though SaaS is expanding most quickly among new implementations.
End User:
Procurement authority varies sharply—energy buyers centralize decisions at headquarters while construction purchasing fragments across project sites.
- Energy:Oil and gas operators require unified platforms spanning upstream extraction through downstream refining. US Gulf Coast operators are integrating carbon tracking with process safety systems ahead of tightening EPA methane regulations.
- Manufacturing:Automotive and electronics producers demand configurability across multinational plant networks with divergent local compliance obligations.
- Construction:Project-based workflows create demand for mobile-first inspection tools and subcontractor compliance verification.
- Transportation:Fleet operators prioritize driver safety monitoring and hazardous materials documentation for cross-border movements.
Energy verticals anchor current revenue, with Manufacturing gaining share fastest through automotive supply chain consolidation.
Industry Vertical:
Regulatory stringency and penalty severity determine willingness-to-pay across vertical applications.
- Chemicals:Process safety management and toxic substance tracking dominate software requirements. Louisiana and Texas petrochemical corridors are deploying edge-computing sensor arrays that stream directly to cloud dashboards for continuous emissions monitoring.
- Pharmaceuticals:FDA 21 CFR Part 11 compliance for electronic records drives validation-intensive platform selections with extensive audit trail capabilities.
- Utilities:Electric and gas distribution operators integrate EHS platforms with SCADA systems to manage worker safety around energized equipment.
- F&B:Food and beverage processors prioritize occupational health modules for allergen exposure monitoring and sanitation chemical handling.
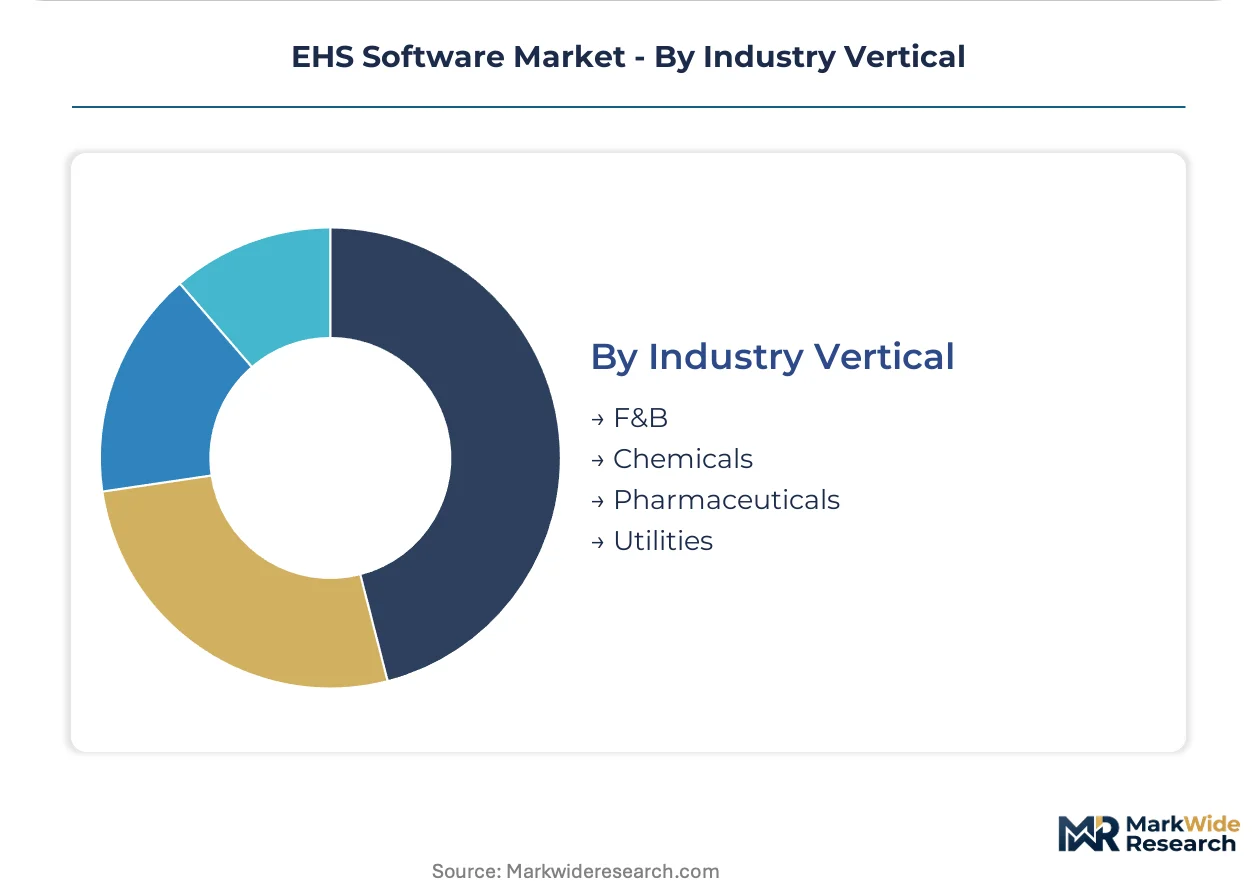
Chemicals verticals retain the deepest penetration, while Pharmaceuticals shows the steepest expansion trajectory on regulatory validation demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Energy buyers in the United States deploy EHS platforms for carbon tracking and incident reporting, while German manufacturers prioritize configurability across multinational plant networks. Chinese industrial clusters digitize safety workflows without dedicated IT staff, creating divergent procurement patterns across major economies.
United States
OSHA electronic submission mandates and EPA methane rule tightening drive platform upgrades across manufacturing and oil and gas sectors. The SEC climate disclosure requirements force API connectivity between EHS systems and ERP general ledger modules. Gulf Coast petrochemical operators in Texas and Louisiana deploy edge-computing sensor arrays for continuous emissions monitoring.
Germany
Automotive supply chain consolidation pushes Tier 1 suppliers toward unified compliance suites covering environmental, safety, and occupational health functions. EU REACH compliance deadlines and CSRD sustainability reporting standards shape software feature roadmaps. Industrial clusters in Bavaria and Baden-Württemberg mandate predictive risk modeling for construction infrastructure projects.
China
Mid-market manufacturers in the Pearl River Delta adopt cloud-native SaaS deployments to bypass dedicated IT hiring constraints. MEE emissions monitoring requirements and dual carbon goals accelerate platform procurement. Yangtze River Delta chemical processors integrate environmental management modules with operational safety systems.
United Kingdom
Financial services and pharmaceutical firms drive demand for audit trail capabilities aligned with FDA 21 CFR Part 11 validation standards. HSE enforcement patterns influence safety management module prioritization. London and Southeast England host EHS software vendor development centers serving European multinational clients.
India
Manufacturing expansion in Maharashtra and Gujarat creates demand for mobile-first inspection tools and subcontractor compliance verification. Factory Act compliance obligations and state-level pollution control board reporting requirements shape platform selection. Karnataka's technology corridor attracts SaaS vendors targeting mid-market industrial digitization.
EHS Software Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with differentiation hinging on industry-specific workflow depth versus cross-functional platform breadth. The upper tier commands premium pricing through embedded analytics and automated regulatory reporting, while specialists capture niche segments with tailored hazard management tools. Three archetypes dominate: cloud-native generalists targeting rapid mid-market deployment, chemical industry experts with process safety integration, and configurability-focused vendors serving multinational industrials. Consolidation pressure intensifies as procurement teams mandate single-platform coverage, driving strategic partnerships between sensor hardware manufacturers and software platforms.
Within the integrated platform tier, VelocityEHS exemplifies cloud-native architecture adoption, Sphera anchors chemical sector specialization, and Intelex occupies the configurability position for large multinational deployments. These three vendors represent contrasting strategic bets on how enterprise buyers balance implementation speed against customization depth. VelocityEHS captures manufacturers without dedicated IT staff through SaaS delivery models. Sphera's positioning reflects deep process safety expertise in toxic substance tracking. Intelex serves automotive and electronics producers requiring tailored incident management workflows across divergent local compliance obligations. The competitive dynamic between these archetypes determines pricing power and customer retention patterns across end-user segments.
| Leading Market Players |
|---|
| Enablon |
| Gensuite |
| VelocityEHS |
| KPA EHS |
| ETQ Reliance |
| Intelex |
| EcoOnline |
| Sphera |
| Cority |
| Others |
Supply Flow & Price Mechanics
OSHA electronic submission mandates and EPA methane rule compliance deadlines gate both vendor qualification and price differentiation simultaneously, forcing buyers to pay premiums for platforms with pre-validated reporting modules while squeezing mid-market providers lacking embedded analytics.
Pricing Analysis
Long-term SaaS subscriptions dominate contract structures, with three-tier pricing separating enterprise configurability from mid-market rapid-deployment packages and basic compliance-only tiers. Price differentiation rests on ISO 27001 certification status and vertical-specific workflow depth, particularly for chemical process safety integration. Cost compression in the mid-market tier is intensifying because cloud-native entrants are undercutting legacy on-premises providers. Small manufacturers in China's Pearl River Delta exhibit highest price sensitivity, while Gulf Coast petrochemical operators show lowest sensitivity due to penalty avoidance value.
Supply Chain Analysis
Just-in-time implementation models prevail among SaaS vendors, though strategic stockpiling of certified implementation partners occurs ahead of major regulatory deadlines. Software development concentrates in the United States, Germany, and India, with cloud infrastructure drawing from hyperscaler networks anchored in Virginia, Frankfurt, and Singapore. The supply chain rests on API interoperability with SAP and Oracle ERP systems, creating single-source vulnerability where legacy integration specialists dominate. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for multinational deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial intelligence audit capabilities are compressing procurement cycles and reshaping competitive positioning, as buyers prioritize predictive analytics over customization depth.
For Market Incumbents: Compound platform stickiness through backward integration into IoT sensor hardware partnerships, capturing subscription revenue streams from wearable safety devices. Invest in FDA 21 CFR Part 11 validation capabilities to defend against cloud-native entrants targeting pharmaceutical white space. Prioritize API development resources for SAP and Oracle ERP synchronization, addressing the legacy integration bottleneck that delays enterprise deployments.
For New Entrants and Emerging Players: Anchor in mid-market manufacturing verticals in India and Southeast Asia, where Factory Act compliance digitization lags and price sensitivity favors SaaS rapid-deployment models. Target construction safety management modules with mobile-first inspection tools, exploiting fragmentation among project-based purchasing committees. Pursue channel partnerships with industrial equipment distributors to bypass direct sales infrastructure requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment architectures, enabling asset-light scaling and improving return thresholds. Focus acquisition screening on chemical industry specialists with REACH compliance expertise and embedded process safety workflows. Watch for inflection when SEC climate disclosure enforcement triggers mandatory ERP-EHS integration demand among publicly traded manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connectivity with SAP and Oracle ERP modules addresses legacy system bottlenecks delaying enterprise procurement. |
| Acquisition of Specialist Firm | Chemical process safety expertise from Louisiana and Texas corridors accelerates REACH compliance module development. |
| Strategic Partnership | IoT sensor hardware alliances with wearable safety device manufacturers unlock recurring subscription revenue streams. |
| Product Launch | AI-driven predictive risk modeling targets construction and transportation near-miss tracking requirements in Germany. |
| Geographic Expansion | Cloud-native SaaS deployment in India's Maharashtra and Gujarat manufacturing corridors bypasses IT hiring constraints. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, EPA enforcement databases, EU REACH registration data, and hyperscaler capex disclosures. Interviews with EHS software procurement officers, plant safety directors, regulatory compliance leads, and systems integration specialists informed demand-side validation. Bottom-up deployment counts across cloud and on-premises architectures triangulate against top-down vendor revenue segmentation.
Segmentation dimensions modeled span deployment architecture, organization size tier, vertical industry application, integration complexity level, and regional regulatory cluster. CAGRs derive from installation base expansion rates and average revenue per account trajectories across the projection horizon. Forecast inputs incorporate OSHA electronic submission mandate timelines and CSRD sustainability reporting phase-in schedules.
Material uncertainties — regulatory enforcement intensity variations, AI audit standard emergence, and legacy ERP migration pace — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued cloud adoption preference and mid-market IT staffing constraints. Revision becomes warranted when EPA methane rule enforcement crosses thresholds triggering accelerated platform replacement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
Harbor Management Software Market
Digital Solutions
Application Performance Management Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Tablet Based E-Detailing Market
Digital Solutions
Revops Platform Market
Digital Solutions
Business Transcription Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Docketing Solution Market
Digital Solutions
North America Digital Pen Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Australia Cloud OSS BSS Market
Digital Solutions
Transit Station Display Board Market
Digital Solutions
Healthcare Computerized Maintenance Management System Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
Weather App Market