
 Global Thermodilution Catheter Market | 2026-2036
Global Thermodilution Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermodilution Catheter Market Foresight
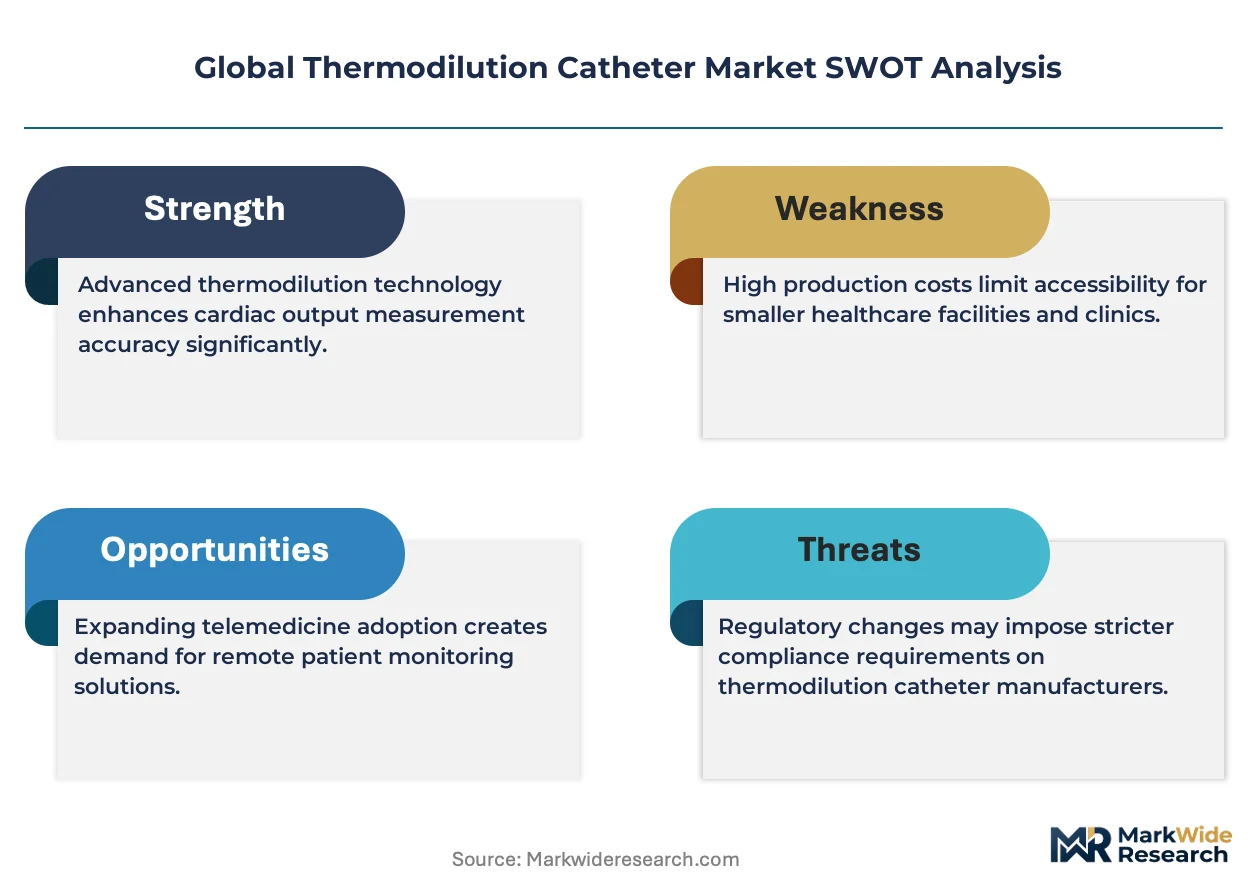
EU MDR is broadening the cost-of-entry calculus for thermodilution catheter manufacturers seeking CE marking. Edwards Lifesciences leverages its hemodynamic monitoring heritage to sustain premium positioning across integrated platforms. B. Braun Melsungen AG anchors European supply chains through vertically controlled manufacturing of disposable cardiac catheters. Teleflex Incorporated competes on global scale with specialized pulmonary artery catheter portfolios.
A thermodilution catheter is a flexible, multi-lumen vascular device typically manufactured from polyurethane or PVC with an inflatable balloon tip and temperature-sensing thermistor; it measures cardiac output via the Stewart-Hamilton equation by detecting blood temperature changes after cold saline injection. The primary commercial purpose is real-time hemodynamic assessment during cardiac surgery and critical care management. Balloon thermodilution configurations occupy the mature volume tier due to decades of clinical validation, while fiber optic variants represent the fastest-growing segment as hospitals demand continuous monitoring without manual bolus injections. Critical care units generate the deepest margin pools among end users because of high procedure frequency and bundled device-consumable contracts.
FDA premarket notification requirements, EU MDR technical documentation mandates, and Japan's PMDA quality management standards collectively shape product development timelines and sterilization validation protocols for manufacturers. ISO 10993 biocompatibility testing and IEC 60601 electrical safety standards add parallel compliance layers that filter smaller entrants from premium segments. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA digital health pre-certification pathways as these determine speed-to-market for next-generation integrated monitoring platforms.
Market Dynamics
EU MDR notified body capacity constraints are compressing CE marking timelines for thermodilution catheter manufacturers, forcing portfolio rationalization and accelerated sterilization validation investments ahead of 2027 certificate expiry waves.
Growth Catalysts
- Aging demographics:Japan, Germany, and the United States report expanding cardiac surgery volumes as populations over 65 require hemodynamic monitoring during critical interventions.
- EU MDR compliance deadlines:Manufacturers accelerating technical documentation submissions ahead of certificate renewals are driving near-term catheter inventory builds across European hospital supply chains.
- Fiber optic thermodilution:Continuous cardiac output monitoring without manual saline bolus injections is displacing intermittent balloon catheter protocols in high-acuity surgical suites.
Market Restraints
- Polyurethane resin volatility:Medical-grade catheter material costs fluctuate with petrochemical feedstock markets, squeezing gross margins for disposable device manufacturers.
- Notified body concentration:Only 12 EU MDR-designated bodies currently handle Class III cardiovascular devices, creating bottlenecks for new market entrants seeking CE marking.
- Pressure transducer substitution:Arterial line waveform analysis and non-invasive cardiac output monitors are capturing low-acuity monitoring volumes previously served by pulmonary artery catheters.
Strategic Opportunities
- India cardiac centers:Private hospital chains in Mumbai, Delhi, and Chennai are installing hybrid operating suites requiring integrated hemodynamic monitoring platforms.
- Japan PMDA pre-market consultation:Early engagement pathways for novel catheter designs reduce time-to-approval for manufacturers targeting the world's third-largest cardiac device market.
- Disposable-sensor bundling:Single-use thermistor-equipped catheter kits paired with multi-parameter monitors are capturing recurring revenue streams in US critical care contracts.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization studies face 6-9 month backlogs at contract laboratories, delaying sterilization validation for new catheter formulations.
- Legacy monitor integration:Fiber optic catheters require proprietary interface modules incompatible with installed base hemodynamic monitors across hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermodilution Catheter Market |
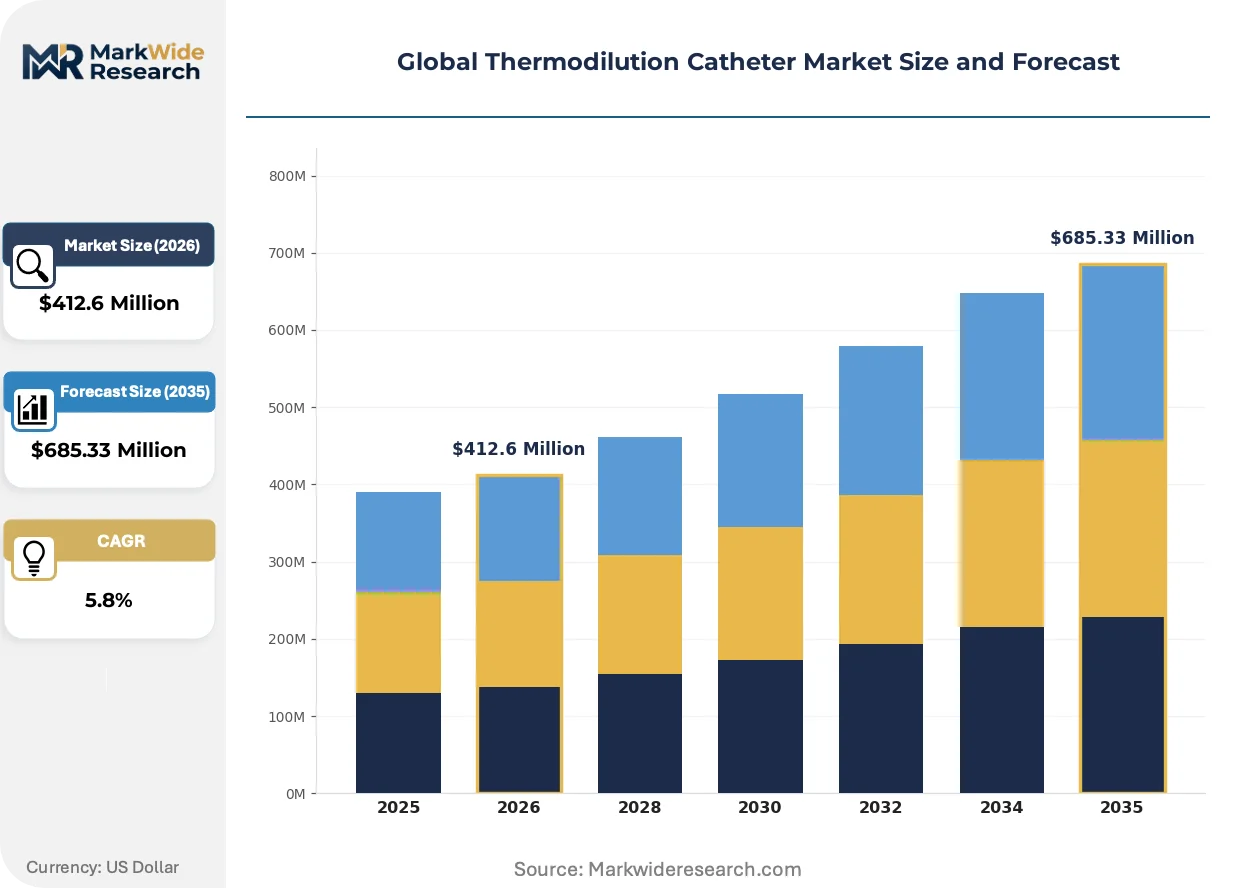
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Thermodilution, Piezoelectric Thermodilution, Ultrasound Thermodilution, Fiber Optic Thermodilution Therapy Area: Cardiac Output Monitoring, Pulmonary Artery Pressure, Hemodynamic Management, Critical Care Management End User: Critical Care Units, Cardiac Surgery Centers, Ambulatory Care Facilities, Research Laboratories Deployment: Single Use, Reusable, Standalone Systems, Integrated Monitoring Platforms |
| Companies Covered | DeRoyal Industries, B. Braun Melsungen AG, Edwards Lifesciences, Aesculap, Alpha Medical Instruments LLC, Teleflex Incorporated, Merit Medical Systems Inc, Argon Medical Devices, ICU Medical Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermodilution Catheter Market Shifts & Advancements
Continuous monitoring modalities and regulatory data requirements are compressing product development cycles while elevating sensor integration complexity across next-generation catheter platforms.
Closed-loop thermodilution systems incorporating automated saline injectors and real-time cardiac output algorithms are rewriting hemodynamic workflow protocols in cardiac surgery departments. Leading academic medical centers in Boston, Heidelberg, and Tokyo are piloting these platforms to eliminate manual measurement variability. The technology is compressing staffing requirements per procedure while demanding upgraded central monitoring infrastructure.
EU MDR Annex XIV post-market surveillance mandates now require systematic clinical follow-up data for Class III cardiovascular devices. Manufacturers must establish PMCF study protocols capturing real-world catheter performance across diverse hospital settings. High-volume implanting centers in France, Germany, and Italy face expanded documentation burdens that favor larger suppliers with dedicated clinical affairs teams.
Hospital procurement committees are consolidating catheter purchasing through integrated delivery networks spanning multiple surgical service lines. Standalone cardiac catheter orders are giving way to multi-year hemodynamic monitoring platform agreements bundling devices, disposables, and software subscriptions. This concentration is most pronounced in US health systems where IDN purchasing controls access to 340B-eligible cardiac centers.
Global Thermodilution Catheter Market Segmentation
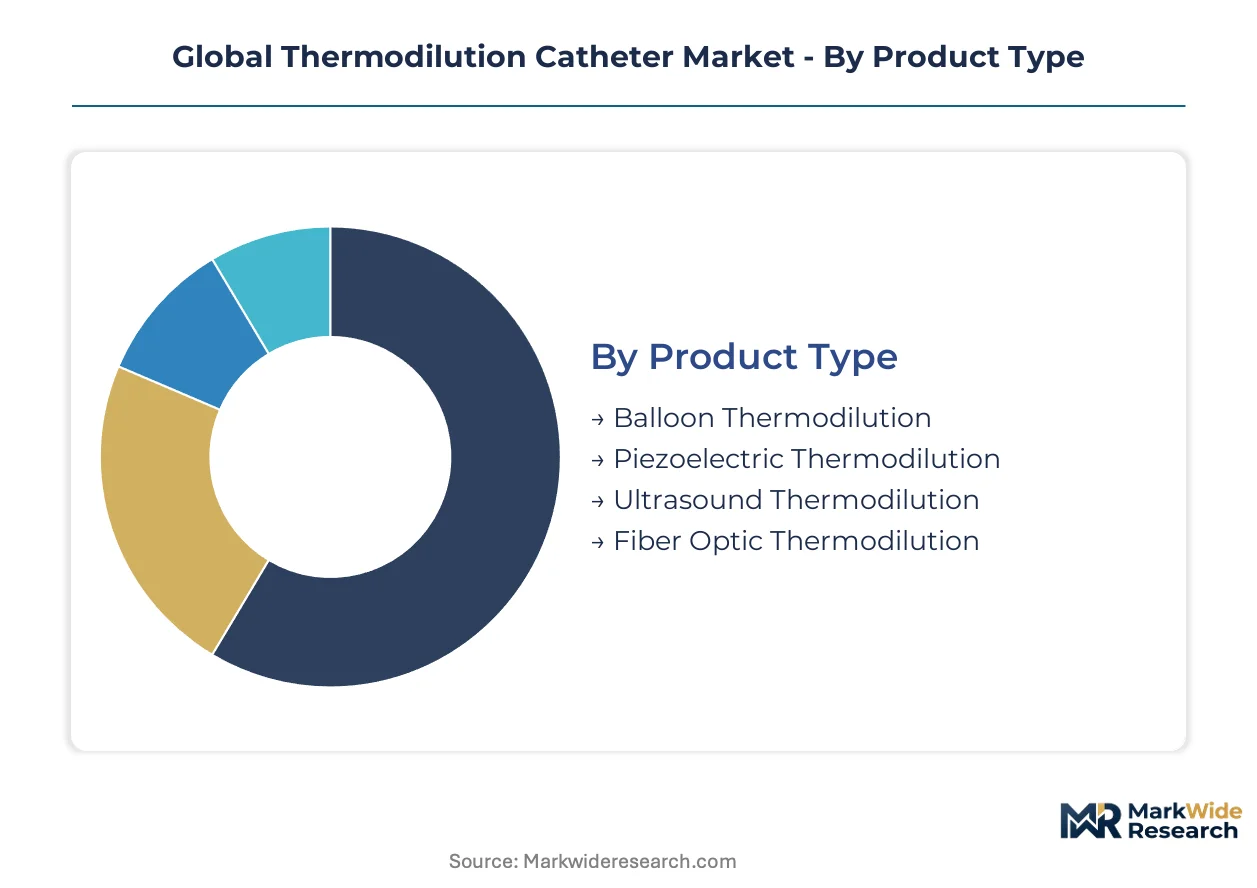
Thermodilution catheter procurement varies sharply across clinical settings, with material specifications and connectivity requirements driving divergent margin structures. Manufacturers must align R&D investments with the specific validation protocols each segment demands.
Product Type:
Supply concentration in balloon catheter production has created manufacturing scale advantages for established polyurethane processors, while fiber optic assembly requires specialized optical fiber splicing capabilities concentrated in precision electronics clusters.
- Balloon Thermodilution:Polyurethane or PVC construction with inflatable distal balloon and thermistor bead for temperature sensing. Demand clusters in United States academic medical centers performing high-volume cardiac surgery, constrained by EU MDR sterilization validation timelines for legacy device families.
- Fiber Optic Thermodilution:Continuous cardiac output monitoring via fiber optic pressure-temperature sensors embedded in catheter wall. German and Japanese cardiac surgery departments are displacing intermittent bolus methods with these systems, drawn by reduced nursing workload and elimination of cold saline injection errors.
- Piezoelectric Thermodilution:Crystal-based flow detection with minimal thermal mass.
- Ultrasound Thermodilution:Doppler-enhanced measurement for low-flow states.
Today's leader: Balloon Thermodilution. Tomorrow's challenger: Fiber Optic Thermodilution.
Therapy Area:
Cost tier differentiation separates high-acuity hemodynamic management from routine cardiac output screening, with reimbursement codes in Germany and Japan directly linking procedure complexity to device reimbursement ceilings.
- Cardiac Output Monitoring:Perioperative assessment using Stewart-Hamilton equation calculations. United States cardiac surgery centers generate concentrated demand through bundled payment contracts that favor disposable catheter protocols over capital equipment alternatives.
- Hemodynamic Management:Integrated pressure-flow-volume optimization in shock states. French and Italian critical care networks are expanding adoption of continuous monitoring platforms for septic shock protocols, constrained by intensive care nursing shortage and automation requirements.
- Pulmonary Artery Pressure:Right heart catheterization for heart failure stratification.
- Critical Care Management:Multi-parameter monitoring in intensive care settings.
Cardiac Output Monitoring commands current volume leadership. Hemodynamic Management is climbing the fastest as closed-loop automation penetrates European surgical suites.
End User:
Customer type fragmentation creates divergent purchasing modalities, with critical care units negotiating consumable contracts while cardiac surgery centers prioritize platform integration over per-device economics.
- Critical Care Units:High-frequency hemodynamic assessment in medical intensive care. United States health systems with 340B eligibility are consolidating purchasing through integrated delivery networks spanning multiple hospitals, favoring suppliers with national distribution infrastructure.
- Cardiac Surgery Centers:Perioperative monitoring in open-heart and minimally invasive procedures. Private hospital chains in Mumbai, Delhi, and Chennai are installing hybrid operating suites requiring thermodilution catheter compatibility with multi-parameter monitors from Edwards Lifesciences and Getinge.
- Ambulatory Care Facilities:Limited hemodynamic screening in outpatient settings.
- Research Laboratories:Investigational device protocols and clinical trials.
Critical Care Units anchor current revenue concentration. Cardiac Surgery Centers in emerging markets represent the steepest expansion trajectory.
Deployment:
Maturity gradients separate established single-use disposables from emerging integrated platform architectures, with regulatory pathways in Japan and the United States diverging sharply for reusable device reprocessing claims.
- Single Use:Sterile disposable catheters with pre-connected transducer kits. German hospital procurement committees are mandating single-use protocols for pulmonary artery catheterization to eliminate cross-contamination risk in multidrug-resistant organism outbreaks.
- Integrated Monitoring Platforms:Catheter-sensor-monitor bundles with proprietary data interfaces. United States health systems are locking into multi-year agreements combining devices, software subscriptions, and remote technical support, displacing standalone catheter purchasing.
- Reusable:Limited reprocessing for research and veterinary applications.
- Standalone Systems:Catheter-transducer combinations without central monitoring integration.
Single Use maintains volume dominance. Integrated Monitoring Platforms are gaining share fastest as IDN procurement consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac surgery specialists cluster in tertiary medical centers across Germany, Japan, and the United States, anchoring demand for advanced hemodynamic monitoring platforms. Regulatory pathways in these markets filter device approvals through divergent technical documentation requirements. Manufacturing and clinical validation activities concentrate in metropolitan hospital networks with established cardiac surgery volumes.
United States
Academic medical centers in Boston and New York Metro drive demand for continuous cardiac output monitoring during complex valve replacement procedures. FDA premarket notification pathways for Class II cardiovascular devices require 510(k) submissions with predicate device comparisons. Hybrid operating suite installations at Cleveland Clinic and Mayo Clinic Rochester anchor procurement of integrated catheter-monitor bundles.
Germany
University hospitals in Heidelberg and Berlin expand adoption of fiber optic thermodilution systems for septic shock management in surgical intensive care. EU MDR technical documentation mandates for Class III cardiovascular devices compress CE marking timelines through 2027 certificate renewals. The Baden-Württemberg medical technology corridor hosts sterilization validation facilities serving catheter manufacturers across Central Europe.
Japan
Aging cardiac surgery volumes in Tokyo and Osaka metropolitan areas sustain demand for precision hemodynamic assessment during open-heart procedures. PMDA quality management standards require pre-market consultation for novel catheter designs with continuous monitoring capabilities. The Kansai region's medical device cluster supports domestic assembly of thermistor-equipped disposable catheters.
India
Private hospital chains in Mumbai and Delhi install hybrid cardiovascular suites requiring thermodilution catheter compatibility with multi-parameter monitoring platforms. CDSCO medical device registration rules mandate local clinical investigation data for Class C and D cardiovascular devices. Chennai's medical tourism corridor attracts cardiac surgery patients from Southeast Asia and the Middle East, expanding procedure volumes.
United Kingdom
NHS England specialized commissioning frameworks concentrate cardiac surgery in London and Manchester tertiary centers with dedicated perfusion teams. MHRA post-market surveillance requirements align with EU MDR transitional provisions for legacy device certificates. The Oxford-Cambridge healthcare innovation arc pilots closed-loop hemodynamic monitoring systems in academic hospital partnerships.
Global Thermodilution Catheter Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions in thermodilution catheter supply. Three structural archetypes dominate: integrated hemodynamic monitoring platform vendors, disposable cardiovascular device manufacturers with captive sterilization capacity, and specialty catheter producers serving niche procedural applications. Competitive moves concentrate on strategic partnerships with monitor manufacturers and accelerated MDR technical documentation investments ahead of 2027 regulatory deadlines.
Among diversified medical technology conglomerates, B. Braun Melsungen AG exemplifies European supply chain anchoring through vertically controlled manufacturing infrastructure. Edwards Lifesciences occupies a position representing integrated platform specialization, with heritage in hemodynamic monitoring systems spanning decades of cardiac surgery application. Teleflex Incorporated sits within the specialty catheter tier, competing through pulmonary artery catheter portfolios with global distribution reach.
| Leading Market Players |
|---|
| DeRoyal Industries |
| B. Braun Melsungen AG |
| Edwards Lifesciences |
| Aesculap |
| Alpha Medical Instruments LLC |
| Teleflex Incorporated |
| Merit Medical Systems Inc |
| Argon Medical Devices |
| ICU Medical Inc |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap catheter specialists in Germany and Japan anchor regional supply clusters through multi-generational manufacturing expertise, translating captive sterilization capacity into pricing discipline that resists commoditization pressure from Asian disposable producers.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated platform contracts from standalone catheter transactions. Three-tier pricing structure across premium fiber optic systems, standard balloon configurations, and economy PVC alternatives reflects ISO 10993 biocompatibility certification tiers and after-sales technical support depth. Pricing pressure stems from arterial line waveform substitutes capturing low-acuity monitoring volumes previously served by pulmonary artery catheters. Critical care units negotiating through US integrated delivery networks exhibit highest price sensitivity, while German university hospitals prioritize platform integration over per-device economics.
Supply Chain Analysis
Regional distribution centers in Baden-Württemberg, Kansai, and Minneapolis-St. Paul anchor hub-and-spoke patterns serving hospital networks within 48-hour replenishment windows. Manufacturing concentrates in Germany, Japan, and the United States, drawing from medical-grade polyurethane resin feedstocks, precision thermistor components, and optical fiber assemblies. Single-source vulnerability around EU MDR-designated sterilization facilities creates bottleneck risk as certificate renewal waves compress capacity. Distribution runs through manufacturer-direct field inventory programs and specialized cardiovascular device distributors with cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in thermodilution catheters rests on fiber optic premium-tier adoption displacing manual bolus protocols, while polyurethane resin cost volatility creates procurement arbitrage opportunities for manufacturers with backward-integrated compounding operations.
For Market Incumbents: Extend platform ecosystem control through proprietary monitor interface modules that lock fiber optic catheter compatibility into installed base infrastructure. Accelerate EU MDR technical documentation submissions ahead of certificate expiry waves to capture sterilization capacity before notified body bottlenecks intensify. Defend against pressure transducer substitution by embedding closed-loop automation algorithms that arterial line monitors cannot replicate. For New Entrants and Emerging Players: The price-point gap between Edwards Lifesciences premium platforms and economy balloon catheters creates white-space for mid-tier fiber optic alternatives with simplified monitor integration. Target private hospital chains in Mumbai, Delhi, and Chennai installing hybrid cardiovascular suites without legacy monitor infrastructure constraints. Pursue Japan PMDA pre-market consultation pathways to reduce time-to-approval for novel continuous monitoring designs. For Investors and Strategic Acquirers: Valuations sit cheapest among European disposable catheter manufacturers facing EU MDR compliance cost cliffs without dedicated clinical affairs teams. Long-term viability across the analysis window favors targets with captive sterilization validation infrastructure and established PMCF study protocols. Monitor notified body capacity expansion announcements as inflection indicator for CE marking timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation investments determine speed-to-market for next-generation catheters in Heidelberg and Berlin hospital networks. |
| Hospital System Partnership | Integrated delivery network agreements in US 340B-eligible cardiac centers lock recurring revenue through bundled device-consumable contracts. |
| Software Companion Development | Closed-loop cardiac output algorithms differentiate fiber optic platforms from intermittent bolus methods in Boston academic medical centers. |
| Backward Integration | In-house polyurethane compounding buffers gross margin compression from petrochemical feedstock volatility affecting disposable catheter producers. |
| Reimbursement Strategy | German diagnosis-related group coding alignment maximizes device reimbursement ceilings for hemodynamic management procedures in surgical intensive care. |
Research Methodology
Multiple input streams — hospital procurement database analysis, regulatory filing review, and clinician workflow observation — were reconciled through structured primary interviews with cardiac surgeons, critical care intensivists, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearances, EU MDR notified body designation records, PMDA pre-market consultation summaries, and hospital capital expenditure disclosures. Bottom-up catheter shipment estimates and top-down cardiac surgery procedure volumes were triangulated to anchor market sizing.
Historical utilization patterns were cross-referenced against panel input from hemodynamic monitoring platform vendors and integrated delivery network purchasing committees. Segmentation modeling captured product type, therapy area, end user, and deployment configuration dimensions across the projection horizon. CAGRs were derived from procedure volume trajectories, technology substitution curves, and reimbursement framework evolution. Forecast inputs incorporated EU MDR certificate renewal timelines, fiber optic sensor yield rates, and hybrid operating suite installation pipelines.
Caveats apply where notified body capacity constraints, polyurethane resin price spikes, or non-invasive cardiac output monitor accuracy improvements could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology adoption elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market
Medical Devices
Global Medical Laser Systems Market
Medical Devices
Skin Revitalizing Handheld Devices Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Market
Medical Devices
Breast Cancer Core Needle Biopsy Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Global Vagus Nerve Stimulation Market
Medical Devices
Veterinary Ultrasound Scanners Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Facial Pumps Market
Medical Devices
Laryngeal Masks Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Anesthesia Vaporizers Market
Medical Devices
Middle East and Africa Hip and Knee Reconstruction Devices Market