
 Coaxial Splitters Market | 2026-2036
Coaxial Splitters Market Size, Share, and Industry Trends Forecast 2026-2036
Coaxial Splitters Market Outlook
Asset-light leasing models for test and measurement equipment are narrowing the capital barrier for smaller RF component manufacturers seeking cable operator qualification. Extreme Broadband Engineering leverages its specialized foundry relationships to sustain rapid prototyping cycles for custom splitter configurations. Holland Electronics anchors its position through backward integration into precision die-cast aluminum housing production, controlling material consistency for high-frequency performance.
A coaxial splitter is a passive RF device that divides an incoming broadband signal across multiple output ports with specified insertion loss and isolation parameters, typically engineered with impedance-matched internal circuitry and shielded housings to minimize electromagnetic interference in cable television and data networks. The 1x8 splitter segment captures substantial volume as telecommunications providers balance port density against cascaded noise figure budgets in node-plus-zero architectures. Plastic-bodied variants compete aggressively in residential self-install channels where cost sensitivity outweighs thermal durability requirements, while copper-alloy internal components dominate commercial and headend applications demanding superior conductivity and corrosion resistance.
FCC Part 15 emissions standards and EU RoHS substance restrictions collectively shape material selection and shielding design across the supplier base, with non-compliant products facing automatic disqualification from operator procurement lists. The National Electrical Code and UL 1863 safety certifications further constrain enclosure and termination geometries for North American deployments. Stakeholders must monitor evolving DOCSIS 4.0 spectrum plans and corresponding splitter bandwidth specifications, as premature product architecture commitments risk stranding inventory against shifting upstream frequency requirements.
Market Dynamics
DOCSIS 4.0 spectrum expansion is compressing product refresh cycles as cable operators demand splitters rated for 1.8 GHz upstream capacity, forcing manufacturers to obsolete legacy 1.2 GHz designs before end-of-life depreciation schedules complete.
Growth Catalysts
- Fiber-Deep Architectures:Cable operators in the United States are pushing optical nodes closer to subscriber premises, multiplying the number of active taps and passive splitters required per plant mile.
- RoHS Material Compliance:The EU directive restricting lead and cadmium in electronic components is accelerating substitution toward tin-silver-copper solder alloys that improve thermal fatigue resistance in outdoor enclosures.
- Symmetrical Multi-Gigabit Targets:Broadband service providers are upgrading last-mile coaxial infrastructure to support matching upload and download speeds, requiring higher-port-count splitters with improved isolation specifications.
Market Restraints
- Aluminum Price Volatility:Die-cast housing producers face margin compression when London Metal Exchange aluminum contracts spike, forcing quarterly price renegotiations with cable operator procurement desks.
- Chinese Component Concentration:Precision-machined brass RF connectors and F-type terminations source predominantly from Zhejiang and Guangdong provinces, exposing supply continuity risks during port congestion or trade policy shifts.
- Passive Device Substitution:Micro-Node architectures with integrated splitting functions are displacing discrete splitter deployments in greenfield fiber-coaxial hybrid builds.
Strategic Opportunities
- Rural Broadband Subsidies:The FCC Rural Digital Opportunity Fund is channeling construction dollars toward unserved census blocks, expanding addressable demand for outdoor-rated 1x4 and 1x8 splitters in low-density markets.
- DOCSIS 4.0 Certification Pre-Positioning:Manufacturers that complete CableLabs qualification testing early can capture sole-source positions during operator technology transition windows.
- Self-Install Retail Channels:Big-box electronics retailers are expanding coaxial accessory aisles for cord-cutters assembling over-the-air antenna systems, creating pull-through demand for consumer-grade 2-way and 4-way splitters.
Industry Challenges
- RF Simulation Talent Scarcity:Finite-element modeling expertise for high-frequency electromagnetic performance optimization remains concentrated among legacy defense and aerospace engineering cohorts.
- CableLabs Certification Timelines:Extended validation queues for splitter insertion loss and return-loss testing are stretching product launch schedules beyond fiscal planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coaxial Splitters Market |
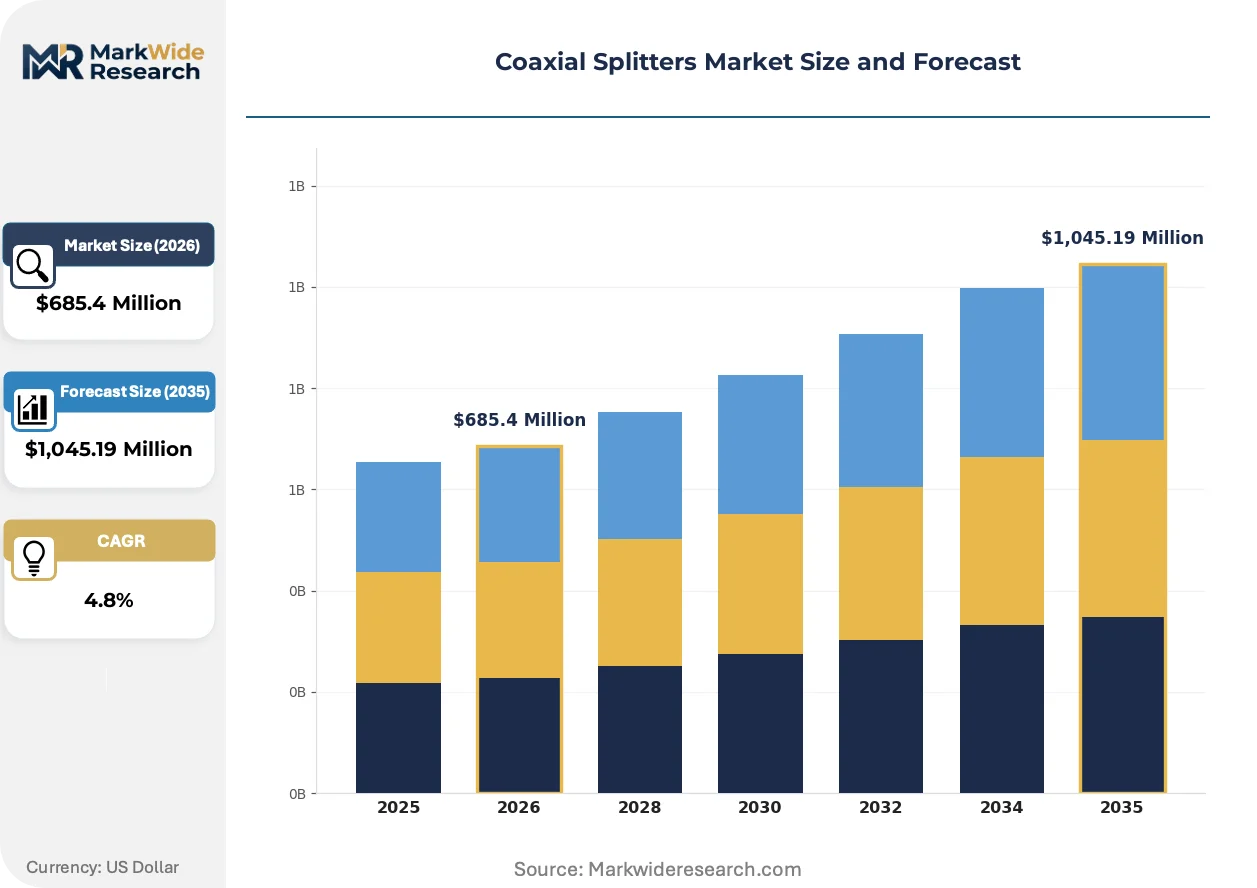
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 1x2 Splitters, 1x4 Splitters, 1x8 Splitters, 1x16 Splitters Material: Aluminum, Plastic, Copper, Stainless Steel Application: Television Distribution, Internet Connectivity, Signal Processing, RF Distribution End User: Residential Users, Commercial Installers, Telecommunications Providers, System Integrators |
| Companies Covered | General Electric, Legrand, BAMF Manufacturing, Extreme Broadband Engineering, Holland Electronics, ONN, Blackweb, RCA, Antronix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coaxial Splitters Market Strategic Shifts
Passive RF component engineering is pivoting toward software-defined characterization and automated production testing, compressing development cycles while tightening performance tolerances for next-generation cable plants.
Surface-mount technology is digitizing splitter manufacturing by replacing hand-soldered discrete inductors and capacitors with automated pick-and-place assembly of multilayer ceramic components. Contract manufacturers in Mexico and Eastern Europe are adopting these lines to serve North American and European cable operators respectively. This automation is digitizing quality consistency and reducing lot-to-lot variation that previously required manual tuning.
The FCC Part 15 emissions framework is tightening shielding effectiveness requirements for consumer-grade splitters, mandating additional metallization layers on plastic housings. Manufacturers must redesign mold tools and validate new conductive coating chemistries. Residential self-install products face the steepest compliance cost increases as they previously operated under less stringent Class B thresholds.
Operator procurement desks are consolidating vendor lists and demanding extended warranty terms that transfer field-failure liability upstream. Tier-2 and Tier-3 cable multiple-system operators are following the sourcing consolidation patterns established by major MSOs. This concentration is most visible in the United States, where private-equity-backed regional operators are adopting the qualification standards of their larger acquisition targets without independent testing infrastructure.
Coaxial Splitters Market Segmentation
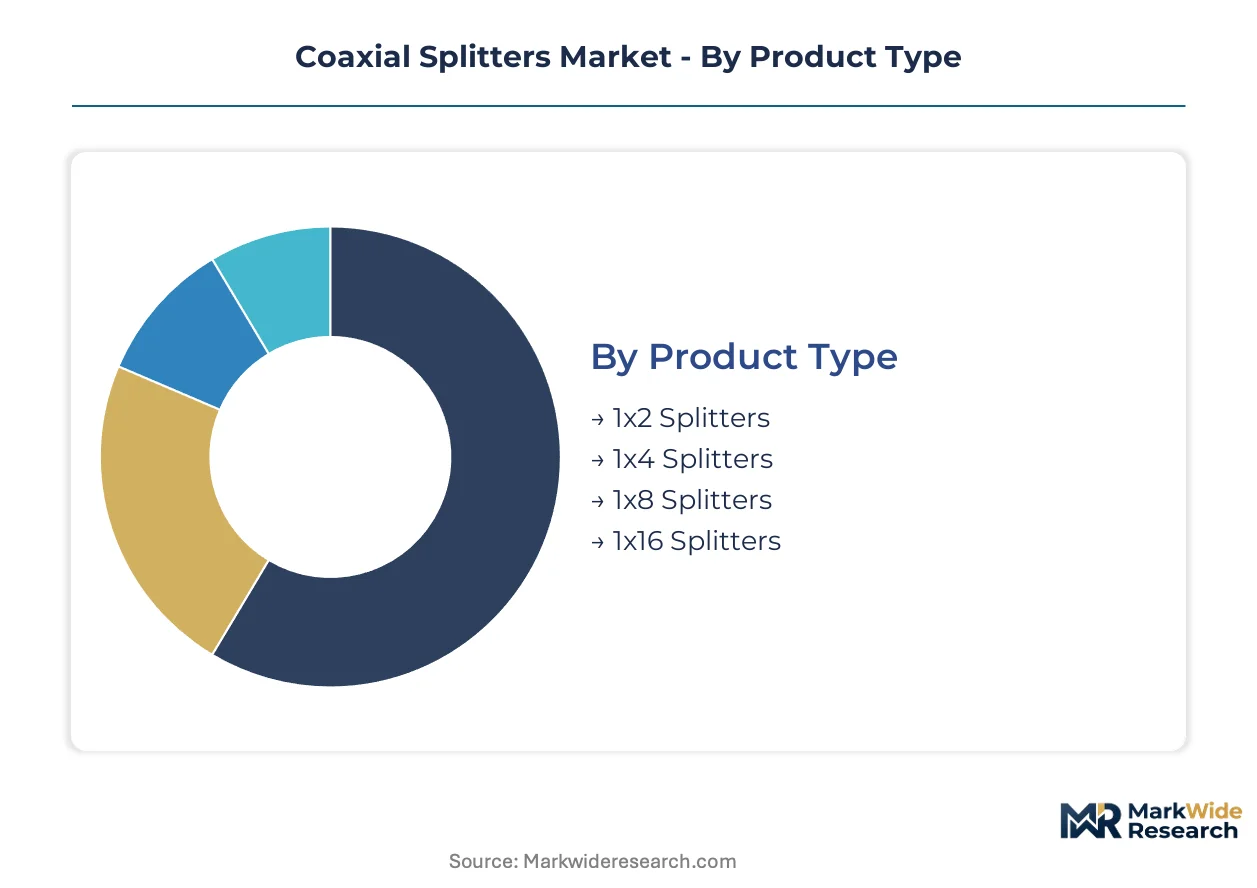
Coaxial splitter configurations diverge sharply across deployment contexts, with port count, housing material, and shielding grade determining suitability for node-plus-zero architectures versus residential self-install scenarios. Cable operators calibrate procurement specifications against cascaded noise budgets, thermal cycling requirements, and electromagnetic compliance thresholds that vary by installation environment.
Product Type:
Use-case spectrum spans compact residential installations through high-density headend distribution, with port density directly correlating to signal attenuation budgets and amplifier spacing requirements.
- 1x8 Splitters:Eight-port configurations balance subscriber reach against insertion loss in fiber-deep node architectures. United States MSOs specify these units for node-plus-zero deployments where optical-electrical conversion occurs at the curb, demanding tight isolation specifications to prevent upstream ingress noise accumulation.
- 1x4 Splitters:Four-way designs dominate residential drop installations and small commercial buildings, offering moderate port expansion with manageable signal degradation. Rural broadband subsidy programs channel construction dollars toward outdoor-rated 1x4 units in low-density census blocks where amplifier cascades prove uneconomical.
- 1x2 Splitters:Two-port variants serve minimal-expansion scenarios and diagnostic tap points within cable plants.
- 1x16 Splitters:Sixteen-port units concentrate in headend RF distribution and large multi-dwelling unit backbone feeds.
The dominant share belongs to 1x8 Splitters, while 1x4 Splitters is closing the gap fastest.
Material:
Cost tier differentiation separates premium thermal performance from economy-grade residential solutions, with conductivity and corrosion resistance commanding substantial price premiums in commercial applications.
- Aluminum:Die-cast aluminum housings deliver superior electromagnetic shielding and thermal dissipation for outdoor pedestal and aerial installations. Precision casting operations in North America and Mexico serve cable operator qualification programs requiring material traceability and lot consistency for FCC Part 15 emissions compliance.
- Plastic:Injection-molded polymer enclosures dominate consumer retail channels where cost sensitivity outweighs durability requirements. FCC tightening of Class B shielding effectiveness mandates is forcing metallization layer additions that compress margins on residential self-install products.
- Copper:Copper-alloy internal components and select housing applications target high-frequency performance in commercial headend environments.
- Stainless Steel:Corrosion-resistant stainless configurations concentrate in coastal and industrial atmospheric exposure zones.
Aluminum captures the volume lead, though Plastic is expanding most quickly through big-box retail distribution.
Application:
Customer type stratification distinguishes broadcast television legacy infrastructure from symmetrical broadband service delivery, with spectrum allocation shifts rewriting performance specifications.
- Internet Connectivity:Data-centric deployments demand splitters rated for extended upstream frequency ranges as DOCSIS 4.0 spectrum plans push toward 1.8 GHz capacity. Cable operators in the United States are obsoleting legacy 1.2 GHz designs ahead of depreciation schedules to accommodate symmetrical multi-gigabit service targets.
- Television Distribution:Broadcast signal splitting retains substantial installed base in hybrid fiber-coaxial plants, though video subscriber erosion is compressing replacement cycle frequency.
- RF Distribution:General radio frequency routing serves cellular DAS, satellite, and private network applications beyond cable television.
- Signal Processing:Specialized conditioning and monitoring tap configurations support network diagnostics and spectrum analysis functions.
Internet Connectivity holds the dominant position, while Television Distribution is losing share to data-centric infrastructure.
End User:
Procurement concentration patterns separate centralized operator qualification programs from fragmented retail and contractor channels with divergent warranty and technical support expectations.
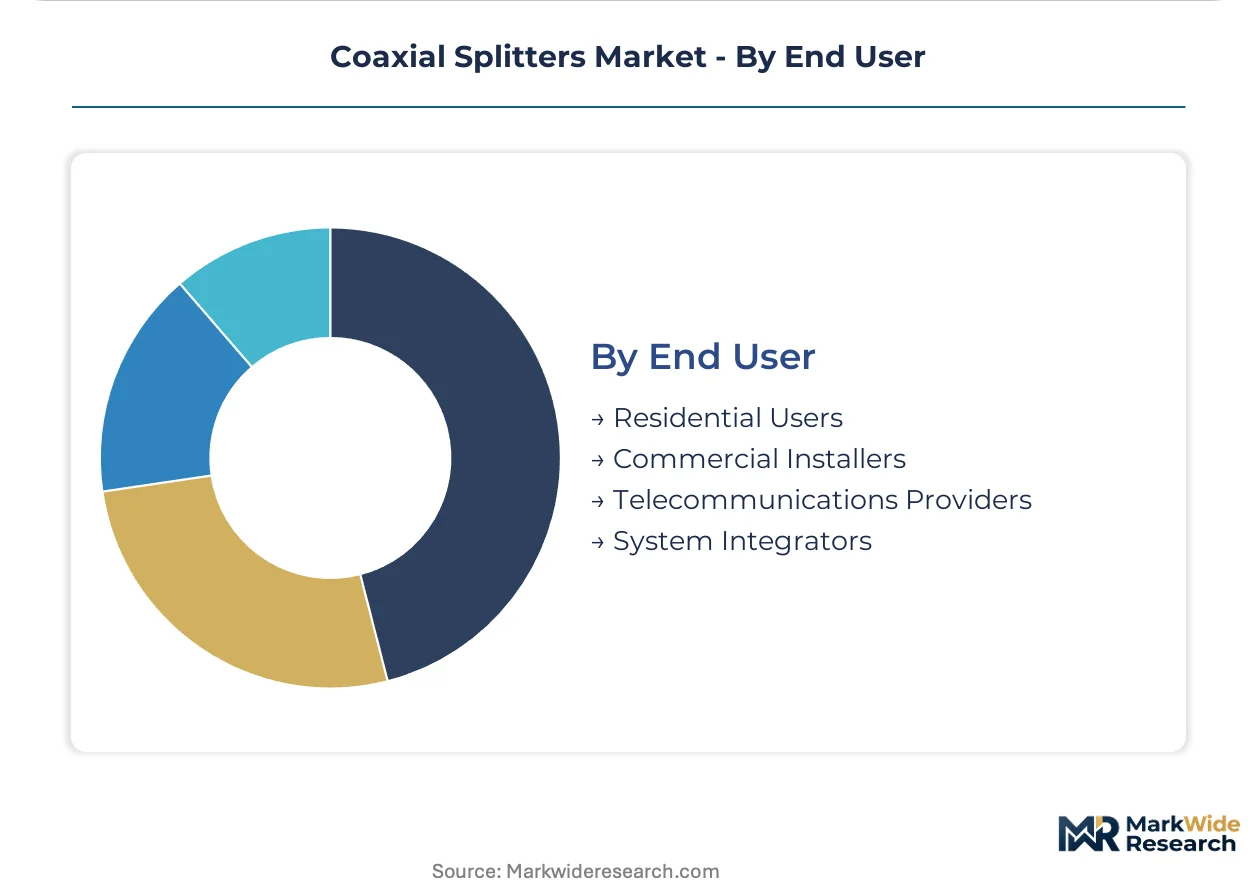
- Telecommunications Providers:Major MSOs and regional cable operators drive volume through centralized procurement desks demanding CableLabs certification, extended warranty terms, and field-failure liability transfer. Vendor list consolidation is concentrating supplier relationships among qualified manufacturers with proven DOCSIS interoperability.
- Residential Users:Self-install consumers purchase through electronics retailers and e-commerce platforms for over-the-air antenna systems and cord-cutter configurations. Big-box retailers are expanding coaxial accessory aisles, creating pull-through demand for consumer-grade 2-way and 4-way units with minimal technical documentation.
- Commercial Installers:Contractor channels serve multi-dwelling unit and small business deployments with professional-grade specifications.
- System Integrators:Enterprise and institutional project contractors specify custom configurations for campus and facility-wide distribution.
Telecommunications Providers command the largest share, though Residential Users is climbing the fastest through retail channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Rural Digital Opportunity Fund disbursements are accelerating coaxial infrastructure deployment across underserved census blocks, while EU RoHS enforcement tightens material compliance for passive RF components entering European markets.
United States
Major MSOs including Comcast and Charter Communications are modernizing last-mile coaxial infrastructure to meet symmetrical multi-gigabit service targets. FCC Part 15 emissions standards and UL 1863 safety certifications constrain enclosure geometries for North American deployments. CableLabs certification queues in Louisville, Colorado are stretching product launch schedules as manufacturers compete for DOCSIS 4.0 qualification slots.
Germany
Vodafone Deutschland and regional cable operators are upgrading hybrid fiber-coaxial plants to support extended upstream spectrum allocations. EU RoHS substance restrictions and REACH chemical registration requirements shape material selection for die-cast housings and solder alloys. Precision manufacturing clusters in Baden-Württemberg host foundry operations supplying electromagnetic shielding components for outdoor-rated splitters.
China
Domestic cable operators and export-oriented contract manufacturers drive volume for F-type terminations and precision-machined brass connectors. MIIT equipment approval processes and GB standards compliance govern product entry into telecommunications infrastructure projects. Manufacturing concentration in Zhejiang and Guangdong provinces exposes supply continuity risks during port congestion or trade policy adjustments.
Japan
J:COM and regional CATV operators maintain steady replacement demand for high-isolation splitters in dense urban deployments. METI energy efficiency guidelines and JIS standards influence thermal dissipation specifications for outdoor pedestal installations. Industrial corridors in the Chubu region around Nagoya host precision die-casting facilities serving both domestic and export cable equipment markets.
India
Hathway Cable and Datacom alongside regional MSOs are expanding addressable networks under BharatNet rural broadband initiatives. BIS certification requirements and TRAI quality of service mandates tighten performance thresholds for passive RF components. Manufacturing hubs in Maharashtra and Tamil Nadu are developing assembly capacity for plastic-bodied consumer-grade splitters targeting retail distribution channels.
Coaxial Splitters Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. Vendor list consolidation among major MSOs is concentrating qualified supplier relationships, while regional operators adopt sourcing standards from larger acquisition targets without independent testing infrastructure. Three archetypes dominate: vertically integrated housing manufacturers, specialized RF engineering boutiques, and contract manufacturing platforms. Competitive moves center on CableLabs certification pre-positioning and backward integration into precision casting operations.
Among US-based engineering specialists, Extreme Broadband Engineering and Holland Electronics exemplify the RF optimization tier. Extreme Broadband Engineering occupies a position leveraging foundry relationships for rapid prototyping cycles, while Holland Electronics anchors the backward-integrated archetype through captive die-cast aluminum housing production. European conglomerate Legrand represents the diversified electrical component platform seeking cable operator qualification entry.
| Leading Market Players |
|---|
| General Electric |
| Legrand |
| BAMF Manufacturing |
| Extreme Broadband Engineering |
| Holland Electronics |
| ONN |
| Blackweb |
| RCA |
| Antronix |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Guangdong province manufacturing clusters for precision-machined brass RF connectors and F-type terminations concentrate upstream supply leverage, positioning die-cast housing producers and cable operator procurement desks as the primary margin capture points downstream. London Metal Exchange aluminum contract volatility feeds directly into quarterly price renegotiations, compressing converter margins when raw material spikes coincide with fixed operator contract terms.
Pricing Analysis
CableLabs certification tier creates the primary spread between qualified and unqualified supplier pricing, with FCC Part 15 emissions compliance and UL 1863 safety ratings further stratifying premiums. Three-tier pricing structure across CableLabs-certified, CE-marked, and uncertified economy levels reflects the cost of validation queues and extended warranty liability transfer. Cost compression in residential self-install channels is intensifying because FCC Class B shielding mandates force metallization layer additions onto plastic housings. Big-box retail consumers exhibit highest price sensitivity, while major MSOs prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Export control restrictions on precision RF simulation software and electromagnetic modeling tools limit technology transfer to contract manufacturers in Mexico and Eastern Europe. Component sourcing draws from China for machined brass terminations, North America for die-cast aluminum housings, and Japan for multilayer ceramic capacitors. Single-source vulnerability concentrates in Zhejiang province F-connector suppliers during port congestion episodes. Distribution runs through CableLabs-qualified vendor lists for telecommunications providers, diverging to big-box retail and e-commerce for residential self-install channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended warranty and field-failure liability transfer services are expanding faster than hardware unit sales as operator procurement desks consolidate vendor relationships and demand performance guarantees. Cable operators now bundle installation support and spectrum migration consulting with splitter procurement, creating recurring revenue pools that outpace passive component margins.
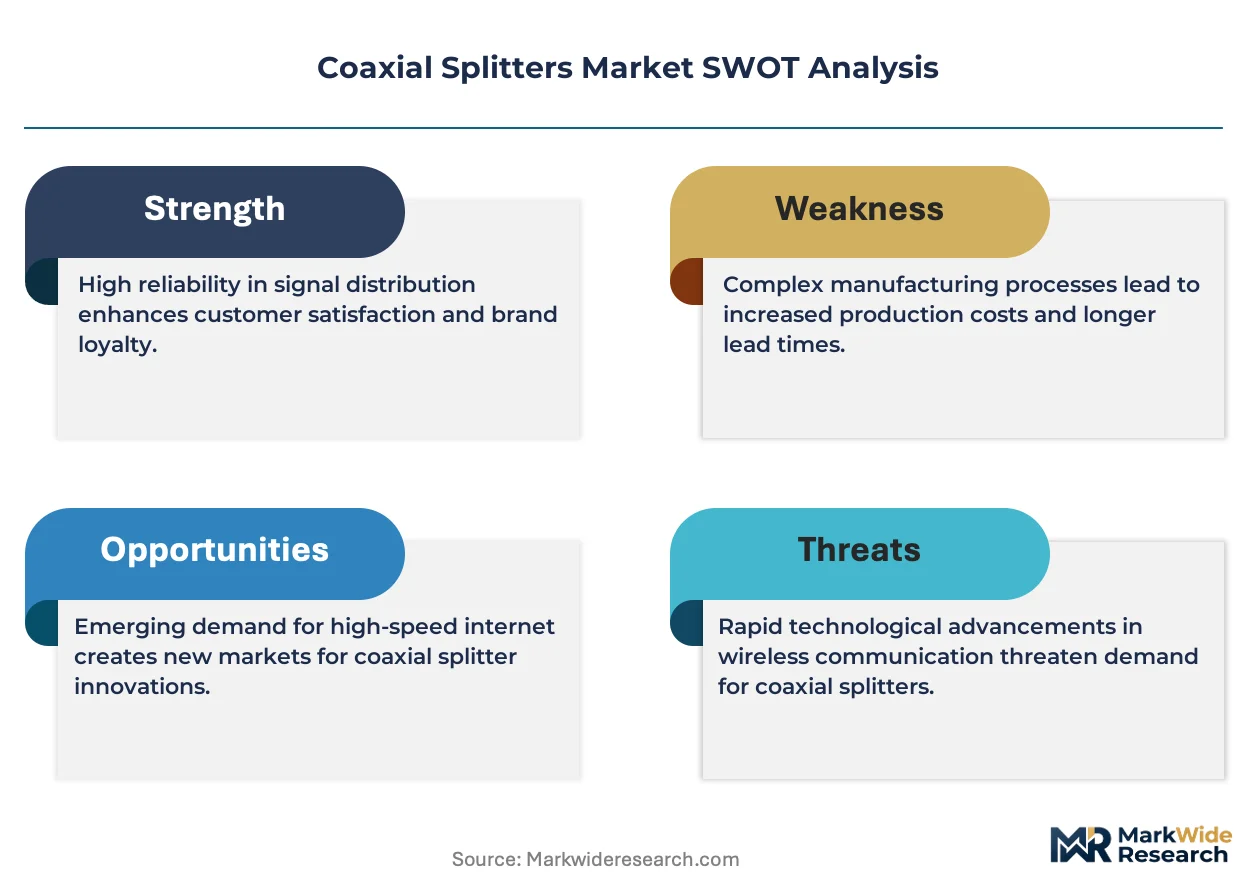
For Market Incumbents: Entrench through backward integration into precision die-cast aluminum housing production and captive CableLabs certification infrastructure. Micro-Node architectures with integrated splitting functions threaten discrete splitter volumes in greenfield builds; defend by locking in node-plus-zero architecture specifications with major MSOs through early DOCSIS 4.0 qualification partnerships.
For New Entrants and Emerging Players: Build out rural broadband subsidy program participation targeting FCC Rural Digital Opportunity Fund disbursements in low-density census blocks. The most penetrable segment sits in outdoor-rated 1x4 and 1x8 splitters for unserved markets where amplifier cascades prove uneconomical. Go-to-market leverage rests on asset-light leasing models for test and measurement equipment that narrow capital barriers for cable operator qualification.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed regional cable operators adopting qualification standards from larger acquisition targets without independent testing infrastructure. Long-term viability hinges on DOCSIS 4.0 spectrum migration completion and fiber-deep architecture persistence against full-fiber substitution. The signal to monitor is CableLabs certification queue compression indicating technology transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CableLabs Certification Pre-Positioning | Early qualification captures sole-source positions during operator technology transition windows. |
| Backward Integration into Die-Casting | Captive aluminum housing production controls material consistency for FCC Part 15 compliance. |
| Surface-Mount Technology Adoption | Automated pick-and-place assembly reduces lot-to-lot variation previously requiring manual tuning. |
| Rural Broadband Subsidy Channel Entry | FCC Rural Digital Opportunity Fund disbursements expand addressable demand in unserved census blocks. |
| Extended Warranty Service Bundling | Field-failure liability transfer creates recurring revenue layers outpacing hardware unit margins. |
Study Parameters
Desk research of FCC equipment authorization databases, CableLabs certification registries, and EU RoHS compliance filings preceded structured interviews with cable operator procurement executives, RF component engineering directors, and contract manufacturing operations managers. Secondary validation drew from SEC 10-K filings of publicly traded MSOs, London Metal Exchange aluminum price series, and customs trade data for F-type termination imports. Bottom-up unit demand estimates triangulated against top-down infrastructure spending projections from rural broadband subsidy programs.
Assumption sets held DOCSIS 4.0 spectrum expansion timelines and fiber-deep architecture penetration rates as primary scenario variables across the projection horizon. Segmentation modeling spanned port count configurations, housing material tiers, application types, and end-user procurement channels. CAGRs derived from regression analysis of historical deployment cycles correlated with operator capital expenditure disclosures and regulatory funding authorization trajectories. Forecast inputs incorporated aluminum price volatility bands and CableLabs certification queue duration estimates.
Sensitivities concentrate around DOCSIS 4.0 upstream frequency specification shifts, aluminum contract price spikes, and Chinese component supply disruptions. Forecasts reflect documented assumptions regarding operator technology refresh cadence and subsidy program disbursement velocity. Material shifts in FCC spectrum allocation plans or trade policy adjustments affecting Zhejiang province connector exports would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF Spectrum Analyzer Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
Asia-Pacific Small Signal Transistor Market
RF Components
RF Front End Module Market
RF Components
RF Over Fiber (Rfof) Market
RF Components
Global Small Cell Power Amplifier Market
RF Components
RF Components Market
RF Components
Coaxial Connectors (RF) Market
RF Components
RF Power Dividers Market
RF Components
Global RF Power Semiconductor Market
RF Components
RFID Tags Market
RF Components
Noise Suppression Components Market
RF Components
Tunable Capacitors Market
RF Components
Smart Antenna Market
RF Components
High Power RF Amplifier Module Market
RF Components
RF Antenna Market