
 M Commerce Payment Market | 2026-2036
M Commerce Payment Market Size, Share, and Industry Trends Forecast 2026-2036
M Commerce Payment Market Intelligence
The share of the transportation vertical within the overall industry mix is expanding as ride-sharing and mobility-as-a-service platforms integrate seamless in-app payments. Apple Inc. leverages its hardware ecosystem to drive adoption of its mobile wallet. Stripe specializes in providing developer-friendly payment APIs for online and mobile businesses. Visa Inc. positions its tokenization services to secure transactions across various mobile platforms, reinforcing its network's relevance in the mobile era.
M commerce payment refers to the systems enabling financial transactions for goods and services through a mobile device. These systems often utilize technologies like Near Field Communication (NFC) for contactless payments or encrypted QR codes for point-of-sale interactions. While credit and debit cards remain foundational, the mobile wallet segment represents the fastest-growing payment method. Smartphones continue to dominate the device type category, though wearables are an emerging channel for transaction volume.
Regulatory frameworks like the EU's GDPR and oversight from the US Federal Trade Commission impose strict data privacy and security requirements on payment processors. In parallel, central bank directives, such as those from the Reserve Bank of India, shape interoperability and digital payment infrastructure. Providers must now navigate the challenge of delivering frictionless user experiences while adhering to an increasingly complex and fragmented compliance landscape.
Market Dynamics
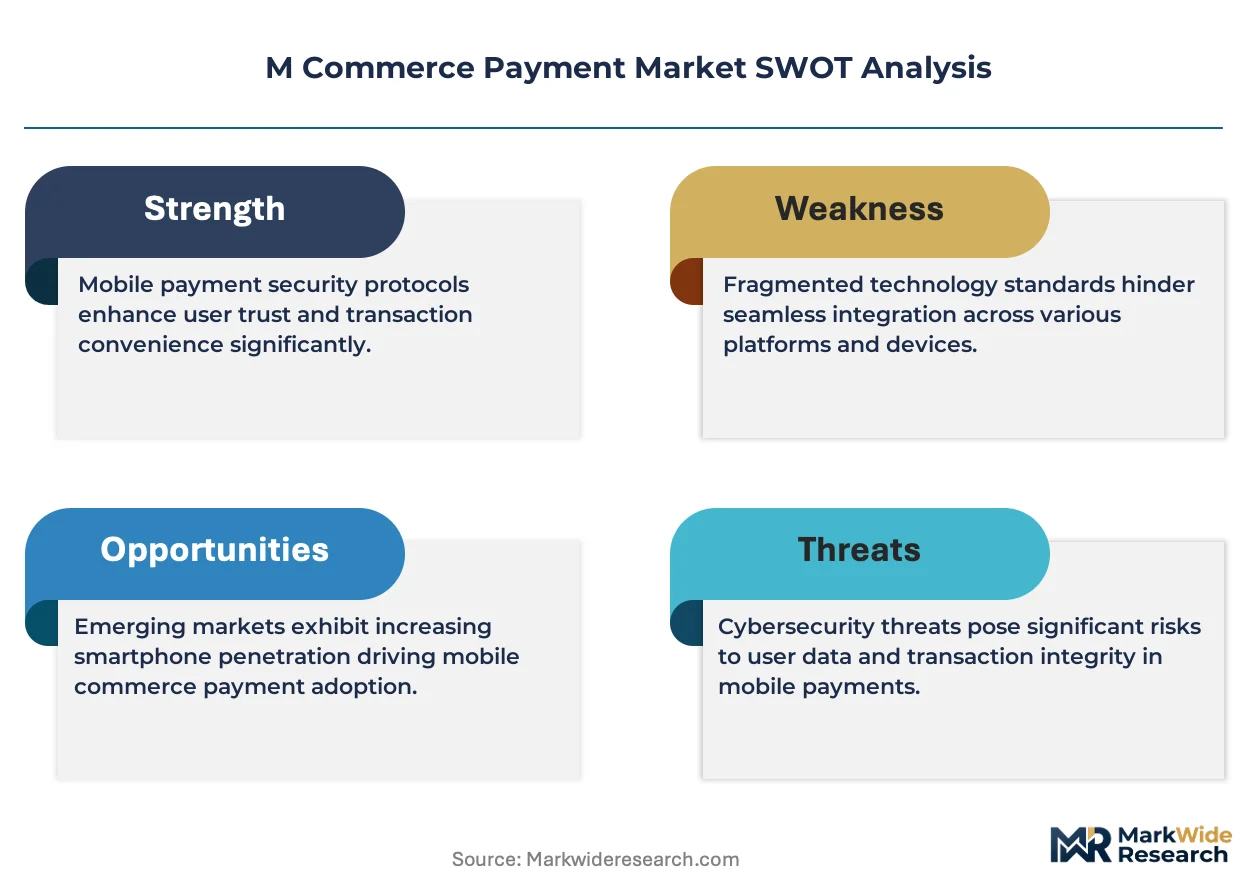
The central dynamic shaping the M Commerce Payment Market is the tension between open banking frameworks, which mandate interoperability, and the closed-loop ecosystems built by technology giants, which seek to lock in users through integrated hardware and software experiences.
Growth Catalysts
- Open Banking Frameworks:Regulations like Europe's PSD2 compel financial institutions to open their data via APIs, enabling third-party fintech developers to build innovative payment aggregation and wallet services that accelerate market growth.
- 5G Network Deployment:The global rollout of 5G infrastructure provides the low-latency, high-bandwidth connectivity needed for seamless mobile transactions, particularly for streaming media purchases and enhanced in-app retail experiences.
- Financial Inclusion Initiatives:Government-led programs in countries such as India and Brazil promote digital payments to bring unbanked and underbanked populations into the formal economy, creating a massive new user base for mobile-first payment solutions.
Market Restraints
- Persistent Digital Divide:In many rural areas of Africa and Southeast Asia, inadequate internet infrastructure and the high cost of data plans remain significant barriers, limiting the addressable market for mobile payment services.
- Fragmented Regulatory Landscapes:Divergent data privacy and security regulations, such as the EU's GDPR and various US state laws, create significant compliance burdens and development costs for payment providers operating across multiple jurisdictions.
- Consumer Trust in Traditional Payments:The entrenched habit and perceived security of using physical credit and debit cards, especially among older demographics, slows the full transition to mobile-only payment behaviors for everyday transactions.
Strategic Opportunities
- Underpenetrated Geographies:Markets in Latin America, where smartphone ownership is high but the use of mobile payments for daily commerce is still developing, offer substantial growth potential for providers who can address local needs.
- IoT and Connected Commerce:The integration of payment capabilities into connected devices, such as smart appliances and automobiles, opens new revenue streams for automated and subscription-based transactions without direct user interaction.
- Biometric Authentication Integration:Combining mobile wallets with biometric technologies like facial recognition and fingerprint scanning enhances transaction security, increases consumer confidence, and enables higher-value purchases on mobile devices.
Industry Challenges
- Legacy System Integration:Merchants, particularly small and medium-sized businesses, face significant technical hurdles and costs when attempting to integrate a multitude of new mobile payment APIs with their existing point-of-sale and accounting systems.
- Evolving Fraud Tactics:The increasing sophistication of cyber threats, including specialized malware and social engineering schemes targeting mobile payment users, demands continuous and costly investment in advanced fraud detection and prevention systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | M Commerce Payment Market |
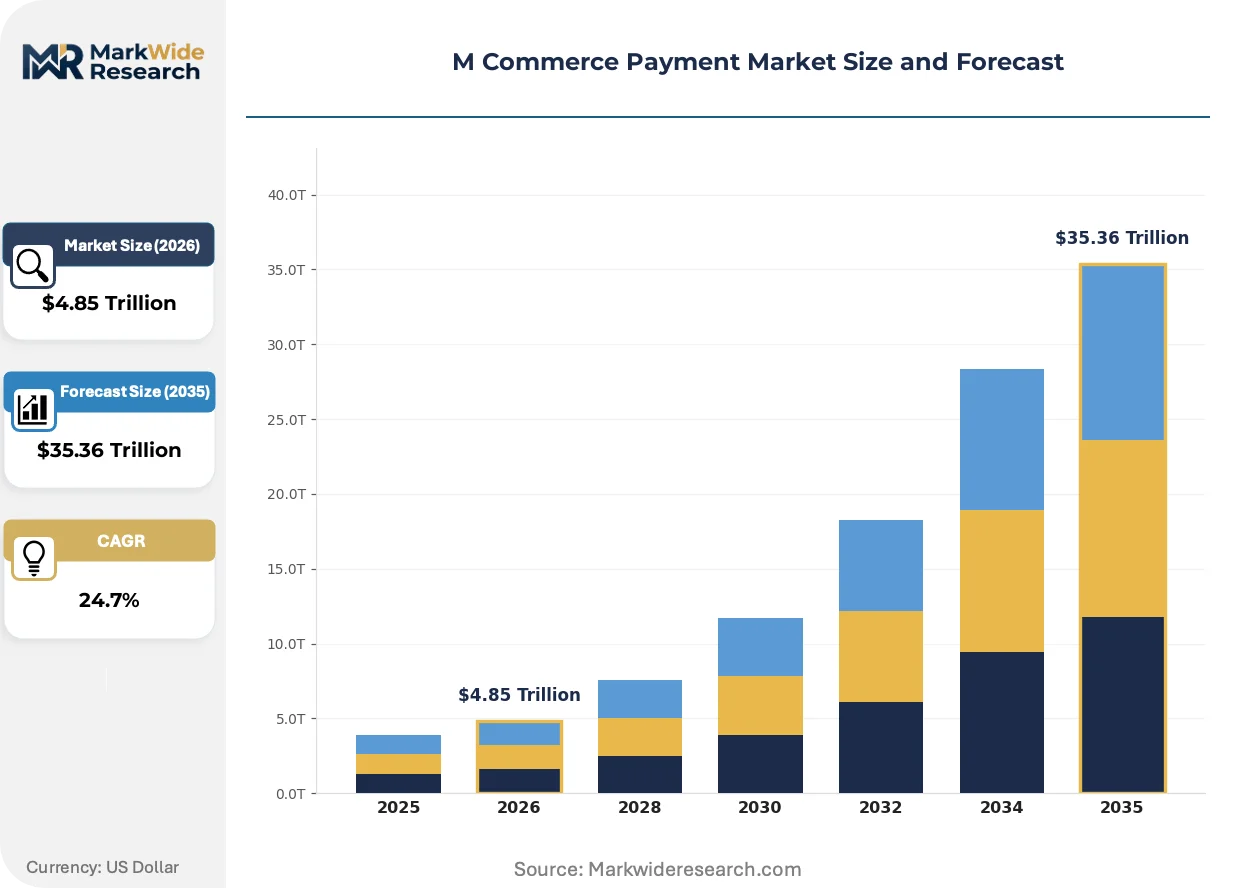
| Market Size in 2026 | $4.85 Trillion |
| Market Size in 2035 | $35.36 Trillion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallet, Bank Transfer Service Type: Payment Processing, Fraud Detection, Account Management, Customer Support Device Type: Smartphones, Tablets, Wearables, Laptops Industry Vertical: Retail, Hospitality, Transportation, Entertainment |
| Companies Covered | PayPal Holdings, Inc., Apple Inc., Alphabet Inc., Visa, Inc., Mastercard, Square, Inc., Amazon.com Inc., Stripe, Adyen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
M Commerce Payment Market Strategic Shifts & Innovations
The market is shifting from monolithic, all-in-one payment processing systems toward a more disaggregated and API-driven model. This allows merchants to assemble best-of-breed solutions for different functions like fraud detection, authentication, and loyalty, creating highly customized checkout experiences for consumers.
Tokenization technology replaces sensitive primary account numbers with unique, non-reusable digital identifiers for each transaction. Online merchants and mobile application developers are rapidly adopting this method to reduce their PCI DSS compliance scope and mitigate the impact of data breaches. This technology is modularizing the security stack, enabling businesses to enhance payment protection without re-architecting their entire backend infrastructure.
Policy frameworks like India's Unified Payments Interface (UPI) are forcing a fundamental re-evaluation of payment infrastructure. This government-backed, real-time system has created a fully interoperable ecosystem, sparking intense competition and innovation among banks and fintech startups. The retail and service sectors in India have been most transformed, building new business models directly on top of the instant, low-cost payment rails provided by UPI.
A notable shift in consumer behavior is the rapid adoption of "Buy Now, Pay Later" (BNPL) options integrated directly within mobile commerce checkout flows. This financing model directly competes with traditional credit card revolving debt, especially for millennial and Gen Z consumers making discretionary purchases. The trend is most prominent within the apparel, consumer electronics, and home furnishings verticals in markets across North America and Europe.
M Commerce Payment Market Segmentation
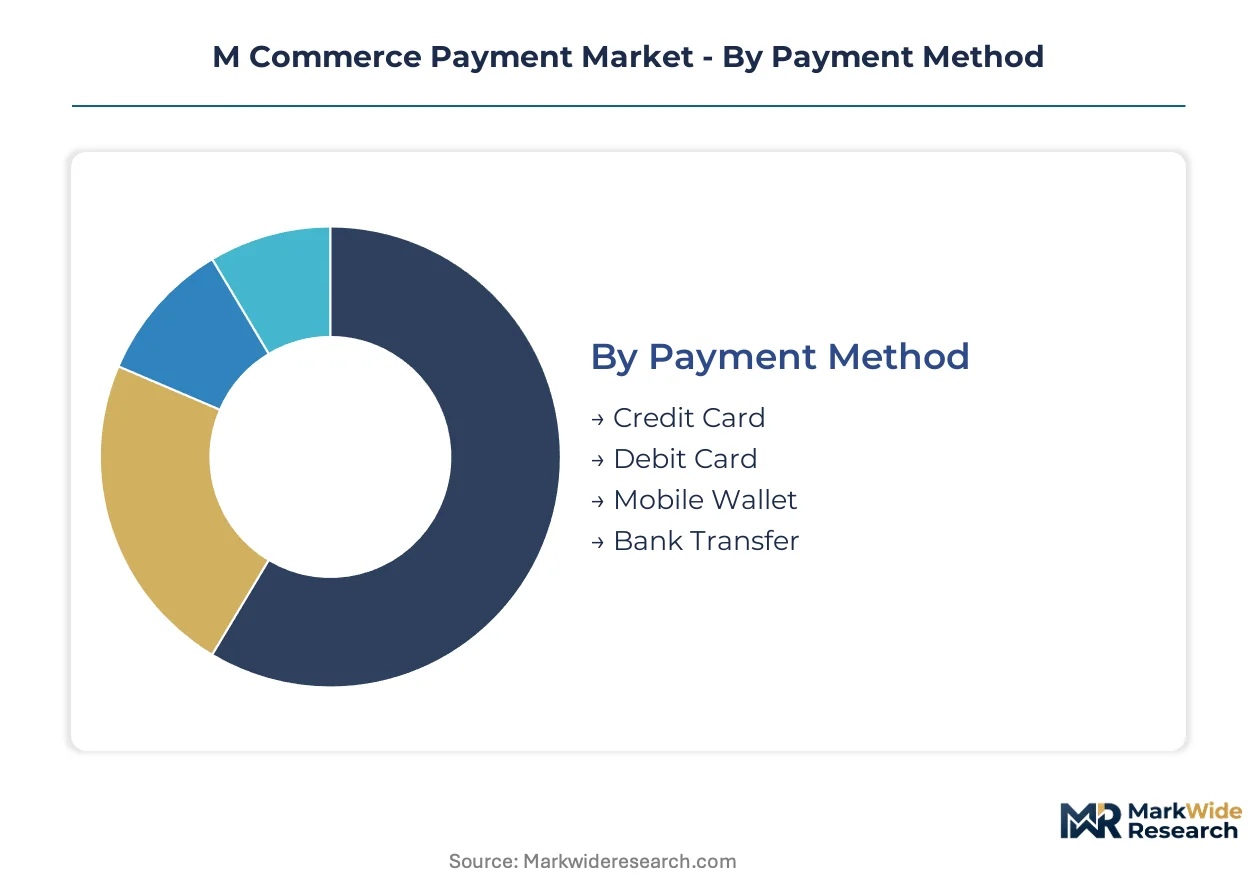
Understanding the M Commerce Payment Market requires a detailed segmentation analysis, revealing distinct user behaviors and technological preferences. This breakdown helps identify specific growth opportunities and challenges across various payment methods, service types, device categories, and industry applications. Strategic insights emerge from examining these granular distinctions.
Payment Method:
Buyer preferences in M commerce payments are significantly shaped by convenience, security perceptions, and existing financial habits.
- Credit Card:Represents a traditional payment rail, frequently tokenized for mobile transactions. This method remains foundational for higher-value purchases across North America and Europe, supported by established consumer trust.
- Debit Card:Directly links to bank accounts, providing real-time fund deductions for mobile purchases.
- Mobile Wallet:Mobile Wallet systems leverage encrypted digital credentials and often integrate biometric authentication for enhanced security. Demand for mobile wallets concentrates in rapidly digitizing economies like India, driven by government initiatives and a large unbanked population.
- Bank Transfer:Facilitates direct account-to-account payments, often used for larger transactions or bill payments via mobile banking apps.
Credit Card transactions lead current M commerce payment volumes; Mobile Wallet is gaining share fastest.
Service Type:
The functional applications of M commerce payment services address distinct operational needs for businesses and consumers.
- Payment Processing:Encompasses the entire transaction lifecycle, from authorization to settlement, integrating various payment methods. This core service sees demand from online retailers and ride-sharing platforms seeking seamless checkout experiences.
- Fraud Detection:Employs AI and machine learning algorithms to identify and prevent suspicious mobile transactions in real-time. Demand for advanced fraud detection is high among financial institutions and high-volume e-commerce platforms facing evolving cyber threats.
- Account Management:Provides tools for users and merchants to track transactions, manage payment methods, and oversee financial activity.
- Customer Support:Offers assistance for transaction issues, technical problems, and general inquiries related to mobile payment services.
Payment Processing services form the revenue backbone, while Fraud Detection capabilities are becoming essential for maintaining trust and security.
Device Type:
The nature of user interaction and transaction mobility primarily defines the segmentation by device type.
- Smartphones:Represent the primary device for M commerce payments, offering integrated mobile wallets and app-based transaction capabilities. Demand remains highest in all geographies, particularly in Asia-Pacific with its high smartphone penetration and digital payment adoption.
- Tablets:Offer a larger screen interface for mobile shopping and payment, often used for in-home commerce and content consumption.
- Wearables:Include smartwatches and fitness trackers integrating NFC for contactless payments, enabling quick, hands-free transactions. This emerging channel is gaining traction among younger demographics in urban centers across Europe and North America.
- Laptops:Facilitate web-based M commerce transactions, providing a more traditional desktop-like experience for online purchases.
Smartphones dominate transaction volumes, while wearables offer significant potential for future contactless payment growth.
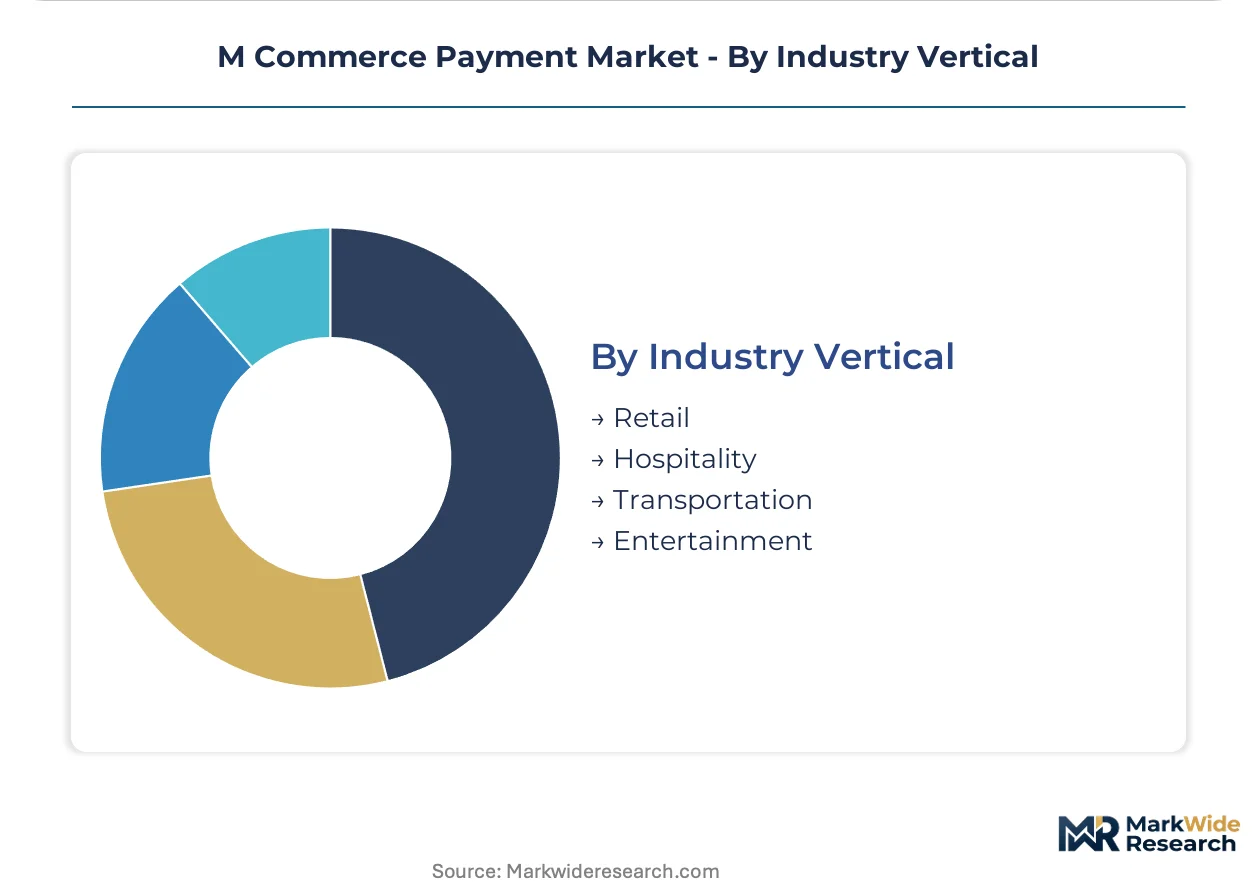
Industry Vertical:
Specific end-use applications within various industry verticals drive distinct requirements for M commerce payment solutions.
- Retail:Encompasses online and in-store mobile purchases of goods, leveraging QR codes, NFC, and in-app payments. This vertical experiences high transaction frequency globally, particularly in consumer electronics and apparel.
- Hospitality:Covers mobile payments for hotel bookings, restaurant bills, and food delivery services, enhancing customer convenience.
- Transportation:Includes ride-sharing, public transit ticketing, and mobility-as-a-service platforms integrating seamless in-app payment systems. This sector exhibits rapid growth in urban areas, with platforms like Uber and Lyft driving adoption in the US and Europe.
- Entertainment:Involves mobile ticketing for events, in-app purchases for gaming, and streaming service subscriptions, catering to digital content consumption.
The Retail sector maintains the largest share of M commerce payment volumes, with Transportation demonstrating the most dynamic growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The M Commerce Payment Market exhibits varying growth trajectories influenced by regulatory environments, creating a form of regulatory arbitrage where innovation flourishes in supportive frameworks. Countries with proactive digital payment policies often attract investment and foster rapid adoption, while fragmented or overly stringent regulations can slow market development. This dynamic shapes where payment solution providers prioritize their strategic expansion and product development efforts.
India
Massive smartphone penetration and government-led financial inclusion initiatives drive significant demand for mobile payments in India. The Reserve Bank of India (RBI) actively promotes digital transactions through frameworks like the Unified Payments Interface (UPI). Delhi-NCR and Bengaluru serve as major fintech hubs, fostering intense competition and innovation among payment service providers.
United States
Consumer preference for mobile wallets and the widespread use of credit/debit cards as foundational rails stimulate M commerce growth. The US Federal Trade Commission (FTC) imposes strict data privacy and security requirements on payment processors. Silicon Valley in California remains a key center for payment technology development, driving advancements in tokenization and mobile security.
Germany
Demand for secure and convenient mobile payment options is rising, particularly for in-app retail and contactless transactions. Europe's PSD2 framework mandates open banking, accelerating innovation in payment aggregation across Germany. Frankfurt, a major financial center, witnesses significant development in fintech solutions leveraging these open banking protocols.
Brazil
Government initiatives to bring unbanked populations into the formal economy create a substantial user base for mobile-first payment solutions. Brazil's Central Bank directives aim to shape interoperability and digital payment infrastructure. São Paulo's tech ecosystem is a focal point for developing localized mobile payment applications and financial inclusion tools.
M Commerce Payment Market Key Industry Players
Branded platform providers and specialized payment processors split share differently across M commerce segments, reflecting diverse business models. The market structure exhibits a blend of established financial networks and agile fintech innovators. Strategic archetypes include ecosystem-driven players, network facilitators, and pure-play processing specialists. Companies actively pursue strategic partnerships to expand their reach and engage in continuous technology licensing to integrate new authentication and security features.
Specialists in integrated hardware-software ecosystems, such as Apple Inc., leverage their device dominance to drive mobile wallet adoption and control the user experience. Visa Inc. exemplifies the established financial network archetype, positioning its tokenization services to secure transactions across various mobile platforms and reinforcing its relevance in the mobile era. Stripe occupies a position as a developer-centric payment API provider, catering to online and mobile businesses seeking flexible integration solutions for seamless mobile commerce. These entities collectively shape the competitive dynamics, focusing on either broad ecosystem control, foundational transaction security, or merchant-side integration efficiency.
| Leading Market Players |
|---|
| PayPal Holdings, Inc. |
| Apple Inc. |
| Alphabet Inc. |
| Visa, Inc. |
| Mastercard |
| Square, Inc. |
| Amazon.com Inc. |
| Stripe |
| Adyen |
Cost & Logistics Intelligence
Retailers and service providers, seeking frictionless checkout, typically encounter a transactional fee-based pricing model. This structure often includes a percentage of the transaction value plus a fixed per-transaction fee.
Pricing Analysis
Interchange fees form a foundational layer of pricing within the M Commerce Payment market, directly influencing overall transaction costs. The dominant model involves per-transaction fees, often complemented by subscription tiers for advanced features like enhanced fraud detection or specialized reporting. Price differentiation arises from the sophistication of security features and the depth of API integration capabilities. Pricing softness reflects intense competition, with small and medium-sized businesses exhibiting the highest price sensitivity compared to large enterprises prioritizing comprehensive service bundles.
Supply Chain Analysis
Dual-sourcing requirements for payment infrastructure, particularly for critical cloud and data center services, ensure operational resilience for large financial institutions. The underlying infrastructure supply concentrates in technology hubs such as the United States, Ireland, and India, drawing from high-performance network equipment and secure hardware modules. A significant structural risk involves cybersecurity vulnerabilities across the network, demanding continuous vigilance. Distribution runs through direct enterprise sales, developer platforms, and strategic partnerships with banks and fintech aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The M Commerce Payment market acts as a regulatory compounder, with Europe's PSD2 framework significantly driving demand for open banking solutions. This regulation compels financial institutions to innovate, fostering new payment aggregation services.
For Market Incumbents: Anchor existing market share by aggressively investing in advanced tokenization services and expanding global network reach. Consolidate capabilities through strategic acquisitions of specialized fintechs, particularly those focused on AI-driven fraud detection. This defends against the threat posed by agile fintechs leveraging open banking frameworks. A key lever involves leveraging established brand trust and regulatory compliance expertise to differentiate offerings.
For New Entrants and Emerging Players: India's Unified Payments Interface (UPI) opens a window for new entrants to build innovative, low-cost payment solutions. Target underpenetrated geographies in Latin America, focusing on mobile wallet solutions for unbanked populations. Integrate biometric authentication as a core feature to enhance security and build consumer trust, which is a key white-space target. A developer-friendly API strategy allows rapid integration with local merchants and existing digital ecosystems.
For Investors and Strategic Acquirers: Large technology companies and established financial institutions are the most active acquirers in this space, recognizing its long-term viability as digital payments become ubiquitous. Prioritize acquisition targets with strong intellectual property in biometric authentication or developer-friendly API platforms. These specialized fintechs offer critical capabilities for ecosystem expansion. Watch for widespread adoption rates of IoT-integrated payment solutions as a key inflection indicator for future growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Developer-Friendly APIs | This enables seamless integration for online retailers and mobile application developers, accelerating merchant adoption. |
| Integrate Biometric Authentication | Integrating biometric authentication enhances transaction security and consumer confidence for higher-value purchases on mobile devices. |
| Expand into Underpenetrated Geographies | Expansion into markets like Latin America captures substantial growth potential for mobile payment providers. |
| Ensure Open Banking Compliance | Compliance with frameworks like Europe's PSD2 unlocks new payment aggregation opportunities for financial institutions. |
| Advance Tokenization Services | Advancing tokenization services reduces PCI DSS compliance scope for merchants and mitigates data breach impacts. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Interviews engaged payment processor executives, fintech founders, retail technology officers, and central bank regulators. Secondary data sources included central bank reports, FTC filings, and payment network transaction data. This approach facilitated bottom-up market sizing and top-down validation of segment projections.
Segment-weighting approaches were applied to project market evolution across the analysis window, integrating volume and value outputs. Segmentation dimensions modeled included payment method, service type, device type, industry vertical, and regional regulatory environment. Compound Annual Growth Rates were derived from historical growth rates and projected adoption trends. Key forecast inputs included global smartphone penetration rates and government digital payment policy initiatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid technological shifts or unforeseen regulatory changes. These forecasts reflect assumptions regarding market dynamics and adoption rates. Deviation in major cybersecurity incidents or central bank policy shifts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Europe Payment Gateways Market
Payments
Mexico POS Terminals Market
Payments
Japan Prepaid Cards Market
Payments
GCC Payment Gateway Market
Payments
Australia Buy Now Pay Later Services Market
Payments
Master Recharge API Market
Payments
Retail Point of Sale (POS) Market
Payments
Voice-Based Payments Market
Payments
Telecom Cloud Billing Market
Payments
United States Electronic Toll Collection Market
Payments
Global Utility Billing Software Market
Payments
Payment Security Market
Payments
Latin America Mobile Payment Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
Forex Prepaid Cards Market
Payments
Direct Carrier Billing Market