
 Wireless POS Terminals Market | 2026-2036
Wireless POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless POS Terminals Market Intelligence
Asset-light leasing and terminal-as-a-service models are reconfiguring competitive entry barriers for smaller merchants who previously could not afford upfront hardware purchases. Ingenico leverages its European manufacturing footprint to sustain channel density across high-traffic retail environments. Verifone anchors North American market presence through integrated software-hardware bundles for enterprise hospitality chains. PAX Global Technology competes aggressively on cost-engineered Android terminals for emerging-market acquirers.
A wireless POS terminal is a battery-powered electronic device that processes card and mobile wallet transactions through encrypted radio frequency links, typically incorporating NFC antennas, EMV chip readers, and PCI-DSS compliant secure elements. These devices enable tableside, curbside, and roaming checkout in venues where fixed cabling is impractical or customer throughput demands mobility. Mobile terminals lead unit shipments among product formats because couriers, pop-up vendors, and delivery fleets require pocket-sized hardware with all-day battery endurance. Cloud-based terminals represent the fastest-growing architecture as acquirers shift firmware management and transaction routing to hosted platforms that reduce on-site IT overhead. Bluetooth and Wi-Fi connectivity dominate technology configurations in indoor retail and restaurant settings where cellular data costs are avoidable.
PCI Security Standards Council requirements, GDPR data handling rules in Europe, and India's RBI digital payment security guidelines collectively shape hardware certification timelines and data architecture choices for terminal manufacturers. FDA does not regulate this equipment class, but FCC emissions compliance in the United States and CE marking under EU radio equipment directives create pre-market testing obligations that filter out undercapitalized entrants. Stakeholders must monitor how central bank real-time payment rollouts and biometric authentication mandates alter the terminal feature sets that merchants will demand next.
Market Dynamics
The Wireless POS Terminals Market is reconfiguring around contactless payment mandates and cloud-native architectures that compress hardware refresh cycles from five-year to three-year intervals.
Growth Catalysts
- Contactless Payment Mandates:The European Union's Payment Services Directive 2 and India's RBI digital payment security guidelines compel merchant hardware upgrades. Street vendors and small merchants in India digitize under government financial inclusion programs.
- Tableside Service Models:Full-service restaurants deploy handheld terminals to reduce checkout friction. Curbside pickup and delivery fleets require pocket-sized hardware with all-day battery endurance.
- Terminal-as-a-Service Leasing:Asset-light subscription models eliminate upfront capital barriers for micro-merchants. Acquirers bundle firmware management and transaction routing through hosted platforms.
Market Restraints
- Semiconductor Supply Concentration:Secure element chip fabrication concentrates among a limited set of foundries. PCI-DSS certification delays extend hardware release timelines when component substitutions occur.
- Cellular Data Cost Volatility:Mobile terminal connectivity depends on roaming agreements between acquirers and network operators. Emerging-market merchants face unpredictable data pricing that erodes transaction margins.
- Bluetooth Range Limitations:Indoor retail settings with dense concrete infrastructure experience signal degradation. Merchants in multi-floor venues must deploy additional access points or revert to cabled backup systems.
Strategic Opportunities
- Biometric Authentication Convergence:Fingerprint and facial recognition modules integrate with NFC antennas. European regulators pilot biometric payment authorization frameworks that would mandate new terminal feature sets.
- Pop-Up and Event Commerce:Temporary retail installations lack fixed infrastructure. Festival organizers and brand activations rent cloud-based terminals for weekend deployments without long-term contracts.
- Real-Time Payment Rail Integration:Central bank instant settlement systems in Brazil, India, and the European Union require terminal firmware updates. Acquirers that preload these protocols capture merchant switching momentum.
Industry Challenges
- PCI-DSS Certification Bottlenecks:Secure element validation requires six-to-nine month testing windows with the PCI Security Standards Council. Hardware manufacturers face revenue recognition delays when certification timelines slip.
- Legacy POS Integration Complexity:Enterprise hospitality chains operate mixed estates of fixed and mobile terminals. Property management system APIs vary by vendor, forcing custom integration work for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless POS Terminals Market |
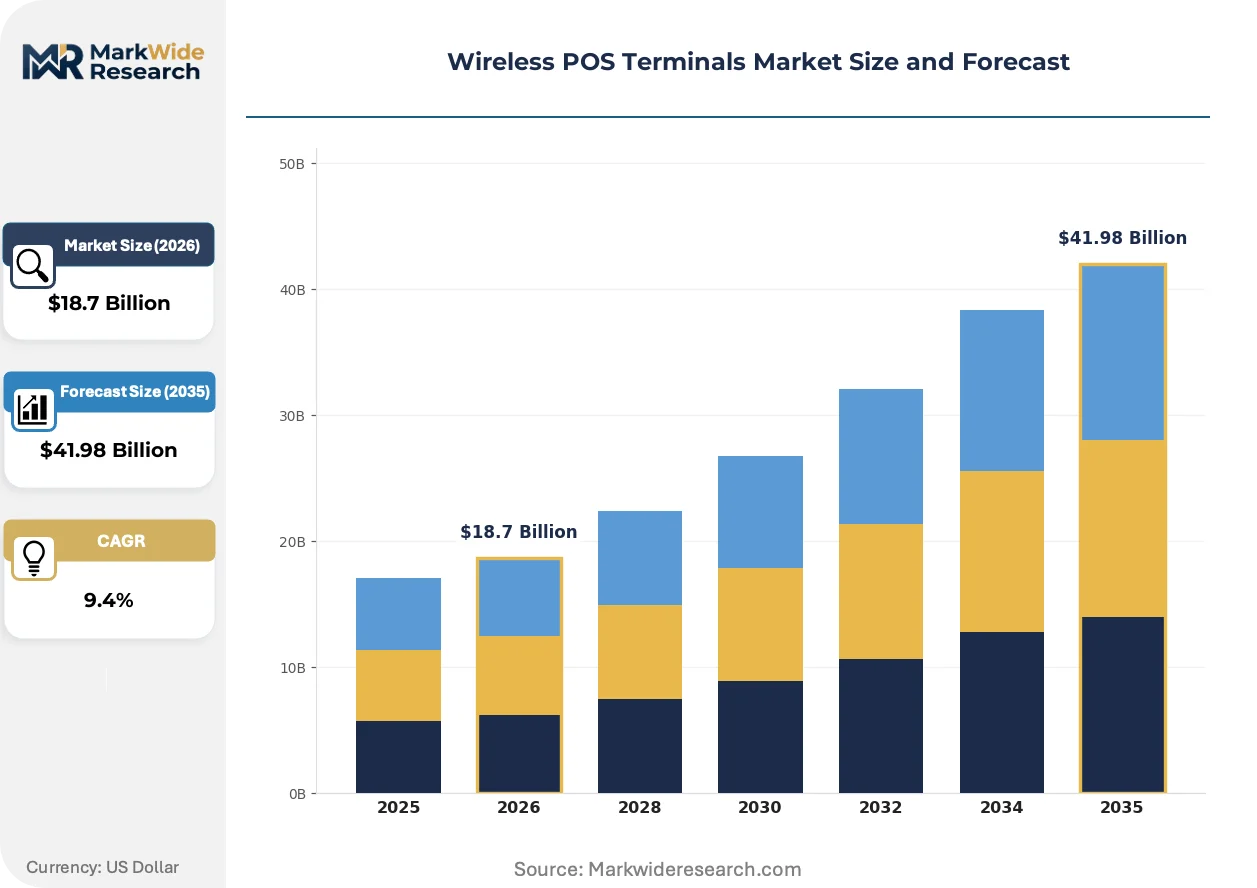
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Terminals, Fixed Terminals, Handheld Terminals, Cloud-Based Terminals Technology: Bluetooth, NFC, Wi-Fi, 4G LTE End User: Retail Stores, Restaurants, Hospitality, Service Providers Payment Method: Credit Cards, Debit Cards, Mobile Wallets, Contactless Payments |
| Companies Covered | Newland Payment, Castles Technology, Ingenico, Nexgo, Bitel, Verifone, Centerm, Clover, PAX Global Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless POS Terminals Market Strategic Shifts & Innovations
Cloud-native terminal architectures are displacing on-premise firmware management. Three developments are compressing competitive differentiation timelines and reshaping how acquirers bundle hardware with payment processing.
SoftPOS technology converts standard Android smartphones into payment acceptance devices without dedicated hardware. Micro-merchants and gig economy couriers adopt these applications for zero capital entry. This capability is digitizing the long tail of cash-dependent street vendors and informal service providers who previously rejected dedicated terminal investments.
The EU AI Act and GDPR data handling rules impose algorithmic transparency requirements on transaction fraud detection systems. Terminal manufacturers must document how on-device risk scoring models process personal data. European acquirers are redesigning data architectures to keep biometric templates and transaction histories within regional cloud boundaries.
Merchant procurement preferences are fragmenting between ownership and subscription models. Large retail chains negotiate volume purchases with extended warranty terms. Small merchants prefer per-transaction pricing that bundles hardware, connectivity, and support into a single percentage fee. Brazil and Southeast Asian markets exhibit the strongest subscription uptake among emerging economies.
Wireless POS Terminals Market Segmentation
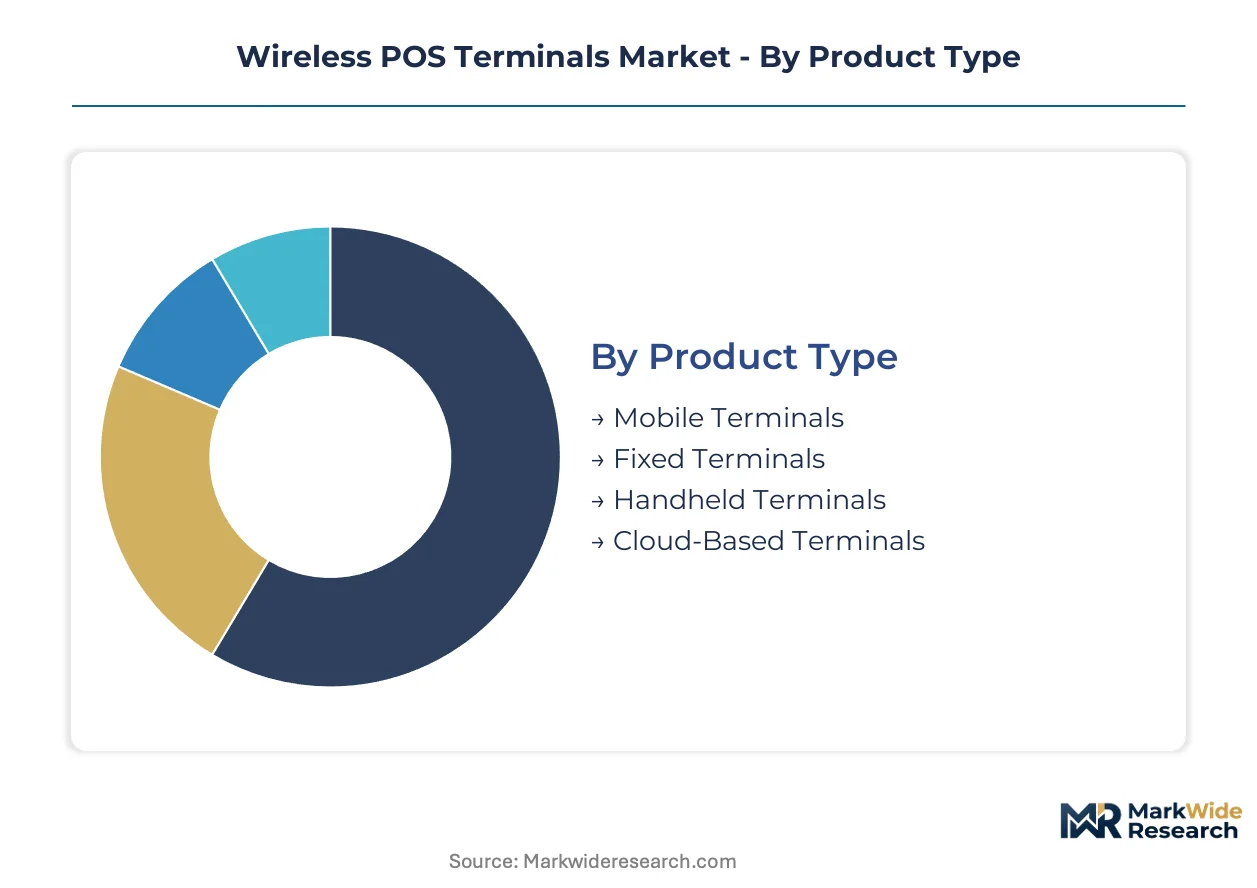
Wireless POS terminal segmentation reveals how hardware form factors, connectivity protocols, and merchant verticals create distinct procurement patterns. Terminal manufacturers configure product portfolios around these divides to match payment acceptance requirements across mobility-intensive environments.
Product Type:
Mature hardware formats dominate installed bases while cloud-native architectures reshape firmware delivery economics.
- Mobile Terminals:Battery-powered pocket-sized devices with cellular radios enable courier fleets, pop-up vendors, and street merchants to process payments without fixed infrastructure. Demand concentrates in India where government financial inclusion programs digitize small merchants and informal service providers.
- Cloud-Based Terminals:These devices offload firmware management and transaction routing to hosted platforms, eliminating on-premise IT overhead for acquirers. European and North American hospitality chains adopt these architectures to compress hardware refresh cycles from five-year to three-year intervals.
- Fixed Terminals:Countertop units with Ethernet connectivity serve high-throughput retail checkout lanes where mobility is unnecessary.
- Handheld Terminals:Larger-format battery devices suit tableside service in full-service restaurants requiring screen visibility and receipt printing.
Mobile terminals handle the majority of throughput; cloud-based terminals are expanding most quickly on share.
Technology:
Cost tier stratification separates indoor connectivity solutions from cellular-dependent field deployments.
- NFC:Near-field communication antennas enable tap-to-pay transactions through encrypted radio links at ranges under 4 centimeters. Regulatory mandates from the European Union's Payment Services Directive 2 and India's RBI digital payment security guidelines compel merchant hardware upgrades to support contactless protocols.
- Wi-Fi:Indoor wireless connectivity dominates restaurant and retail settings where merchants avoid recurring cellular data charges. Dense concrete infrastructure in multi-floor venues creates signal degradation challenges that force additional access point deployment.
- Bluetooth:Short-range radio links connect peripheral card readers to smartphones or tablets in low-cost SoftPOS configurations.
- 4G LTE:Cellular connectivity enables true mobility for delivery fleets and outdoor commerce where Wi-Fi infrastructure is absent.
Wi-Fi anchors volume in established markets; NFC is gaining share fastest as contactless mandates proliferate.
End User:
Application intensity varies across merchant verticals with divergent mobility requirements and transaction velocity profiles.
- Restaurants:Full-service dining establishments deploy handheld and mobile terminals for tableside checkout, reducing friction between meal completion and payment. Curbside pickup and delivery fleet integration drives demand for all-day battery endurance.
- Retail Stores:Fixed-terminal dominance in high-throughput checkout lanes is eroding as merchants experiment with roaming associates equipped with mobile devices for line-busting during peak hours.
- Hospitality:Hotels and resorts require mixed estates of fixed front-desk terminals and mobile units for poolside, spa, and event charging.
- Service Providers:Plumbers, electricians, and home healthcare workers adopt SoftPOS or dedicated mobile terminals to accept payment at point of service completion.
Restaurants command the steepest mobility requirements; retail stores retain the largest installed base.
Payment Method:
Customer type fragmentation separates legacy card-present transactions from emerging wallet-based acceptance.
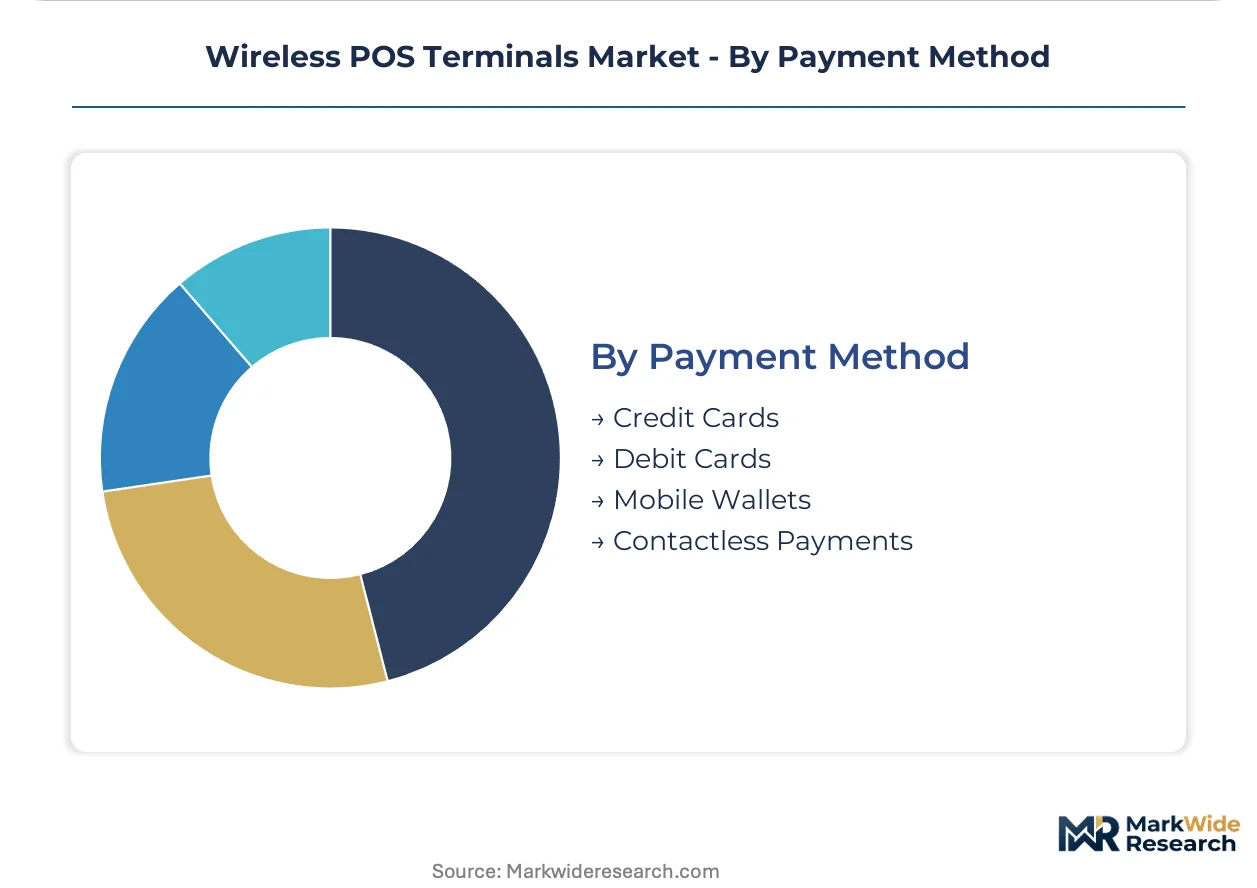
- Contactless Payments:Tap-to-pay protocols using NFC or QR codes accelerate checkout velocity in high-traffic environments. Street vendors in India and quick-service restaurants in Europe lead adoption as consumers abandon cash and chip-insertion delays.
- Mobile Wallets:Apple Pay, Google Pay, and regional wallet applications require terminal NFC capability and certified secure element integration. Central bank real-time payment rollouts in Brazil and the European Union drive firmware updates to support wallet-to-wallet transfers.
- Credit Cards:EMV chip-and-PIN or chip-and-signature transactions remain the revenue backbone for acquirer interchange economics.
- Debit Cards:PIN-based debit routing carries lower interchange rates but higher transaction volume in everyday commerce.
Credit cards process the highest transaction value; contactless payments are climbing the fastest on volume share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wireless POS terminal trade flows reflect divergent regulatory mandates and merchant digitization speeds across major economies. Hardware exporters in East Asia supply acquirers in Europe and North America facing accelerated refresh cycles. Import-dependent emerging markets leverage government financial inclusion programs to compress cash-to-digital transitions.
United States
Enterprise hospitality chains and quick-service restaurants drive terminal procurement for tableside and curbside checkout. FCC emissions compliance creates pre-market testing obligations that filter out undercapitalized hardware entrants. California and New York Metro clusters host fintech acquirers bundling software-hardware solutions for national retail rollouts.
Germany
Retail chains and fuel stations upgrade fixed-terminal estates under contactless payment adoption pressure. GDPR data handling rules and EU AI Act algorithmic transparency requirements reshape terminal firmware architectures. The Eindhoven-Randstad corridor channels hardware distribution into Benelux retail environments.
India
Street vendors and small merchants digitize payments under RBI digital payment security guidelines and government financial inclusion programs. Domestic terminal manufacturing scales to serve micro-merchant segments previously excluded from formal banking. Maharashtra and Karnataka urban clusters concentrate acquirer deployment teams for merchant onboarding.
Brazil
Central bank real-time payment rails and instant settlement systems drive firmware updates across existing terminal installed bases. Subscription-based terminal-as-a-service models gain traction among informal commerce operators avoiding upfront hardware purchases. São Paulo anchors acquirer competition for merchant switching momentum.
United Kingdom
Payment Services Directive 2 compliance compels hardware upgrades across hospitality and retail merchant categories. SoftPOS adoption accelerates among gig economy couriers and temporary event vendors. London fintech clusters develop cloud-native terminal management platforms for European market expansion.
Wireless POS Terminals Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying secure elements and radio modules. Market structure concentrates around three to five vertically integrated terminal manufacturers with PCI-DSS certification capabilities and established acquirer relationships. Two strategic archetypes dominate: European manufacturers leveraging regional regulatory proximity and East Asian cost-engineered Android terminal producers. Competitive moves center on cloud-native firmware platform development and biometric authentication module integration.
Within the integrated hardware tier, Ingenico and Verifone occupy positions exemplifying European and North American regulatory anchoring strategies. PAX Global Technology represents the cost-engineered Android terminal archetype competing for emerging-market acquirer contracts. Newland Payment and Castles Technology sit within the specialist manufacturer segment serving regional payment networks with customized form factors.
| Leading Market Players |
|---|
| Newland Payment |
| Castles Technology |
| Ingenico |
| Nexgo |
| Bitel |
| Verifone |
| Centerm |
| Clover |
| PAX Global Technology |
| Others |
Cost & Logistics Intelligence
The Shenzhen-Rotterdam maritime corridor carries secure element chips and radio modules from East Asian foundries to European assembly facilities, with freight cost volatility amplifying price spreads between premium-certified and economy-tier terminal configurations. Supply concentration in Taiwan and South Korea for PCI-DSS compliant secure elements grants upstream suppliers pricing leverage over downstream hardware manufacturers serving price-sensitive micro-merchant segments.
Pricing Analysis
Enterprise hospitality chains anchor terminal-as-a-service subscription pricing across three tiers: premium bundles with biometric modules, standard cloud-native configurations, and economy units for single-location merchants. Price differentiation rests on PCI-DSS certification grade and after-sales firmware support intensity. Cost compression in the economy tier is intensifying because SoftPOS applications eliminate dedicated hardware requirements for gig economy couriers. Street vendors and informal service providers exhibit highest price sensitivity; multinational retail chains negotiating volume commitments show lowest.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier financing arrangements between Taiwanese secure element foundries and terminal OEMs managing working capital through supply-chain finance facilities. Manufacturing concentrates in China, Taiwan, and Vietnam for final assembly, drawing from South Korean NFC antenna substrates and Dutch semiconductor lithography equipment. Single-source vulnerability in EMV chip fabrication creates procurement risk when foundry capacity reallocates to automotive semiconductors. Distribution runs through acquirer-direct channels and regional payment network partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contactless payment mandates across the European Union, India, and Brazil are compressing hardware refresh cycles and opening white-space for biometric-enabled terminal architectures. This regulatory inflection creates asymmetric opportunity for prepared participants.
For Market Incumbents: Pre-empt SoftPOS displacement by accelerating cloud-native firmware platform deployment and securing exclusive biometric authentication partnerships with European regulators piloting facial recognition payment frameworks. Vertical integration into secure element sourcing mitigates foundry concentration risk. Channel control through acquirer-exclusive bundles defends against Android terminal cost competition from East Asian entrants. For New Entrants and Emerging Players: Establish a beachhead in India's micro-merchant segment where government financial inclusion programs subsidize terminal deployment and domestic manufacturing incentives reduce import cost barriers. Pop-up commerce and festival event rentals offer the most penetrable application with minimal incumbent lock-in. A per-transaction pricing model bundling hardware, connectivity, and support eliminates upfront capital objections from cash-dependent street vendors. For Investors and Strategic Acquirers: EU AI Act algorithmic transparency requirements reshape the acquisition landscape by elevating terminal manufacturers with documented on-device risk scoring architectures and regional cloud data residency capabilities. Long-term viability centers on firmware platform recurring revenue rather than hardware shipment economics. The signal to watch is central bank real-time payment rail integration timelines in Brazil and India as merchant switching momentum indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Module Integration | European Payment Services Directive 2 pilots position fingerprint-enabled terminals for regulatory-mandated authorization frameworks. |
| Cloud-Native Firmware Platform | Hosted transaction routing reduces on-premise IT overhead for acquirers managing multi-merchant estates across dispersed geographies. |
| SoftPOS Application Development | Android smartphone conversion eliminates dedicated hardware costs for gig economy couriers and informal service providers. |
| Regional Manufacturing Footprint | India's PLI scheme incentives enable cost-competitive production for government financial inclusion program procurement. |
| Real-Time Payment Rail Preloading | Central bank instant settlement protocol integration captures merchant switching momentum in Brazil and European Union markets. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with terminal OEM product managers, acquirer merchant onboarding directors, payment network certification officers, and PCI Security Standards Council audit specialists; and secondary validation through SEC 10-K hardware revenue disclosures, RBI digital payment security guideline amendments, EU Payment Services Directive 2 implementation trackers, and customs import records for secure element chip trade flows. Bottom-up merchant adoption modeling and top-down terminal shipment aggregation were triangulated against regional regulatory rollout schedules.
Forecast inputs considered product type segmentation across mobile, cloud-based, fixed, and handheld architectures; technology configurations spanning NFC, Wi-Fi, Bluetooth, and 4G LTE; and end-user verticals including restaurants, retail stores, hospitality, and service providers. CAGRs were derived from regression analysis against contactless payment mandate implementation timelines and central bank real-time payment system deployment schedules across the projection horizon. Industry-specific inputs incorporated PCI-DSS certification bottleneck durations and SoftPOS smartphone penetration elasticity.
Stress conditions across secure element foundry capacity allocation, cellular data roaming tariff volatility, and biometric authentication regulatory approval timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding mandate compliance deadlines and merchant digitization subsidy continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Middle East and Africa Payment Gateway Market
Payments
Cyprus POS Terminals Market
Payments
Mobile Wallet Market
Payments
Philippines Remittance Market
Payments
Payment Orchestration Platform Market
Payments
Global Prepaid Cards Market
Payments
LAMEA Payment Gateway Market
Payments
Electronic Cash Register Market
Payments
Europe Mobile Payment Market
Payments
Global Gift Card Market
Payments
Japan Payments Market
Payments
Middle East and Africa Prepaid Card Market
Payments
B2C Payment Market
Payments
Fuel and Convenience Store POS Market
Payments
Canada Payment Gateway Market
Payments
Asia Pacific Buy Now Pay Later Service Market