
 Australia Buy Now Pay Later Services Market | 2026-2036
Australia Buy Now Pay Later Services Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Buy Now Pay Later Services Market Outlook
Australian fintech infrastructure is consolidating around embedded lending rails. Afterpay Limited anchors the domestic landscape through merchant network density and brand recognition among younger demographics. Zip Co Limited competes via geographic extension into adjacent financial services beyond pure checkout credit. Humm Group Limited specializes in higher-ticket verticals including healthcare and automotive, diversifying away from saturated retail segments.
Buy Now Pay Later services constitute short-term, interest-free installment credit products repaid through automated debit schedules tied to consumer bank accounts or cards. These instruments embed directly at merchant point-of-sale, splitting transactions into equal payments with merchant-funded interchange-style fees replacing traditional interest income. The e-commerce segment leads transaction volume due to cart abandonment reduction and checkout conversion optimization, while healthcare represents an emerging margin pool as dental and optical providers adopt patient financing. Millennials dominate current enrollment, though Gen Z accounts for the fastest-growing cohort as first-time credit seekers bypass legacy card products.
ASIC enforces design and distribution obligations requiring issuers to demonstrate target market appropriateness, while the National Consumer Credit Protection Act governs responsible lending assessments for higher-risk products. The Australian Treasury's ongoing BNPL regulatory framework review threatens reclassification under credit licensing regimes, compelling providers to fortify compliance architecture. Stakeholders must monitor whether prescriptive affordability checks displace the frictionless onboarding that currently drives merchant adoption and consumer enrollment.
Market Dynamics
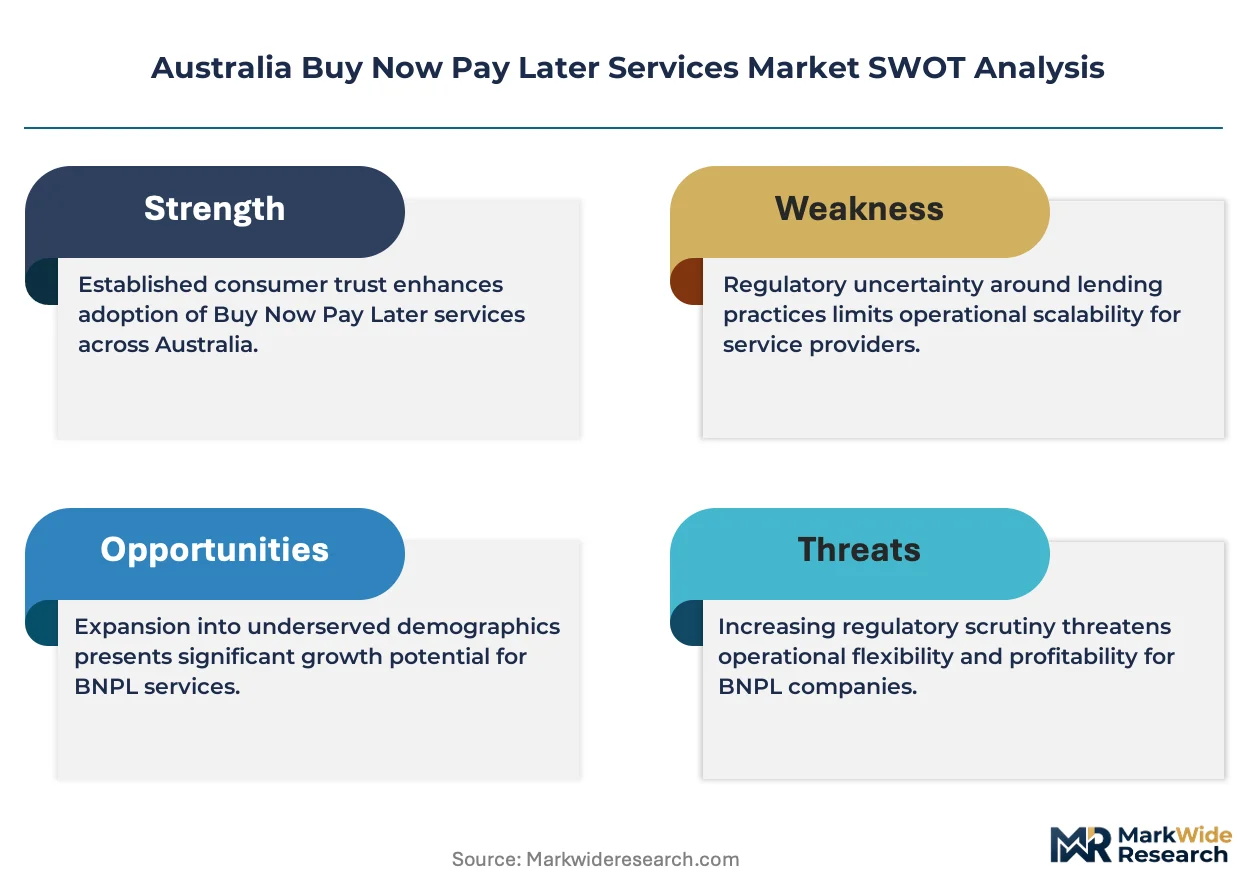
ASIC's design and distribution obligations and the Treasury's pending BNPL regulatory review are compressing onboarding friction while forcing issuers to rebuild compliance architecture around affordability verification.
Growth Catalysts
- Merchant-funded fee structures:Retailers absorb interchange-style fees to reduce cart abandonment, embedding installment options at Sydney and Melbourne checkout flows without consumer interest burdens.
- Healthcare vertical expansion:Dental and optical providers adopt patient financing for elective procedures, opening margin pools beyond saturated retail segments.
- Automated debit rails:Direct bank account linking through NPP infrastructure enables seamless repayment scheduling without card network dependencies.
Market Restraints
- Regulatory reclassification risk:The National Consumer Credit Protection Act threatens to impose credit licensing regimes on BNPL providers, raising capital adequacy and compliance cost structures.
- Funding concentration:Wholesale debt markets in Australia supply the majority of origination capital, exposing providers to RBA rate volatility and bank funding cost pass-through.
- Substitute product pressure:Low-rate credit cards and personal loans from major banks compete for the same millennial and Gen Z borrower segments.
Strategic Opportunities
- Regional bank partnerships:Collaborations with Queensland and Western Australian mutual banks extend distribution into underpenetrated non-metropolitan postcodes.
- Superannuation-linked products:Early access frameworks for hardship withdrawals create adjacent financing structures for healthcare and education verticals.
- Open Banking convergence:CDR data sharing mandates enable real-time income verification, reducing default rates while preserving frictionless enrollment.
Industry Challenges
- Responsible lending skill gaps:ASIC's target market determinations require specialized compliance functions that fintechs must build or acquire rapidly.
- Legacy core banking integration:Real-time payment scheduling demands API connectivity with incumbent transaction banking platforms that resist modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Buy Now Pay Later Services Market |
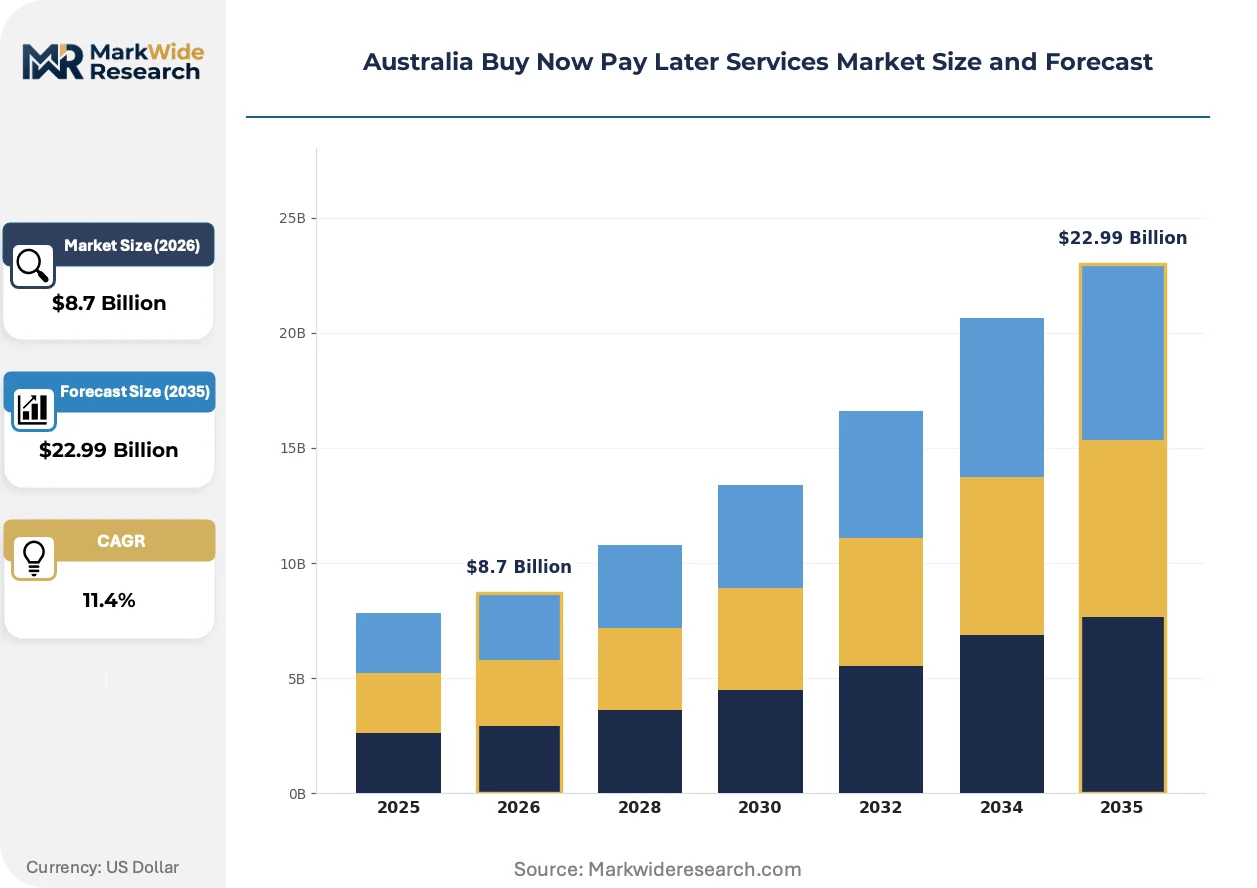
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Retail, Travel, E-commerce, Healthcare Customer Type: Millennials, Gen Z, Families, Students Payment Method: Debit Card, Credit Card, Direct Debit, Digital Wallet Transaction Size: Small, Medium, Large, High Value |
| Companies Covered | Klarna, Sezzle, Afterpay Limited, Openpay, Laybuy, Zip Co Limited, CommBank StepPay, Payright, Humm Group Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Buy Now Pay Later Services Market Strategic Shifts
Embedded finance architecture and real-time payment infrastructure are dissolving boundaries between lending, payments, and commerce in the Australian BNPL sector.
Machine learning-based transaction monitoring is automating fraud detection and credit decisioning at enrollment. Major merchants in Brisbane and Perth deploy these tools to approve applications in under 30 seconds. The compression of manual underwriting is automating scale without proportional headcount growth.
ASIC's design and distribution obligations now mandate documented target market appropriateness for all credit products. Issuers must maintain granular records of consumer suitability assessments. The regulatory burden falls most heavily on smaller providers lacking dedicated compliance infrastructure, accelerating consolidation toward scaled platforms.
Younger borrowers increasingly bypass traditional credit bureaus entirely, preferring cash-flow-based underwriting that analyzes transaction history over legacy scorecards. This behavioral pivot favors fintechs with direct bank account connectivity. The shift concentrates in Sydney and Melbourne metropolitan corridors where digital banking penetration peaks.
Australia Buy Now Pay Later Services Market Segmentation
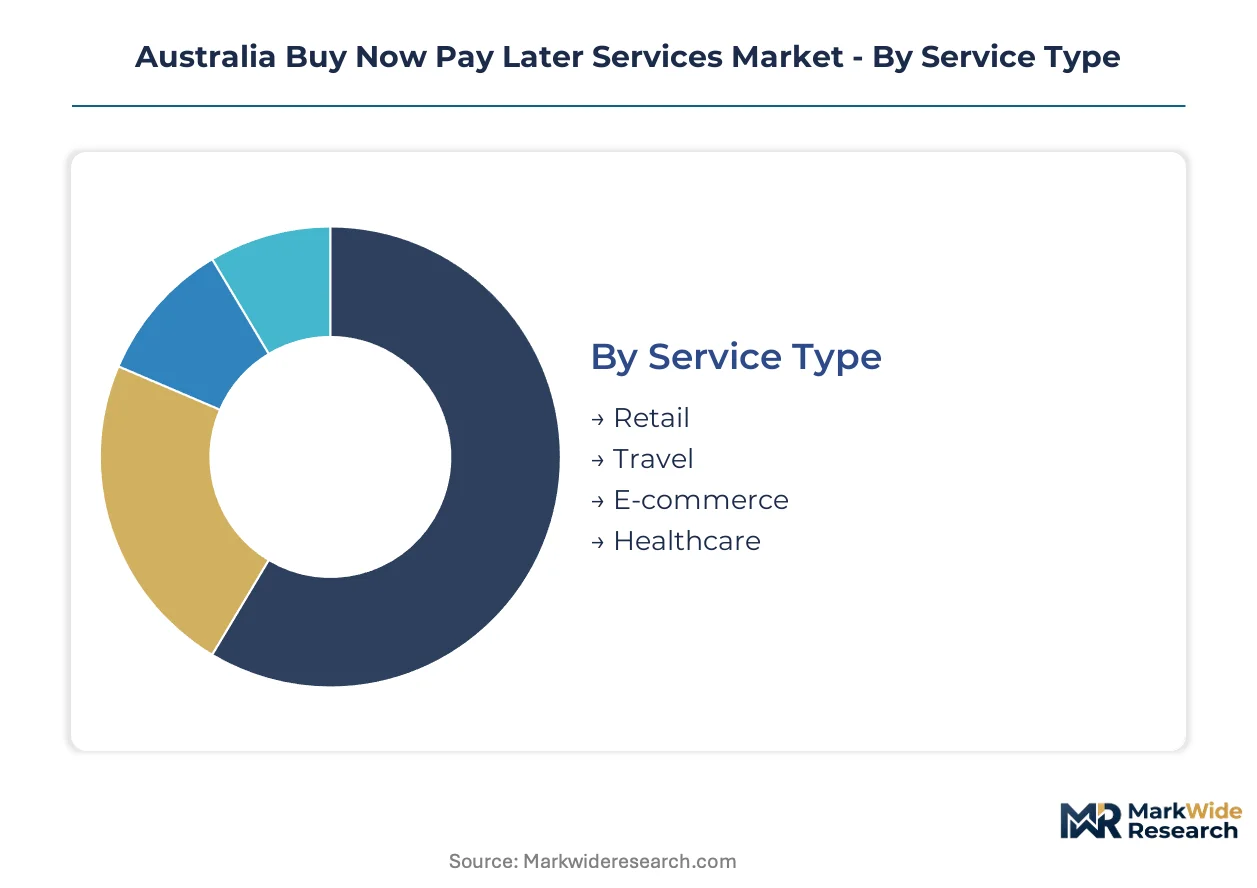
Australian BNPL providers structure product architecture around distinct risk-return profiles. Service type and customer cohort determine underwriting models, while payment rails and transaction size shape operational cost structures.
Service Type:
Merchant category codes drive fee negotiation leverage and default probability curves.
- Retail:Apparel and electronics merchants fund interchange-style fees to reduce cart abandonment at Sydney and Melbourne checkout flows. ASIC's design and distribution obligations compel documented target market appropriateness for discretionary spending categories.
- E-commerce:Online checkout integration enables seamless enrollment through embedded finance widgets. Brisbane and Perth merchants deploy machine learning decisioning to compress approval times below 30 seconds.
- Healthcare:Dental and optical providers adopt patient financing for elective procedures, opening margin pools beyond saturated retail segments.
- Travel:Airlines and accommodation platforms use installment structures to convert high-ticket bookings without traditional credit card interest burdens.
Volume sits with Retail; growth tilts toward Healthcare.
Customer Type:
Generational credit behavior determines acquisition channel strategy and product messaging.
- Gen Z:First-time credit seekers bypass legacy card products entirely, preferring cash-flow-based underwriting through direct bank account connectivity.
- Millennials:Established digital banking users concentrate in metropolitan corridors where NPP infrastructure enables seamless repayment scheduling.
- Families:Household budget smoothing drives adoption for back-to-school and seasonal spending clusters.
- Students:Limited credit history segments require alternative data integration through Open Banking frameworks.
Millennials anchor current enrollment; Gen Z climbs the fastest as native digital payment behavior matures.
Payment Method:
Rail selection shapes funding cost exposure and regulatory treatment boundaries.
- Direct Debit:NPP-linked bank account pulls eliminate card network dependencies and reduce merchant discount rates.
- Debit Card:Consumer-funded repayment structures limit issuer exposure to overdraft sequences.
- Digital Wallet:Apple Pay and Google Pay integration streamlines mobile-first enrollment flows.
- Credit Card:Card-on-file arrangements persist among legacy users though regulatory scrutiny intensifies on layered credit products.
Direct Debit captures transaction volume; Digital Wallet gains share fastest through smartphone-native demographics.
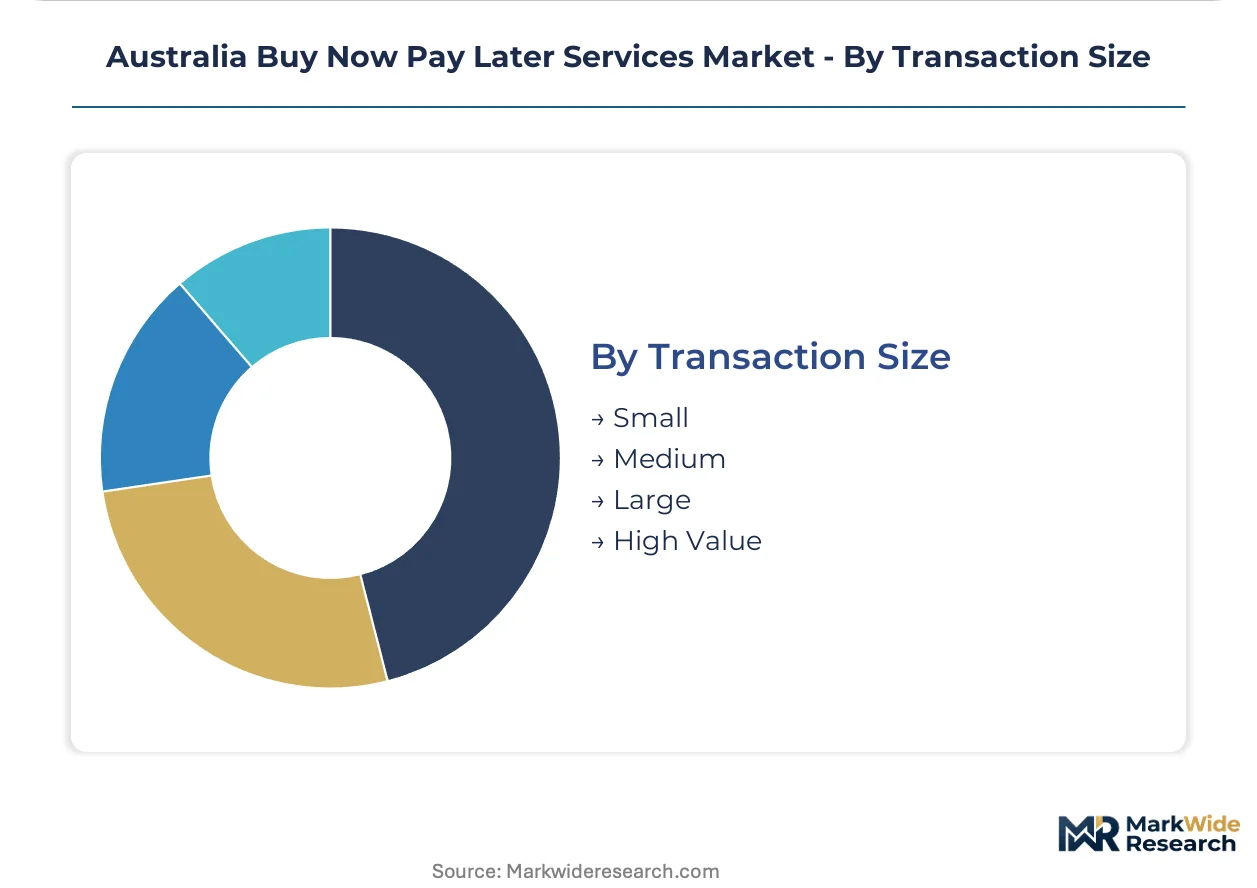
Transaction Size:
Ticket stratification determines capital allocation intensity and default loss severity.
- Small:Sub-$200 purchases dominate frequency metrics and merchant network density calculations.
- Medium:$200-$1,000 baskets balance unit economics with manageable affordability verification burdens.
- Large:$1,000-$5,000 tickets require enhanced income verification through CDR data sharing mandates.
- High Value:Elective healthcare and automotive segments demand specialized underwriting for extended repayment schedules.
Small transactions sustain network scale; High Value delivers margin expansion through specialized vertical focus.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore deposits in Western Australia's Pilbara region anchor the nation's commodity-linked consumer credit infrastructure. The concentration of mining payrolls in Perth and regional hubs generates stable income streams that BNPL providers underwrite through automated bank account verification.
New South Wales
Sydney's fintech corridor drives merchant network density across apparel and electronics verticals. ASIC's design and distribution obligations compel documented target market assessments for discretionary spending products. The Parramatta-Inner West cluster hosts embedded finance engineering teams building real-time decisioning infrastructure.
Victoria
Melbourne's healthcare precincts expand patient financing for dental and optical procedures beyond saturated retail segments. The state's Consumer Affairs Victoria enforces responsible lending standards alongside federal Treasury frameworks. The Docklands-Southbank corridor concentrates BNPL engineering talent and merchant partnership headquarters.
Queensland
Brisbane's tourism and accommodation platforms adopt installment structures for high-ticket bookings without traditional interest burdens. The Queensland Civil and Administrative Tribunal adjudicates consumer credit disputes under harmonized national standards. The Gold Coast-Sunshine Coast corridor tests regional bank partnerships for non-metropolitan distribution.
Western Australia
Perth's mining payroll concentration enables cash-flow-based underwriting through direct NPP-linked bank account connectivity. The state's Department of Mines, Industry Regulation and Safety monitors consumer protection in resource-dependent communities. The Pilbara-Kalgoorlie corridor represents an underpenetrated postcode cluster for specialized income-verification products.
South Australia
Adelaide's automotive retail sector adopts higher-ticket installment financing for vehicle purchases and maintenance clusters. The state's Office of Consumer and Business Affairs enforces credit code compliance alongside ASIC federal obligations. The Adelaide Hills-Barossa corridor tests superannuation-linked hardship financing for elective healthcare verticals.
Australia Buy Now Pay Later Services Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue geographic extension and vertical specialization beyond pure checkout credit. The market exhibits tiered consolidation around three strategic archetypes: merchant network density specialists, healthcare vertical diversifiers, and banking-integrated incumbents. Competitive positioning sharpens through M&A consolidation of smaller providers lacking dedicated compliance infrastructure, alongside strategic partnerships with regional mutual banks for non-metropolitan distribution.
Within the banking-integrated tier, CommBank StepPay represents incumbent defensive positioning against fintech disruption. Among pure-play specialists, Afterpay Limited and Zip Co Limited exemplify contrasting geographic and vertical strategies. Humm Group Limited occupies a position in higher-ticket specialization. These three anchors demonstrate how scale, regulation, and vertical focus separate surviving platforms from acquisition targets.
| Leading Market Players |
|---|
| Klarna |
| Sezzle |
| Afterpay Limited |
| Openpay |
| Laybuy |
| Zip Co Limited |
| CommBank StepPay |
| Payright |
| Humm Group Limited |
| Others |
Value Chain & Pricing Dynamics
Embedded compliance engineering talent concentrated in Sydney's Parramatta-Inner West corridor commands premium compensation differentials that widen pricing spreads between tier-one platforms and regional challengers. Labor cost stratification reinforces three-tier pricing architecture across premium merchant-integrated, standard checkout-embedded, and economy white-label service tiers.
Pricing Analysis
Merchant-funded interchange-style fees bundle automated repayment scheduling and fraud monitoring without unbundling credit risk assessment as a separate line item. Three-tier pricing structure across premium, standard, and economy levels reflects underwriting automation depth and API integration sophistication. Pricing pressure stems from ASIC's pending affordability verification mandates compelling compliance infrastructure investment. Small regional fintechs exhibit highest price sensitivity; scaled platforms with dedicated compliance functions absorb cost compression most effectively.
Supply Chain Analysis
Direct-to-merchant API channels handle hyperscale retailer demand in Sydney and Melbourne, while indirect distribution through payment processors extends reach into Brisbane and Perth mid-market segments. Wholesale debt markets in Australia, the United States, and the United Kingdom supply origination capital. Funding cost exposure rests on RBA rate volatility and bank funding pass-through mechanisms. Single-source vulnerability concentrates in domestic wholesale debt dependence. Distribution runs through embedded finance widgets at merchant checkout and white-label partnerships with regional mutual banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASIC's design and distribution obligations function as a cost-of-compliance moat, elevating barrier-to-entry economics that favor incumbent platforms with dedicated regulatory infrastructure over capital-constrained challengers.
For Market Incumbents: Acquire specialized compliance functions and target market determination documentation capabilities to consolidate market position. Defensive consolidation of smaller providers lacking ASIC-mandated infrastructure accelerates network density advantages. Threat substitution from low-rate credit card products intensifies as major banks sharpen millennial acquisition strategies. Channel control through exclusive merchant partnerships in healthcare verticals reinforces pricing power. For New Entrants and Emerging Players: Capture underpenetrated non-metropolitan postcodes in Western Australia's Pilbara-Kalgoorlie corridor and Queensland's Gold Coast-Sunshine Coast region where income verification products tied to mining payrolls face limited competition. White-space concentration sits with superannuation-linked hardship financing for elective healthcare procedures. Go-to-market execution through partnerships with Queensland and Western Australian mutual banks extends distribution without proprietary merchant network buildout. For Investors and Strategic Acquirers: Re-rating potential sits with healthcare-vertical specialists given dental and optical patient financing margin expansion and regulatory clarity from Treasury's BNPL framework review. Long-term viability across the analysis window favors platforms with Open Banking-enabled real-time income verification and NPP-linked repayment infrastructure. Acquisition target archetype: scaled providers with documented target market appropriateness systems and geographic extension capabilities. Signal to watch: Treasury regulatory reclassification timing and capital adequacy requirement implementation.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Infrastructure Buildout | ASIC-mandated target market determination systems create sustainable competitive differentiation against undercapitalized rivals. |
| Healthcare Vertical Partnership | Dental and optical provider networks unlock margin pools beyond saturated retail apparel and electronics segments. |
| Open Banking Integration | CDR data sharing mandates enable real-time income verification that reduces default rates while preserving frictionless enrollment. |
| Regional Bank Collaboration | Queensland and Western Australian mutual bank partnerships extend distribution into underpenetrated non-metropolitan postcodes. |
| NPP Rail Migration | Direct bank account linking through New Payments Platform infrastructure eliminates card network dependencies and merchant discount rate exposure. |
Study Parameters
ASIC regulatory filings, Treasury consultation papers, and NPP Australia infrastructure disclosures formed the secondary backbone for compliance architecture and payment rail evolution assessment. Primary interviews with BNPL product executives, merchant partnership leads, regulatory affairs specialists, and Open Banking integration engineers combined with secondary validation. Bottom-up transaction volume modeling and top-down market sizing triangulation anchored quantitative outputs.
Historical trendline analysis of enrollment growth, merchant network expansion, and default rate trajectories informed projection frameworks across the modeling period. Segmentation dimensions modeled include service type, customer cohort, payment rail, and transaction size tier. CAGRs derived from regression analysis of adoption curves and regulatory impact scenarios. Forecast inputs incorporated NPP penetration rates and CDR data sharing mandate implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Treasury regulatory reclassification timing and RBA rate cycle trajectory. Forecasts reflect base-case assumptions regarding affordability verification implementation scope and merchant fee absorption capacity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Money Transfer Agencies Market
Payments
Europe Payment Analytics Software Market
Payments
Saudi Arabia Payment Gateway Market
Payments
Sweden Payments Market
Payments
Direct Carrier Billing Market
Payments
Indonesia Payments Infrastructure Market
Payments
Middle East & North Africa Digital Payments Market
Payments
UK Virtual Cards Market
Payments
Social Media Payment Solution Market
Payments
Subscription Billing Management Market
Payments
Europe Clearing Houses and Settlements Market
Payments
Direct Carrier Billing Platform Market
Payments
Global Wearable Payment Device Market
Payments
Payment Processing Solutions Market
Payments
Accelerator Card Market
Payments
Clearing Houses and Settlements Market