
 NFC Payments Market | 2026-2036
NFC Payments Market Size, Share, and Industry Trends Forecast 2026-2036
NFC Payments Market Analysis
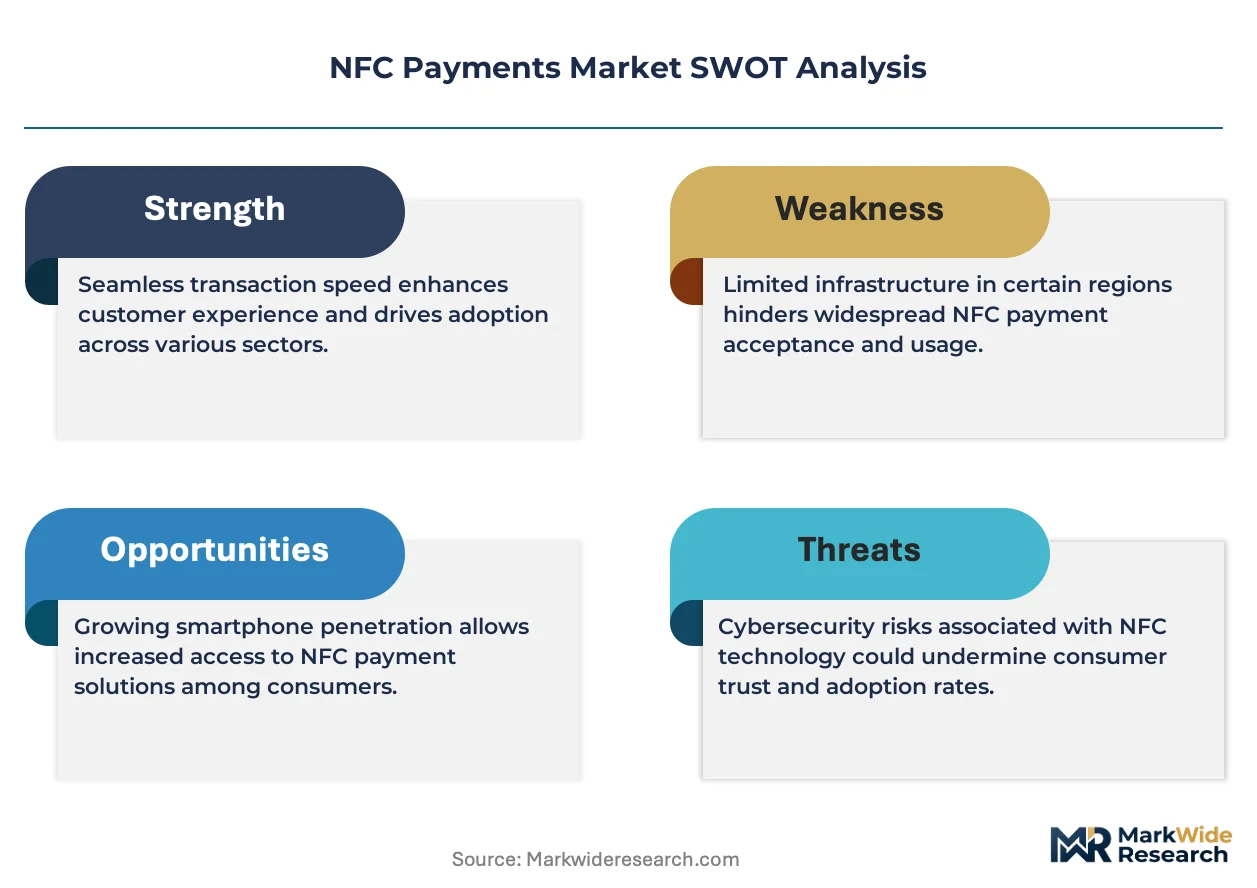
The gap between premium tokenized wallet experiences and commodity NFC transit passes is repositioning how vendors allocate engineering resources. Apple leverages its secure element architecture to dominate high-value in-store payments. Samsung Electronics competes through Knox security integration across its device ecosystem. Adyen sustains merchant relationships by unifying online and offline acceptance rails.
NFC payments rely on near-field communication protocols operating at 13.56 MHz to exchange encrypted data between devices and readers across distances under 10 centimeters, primarily enabling contactless financial transactions and access control. The technology's industrial purpose centers on reducing checkout friction while maintaining EMVCo security standards for card-present equivalence. Digital wallet and wearable device segments are capturing margin pools as consumers shift from physical card tap-to-pay toward smartphone and smartwatch provisioning. POS terminal deployments lag smartphone penetration, creating a hardware upgrade cycle that benefits terminal manufacturers and merchant acquirers.
The US Federal Reserve and NHTSA influence payment system stability and connected vehicle commerce standards respectively, while the EU's PSD2 strong customer authentication rules shape how European issuers validate NFC transactions. Compliance with PCI DSS and EMVCo certification frameworks determines market access for new terminal entrants and wallet providers. Stakeholders must monitor how central bank digital currency pilots reshape tokenization requirements and merchant fee structures.
Market Dynamics
Merchant POS terminal refresh cycles are compressing as transit authorities and grocery chains mandate contactless acceptance, forcing acquirers to reconcile hardware deployment costs against thin interchange margins.
Growth Catalysts
- EU PSD2 Strong Customer Authentication:European issuers must validate NFC transactions through multi-factor protocols, expanding tokenization infrastructure demand across the continent's payment rails.
- Transit Authority Modernization:Urban transportation systems in the United States are replacing legacy fare collection with open-loop NFC acceptance, creating captive volume for terminal manufacturers.
- Secure Element Architecture:Hardware-based encryption is displacing software-only security in high-value in-store payments, elevating certification requirements for wallet providers.
Market Restraints
- Terminal Hardware Concentration:POS device manufacturing concentrates among Asian component suppliers, exposing acquirers to semiconductor allocation volatility and extended lead times.
- EMVCo Certification Friction:New terminal entrants face 12-18 month approval timelines for contactless kernel compliance, delaying market entry and freezing small vendor participation.
- Biometric Data Liability:GDPR and the EU AI Act impose strict processing constraints on facial and fingerprint authentication, raising compliance costs for wallet providers operating across European jurisdictions.
Strategic Opportunities
- Connected Vehicle Commerce:NHTSA-influenced standards for in-car payments are converging with NFC and ultra-wideband protocols, opening fuel and tolling applications for automotive OEM integration.
- Central Bank Digital Currency Pilots:Federal Reserve experimentation with tokenized settlement is reshaping backend infrastructure requirements for merchant acquirers preparing for programmable money.
- Wearable Device Provisioning:Smartwatch payment activation rates lag smartphone penetration by 40 percentage points, representing white space for OEM-wallet partnerships in the United States.
Industry Challenges
- Legacy POS Integration Complexity:Merchants operating mixed estates of countertop and mobile terminals face fragmented reporting and reconciliation workflows that erode operational efficiency.
- PCI DSS Audit Compression:Annual certification cycles for Level 1 merchants are compressing as attack surface expansion from IoT-connected terminals triggers more frequent assessor reviews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NFC Payments Market |
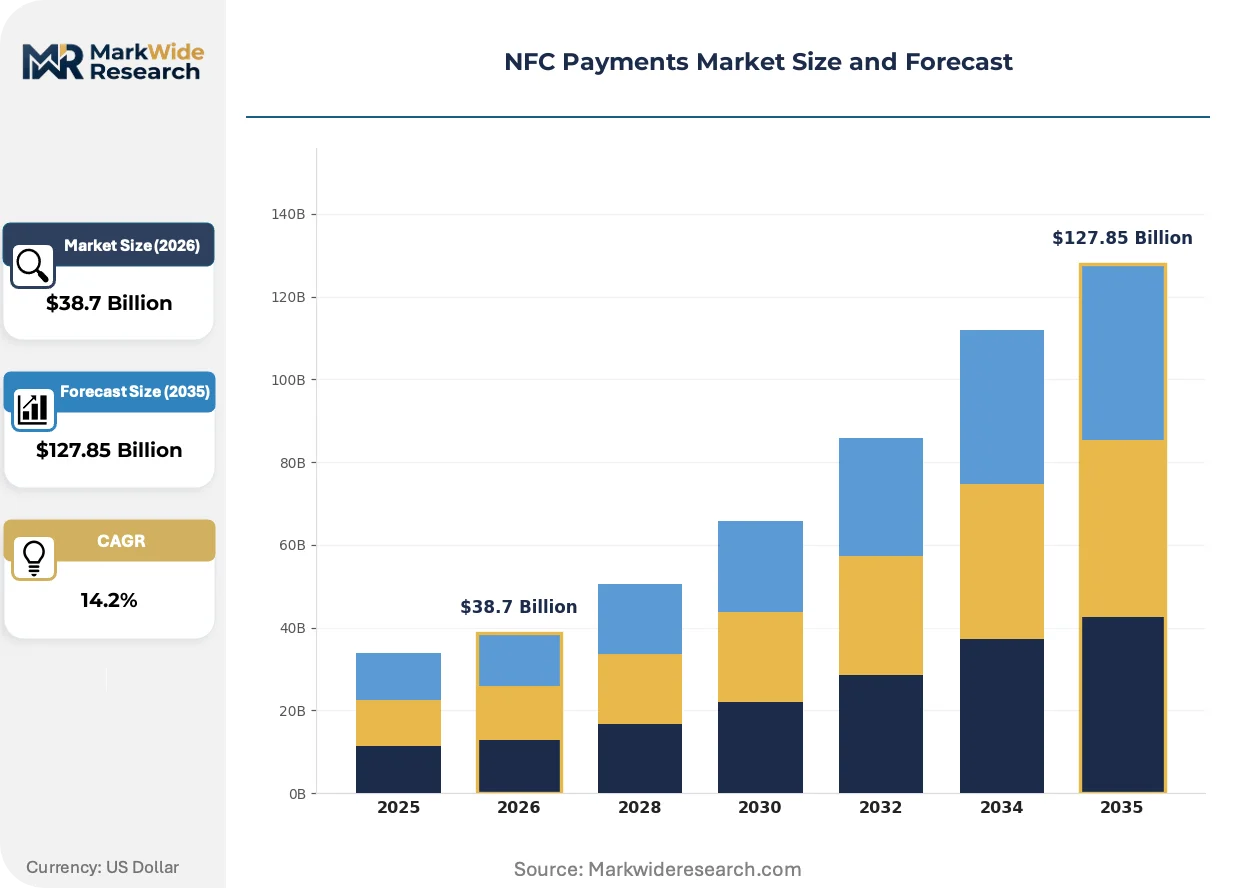
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Digital Wallet, Mobile App, Wearable Device End User: Retail Consumers, Businesses, Merchants, Online Shoppers Device Type: Smartphones, Tablets, POS Terminals, Smartwatches Transaction Type: In-Store Payments, Online Transactions, Peer-to-Peer Transfers, Bill Payments |
| Companies Covered | PayPal, Stripe, Apple, Visa, Block, Google, Adyen, Mastercard, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NFC Payments Market Emerging Trajectories
Tokenization architecture is fragmenting across cloud-based credential vaults and device-bound secure elements, forcing payment processors to maintain dual infrastructure stacks while interchange economics favor consolidation.
Host card emulation combined with software security modules is decentralizing the authentication stack away from hardware-dependent secure elements. Mid-market merchants in the United States are adopting these solutions to avoid premium terminal leases. This shift is compressing margins for traditional POS manufacturers while expanding addressable market for pure-play software providers.
The EU AI Act's risk-based classification system is imposing algorithmic audit requirements on biometric authentication workflows used in high-value contactless transactions. Payment processors serving European issuers must now document training data provenance and discrimination testing for facial recognition models. Wallet providers are responding by segregating EU user data processing from global infrastructure to contain compliance scope.
Transit agencies are unbundling fare collection from proprietary closed-loop cards toward open payment acceptance that rides on standard NFC protocols. This procurement pattern shift is displacing specialized transit equipment vendors with conventional POS terminal suppliers in cities from Chicago to London. The behavioral consequence is collapsing the distinction between transit and retail payment credentials among urban commuters.
NFC Payments Market Segmentation
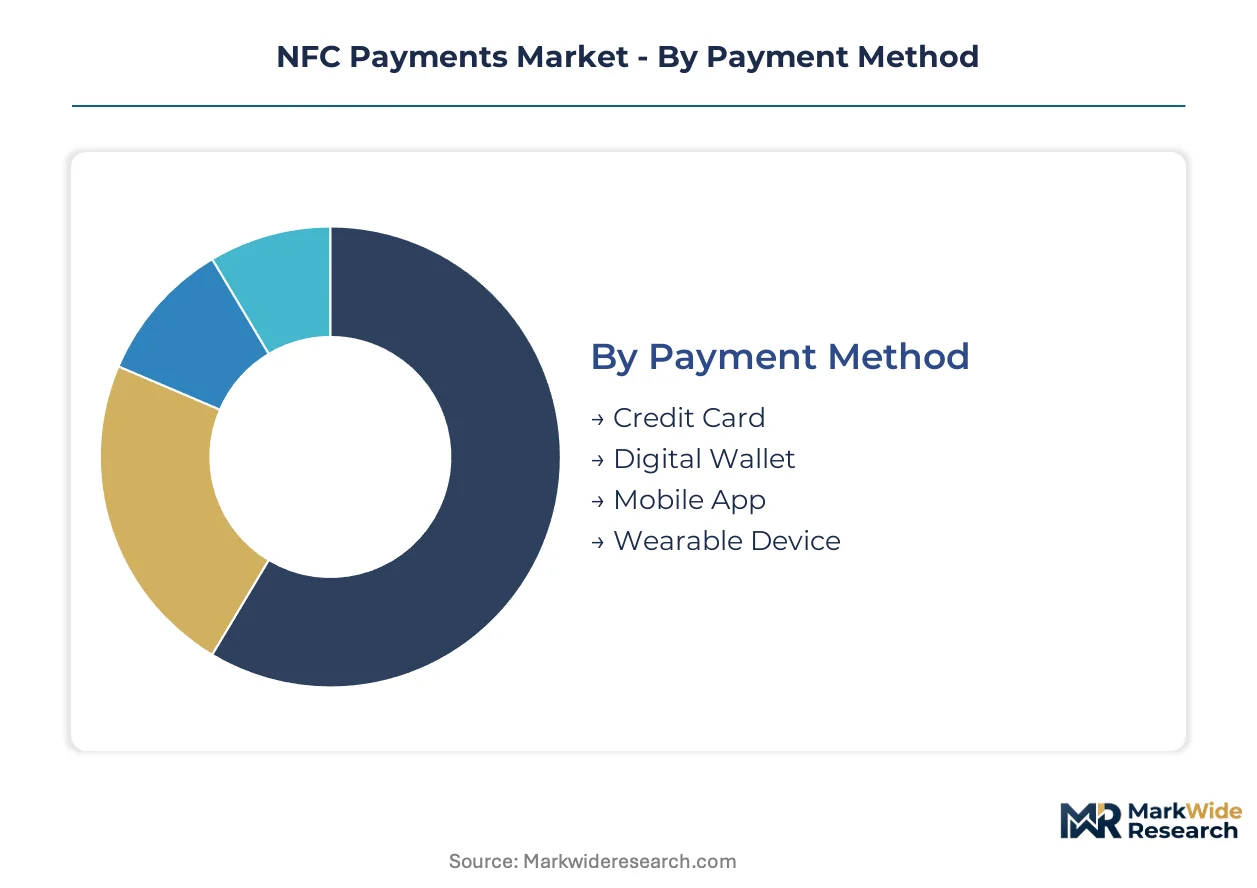
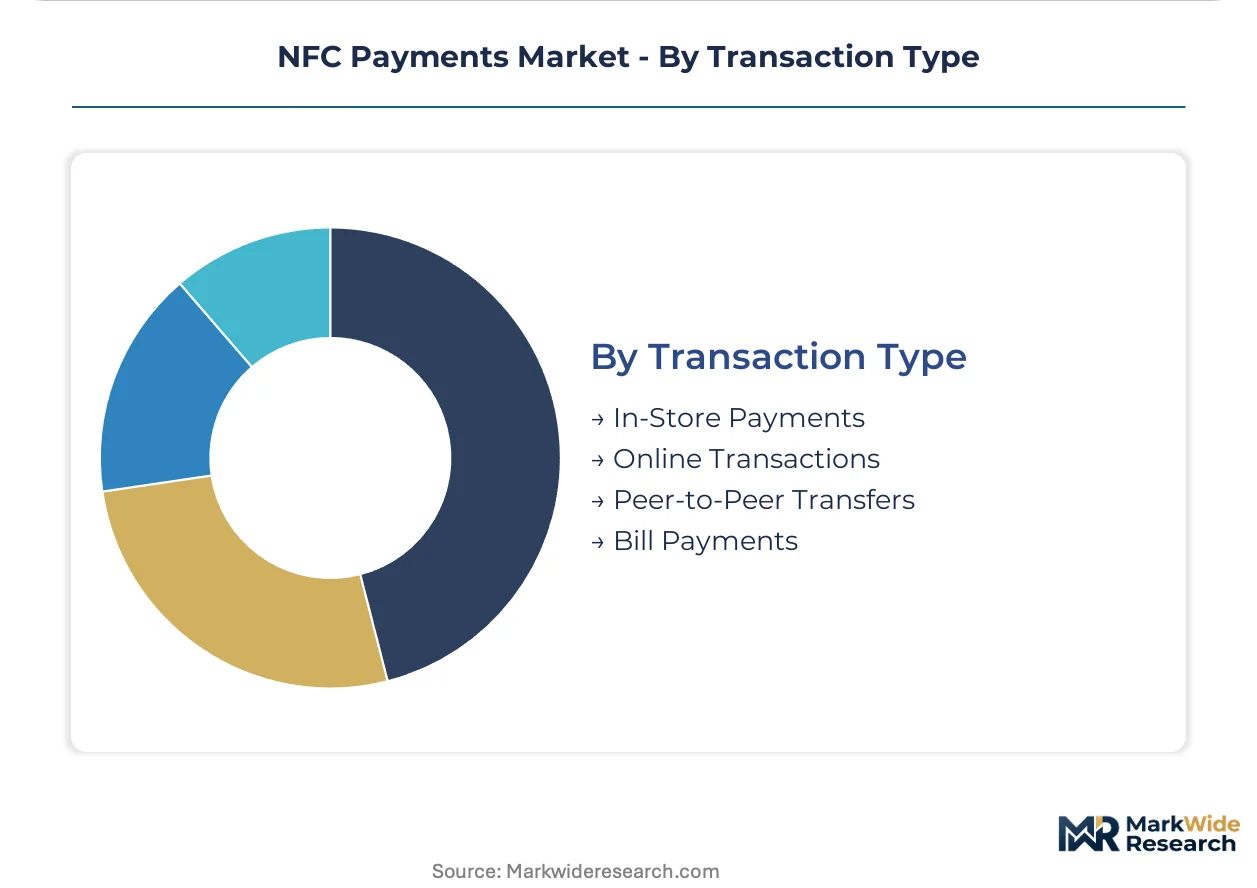
NFC payment architectures fragment across credential storage methods, transaction environments, and hardware form factors. Each segmentation axis reveals divergent margin structures and certification requirements that reshape vendor resource allocation.
Payment Method:
Volume concentrates in card-present rails, while premium economics accrue to software-native provisioning.
- Digital Wallet:Tokenized credentials reside in secure element enclaves or cloud-hosted vaults, enabling smartphone-based tap-to-pay without physical card presentment. Demand clusters in United States grocery chains and transit systems where EMVCo certification speeds checkout throughput. Tokenization infrastructure investments by major platforms are displacing merchant-issued closed-loop programs.
- Credit Card:Plastic credentials with embedded NFC antennas operate at 13.56 MHz across contactless-enabled POS terminals, maintaining backward compatibility with magnetic stripe infrastructure. European issuers under PSD2 strong customer authentication mandates are upgrading contactless limits and biometric verification workflows. Interchange economics favor this segment for high-value transactions despite hardware dependency.
- Mobile App:Host card emulation enables NFC transactions through software modules without dedicated secure elements, reducing terminal certification burdens for mid-market merchants.
- Wearable Device:Smartwatch and fitness band form factors provision payment credentials through paired smartphone bridges or standalone connectivity.
Mature deployment sits with Credit Card. Newer deployment is concentrated in Digital Wallet.
End User:
Merchant acceptance infrastructure determines transaction economics, while consumer-facing interfaces drive credential proliferation.
- Merchants:countertop and mobile POS terminal operators manage EMVCo certification, PCI DSS compliance, and reconciliation workflows across mixed hardware estates. United States acquirers are compressing terminal refresh cycles as transit authority open-loop mandates force contactless upgrades. Hardware concentration among Asian component suppliers creates allocation vulnerability.
- Retail Consumers:Individual credential holders execute tap-to-pay transactions through smartphones, cards, or wearables, generating interchange revenue for issuers and network fees for schemes. European GDPR and EU AI Act constraints on biometric authentication are raising compliance costs for wallet providers serving this segment.
- Businesses:Corporate card programs and fleet payment systems integrate NFC for expense management and fuel purchasing.
- Online Shoppers:E-commerce credential provisioning for in-app NFC pickup or curbside fulfillment bridges digital and physical payment rails.
Volume leadership belongs to Retail Consumers. Steepest expansion trajectory is occurring in Merchants.
Device Type:
Smartphone penetration outpaces terminal deployment, creating a hardware mismatch that benefits OEM-wallet partnerships.
- Smartphones:Handset-based secure elements and host card emulation protocols enable credential storage and transaction initiation across iOS and Android ecosystems. United States consumer activation rates for tap-to-pay are climbing as merchant acceptance density reaches critical mass in urban corridors.
- POS Terminals:Merchant-facing readers with contactless kernels require 12-18 month EMVCo certification timelines, freezing small vendor participation and concentrating supply among established manufacturers.
- Smartwatches:Wrist-worn form factors with NFC antennas extend payment utility for transit and quick-service restaurant use cases.
- Tablets:Larger-screen mobile devices serve line-busting and tableside payment acceptance in hospitality environments.
Installed base dominance rests with Smartphones. Fastest credential activation is occurring in Smartwatches.
Transaction Type:
Physical proximity requirements segment use cases by authentication friction and settlement timing.
- In-Store Payments:Card-present NFC transactions at physical merchant locations require sub-10 centimeter proximity and complete within milliseconds, satisfying EMVCo security standards for counterfeit resistance. United States grocery chains and transit authorities are mandating contactless acceptance, forcing terminal refresh cycles.
- Peer-to-Peer Transfers:Device-to-device NFC pairing enables immediate fund exchange without network routing, popular for splitting expenses and informal settlement.
- Online Transactions:E-commerce platforms provision NFC credentials for in-store pickup or delivery verification, bridging digital origination with physical fulfillment.
- Bill Payments:Recurring utility and service payments leverage stored NFC credentials for automated settlement.
Transaction volume concentrates in In-Store Payments. Gaining share fastest is Peer-to-Peer Transfers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco Bay Area technology corridors anchor NFC payment innovation through venture deployment and merchant pilot programs. Transit authorities in Chicago, New York, and Los Angeles are accelerating contactless fare collection modernization. Central bank digital currency experimentation in Washington and Frankfurt is reshaping backend settlement infrastructure.
United States
Merchant POS terminal refresh cycles compress as grocery chains and transit authorities mandate contactless acceptance. NHTSA influences connected vehicle commerce standards for fuel and tolling applications. Chicago Transit Authority and New York MTA deployments create captive volume for terminal manufacturers upgrading legacy fare collection systems.
Germany
PSD2 strong customer authentication mandates drive tokenization infrastructure investment across European payment rails. EU AI Act risk-based classifications impose algorithmic audit requirements on biometric authentication workflows. Frankfurt's financial services cluster hosts processor data centers segregating EU user processing from global infrastructure.
United Kingdom
Transport for London's open-loop payment acceptance established early precedent for transit-retail credential convergence. Financial Conduct Authority supervision shapes issuer compliance with contactless transaction limits. London fintech corridors concentrate wallet provider engineering resources for European market entry.
China
MIIT standards for near-field communication protocols govern domestic device certification and terminal interoperability. Dual carbon goals accelerate transit authority electrification and contactless fare modernization. Shenzhen manufacturing clusters supply POS terminal components to global acquirers facing semiconductor allocation volatility.
South Korea
Seoul Capital Area transit systems pioneered smartphone-based tap-to-pay for multimodal transportation. MFDS-equivalent financial regulators supervise payment processor licensing for biometric authentication services. Busan-Ulsan manufacturing corridors produce NFC antenna components for wearable device integration.
NFC Payments Market Vendor Landscape
Premium-margin players sit above commodity-margin players across secure element architecture and tokenization infrastructure tiers. The vendor base stratifies between hardware-integrated ecosystem owners and software-native payment processors. Three archetypes dominate: secure element architects, merchant acquirer platforms, and transit-specialized terminal suppliers. Consolidation pressure intensifies through strategic partnerships between OEMs and payment networks, while geographic expansion into transit authority procurement channels accelerates.
Within the secure element tier, Apple and Samsung Electronics exemplify hardware-integrated ecosystem control. Adyen occupies a position among merchant-facing platform specialists unifying online and offline acceptance rails. These three anchors represent divergent margin structures: device-bound security commands premium economics, while processor scale depends on interchange volume density and terminal deployment velocity.
| Leading Market Players |
|---|
| PayPal |
| Stripe |
| Apple |
| Visa |
| Block |
| Adyen |
| Mastercard |
| Samsung Electronics |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up terminal manufacturers anchor supply discipline through leveraged balance sheets that resist price wars during semiconductor allocation crunches, while their consolidated purchasing power extracts volume concessions from Asian component suppliers that independent acquirers cannot match.
Pricing Analysis
Value-based pricing anchored to transaction throughput per terminal dominates merchant acquirer contracts, with EMVCo certification tier and secure element integration grade serving as the primary differentiation drivers. Cost compression in host card emulation solutions is intensifying because mid-market merchants reject premium hardware leases in favor of software-native provisioning. Small grocery chains and independent transit authorities exhibit the highest price sensitivity, while tier-one retailers with mixed terminal estates prioritize uptime guarantees over per-unit costs.
Supply Chain Analysis
Secure element fabrication rests on Taiwanese semiconductor foundries and South Korean memory suppliers, with NFC antenna components drawing from Shenzhen manufacturing clusters and Busan-Ulsan electronics corridors. Semiconductor allocation volatility and extended lead times for EMVCo-certified contactless kernels constitute the dominant supply chain risk. Distribution runs through merchant acquirer procurement channels that bundle hardware deployment with interchange revenue-sharing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMVCo certification friction and terminal hardware concentration are forcing consolidation among sub-scale wallet providers and regional acquirers unable to sustain 12-18 month approval timelines.
For Market Incumbents: Cement secure element architecture leadership through backward integration into semiconductor packaging facilities in Taiwan and South Korea, while locking transit authority procurement channels through multi-year open-loop fare collection mandates that freeze out unproven terminal entrants. For New Entrants and Emerging Players: Direct-to-merchant software provisioning offers the most penetrable route around hardware certification barriers, targeting mid-market U.S. grocery chains with host card emulation solutions that bypass EMVCo kernel requirements through cloud-based tokenization partnerships. For Investors and Strategic Acquirers: Distressed-cycle entries favor biometric authentication specialists with EU data residency infrastructure in Frankfurt and Amsterdam, as GDPR and EU AI Act compliance costs force asset sales from undercapitalized wallet providers. Watch central bank digital currency pilot announcements from the Federal Reserve and European Central Bank as inflection indicators for backend infrastructure consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Backward Integration | Captive semiconductor packaging in Taiwan insulates Apple and Samsung from allocation volatility. |
| Transit Authority Channel Lock-In | Chicago CTA and New York MTA deployments create decade-long terminal refresh cycles for incumbents. |
| EU Data Residency Segregation | Frankfurt processor data centers contain GDPR and EU AI Act compliance scope for biometric workflows. |
| Host Card Emulation Platform Launch | Software-native provisioning bypasses 12-18 month EMVCo certification for mid-market merchant acquisition. |
| Wearable Device OEM Partnership | Smartwatch activation rates lag smartphones by 40 points, creating white space for credential provisioning deals. |
Methodological Framework
SEC 10-K filings, EMVCo certification registries, and transit authority procurement databases formed the secondary backbone, supplemented by primary interviews with merchant acquirer platform engineers, POS terminal procurement leads at U.S. grocery chains, transit authority fare collection managers, and biometric authentication compliance officers at European wallet providers. Bottom-up terminal deployment tallies and top-down interchange volume estimates were triangulated against smartphone penetration curves and wearable activation data.
Bottom-up modeling of merchant POS terminal refresh cycles and transit authority modernization budgets anchored volume projections across the analysis window, with segmentation across payment method, device type, and transaction environment dimensions. CAGRs were derived from credential provisioning growth rates and hardware deployment velocity, incorporating Federal Reserve CBDC pilot disclosures and NHTSA connected vehicle commerce standards as scenario inputs.
Inputs from EMVCo certification timelines and Asian semiconductor foundry utilization reports were available through the study window; gaps in small merchant terminal deployment intentions introduce uncertainty bands around mid-market adoption curves. A small set of triggers—central bank digital currency settlement architecture shifts, EU AI Act enforcement actions on biometric models, and NHTSA fuel payment protocol finalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
UK Virtual Cards Market
Payments
China Real Time Payments Market
Payments
Saudi Arabia Payments Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Indonesia Mobile Payments Market
Payments
Cyprus POS Terminals Market
Payments
Hong Kong Credit Cards Market
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
China Prepaid Cards Market
Payments
Middle East and Africa Payments Market
Payments
North America Accounts Payable Automation Market
Payments
Croatia POS Terminals Market
Payments
Canada Gift Card and Incentive Card Market
Payments
US Buy Now Pay Later Services Market
Payments
Europe Prepaid Card Market
Payments
Portugal POS Terminals Market