
 Slovakia POS Terminal Market | 2026-2036
Slovakia POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Slovakia POS Terminal Market Analytics
Software-defined subscription layers for terminal management is expanding the addressable revenue per unit beyond hardware margins. Ingenico leverages its European service infrastructure to sustain long-term maintenance contracts across Slovak retail networks. Verifone competes through integrated payment-platform bundles that anchor merchant loyalty. PAX Technology specializes in cost-optimized Android terminals that dominate price-sensitive hospitality deployments.
A POS terminal constitutes an electronic payment device combining secure card-reading hardware, encryption modules, and network connectivity to process card-present transactions at merchant locations. These systems employ PCI-DSS certified architectures with tamper-resistant security elements to protect cardholder data during authorization and settlement. Fixed POS terminals retain the largest installed base across Slovak retail, though mobile POS is recording the fastest hardware refresh rate as table-service restaurants adopt smartphone-connected readers. Cloud-based deployment models are capturing margin pools previously held by on-premise server installations, with SaaS pricing restructuring vendor cash flows toward recurring revenue streams.
The National Bank of Slovakia supervises payment system stability and enforces PSD2 compliance deadlines that force terminal upgrades for strong customer authentication. GDPR requirements from EU regulators mandate audit trails and data-localization features that shape product specifications for any vendor accessing the Slovak market. Stakeholders must monitor whether the EU's Digital Operational Resilience Act extends certification burdens to POS terminal firmware as critical payment infrastructure.
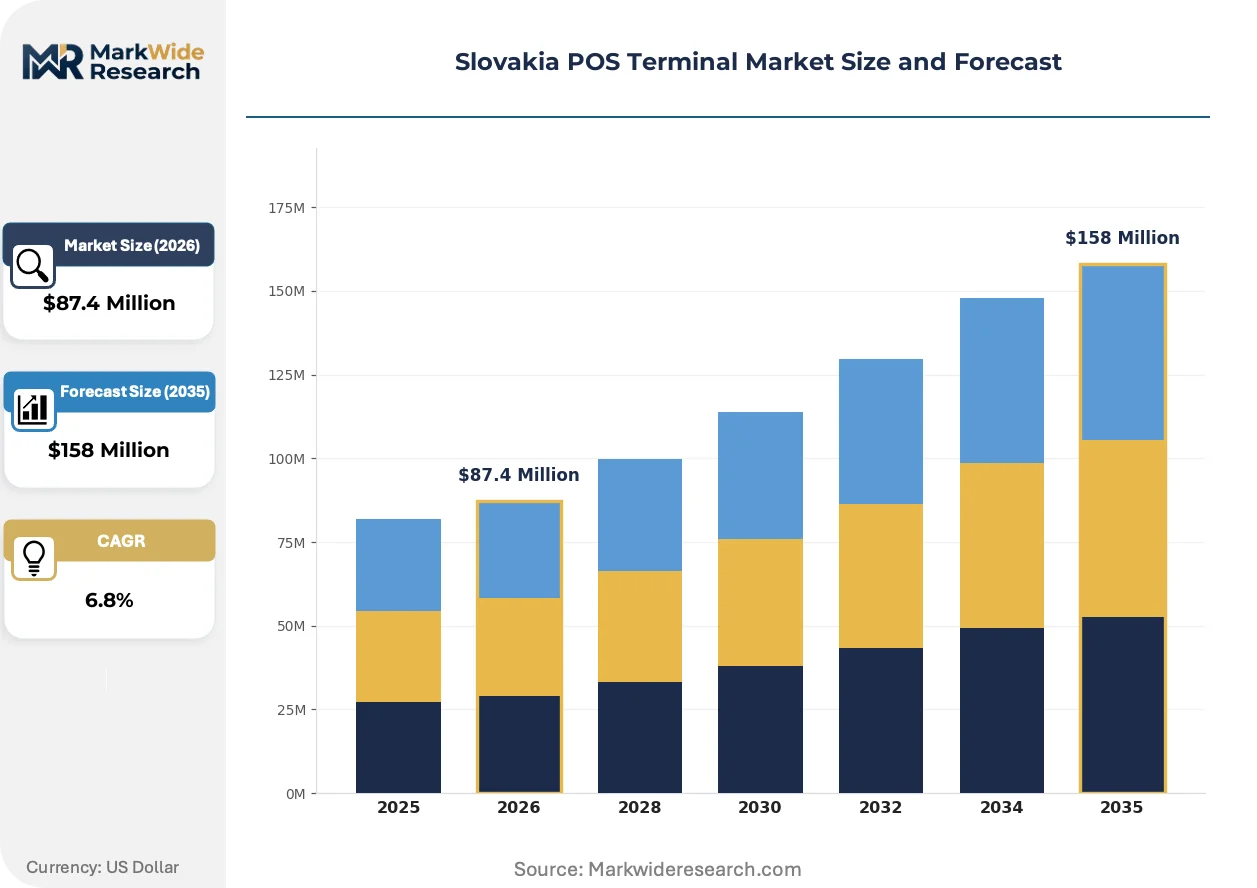
Market Dynamics
Slovak retail chains are executing hardware refresh cycles driven by Payment Services Directive 2 mandates from the EU, forcing terminal upgrades for strong customer authentication while cloud migration restructures vendor economics toward recurring revenue.
Growth Catalysts
- PSD2 Compliance Deadlines:The EU's strong customer authentication requirements force terminal replacements across Slovak merchant networks, accelerating procurement timelines for contactless-capable hardware.
- Cloud-Connected Terminal Architecture:SaaS deployment models capture margin pools previously held by on-premise server installations, restructuring cash flows toward subscription revenue streams.
- Tourism Footfall Concentration:Bratislava and Košice generate concentrated procurement volumes where franchise density and hospitality transaction volumes sustain hardware refresh demand.
Market Restraints
- Semiconductor Supply Concentration:Tamper-resistant security element production concentrates in Asian foundries, exposing Slovak terminal assemblers to input volatility and extended lead times.
- GDPR Data Localization Burden:EU audit trail and data-localization requirements inflate firmware development costs and extend certification timelines for vendors accessing the Slovak market.
- Mobile Payment Substitution:Smartphone-based QR code and NFC wallet transactions reduce merchant dependency on dedicated terminal hardware in low-ticket retail segments.
Strategic Opportunities
- Eastern Slovakia Penetration Gap:Prešov and Žilina regions exhibit lower terminal density per merchant than Bratislava, creating whitespace for cost-optimized Android deployments.
- Integrated Payment-Platform Bundles:Vendors anchoring merchant loyalty through software-defined subscription layers expand addressable revenue per unit beyond hardware margins.
- Digital Operational Resilience Act Tailwind:Potential EU extension of certification burdens to POS firmware as critical infrastructure creates compliance service revenue streams.
Industry Challenges
- PCI-DSS Certification Timeline Compression:Hardware vendors face extended validation cycles for tamper-resistant security architectures, delaying product launches.
- Legacy System Integration Friction:Slovak retail chains replacing decades-old checkout infrastructure encounter middleware compatibility gaps with modern cloud APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slovakia POS Terminal Market |
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mobile POS, Fixed POS, Self-Service Kiosks, Contactless Readers End User: Retail Stores, Restaurants, Hospitality, Health & Wellness Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Saas Models Feature: Inventory Management, Sales Tracking, CRM Integration, Loyalty Programs |
| Companies Covered | Ingenico, Verifone, PAX Technology, SumUp, Fiserv, Global Payments, myPOS World, eKasa, Payten, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slovakia POS Terminal Market Evolving Landscape
Terminal architecture is converging around Android-based open platforms while regulatory mandates reshape security specifications and merchant procurement patterns favor integrated service bundles over discrete hardware transactions.
Contactless NFC modules are absorbing transaction volume from magnetic stripe and chip-insert protocols across Slovak hospitality and retail deployments. Table-service restaurants in Bratislava's city center are adopting smartphone-connected mobile POS readers at the fastest hardware refresh rate. This shift is absorbing margin from fixed countertop terminals while enabling tableside payment workflows.
GDPR requirements from EU regulators mandate audit trails and data-localization features that shape product specifications for terminal firmware. The National Bank of Slovakia enforces PSD2 compliance deadlines that force hardware upgrades for strong customer authentication. Slovak merchants in high-ticket retail segments face the steepest compliance-driven replacement cycles.
Merchant procurement patterns are gravitating toward integrated payment-platform bundles that combine hardware, processing, and software management. Independent software vendors and payment processors are disintermediating traditional distributor channels in Bratislava. Hospitality operators in Košice exhibit the strongest preference for single-vendor service contracts over hardware-only purchases.
Slovakia POS Terminal Market Segmentation
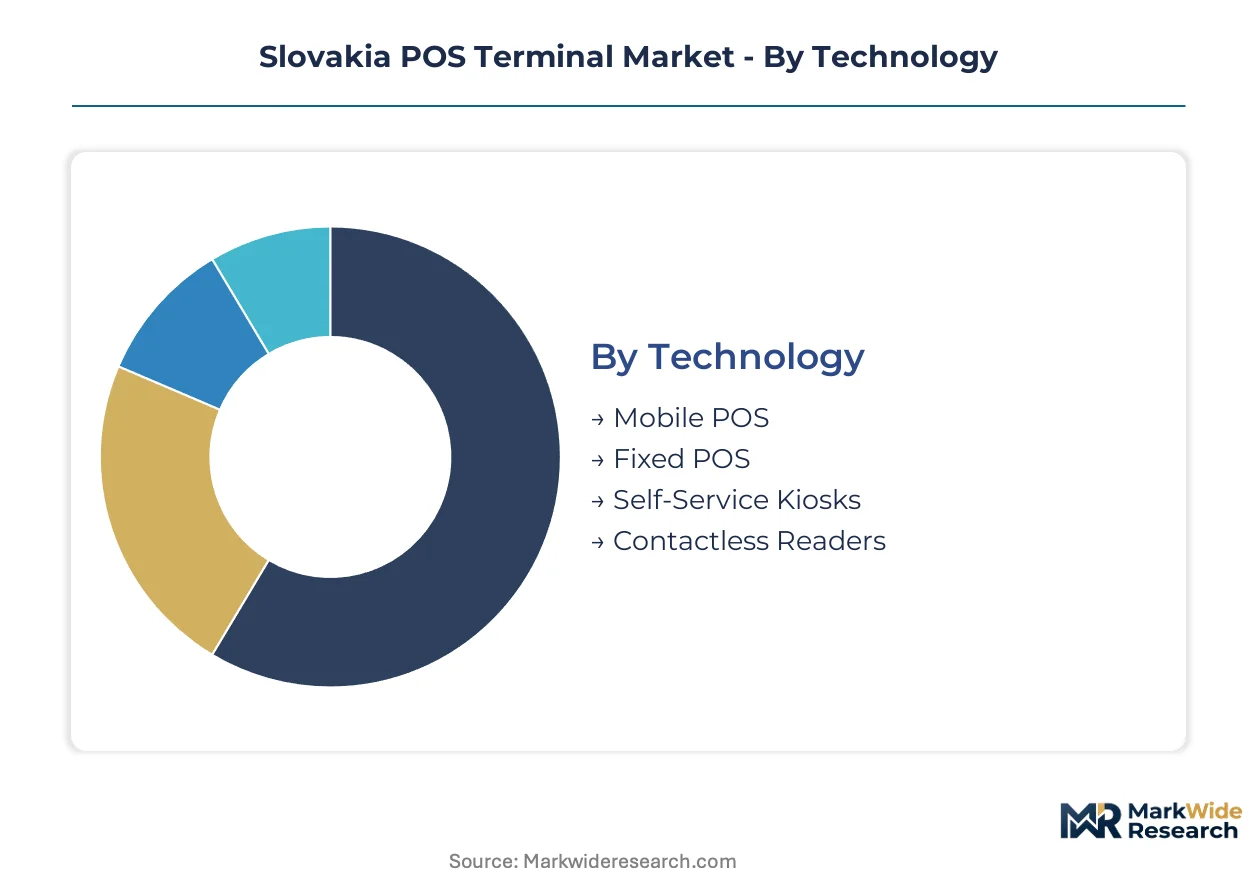
POS terminal procurement patterns in Slovakia diverge sharply across merchant scale and regulatory exposure. Understanding these fault lines reveals where hardware margins concentrate and where SaaS conversions unlock recurring revenue streams.
Technology:
Standardized PCI-DSS architectures dominate high-volume deployments, while customizable Android platforms capture price-sensitive hospitality merchants seeking app extensibility.
- Mobile POS:Smartphone-connected readers with Bluetooth pairing enable tableside payment workflows. Bratislava's restaurant district drives concentrated refresh demand as table-service operators abandon fixed countertop units for portable flexibility.
- Fixed POS:Countertop terminals with integrated receipt printers and customer-facing displays retain the largest installed base across Slovak retail chains. Legacy replacement cycles concentrate in Košice's franchise networks where PSD2 compliance deadlines force authentication-capable upgrades.
- Self-Service Kiosks:Unattended ordering and payment terminals expanding in quick-service food locations.
- Contactless Readers:Dedicated NFC modules absorbing volume from chip-insert protocols in high-throughput retail.
Leading the category by volume: Fixed POS. Expanding most quickly: Mobile POS.
End User:
Cost tier separation shapes procurement—enterprise retail chains negotiate integrated platform bundles while independent merchants prioritize hardware acquisition cost.
- Retail Stores:Multi-lane checkout environments requiring centralized transaction reconciliation and inventory synchronization. Bratislava's shopping centers sustain concentrated procurement volumes where franchise density accelerates cloud migration timelines.
- Restaurants:Table-service and quick-service operators demanding split-check functionality and tip-adjustment workflows. Košice's hospitality corridor exhibits strongest preference for single-vendor service contracts over discrete hardware purchases.
- Hospitality:Hotels and accommodation providers integrating payment terminals with property management systems.
- Health & Wellness:Clinics and pharmacies requiring HIPAA-aligned audit trails and appointment-linked billing.
Volume concentration: Retail Stores. Steepest expansion trajectory: Restaurants.
Deployment:
Application maturity determines cloud readiness—transaction-heavy retail migrates fastest while compliance-sensitive segments retain on-premise control.
- On-Premise:Local server installations retaining data sovereignty for merchants with legacy ERP dependencies. GDPR audit trail requirements inflate maintenance burdens as firmware patches require manual distribution.
- Cloud-Based:Centralized terminal management with real-time transaction monitoring and remote software updates. Slovak retail chains in Bratislava prioritize these deployments to restructure vendor economics toward subscription revenue.
- Hybrid Solutions:Mixed architectures preserving sensitive data locally while pushing analytics to cloud infrastructure.
- SaaS Models:Software-defined subscription layers bundling hardware, processing, and management tools.
Current volume leader: On-Premise. Gaining share fastest: Cloud-Based.
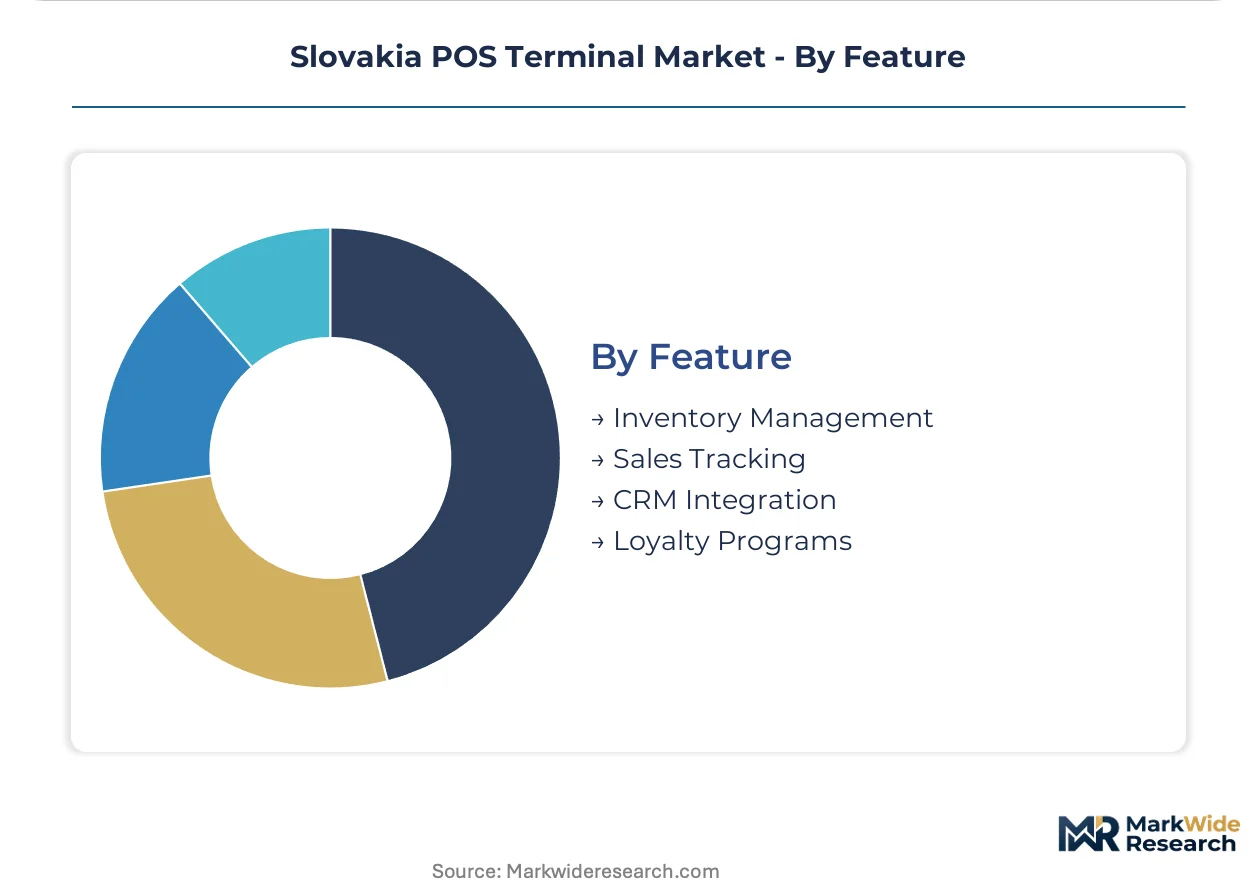
Feature:
Customer type segmentation separates enterprise merchants seeking operational integration from small operators prioritizing payment acceptance alone.
- Inventory Management:Real-time stock synchronization across multi-location retail networks. Large Slovak chains deploy these capabilities to reduce shrinkage and automate reorder points.
- Sales Tracking:Granular transaction analytics enabling hourly performance monitoring and staff productivity metrics. Franchise operators in Košice leverage these tools for centralized oversight of dispersed locations.
- CRM Integration:Customer profile linking to purchase history for personalized marketing.
- Loyalty Programs:Points accumulation and redemption workflows embedded at payment touchpoints.
Widest adoption: Sales Tracking. Fastest feature attachment: Inventory Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Slovakia consumes POS terminals faster than domestic production supplies them. Hardware assembly concentrates in Bratislava and Košice industrial zones, while firmware and security module sourcing reaches into Asian foundries. This import dependency shapes procurement lead times and vendor selection criteria across merchant networks.
Bratislava Region
Franchise density and tourism footfall generate the steepest terminal refresh demand nationwide. The National Bank of Slovakia enforces PSD2 compliance deadlines that accelerate authentication-capable hardware procurement. Shopping centers and hospitality clusters in the capital sustain concentrated cloud migration timelines among retail chains.
Košice Region
Eastern Slovakia's commercial corridor exhibits strongest preference for single-vendor service contracts over discrete hardware purchases. GDPR audit trail requirements inflate firmware development costs for vendors accessing this market. Hospitality operators drive mobile POS adoption as table-service restaurants abandon fixed countertop units.
Prešov Region
Lower terminal density per merchant creates whitespace for cost-optimized Android deployments. The EU's Digital Operational Resilience Act threatens to extend certification burdens to POS firmware as critical infrastructure. Regional distributors target independent merchants with subscription-based terminal management bundles.
Žilina Region
Industrial logistics and manufacturing supply chains sustain specialized payment acceptance needs. PCI-DSS certification timelines compress product launch windows for hardware vendors. Automotive sector procurement concentrates in this northwestern cluster with enterprise-grade integration requirements.
Banská Bystrica Region
Mid-sized retail networks and health services drive steady replacement cycles. Central location advantages support distribution logistics into surrounding territories. Local merchants prioritize hardware acquisition cost over integrated platform bundles compared to Bratislava-based counterparts.
Slovakia POS Terminal Market Competitive Landscape
Top-tier vendors anchor enterprise retail chains, while regional specialists and fintech entrants capture price-sensitive hospitality segments. The vendor base stratifies across three tiers: multinational payment hardware manufacturers, European service infrastructure operators, and agile fintech challengers with software-first economics. Two strategic archetypes dominate—those bundling integrated payment platforms to anchor merchant loyalty, and those competing through cost-optimized Android terminals with app extensibility. Competitive moves concentrate on SaaS pricing restructuring and cloud migration partnerships with retail networks.
Among the multinational hardware tier, Ingenico and Verifone exemplify divergent positioning strategies—one leveraging European service infrastructure for long-term maintenance contracts, the other competing through integrated payment-platform bundles. PAX Technology occupies a distinct position as a cost-optimized Android specialist targeting price-sensitive hospitality deployments. These three anchors represent the strategic fault lines shaping procurement patterns across Slovak merchant segments.
| Leading Market Players |
|---|
| Ingenico |
| Verifone |
| PAX Technology |
| SumUp |
| Fiserv |
| Global Payments |
| myPOS World |
| eKasa |
| Payten |
| Others |
Value Network & Pricing Analysis
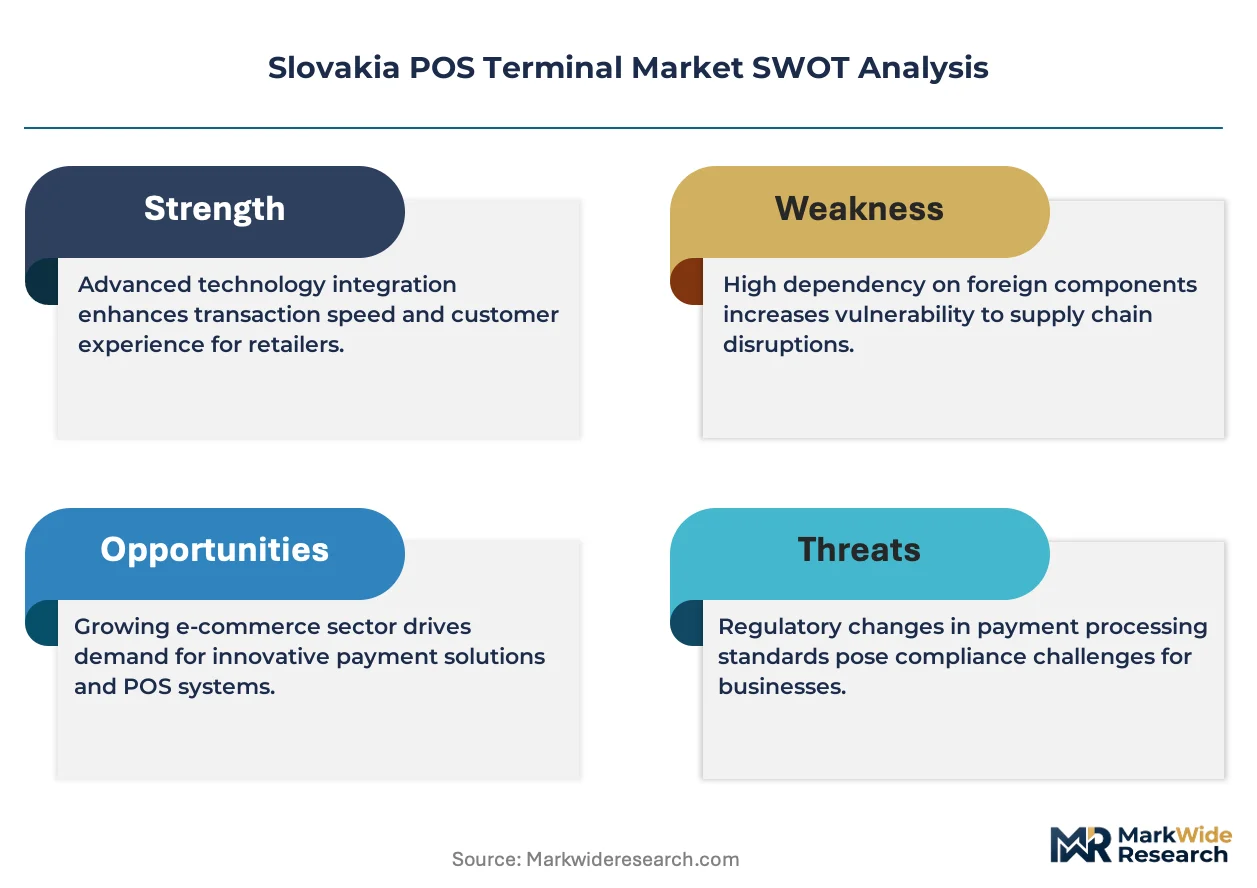
Cloud-connected terminal architecture simultaneously compresses hardware margins and concentrates procurement leverage among retail chains capable of negotiating SaaS-tiered volume discounts. This dual shift rewards vendors with European service infrastructure while squeezing pure hardware assemblers dependent on Asian security module sourcing.
Pricing Analysis
Cost-down pressure on entry-tier terminals accelerates because PAX Technology and Android-based challengers are commoditizing basic payment acceptance hardware. Three-tier pricing structure across premium, standard, and economy levels separates Ingenico's maintenance-bundled enterprise contracts from Verifone's integrated platform subscriptions and from unbranded white-label imports. Price differentiation hinges on PCI-DSS certification grade and after-sales service bundling. Hospitality operators in Košice exhibit highest price sensitivity, while Bratislava's retail chains prioritize authentication capability over unit cost.
Supply Chain Analysis
PCI-DSS certification gating forces Slovak terminal assemblers to source tamper-resistant security elements from Taiwan, South Korea, and China, creating single-source vulnerability for cryptographic chip supply. Firmware development draws from Indian engineering centers and German compliance consultancies, with final assembly concentrating in Bratislava and Košice industrial zones. Semiconductor supply concentration in Asian foundries exposes vendors to extended lead time volatility. Distribution runs through national distributors disintermediated by direct processor relationships in the capital region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PSD2 compliance deadlines and GDPR certification burdens are forcing consolidation among firmware-dependent vendors unable to sustain European regulatory investment. Weaker assemblers without cloud service capabilities face exit pressure as retail chains consolidate procurement around integrated platform providers.
For Market Incumbents: Cement defensible positioning by deepening backward integration into security module sourcing and acquiring Slovak SaaS terminal management specialists before processor partnerships lock out distributor channels. Ingenico's European service infrastructure model provides template for anchoring long-term maintenance contracts against fintech challengers with software-first economics.
For New Entrants and Emerging Players: Begin with cost-optimized Android deployments targeting Prešov and Žilina regions where terminal density per merchant remains below Bratislava benchmarks. Independent hospitality operators in eastern Slovakia present most penetrable segment given their preference for single-vendor service contracts over hardware-only purchases. Partner with regional distributors offering subscription-based terminal management bundles to bypass entrenched capital relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to payment processors seeking European hardware-service integration capabilities. Long-term viability favors vendors with PCI-DSS certification infrastructure and recurring SaaS revenue exceeding hardware replacement cycles. Monitor National Bank of Slovakia enforcement patterns for PSD2 deadline extensions as inflection signal for hardware refresh timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Migration Partnership | Restructures vendor cash flows toward subscription revenue streams with Bratislava retail chains. |
| Security Module Backward Integration | Reduces single-source vulnerability to Asian foundry concentration for cryptographic chip supply. |
| SaaS Terminal Management Acquisition | Captures margin pools previously held by on-premise server installations in mid-market segments. |
| Regional Distributor Partnership | Enables whitespace penetration in Prešov and Žilina where processor direct relationships remain underdeveloped. |
| GDPR Compliance Service Launch | Creates recurring revenue from audit trail and data-localization firmware development mandates. |
Research Methodology
Multi-period observation of terminal refresh cycles, merchant procurement patterns, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with payment hardware procurement managers at Slovak retail chains, firmware engineering directors at terminal manufacturers, National Bank of Slovakia supervisory staff, hospitality operations controllers in Bratislava and Košice, and regional distribution channel partners. Secondary validation drew from EU PSD2 implementation reports, PCI-DSS certification databases, GDPR enforcement notices, customs import records for payment hardware, and National Bank of Slovakia payment system stability publications. Bottom-up merchant demand modeling and top-down vendor revenue triangulation converged on segment-level estimates.
The input-output matrix framed demand as function of merchant count by category, terminal replacement age distribution, compliance deadline proximity, and cloud-readiness segmentation across retail, hospitality, and services verticals. Deployment model, merchant scale tier, authentication capability requirement, and regional adoption pattern provided segmentation dimensions. CAGRs were derived from terminal unit deployment trajectories and SaaS pricing penetration curves, with hardware refresh elasticity to regulatory deadlines and tourism footfall indices as industry-specific forecast inputs across the projection horizon.
Regulatory enforcement variance, semiconductor supply disruption, and mobile payment substitution acceleration are the dominant revision risks that could compress hardware demand or accelerate cloud migration timing. A model refresh is warranted upon material change in National Bank of Slovakia PSD2 deadline enforcement or EU Digital Operational Resilience Act certification scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Enterprise Payment Software Market
Payments
South Korea Digital Payments Market
Payments
Asia Pacific Real Time Payment Market
Payments
Malaysia Payments Market
Payments
Cash Management Software Market
Payments
Mobile Point of Sale Devices (Mpos) Market
Payments
United States Real Time Payments Market
Payments
Sweden Mobile Payments Market
Payments
United States Payment Gateways Market
Payments
Remittance Market
Payments
B2C Payment Market
Payments
France POS Terminal Market
Payments
Italy POS Terminals Market
Payments
Africa Virtual Cards Market
Payments
India Real Time Payments Market
Payments
Global Wearable Payment Device Market