
 Global Payment Gateways Market | 2026-2036
Global Payment Gateways Market Size, Share, and Industry Trends Forecast 2026-2036
Global Payment Gateways Market Intelligence
Modular unbundling of payment services is recalibrating how merchants evaluate gateway partnerships. Stripe leverages developer-centric API architectures to anchor its position among high-growth digital-native businesses. Adyen competes through unified commerce platforms that sustain margin efficiency across online and in-store channels. PayPal differentiates via its dual-sided consumer-merchant network, which controls substantial checkout flow volume.
Payment gateways are software-layer infrastructure that encrypt, route, and settle transaction data between merchant systems and acquiring banks, typically processing authorization requests within sub-500 millisecond windows to prevent checkout abandonment. Their primary commercial purpose is reducing payment friction while managing fraud exposure and regulatory compliance for merchants. Cloud-based deployment models are capturing disproportionate growth as retailers prioritize elastic capacity during seasonal demand spikes. E-wallet payment methods are expanding fastest in emerging markets where card penetration remains limited and mobile-first banking dominates consumer behavior.
PCI DSS compliance frameworks, the EU AI Act's algorithmic decision-making transparency requirements, and India's RBI digital payment security guidelines collectively shape product architecture and market access conditions for gateway operators. PSD3 provisions in Europe are forcing open-banking integration standards that alter technical roadmaps for cross-border providers. Stakeholders must monitor how real-time payment system proliferation across national central banks reshapes the competitive boundary between traditional gateways and account-to-account infrastructure.
Market Dynamics
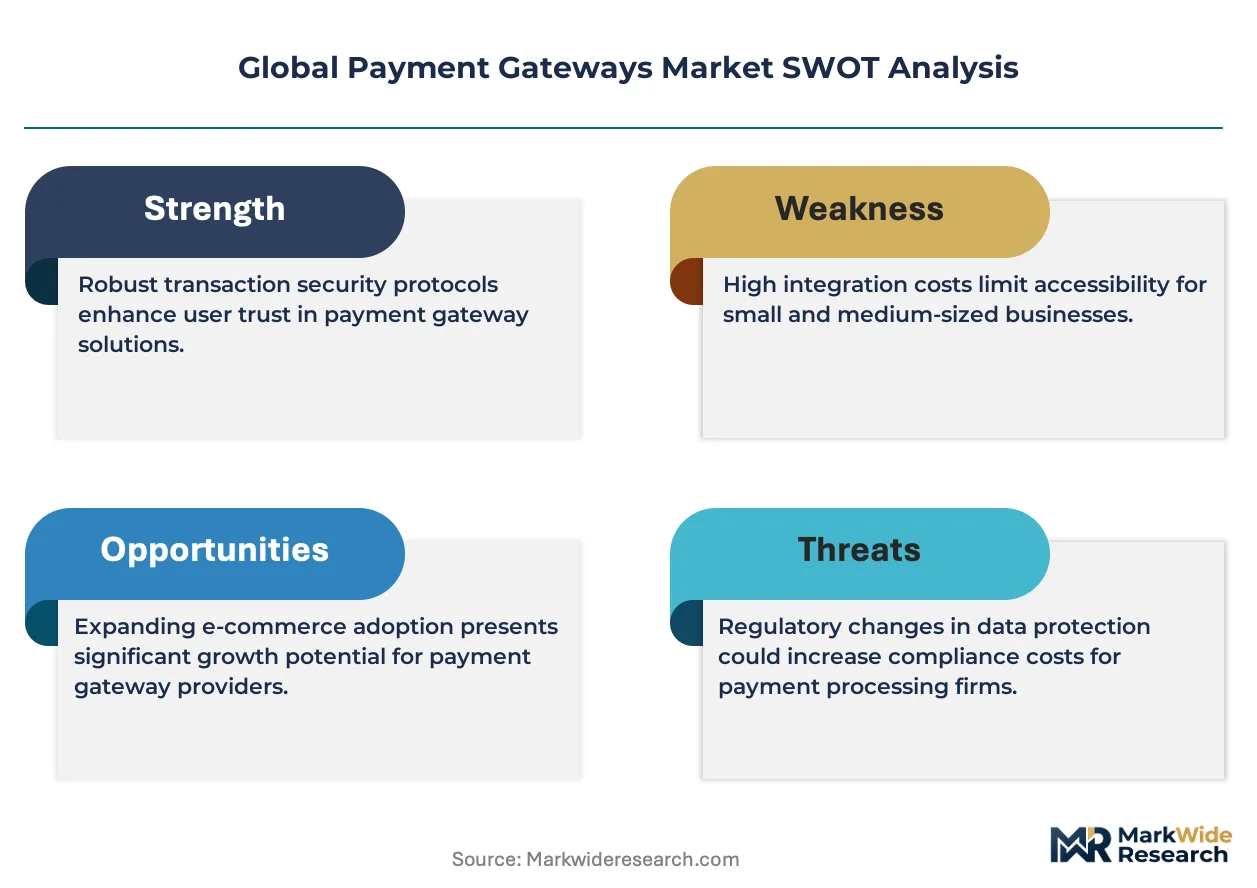
Real-time payment infrastructure proliferation is fragmenting transaction routing economics, forcing gateways to defend margin structures against account-to-account alternatives while absorbing compliance costs from algorithmic transparency mandates.
Growth Catalysts
- India's UPI ecosystem expansion:The RBI's digital payment infrastructure push generates substantial gateway volume through mobile-first banking penetration where card networks remain underdeveloped.
- EU AI Act algorithmic requirements:Mandatory transparency for fraud-scoring decisions creates competitive differentiation for compliant operators serving cross-border merchants.
- Cloud-native deployment elasticity:Retailers demand sub-500 millisecond authorization windows during seasonal spikes, favoring API-first architectures over legacy on-premise stacks.
Market Restraints
- PCI DSS compliance cost escalation:Certification cycles and audit frequency impose disproportionate burdens on mid-tier gateway operators with limited security engineering scale.
- Acquiring bank concentration in North America:Three processor groups control substantial domestic settlement infrastructure, extracting interchange-adjacent fees that compress gateway net revenue.
- Central bank real-time payment substitution:FedNow and equivalent national systems enable direct account-to-account transfers that bypass traditional card-gateway economics entirely.
Strategic Opportunities
- Brazil's PIX open-banking convergence:The central bank's instant payment mandate creates white space for gateway operators integrating PIX rails with merchant acquiring services.
- Embedded finance B2B penetration:Vertical SaaS platforms in logistics and procurement seek white-labeled payment orchestration, displacing standalone gateway relationships.
- Tokenized credential vaulting:Network token services from Visa and Mastercard reduce fraud liability while enabling subscription commerce across recurring billing use cases.
Industry Challenges
- Legacy ERP integration complexity:Enterprise merchants maintain decades-old order management systems requiring custom middleware development for modern API connectivity.
- PSD3 open-banking timeline compression:European providers face accelerated technical roadmaps to meet account-to-account initiation standards while maintaining existing card-acquiring relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Payment Gateways Market |
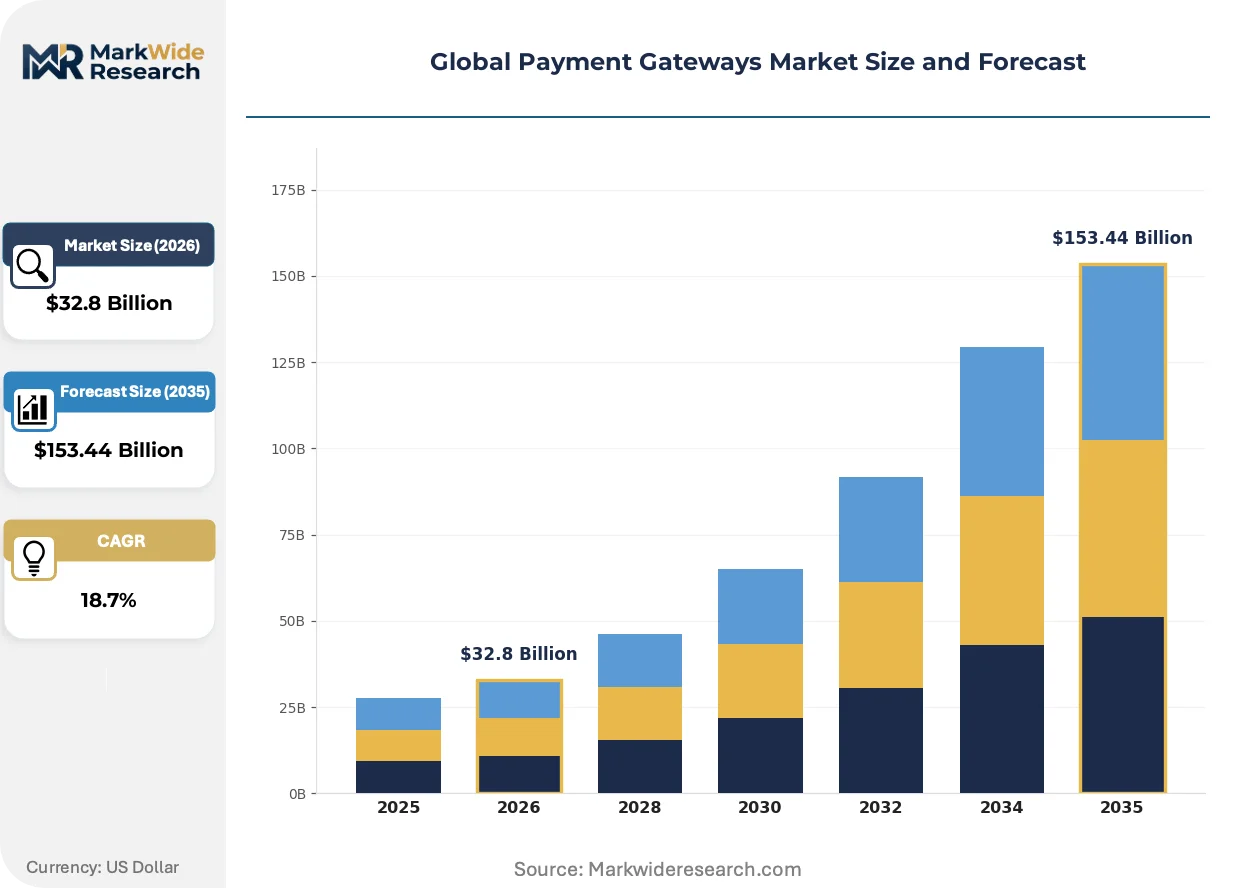
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $153.44 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, E-Wallet, Bank Transfer Deployment Model: On-Premise, Cloud-Based, Hybrid, Self-Hosted End User: E-Commerce, Retail, Hospitality, Healthcare Transaction Type: In-Store, Online, Mobile, Recurring |
| Companies Covered | Stripe, Adyen, PayPal, Worldpay, PayU, Payoneer, Checkout.com, Braintree, Fiserv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Payment Gateways Market Strategic Shifts & Innovations
Gateway architecture is bifurcating between unified commerce platforms serving omnichannel merchants and modular orchestration layers enabling payment-method diversification. This split reflects diverging buyer priorities: operational consolidation versus routing optimization.
Network tokenization is expanding into subscription commerce and recurring billing verticals. SaaS platforms serving membership and utility billing segments adopt vaulting services to reduce PCI scope and improve authorization rates. This capability compression is collapsing the distinction between gateway core functions and value-added security layers.
The EU AI Act's algorithmic decision-making transparency requirements are forcing fraud-scoring engine redesigns. Gateway operators must document model logic for transaction declines and risk holds, adding compliance engineering headcount. European cross-border merchants represent the most affected segment, with providers accelerating explainable AI investments to maintain market access.
Merchant procurement of payment infrastructure is consolidating around developer experience metrics rather than rate tables. Digital-native businesses evaluate integration velocity, documentation quality, and sandbox reliability as primary selection criteria. This behavioral shift is most visible among high-growth e-commerce verticals in India and Southeast Asia, where engineering-led vendor selection displaces traditional procurement processes.
Global Payment Gateways Market Segmentation
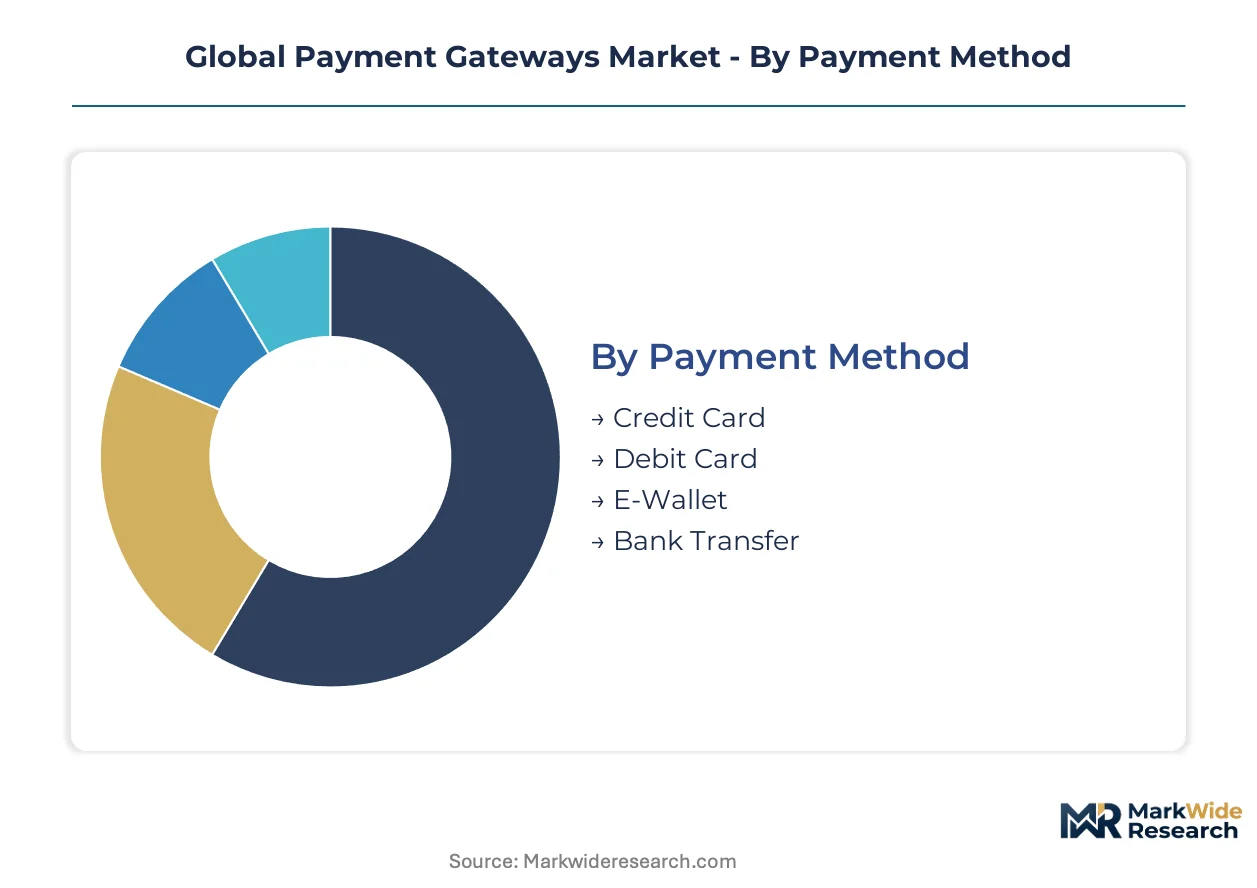
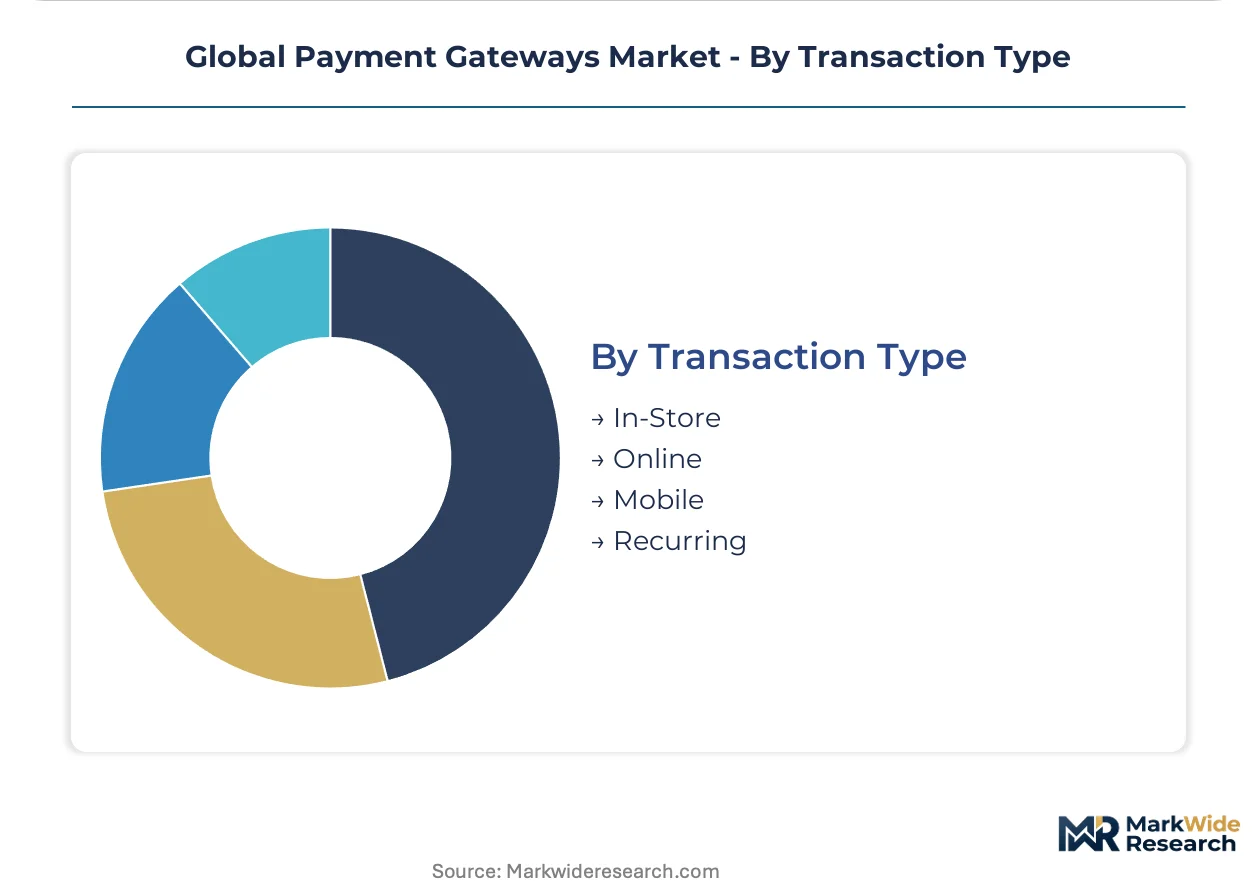
Payment gateway segmentation reveals divergent infrastructure economics across deployment models and transaction types. Merchant procurement patterns cluster around technical requirements rather than traditional industry verticals, reshaping how providers configure service tiers.
Payment Method:
Capital intensity varies sharply across payment rails, with credential vaulting and network tokenization demanding specialized security engineering.
- Credit Card:Dominant transaction volume globally, requiring PCI DSS Level 1 certification and network fee structures that compress gateway margins. Demand concentrates among enterprise e-commerce merchants in India and Brazil where cross-border acquiring relationships reduce decline rates.
- E-Wallet:Mobile-first payment credentials stored in device-secure elements, bypassing traditional card-network routing. India's UPI ecosystem and Brazil's PIX infrastructure are driving fastest adoption where smartphone penetration outpaces card issuance.
- Debit Card:Direct bank account debiting with lower interchange economics, favored by cost-sensitive merchants in European markets under PSD3 cost-transparency pressures.
- Bank Transfer:Account-to-account initiation bypassing card networks entirely, gaining traction where real-time payment rails like FedNow reduce settlement latency.
Credit card infrastructure absorbs the bulk of installed capacity; e-wallet is expanding most quickly.
Deployment Model:
Operational cost structures separate merchant segments by engineering sophistication and compliance risk tolerance.
- Cloud-Based:Elastic compute provisioning through AWS, Azure, or GCP infrastructure enables sub-500 millisecond authorization scaling during demand spikes. Digital-native retailers in Southeast Asia prioritize API-first architectures with automated failover across availability zones.
- On-Premise:Dedicated hardware stacks in merchant data centers, maintaining full custody of transaction data. Heavily regulated healthcare and financial services verticals in Germany and Switzerland demand this model for data residency compliance.
- Hybrid:Sensitive authentication data retained on-premise while routing logic operates in cloud environments, splitting PCI scope.
- Self-Hosted:Open-source gateway software deployed on merchant-controlled infrastructure, favored by developer-heavy organizations with dedicated security engineering teams.
Cloud-based deployments command the largest share of new merchant acquisitions; self-hosted is climbing the fastest among technically sophisticated vertical SaaS platforms.
End User:
Vertical-specific compliance requirements and checkout latency sensitivity shape gateway feature prioritization.
- E-Commerce:Pure-play online merchants demanding omnichannel token vaulting and subscription billing APIs. India's DPIIT-registered startups and direct-to-consumer brands in the US represent concentrated demand for one-click checkout optimization.
- Retail:Brick-and-mortar networks requiring unified commerce platforms that synchronize inventory, loyalty, and payment data across POS and mobile channels.
- Hospitality:Pre-authorization holds and incremental settlement capabilities for hotels and restaurants managing chargeback exposure from no-show bookings.
- Healthcare:HIPAA-aligned transaction processing with HSA/FSA card acceptance and insurance co-pay splitting, concentrated among US provider networks and pharmacy chains.
E-commerce accounts for the dominant share of transaction volume; healthcare is gaining share fastest as patient payment responsibility shifts to consumer-directed models.
Transaction Type:
Authorization flow architecture and fraud scoring intensity diverge meaningfully across channel contexts.
- Online:Browser-based checkout with 3D Secure 2.0 authentication and device fingerprinting for fraud prevention. Cross-border merchants serving India and Nigeria face highest scrutiny from EU AI Act algorithmic transparency requirements for automated decline decisions.
- Mobile:In-app SDK integration with biometric authentication and native wallet provisioning, expanding fastest where super-app ecosystems dominate consumer behavior.
- In-Store:EMV contact and contactless terminal integration with tap-to-pay credential transmission, requiring PCI PTS certification for hardware security modules.
- Recurring:Credential-on-file transactions with network token lifecycle management and intelligent retry logic for failed renewals, critical for subscription SaaS and utility billing verticals.
Online transactions absorb the majority of gateway processing volume; recurring is expanding most quickly as subscription commerce penetrates B2B procurement and consumer services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gateway infrastructure investment concentrates in economies with underdeveloped card networks and aggressive central bank digitization mandates. Consumption gravity sits with mobile-first populations where smartphone penetration outpaces traditional banking access. Production of payment software and API architectures clusters in technology hubs with deep engineering talent pools.
India
Merchant demand concentrates around UPI-enabled checkout flows and subscription billing APIs for DPIIT-registered startups. RBI guidelines on digital payment security and tokenization vaulting reshape technical roadmaps for domestic and cross-border providers. Bangalore's fintech corridor anchors engineering centers for API-first gateway architectures serving Southeast Asian expansion.
United States
E-commerce merchants and vertical SaaS platforms drive procurement of cloud-native orchestration layers with sub-500 millisecond authorization scaling. FedNow real-time payment rails create substitution pressure on traditional card-gateway economics for account-to-account transfers. San Francisco Bay Area and New York Metro clusters host developer-centric platforms competing on integration velocity metrics.
Germany
Enterprise retailers and healthcare networks prioritize hybrid deployment models with on-premise credential custody for data residency compliance. PSD3 open-banking integration standards compress technical roadmaps for account-to-account initiation capabilities. Frankfurt's financial infrastructure hub concentrates compliance engineering for EU AI Act algorithmic transparency requirements.
Brazil
Merchant acquiring demand converges on PIX instant payment integration with omnichannel token vaulting for recurring billing use cases. Central bank mandates on open-banking convergence create white space for gateway operators embedding PIX rails with value-added services. São Paulo's fintech ecosystem anchors product development for Latin American market expansion.
United Kingdom
Cross-border e-commerce merchants seek unified commerce platforms synchronizing inventory, loyalty, and payment data across online and in-store channels. FCA and Payment Systems Regulator oversight on strong customer authentication and open-banking standards shapes vendor selection criteria. London's financial technology cluster concentrates sales engineering for European merchant acquisition.
Global Payment Gateways Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered service configurations. The vendor base organizes around three strategic archetypes: developer-centric API platforms, unified commerce infrastructure providers, and dual-sided consumer-merchant networks. Consolidation pressure intensifies as mid-tier operators absorb PCI DSS compliance cost escalation. Dominant competitive moves include M&A-driven capability expansion and strategic partnerships embedding gateway services into vertical SaaS workflows.
Within the developer-centric tier, Stripe and Checkout.com occupy positions exemplifying API-first architectural competition. Adyen anchors the unified commerce vector spanning online and in-store channel consolidation. PayPal represents the network-effects archetype leveraging consumer wallet penetration to control checkout flow volume. PayU exemplifies emerging market specialization with India and Latin America geographic concentration. These five entities collectively illustrate how procurement criteria have shifted toward engineering experience metrics and integration velocity benchmarks.
| Leading Market Players |
|---|
| Stripe |
| Adyen |
| PayPal |
| Worldpay |
| PayU |
| Payoneer |
| Checkout.com |
| Braintree |
| Fiserv |
| Others |
Cost & Logistics Intelligence
PCI DSS Level 1 certification costs cascade from specialized security engineering labor through three distinct pricing tiers, with cloud-native API platforms commanding premium positioning over legacy on-premise operators burdened by compliance audit cycles.
Pricing Analysis
Margin tightening in mid-tier gateway operations reflects escalating PCI DSS audit frequency and security engineering headcount requirements. Three-tier pricing structure across enterprise API platforms, mid-market orchestration layers, and economy-tier basic routing services segments buyer archetypes by integration complexity needs. Cost-down pressure on standard-tier providers accelerates because acquiring bank concentration in North America extracts interchange-adjacent fees. Digital-native e-commerce merchants in India and Southeast Asia exhibit highest price sensitivity, prioritizing developer experience metrics over rate tables; enterprise healthcare networks in Germany demonstrate lowest sensitivity due to data residency compliance mandates.
Supply Chain Analysis
Regional distribution centers for gateway infrastructure cluster in Bangalore's fintech corridor, São Paulo's technology hub, and the San Francisco Bay Area, creating hub-and-spoke patterns for API architecture deployment. Engineering talent concentration in India, Brazil, and the United States anchors software development capacity. Raw material dependencies center on cloud compute provisioning from AWS, Azure, and GCP; network token services from Visa and Mastercard; and specialized fraud-scoring algorithm libraries. Single-source vulnerability in hyperscaler infrastructure poses structural risk. Distribution runs through direct API integration with merchant development teams, displacing traditional channel partner models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Security engineering talent scarcity props pricing power for compliant operators, constraining capacity expansion among mid-tier competitors unable to absorb PCI DSS certification overhead.
For Market Incumbents: Acquire specialized fraud-scoring algorithm developers to fortify EU AI Act compliance capabilities before algorithmic transparency mandates harden competitive moats. Defend against account-to-account substitution by embedding real-time payment rails like FedNow and PIX directly into unified commerce platforms. Capacity addition in Bangalore and São Paulo engineering clusters sustains API-first development velocity against emerging modular orchestration competitors. For New Entrants and Emerging Players: PSD3 in Europe opens a window for account-to-account initiation specialists targeting cross-border merchants facing compressed technical roadmaps. Brazil's PIX open-banking convergence represents the most penetrable geography, with central bank mandates creating white space for integrated acquiring services. Developer-centric go-to-market positioning emphasizing sandbox reliability and documentation quality displaces traditional procurement in Southeast Asian digital-native verticals. For Investors and Strategic Acquirers: RBI digital payment security guideline enforcement is the leading indicator that India-based gateway operators will command sustained valuation premiums over the next decade. Acquisition target archetype: cloud-native orchestration layers with established UPI integration and recurring billing API traction. Monitor FedNow transaction volume growth as the inflection signal for account-to-account infrastructure substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Network Tokenization Integration | Visa and Mastercard vaulting services reduce PCI scope for subscription commerce merchants. |
| Real-Time Payment Rail Embedding | FedNow and PIX integration defends against account-to-account bypass of traditional gateway economics. |
| Explainable AI Investment | EU AI Act algorithmic transparency requirements force fraud-scoring engine redesigns for European access. |
| Vertical SaaS Partnership | Embedded finance penetration in logistics and procurement displaces standalone gateway relationships. |
| Hybrid Deployment Certification | German and Swiss healthcare demand for on-premise credential custody creates premium service tier. |
Research Approach
Document review covered RBI circulars on digital payment security, EU AI Act implementation guidance, and PCI DSS certification frameworks, complemented by interviews with gateway platform CTOs, merchant integration specialists, and acquiring bank product officers. Secondary validation drew from SEC filings of publicly listed payment processors, hyperscaler infrastructure capex disclosures, and central bank real-time payment system reports. Bottom-up merchant procurement pattern analysis and top-down regulatory impact assessment were triangulated.
Cross-referencing historical authorization volume trajectories against panel input from engineering-led vendor selection processes shaped the analytical framework across the analysis window. Segmentation dimensions modeled include deployment model, payment method, end-user vertical, transaction type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves. Industry-specific inputs encompassed UPI transaction growth patterns and PSD3 technical roadmap acceleration timelines.
The model assumes a particular technology adoption path; alternative pathways for account-to-account real-time payment infrastructure would alter the outlook substantially. Forecasts reflect stated assumptions regarding regulatory implementation timing and merchant procurement behavioral continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Mexico Real Time Payments Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Canada POS Terminal Market
Payments
Global Digital Wallets Market
Payments
UAE Buy Now Pay Later Services Market
Payments
Telecom Cloud Billing Market
Payments
Saudi Arabia Mobile Payments Market
Payments
Japan Payment Gateway Market
Payments
United States Payments Market
Payments
Credit Card Payments Market
Payments
B2B Payments Platform Market
Payments
Japan Virtual Cards Market
Payments
Cash Management Software Market
Payments
Sweden Mobile Payments Market
Payments
Face-Swiping Payment Market
Payments
Germany Real Time Payments Market