
 Digital Transfer Services Market | 2026-2036
Digital Transfer Services Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Transfer Services Market Insights
Developer talent scarcity for real-time payment protocol integration is bifurcating competitive outcomes in the Digital Transfer Services Market. Western Union Holdings sustains extensive agent-network coverage across corridors with limited digital penetration. Wise differentiates through transparent mid-market rate positioning and API-first infrastructure. PayPal Holdings leverages dual-sided consumer and merchant ecosystems to control cross-border checkout flows.
Digital transfer services encompass encrypted, protocol-governed movement of monetary value or data payloads between disparate financial systems, typically operating through SWIFT, blockchain, or REST API architectures with sub-second settlement windows for real-time variants. Cloud-based deployment models now dominate new implementations, though hybrid configurations retain share among BFSI institutions with legacy core banking dependencies. API-based transfer services represent the fastest-expanding segment as embedded finance partnerships proliferate, while secure file transfer maintains stable revenue within government and healthcare compliance frameworks.
ISO 20022 mandates from the European Central Bank and the US Federal Reserve are forcing infrastructure upgrades across correspondent banking networks. India's RBI guidelines on UPI international expansion and the EU's PSD3 framework are reshaping market access rules for non-bank payment service providers. Stakeholders must monitor which regulatory jurisdictions adopt mutual recognition agreements versus unilateral licensing requirements.
Market Dynamics
ISO 20022 migration mandates from the European Central Bank and the US Federal Reserve are forcing correspondent banks to replace legacy SWIFT MT messaging infrastructure, creating a structural divide between institutions that have completed protocol upgrades and those still operating on deprecated standards.
Growth Catalysts
- UPI International Expansion:India's RBI guidelines enabling cross-border UPI corridors are accelerating real-time retail remittance volumes between India and the UAE, Singapore, and the United Kingdom.
- PSD3 Framework:The EU's revised payment services directive is reducing licensing friction for non-bank payment service providers seeking passported access across member states.
- Embedded Finance APIs:REST-based transfer interfaces are enabling SaaS platforms and e-commerce marketplaces to embed cross-border payout capabilities without building proprietary banking infrastructure.
Market Restraints
- Correspondent Banking Concentration:Dollar clearing remains dominated by a narrow set of US-headquartered global systemically important banks, creating single-point-of-failure risk for emerging market corridors.
- Compliance Cost Escalation:Enhanced due diligence requirements under FATF Recommendation 16 are inflating operational costs for smaller remittance operators serving high-risk jurisdictions.
- Legacy Core Dependencies:Hybrid cloud deployments required by BFSI institutions with mainframe-based core banking systems are constraining real-time settlement architecture adoption.
Strategic Opportunities
- Sub-Saharan Africa Corridors:Underpenetrated mobile money interoperability between East African markets and Gulf Cooperation Council states offers first-mover positioning for API-native providers.
- Stablecoin Settlement Rails:Convergence between licensed payment institutions and regulated digital asset custody frameworks is enabling same-day settlement for B2B trade finance without correspondent banking delays.
- India Stack Integration:Account Aggregator framework and OCEN protocol adoption are creating new data-permissioned lending and payment orchestration services for domestic and diaspora users.
Industry Challenges
- Real-Time Protocol Engineering Talent:Scarcity of developers proficient in ISO 20022 message mapping and distributed ledger interoperability is extending implementation timelines for infrastructure upgrades.
- Multi-Jurisdiction Licensing Complexity:Fragmented state-level money transmitter licensing in the United States and unilateral regulatory requirements in Southeast Asian markets are consuming 18-24 month market entry cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Transfer Services Market |
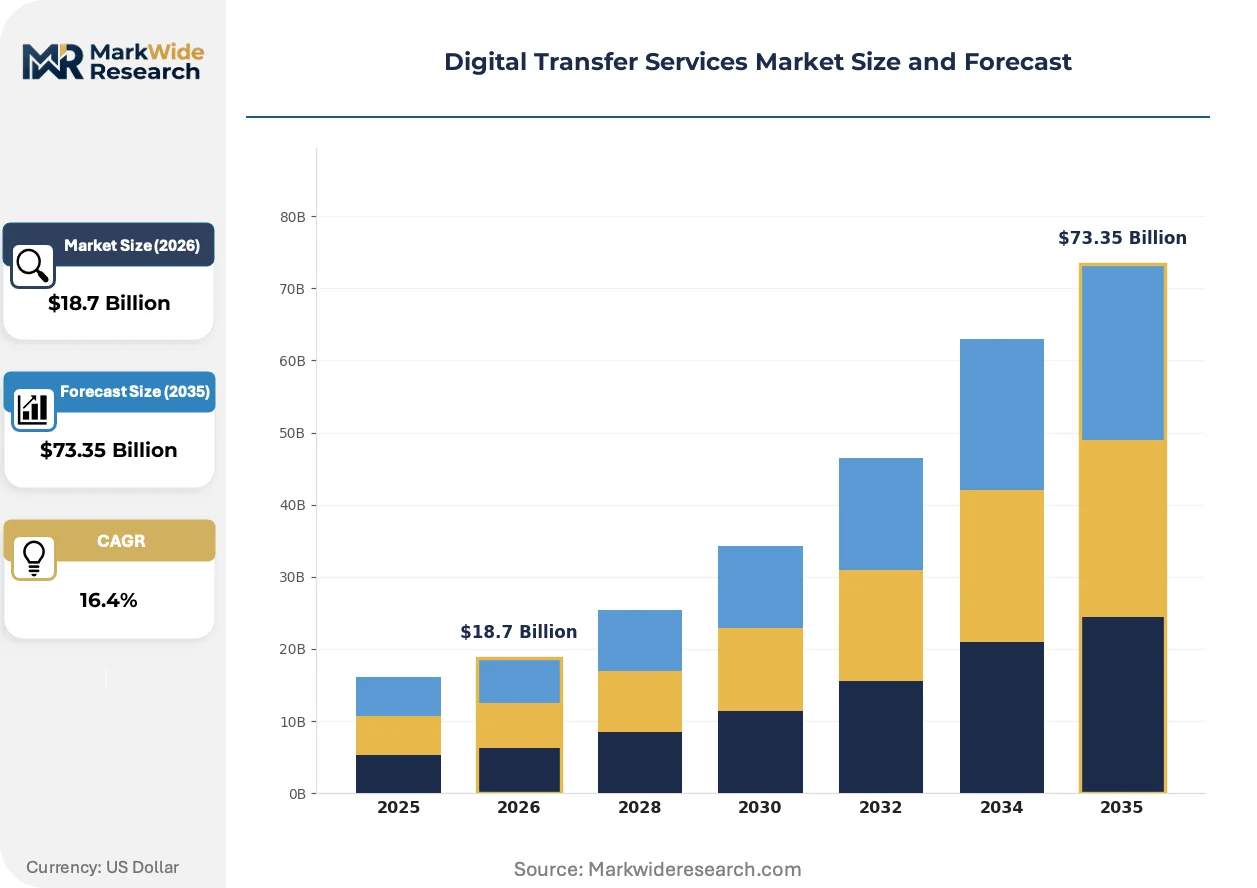
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Migration, Secure File Transfer, API-Based Transfer, Cloud Backup, Real-Time Sync Deployment Model: Cloud-Based, On-Premises, Hybrid, Multi-Cloud, Edge Computing End User Industry: BFSI Institutions, Telecommunications, Education Providers, Government Agencies, Media Companies Distribution Channel: Direct Sales, Channel Partners, Online Marketplaces, System Integrators, Managed Service Providers |
| Companies Covered | Western Union Holdings, PayPal Holdings, Wise, MoneyGram International, Remitly Global, WorldRemit, Azimo Limited, Ria Financial Services, TransferGo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Transfer Services Market Trends and Innovations
Payment infrastructure is splitting between closed-loop proprietary networks and open-protocol interoperable systems, with regulatory mandates determining which architecture gains adoption in each corridor. This divergence is reshaping vendor strategies and partnership requirements.
Blockchain-based settlement layers with sub-second finality are bifurcating wholesale cross-border payment markets. Large corporate treasury departments at multinational manufacturers are piloting these rails for intra-group liquidity movements. The technology is compressing settlement windows from T+2 to real-time while reducing nostro-vostro liquidity requirements.
REACH-style data portability principles embedded in the EU's PSD3 framework are compelling payment service providers to expose transaction history through standardized APIs. This industrial consequence enables account-to-account payment initiation without card network intermediation. Retail e-commerce merchants in Germany and the Netherlands are responding by integrating open banking checkout flows that bypass interchange fees.
Gig-economy workforce payment expectations are compressing cross-border payroll cycles from monthly to on-demand. Platform employers in ride-hailing and freelance services are unbundling traditional remittance channels in favor of direct digital wallet provisioning. This pattern is most visible in India-originating corridors serving construction and domestic worker diaspora populations in the Middle East.
Digital Transfer Services Market Segmentation
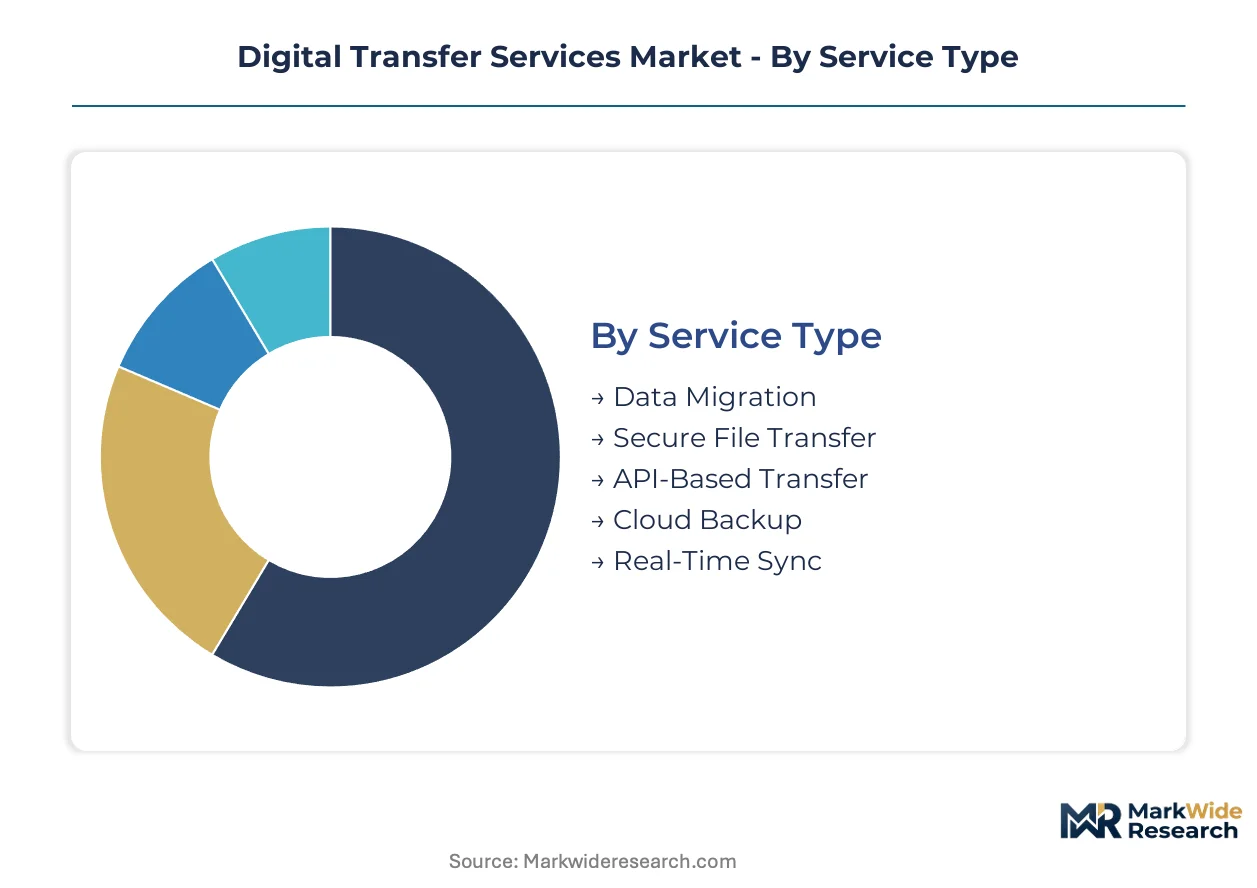
Segmentation in digital transfer services reveals distinct margin architectures across service modalities and infrastructure choices. Deployment model selection and end-user vertical concentration determine vendor profitability more than transaction volume alone.
Service Type:
Margin pools concentrate in protocol-governed real-time services and API-first integration layers rather than commodity file movement.
- API-Based Transfer:REST and gRPC interfaces enabling embedded finance orchestration with sub-second settlement windows. Demand concentrates among SaaS platforms in India and Singapore building cross-border payout capabilities without correspondent banking infrastructure, driven by UPI international expansion mandates from RBI.
- Real-Time Sync:Continuous data replication with conflict resolution for distributed ledger and core banking interoperability. BFSI institutions in the United Kingdom and Germany are prioritizing these services to meet European Central Bank ISO 20022 migration deadlines for TARGET2 and SWIFT gpi compatibility.
- Secure File Transfer:Encrypted batch protocols for healthcare and government compliance frameworks.
- Data Migration:Large-scale structured and unstructured data movement during core banking system replacements.
- Cloud Backup:Disaster recovery and archival storage with geographic redundancy requirements.
The dominant share belongs to API-Based Transfer, while Real-Time Sync is closing the gap fastest.
Deployment Model:
Cost tier stratification separates hyperscale cloud commitments from regulated hybrid configurations requiring mainframe coexistence.
- Cloud-Based:Fully managed infrastructure with consumption-based pricing and automatic scaling. Volume concentrates among fintech startups in the United Arab Emirates and United Kingdom bypassing capital expenditure barriers, constrained by data localization requirements in Saudi Arabia and India.
- Hybrid:Split workloads between on-premises legacy systems and cloud orchestration layers. BFSI institutions in Germany and France with decades-old core banking dependencies require this model to maintain regulatory audit trails while accessing real-time API capabilities.
- On-Premises:Dedicated hardware deployments for classified government and defense data corridors.
- Multi-Cloud:Redundant architectures across AWS, Azure, and regional providers to mitigate vendor lock-in.
- Edge Computing:Distributed processing nodes for latency-sensitive trading and IoT payment triggers.
Cloud-Based deployments command the largest installed base, though Hybrid configurations are expanding most quickly among established financial institutions.
End User Industry:
Application-specific compliance requirements and transaction frequency patterns shape vendor selection criteria across verticals.
- BFSI Institutions:Banks, insurers, and payment service providers requiring SWIFT, ISO 20022, and open banking protocol compliance. Correspondent banking networks in the United States and United Kingdom are upgrading infrastructure to maintain dollar and pound clearing access, pressured by Federal Reserve and Bank of England migration timelines.
- Government Agencies:Sovereign payment systems and treasury operations with national security classification requirements. India's state-level implementations of UPI-linked welfare disbursements and the European Commission's digital euro pilot programs are driving specialized procurement.
- Telecommunications:Mobile money interoperability and airtime remittance corridors.
- Media Companies:High-volume content delivery with digital rights management integration.
- Education Providers:Cross-border tuition payment processing and research data collaboration.
BFSI Institutions retain the dominant procurement volume, while Government Agencies are gaining share fastest through sovereign digital currency and welfare payment modernization.
Distribution Channel:
Customer type and purchasing sophistication determine whether direct vendor relationships or intermediary layers prove more efficient.
- System Integrators:Accenture, TCS, and regional consulting firms bundling transfer services with core banking transformation programs. Large BFSI institutions in Germany and the United States prefer this channel for complex ISO 20022 migration projects requiring change management and regulatory filing support.
- Managed Service Providers:Outsourced operations with guaranteed uptime SLAs and compliance monitoring. Mid-tier banks in Singapore and the United Arab Emirates lacking in-house protocol engineering talent are consolidating procurement through MSPs to access scarce ISO 20022 expertise.
- Direct Sales:Enterprise agreements with top-tier global banks and payment networks.
- Channel Partners:Value-added resellers with regional regulatory specialization.
- Online Marketplaces:Self-service API provisioning for developers and startups.
System Integrators control the largest revenue flow, though Managed Service Providers are climbing the fastest as talent scarcity forces outsourcing decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across corridors. India and the United Arab Emirates prioritize real-time retail remittances through mobile-first infrastructure, while Germany and the United Kingdom concentrate procurement on wholesale banking protocol upgrades. The United States maintains dollar-clearing dominance through correspondent banking concentration.
India
UPI international expansion and Account Aggregator framework adoption are accelerating cross-border payment volumes. RBI guidelines mandating UPI linkages with UAE, Singapore, and UK corridors are reshaping remittance infrastructure requirements. Mumbai and Bengaluru clusters host API-native fintech startups building embedded payout capabilities for diaspora corridors.
United Arab Emirates
Gig-economy workforce payment expectations are compressing payroll cycles from monthly to on-demand for South Asian construction and domestic worker populations. Central Bank of the UAE open banking regulations are enabling non-bank payment service provider licensing for remittance operators. Dubai International Financial Centre concentrations are attracting API-first transfer infrastructure providers targeting India-originating corridors.
Germany
BFSI institutions with decades-old core banking dependencies are prioritizing hybrid cloud deployments to maintain regulatory audit trails. European Central Bank ISO 20022 migration deadlines for TARGET2 compatibility are forcing infrastructure replacement timelines. Frankfurt and Munich banking clusters are consolidating procurement through system integrators for complex protocol migration projects.
United Kingdom
Wholesale banking networks are upgrading SWIFT gpi infrastructure to maintain pound clearing access amid protocol transition pressures. Bank of England migration timelines are accelerating correspondent banking replacement cycles. London financial services concentrations are driving demand for real-time sync services enabling distributed ledger and core banking interoperability.
United States
Dollar clearing concentration among US-headquartered global systemically important banks creates single-point-of-failure risk for emerging market corridors. Federal Reserve ISO 20022 migration mandates are forcing legacy SWIFT MT infrastructure replacement. New York and Chicago financial centers are experiencing extended implementation timelines due to scarcity of developers proficient in protocol mapping and distributed ledger interoperability.
Digital Transfer Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling correspondent banking access and dual-sided network effects while specialists capture corridor-specific volume through rate transparency and API velocity. The structure rewards scale in clearing relationships and regulatory licensing breadth. Three archetypes dominate: agent-network incumbents with geographic density, API-native challengers with embedded finance partnerships, and platform-integrated ecosystems with checkout flow control. Consolidation is accelerating through corridor-specific acquisitions and protocol engineering talent poaching.
Among the integrated leaders, Western Union Holdings exemplifies the agent-network archetype with extensive corridor coverage in markets with limited digital penetration. PayPal Holdings occupies the platform-integrated position, leveraging dual-sided consumer and merchant ecosystems. Wise represents the API-native challenger model, differentiating through transparent mid-market rate positioning and infrastructure-first architecture.
| Leading Market Players |
|---|
| Western Union Holdings |
| PayPal Holdings |
| Wise |
| MoneyGram International |
| Remitly Global |
| WorldRemit |
| Azimo Limited |
| Ria Financial Services |
| TransferGo |
| Others |
Pricing and Supply Chain Analysis
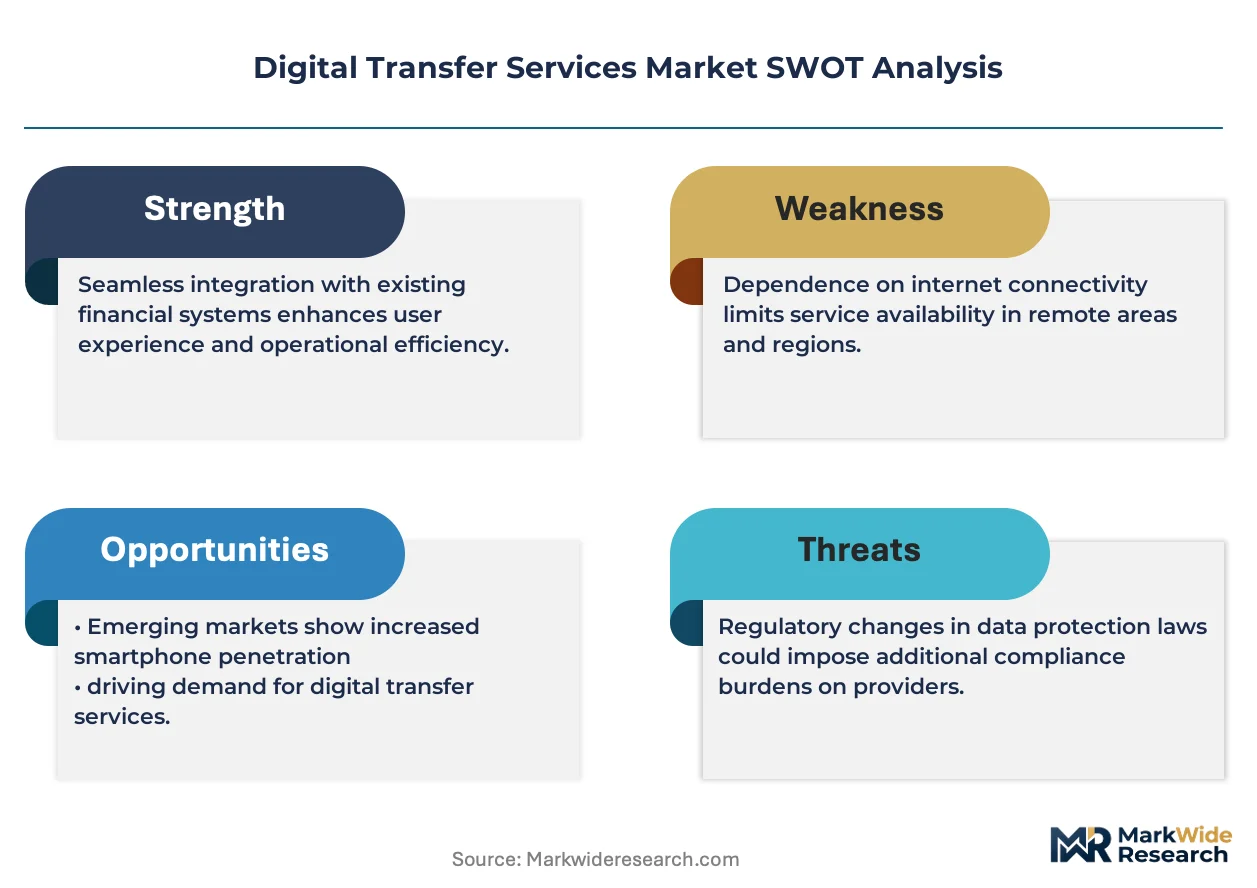
Hyperscale cloud infrastructure commitments in India and the United Arab Emirates generate unit-cost advantages that compress price floors for API-native transfer services while elevating barriers for hybrid-deployment competitors serving German and French BFSI institutions. This scale dynamic concentrates procurement power among consumption-based pricing adopters and forces legacy-dependent vendors into defensive margin structures.
Pricing Analysis
Contract structures bifurcate between long-term enterprise agreements with major correspondent banks and consumption-based SaaS tiers for embedded finance platforms. Three-tier pricing structure across premium, standard, and economy levels separates dedicated ISO 20022 compliance support from self-service API access and basic file transfer capabilities. Cost compression in the standard tier intensifies because RBI-mandated UPI international expansion is democratizing real-time settlement infrastructure. Neobanks and gig-economy platforms exhibit highest price sensitivity, while sovereign payment systems and G-SIBs prioritize compliance guarantees over unit economics.
Supply Chain Analysis
Just-in-time provisioning dominates cloud-native deployments, though strategic stockpiling of protocol engineering talent extends implementation timelines for ISO 20022 migration projects. Infrastructure supply concentrates in India, the United Arab Emirates, and Singapore for API-first development, while Germany and the United Kingdom anchor hybrid cloud integration services. Raw material dependencies include SWIFT network access licenses, cloud compute capacity from hyperscalers, and scarce developer expertise in distributed ledger interoperability. Single-source vulnerability rests on concentrated dollar-clearing relationships among US-headquartered global systemically important banks. Distribution runs through system integrators for complex BFSI transformations and direct API marketplaces for fintech startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital transfer services sit in early-cycle expansion as embedded finance APIs displace traditional correspondent banking for retail remittance corridors, with regulatory mandates accelerating protocol standardization across multiple jurisdictions.
For Market Incumbents: Fortify correspondent banking access through accelerated ISO 20022 infrastructure completion before Federal Reserve and European Central Bank deadlines, while acquiring API-native challengers in India-UAE corridors to neutralize embedded finance displacement threats. Prioritize backward integration into cloud orchestration layers to reduce hyperscaler dependency and defend margin structures against consumption-based pricing erosion.
For New Entrants and Emerging Players: Anchor in Sub-Saharan Africa mobile money interoperability gaps, specifically East African to Gulf Cooperation Council corridors where incumbent agent networks retain limited digital penetration. Target API-first positioning for gig-economy payroll platforms serving South Asian diaspora construction and domestic worker populations in the Middle East, leveraging direct developer marketplace distribution to bypass system integrator gatekeeping.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors protocol engineering specialists with demonstrated ISO 20022 migration delivery and regulatory licensing breadth across multiple jurisdictions. Long-term viability hinges on capture of real-time settlement infrastructure contracts as legacy SWIFT MT depreciation accelerates. Watch for inflection signals in mutual recognition agreement adoption between RBI, Central Bank of the UAE, and Monetary Authority of Singapore, which would consolidate corridor access requirements and favor scale players.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Migration Completion | Secures correspondent banking access amid Federal Reserve and ECB mandate deadlines. |
| Embedded Finance API Partnership | Enables SaaS platforms to provision cross-border payouts without proprietary infrastructure. |
| UPI International Corridor Expansion | Captures RBI-mandated retail remittance volume between India and UAE-Singapore-UK markets. |
| Stablecoin Settlement Rail Licensing | Converges licensed payment institutions with regulated digital asset custody frameworks. |
| Protocol Engineering Talent Acquisition | Addresses scarcity extending ISO 20022 implementation timelines at US and UK banks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings from the Reserve Bank of India, European Central Bank, and US Federal Reserve, alongside SWIFT infrastructure disclosure documents and cloud hyperscaler capex reports. Primary interviews engaged payment protocol engineers at correspondent banks, regulatory compliance officers at non-bank payment service providers, treasury technology leads at multinational manufacturers, and API product managers at embedded finance platforms. Secondary validation drew from BIS innovation hub publications, IMF cross-border payment progress reports, and national payment system operator annual disclosures. Bottom-up transaction volume modeling triangulated against top-down corridor value estimates.
Segmentation dimensions modeled include service type, deployment model, end-user industry, and distribution channel, with additional granularity on protocol standard adoption status across the analysis window. CAGRs derived from historical volume trajectories in UPI-linked corridors and projected embedded finance API penetration curves, incorporating regulatory mandate acceleration effects and talent scarcity implementation delays. Industry-specific forecast inputs encompass ISO 20022 migration completion schedules and open banking API adoption rates by jurisdiction.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory momentum for real-time payment protocol standardization and stable cloud infrastructure pricing; material deviation in mutual recognition agreement adoption or correspondent banking consolidation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
India Gift Card and Incentive Card Market
Payments
Vietnam Payments Market
Payments
Cross-Border Payment Platform Market
Payments
Payment Card Market
Payments
Forex Cards Market
Payments
Europe Mobile Payment Market
Payments
Saudi Arabia Payments Market
Payments
Spain Real Time Payments Market
Payments
Subscription Billing Management Market
Payments
Denmark POS Terminals Market
Payments
Epayment System Market
Payments
Mexico POS Terminals Market
Payments
Belgium Payments Market
Payments
Europe Accounts Payable Automation Market
Payments
North America Payments Market
Payments
Direct Carrier Billing Market