
 Retail POS Terminals Market | 2026-2036
Retail POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Retail POS Terminals Market Analysis
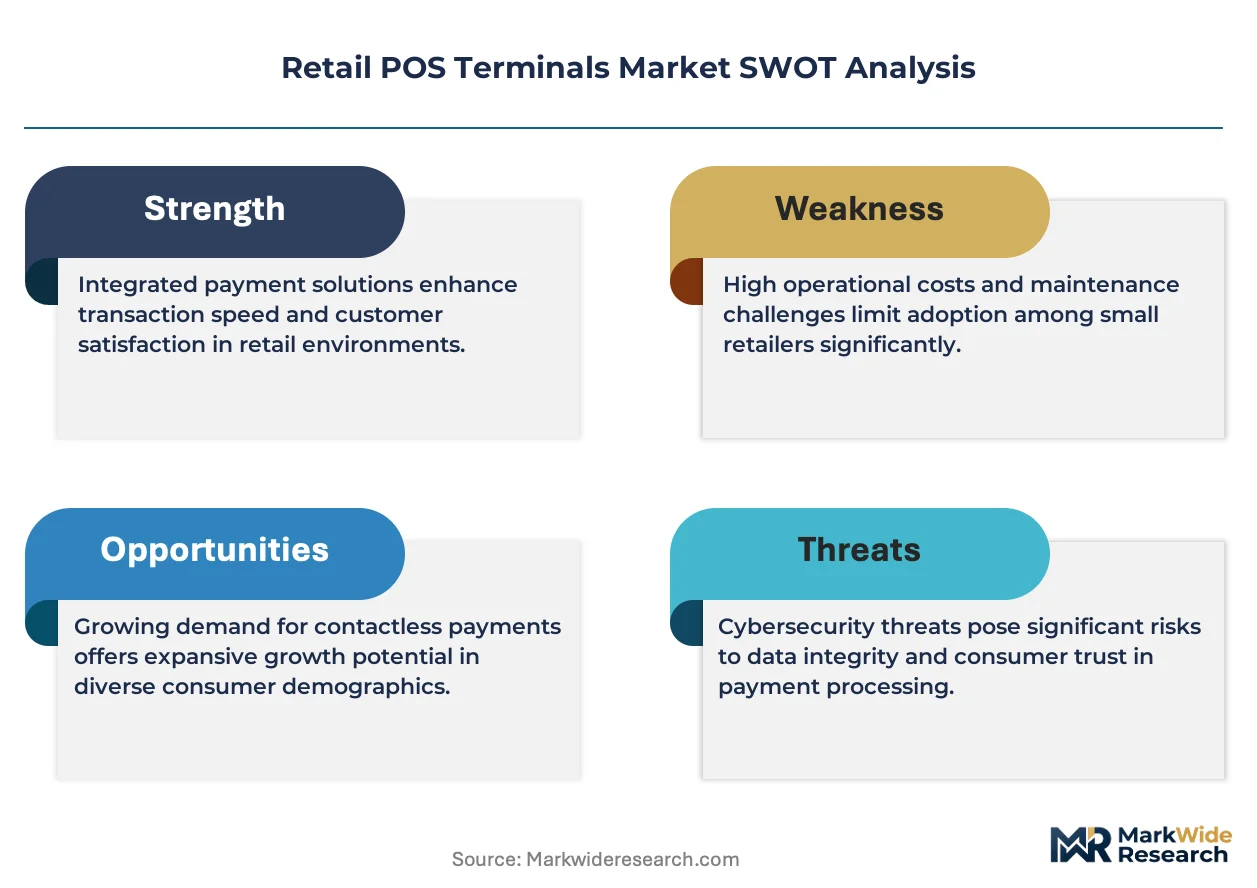
PCI DSS 4.0 is consolidating the cost-of-entry calculus for new hardware vendors seeking merchant processor certifications. NCR Corporation leverages its integrated payments ecosystem to sustain enterprise-grade deployment pipelines across grocery and hospitality chains. Ingenico Group anchors European certification pathways while PAX Technology competes aggressively on Android-based terminal architectures in Asian markets.
Retail POS terminals constitute electronic transaction devices combining secure payment processors, touchscreen interfaces, and encrypted communication modules to authenticate and settle consumer purchases at physical points of sale. These systems integrate EMV chip readers, NFC antennas, and barcode scanners to process multiple tender types while transmitting encrypted data to acquiring banks. Mobile POS and cloud-based deployment segments lead current growth trajectories as merchants prioritize flexible, software-defined checkout experiences over fixed countertop infrastructure. Contactless payment technology dominates technology segment dynamics as NFC-enabled terminal penetration accelerates across quick-service restaurant and supermarket end users.
FDA guidelines for retail pharmacy POS integrations, FCC Part 15 emissions standards for wireless terminal hardware, and PCI SSC security certification requirements collectively shape product development timelines and market access conditions for terminal manufacturers. The EU AI Act introduces emerging compliance dimensions for POS systems incorporating biometric authentication or predictive analytics capabilities. Stakeholders must monitor evolving encryption standards and regional data-localization mandates to align hardware roadmaps with shifting compliance architectures.
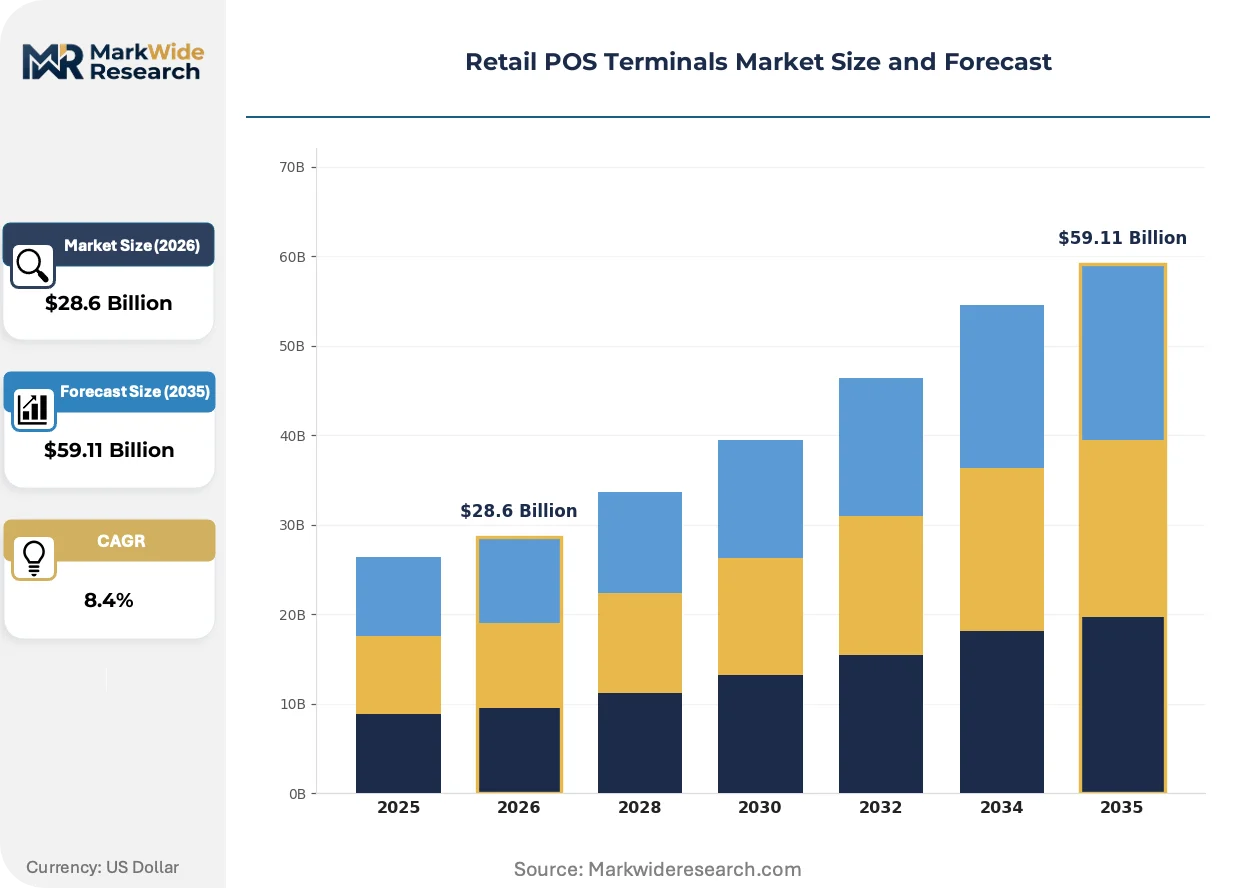
Market Dynamics
Contactless payment mandates from the PCI Security Standards Council are compressing hardware refresh cycles across quick-service restaurant and supermarket chains, forcing merchants to abandon mag-stripe infrastructure ahead of end-of-life timelines.
Growth Catalysts
- PCI DSS 4.0 compliance deadlines:Merchant processors in the United States are rejecting non-compliant terminals, creating forced-upgrade demand across independent retailers and franchise networks.
- Quick-service restaurant digitization:Drive-thru and kiosk deployments require NFC-enabled terminals with encrypted communication modules to process tap-to-pay transactions at speed.
- Supermarket self-checkout expansion:Grocery chains are replacing fixed lanes with modular terminal arrays that integrate barcode scanning and contactless payment in single-footprint devices.
Market Restraints
- Semiconductor supply concentration:Secure element chip fabrication concentrates among Asian foundries, creating procurement bottlenecks for terminal manufacturers seeking EMV certification.
- Certification cost escalation:PCI SSC laboratory testing fees and processor integration timelines extend product launch cycles by 8-14 months for new hardware entrants.
- Smartphone payment substitution:Soft-POS applications on consumer handsets threaten dedicated terminal demand among micro-merchants and pop-up retailers.
Strategic Opportunities
- India merchant digitization:RBI push for card-present infrastructure among unorganized retailers creates first-mover positioning for Android-based terminal architectures.
- EU AI Act biometric compliance:Facial authentication integration in POS systems opens premium pricing tiers for terminals with embedded neural processing units.
- Cloud-native terminal management:Remote software deployment and over-the-air security updates enable hardware-as-a-service revenue models replacing outright purchase.
Industry Challenges
- Embedded systems engineering scarcity:Terminal manufacturers compete for firmware developers with expertise in secure boot architectures and cryptographic key injection.
- Legacy payment processor integration:ISO 8583 protocol variations across acquiring banks force custom certification work for each deployment geography.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail POS Terminals Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile POS, Countertop POS, Self-Service Kiosk, Cloud-Based POS Technology: Contactless Payment, NFC, EMV, Barcode Scanning End User: Small Retailers, Supermarkets, Restaurants, E-Commerce Platforms Deployment: On-Premise, Cloud, Hybrid, Outsourced |
| Companies Covered | NCR Corporation, Ingenico Group, PAX Technology, VeriFone Systems, Epicor Software Corporation, Toast Inc., Lightspeed Commerce, Block Inc., Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail POS Terminals Market Emerging Trajectories
Software-defined checkout experiences are displacing fixed countertop infrastructure as merchants prioritize flexibility over hardware longevity. Terminal architecture is shifting from proprietary operating systems to open Android platforms.
Android-based POS operating systems are electrifying hardware commoditization by enabling application marketplaces and third-party payment app sideloading. Quick-service restaurant chains in Southeast Asia are deploying these terminals at twice the pace of proprietary systems. The shift is compressing margins for incumbent manufacturers while opening entry paths for white-label hardware vendors.
The EU AI Act is imposing algorithmic transparency requirements on POS systems incorporating biometric authentication or predictive analytics. Terminal manufacturers must document training data provenance and decision logic for facial recognition payment flows. European supermarket operators are delaying biometric checkout pilots pending regulatory clarity, redirecting R&D budgets toward NFC antenna optimization instead.
Merchant procurement is consolidating around integrated payments ecosystems that bundle hardware, processing, and software subscriptions. Independent sales organizations and ISOs are losing share to direct relationships between terminal vendors and acquiring banks. This concentration is most visible in the United States, where vertical integration between hardware OEMs and payment processors is narrowing merchant choice.
Retail POS Terminals Market Segmentation
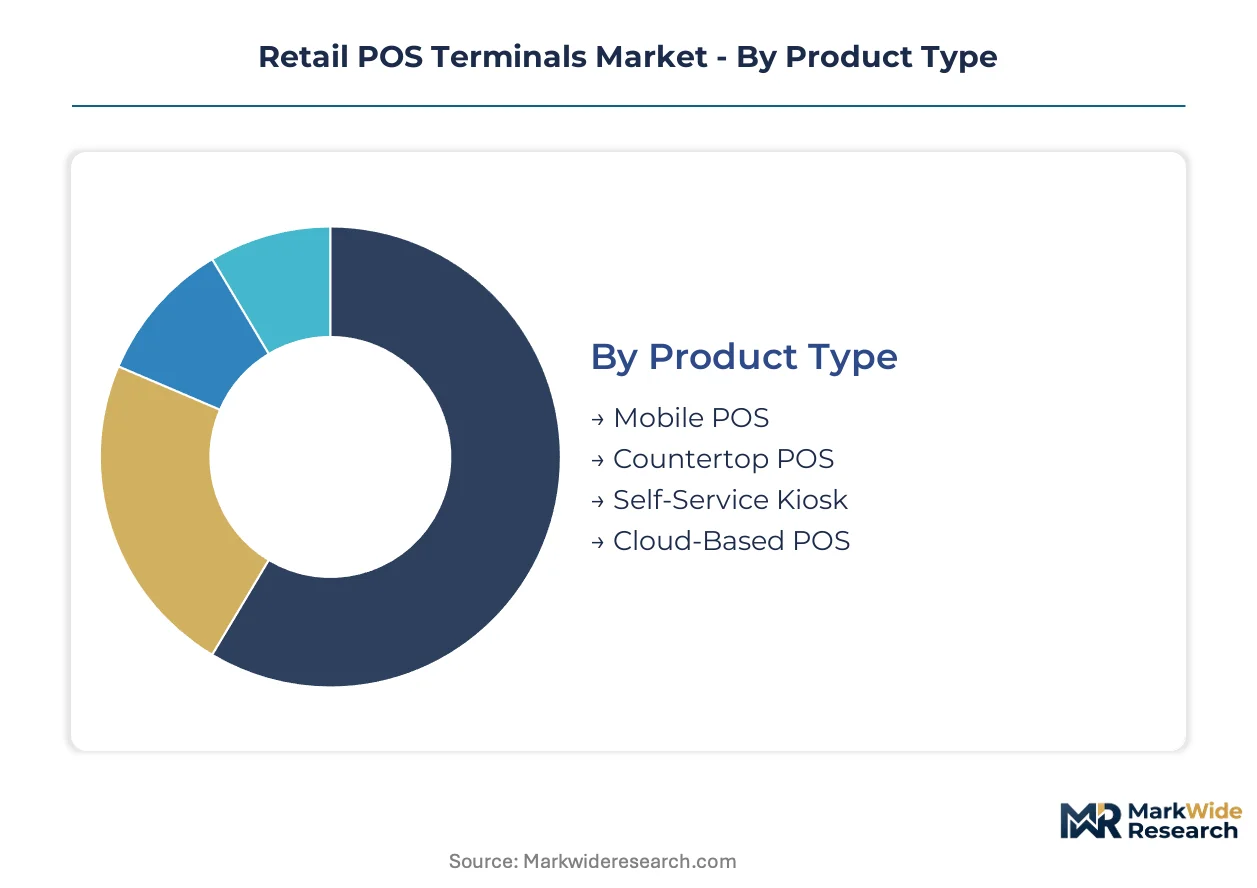
POS terminal segmentation reveals divergent hardware economics between high-volume commodity deployments and premium integrated systems. Merchant procurement patterns split sharply across product architectures, with mobile and cloud-native solutions commanding fundamentally different margin structures than fixed countertop infrastructure.
Product Type:
Volume concentration favors countertop units in grocery and big-box retail, while premium pricing attaches to modular, software-defined architectures.
- Mobile POS:Battery-powered terminals with integrated card readers and wireless connectivity modules enable line-busting and pop-up commerce. Quick-service restaurants in the United States deploy these units for curbside pickup and drive-thru lane extension, compressing transaction times during peak hours.
- Countertop POS:Fixed-position terminals with Ethernet tethering and proprietary operating systems dominate supermarket checkout lanes. These units prioritize EMV certification stability and processor integration reliability over feature flexibility, locking in longer replacement cycles.
- Self-Service Kiosk:Large-format touchscreen terminals with integrated barcode scanners and cash recyclers.
- Cloud-Based POS:Browser-native checkout interfaces running on commodity tablets with peripheral card readers.
Mature deployment sits with countertop POS. Newer deployment is concentrated in cloud-based POS.
Technology:
Certification cost tiers separate contactless infrastructure from legacy mag-stripe hardware, with EMV compliance acting as the primary gating factor for merchant processor approval.
- Contactless Payment:NFC antenna arrays and secure element chips enabling tap-to-pay transactions under 500 milliseconds. PCI DSS 4.0 mandates are accelerating terminal refreshes across quick-service restaurant chains in the United States, forcing mag-stripe abandonment ahead of hardware end-of-life.
- NFC:Near-field communication protocols operating at 13.56 MHz for smartphone wallet and wearable payment acceptance. European supermarkets are prioritizing NFC antenna range optimization over biometric checkout pilots, redirecting R&D budgets pending EU AI Act regulatory clarity.
- EMV:Chip card authentication standards with cryptographic transaction certificates.
- Barcode Scanning:Linear and 2D imager modules for product lookup and loyalty program integration.
Barcode scanning commands the widest installed base. Contactless payment is climbing the fastest.
End User:
Scale economics divide enterprise procurement with dedicated integration teams from small-merchant self-service adoption.
- Small Retailers:Independent merchants with sub-five-lane footprints and minimal IT support infrastructure. These operators prioritize all-in-one hardware bundles with bundled payment processing, accepting higher per-transaction fees for reduced technical complexity.
- Supermarkets:Grocery chains with 20-plus lane configurations and centralized IT departments. Self-checkout expansion is driving modular terminal array procurement, integrating barcode scanning and contactless payment in single-footprint devices to reduce lane conversion costs.
- Restaurants:Full-service and quick-service operators with tableside and counter service models.
- E-Commerce Platforms:Online-first retailers deploying physical pickup and return locations.
Supermarkets anchor hardware volume. Small retailers represent the steepest expansion trajectory.
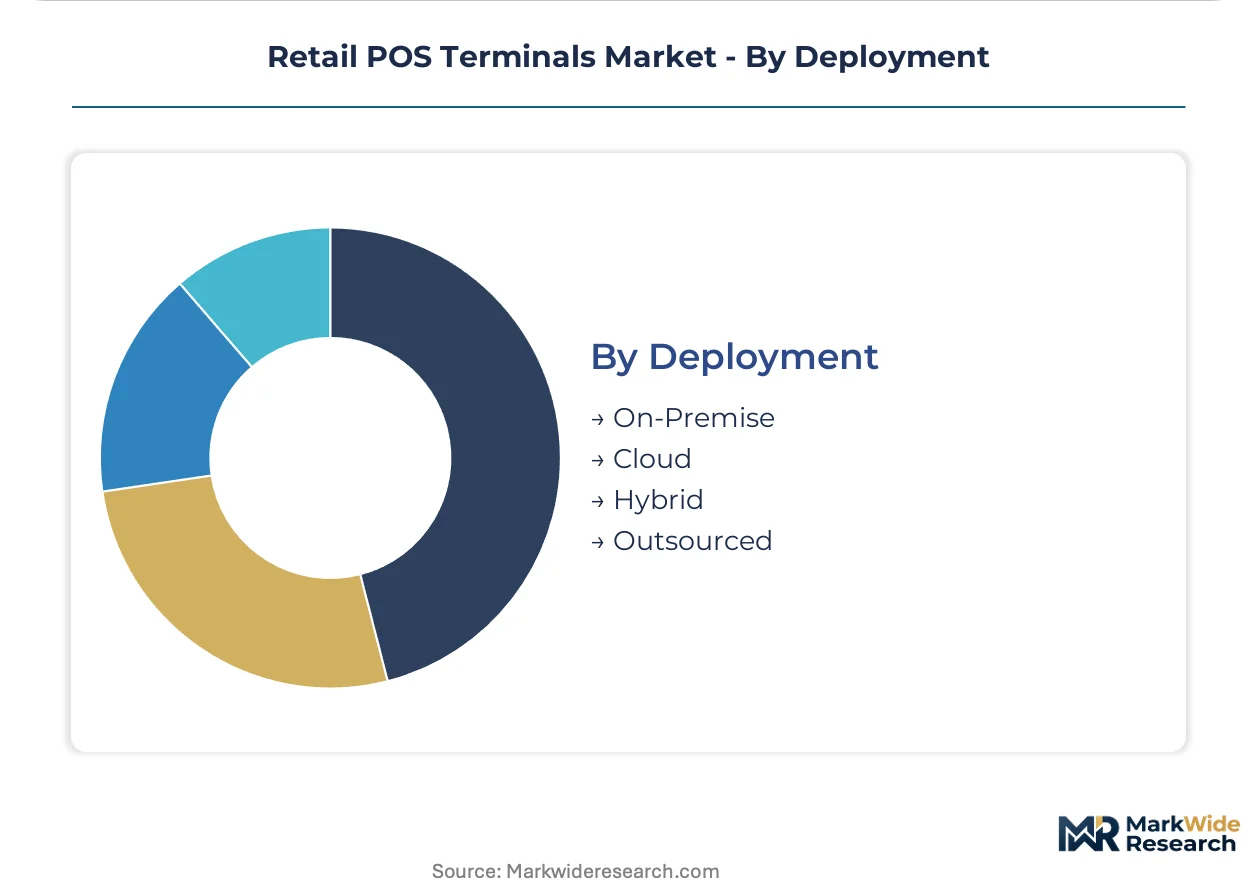
Deployment:
Operational control preferences separate merchants with compliance audit requirements from those prioritizing capital expenditure minimization.
- On-Premise:Locally hosted transaction processing with dedicated server infrastructure and direct acquiring bank connections. Large grocery chains maintain these deployments for sub-second authorization response times and offline transaction continuity during network outages.
- Cloud:Browser-based POS interfaces with API-connected payment processors and automatic security patch deployment. Quick-service restaurant franchises favor this model for centralized menu management and real-time sales analytics across distributed locations.
- Hybrid:Mixed architectures with local transaction caching and cloud synchronization.
- Outsourced:Fully managed POS services with hardware leasing and bundled technical support.
On-premise systems retain mission-critical retail. Cloud deployment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and the Pearl River Delta anchor terminal manufacturing concentration, drawing component suppliers and certification laboratories into clustered production corridors that feed global supply chains for NFC-enabled hardware.
United States
EMV liability shifts and PCI DSS 4.0 deadlines are forcing independent retailers and franchise networks into accelerated refresh cycles. The Federal Communications Commission enforces Part 15 emissions standards for wireless terminal hardware. Atlanta hosts major payment processor integration hubs where acquiring banks certify terminal deployments for national grocery chains.
China
Android-based terminal architectures dominate export manufacturing for Southeast Asian quick-service restaurant chains. The Ministry of Industry and Information Technology oversees GB standards compliance for wireless payment devices. Shenzhen's special economic zone concentrates secure element chip packaging facilities and EMV certification laboratories serving domestic and export markets.
Germany
Supermarket operators are redirecting R&D budgets toward NFC antenna optimization pending EU AI Act clarity on biometric checkout systems. The Federal Network Agency regulates terminal telecommunications interfaces under national implementation of European standards. Munich anchors enterprise POS integration teams for continental grocery and hospitality chains.
India
The Reserve Bank of India's push for card-present infrastructure among unorganized retailers is creating first-mover positioning for Android-based terminal architectures. Bureau of Indian Standards certification requirements govern terminal electromagnetic compatibility and safety. Mumbai and Bangalore host fintech clusters where payment aggregators pilot soft-POS alternatives to dedicated hardware.
United Kingdom
Contactless payment penetration above ninety percent is sustaining replacement demand for NFC-enabled countertop units in high-street retail. The Financial Conduct Authority coordinates with PCI SSC on merchant processor compliance frameworks. London's financial technology corridor concentrates terminal vendor sales operations and acquiring bank partnership teams.
Retail POS Terminals Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. Enterprise-grade deployment pipelines favor integrated payments ecosystems bundling hardware, processing, and software subscriptions. Three archetypes dominate: full-stack platform operators, hardware-centric OEMs, and cloud-native software vendors. M&A activity concentrates on payment processor acquisitions by terminal manufacturers, while strategic partnerships between acquiring banks and hardware OEMs narrow merchant procurement alternatives.
Among North American platform operators, NCR Corporation and Toast Inc. exemplify vertical integration strategies combining proprietary hardware with captive payment processing. Ingenico Group and PAX Technology represent contrasting geographic anchors for certification pathway dominance—European laboratory networks versus Asian Android-based manufacturing scale. VeriFone Systems occupies a position between these poles, maintaining processor-agnostic hardware architectures while building direct acquiring bank relationships.
| Leading Market Players |
|---|
| NCR Corporation |
| Ingenico Group |
| PAX Technology |
| VeriFone Systems |
| Epicor Software Corporation |
| Toast Inc. |
| Lightspeed Commerce |
| Block Inc. |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Android-based terminal architecture migration is compressing hardware margins while concentrating procurement leverage among Asian contract manufacturers with captive secure element packaging capabilities. This dual transformation simultaneously erodes proprietary OS pricing premiums and amplifies volume-scale advantages for Shenzhen-based production clusters feeding quick-service restaurant refresh cycles.
Pricing Analysis
Premium pricing for PCI DSS 4.0 pre-certified terminals with sub-90-day delivery windows contrasts with spot-market discounts on legacy mag-stripe inventory facing processor rejection. Three-tier pricing structure across enterprise-integrated, mid-tier ISO-bundled, and economy white-label tiers reflects certification grade and after-sales service bundling. Price differentiation hinges on EMV laboratory certification status and processor integration completeness. Cost compression in economy tiers is intensifying because Android commoditization enables application sideloading that bypasses proprietary software lock-in. Small retailers exhibit highest price sensitivity, accepting elevated per-transaction fees for reduced technical complexity, while supermarket chains prioritize authorization speed and offline continuity over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from national grocery chains, while distributor networks serve fragmented independent merchant procurement. Component concentration centers on Taiwan for secure element chip fabrication, China for NFC antenna module assembly, and South Korea for display panel supply. Raw material dependencies include cryptographic processor chips, EMV-certified card reader mechanisms, and wireless communication modules. Single-source vulnerability in secure element packaging creates procurement bottlenecks extending certification timelines. Distribution runs through acquiring bank partnership programs that bundle hardware with merchant processing agreements, narrowing direct vendor access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The retail POS terminal market sits in a technology-transition phase where cloud-native software-defined checkout experiences are systematically displacing fixed countertop infrastructure with proprietary operating systems.
For Market Incumbents: Hedge against Android commoditization by deepening captive payment processing relationships and accelerating cloud-native terminal management platform deployment. Defensive consolidation through acquiring bank partnership exclusivity protects enterprise-grade deployment pipelines from white-label hardware erosion. Certification investment in EU AI Act biometric compliance creates premium pricing tiers ahead of regulatory clarity.
For New Entrants and Emerging Players: The price-point gap between premium integrated ecosystems and economy white-label hardware creates white-space positioning for mid-tier Android-based architectures with modular certification pathways. India's unorganized retailer digitization push under RBI infrastructure mandates represents the most penetrable geography for first-mover terminal deployment. Go-to-market execution through payment aggregator partnerships bypasses direct processor integration barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in payment processor acquisitions by terminal manufacturers seeking vertical integration. Long-term viability across the analysis window favors platform operators with recurring software subscription revenue over hardware-centric OEMs exposed to margin compression. Acquisition target archetype: cloud-native POS software vendors with established API ecosystems. The signal to watch is merchant processor rejection rates for non-PCI DSS 4.0 terminals as forced-upgrade demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Payment Processor Acquisition | Captures recurring transaction revenue streams and locks in hardware deployment pipelines. |
| Cloud-Native Platform Migration | Enables hardware-as-a-service revenue models with remote security patch deployment. |
| EU AI Act Biometric Certification | Opens premium pricing tiers for terminals with embedded neural processing units. |
| Android Architecture Standardization | Reduces firmware development costs while enabling third-party application marketplaces. |
| India Market Entry Partnership | Positions for RBI-mandated card-present infrastructure expansion among unorganized retailers. |
Methodological Framework
Multi-period observation of terminal refresh cycle velocity, certification backlog duration, and merchant processor rejection rates anchored the trend analysis, supplemented by interviews with payment hardware engineering directors, acquiring bank certification leads, supermarket IT procurement managers, quick-service restaurant franchise operations heads, and fintech platform executives. Secondary validation drew from PCI SSC certification databases, FCC Part 15 equipment authorization filings, SEC 10-K disclosures from listed terminal manufacturers, and customs trade data for secure element chip imports. Bottom-up deployment volume estimates triangulated against top-down payment transaction flow analysis.
Segment-weighting applied differential growth assumptions across mobile, countertop, self-service kiosk, and cloud-based POS product architectures, with technology segments modeled separately for contactless payment, NFC, EMV, and barcode scanning modules. End-user segmentation incorporated small retailer, supermarket, restaurant, and e-commerce platform deployment patterns. CAGRs derived from logistic diffusion curves fitted to historical replacement cycle data and regulatory deadline impacts. Industry-specific forecast inputs included PCI DSS 4.0 compliance penetration curves and RBI infrastructure mandate implementation velocity.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time merchant processor rejection rate reporting introduce uncertainty bands around near-term refresh cycle acceleration estimates. Forecasts reflect documented assumptions regarding certification laboratory capacity and secure element chip foundry allocation. Periodic stress-testing of base assumptions is recommended given semiconductor supply concentration and evolving encryption standard timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Retail Cash Management Market
Payments
Middle East and Africa Prepaid Card Market
Payments
Hong Kong Payments Market
Payments
South Korea Payments Market
Payments
Global Accounts Payable Software Market
Payments
Mobile Money Market
Payments
Japan Payments Market
Payments
Remote Deposit Capture Market
Payments
Global Master Card Market
Payments
Philippines Remittance Market
Payments
Payment Security Software Market
Payments
Retail Point of Sale (POS) Market
Payments
Africa Mobile Money Market
Payments
US Gift Card and Incentive Card Market
Payments
Vietnam Mobile Payments Market
Payments
South Korea Mobile Payment Market