
 Currency Exchange Bureau Software Market | 2026-2036
Currency Exchange Bureau Software Market Size, Share, and Industry Trends Forecast 2026-2036
Currency Exchange Bureau Software Market Outlook
The capital-intensity divergence between cloud-native entrants and legacy on-premises vendors is reorganizing competitive dynamics in currency exchange software. Calyx Solutions leverages its API-first architecture to serve mid-market retail bureaus seeking rapid deployment. OANDA anchors its position through deep liquidity integration and institutional-grade risk management tools. Broadway Technology competes in the high-frequency segment with low-latency pricing engines tailored to tier-one financial institutions.
Currency exchange bureau software encompasses applications that automate rate quotation, transaction processing, regulatory reporting, and vault reconciliation for physical and digital currency exchange operations. Core systems integrate real-time feed handlers, multi-currency ledgers, and audit trails that satisfy anti-money laundering protocols. Cloud-based deployment models are capturing the fastest expansion as bureau operators abandon server maintenance overhead for elastic infrastructure. API integration segments command premium pricing by enabling embedded foreign-exchange services within banking and travel platforms. On-premises solutions retain share among operators in jurisdictions with strict data sovereignty requirements.
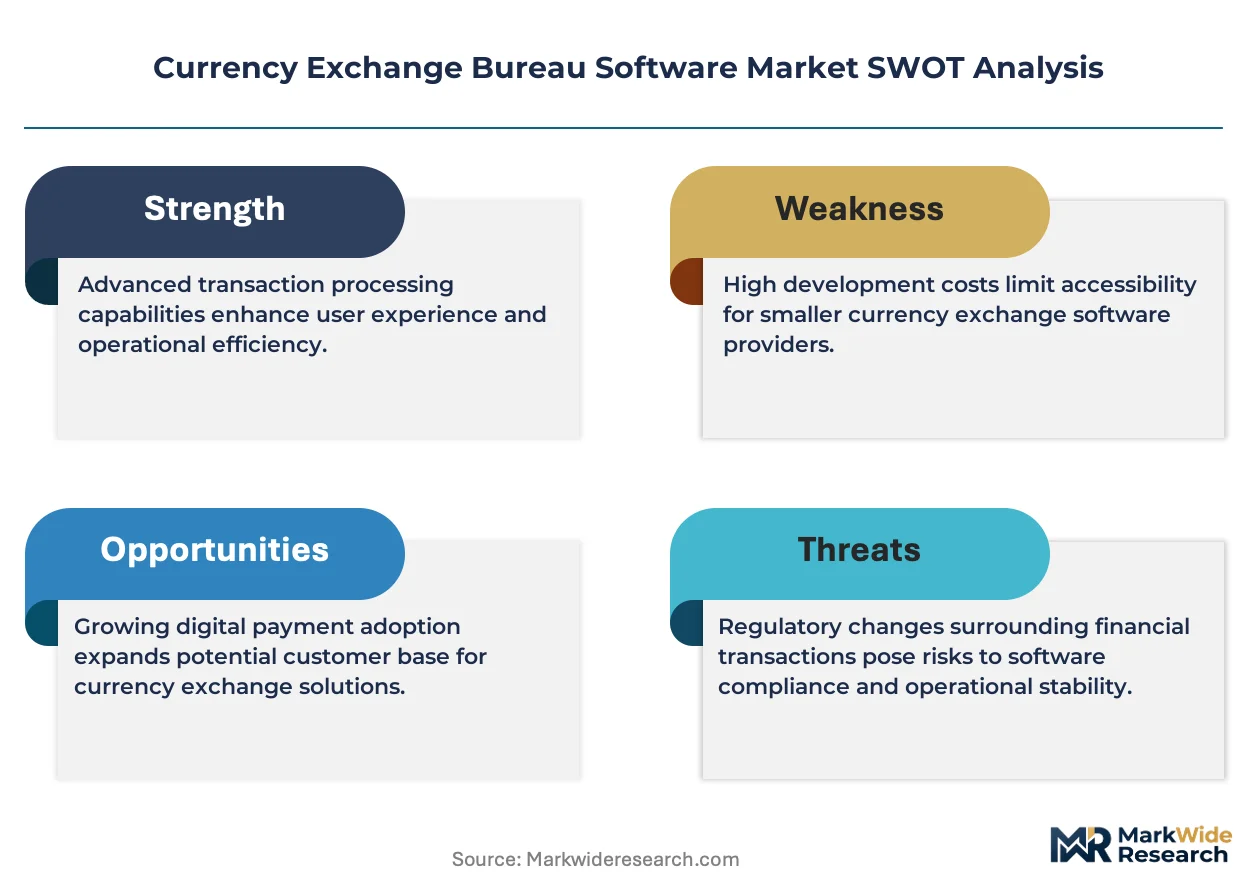
The Financial Conduct Authority in the United Kingdom, FinCEN in the United States, and the UAE's central bank each enforce know-your-customer and transaction-monitoring mandates that directly shape software procurement specifications. Compliance management modules have become non-negotiable components as penalties for inadequate surveillance escalate across jurisdictions. Stakeholders must evaluate whether their current platforms can absorb forthcoming real-time reporting obligations without wholesale replacement.
Market Dynamics
Cloud migration is compressing deployment cycles for retail bureaus while real-time API connectivity reconfigures how liquidity providers integrate with front-office systems. The shift from on-premises infrastructure to elastic cloud environments represents the dominant structural force reshaping procurement patterns and vendor selection criteria across the industry.
Growth Catalysts
- FinCEN Transaction Monitoring Mandates:US retail bureaus must upgrade surveillance capabilities to satisfy real-time reporting obligations, forcing systematic platform replacements.
- Embedded Finance APIs:Travel platforms and neobanks in the United Arab Emirates are white-labeling currency exchange modules, expanding addressable endpoints for software vendors.
- Multi-currency Ledger Automation:Vault reconciliation engines reduce manual settlement errors by integrating real-time feed handlers with position-keeping systems.
Market Restraints
- Data Sovereignty Requirements:Operators in the United Kingdom face constraints from Financial Conduct Authority localization rules that delay cloud adoption.
- Legacy System Interoperability Costs:On-premises core banking integrations require expensive middleware development, inflating total cost of ownership for mid-market bureaus.
- Specialized Compliance Talent Scarcity:Shortages of AML surveillance engineers in the United Arab Emirates extend implementation timelines for automated monitoring modules.
Strategic Opportunities
- Underpenetrated Tier-Two UK Cities:Regional retail bureaus in Manchester and Birmingham lack sophisticated rate-quotation engines, creating whitespace for cloud-native entrants.
- Open Banking Convergence:PSD2-mandated account aggregation in the United Kingdom enables embedded FX execution within personal finance applications.
- Real-Time Risk Dashboards:Institutional-grade position monitoring tools developed for tier-one banks can be downmarketed to high-volume retail operators.
Industry Challenges
- Cross-Border Certification Complexity:Vendors must simultaneously satisfy FinCEN, FCA, and UAE central bank audit trail specifications, fragmenting engineering resources.
- API Security Architecture Gaps:Mid-market bureaus lack in-house cybersecurity expertise to harden real-time connectivity endpoints against credential-stuffing attacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Currency Exchange Bureau Software Market |
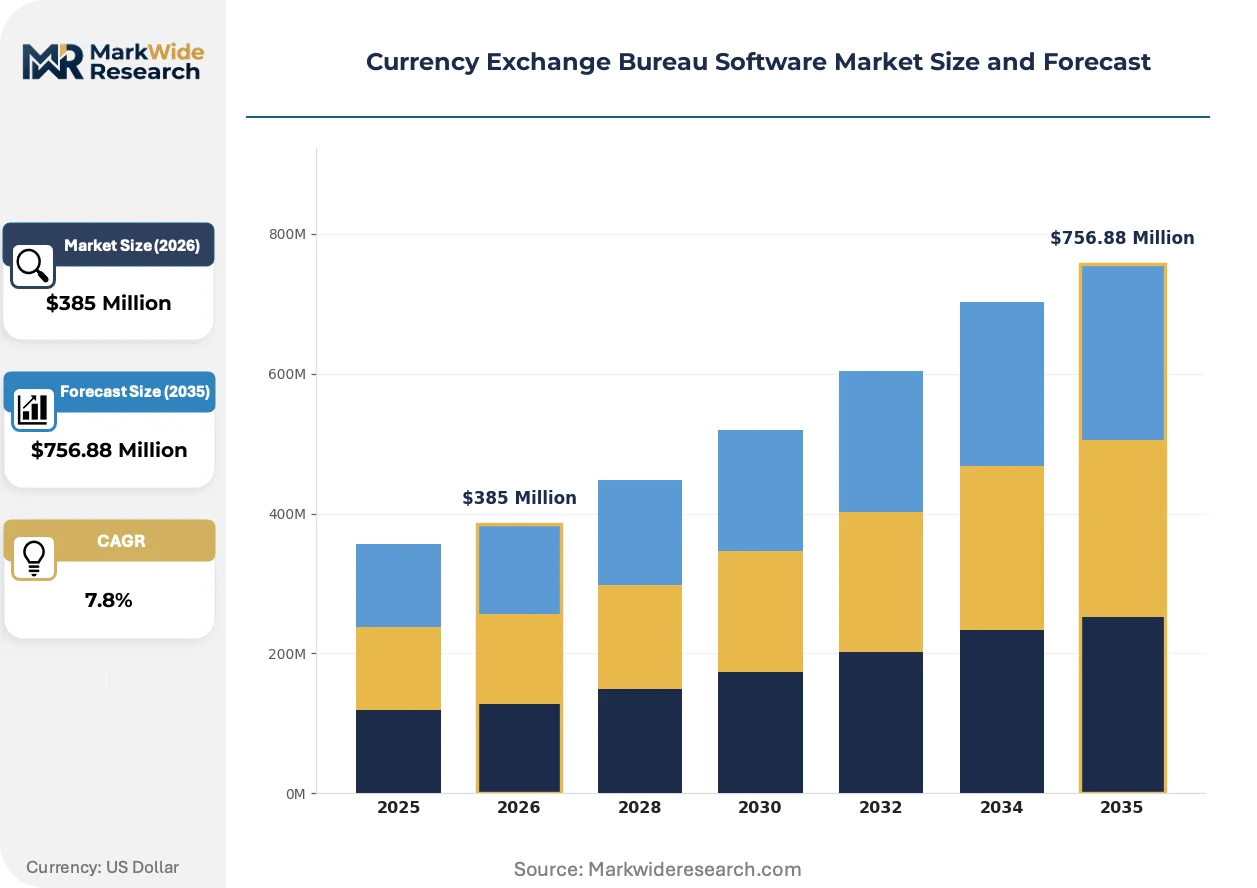
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $756.88 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Web-based, Mobile Application, Desktop Application, API Integration Deployment Model: Cloud-based, On-premises, Hybrid Model, Managed Services End User: Retail Bureau, Online Exchange, Financial Institution, Travel Agency Service Type: Payment Processing, Currency Conversion, Reporting Tools, Compliance Management |
| Companies Covered | Calyx Solutions, OANDA, Cymonz, Broadway Technology, Clear View Systems, Digital Currency Systems, Merkeleon, CurrencyXchanger, eBEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Currency Exchange Bureau Software Market Strategic Shifts
Software architecture decisions are polarizing the vendor landscape as API-first platforms capture growth from monolithic legacy systems. The pace of innovation concentrates on compliance automation, latency reduction, and embedded distribution models.
Microservices-based rate engines are fragmenting the traditional core-systems market. These modular architectures allow retail bureaus to swap individual components—quotation, settlement, reporting—without wholesale replacement. Mid-market operators in the United States are adopting containerized deployments twelve to eighteen months faster than historical upgrade cycles. The disaggregation is compressing pricing power for integrated suite vendors while enabling point-solution specialists to capture discrete workflow segments.
The EU AI Act's risk-classification framework is reshaping algorithmic surveillance procurement. Automated transaction-monitoring systems must now document decision logic for high-risk customer profiles, forcing vendors to retrofit explainability layers. Retail bureaus serving correspondent banking relationships face the steepest compliance burdens, with UK-based operators accelerating procurement of auditable machine-learning models ahead of enforcement deadlines.
Subscription pricing for compliance modules is displacing perpetual-license structures in bureau procurement. Tier-two operators in the United Arab Emirates favor usage-based AML surveillance fees tied to transaction volumes rather than upfront capital expenditure. This shift compresses vendor cash conversion cycles while lowering barriers to entry for cloud-native competitors without legacy maintenance revenue dependencies.
Currency Exchange Bureau Software Market Segmentation
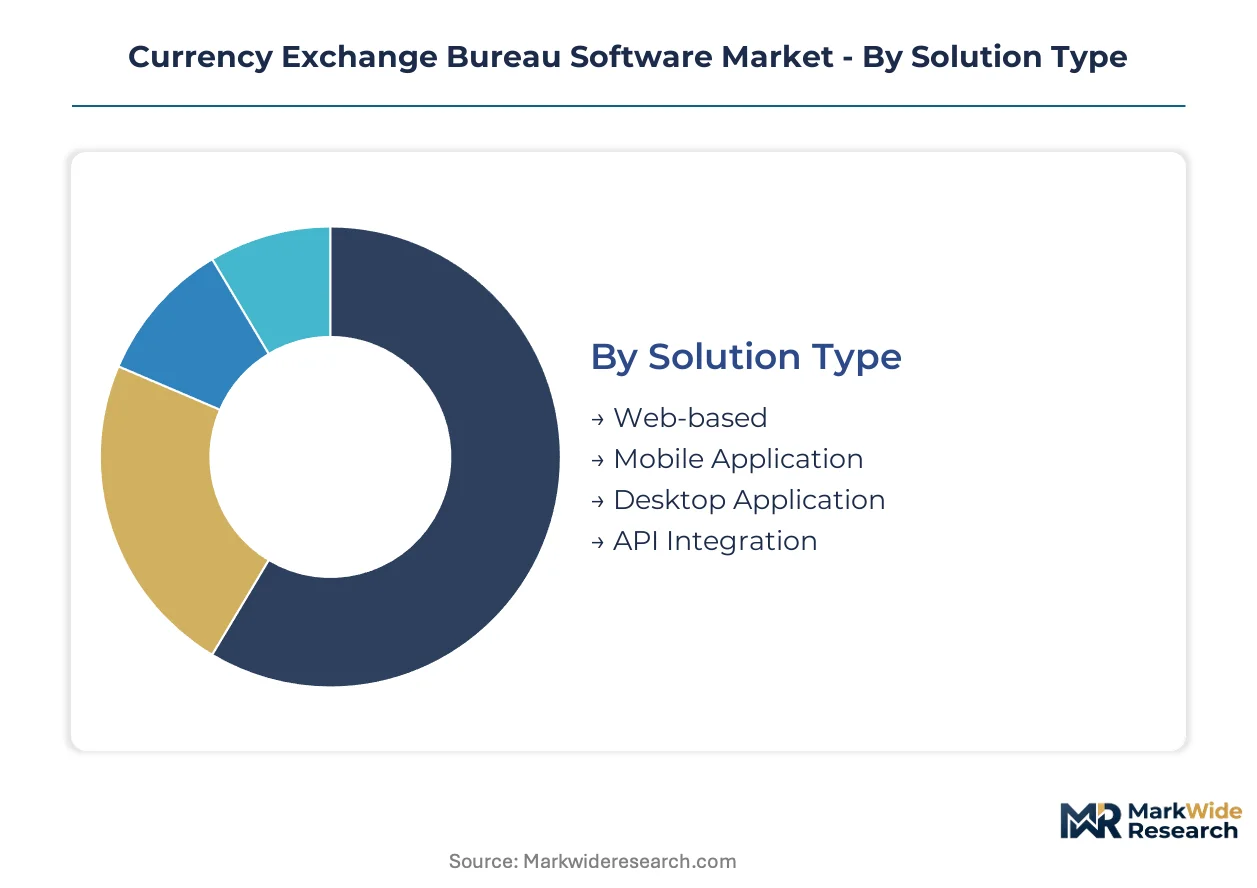
Segmentation in currency exchange bureau software reveals how procurement priorities diverge across operational scales and regulatory exposure. Bureau operators select solution architectures based on transaction velocity, compliance burden, and integration complexity rather than feature checklists alone.
Solution Type:
Margin pools concentrate in API Integration and Mobile Application segments where recurring connectivity fees and white-label licensing generate predictable revenue streams.
- API Integration:Embedded foreign-exchange modules connect retail bureaus to banking platforms and travel booking engines through standardized endpoints. Travel platforms in the United Arab Emirates and neobanks in the United Kingdom are white-labeling these capabilities, expanding addressable endpoints for vendors without direct customer acquisition costs.
- Mobile Application:Native iOS and Android clients enable customer self-service for rate quotation and transaction initiation, reducing teller labor costs. Retail bureaus in high-footfall urban locations across the United States deploy these to capture walk-in traffic that would otherwise queue at physical counters.
- Web-based:Browser-accessible platforms serve smaller operators with limited IT infrastructure, offering lower total cost of ownership through subscription pricing.
- Desktop Application:Thick-client installations persist in jurisdictions with intermittent connectivity or strict offline transaction logging requirements.
The dominant share belongs to Web-based solutions among legacy operators, while API Integration is closing the gap fastest as embedded finance partnerships proliferate.
Deployment Model:
Cloud-based deployments command premium pricing elasticity compared to fixed-cost on-premises alternatives, reshaping how vendors structure recurring revenue.
- Cloud-based:Elastic infrastructure eliminates server maintenance overhead and enables automatic compliance updates without operator intervention. Mid-market retail bureaus in the United States are adopting these deployments twelve to eighteen months faster than historical upgrade cycles, compressing procurement timelines.
- On-premises:Local server installations satisfy data sovereignty mandates from the Financial Conduct Authority in the United Kingdom and similar regulators, preserving share among risk-averse operators despite higher capital expenditure.
- Hybrid Model:Split architectures keep sensitive transaction data local while pushing customer-facing interfaces to cloud edge nodes, balancing compliance and scalability.
- Managed Services:Outsourced infrastructure operations appeal to family-owned bureaus lacking dedicated IT staff, transferring operational risk to vendor specialists.
Cloud-based deployments hold the revenue concentration, though Hybrid Model adoption is expanding most quickly as operators seek jurisdictional flexibility.
End User:
Application intensity varies sharply by customer type, with Financial Institutions demanding institutional-grade risk tools that Retail Bureaus rarely require.
- Retail Bureau:Physical exchange operators need integrated point-of-sale terminals, vault reconciliation engines, and teller workflow management. These operators in tier-two United Kingdom cities like Manchester and Birmingham currently lack sophisticated rate-quotation engines, creating whitespace for cloud-native entrants.
- Financial Institution:Banks and credit unions require deep liquidity integration, real-time position monitoring, and correspondent banking compliance modules that satisfy multiple regulatory regimes simultaneously.
- Online Exchange:Digital-native platforms prioritize automated KYC verification and algorithmic rate optimization over physical cash handling capabilities.
- Travel Agency:Tour operators and booking platforms embed currency modules as ancillary revenue streams, favoring simple API integrations over full-featured trading systems.
Retail Bureau deployments constitute the volume base, yet Financial Institution contracts are climbing the fastest as banks consolidate treasury operations onto unified platforms.
Service Type:
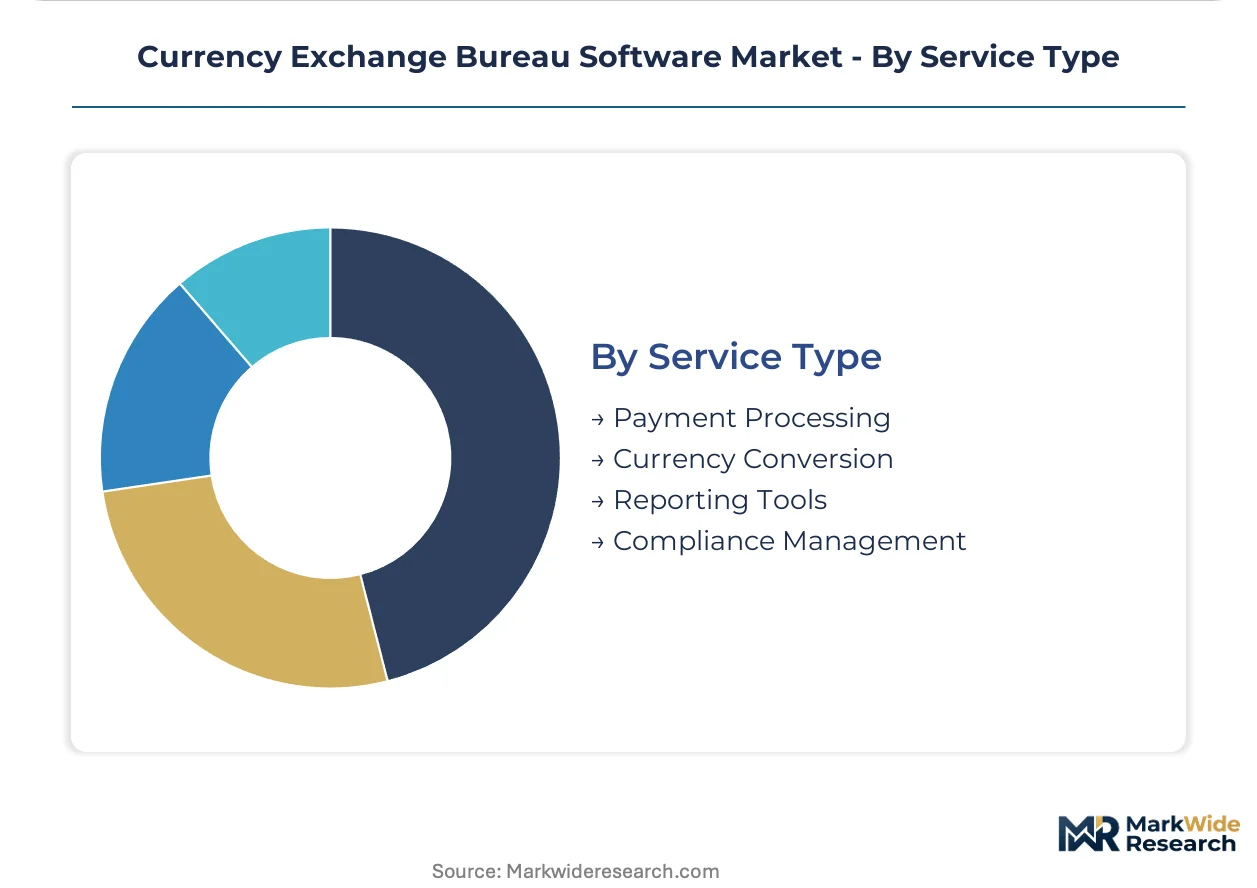
Compliance Management modules have become non-negotiable components as penalties for inadequate surveillance escalate across United States, United Kingdom, and United Arab Emirates jurisdictions.
- Compliance Management:Automated AML surveillance, know-your-customer verification, and audit trail generation satisfy FinCEN, FCA, and UAE central bank mandates. Subscription pricing for these modules is displacing perpetual-license structures, with tier-two operators favoring usage-based fees tied to transaction volumes.
- Payment Processing:Real-time settlement engines integrate with SWIFT, SEPA, and regional clearing systems to execute cross-border transfers with position-keeping accuracy.
- Currency Conversion:Rate quotation engines aggregate liquidity from multiple providers to offer competitive spreads while maintaining margin protection through automated hedging.
- Reporting Tools:Regulatory filing automation and management dashboards reduce manual preparation time for periodic examinations and internal audits.
Currency Conversion generates the highest transaction volume, but Compliance Management is gaining share fastest as real-time reporting obligations force systematic platform replacements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The export-import intensity of the United States, United Kingdom, and United Arab Emirates generates disproportionate software procurement volumes as cross-border transaction velocity mandates real-time rate engines and automated compliance infrastructure.
United States
Remittance corridors connecting the United States to Latin America and Asia drive demand for multi-currency ledger automation. FinCEN transaction monitoring mandates force systematic platform replacements among retail bureaus. High-volume operators in Miami and New York City deploy cloud-native compliance modules to satisfy real-time reporting obligations.
United Kingdom
Correspondent banking relationships and fintech density concentrate procurement budgets in London. Financial Conduct Authority data localization rules delay cloud adoption among risk-averse operators. Regional retail bureaus in Manchester and Birmingham currently lack sophisticated rate-quotation engines, creating whitespace for cloud-native entrants.
United Arab Emirates
Tourism flows and gold trade generate exceptional currency transaction velocity across Dubai and Abu Dhabi. The UAE central bank enforces know-your-customer mandates that shape software specifications. Travel platforms and neobanks white-label embedded FX modules, expanding addressable endpoints for API-first vendors.
Germany
Industrial export dominance and SME internationalization sustain demand for institutional-grade risk management tools. BaFin surveillance requirements mandate auditable transaction trails for cross-border payments. Frankfurt-based financial institutions consolidate treasury operations onto unified platforms with deep liquidity integration.
Singapore
Wealth management inflows and regional headquarters concentration drive premium software procurement. Monetary Authority of Singapore digital payment infrastructure standards accelerate API connectivity adoption. Marina Bay financial district operators prioritize low-latency pricing engines for high-frequency treasury execution.
Currency Exchange Bureau Software Market Competitive Environment
Concentration sits with API-first cloud-native specialists and institutional-grade liquidity integrators. The vendor base organizes around three strategic archetypes: modular microservices providers serving mid-market retail bureaus, low-latency engine developers targeting tier-one financial institutions, and embedded finance enablers white-labeling through travel and banking platforms. Dominant competitive moves include geographic expansion into underpenetrated tier-two cities and strategic partnerships with neobanks seeking turnkey FX capabilities.
Within the API-first tier, Calyx Solutions and Cymonz exemplify modular architecture approaches that compress deployment cycles for mid-market operators. OANDA anchors the institutional-grade segment through deep liquidity integration capabilities. Broadway Technology occupies a position in the high-frequency vector with pricing engine specialization. These three represent the competitive poles around which procurement decisions cluster: rapid cloud deployment, institutional risk infrastructure, and latency-optimized execution.
| Leading Market Players |
|---|
| Calyx Solutions |
| OANDA |
| Cymonz |
| Broadway Technology |
| Clear View Systems |
| Digital Currency Systems |
| Merkeleon |
| CurrencyXchanger |
| eBEX |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at cloud infrastructure hyperscalers in the United States, United Kingdom, and United Arab Emirates shapes both vendor cost structures and end-user price floors for currency exchange bureau software. Elastic compute provisioning allows API-first vendors to compress marginal delivery costs below legacy on-premises maintenance thresholds, redistributing pricing power toward modular solution providers.
Pricing Analysis
Mid-market retail bureau buyers anchor subscription-tier pricing structures across the deployment spectrum. Pricing stratifies across premium compliance-integrated, standard API-connected, and economy web-based tiers, with differentiation driven by FinCEN audit trail certification depth and real-time feed handler latency specifications. Cost compression in the standard tier is intensifying because containerized microservices reduce vendor engineering overhead. Tier-two operators in Manchester and Birmingham exhibit highest price sensitivity, while correspondent banking relationships in London tolerate premium positioning for multi-jurisdiction surveillance modules.
Supply Chain Analysis
Frankfurt-London-Dubai data center corridors concentrate cloud infrastructure supply for financial services software delivery. Engineering talent pipelines draw from India, Poland, and the United Kingdom, while compliance module development rests on regulatory technology partnerships in Singapore and Switzerland. Single-source vulnerability sits with SWIFT messaging infrastructure dependencies for cross-border settlement integration. Distribution runs through direct vendor sales teams for institutional contracts and channel partners for mid-market retail bureau penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Currency exchange bureau software demand tracks remittance corridor cyclicality, with FinCEN mandate enforcement driving replacement waves that compress procurement timelines below historical eighteen-month cycles.
For Market Incumbents: Compound defensive positioning through backward integration into compliance data providers and captive development of explainable AI surveillance layers. Cloud-native entrants with API-first architectures threaten legacy installed base stickiness. Certification investment in UAE central bank and FCA audit trail specifications preserves pricing power in correspondent banking segments.
For New Entrants and Emerging Players: Lead with white-label embedded finance modules targeting travel platforms in Dubai and neobank partnerships in London, where procurement cycles run six months shorter than direct retail bureau sales. Regional retail bureaus in Birmingham and Manchester lack sophisticated rate-quotation engines, creating addressable whitespace for containerized deployment specialists.
For Investors and Strategic Acquirers: Modular microservices specialists with proven FinCEN compliance retrofit capabilities offer the strongest acquisition target profile for platform consolidation plays. Long-term viability hinges on regulatory technology moats rather than feature breadth alone. The signal to monitor is real-time reporting mandate expansion beyond current FinCEN, FCA, and UAE central bank jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Retrofit | Explainable AI layers satisfy EU AI Act documentation requirements for high-risk customer surveillance. |
| API-First Architecture Migration | Microservices deployment compresses upgrade cycles for tier-two retail bureaus in underpenetrated UK cities. |
| Embedded Finance Partnership | White-label integration with UAE travel platforms expands addressable endpoints without customer acquisition costs. |
| Hybrid Deployment Certification | Split cloud-local architectures balance FCA data sovereignty rules against scalability requirements. |
| Real-Time Risk Dashboard Downmarket | Institutional-grade position monitoring tools capture high-volume retail operators seeking treasury-grade visibility. |
Study Parameters
Operator-level perspectives from retail bureau owners, compliance officers at correspondent banks, API integration specialists, and cloud infrastructure procurement managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FinCEN guidance documents, FCA consultation papers, UAE central bank circulars, and SEC filings from publicly traded financial software vendors. Bottom-up deployment volume estimates triangulated against top-down addressable market calculations across the analysis window.
Sensitivity analysis tested forecast robustness across regulatory enforcement intensity scenarios and cloud adoption pace variations. Segmentation modeling incorporated deployment model, end-user operational scale, integration complexity tier, and regional regulatory cluster dimensions throughout the projection horizon. CAGRs derived from fitted growth curves applied to disclosed vendor revenue ranges and bureau operator technology spend surveys, with cross-border transaction velocity and compliance mandate expansion serving as primary demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained FinCEN real-time reporting enforcement or accelerated EU AI Act implementation timelines would require recalibration. Forecasts reflect documented assumptions regarding regulatory technology adoption curves and hyperscaler infrastructure pricing trajectories. Practitioners should keep alternative scenarios live as cross-border certification complexity and API security architecture gaps evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Mobile Notary Service Market
Financial Services
Global P2P Fundraising Tool Market
Financial Services
Global Management Consulting Services Market
Financial Services
E-Invoicing Market
Financial Services
China Supply Chain Financing Market
Financial Services
Direct Selling Market
Financial Services
Latin America Factoring Services Market
Financial Services
Europe Financial Advisory Services Market
Financial Services
Online Lottery Market
Financial Services
Virtual Account Management Software Market
Financial Services
Africa Factoring Services Market
Financial Services
Online Sports Betting Market
Financial Services
Global Financial Consulting Software Market
Financial Services
Digital Account Opening Market
Financial Services
LAMEA Financial Services Software Market
Financial Services
Back-Office Outsourcing in Financial Services Market