
 France Buy Now Pay Later Services Market | 2026-2036
France Buy Now Pay Later Services Market Size, Share, and Industry Trends Forecast 2026-2036
France Buy Now Pay Later Services Market Foresight
Younger buyers is reorganizing demand composition across France's BNPL landscape. Klarna leverages its app-based discovery engine to capture repeat purchases among digitally native consumers. Cofidis anchors its position through embedded partnerships with established retail networks, sustaining merchant loyalty via white-label infrastructure.
Buy Now Pay Later services constitute short-term consumer credit products that split purchase amounts into equal installments, typically operating through automated repayment schedules linked to debit cards or bank accounts. Their primary commercial purpose centers on reducing checkout friction and lifting conversion rates for merchants while extending purchasing power to consumers without traditional revolving credit. Installment plans dominate transaction volumes due to their predictable structure and lower default exposure, while split payment solutions attract fashion retailers seeking to minimize basket abandonment. Mobile apps command the fastest-growing distribution channel as in-app checkout streamlines authentication through biometric verification.
France's national financial regulator, the Autorité de Contrôle Prudentiel et de Résolution, supervises BNPL providers under evolving EU consumer protection frameworks, including strengthened affordability assessments mandated by revised Consumer Credit Directive implementation. The Commission Nationale de l'Informatique et des Libertés enforces data handling standards for biometric identity verification and transaction profiling used in real-time credit decisions. Stakeholders must monitor how forthcoming French transposition of EU-wide open finance regulations reshapes account-linking protocols and merchant onboarding requirements.
Market Dynamics
France's BNPL sector is compressing under regulatory density as the EU Consumer Credit Directive revision forces real-time affordability checks and disclosure standardization across all deferred payment providers operating in the market.
Growth Catalysts
- Île-de-France E-commerce Density:Paris and surrounding departments concentrate France's highest online retail penetration, creating natural testbed environments for checkout-embedded installment products.
- EU Consumer Credit Directive Revision:Harmonized disclosure requirements reduce compliance fragmentation across French-EU cross-border transactions, lowering operational friction for providers scaling nationally.
- Biometric Authentication Adoption:Fingerprint and facial recognition integration into mobile banking apps streamlines identity verification, cutting onboarding abandonment for first-time BNPL users.
Market Restraints
- CNIL Data Handling Scrutiny:France's data protection authority enforces strict limits on transaction profiling and biometric storage, constraining real-time credit scoring sophistication.
- Traditional Revolving Credit Substitution:Established bank card deferred payment options compete directly with independent BNPL providers for consumer wallet share.
- Affordability Assessment Infrastructure Costs:Mandated real-time income verification requires API integrations with French banking networks, elevating fixed costs for market entrants.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur Merchant Expansion:Tourism-dependent retail corridors in Nice and Marseille remain underpenetrated by installment checkout solutions relative to Paris basin saturation.
- Open Finance Regulatory Tailwind:Forthcoming French transposition of EU-wide account-linking protocols will standardize bank connection APIs, reducing technical barriers to automated repayment scheduling.
- White-Label Infrastructure Convergence:Embedded finance APIs merging with legacy retail ERP systems enable non-fintech merchants to launch branded installment programs without proprietary development.
Industry Challenges
- Credit Risk Modeling Talent Scarcity:Shortage of data scientists experienced in French regulatory constraints limits provider capacity to optimize default prediction under ACPR supervision.
- Legacy Bank Integration Complexity:Core banking system architectures at established French financial institutions resist real-time API connectivity required for instant installment approval workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Buy Now Pay Later Services Market |
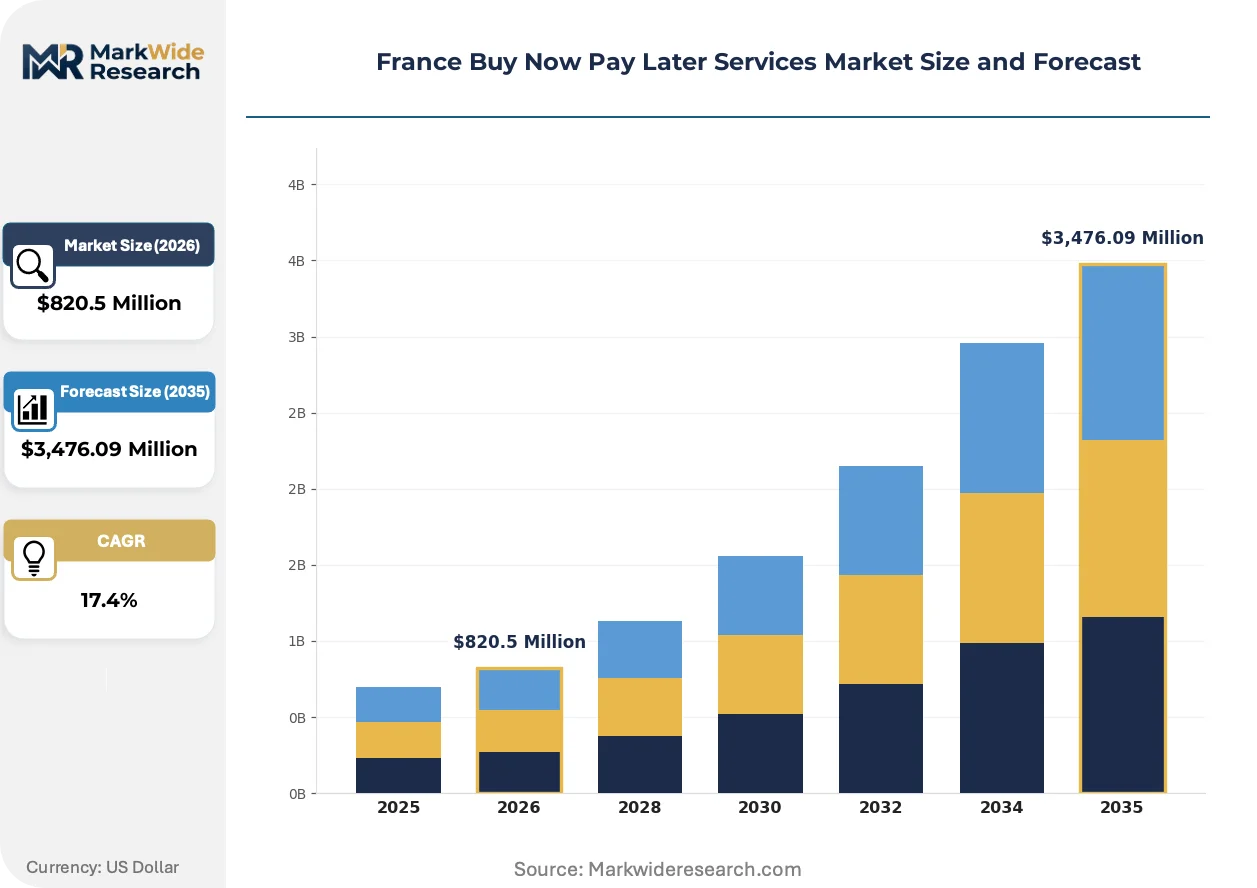
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $3,476.09 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Installment Plans, Deferred Payment, Revolving Credit, Split Payment, Cash on Delivery End User: Online Shoppers, Small Merchants, Fashion Retailers, Electronics Customers, Travel Bookers Distribution Channel: Mobile Apps, E-commerce Platforms, Physical Stores, Payment Gateways, Social Commerce Customer Type: Millennials, Gen Z, Working Professionals, Freelancers, Retirees |
| Companies Covered | FLOA, Cetelem, Alma, Scalapay, PayPal, Klarna, Cofidis, BNP Paribas Personal Finance, Oney, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Buy Now Pay Later Services Market Shifts & Advancements
Checkout technology is fragmenting across authentication modalities as French consumers and merchants negotiate friction-reduction against security demands. Three distinct vectors are reshaping competitive positioning.
Biometric identity verification is bifurcating the authentication layer between high-trust facial recognition for repeat users and document-heavy manual review for first-time applicants. Fashion and electronics retailers with high customer lifetime value are prioritizing seamless return-visitor experiences. This split is compressing onboarding time differentials between established providers and new entrants.
France's national financial regulator, the Autorité de Contrôle Prudentiel et de Résolution, is tightening supervision frameworks to align with EU-wide consumer protection harmonization. Revised affordability assessment mandates now require documented income verification before credit extension. Small-ticket BNPL providers serving sub-200 euro transactions face disproportionate compliance cost pressure relative to average transaction value.
Merchant procurement of checkout solutions is rotating from standalone BNPL contracts toward bundled payment service provider arrangements. Retailers in Occitanie and Auvergne-Rhône-Alpes are consolidating vendor relationships to reduce technical integration overhead. This concentration favors infrastructure-heavy platforms with existing banking partnerships over pure-play installment specialists.
France Buy Now Pay Later Services Market Segmentation
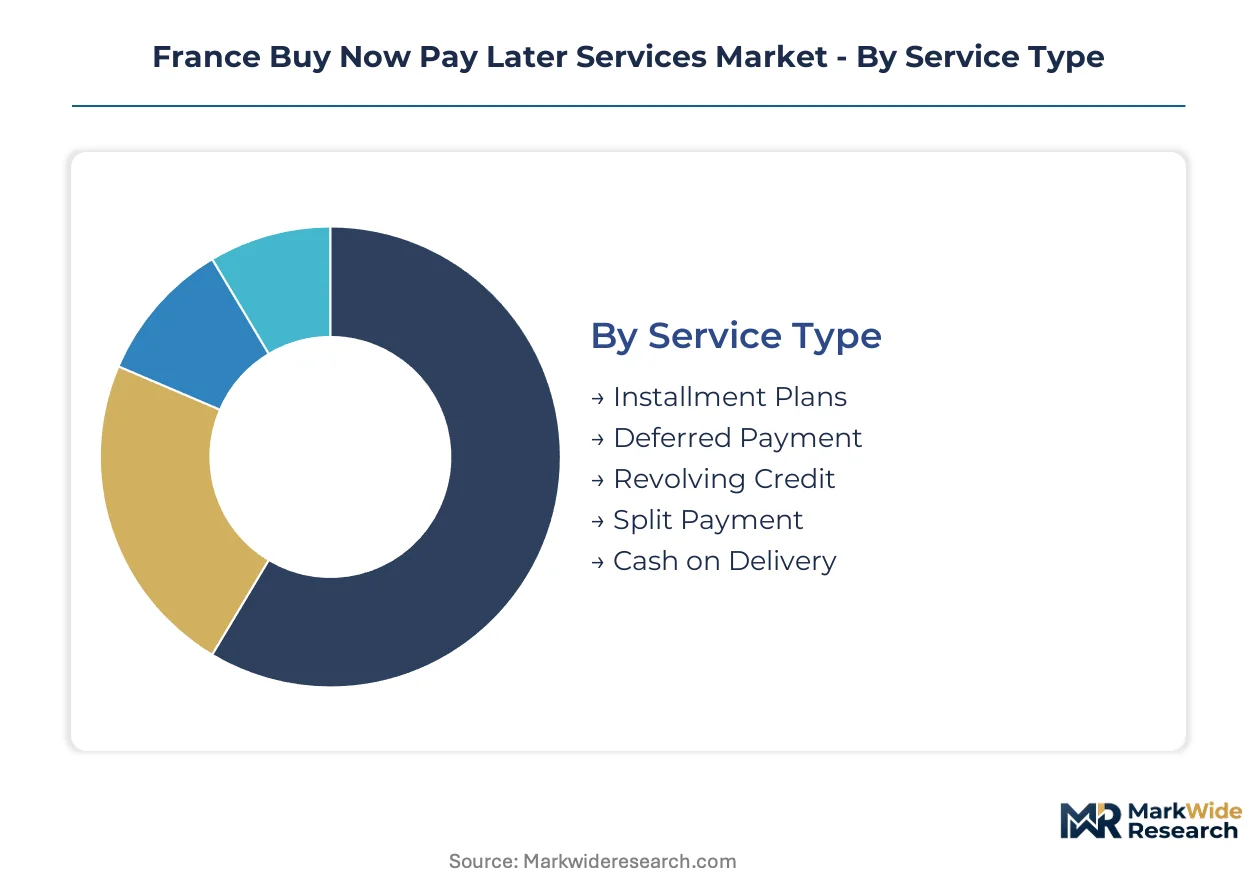
Segmentation in France's BNPL market reveals how regulatory pressure and demographic shifts are fragmenting demand across service models and customer profiles. Understanding these divisions exposes where compliance costs concentrate and which channels are capturing digitally native purchasing behavior.
Service Type:
Domestic demand concentrates on installment structures suited to ACPR affordability mandates, while export-oriented French fintechs push split-payment APIs into cross-border e-commerce.
- Installment Plans:Fixed-schedule repayment products divide purchase amounts into equal portions over 3-12 months. Paris and Île-de-France fashion retailers deploy these to reduce basket abandonment, though ACPR-mandated income verification adds friction to sub-200 euro transactions.
- Deferred Payment:Single-postponement products allow 14-30 day settlement without interest accrual. Electronics customers in Lyon and Marseille favor this for high-ticket purchases, but CNIL data-handling limits constrain real-time eligibility scoring.
- Revolving Credit:Traditional bank-issued deferred payment options compete directly with independent BNPL providers.
- Split Payment:Two-installment structures at checkout minimize merchant technical integration.
- Cash on Delivery:Remaining holdout in rural Auvergne-Rhône-Alpes retail corridors with limited digital banking penetration.
Installment plans command the established base. The steepest expansion runs through split payment solutions.
End User:
Volume tiers separate high-frequency low-value online shoppers from merchant-facing infrastructure clients carrying platform economics.
- Online Shoppers:Individual consumers completing e-commerce transactions through embedded checkout options. Millennials and Gen Z in Paris basin drive repeat purchase frequency, though biometric authentication adoption varies by banking app integration.
- Small Merchants:Independent retailers procuring white-label installment infrastructure. Provence-Alpes-Côte d'Azur tourism vendors represent underpenetrated demand relative to saturation in northern France.
- Fashion Retailers:Apparel merchants prioritizing seamless return-visitor experiences.
- Electronics Customers:High-ticket purchasers requiring extended repayment horizons.
- Travel Bookers:Seasonal demand concentrated in Q2-Q3 booking windows.
Online shoppers anchor transaction volume. Small merchants are climbing the fastest as embedded finance APIs reduce technical barriers.
Distribution Channel:
Channel maturity splits between established e-commerce platform integrations and emerging social commerce formats requiring new authentication protocols.
- Mobile Apps:Native application interfaces with biometric identity verification. Fingerprint and facial recognition streamline onboarding for repeat users, though first-time applicants face document-heavy manual review under CNIL guidelines.
- E-commerce Platforms:Marketplace-embedded checkout solutions at major French retail sites.
- Physical Stores:Point-of-sale terminal integrations in Île-de-France department stores.
- Payment Gateways:Aggregator-layer infrastructure serving multi-merchant networks.
- Social Commerce:Checkout-embedded options within content platforms gaining traction among Gen Z purchasers.
E-commerce platforms retain the established base. Mobile apps are expanding most quickly as in-app biometric verification cuts abandonment.
Customer Type:
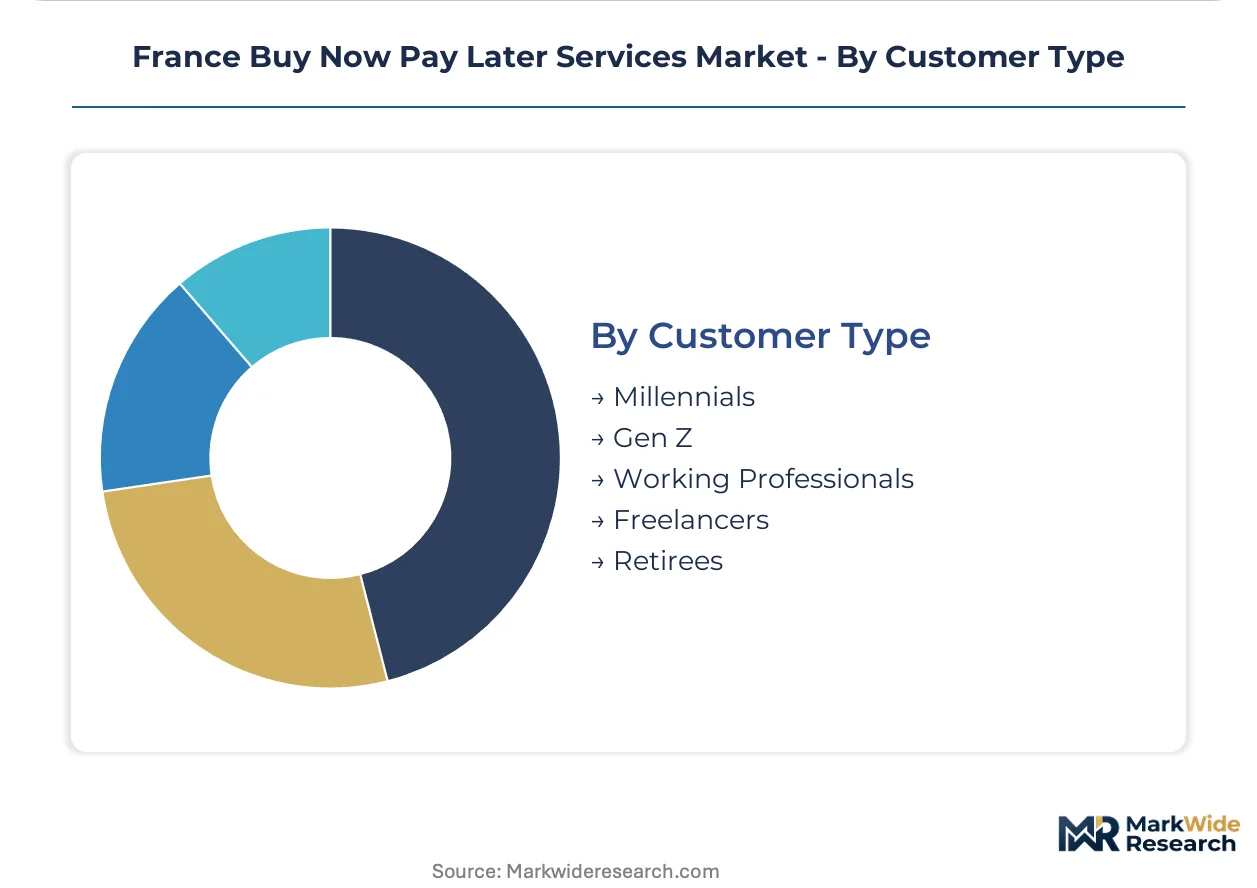
Generational divides structure adoption patterns, with younger demographics driving mobile-first engagement and older segments requiring education on automated repayment mechanics.
- Millennials:Consumers aged 28-43 with established credit histories and stable income documentation. Working professionals in Paris concentrate demand for travel and electronics financing, though affordability assessment mandates now require explicit income verification.
- Gen Z:Digital-native consumers aged 18-27 entering credit markets. Fashion and social commerce purchases dominate transaction profiles, with biometric authentication preferences compressing onboarding differentials between providers.
- Working Professionals:Salaried employees with documented income streams.
- Freelancers:Independent workers facing income verification complexity under revised Consumer Credit Directive implementation.
- Retirees:Limited adoption segment requiring simplified disclosure standards.
Millennials command the established base. Gen Z is gaining share fastest as app-based discovery engines capture repeat purchase behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provider infrastructure clusters heavily around Paris and the Île-de-France region, where merchant density and fintech integration create self-reinforcing network effects. The regulatory framework from the Autorité de Contrôle Prudentiel et de Résolution shapes operational requirements across all French sub-regions.
Île-de-France
E-commerce penetration peaks in Paris and surrounding departments, driving merchant demand for embedded checkout solutions. The ACPR's affordability assessment mandates apply most stringently here due to transaction volume concentration. La Défense and Station F host the densest fintech provider clusters.
Auvergne-Rhône-Alpes
Lyon anchors electronics and high-ticket retail demand for deferred payment products. CNIL data-handling standards constrain biometric authentication rollout for first-time users. The Grenoble-Annecy corridor shows emerging merchant adoption among outdoor equipment retailers.
Provence-Alpes-Côte d'Azur
Tourism-dependent retail in Nice and Marseille remains underpenetrated relative to northern saturation. Seasonal booking patterns create unique credit risk profiles for travel-focused BNPL deployment. The Aix-en-Provence tech corridor attracts secondary provider offices seeking lower operational costs.
Hauts-de-France
Lille's cross-border e-commerce activity generates demand for harmonized EU disclosure compliance. Traditional bank-issued deferred payment options retain stronger wallet share among older demographics. The Lille metropolitan area tests white-label infrastructure for mid-market retail chains.
Occitanie
Toulouse and Montpellier merchants are consolidating vendor relationships toward bundled payment service providers. Open finance regulatory preparation is accelerating API integration with regional banking networks. The corridor shows fastest growth in small merchant embedded finance adoption.
France Buy Now Pay Later Services Market Competitive Landscape
Concentration sits with established financial services conglomerates and specialized fintech platforms. The market exhibits tiered structure with bank-affiliated providers commanding merchant trust and independent specialists driving mobile-first innovation. Two strategic archetypes dominate: white-label infrastructure providers embedding through retail ERP systems, and app-based discovery platforms capturing repeat consumer engagement. Competitive moves center on strategic partnerships with merchant networks and portfolio diversification into adjacent credit products.
Among France-based financial services providers, FLOA, Cetelem, and Cofidis exemplify the bank-affiliated archetype leveraging established regulatory relationships and merchant loyalty through white-label deployment. These entities occupy positions where compliance infrastructure and legacy banking integrations create defensive moats against pure-play entrants. Klarna and Alma represent the mobile-native specialist tier, anchoring consumer-facing discovery and streamlined onboarding experiences. The competitive tension between these archetypes is reshaping merchant procurement patterns across French retail corridors.
| Leading Market Players |
|---|
| FLOA |
| Cetelem |
| Alma |
| Scalapay |
| PayPal |
| Klarna |
| Cofidis |
| BNP Paribas Personal Finance |
| Oney |
| Others |
Supply & Pricing Matrix
Platform transaction density in Paris and Île-de-France generates scale economies that compress merchant acquisition costs while establishing price floors for smaller providers serving peripheral regions. This concentration dynamic rewards infrastructure-heavy incumbents with existing banking integrations and strains pure-play entrants facing fixed compliance costs across sparse transaction volumes.
Pricing Analysis
Volume-discount tiering structures dominate merchant pricing, with large retail networks commanding preferential rates through committed transaction minimums. Price differentiation rests on integration complexity and white-label customization depth, while cost compression in the sub-200 euro segment intensifies due to ACPR-mandated affordability assessment overhead. Small merchants show highest price sensitivity, whereas enterprise retail chains prioritize technical reliability over marginal rate reductions.
Supply Chain Analysis
Ireland and Estonia host critical cloud infrastructure for real-time credit decisioning engines serving French BNPL providers. Core banking system dependencies draw from Germany and Belgium for API gateway technologies, while biometric authentication modules source from Netherlands-based specialists. Single-source vulnerability concentrates in legacy core banking architectures resistant to real-time connectivity. Distribution runs through payment gateway aggregators consolidating multi-merchant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's BNPL sector represents high-growth disruption as EU Consumer Credit Directive implementation forces real-time affordability infrastructure investment that separates capitalized incumbents from constrained entrants.
For Market Incumbents: Shield merchant relationships through accelerated white-label ERP integration before open finance protocols standardize bank connectivity. Vertical integration into proprietary affordability assessment APIs reduces dependency on third-party verification services threatened by CNIL data-handling restrictions. Capacity addition in Provence-Alpes-Côte d'Azur tourism corridors captures underpenetrated demand ahead of competitor expansion.
For New Entrants and Emerging Players: Lead with split-payment solutions targeting electronics retailers in Lyon and Marseille where deferred payment preferences outstrip installment plan saturation. Social commerce checkout integration offers the most penetrable channel among Gen Z purchasers in Paris basin. Go-to-market positioning should emphasize biometric-native onboarding to compress time-to-first-transaction against document-heavy incumbent workflows.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among bank-affiliated providers with embedded retail network contracts sustaining predictable transaction flows. Long-term viability across the projection horizon favors acquisition targets possessing ACPR regulatory relationships and white-label infrastructure rather than consumer-facing app platforms vulnerable to engagement volatility. Watch open finance implementation timelines as inflection indicators for technical integration cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| White-Label Infrastructure Expansion | Embedded finance APIs reduce merchant technical barriers while capturing recurring SaaS revenue streams. |
| Biometric Authentication Investment | CNIL-compliant facial recognition cuts onboarding abandonment for repeat users in fashion retail. |
| Open Finance API Preparation | Standardized bank connection protocols lower automated repayment scheduling development costs. |
| Provincial Merchant Acquisition | Tourism-dependent retail corridors in Nice and Marseille remain underpenetrated relative to Paris saturation. |
| Affordability Assessment Proprietary Development | In-house income verification reduces third-party dependency under ACPR supervision tightening. |
Research Methodology
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings. Primary fieldwork engaged fintech product managers, ACPR compliance officers, retail procurement leads at French department stores, and payment gateway technical architects. Secondary sources included ACPR supervision reports, CNIL data protection guidance, EU Consumer Credit Directive implementation texts, and French banking federation API documentation. Bottom-up transaction volume modeling triangulated against top-down macroeconomic consumption indicators.
Sensitivity analysis tested forecast robustness across alternative regulatory implementation timelines and open finance adoption scenarios. Segmentation dimensions modeled encompass service type, end-user archetype, distribution channel maturity, and regional e-commerce penetration patterns. CAGRs derived from curve-fitting historical growth trajectories against structural breakpoint assumptions. Industry-specific inputs incorporated merchant onboarding cost curves and biometric authentication adoption elasticities.
Forecasts assume regulatory continuity in French transposition of EU consumer protection frameworks; material policy shifts would require re-modeling. Specific risks include accelerated CNIL restrictions on transaction profiling and legacy bank system modernization delays disrupting real-time approval workflows. Recalibration cycles align with material shifts in open finance implementation schedules and ACPR supervision intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
South Korea Real Time Payments Market
Payments
Buy Now Pay Later Market
Payments
Middle East and Africa Prepaid Card Market
Payments
France Virtual Cards Market
Payments
Belgium Payments Market
Payments
Online Charging System (OCS) Market
Payments
Cyprus POS Terminals Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
Mobile Point of Sale (POS) Market
Payments
Mobile Money Market
Payments
Africa Virtual Cards Market
Payments
Mobile Wallet Market
Payments
Retail POS Terminals Market
Payments
Social Media Payment Solution Market
Payments
New Zealand Payments Market
Payments
United States Clearing Houses and Settlements Market