
 Digital Optical Transmitter Market | 2026-2036
Digital Optical Transmitter Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Optical Transmitter Market Insights
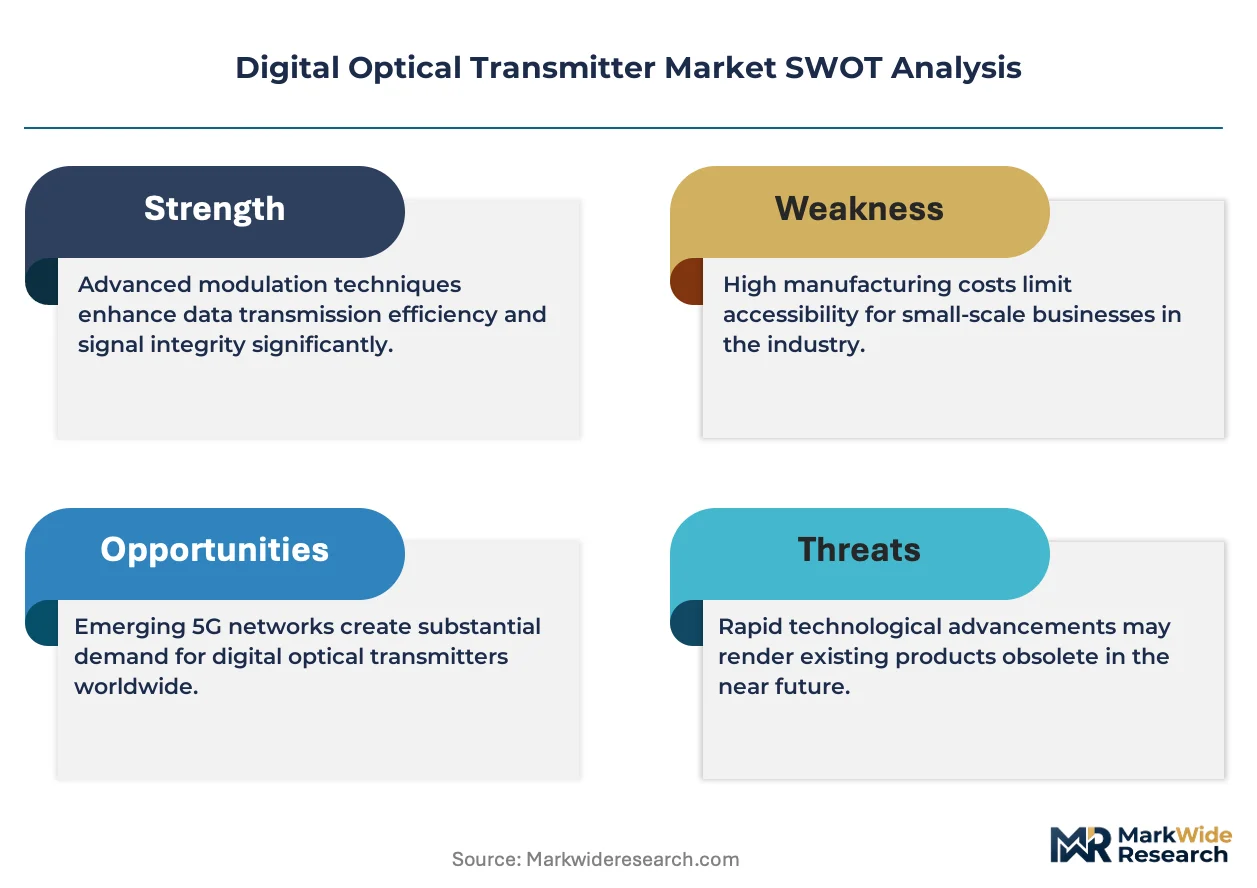
Silicon photonics integration is reconfiguring how digital optical transmitters achieve cost-per-bit reductions at 400G and beyond. Coherent Corp. leverages its indium phosphide and silicon photonics foundry capabilities to anchor high-margin coherent module production. Lumentum Holdings Inc. specializes in tunable lasers and advanced packaging for datacom transceivers. Huawei Technologies Co. Ltd. dominates supply to Chinese telecom operators through captive vertical integration from chip design to system assembly.
A digital optical transmitter converts electrical signals into modulated light for fiber-optic communication, typically operating at wavelengths near 1310 nm or 1550 nm with output powers ranging from 0 dBm to 10 dBm depending on link budget requirements. Coherent transmitters command the highest value per port due to DSP-intensive modulation formats, while non-coherent variants retain volume leadership in access networks where cost sensitivity dominates. Data center end users represent the fastest-expanding demand pool as hyperscalers upgrade spine-leaf architectures to 800G.
The FCC enforces electromagnetic compatibility and laser safety standards that constrain transmitter design and certification timelines for US-bound products. China's MIIT administers network equipment access licenses that favor domestic suppliers meeting GB standards for optical transport. ETSI and the ITU-T define interoperability frameworks that shape procurement specifications for European telecom operators. Stakeholders must monitor divergence between regional wavelength grid standards and DSP algorithm requirements when allocating R&D across product portfolios.
Market Dynamics
Silicon photonics is concentrating optical component manufacturing into fewer high-volume foundries, collapsing traditional cost structures for 400G and 800G coherent modules while redistributing margin pools toward DSP and packaging specialists.
Growth Catalysts
- FCC Broadband Equity Access and Deployment Program:The United States is channeling infrastructure subsidies toward fiber-to-the-home deployments, mandating optical hardware that meets stringent performance benchmarks for rural connectivity.
- Hyperscale data center spine-leaf upgrades:Cloud operators in China are scaling 800G port densities to support AI training clusters, creating pull-through demand for high-output coherent transmitters with integrated silicon photonics.
- Indium phosphide foundry consolidation:Specialized III-V semiconductor fabrication is concentrating among captive suppliers, enabling cost-per-bit reductions that accelerate 400G adoption in metro transport networks.
Market Restraints
- III-V semiconductor supply concentration:Indium phosphide substrate manufacturing centers on Japanese and Chinese suppliers, exposing module vendors to input volatility and geopolitical sourcing risk.
- MIIT network equipment licensing:China's domestic certification requirements for optical transport hardware create regulatory friction for foreign suppliers seeking access to state-backed telecom procurement.
- Power consumption scaling limits:DSP-intensive coherent modulation formats face thermal dissipation constraints in pluggable form factors, capping deployment density in space-constrained data center environments.
Strategic Opportunities
- Co-packaged optics convergence:Silicon photonics is hybridizing with electronic switching ASICs to eliminate retimer power and latency, opening architecture redesign opportunities for hyperscale switch vendors.
- India's BharatNet rural fiber expansion:The country's national broadband mission is creating demand for cost-optimized non-coherent transmitters in access network applications with price-sensitive procurement.
- ETSI Open ZR+ interoperability frameworks:European standardization of coherent pluggable specifications is lowering vendor lock-in barriers, enabling module suppliers to address multi-operator procurement consortiums.
Industry Challenges
- Silicon photonics packaging talent scarcity:Advanced flip-chip and fiber-attach processes require specialized process engineers that concentrate among a handful of contract manufacturers in Taiwan and Malaysia.
- Multi-standard wavelength grid fragmentation:Divergent ITU-T, IEEE, and OIF specifications force product portfolio duplication, stretching R&D resources across incompatible DSP algorithm implementations.
- Legacy SONET/SDH integration complexity:Telecom operators maintaining TDM infrastructure demand backward-compatible transmitter variants, fragmenting production volumes and complicating supply chain planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Optical Transmitter Market |
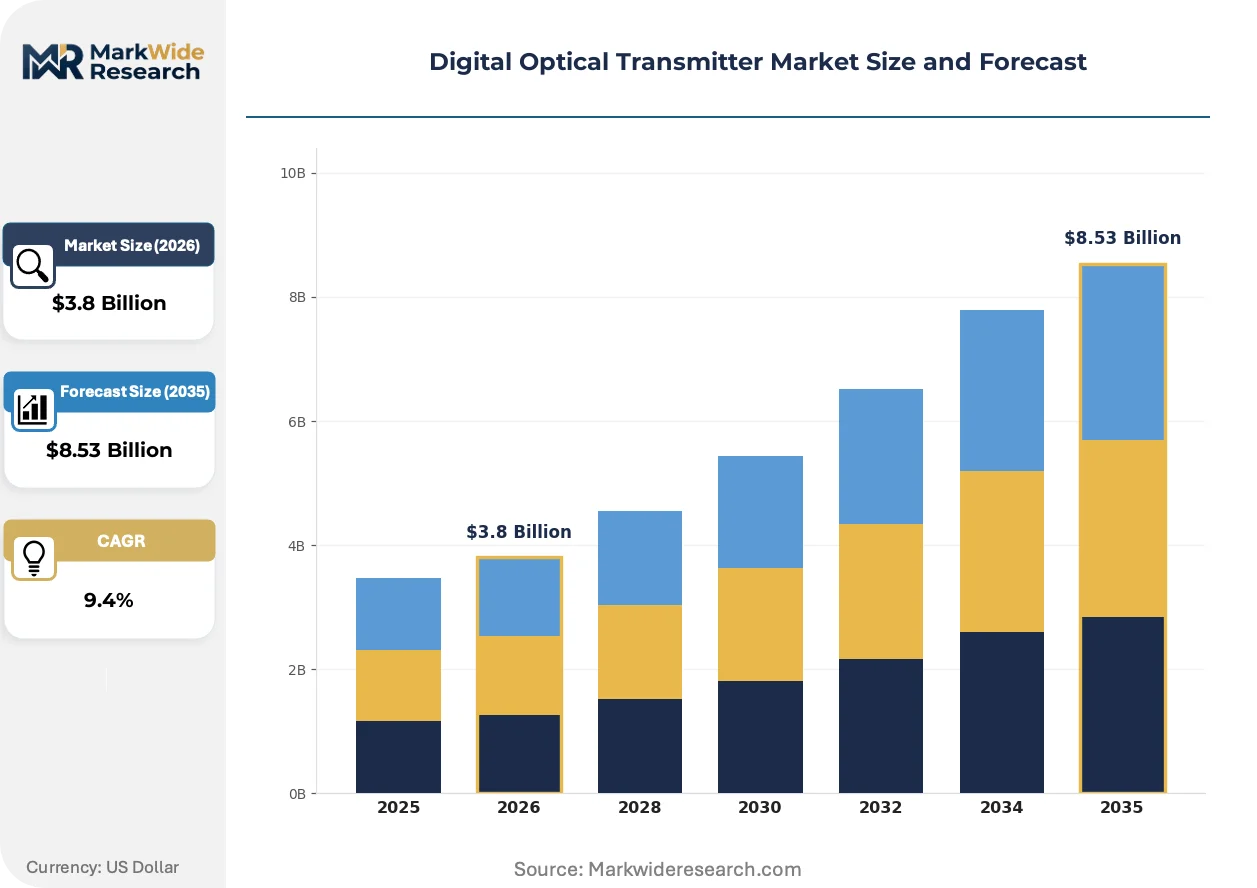
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coherent, Non-Coherent, Optical Amplifiers, Transponder End User: Telecom Operators, Data Centers, Enterprises, Government Agencies Technology: Wavelength Division Multiplexing, Time Division Multiplexing, Analog Transmission, Digital Transmission Installation Type: Indoor, Outdoor, Rack-Mounted, Integrated Solutions |
| Companies Covered | Broadcom Inc., Sumitomo Electric Industries Ltd., Coherent Corp., Fujitsu Optical Components Limited, Infinera Corporation, Cisco Systems Inc., Lumentum Holdings Inc., Applied Optoelectronics Inc., Huawei Technologies Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Optical Transmitter Market Trends and Innovations
Optical transmission architecture is bifurcating between power-efficient pluggable coherent modules and high-performance embedded systems, with silicon photonics serving as the common substrate technology reshaping competitive boundaries.
Silicon photonics is hybridizing indium phosphide lasers with CMOS-compatible waveguides to achieve wafer-scale integration of coherent transmitters. Hyperscalers in the United States and China are adopting these hybrid platforms for 800G datacenter interconnects at accelerated procurement cycles. The technology is compressing traditional discrete component supply chains by collapsing laser, modulator, and multiplexer functions onto single dies.
ETSI and the ITU-T are tightening interoperability specifications for coherent pluggable modules through Open ZR+ and 400ZR framework extensions. European telecom operators are now mandating multi-vendor compatibility in transport procurement tenders, forcing module suppliers to standardize DSP firmware interfaces. Metro and regional network segments face the steepest compliance redesign timelines as operators refresh aging ROADM infrastructure.
Hyperscale buyers are consolidating optical module procurement through direct foundry partnerships rather than traditional distributor channels. Cloud operators in China and the United States are establishing captive qualification programs that bypass legacy telecom supply chains. This concentration is most visible in 400G and 800G datacenter transceiver categories where volume scale justifies dedicated production lines.
Digital Optical Transmitter Market Segmentation
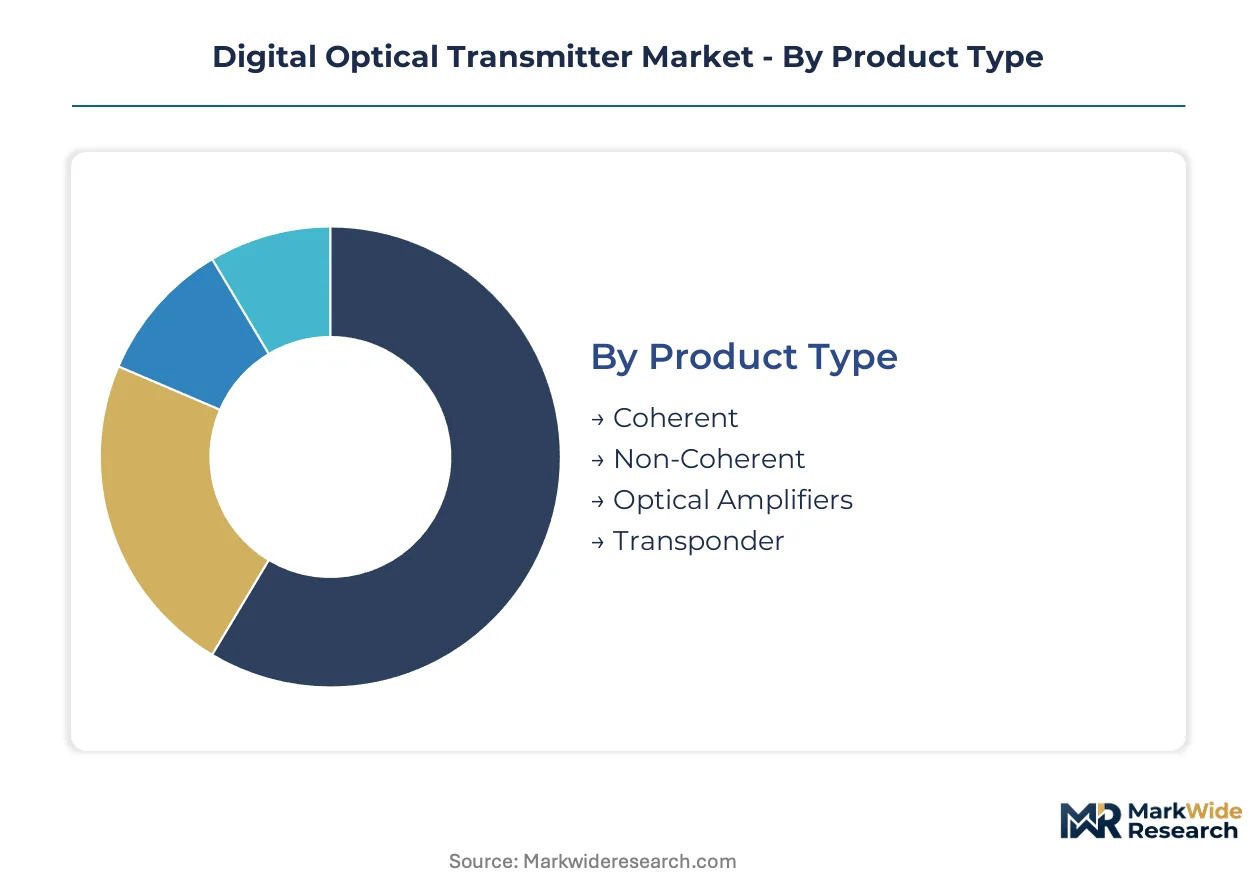
Digital optical transmitter procurement cycles vary dramatically by application, with hyperscale data centers refreshing equipment every 18-24 months while telecom transport infrastructure operates on 7-10 year depreciation schedules. Understanding these velocity differentials helps suppliers align inventory planning and R&D roadmaps against actual replacement demand rather than installed base metrics.
Product Type:
Coherent modules turn over fastest as DSP algorithms advance, while optical amplifiers and transponders in legacy transport networks face extended replacement cycles due to embedded software dependencies and chassis compatibility requirements.
- Coherent:DSP-intensive modulation formats enable 400G and 800G transmission over single wavelengths. Hyperscale data centers in China and the United States are driving procurement volume for pluggable coherent modules as spine-leaf architectures scale to support AI training clusters.
- Non-Coherent:Simpler modulation schemes dominate access networks and metro edges where cost-per-bit sensitivity outweighs spectral efficiency requirements. India's BharatNet rural fiber expansion is generating pull-through demand for cost-optimized non-coherent variants in price-sensitive procurement environments.
- Optical Amplifiers:Erbium-doped fiber amplifiers extend reach without optical-to-electrical conversion, serving long-haul submarine and terrestrial routes.
- Transponder:Protocol-agnostic wavelength conversion enables interoperability between client-side and line-side interfaces in multi-vendor networks.
Non-coherent transmitters anchor the volume base while coherent modules gain share at the steepest rate.
End User:
Procurement concentration and technical specifications diverge sharply across buyer categories, with data centers prioritizing power density and hot-swappability while government agencies emphasize security certification and domestic sourcing mandates.
- Telecom Operators:Incumbent carriers and competitive local exchange carriers deploy transmitters across access, aggregation, and core network tiers. FCC broadband infrastructure subsidies in the United States are accelerating fiber-to-the-home equipment procurement with stringent performance benchmarks for rural connectivity.
- Data Centers:Hyperscale cloud operators and colocation providers drive demand for high-port-density coherent modules. China's domestic cloud providers are scaling 800G deployments fastest, creating concentrated demand for silicon photonics-based transmitters with integrated DSP.
- Enterprises:Private campus and industrial fiber networks require cost-optimized transmitters with simplified management interfaces.
- Government Agencies:Defense and civilian networks mandate TEMPEST shielding and domestic supply chain verification for classified and critical infrastructure communications.
Telecom operators maintain the largest installed base while data center procurement is climbing the fastest.
Technology:
Technology selection determines spectral efficiency, latency, and interoperability boundaries, with WDM and digital transmission commanding premium positioning while analog and TDM retain niche applications in legacy infrastructure.
- Wavelength Division Multiplexing:Multiple optical carriers share single fiber through precise wavelength separation, maximizing fiber utilization. ETSI Open ZR+ interoperability frameworks in Europe are standardizing WDM coherent pluggable specifications to reduce vendor lock-in.
- Time Division Multiplexing:Electrical domain multiplexing aggregates lower-rate signals before optical conversion, persisting in legacy SONET/SDH infrastructure.
- Analog Transmission:Direct intensity modulation supports radio frequency over fiber and cable television distribution networks.
- Digital Transmission:Discrete signal processing enables forward error correction and adaptive modulation for maximum reach and reliability.
Digital transmission anchors revenue concentration while WDM capacity additions are expanding most quickly.
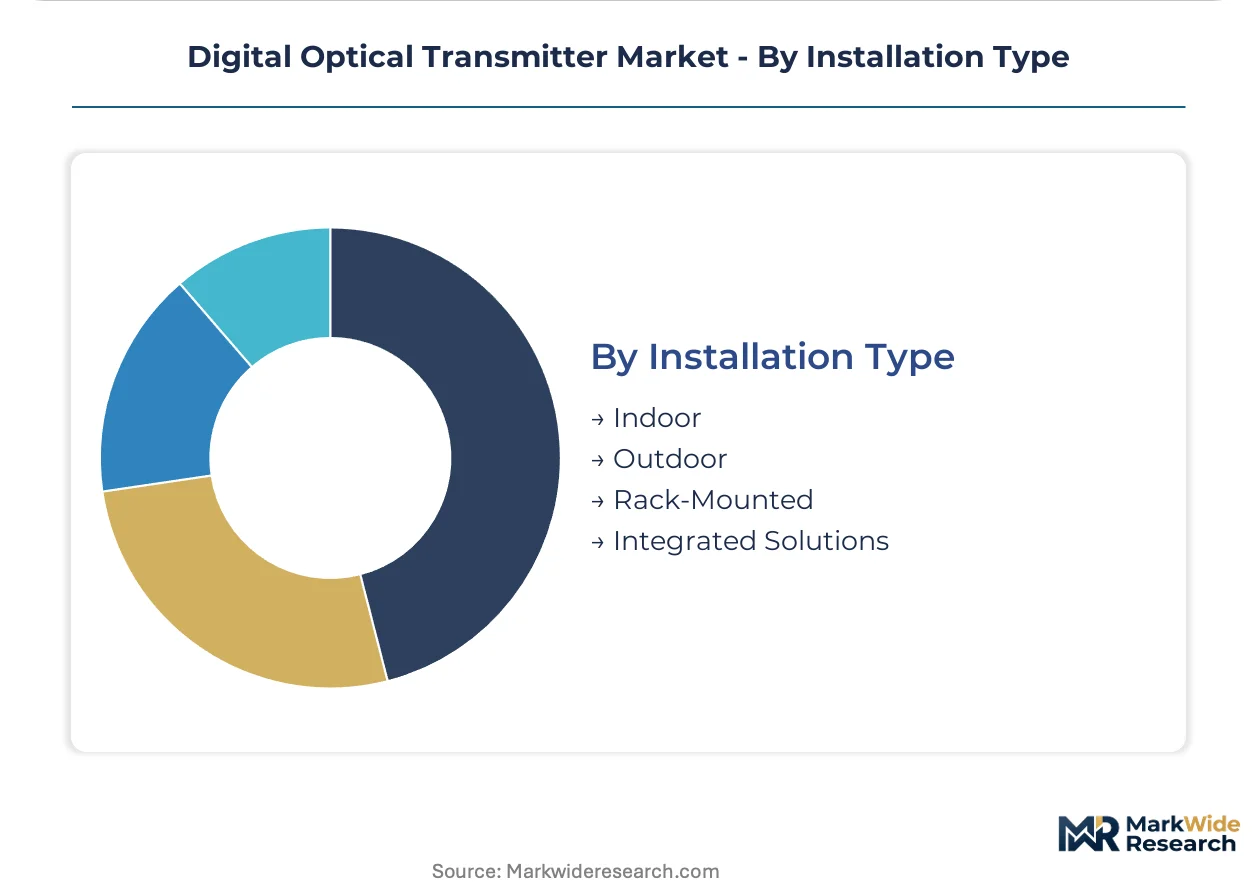
Installation Type:
Physical deployment constraints shape thermal management, power delivery, and service access requirements, with outdoor installations facing environmental sealing challenges and rack-mounted variants competing for limited data center floor space.
- Indoor:Climate-controlled environments enable passive cooling and standard connector interfaces for enterprise and data center applications.
- Outdoor:Hardened enclosures withstand temperature extremes, moisture, and particulate contamination for cell site and remote terminal deployments.
- Rack-Mounted:Standard 19-inch chassis integration supports hot-swappable module replacement and centralized power distribution in facility environments.
- Integrated Solutions:Transmitter functions embed within larger systems such as ROADM nodes and packet-optical transport platforms.
Rack-mounted configurations dominate current shipments while integrated solutions are gaining share fastest through disaggregated optical system architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center operators in the United States and China dominate procurement volume, while telecom infrastructure programs in India and Europe create secondary demand pools for access-grade hardware.
United States
FCC broadband infrastructure subsidies are accelerating fiber-to-the-home deployments across rural markets. The Broadband Equity Access and Deployment Program mandates optical hardware meeting stringent performance benchmarks for unserved communities. Silicon photonics foundry clusters in California and Texas are scaling 800G coherent module production for hyperscale cloud operators.
China
Domestic cloud providers are deploying 800G spine-leaf architectures at the fastest global pace to support AI training clusters. MIIT network equipment licensing favors domestic suppliers meeting GB standards for optical transport systems. Shenzhen and Shanghai anchor captive vertical integration from indium phosphide chip design through system assembly for state-backed telecom procurement.
India
BharatNet rural fiber expansion is generating concentrated demand for cost-optimized non-coherent transmitters in price-sensitive access networks. TRAI mandates domestic value-add requirements for government-funded connectivity projects. Industrial corridors in Gujarat and Tamil Nadu are attracting module packaging investments to serve national broadband mission procurement.
Germany
ETSI Open ZR+ interoperability frameworks are standardizing coherent pluggable specifications for multi-vendor transport networks. The EU Green Deal is tightening energy efficiency requirements for data center optical hardware. Munich and Stuttgart host precision photonics packaging specialists serving European telecom operator refresh cycles.
Japan
METI funding programs are accelerating indium phosphide substrate manufacturing capacity for 400G metro transport modules. JIS standards govern electromagnetic compatibility certification timelines for optical transmission equipment. Yokohama and Osaka clusters concentrate advanced flip-chip packaging talent for coherent transmitter assembly.
Digital Optical Transmitter Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement environments. The vendor base organizes around three strategic archetypes: captive-integrated telecom equipment suppliers, silicon photonics foundry specialists, and discrete component pure-plays. Consolidation pressure is intensifying as hyperscale buyers consolidate procurement through direct foundry partnerships rather than distributor channels. Competitive moves center on backward integration into III-V semiconductor fabrication and co-packaged optics architecture licensing.
Within the captive-integrated tier, Huawei Technologies Co. Ltd. exemplifies vertical control from chip design through system assembly. Among silicon photonics specialists, Coherent Corp. and Lumentum Holdings Inc. occupy positions anchoring high-margin coherent module production through foundry capabilities and advanced packaging expertise respectively.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Sumitomo Electric Industries Ltd. |
| Coherent Corp. |
| Fujitsu Optical Components Limited |
| Infinera Corporation |
| Cisco Systems Inc. |
| Lumentum Holdings Inc. |
| Applied Optoelectronics Inc. |
| Huawei Technologies Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Japanese and Chinese indium phosphide substrate suppliers compresses pricing tier spreads while forcing module vendors toward cost-plus contracts indexed to III-V wafer spot markets. This concentration simultaneously elevates premium pricing for vertically integrated coherent module producers and squeezes margins for non-captive packaging houses dependent on spot procurement.
Pricing Analysis
Cost-plus contracts with indium phosphide wafer indexation dominate procurement between substrate suppliers and module manufacturers. Pricing stratifies across DSP-intensive coherent tiers, standard pluggable formats, and economy non-coherent access variants, with certification to FCC Part 15 and MIIT GB standards commanding substantial premiums. Cost compression in 400G datacenter modules intensifies as hyperscale buyers consolidate direct foundry relationships. Access network operators in India exhibit the highest price sensitivity, while Chinese cloud providers absorb premium coherent pricing for 800G spine-leaf deployments.
Supply Chain Analysis
Extended payment terms from hyperscale cloud operators to module vendors now reach 90-120 days, forcing suppliers to tap supply-chain finance facilities anchored by receivables. Manufacturing concentrates in China, Taiwan, and Malaysia, with substrate fabrication drawing from Japanese and Chinese III-V foundries. Critical inputs include indium phosphide wafers, silicon photonics interposers, and DSP ASICs. Tariff exposure on Chinese-assembled modules shipped to US data centers looms as the primary structural risk. Distribution runs through direct foundry partnerships rather than legacy telecom distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in firmware management and field-programmable DSP upgrades are expanding faster than hardware shipments, as hyperscale operators demand lifecycle optimization over transactional procurement. Recurring revenue from remote diagnostics and thermal monitoring subscriptions now commands valuation multiples exceeding pure hardware plays.
For Market Incumbents: Harden supply security through captive indium phosphide substrate sourcing or long-term offtake agreements with Japanese suppliers. Deepen backward integration into silicon photonics foundry capacity to defend margin position against DSP-agnostic packaging houses. Invest in Open ZR+ firmware certification to maintain interoperability leverage as European operators consolidate procurement.
For New Entrants and Emerging Players: India's BharatNet rural fiber expansion offers the most penetrable white-space for cost-optimized non-coherent transmitter assembly. Target state-level value-add requirements through packaging investments in Gujarat industrial corridors. Pursue white-label partnerships with established DSP licensors to bypass R&D scale barriers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors silicon photonics packaging specialists with proven flip-chip yield rates. Long-term viability hinges on co-packaged optics architecture licensing positions rather than discrete module assembly. Watch hyperscale direct-qualification program announcements as the signal for procurement channel inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into III-V Fabrication | Captive indium phosphide wafer supply secures margin against substrate volatility. |
| Open ZR+ Firmware Certification | ETSI interoperability compliance unlocks European multi-operator procurement consortiums. |
| Co-Packaged Optics Architecture Licensing | Silicon photonics-electronic ASIC hybridization eliminates retimer power in hyperscale switches. |
| Direct Foundry Partnership Establishment | Bypassing distributor channels captures volume commitment from Chinese and US cloud operators. |
| India Packaging Facility Investment | TRAI domestic value-add mandates create localized procurement preference for BharatNet tenders. |
Research Methodology
Operator-level perspectives from data center procurement directors, telecom transport engineers, silicon photonics foundry managers, and III-V substrate supply planners anchored the qualitative base. Primary interviews combined with secondary validation from FCC equipment authorization databases, MIIT network access license filings, ETSI technical specifications, and hyperscaler capital expenditure disclosures. Bottom-up module shipment estimates triangulated against top-down optical transport equipment revenue analysis.
Scenario-bracketing around silicon photonics yield trajectories and coherent DSP algorithm refresh cycles framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, end user category, technology protocol, and installation environment, with regional procurement velocity differentials incorporated. CAGRs derived from replacement cycle analysis against installed base depreciation schedules, with AI training cluster expansion and rural broadband subsidy uptake as industry-specific demand inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by captive-integrated Chinese equipment suppliers or sudden Open RAN procurement shifts would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Portable Lenses Market
Optical Components
Co-Packaged Optics Market
Optical Components
RF-Over-Fiber (Rfof) Solution Market
Optical Components
Planar Lightwave Circuit Splitter Market
Optical Components
Optical Isolator Market
Optical Components
Global Optical Measurement Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
Laser Module Market
Optical Components
Liquid Lenses Market
Optical Components
Global Mask Alignment Systems Market
Optical Components
Optical Waveguide Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Electronic Digital Magnifiers Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
Objective Lens Market
Optical Components
Optical Lens Edger Market