
 RF-Over-Fiber (Rfof) Solution Market | 2026-2036
RF-Over-Fiber (Rfof) Solution Market Size, Share, and Industry Trends Forecast 2026-2036
RF-Over-Fiber (Rfof) Solution Market Analytics
Market Context with Strategic Players
Photonic engineering talent scarcity is bifurcating the competitive landscape between integrated suppliers and specialized component vendors. EMCORE Corporation leverages in-house gallium arsenide foundry capacity to sustain vertical control over transmitter chip supply. HUBER+SUHNER anchors European defense contracts through MIL-STD qualified cable assemblies and connector systems. Coherent Corp. competes on high-volume coherent optical engine platforms that extend into RFoF signal conditioning modules.
Technical Definition and Structural Segments
RF-Over-Fiber (Rfof) Solutions convert radio frequency signals into optical carriers for transmission over fiber optic cables, typically operating in the 1310 nm or 1550 nm wavelength windows with spurious-free dynamic range exceeding 100 dB·Hz^(2/3), enabling kilometer-scale signal transport without electromagnetic interference. The primary industrial purpose centers on eliminating coaxial cable attenuation limitations in distributed antenna systems, radar remoting, and satellite ground station feeder links. Transceivers dominate product-level value capture due to laser diode and photodetector integration complexity, while Dense Wavelength Division Multiplexing technology leads growth velocity as telecom operators multiplex multiple RF bands onto single fiber strands. Government end users concentrate procurement around ruggedized form factors with extended temperature specifications, whereas data center demand prioritizes compact pluggable modules for 5G fronthaul aggregation.
Regulatory Framework and Outlook
FCC Part 15 emissions standards govern commercial RFoF deployment in unlicensed and licensed spectrum bands, while ITAR regulations constrain military-grade product exports from U.S. suppliers to approved destination countries. The EU Radio Equipment Directive mandates CE marking for RFoF subsystems operating above specified power thresholds, creating dual certification burdens for Atlantic-crossing vendors. Stakeholders must monitor spectrum reallocation proceedings and defense procurement shifts as 5G mid-band expansion and satellite constellation deployments reshape addressable RF transport requirements.
Market Dynamics
Defense procurement cycles and telecom infrastructure buildouts are creating divergent demand profiles for RF-over-fiber solutions, with military buyers prioritizing ruggedization and spectrum security while commercial operators chase bandwidth density and cost-per-link economics.
Growth Catalysts
- NATO Communications Modernization:Allied defense ministries are mandating low-loss RF transport for distributed antenna systems in forward operating bases, creating sustained procurement pipelines for qualified vendors.
- 5G Mid-Band Spectrum Allocation:FCC auctions of C-band and 3.45 GHz spectrum are accelerating fronthaul network builds requiring WDM-enabled RFoF links to aggregate multiple cell sites.
- Indium Phosphide Laser Maturation:Foundry yield improvements at compound semiconductor fabs are reducing transmitter module costs and expanding addressable commercial deployments.
Market Restraints
- Gallium Arsenide Substrate Concentration:Six-inch GaAs wafer supply concentrates among three foundry operators in East Asia, exposing transceiver manufacturers to geopolitical supply interruptions.
- ITAR Export Licensing Friction:U.S. State Department controls on military-grade RFoF components delay revenue recognition for defense contractors seeking approved-destination country sales.
- Coaxial Cable Substitution in Low-Frequency Applications:Legacy copper infrastructure retains cost advantages for sub-3 GHz distribution runs under 500 meters in cost-constrained venue installations.
Strategic Opportunities
- LEO Ground Station Buildouts:Satellite constellation operators in the United States are procuring high-dynamic-range RFoF feeder links for gateway antenna farms tracking thousands of orbital passes daily.
- EU Defense Fund Procurement Windows:European Commission joint acquisition mechanisms are pooling member state demand for interoperable military communications hardware with RFoF backbones.
- Silicon Photonics Convergence:Integration of CMOS-compatible optical modulators with RF conditioning electronics promises cost-disruptive transceiver architectures for volume 5G deployments.
Industry Challenges
- Compound Semiconductor Process Engineering Talent:Photonic device fabrication expertise concentrates among aging specialists at legacy GaAs and InP foundries, constraining capacity expansion timelines.
- MIL-STD-810 Qualification Duration:Environmental testing protocols for extended temperature and shock specifications extend defense product development cycles by 18-24 months versus commercial equivalents.
- Multi-Band Signal Integrity Verification:Spurious-free dynamic range certification across concurrent RF bands demands specialized anechoic chamber infrastructure that smaller vendors struggle to access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF-Over-Fiber (Rfof) Solution Market |
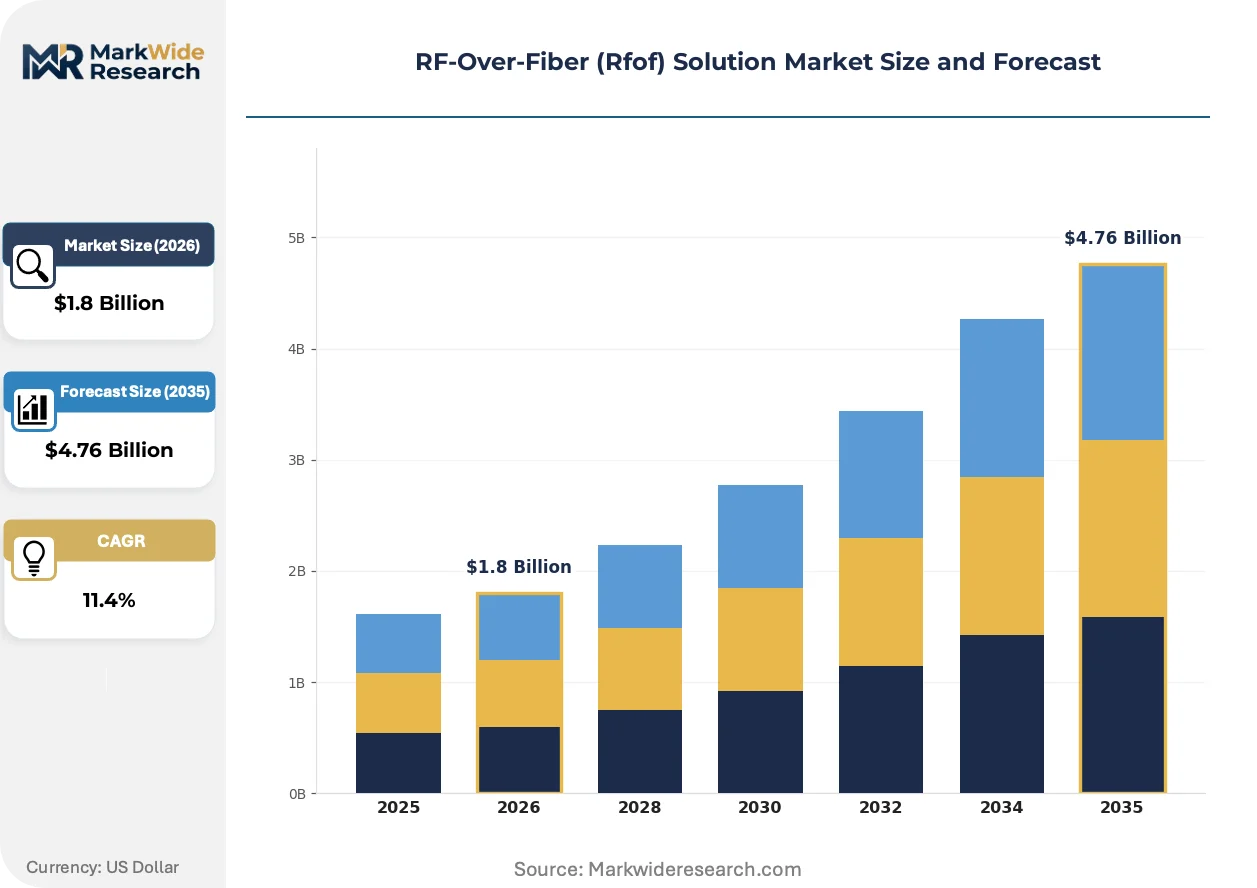
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transceivers, Amplifiers, Splitters, Couplers Application: Telecommunication, Broadcasting, Military, Industrial Technology: Single-Mode Fiber, Multi-Mode Fiber, Wavelength Division Multiplexing, Dense Wavelength Division Multiplexing End User: Telecom Operators, Data Centers, Government, Enterprises |
| Companies Covered | HUBER+SUHNER, EMCORE Corporation, G&H Group, SEIKOH GIKEN, Broadcom, Coherent Corp., Optical Zonu Corporation, ViaLite Communications, DEV Systemtechnik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF-Over-Fiber (Rfof) Solution Market Evolving Landscape
Photonic integration and defense-commercial technology transfer are compressing product development cycles while reshaping competitive differentiation from discrete component performance to subsystem-level signal conditioning.
Coherent optical detection with digital signal processing is displacing direct-detection architectures in high-performance RFoF links. Satellite ground station operators in the United States and European spaceports are adopting these platforms for multi-gigahertz instantaneous bandwidth applications. The technology is displacing legacy intensity-modulation schemes in feeder links where link budget and linearity requirements exceed 100 dB·Hz^(2/3).
EU Radio Equipment Directive harmonization is mandating CE marking for RFoF subsystems operating above specified electromagnetic compatibility thresholds. Atlantic-crossing vendors now face dual certification burdens combining FCC Part 15 emissions testing with European notified body review. Defense contractors serving NATO interoperability requirements are consolidating procurement specifications to reduce variant proliferation across certification regimes.
Systems integrators are bundling RFoF transport with antenna positioning and spectrum monitoring as unified service contracts rather than discrete hardware sales. European telecom infrastructure providers are leading this transition, unbundling capital expenditure from operational responsibility in 5G fronthaul rollouts. Germany and France exhibit the most advanced contracting sophistication, with network-as-a-service models capturing majority share of new distributed antenna system deployments.
RF-Over-Fiber (Rfof) Solution Market Segmentation
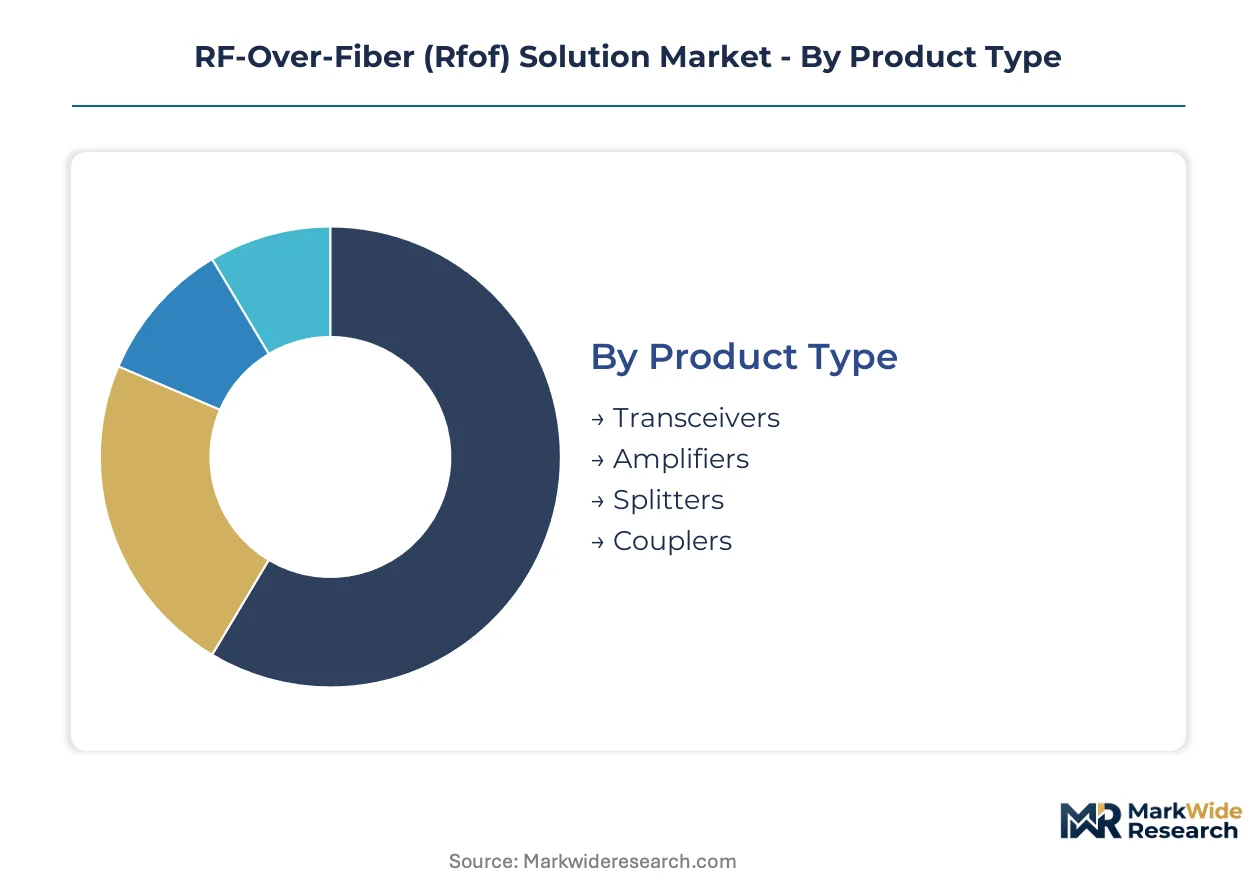
RF-Over-Fiber solution segmentation reveals divergent margin structures across defense-qualified hardware and volume telecom components. Product architecture and end-use certification requirements create distinct competitive arenas with incompatible qualification timelines and pricing models.
Product Type:
Margin pools concentrate in transmitter modules where laser diode integration and hermetic packaging drive cost structures.
- Transceivers:Integrated transmitter-receiver modules incorporating DFB lasers and high-linearity photodetectors in hermetic packages. Defense procurement in the United States prioritizes extended temperature variants for distributed antenna systems, while telecom operators in Germany specify pluggable form factors for 5G fronthaul aggregation.
- Amplifiers:Erbium-doped fiber and semiconductor optical amplifier subsystems that compensate for link losses in long-haul RF transport. Broadcasting networks in France deploy these for studio-to-transmitter links exceeding 20 kilometers where signal integrity cannot degrade.
- Splitters:Passive optical devices dividing RF-modulated carriers across multiple distribution paths. Cable operators in Japan utilize fused biconical taper designs for indoor coax replacement in high-rise buildings.
- Couplers:Directional and hybrid couplers enabling signal monitoring and redundancy switching in mission-critical installations. Military ground station operators specify these for feeder link diversity architectures.
Transceivers hold installed capacity. Amplifiers are rotating up the share rankings.
Application:
Application segments separate by electromagnetic compatibility certification burden and operational environment severity.
- Telecommunication:5G fronthaul and midhaul networks transporting CPRI and eCPRI protocols between baseband units and remote radio heads. FCC C-band auctions in the United States accelerated WDM-enabled link deployment to aggregate multiple cell sites onto single fiber strands.
- Military:Radar remoting, electronic warfare systems, and satellite ground station feeder links requiring MIL-STD-810 environmental qualification. NATO interoperability specifications mandate common RF interfaces across member nation procurement.
- Broadcasting:Studio-to-transmitter links and remote production connectivity for sports and live events. Network operators in France prioritize low-phase-noise performance for HD and UHF signal distribution.
- Industrial:Harsh-environment RF transport for oil and gas platforms, mining operations, and manufacturing automation. Offshore installations in Norway specify explosion-proof enclosures and subsea cable assemblies.
Telecommunication commands volume scale. Military is climbing the fastest on value per link.
Technology:
Technology selection hinges on bandwidth-distance product requirements and multiplexing complexity tradeoffs.
- Wavelength Division Multiplexing:Coarse and dense variants enabling multiple RF bands on single fiber through ITU-grid channel spacing. Telecom infrastructure providers in Germany deploy CWDM for cost-constrained 5G fronthaul while satellite operators adopt DWDM for gateway diversity.
- Dense Wavelength Division Multiplexing:Narrow channel spacing below 100 GHz supporting 40+ wavelengths per fiber. Data center interconnects in the United States utilize these platforms for high-count RF signal aggregation in LEO ground station farms.
- Single-Mode Fiber:Standard ITU-T G.652 and G.654 fibers with 9-micron core diameter for minimal dispersion at 1550 nm. Long-haul military links specify ultra-low-loss variants for radar remoting applications.
- Multi-Mode Fiber:50-micron and 62.5-micron core designs for short-reach indoor distribution under 2 kilometers. Enterprise LAN upgrades in Japan favor OM4 grades for building-wide distributed antenna systems.
Single-Mode Fiber holds installed capacity. Dense Wavelength Division Multiplexing is expanding most quickly in new-build networks.
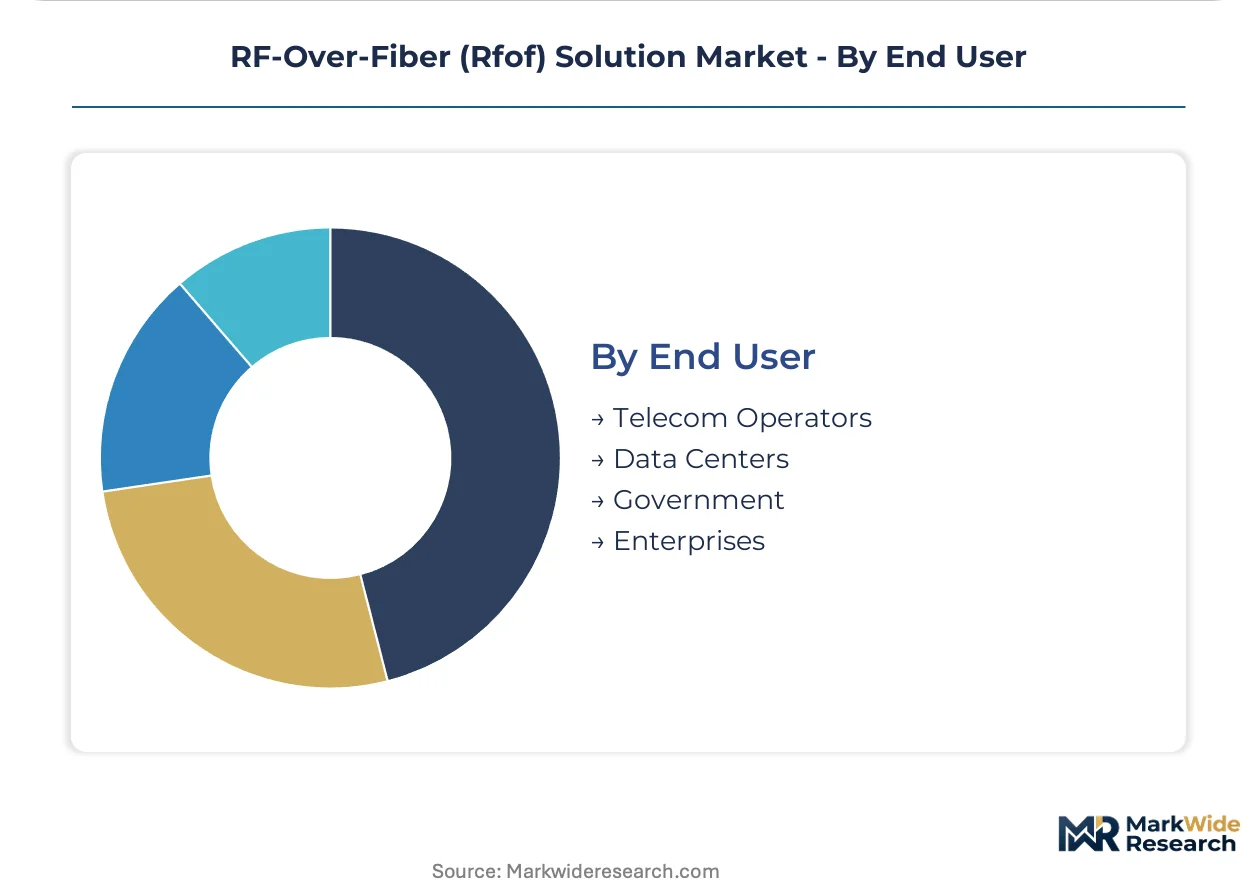
End User:
End user categories diverge by procurement sophistication, with government buyers emphasizing qualification documentation and enterprises prioritizing total cost of ownership.
- Government:Defense ministries and space agencies procuring through ITAR-controlled channels with multi-year qualification cycles. The United States Department of Defense specifies distributed antenna systems and satellite ground stations with extended temperature ratings.
- Telecom Operators:Mobile network operators and fixed-line incumbents building 5G fronthaul and fiber-deep access networks. Operators in France and Germany are consolidating RFoF procurement under network-as-a-service contracts.
- Data Centers:Hyperscale cloud providers and colocation operators interconnecting facilities and supporting 5G edge computing nodes. Facilities in Virginia and Oregon specify pluggable transceivers for rapid deployment cycles.
- Enterprises:Corporate campuses, healthcare systems, and educational institutions deploying private 5G and indoor coverage solutions. Manufacturing campuses in Japan adopt industrial-grade variants for automation network backbones.
Government holds installed capacity. Data Centers are gaining share fastest on hyperscale buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 emissions standards govern commercial RFoF deployment in the United States, while ITAR regulations constrain military-grade exports. Allied defense ministries across NATO members are pooling procurement through joint acquisition mechanisms.
United States
Department of Defense spending on distributed antenna systems and satellite ground stations drives concentrated demand. ITAR export licensing creates friction for defense contractors seeking approved-destination country sales. Virginia and Oregon data center clusters specify pluggable transceivers for rapid 5G edge deployment cycles.
Germany
Telecom infrastructure providers deploy CWDM-enabled RFoF links for cost-constrained 5G fronthaul aggregation. EU Radio Equipment Directive mandates CE marking for subsystems above specified power thresholds. Bavaria and North Rhine-Westphalia host advanced network-as-a-service contracting for distributed antenna system rollouts.
France
Broadcasting networks prioritize low-phase-noise RFoF performance for HD and UHF signal distribution. ANSM and national regulators enforce electromagnetic compatibility certification for commercial deployments. Île-de-France and Provence-Alpes-Côte d'Azur concentrate studio-to-transmitter link installations exceeding 20 kilometers.
Japan
Enterprise LAN upgrades favor OM4 multi-mode fiber for building-wide distributed antenna systems. METI standards guide industrial-grade variant adoption for automation network backbones. Tokyo and Osaka metropolitan areas drive high-rise coax replacement using fused biconical taper splitter designs.
United Kingdom
Ministry of Defence procurement aligns with NATO interoperability specifications for common RF interfaces. National regulations transpose EU directives on radio equipment and electromagnetic compatibility. London and Southeast England cluster satellite ground station operators tracking LEO constellation orbital passes.
RF-Over-Fiber (Rfof) Solution Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the RF-Over-Fiber solution market. The vendor base separates between integrated compound semiconductor suppliers and specialized subsystem assemblers. Three archetypes dominate: gallium arsenide foundry operators, MIL-STD-qualified cable integrators, and coherent optical engine platforms. Capacity expansion at East Asian wafer foundries and strategic partnerships for defense qualification are reshaping competitive positioning.
Among established suppliers, HUBER+SUHNER and EMCORE Corporation exemplify divergent strategic positions. HUBER+SUHNER anchors European defense contracts through qualified cable assembly expertise. EMCORE Corporation occupies a position within the compound semiconductor integration tier. Coherent Corp. represents the optical engine convergence archetype extending into signal conditioning modules. These three entities illustrate how geographic origin and structural focus map to distinct competitive vectors in military and commercial segments.
| Leading Market Players |
|---|
| HUBER+SUHNER |
| EMCORE Corporation |
| G&H Group |
| SEIKOH GIKEN |
| Broadcom |
| Coherent Corp. |
| Optical Zonu Corporation |
| ViaLite Communications |
| DEV Systemtechnik GmbH |
| Others |
Value Network & Pricing Analysis
Indium phosphide laser maturation at East Asian foundries is displacing legacy gallium arsenide transmitters in mid-range RFoF links, compressing unit economics while redistributing component sourcing toward South Korean and Japanese compound semiconductor fabs. This substitution dynamic simultaneously erodes pricing premiums on established GaAs transceiver tiers and rewards vendors with captive InP capacity or qualified second-source arrangements.
Pricing Analysis
Transceiver modules exhibit 40-60% price spreads between U.S. defense-qualified variants and Asian-sourced commercial equivalents, with ITAR certification and MIL-STD-810 environmental testing constituting the primary price differentiation drivers. Three-tier pricing structure across ITAR-restricted, CE-marked European, and unqualified commercial levels is experiencing downward pressure from silicon photonics convergence in volume 5G deployments. Telecom operators demonstrate highest price sensitivity through network-as-a-service contracting, while NATO defense ministries absorb premiums for extended temperature specifications and multi-year qualification documentation.
Supply Chain Analysis
Six-inch gallium arsenide wafer fabrication concentrates in Taiwan, Japan, and China, with indium phosphide epitaxy and erbium-doped fiber amplification components drawing from U.S., German, and South Korean specialist foundries. Raw material dependencies span GaAs substrates, InP wafers, and specialty optical fibers with ultra-low-loss coatings. Single-source vulnerability around qualified hermetic packaging vendors exposes transceiver manufacturers to 18-24 month lead time extensions. Distribution runs through defense prime contractors for military-qualified hardware and direct OEM procurement for telecom volume deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RF-Over-Fiber solution market is entering a cyclical recovery phase as NATO communications modernization programs and LEO ground station buildouts release pent-up procurement demand deferred through prior defense budget compression cycles.
For Market Incumbents: Shield installed base relationships in U.S. Department of Defense distributed antenna system contracts through accelerated ITAR compliance investments and captive gallium arsenide foundry utilization. Deepen backward integration into indium phosphide laser diode supply to offset East Asian wafer concentration risk and preserve margin structure against silicon photonics entrants.
For New Entrants and Emerging Players: Network-as-a-service contracting gaps in European 5G fronthaul aggregation present immediate service-layer white space where incumbents under-serve with legacy hardware-centric models. Target Germany and France telecom infrastructure providers with integrated RFoF transport and antenna positioning service bundles. Pursue silicon photonics-based transceiver architectures as the primary go-to-market angle for cost-disruptive entry into volume commercial deployments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed compound semiconductor specialists possessing qualified MIL-STD cable assembly capabilities but limited optical engine integration depth. Long-term viability over the next decade hinges on convergence between defense qualification expertise and coherent optical detection technology adoption in satellite ground station feeder links. Monitor EU Defense Fund procurement window announcements as the critical inflection signal for European military RFoF demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Platform Development | CMOS-compatible modulator integration threatens compound semiconductor cost structures in volume 5G deployments. |
| ITAR Compliance Certification Investment | U.S. State Department approval unlocks NATO defense procurement pipelines worth multi-year contract visibility. |
| Network-as-a-Service Contracting Model | German and French telecom operators unbundle capital expenditure from operational responsibility in distributed antenna rollouts. |
| LEO Ground Station Feeder Link Qualification | Satellite constellation operators in Virginia and Oregon demand high-dynamic-range RFoF for gateway antenna farms. |
| Indium Phosphide Foundry Capacity Expansion | South Korean and Japanese compound semiconductor fabs reduce transmitter module costs for commercial addressable markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, defense procurement databases, and ITAR-controlled export license records through structured interviews with RFoF product managers, defense contracting officers, and telecom infrastructure procurement leads. Bottom-up unit shipment estimates by product type and application segment were cross-validated against top-down market sizing derived from compound semiconductor foundry capacity disclosures and wavelength division multiplexing equipment revenue reports.
Segmentation dimensions modeled span product architecture, end-use certification requirements, technology platform selection, and geographic procurement regime across the analysis window. CAGRs were derived from trend extrapolation of defense budget appropriation cycles and 5G spectrum auction timing, with specific weighting applied to NATO interoperability specification adoption rates and LEO constellation deployment schedules.
Underlying assumptions cover sustained Department of Defense spending on distributed antenna systems and satellite ground stations, with deviation risk concentrated in ITAR export licensing friction and gallium arsenide substrate supply interruptions. Practitioners should keep alternative scenarios live as EU Defense Fund procurement mechanisms and silicon photonics yield improvements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Mobile Optical Pluggable Market
Optical Components
Polarizer Film Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
CMP Polishing Machine Market
Optical Components
VCSEL for Data Communication Market
Optical Components
Electro Optical System Market
Optical Components
Fiber Optic Plates (FOP) Market
Optical Components
3-7mm Galvo Scanner Market
Optical Components
North America Tunable Laser Market
Optical Components
Passive Optical Component Market
Optical Components
Optical Amplifier Market
Optical Components
Global Non Dispersive Infrared (NDIR) Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
Objective Lens Market
Optical Components
Italy Lithium Niobate Modulator Market
Optical Components
Global Optical Diode Market