
 Global Fragrance Market | 2026-2036
Global Fragrance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fragrance Market Analysis
Market Context with Strategic Players
Prestige beauty retail is hardening as the dominant demand channel for high-concentration fragrance formats, displacing mass-market aerosol sales in key metropolitan clusters. Puig SA leverages its vertical control over raw material sourcing from Grasse to sustain margin capture across the Eau de Parfum tier. LVMH Moet Hennessy-Louis Vuitton anchors its fragrance portfolio through Dior and Givenchy licenses, dominating airport duty-free corridors. Coty Inc competes via licensed celebrity and designer portfolios, extending its reach through specialty store partnerships.
Technical Definition and Structural Segments
Fragrance denotes a formulated mixture of volatile aromatic compounds, fixatives, and solvents—typically ethanol at 60-80% concentration—designed to impart scent to human skin, textiles, or ambient environments through controlled evaporation. Industrial production relies on steam distillation, solvent extraction, and molecular synthesis to isolate or replicate odorant molecules from botanical, animalic, or petrochemical precursors. The Eau de Parfum segment commands the deepest margin pools due to higher oil concentration and perceived longevity, while online retail channels represent the fastest-growing sales pathway as direct-to-consumer sampling technology matures. Unisex formulations are gaining shelf space, though the women's end-user category still occupies the largest revenue share across department store distribution.
Regulatory Frame and Forward-Looking Close
The EU REACH regulation and ECHA allergen disclosure mandates are forcing reformulation of legacy compositions, raising compliance costs for multinational houses. The FDA in the United States and Health Canada both govern cosmetic labeling but diverge on fragrance allergen thresholds, creating dual-track product development requirements. China's NMPA and SAMR enforce separate registration protocols for imported versus domestically manufactured scents, complicating market entry timelines. Stakeholders must monitor evolving patch-test standards and biotech-derived ingredient approvals to anticipate which formulation platforms will secure regulatory clearance ahead of competitors.
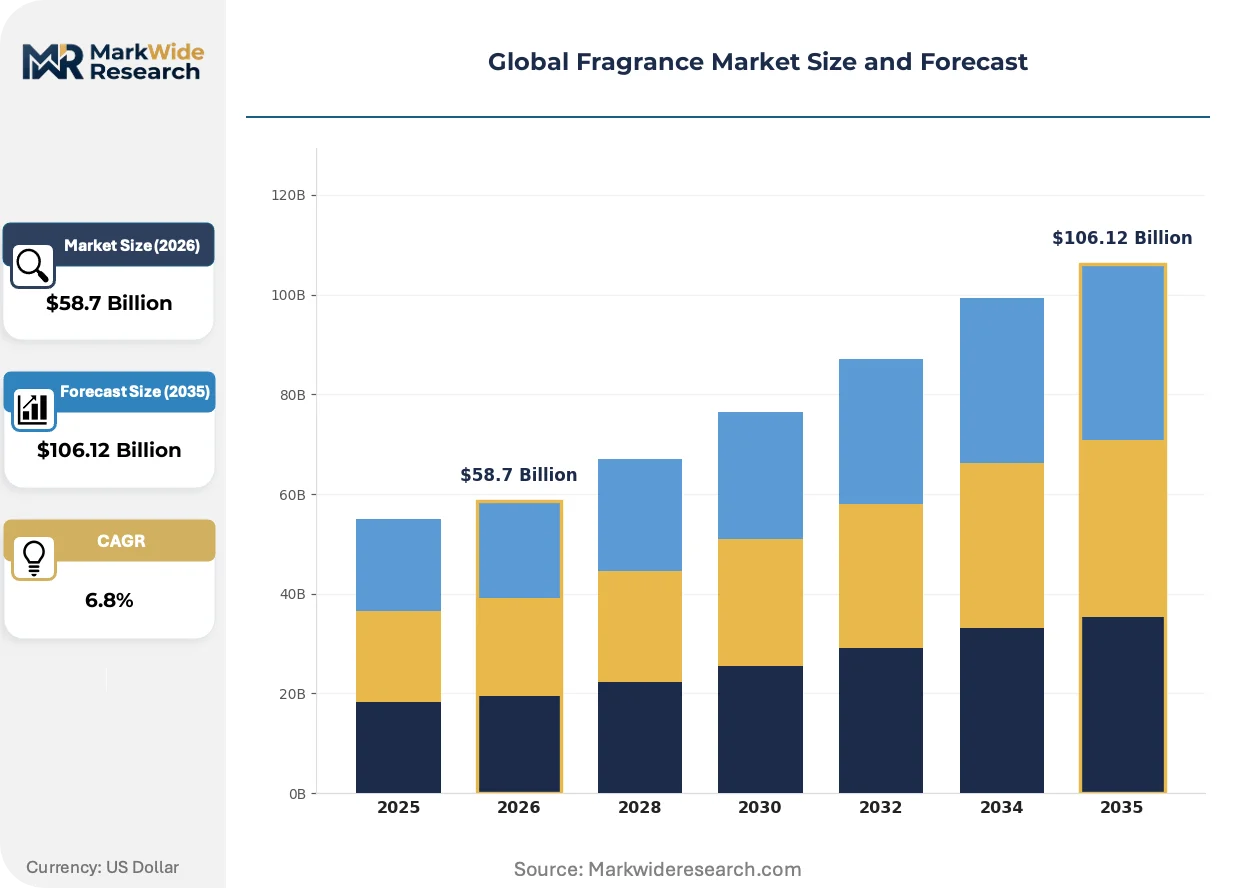
Market Dynamics
Concentration of perfume oil supply in Grasse and regulatory divergence between EU REACH allergen mandates and China's NMPA registration protocols are fragmenting formulation strategies across multinational houses.
Growth Catalysts
- EU REACH allergen transparency mandates:Disclosure requirements above 0.01% concentration are accelerating reformulation toward biotech-derived molecules that bypass traditional botanical extraction bottlenecks.
- China's tier-one city premiumization:Shanghai and Beijing consumers are pivoting from mass-market eaux de toilette toward artisanal concentrated oils, expanding addressable margin pools for niche houses.
- Direct-to-consumer sampling technology:AI-driven scent-matching algorithms and micro-vial subscription models are collapsing traditional department store discovery barriers.
Market Restraints
- Sandalwood and oud supply concentration:Over 70% of sustainable sandalwood cultivation sits with Australian and Indian state-controlled plantations, creating raw material bottlenecks for premium oriental formulations.
- Ethanol purity requirements:Cosmetic-grade ethanol denaturing standards vary between FDA, REACH, and NMPA specifications, forcing redundant distillation runs or parallel inventory stocks.
- Synthetic musk substitution ceiling:Galaxolide and tonalide environmental persistence concerns have triggered EU restriction proposals, yet natural musk alternatives remain cost-prohibitive at scale.
Strategic Opportunities
- India's underpenetrated prestige segment:Mumbai and Delhi luxury retail corridors show nascent demand for concentrated perfume oils, with local BIS standards still evolving for import classification.
- Biotech fermentation platforms:Precision-engineered yeast strains producing rare terpenes and sesquiterpenes are converging with carbon-neutral production mandates to create defensible ingredient supply.
- Airport duty-free digital integration:Pre-order apps linked to travel itineraries are opening bypass channels around traditional wholesale distribution markups.
Industry Challenges
- Perfumer apprenticeship pipeline collapse:Grasse-based training programs and ISIPCA matriculation rates have failed to match retirement velocity among master perfumers born before 1965.
- Dual-track compliance architecture:Simultaneous EU REACH dossier preparation and China NMPA animal-testing waivers demand dedicated regulatory affairs headcount that mid-size houses cannot amortize.
- Legacy ERP integration with batch-level traceability:Allergen disclosure mandates require molecule-level ingredient tracking that conflicts with decades-old formulation databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fragrance Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Perfumes, Colognes, Eau de Parfum, Eau de Toilette End User: Men, Women, Unisex, Children Sales Channel: Online Retail, Specialty Stores, Supermarkets, Department Stores Packaging Type: Glass Bottles, Plastic Bottles, Roll-ons, Spray |
| Companies Covered | Puig SA, L'Oreal Groupe, LVMH Moet Hennessy-Louis Vuitton, Beiersdorf AG, Kering, Coty Inc, CHANEL, Natura & Co, The Estée Lauder Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fragrance Market Emerging Trajectories
Biotechnology is dissolving the boundary between natural extraction and synthetic chemistry, while regulatory fragmentation and channel disintermediation are forcing simultaneous reinvention of supply chains and consumer touchpoints.
Precision fermentation of rare odorant molecules is rewriting cost structures for ingredients previously dependent on volatile agricultural harvests or endangered species harvests. Niche houses in Paris and New York are adopting biotech-derived sandalwood and ambergris alternatives at three times the pace of mass-market competitors. This molecular manufacturing platform is compressing the traditional three-year harvest-to-compound cycle into eight-week bioreactor batches.
ECHA's 2023 expansion of allergen labeling requirements to 86 substances is forcing systematic reformulation of legacy compositions containing linalool, limonene, and citronellol in concentrations above threshold limits. Multinational houses are retiring between fifteen and thirty percent of existing SKUs rather than absorbing compliance documentation costs. The Eau de Parfum segment faces disproportionate impact due to higher oil loads and corresponding allergen concentration risks.
Discovery patterns among millennial and Gen-Z buyers are rotating toward algorithmic curation and micro-sample subscription models, displacing the department store counter as the primary trial venue. Direct-to-consumer channels in the United States and United Kingdom are capturing fragrance discovery occasions previously owned by Sephora and Douglas. This behavioral pivot is most pronounced among unisex and gender-fluid scent categories where traditional retail merchandising conventions create friction.
Global Fragrance Market Segmentation
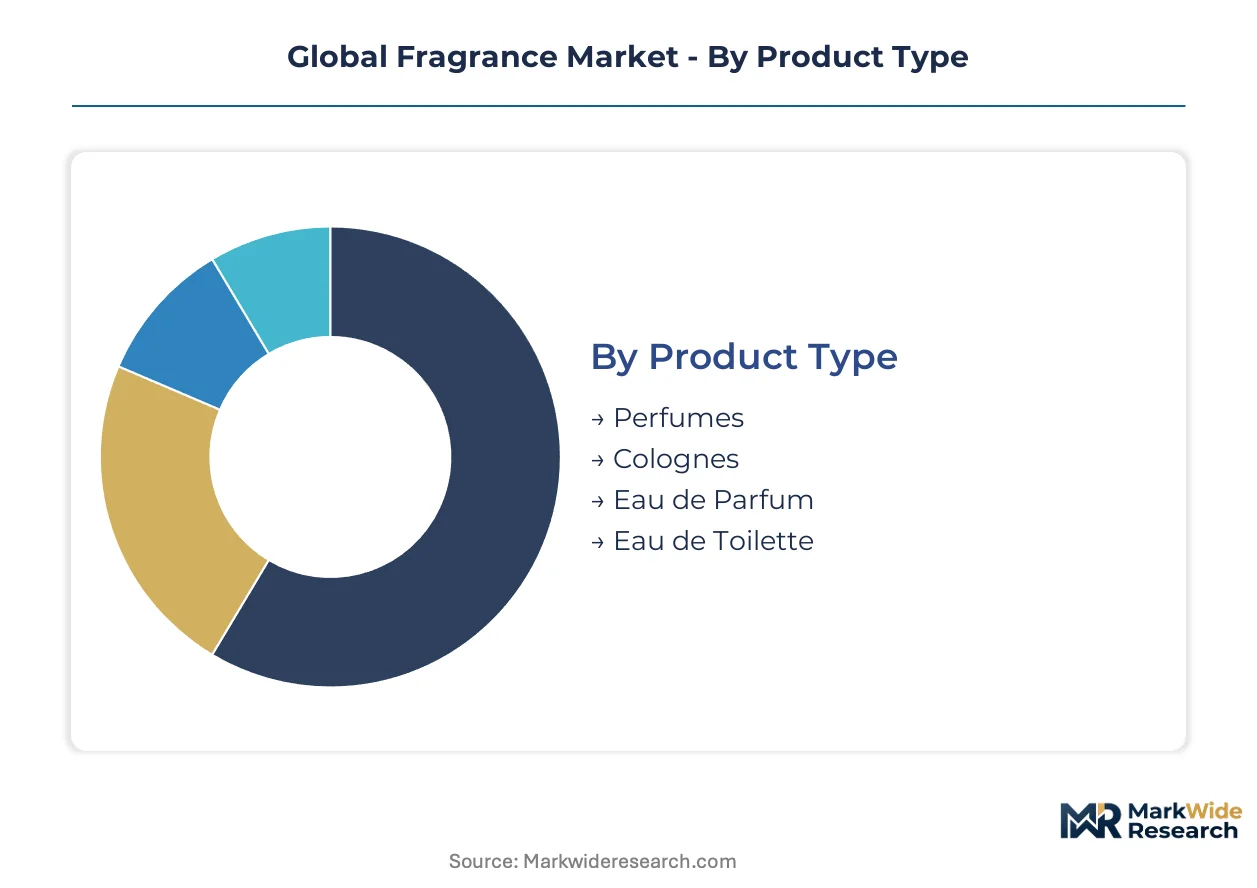
Fragmentation across concentration tiers and distribution channels demands precise segment targeting, as regulatory burdens and margin structures vary sharply between mass-market eaux de toilette and prestige perfume oils. Formulation disclosure requirements under EU REACH and China's NMPA protocols create divergent compliance costs that reshape profitability by product category and sales channel.
Product Type:
Eau de Parfum and perfume extract segments carry the heaviest certification load under EU REACH allergen dossier requirements, while lighter concentrations face streamlined disclosure thresholds in the United States and China.
- Perfumes:Highest oil concentration at 20-30% aromatic compounds delivers extended longevity on skin. Demand concentrates in Paris, Dubai, and Shanghai luxury corridors where consumers prioritize sillage and exclusivity over unit economics. NMPA registration timelines for imported perfume extracts now stretch fourteen months, forcing houses to front-load compliance costs.
- Eau de Parfum:15-20% oil concentration balances performance with accessibility, commanding the deepest margin pools across prestige retail. China's tier-one cities show accelerating pivot toward this tier as consumers abandon mass-market alternatives. ECHA's expanded allergen list disproportionately impacts formulations here due to higher absolute oil loads.
- Eau de Toilette:5-15% concentration dominates volume sales in European drugstore channels and Asian duty-free corridors.
- Colognes:Light 2-5% oil loads serve summer seasonal demand and male-skewing fragrance wardrobes in Mediterranean and Middle Eastern markets.
Leading the category by volume: Eau de Toilette. Growing fastest: Eau de Parfum.
End User:
Gender-targeted segmentation is dissolving as unisex formulations capture discovery occasions previously split between binary merchandising conventions, though legacy SKU architectures still dominate department store floor plans.
- Women:Floral and oriental families retain largest revenue share through licensed designer portfolios and heritage house archives. Sephora and Douglas still merchandise 60% of fragrance square footage to this segment despite share erosion.
- Unisex:Fastest-growing classification as niche houses in Brooklyn, Le Marais, and East London launch gender-fluid collections. Direct-to-consumer sampling technology enables algorithmic matching that bypasses traditional counter conventions.
- Men:Woody and aromatic profiles dominate, with oud and leather accords gaining in Dubai and Mumbai prestige retail.
- Children:Hypoallergenic formulations with restricted allergen palettes serve regulated markets in Germany and Scandinavia.
Dominating current revenue: Women's fragrances. Expanding most quickly: Unisex.
Sales Channel:
Channel economics diverge sharply as duty-free digital pre-order apps and AI-driven subscription models collapse traditional wholesale markups that once sustained department store counters.
- Online Retail:Micro-vial subscription services and scent-matching algorithms now own discovery among millennial and Gen-Z buyers in the United States and United Kingdom. Direct-to-consumer margins bypass 40-50% wholesale layers that burden specialty store distribution.
- Specialty Stores:Sephora, Douglas, and niche perfumeries in Grasse and Paris sustain premium positioning through trained staff and exclusive launches. These venues capture trial occasions for artisanal houses that lack mass-market scale.
- Department Stores:Legacy channel facing foot traffic erosion in American and European malls, though airport-adjacent locations retain strength.
- Supermarkets:Mass-market aerosols and celebrity-licensed eaux de toilette dominate shelf space with price-driven positioning.
Still largest by transaction volume: Department Stores. Gaining share fastest: Online Retail.
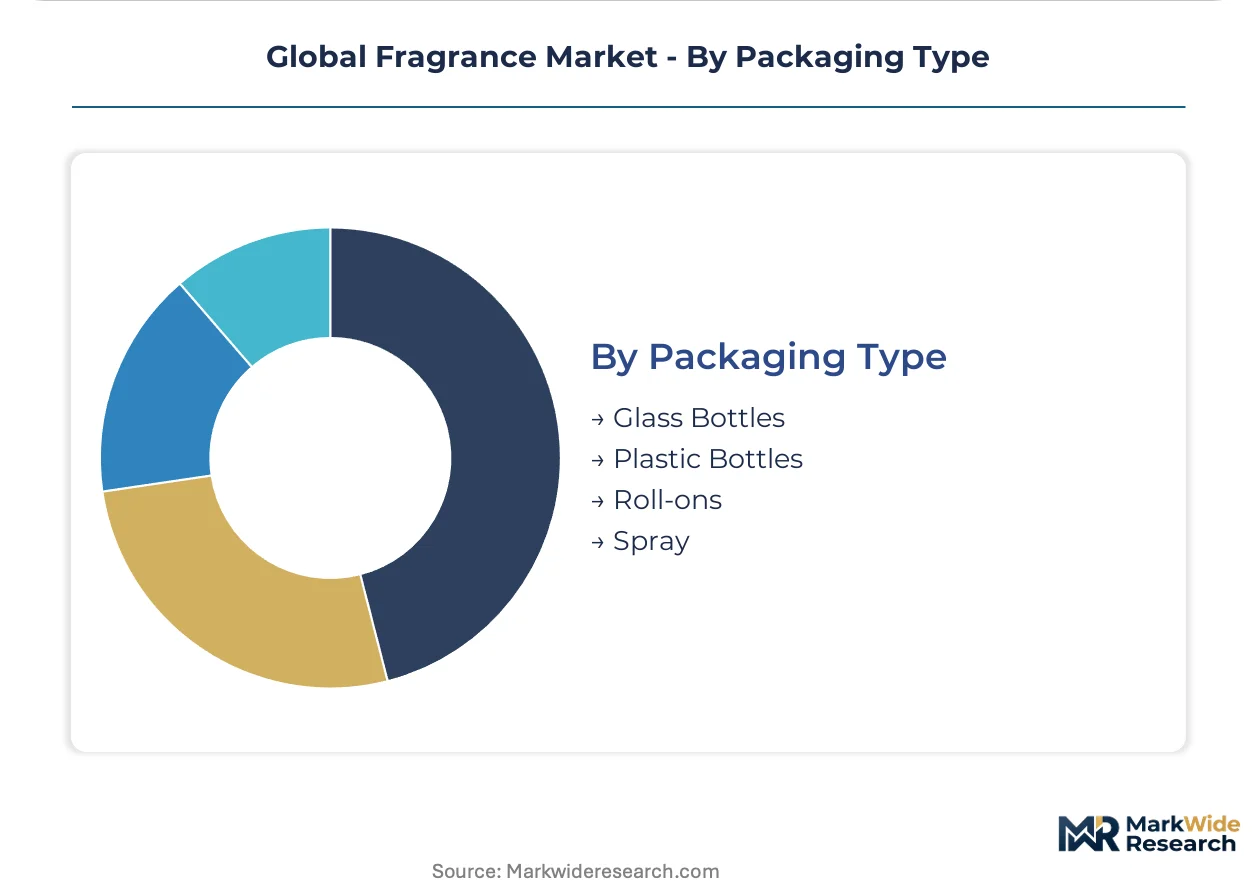
Packaging Type:
Material selection now intersects with carbon-neutral mandates and refill infrastructure investments as houses respond to EU packaging waste directives and consumer pressure on single-use glass.
- Glass Bottles:Dominant prestige format with weighted bases and magnetic closures signaling luxury positioning. Guerlain and Chanel have deployed refillable glass architectures in Paris and London flagship stores to preempt regulatory pressure.
- Spray:Standard atomizer mechanism across all concentration tiers, with fine-mist engineering now a technical differentiator for niche houses.
- Roll-ons:Travel and trial format gaining in Asian markets where portability and discretion are valued.
- Plastic Bottles:Restricted to mass-market and children's segments due to perceived quality degradation and sustainability concerns.
Highest unit value captured by: Glass Bottles. Steepest volume decline: Plastic Bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grasse's tax-advantaged fragrance production zone concentrates raw material processing and master perfumer training, anchoring European supply while Asian luxury corridors reshape demand geography.
United States
Prestige retail demand concentrates in New York and Los Angeles luxury corridors, with direct-to-consumer channels capturing millennial discovery occasions. FDA cosmetic labeling requirements diverge from EU REACH allergen thresholds, forcing parallel formulation tracks. New Jersey's chemical processing cluster supplies cosmetic-grade ethanol to domestic fragrance houses.
France
Grasse remains the dominant cultivation and compounding center for high-value naturals, with ISIPCA training programs feeding perfumer talent to multinational houses. ECHA's expanded allergen disclosure mandates are accelerating biotech ingredient adoption in Paris-based ateliers. The Provence-Alpes-Côte d'Azur region concentrates 80% of EU fragrance oil production capacity.
China
Shanghai and Beijing tier-one consumers are pivoting toward concentrated perfume oils, abandoning mass-market eaux de toilette. NMPA registration protocols for imported extracts now stretch fourteen months, while SAMR enforces separate domestic manufacturing standards. The Yangtze River Delta hosts rising local fragrance compounders serving prestige retail.
United Arab Emirates
Dubai's airport duty-free corridors dominate regional prestige fragrance volume, with oud and amber accords commanding premium positioning. MOHAP cosmetic registration requirements are tightening import documentation for alcohol-based formulations. The Dubai Design District is attracting niche fragrance houses targeting Gulf luxury consumers.
India
Mumbai and Delhi luxury retail corridors show nascent demand for concentrated perfume oils among emerging affluent households. BIS standards for fragrance import classification remain in evolution, creating compliance uncertainty for foreign houses. Karnataka's sandalwood plantations supply sustainable raw material to premium oriental formulations.
Global Fragrance Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with prestige houses controlling formulation IP and compounding partners handling scale production. The market structures around three tiers: vertically integrated luxury conglomerates, licensed portfolio managers, and independent niche ateliers. Strategic moves concentrate on biotech ingredient partnerships and direct-to-consumer channel bypasses around traditional wholesale layers.
Within the vertically integrated tier, LVMH Moet Hennessy-Louis Vuitton and CHANEL exemplify captive control from raw material sourcing through retail distribution. Coty Inc occupies a position representing licensed portfolio scale, while Puig SA anchors the family-owned specialist archetype with concentrated exposure to Mediterranean and Middle Eastern markets. These three patterns illustrate how competitive positioning derives from supply chain configuration and channel access rather than product differentiation alone.
| Leading Market Players |
|---|
| Puig SA |
| L'Oreal Groupe |
| LVMH Moet Hennessy-Louis Vuitton |
| Beiersdorf AG |
| Kering |
| Coty Inc |
| CHANEL |
| Natura & Co |
| The Estée Lauder Companies |
| Others |
Supply Flow & Price Mechanics
Sandalwood futures and oud spot prices cascade through Grasse-based compounders into three-tier pricing structures across premium perfume extracts, standard Eau de Parfum tiers, and economy eaux de toilette, with ethanol purity differentials and REACH compliance documentation costs amplifying spreads between concentration grades.
Pricing Analysis
Lead-time premiums reward fourteen-month NMPA-registered inventory positions in Shanghai and Beijing, while spot purchases of Australian plantation sandalwood trade at discounts reflecting harvest cycle volatility. Three-tier pricing structure across premium, standard, and economy levels separates heritage house extracts from licensed designer Eau de Parfum and mass-market celebrity aerosols. Price compression runs through the Eau de Toilette tier as supermarket buyers enforce volume rebates. Mass-market consumers show acute price sensitivity; prestige retail clients absorb certification premiums for Grasse-origin provenance.
Supply Chain Analysis
Single-source vulnerability sits with Karnataka state-controlled sandalwood plantations supplying over seventy percent of sustainable feedstock for oriental accords. Grasse, the Yangtze River Delta, and New Jersey's chemical corridor anchor upstream concentration, drawing from Indian sandalwood, synthetic musk precursors, and cosmetic-grade ethanol. Tariff exposure intensifies at ethanol denaturing bottlenecks where FDA, REACH, and NMPA specifications diverge. Distribution runs through airport duty-free corridors and direct-to-consumer subscription platforms, bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH allergen disclosure mandates and NMPA registration timelines are consolidating mid-size fragrance houses unable to amortize dual-track compliance headcount, creating acquisition opportunities for well-capitalized competitors.
For Market Incumbents: Anchor backward integration into biotech fermentation platforms producing rare terpenes, securing carbon-neutral supply chains ahead of ECHA restriction proposals. Capture master perfumer talent from retiring ISIPCA cohorts through structured apprenticeship programs. Defend margin pools by controlling Grasse-origin raw material sourcing against emerging fermentation substitutes. For New Entrants and Emerging Players: Enter via algorithmic scent-matching subscriptions targeting Brooklyn, Le Marais, and East London unisex discovery occasions, bypassing Sephora and Douglas shelf-space barriers. Exploit India's underpenetrated prestige corridors in Mumbai and Delhi before BIS standards crystallize. Deploy micro-vial sampling infrastructure to collapse traditional department store trial economics. For Investors and Strategic Acquirers: Distressed-cycle entries favor family-owned niche ateliers with Grasse training lineage and captive Middle Eastern distribution, stranded by REACH documentation costs. Long-term viability hinges on biotech ingredient pipelines and direct-to-consumer channel ownership. Watch ECHA patch-test standard revisions as inflection signals for reformulation platform winners.| Strategic Initiative | Industry Significance |
|---|---|
| Biotech Fermentation Partnership | Precision-engineered yeast strains from Ginkgo Bioworks and Amyris compress harvest-to-compound cycles for sandalwood alternatives. |
| Direct-to-Consumer Channel Launch | AI-driven scent-matching algorithms bypass Sephora and Douglas wholesale markups in US and UK millennial segments. |
| REACH Compliance Dossier Investment | ECHA's expanded allergen list forces systematic SKU retirement; early documentation secures formulation platform clearance. |
| Grasse Master Perfumer Apprenticeship | ISIPCA matriculation shortfalls against retirement velocity threaten heritage house IP continuity. |
| India Prestige Retail Expansion | Mumbai and Delhi luxury corridors show nascent concentrated oil demand amid evolving BIS import classification. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with master perfumers, fragrance house regulatory affairs directors, Sephora category buyers, Grasse compounder operations heads, and airport duty-free procurement managers. ECHA allergen disclosure databases, NMPA registration filings, USITC fragrance import statistics, and IFRA compliance guidelines provided triangulation anchors. Bottom-up volume builds across concentration tiers reconciled against top-down prestige retail audit data.
Segment-level modeling captured product type splits across perfume extracts, Eau de Parfum, Eau de Toilette, and cologne concentrations; end-user categories spanning women's, men's, unisex, and children's formulations; and channel dynamics across online retail, specialty stores, department stores, and duty-free corridors. CAGRs derived from regression analysis against macroeconomic indicators and regulatory event timelines. Biotech ingredient adoption curves and direct-to-consumer penetration rates served as category-specific forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA restriction acceleration or NMPA registration timeline extensions. Assumptions reflect current REACH allergen thresholds, NMPA animal-testing waiver protocols, and sandalwood plantation harvest schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Evaporative Diffusers Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Global Luxury Perfumes Market
Fragrances & Perfumes
Global Scented Candle Market
Fragrances & Perfumes
Organic Perfumes Market
Fragrances & Perfumes
Digital Scent Market
Fragrances & Perfumes
Wax Melts Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Middle East Fragrances Market
Fragrances & Perfumes
Natural Fragrance Market
Fragrances & Perfumes
Clean Perfume Market
Fragrances & Perfumes
Fragrance Emulsion Market
Fragrances & Perfumes
Perfume Vials Market
Fragrances & Perfumes
Cosmetic and Fragrance Retail Chain Market
Fragrances & Perfumes
Home Fragrance Diffusers Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market