
 Organic Perfumes Market | 2026-2036
Organic Perfumes Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Perfumes Market Analytics
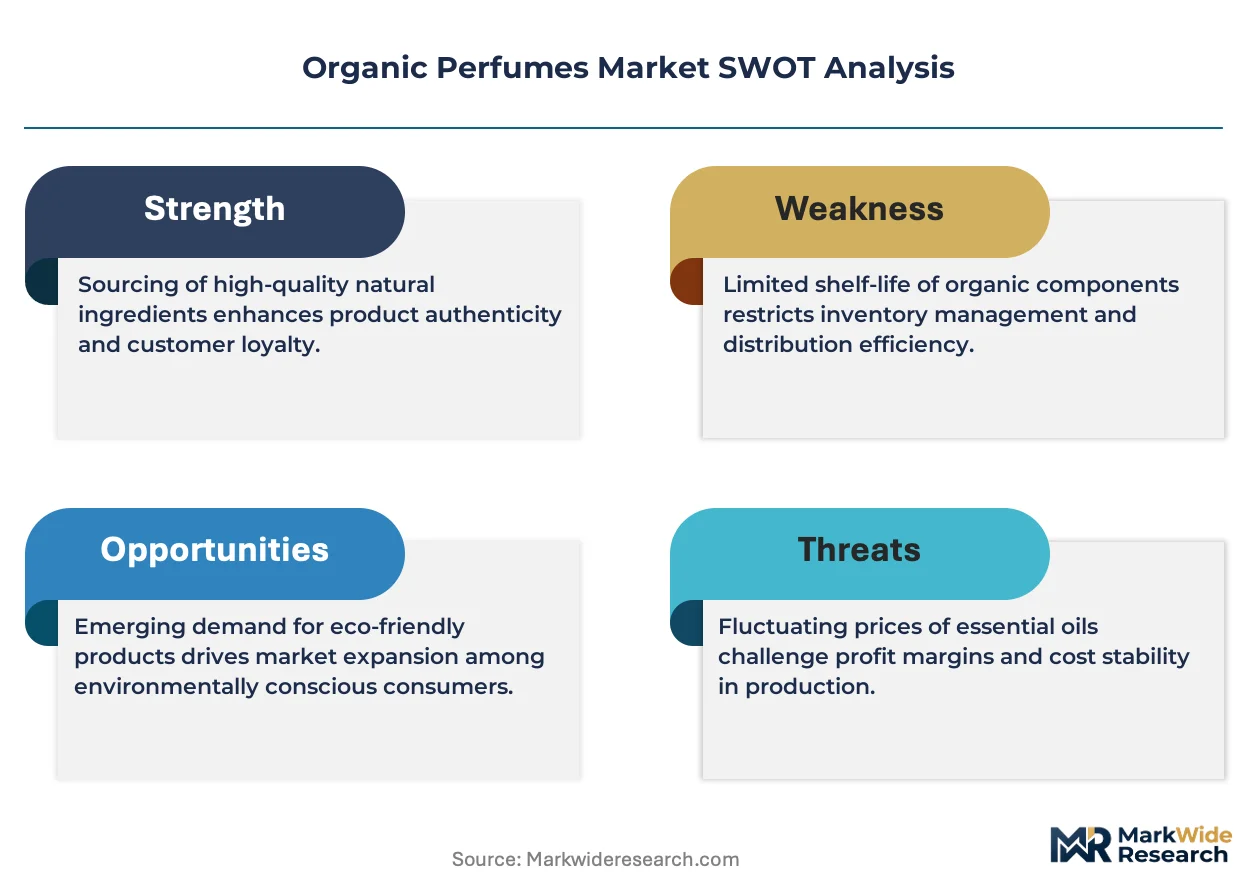
Refillable and modular fragrance systems is recalibrating how consumers build scent wardrobes across price tiers. Henry Rose leverages direct-to-consumer channels to sustain premium positioning with full ingredient transparency. Robertet anchors supply security through captive cultivation of botanicals across multiple growing regions. Aesop competes on minimalist aesthetic and controlled retail environments that reinforce brand discipline.
Organic perfumes are scent compositions derived from naturally sourced essential oils, absolutes, and plant extracts without synthetic aroma chemicals or petrochemical fixatives, typically achieving concentration levels between 15% and 30% aromatic compounds in an alcohol or oil base. These formulations serve consumers seeking reduced skin sensitization risk and traceable botanical provenance. Floral and woody fragrance types dominate current volume, with citrus gaining ground among younger demographics seeking lighter, gender-neutral profiles. Solid perfumes and roll-ons represent the fastest-expanding product forms, as portability and travel-friendly formats align with shifting usage occasions and reduced liquid-restriction friction.
REACH in Europe, FDA cosmetic labeling requirements in the United States, and ECHA substance restrictions collectively govern ingredient disclosure, allergen thresholds, and natural claim substantiation across major markets. Compliance costs favor larger houses with dedicated regulatory affairs capacity, while smaller labels navigate third-party certification complexity. Stakeholders must monitor evolving definitions of "natural" and "organic" across jurisdictions, as divergent standards threaten cross-border positioning and formulation consistency.
Market Dynamics
REACH compliance deadlines and EU Green Deal mandates are compressing formulation timelines while simultaneously opening premium positioning for houses that achieve early certification. Grasse-based distillers now operate as strategic chokepoints in natural essence supply.
Growth Catalysts
- EU Green Deal mandates:Binding sustainability targets across member states accelerate R&D investment in biodegradable fixatives and solvent systems. France's regulatory leadership creates certification templates adopted by neighboring markets.
- Millennial and Gen Z buyer concentration:Premium unisex fragrance demand concentrates in North America and Western Europe, where direct-to-consumer channels enable full ingredient transparency and subscription-based scent discovery.
- Solid perfume formats:Roll-on and portable delivery systems reduce liquid-restriction friction at airports, expanding usage occasions into travel and workplace touch-up contexts.
Market Restraints
- Natural essence supply concentration:Grasse-based distillers and select Mediterranean growers control 70% of premium botanical feedstock, creating vulnerability to climate volatility and harvest disruption.
- ECHA allergen thresholds:Restricted substance lists limit traditional floral absolutes, forcing reformulation of heritage compositions and raising development costs for smaller houses.
- Synthetic aroma chemical substitution:Lab-grown molecules from biotechnology firms offer cost advantages and batch consistency that pressure natural-only positioning at mass-market price points.
Strategic Opportunities
- India regulatory alignment:BIS standards development for natural cosmetics creates first-mover advantage for brands achieving dual EU-India certification ahead of formalized mutual recognition.
- Refillable modular systems:Hardware-plus-consumables business models extend customer lifetime value while supporting circular economy claims under emerging Extended Producer Responsibility frameworks.
- Solid perfume travel retail:TSA-friendly formats unlock duty-free channel expansion previously blocked by liquid volume restrictions, particularly in Middle Eastern and Asian hub airports.
Industry Challenges
- Natural claim substantiation:Divergent definitions of "organic" across FDA, ECHA, and ISO 16128 standards create cross-border labeling complexity and enforcement risk.
- Regulatory affairs capacity scarcity:Smaller houses lack dedicated compliance teams, forcing reliance on expensive third-party certification bodies and delaying market entry timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Perfumes Market |
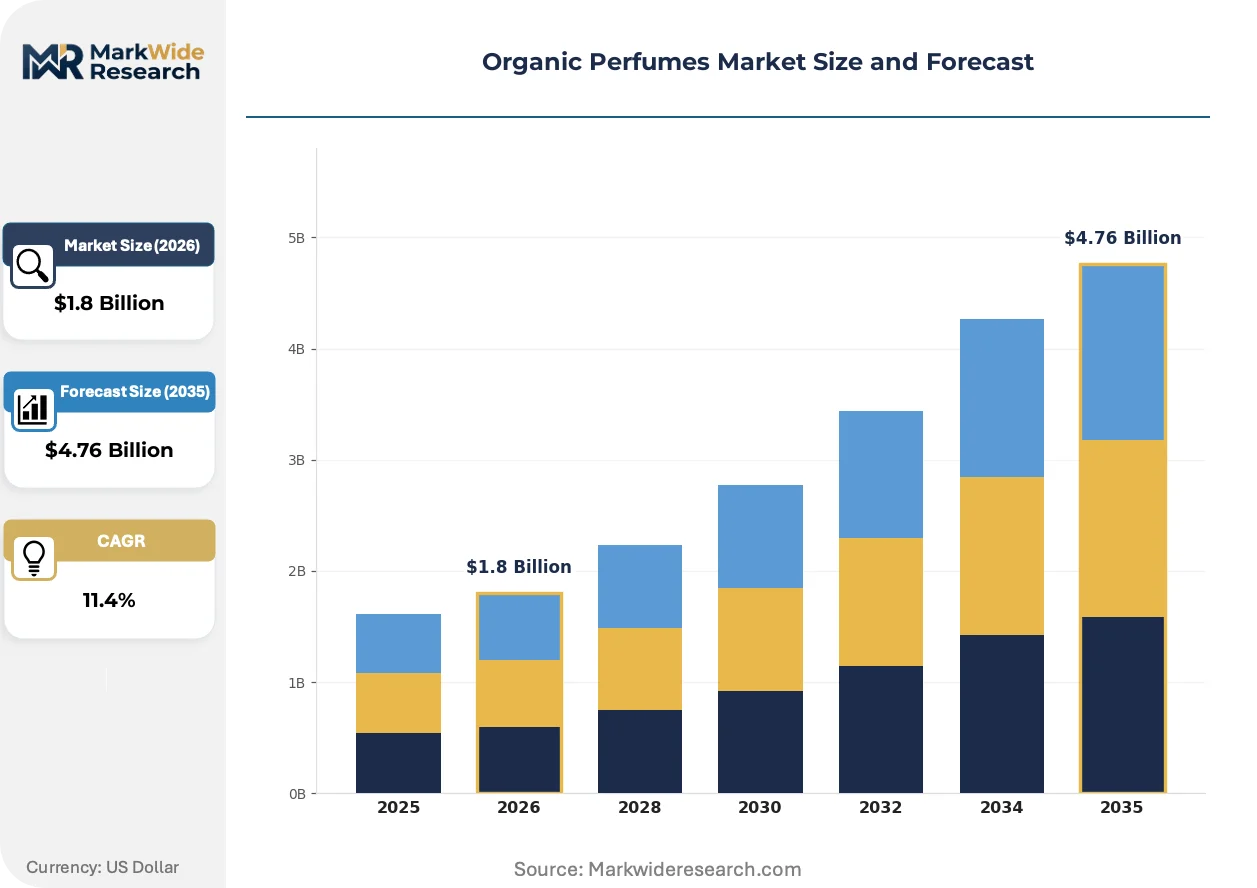
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fragrance Type: Floral, Woody, Citrus, Spicy Product Form: Sprays, Roll-ons, Oils, Solid Perfumes End User: Women, Men, Unisex, Kids Packaging Type: Glass Bottles, Recycled Materials, Eco-friendly Containers, Sample Sizes |
| Companies Covered | Henry Rose, Aesop, Esas Organic Perfumes, Robertet, Wit & West, Inkling Scents, PHLUR, House of Linnic, Evanhealy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Perfumes Market Evolving Landscape
Biotechnology-derived botanicals and modular hardware systems are rewriting production economics and customer relationships simultaneously. Three developments warrant particular attention.
Precision fermentation for rare molecules is converging with traditional distillation methods to resolve supply constraints for sandalwood, oud, and rose absolutes. Niche houses in France and California are piloting hybrid formulations that blend biotech ingredients with estate-grown botanicals. This convergence is compressing the price premium between scarce natural extracts and sustainable alternatives.
REACH authorization requirements for fragrance allergens are tightening disclosure thresholds and mandating quantitative ingredient lists on packaging. ECHA's 2023-2027 substance evaluation roadmap specifically targets synthetic musks and certain phthalate alternatives. Premium segments in Germany and the Netherlands are responding with full-transparency labeling that exceeds minimum requirements as a differentiation mechanism.
Subscription-based scent discovery platforms are displacing traditional counter sampling in millennial purchase journeys. Direct-to-consumer channels now capture significant share of first-time premium fragrance purchases, particularly for unisex and gender-fluid compositions. This shift concentrates most visibly in urban centers across the United States and United Kingdom, where digital-native brands bypass department store intermediaries entirely.
Organic Perfumes Market Segmentation
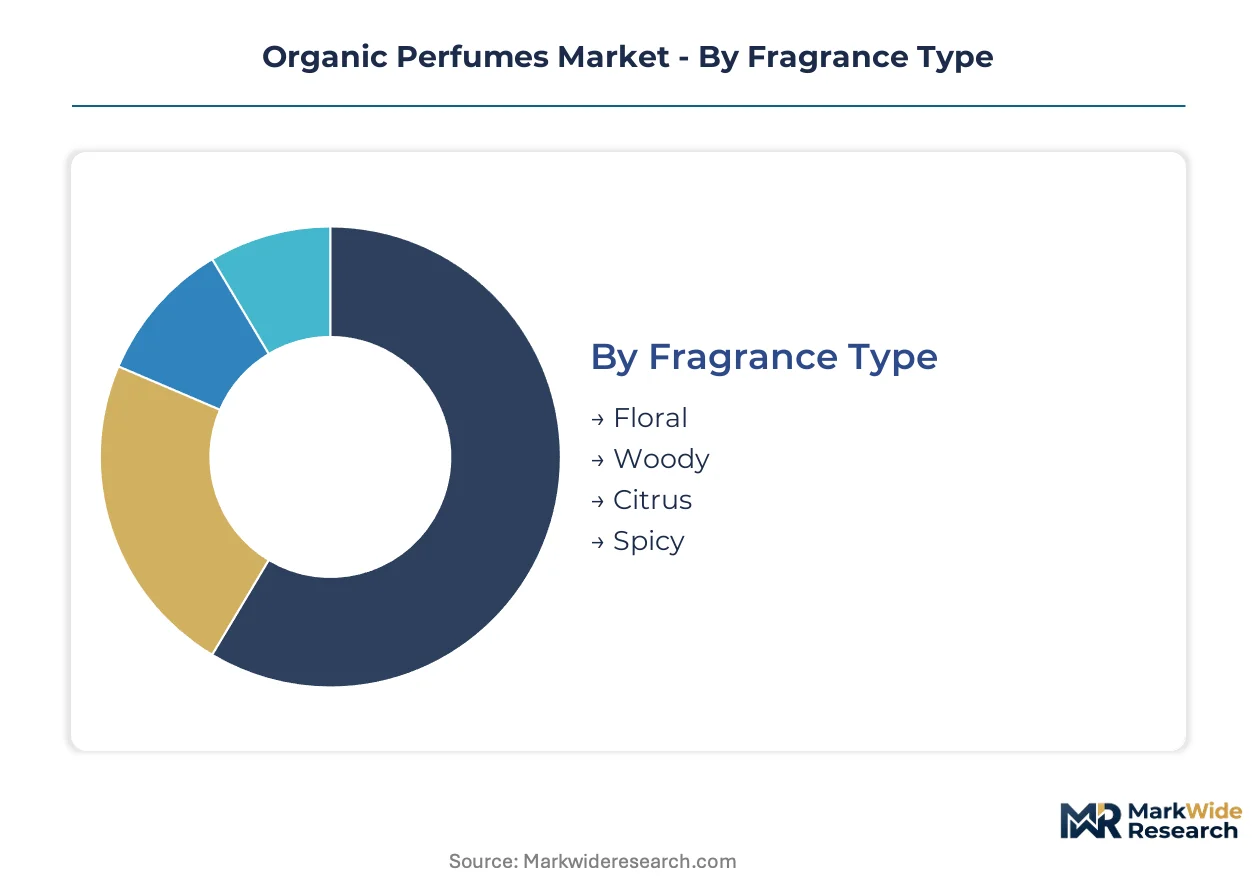
Segmentation in organic perfumes reveals how formulation philosophy, delivery mechanics, and user identity intersect to create distinct commercial battlegrounds. Each dimension carries regulatory and supply chain implications that reshape competitive positioning.
Fragrance Type:
Volume concentrates in mass-appeal profiles, while premium pricing accrues to scarcity-driven compositions with provenance narratives.
- Floral:Rose, jasmine, and neroli absolutes form the backbone of traditional organic perfumery, with Grasse-grown materials commanding price premiums. Demand clusters among heritage houses in France and heritage-seeking consumers in the United States, constrained by ECHA allergen thresholds that limit jasmine absolute concentrations.
- Woody:Sandalwood and cedar formulations anchor unisex and masculine-positioned lines, with Indian sandalwood plantations and Australian sustainable harvesting programs supplying certified feedstock. Supply security drives premium positioning as biotechnology firms introduce fermentation-derived alternatives.
- Citrus:Bergamot and neroli dominate lighter, workplace-appropriate compositions favored by younger demographics seeking gender-neutral profiles.
- Spicy:Cardamom, saffron, and cinnamon extracts serve niche positioning with limited cultivation regions creating natural supply caps.
Today's leader: Floral. Tomorrow's challenger: Woody.
Product Form:
Application mechanics determine regulatory pathway, with liquid formats facing stricter transport and labeling requirements than solids.
- Sprays:Alcohol-based aerosol delivery remains the volume standard, with formulation complexity rising as REACH restricts synthetic fixatives and propellant alternatives. German and Dutch markets now mandate quantitative ingredient disclosure exceeding minimum thresholds.
- Solid Perfumes:Wax and oil-based balms eliminate liquid-restriction friction at airports, expanding usage into travel and workplace touch-up contexts. Format adoption climbs fastest among millennial buyers in United Kingdom and United States urban centers.
- Roll-ons:Precision application and reduced evaporation losses appeal to value-conscious segments with portable usage occasions.
- Oils:Jojoba and fractionated coconut carriers serve skin-sensitive users and ritual-oriented application preferences in Middle Eastern markets.
Sprays retain volume dominance. Solid perfumes gain share fastest through travel-retail expansion.
End User:
Gender positioning is fragmenting as unisex formulations capture premium price tiers previously segmented by traditional masculine-feminine coding.
- Unisex:Gender-neutral compositions now command the fastest-expanding premium segment, with direct-to-consumer brands in California and United Kingdom bypassing department store intermediaries entirely. Subscription discovery platforms concentrate first-time purchases in this category.
- Women:Floral-dominant classics retain volume leadership in France and Italy, though heritage houses reformulate to reduce allergen loads under ECHA pressure.
- Men:Woody and spicy profiles anchor this segment, with solid perfume formats gaining traction for gym and travel contexts.
- Kids:Hypoallergenic positioning with minimal essential oil concentrations serves parental safety concerns, with French and Swiss pediatric certification standards setting quality benchmarks.
Unisex claims the steepest expansion trajectory. Women's retains absolute volume.
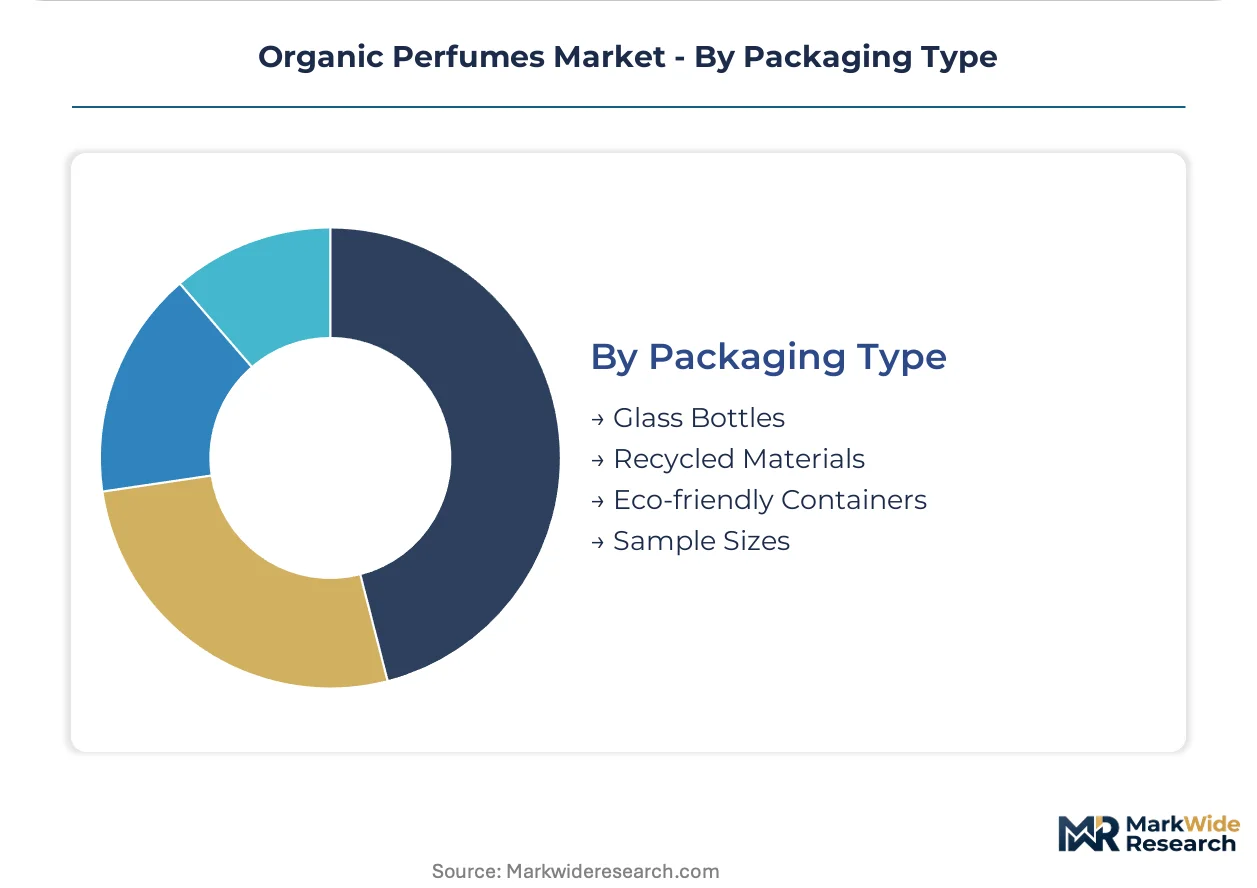
Packaging Type:
Material choice directly impacts circular economy compliance under emerging Extended Producer Responsibility frameworks.
- Glass Bottles:Borosilicate and recycled glass remain the prestige standard, with refillable modular systems extending customer lifetime value. Italian and French glassworks supply premium decoration capabilities.
- Recycled Materials:Post-consumer plastic and aluminum alternatives serve mid-tier positioning with sustainability claims requiring third-party certification to avoid greenwashing enforcement.
- Eco-friendly Containers:Biodegradable polymers and mushroom-based packaging pilot with limited scale, constrained by shelf-life performance and cost premiums.
- Sample Sizes:Miniature formats drive discovery and subscription economics, with solid perfume samples eliminating leakage risk in postal distribution.
Glass bottles defend premium positioning. Recycled materials scale fastest through mass-market adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France established modern organic perfumery through Grasse-based distillers who pioneered steam distillation of jasmine and rose absolutes in the nineteenth century. This heritage concentration now shapes supply security debates as climate volatility threatens Mediterranean harvests.
France
Grasse-based distillers supply premium botanical feedstock to international fragrance houses, with estate-grown jasmine and tuberose commanding price premiums. REACH authorization requirements and EU Green Deal mandates compress formulation timelines for exports. The Provence-Alpes-Côte d'Azur cluster anchors natural essence production, where Robertet maintains captive cultivation across multiple growing regions.
United States
Millennial and Gen Z buyers in California and New York Metro drive direct-to-consumer premium unisex fragrance adoption. FDA cosmetic labeling requirements govern ingredient disclosure thresholds, though California's stricter Proposition 65 enforcement creates additional compliance layers. Henry Rose leverages full transparency positioning through digital-native channels that bypass department store intermediaries entirely.
Germany
Quantitative ingredient disclosure mandates in German and Dutch markets exceed EU minimums, creating premium differentiation for compliant brands. ECHA's 2023-2027 substance evaluation roadmap targets synthetic musks and phthalate alternatives. The North Rhine-Westphalia region concentrates regulatory affairs capacity for mid-sized houses navigating certification complexity.
United Kingdom
Urban centers in London and Manchester show fastest solid perfume format adoption among millennial buyers seeking travel-friendly applications. Post-Brexit regulatory divergence from REACH creates dual compliance burdens for exporters. British fragrance startups occupy subscription discovery platforms that displace traditional counter sampling in first-time premium purchases.
India
BIS standards development for natural cosmetics creates first-mover positioning for brands achieving dual EU-India certification ahead of formalized mutual recognition. Domestic demand for traditional attar formulations overlaps with modern organic positioning in Maharashtra and Karnataka. Mumbai-based distributors increasingly serve as gateways for European houses entering South Asian markets.
Organic Perfumes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and supply chain control dimensions. The vendor base organizes around three strategic archetypes: heritage houses with captive botanical cultivation, digital-native direct-to-consumer brands, and biotechnology-enabled hybrid formulators. Consolidation pressures concentrate among mid-tier players lacking dedicated regulatory affairs capacity. Dominant competitive moves include backward integration into estate-grown feedstock and hardware-plus-consumables business model expansion.
Within the heritage house tier, Robertet exemplifies upstream control through captive cultivation networks. Among digital-native challengers, Henry Rose and Aesop occupy positions defined by channel strategy and aesthetic discipline respectively. These three companies represent distinct competitive vectors: supply security through botanical ownership, transparency through direct consumer relationships, and brand coherence through controlled retail environments.
| Leading Market Players |
|---|
| Henry Rose |
| Aesop |
| Esas Organic Perfumes |
| Robertet |
| Wit & West |
| Inkling Scents |
| PHLUR |
| House of Linnic |
| Evanhealy |
| Others |
Value Network & Pricing Analysis
Jasmine absolute price indices from Grasse-based distillers cascade through formulation tiers, compressing margins at mass-market levels while amplifying premium positioning for houses with captive cultivation or biotech substitution capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and botanical provenance traceability. Price differentiation hinges on EU organic certification tier and estate-grown feedstock documentation, with REACH compliance costs widening spreads between verified and conventional natural claims. Pricing pressure stems from biotechnology-derived molecule substitution at mid-tier price points. Mass-market buyers exhibit highest price sensitivity, while heritage-seeking consumers in France and California absorb premiums for Grasse-provenance absolutes.
Supply Chain Analysis
Freight cost volatility for temperature-controlled botanical shipments from France, India, and Australia compresses margin buffers for non-integrated houses. Raw material sourcing centers on jasmine and rose absolutes from Grasse, sandalwood from Indian plantations and Australian sustainable harvests, and cardamom from Guatemala and India. Single-source vulnerability concentrates in Grasse-based distillers controlling premium floral feedstock. Distribution runs through direct-to-consumer channels for digital-native brands and controlled retail environments for heritage houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic perfumes market compounds steadily as regulatory tailwinds from REACH and EU Green Deal mandates institutionalize premium positioning for compliant formulations.
For Market Incumbents: Extend backward integration into estate-grown botanicals across multiple climate zones to hedge harvest volatility. Lock in long-term offtake agreements with Grasse distillers before biotechnology substitution erodes scarcity premiums. Prioritize regulatory affairs capacity expansion to navigate divergent natural claim standards across FDA, ECHA, and BIS jurisdictions.
For New Entrants and Emerging Players: BIS standards development in India opens a window for dual EU-India certification positioning ahead of formalized mutual recognition. Target solid perfume formats in United Kingdom and United States urban centers where travel-friendly applications and subscription discovery platforms concentrate millennial first purchases. Launch through direct-to-consumer channels with full ingredient transparency to bypass department store margin extraction.
For Investors and Strategic Acquirers: Asymmetric upside sits with biotechnology-enabled hybrid formulators bridging natural scarcity and sustainable scale. Five-to-ten-year viability favors houses combining precision fermentation capabilities with heritage brand equity. Monitor ECHA substance evaluation roadmap progression for synthetic musk restrictions as inflection indicator for natural-only positioning premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Estate Cultivation | Robertet's captive growing regions across Provence and Madagascar secure jasmine supply against climate volatility. |
| Biotechnology-Derived Molecule Adoption | Precision fermentation for sandalwood and oud absolutes compresses price premiums between scarce extracts and sustainable alternatives. |
| Direct-to-Consumer Channel Expansion | Henry Rose's transparency positioning through digital-native platforms bypasses department store intermediaries entirely. |
| Refillable Modular Hardware Systems | Hardware-plus-consumables models extend customer lifetime value under emerging Extended Producer Responsibility frameworks. |
| Dual Certification Investment | Early BIS-EU alignment in India creates first-mover positioning before formalized mutual recognition agreements. |
Research Methodology
Direct dialogue with fragrance house R&D directors, regulatory affairs leads at mid-sized organic labels, Grasse-based distiller operations managers, and subscription platform founders grounded qualitative findings. Secondary validation drew from REACH substance evaluation databases, ECHA allergen threshold documentation, BIS natural cosmetics standards drafts, and customs records for essential oil imports. Bottom-up volume modeling triangulated against top-down category spending estimates from retail audit data.
Top-down market sizing anchored aggregate value estimates across the analysis window, segmented by fragrance type, product form, end user positioning, and packaging material. CAGRs derived from regression analysis against historical premium fragrance category growth rates, adjusted for regulatory acceleration effects and format substitution patterns. Forecast inputs incorporated biotechnology adoption curves for rare molecules and Extended Producer Responsibility implementation timelines.
Revisions become necessary when ECHA substance restrictions expand beyond current allergen thresholds, when climate events disrupt Mediterranean harvests, or when BIS-India mutual recognition accelerates faster than modeled. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Kuwait Perfume Market
Fragrances & Perfumes
Global Fragrances and Perfumes Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Home Fragrance Diffusers Market
Fragrances & Perfumes
Reed Diffusers Market
Fragrances & Perfumes
GCC Perfume and Fragrance Market
Fragrances & Perfumes
Smart Fragrance Box Market
Fragrances & Perfumes
Fragrance Diffuser Market
Fragrances & Perfumes
Home Fragrance Market
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Wax Melts Market
Fragrances & Perfumes
Gourmand Fragrance Market
Fragrances & Perfumes
Digital Fragrance Market
Fragrances & Perfumes
Global Luxury Perfumes Market
Fragrances & Perfumes
Saudi Arabia E-Commerce Cosmetics and Fragrances Market
Fragrances & Perfumes
Saudi Arabia Perfume Market