
 Scented Oil Market | 2026-2036
Scented Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Scented Oil Market Analytics
The EU Green Deal is recalibrating raw material sourcing across European fragrance supply chains. Givaudan leverages biotechnology platforms to secure renewable feedstock pathways. Robertet SA anchors its position through vertically integrated cultivation in Grasse. Firmenich SA differentiates via carbon-neutral manufacturing certifications.
Scented oils comprise volatile aromatic compounds extracted through steam distillation, cold pressing, or solvent extraction, typically diluted in carrier substrates for safe topical or ambient application. Essential oils command premium positioning due to therapeutic-grade certification requirements and limited agricultural yields. Fragrance oils dominate volume in home fragrance and mass personal care, where synthetic consistency lowers unit costs. Carrier oils capture expanding margin pools as clean-label cosmetics brands demand traceable botanical bases.
REACH in Europe and FDA fragrance allergen labeling rules in the United States shape ingredient disclosure and reformulation cycles across the industry. ECHA's expanding SVHC candidate list pressures suppliers to substitute certain synthetic musks and phthalates. China's SAMR cosmetic ingredient registration requirements add compliance layers for imported scented oil formulations. Stakeholders must monitor regulatory divergence between jurisdictions to avoid fragmented product portfolios and duplicated testing expenditures.
Market Dynamics
Biotechnology platforms are restructuring feedstock security across fragrance supply chains, displacing traditional agricultural extraction with microbial fermentation and enzymatic synthesis. This shift compresses harvest-dependent volatility while introducing new capital intensity thresholds.
Growth Catalysts
- EU Green Deal compliance mandates:REACH reformulation deadlines accelerate renewable feedstock adoption across European compound manufacturing. Suppliers retrofit solvent extraction infrastructure to meet ECHA SVHC substitution timelines.
- Wellness center service expansion:North American spa and hospitality chains embed aromatherapy protocols into standardized treatment menus. This institutionalizes recurring bulk oil procurement outside traditional retail channels.
- China tier-one city penetration:Shanghai and Beijing households deepen home fragrance adoption faster than national averages. Urban retail density supports specialty oil boutique expansion.
Market Restraints
- Lavender and rose agricultural yield volatility:Climate stress in Provence and Bulgarian growing regions concentrates supply risk. Limited cultivable acreage caps premium essential oil volumes regardless of price signals.
- Synthetic musk substitution pressure:ECHA's expanding SVHC candidate list forces reformulation of legacy fragrance bases. Compliance-driven ingredient swaps disrupt established scent profiles and consumer recognition.
- Carrier oil traceability cost inflation:Clean-label cosmetics brands demand blockchain-verified botanical sourcing. Smallholder farm aggregation and documentation layers add 15-25% procurement overhead.
Strategic Opportunities
- India ayurvedic export channel development:BIS certification alignment unlocks institutional spa and pharmaceutical offtake for traditional oil blends. Regulatory harmonization with CDSCO cosmetic ingredient rules reduces market entry friction.
- Carbon-neutral manufacturing certification:EU CSRD disclosure requirements create tiered supplier preference for verified low-carbon production. Early certifiers capture premium positioning in European personal care procurement.
- Biotechnology-terpene synthesis convergence:Microbial production of rare sesquiterpenes bypasses agricultural bottlenecks. Givaudan and Firmenich platform investments signal commercial viability timelines.
Industry Challenges
- Cosmetic toxicologist talent scarcity:FDA fragrance allergen labeling rules and SAMR registration requirements demand specialized safety assessment capacity. Recruitment lags regulatory complexity expansion.
- Multi-jurisdiction testing duplication:Divergent REACH, FDA, and SAMR disclosure standards fragment product portfolios. Parallel safety studies inflate new formulation launch costs.
- Cold-press equipment capex intensity:Citrus oil quality premiums require proprietary extraction infrastructure. Mid-scale processors face margin compression against vertically integrated competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scented Oil Market |
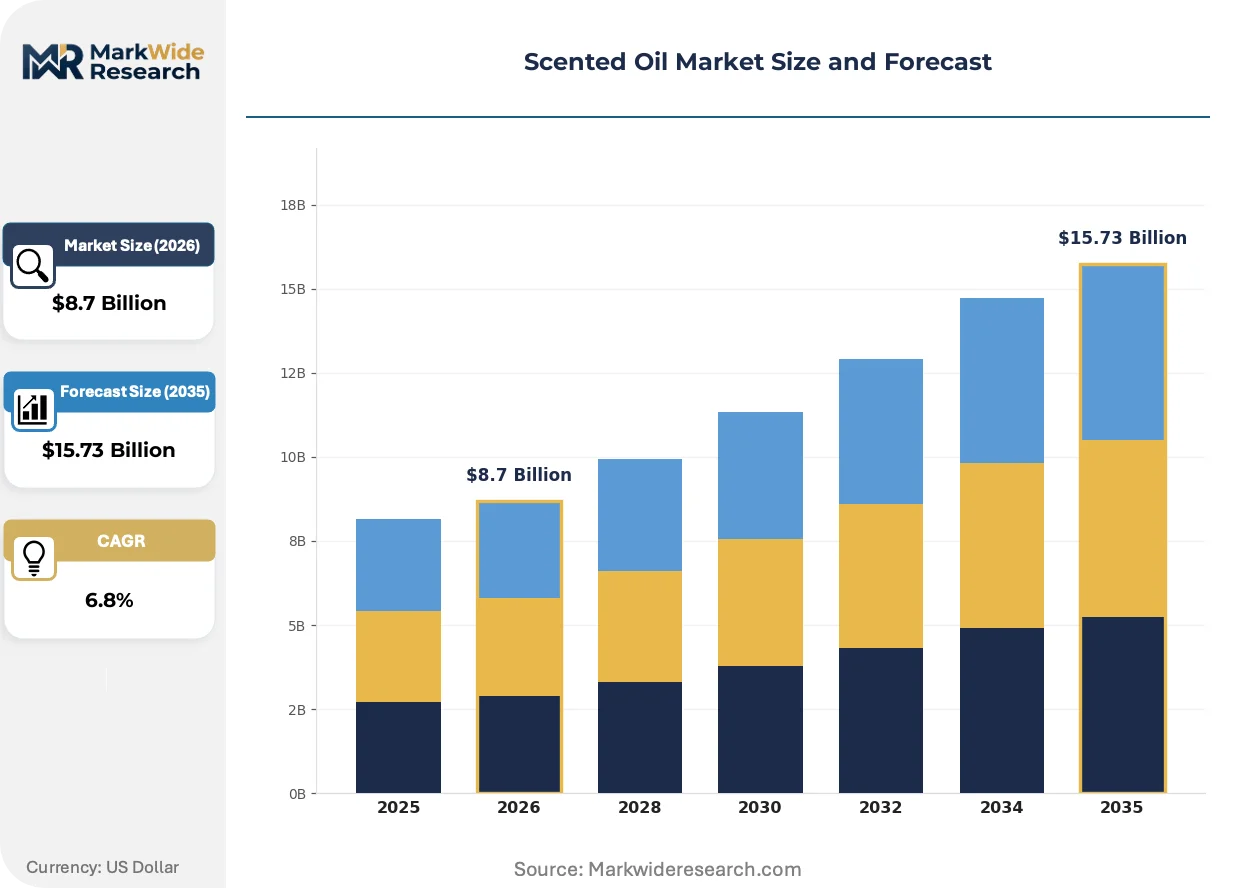
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Fragrance Oils, Carrier Oils, Blend Oils Application: Aromatherapy, Cosmetics, Home Fragrance, Personal Care Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Households, Beauty Salons, Wellness Centers, Spa Facilities |
| Companies Covered | Givaudan, Symrise, International Flavors & Fragrances Inc., Robertet SA, Mane SA, doTERRA, Young Living Essential Oils, Sensient Technologies Corporation, Firmenich SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scented Oil Market Evolving Landscape
Digital traceability infrastructure and biotechnology fermentation are compressing traditional agricultural dependencies while regulatory disclosure mandates reshape supplier qualification criteria. These forces simultaneously enable new market entrants and raise operational complexity.
Enzymatic terpene synthesis is decentralizing rare compound production away from concentrated growing regions. Specialty chemical producers in the Netherlands and Germany adopt continuous fermentation systems for linalool and geraniol. This technology is decentralizing supply risk from climate-vulnerable lavender and rose harvests toward controlled bioreactor environments.
REACH authorization timelines are compressing synthetic musk availability across European formulations. ECHA's 2023-2025 SVHC roadmap accelerates phthalate and nitro-musk substitution programs. Fine fragrance houses in France and Germany absorb the highest compliance costs, diverting R&D budgets toward bio-identical replacements.
Direct-to-spa subscription models are displacing traditional distributor intermediaries in North American wellness procurement. Chains like Equinox and Canyon Ranch negotiate annual volume contracts with compounders for proprietary blend exclusivity. This concentration is most visible in California and New York metro markets where hospitality procurement centralizes.
Scented Oil Market Segmentation
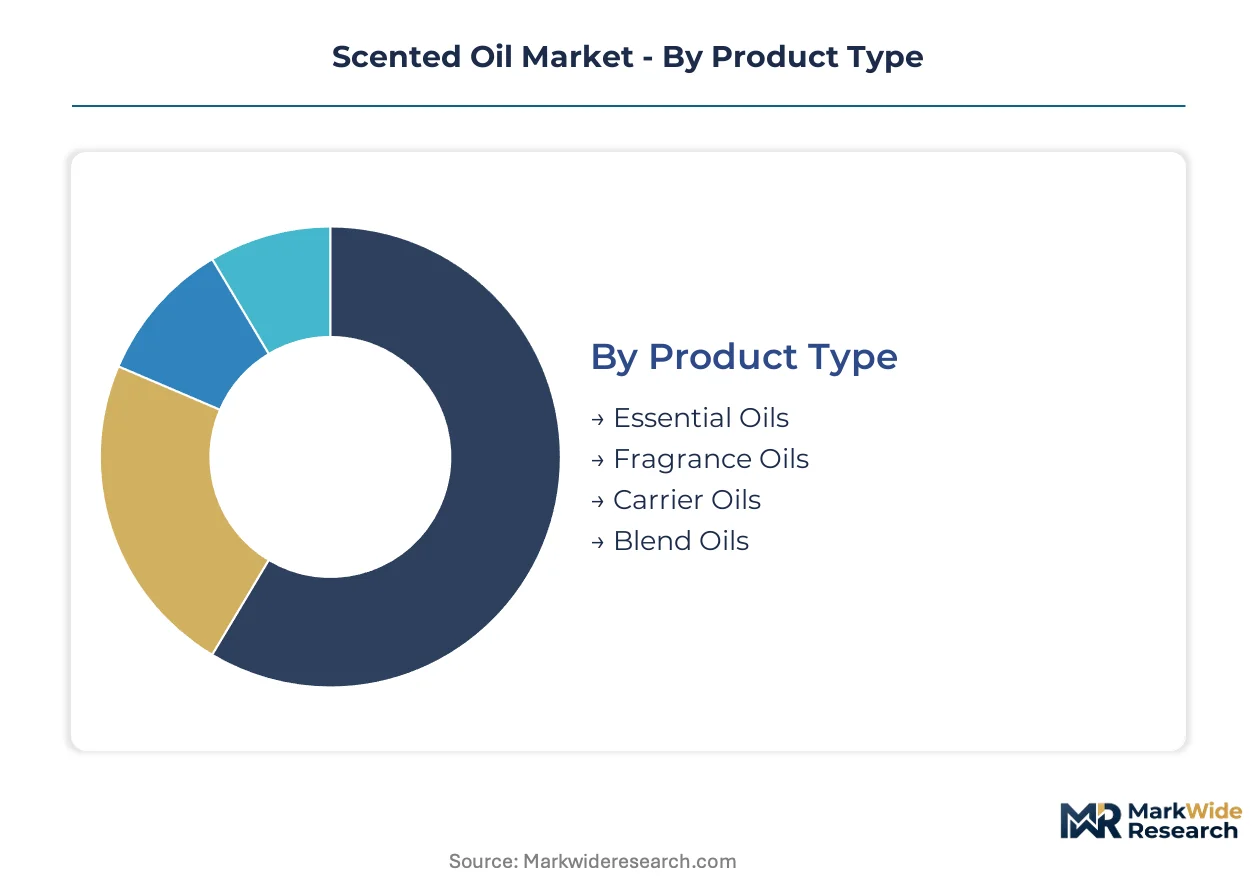
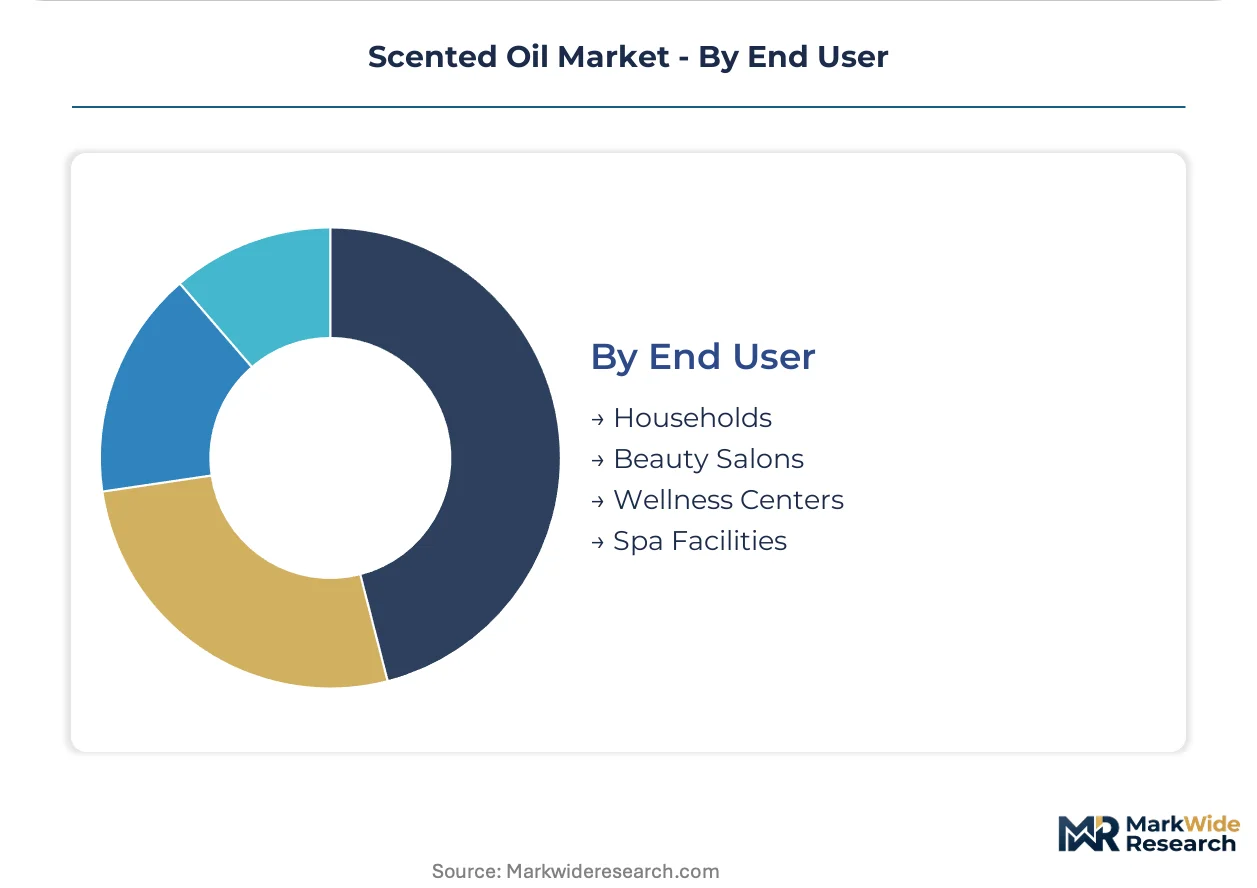
Scented oil purchasing decisions split across therapeutic efficacy, ambient application, and professional service integration. Each segment carries distinct margin profiles and regulatory exposure that reshape supplier portfolio priorities.
Product Type:
Premium positioning and certification requirements drive buyer selection across extraction methods and dilution standards.
- Essential Oils:Pure volatile aromatic compounds extracted via steam distillation, cold pressing, or CO2 extraction without synthetic alteration. Demand concentrates in wellness centers across California and New York where therapeutic-grade certification commands treatment menu premiums. Agricultural yield limits in Provence and Bulgaria constrain volume regardless of price signals.
- Fragrance Oils:Synthetic or nature-identical aromatic compounds engineered for batch consistency and cost efficiency. Home fragrance manufacturers in China's tier-one cities prioritize these for diffuser and candle applications where olfactory stability outweighs natural provenance. REACH SVHC substitution timelines are forcing reformulation of legacy musk bases.
- Carrier Oils:Botanical base substrates diluting concentrated aromatic compounds for safe topical application. Clean-label cosmetics brands demand blockchain-verified sourcing from specific cultivars.
- Blend Oils:Pre-formulated combinations targeting specific therapeutic or ambient outcomes. Direct-to-spa subscription models favor proprietary house blends for treatment protocol standardization.
Fragrance oils lead on scale; essential oils lead on momentum.
Application:
End-use environment determines formulation complexity, dosing precision, and regulatory scrutiny intensity.
- Aromatherapy:Therapeutic deployment of inhaled or topically applied aromatic compounds for wellness outcomes. North American spa chains embed standardized protocols into membership offerings, institutionalizing bulk procurement outside retail channels. FDA fragrance allergen labeling rules complicate therapeutic claim substantiation.
- Cosmetics:Integration into skincare, haircare, and color formulations where scent functions as sensory enhancement or active ingredient. EU CSRD disclosure requirements favor suppliers with carbon-neutral manufacturing certifications.
- Home Fragrance:Ambient scenting through candles, diffusers, and room sprays for residential and hospitality environments. Shanghai and Beijing households are expanding adoption fastest, supporting specialty boutique retail density.
- Personal Care:Daily-use products including soaps, shampoos, and deodorants where fragrance load affects formulation stability. SAMR cosmetic ingredient registration adds compliance layers for imported formulations entering China.
Personal care dominates volume throughput; aromatherapy shows steepest expansion trajectory.
Distribution Channel:
Channel selection reflects purchase frequency, education requirements, and margin capture strategy.
- Online Retail:E-commerce platforms and direct-to-consumer websites offering subscription models and educational content. Specialty oil boutiques leverage digital infrastructure to bypass traditional distributor markups.
- Supermarkets:Mass-market retail placement for standardized home fragrance and personal care SKUs. Shelf space competition favors fragrance oils with synthetic consistency and lower unit costs.
- Specialty Stores:Curated physical retail emphasizing therapeutic consultation and premium extraction storytelling. Urban retail density in tier-one Chinese cities supports experiential format expansion.
- Direct Sales:Bulk contracts negotiated directly with compounders by hospitality chains and wellness institutions. Equinox and Canyon Ranch structures in California and New York concentrate annual volume procurement.
Online retail is gaining share fastest; direct sales captures margin concentration.
End User:
User type dictates order size, formulation customization, and technical support requirements.
- Households:Individual consumers purchasing for personal aromatherapy, home fragrance, and DIY cosmetic applications. China's tier-one cities show deepest penetration as urban retail infrastructure matures.
- Beauty Salons:Service providers integrating scented oils into hair and nail treatments. BIS certification alignment unlocks institutional offtake for traditional oil blends in Indian export channels.
- Wellness Centers:Facilities offering structured aromatherapy protocols as core service offerings. North American expansion embeds recurring bulk procurement into standardized treatment menus.
- Spa Facilities:Hospitality-integrated operations requiring proprietary blend exclusivity and supply security. Annual volume contracts displace traditional distributor intermediaries in concentrated metro markets.
Households anchor volume scale; wellness centers drive contract structure innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grasse in southern France established the modern fragrance extraction industry during the 16th century, with steam distillation techniques spreading to Bulgaria's rose valleys and India's ayurvedic centers by the early 20th century.
France
Provence-Alpes-Côte d'Azur hosts the world's densest concentration of fragrance compounders, with Grasse retaining preeminent cultivation infrastructure for jasmine and rose absolute extraction. REACH authorization timelines force reformulation of legacy musk bases across fine fragrance houses. Paris-based compounders absorb disproportionate compliance costs while maintaining luxury positioning.
United States
California and New York metro wellness chains institutionalize aromatherapy protocols, embedding recurring bulk procurement for essential oil blends. FDA fragrance allergen labeling rules complicate therapeutic claim substantiation for topical applications. Direct-to-spa subscription models concentrate annual volume contracts in Los Angeles and Manhattan hospitality corridors.
China
Shanghai and Beijing households deepen home fragrance adoption faster than national penetration averages, supporting specialty oil boutique retail density. SAMR cosmetic ingredient registration adds compliance layers for imported formulations entering through Yangtze River Delta ports. NMPA alignment with international standards reduces market entry friction for European compounders.
India
Maharashtra and Karnataka anchor ayurvedic oil processing infrastructure for export channel development into institutional spa markets. BIS certification alignment with CDSCO cosmetic ingredient rules streamlines pharmaceutical offtake negotiations. Traditional sandalwood and jasmine extraction clusters in Tamil Nadu face raw material scarcity from protected species regulations.
Germany
Baden-Württemberg specialty chemical producers adopt continuous fermentation systems for linalool and geraniol synthesis, decentralizing supply risk from agricultural harvests. ECHA's expanding SVHC candidate list accelerates phthalate substitution programs across fragrance compound manufacturing. Cologne-based distributors manage European logistics for REACH-compliant formulations.
Scented Oil Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the scented oil value chain, with agricultural cultivators and biotechnology platforms occupying distinct risk-return profiles. The supplier base stratifies between vertically integrated Grasse-based houses controlling raw material provenance and formulation specialists outsourcing extraction to contract manufacturers. Three archetypes dominate: heritage compounders with captive cultivation assets, biotechnology platforms synthesizing rare terpenes through microbial fermentation, and direct-to-consumer wellness brands bypassing traditional distribution. Competitive intensity concentrates on securing renewable feedstock pathways and obtaining carbon-neutral manufacturing certifications ahead of EU CSRD disclosure mandates.
Within the heritage compounder tier, Givaudan and Firmenich SA exemplify biotechnology platform investments signaling commercial viability timelines for enzymatic terpene synthesis. Robertet SA occupies a position anchored through vertically integrated cultivation infrastructure in Provence. These three Swiss and French entities represent contrasting strategic postures on feedstock security amid climate stress in traditional growing regions.
| Leading Market Players |
|---|
| Givaudan |
| Symrise |
| International Flavors & Fragrances Inc. |
| Robertet SA |
| Mane SA |
| doTERRA |
| Young Living Essential Oils |
| Sensient Technologies Corporation |
| Firmenich SA |
| Others |
Value Network & Pricing Analysis
Biotechnology fermentation platforms are compressing cost curves for rare terpenes while simultaneously redistributing supply risk from climate-vulnerable lavender and rose harvests toward controlled bioreactor environments in Germany and the Netherlands. This dual shift weakens traditional agricultural pricing power in Provence and Bulgaria while elevating capital-intensive microbial producers to premium positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates therapeutic-grade essential oils certified for spa protocols from fragrance oils with synthetic consistency and mass-market carrier substrates. Price differentiation rests on certification grade and volume scale, with wellness centers absorbing premiums for batch-traceable blends while home fragrance manufacturers prioritize unit economics. Cost compression in fragrance oils is intensifying because REACH SVHC substitution timelines force R&D budget reallocation. Household consumers in China's tier-one cities show highest price sensitivity, whereas North American spa chains demonstrate lowest sensitivity due to treatment menu premiumization.
Supply Chain Analysis
Dual-sourcing requirements from European fine fragrance houses mandate multi-supplier qualification for jasmine absolute and rose otto, compressing single-origin dependency despite Grasse's cultivation heritage. Geographic supply concentrates in France, Bulgaria, and India for botanical extraction, with Germany and China anchoring biotechnology fermentation capacity. Raw material dependencies center on lavender buds, rose petals, sandalwood heartwood, and microbial feedstock substrates. Single-source vulnerability persists for protected-species sandalwood from Tamil Nadu. Distribution runs through Cologne-based logistics hubs for REACH-compliant formulations serving EU compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor biotechnology platforms and certified carbon-neutral producers as EU CSRD disclosure requirements tier supplier preferences. Clean-label cosmetics procurement is shifting toward blockchain-verified botanical sourcing that commands premium positioning.
For Market Incumbents: Lock in renewable feedstock pathways through captive cultivation contracts in Provence and Karnataka before climate stress intensifies agricultural yield volatility. Secure ECHA SVHC-compliant reformulation capacity ahead of authorization timelines that will disqualify legacy musk suppliers. Prioritize carbon-neutral manufacturing certification to capture tiered procurement preference from European personal care brands. For New Entrants and Emerging Players: Institutional wellness chains in California and New York represent the most penetrable buyer archetype, as direct-to-spa subscription models displace traditional distributor intermediaries. Target ayurvedic export channels into North American hospitality markets where BIS certification alignment unlocks bulk offtake. Pursue proprietary blend exclusivity contracts rather than commodity essential oil spot sales. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale biotechnology platforms because enzymatic terpene synthesis decentralizes supply risk from agricultural bottlenecks toward reproducible bioreactor output. Acquire fermentation specialists with commercial viability timelines for rare sesquiterpenes. Watch ECHA SVHC candidate list expansion velocity as inflection indicator for synthetic musk substitution demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Platform Investment | Microbial fermentation of linalool bypasses Provence harvest volatility for Givaudan and Firmenich. |
| Carbon-Neutral Certification | EU CSRD disclosure requirements create procurement preference for verified low-carbon production. |
| Direct-to-Spa Subscription Model | Equinox and Canyon Ranch structures concentrate annual volume contracts outside distributor channels. |
| Blockchain Traceability Infrastructure | Clean-label cosmetics brands demand documented provenance from specific sandalwood cultivars. |
| REACH Compliance Reformulation | ECHA SVHC substitution timelines force R&D reallocation toward bio-identical musk replacements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fragrance compounder procurement directors, wellness center operations managers, cosmetics brand supply chain leads, and ECHA regulatory affairs specialists with secondary validation from customs trade data, SEC filings of listed flavor and fragrance houses, REACH registration dossiers, and CDSCO cosmetic ingredient databases. Bottom-up volume modeling triangulated against top-down market sizing.
Segment-weighting approaches distributed value across extraction method, certification grade, and end-use application intensity throughout the forecast period. CAGRs derived from historical volatility patterns in agricultural yields and biotechnology capacity expansion timelines. Industry-specific inputs included lavender and rose harvest forecasts from Provence and Bulgarian growing regions, plus SAMR cosmetic ingredient registration pipeline status.
Underlying measurement precision varies by segment; biotechnology fermentation volumes carry tighter precision than agricultural essential oil harvests subject to climate stress. Forecasts reflect assumptions on regulatory authorization timelines and substitution program adoption rates. Deviation in ECHA SVHC candidate list expansion velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Evaporative Diffusers Market
Fragrances & Perfumes
GCC Perfume and Fragrance Market
Fragrances & Perfumes
Smart Fragrance Box Market
Fragrances & Perfumes
Home Fragrance Market
Fragrances & Perfumes
Global Perfume Market
Fragrances & Perfumes
Fragrance Product Market
Fragrances & Perfumes
Perfume Vials Market
Fragrances & Perfumes
North America Perfume Market
Fragrances & Perfumes
Digital Fragrance Market
Fragrances & Perfumes
Natural Fragrance Market
Fragrances & Perfumes
GCC Perfume Market
Fragrances & Perfumes
Digital Perfume Market
Fragrances & Perfumes
Reed Diffusers Market