
 Baby Digital Monitor Market | 2026-2036
Baby Digital Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Digital Monitor Market Insights
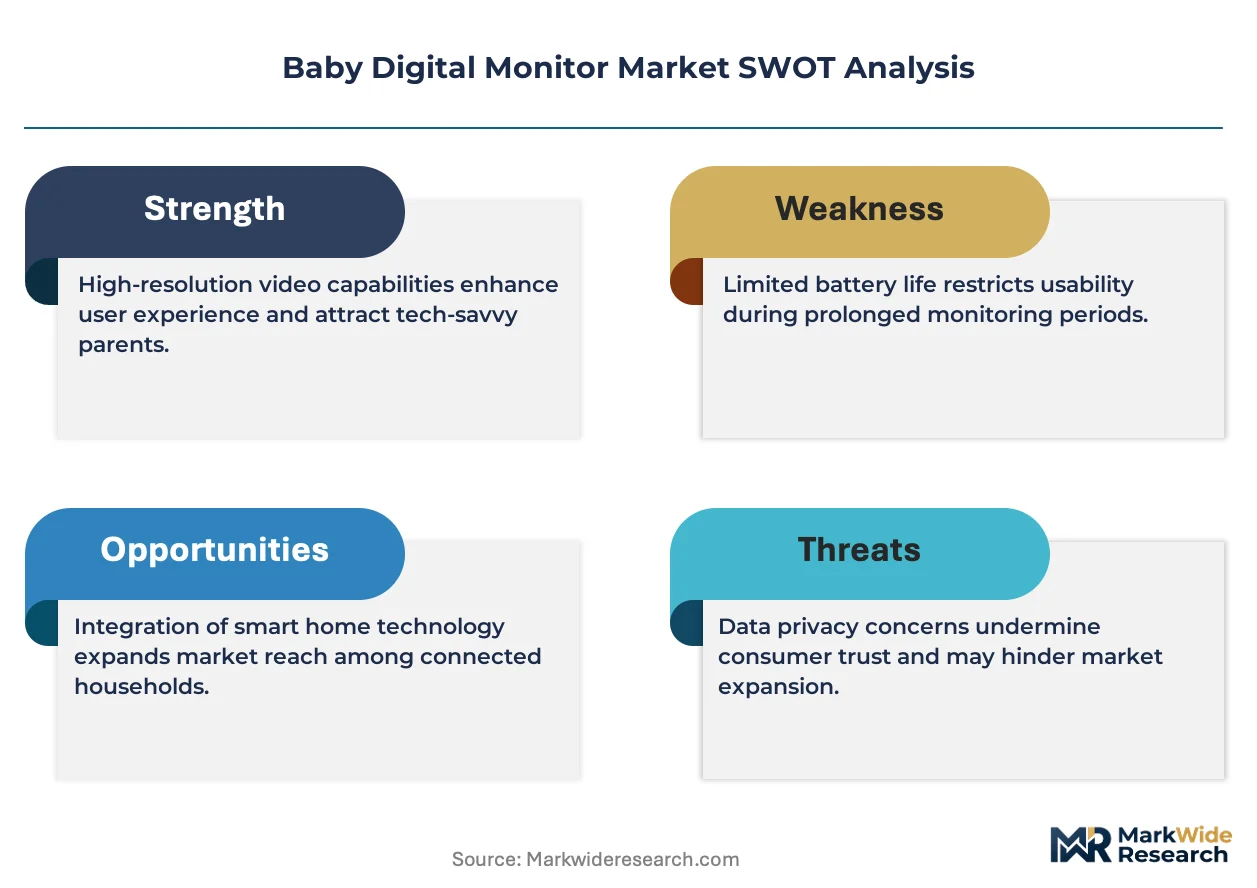
Modular bundling of wearable sensors with video base stations is hardening as the dominant product configuration. VTech Communications Inc. leverages its vertically integrated manufacturing in Southeast Asia to control costs across audio and video monitor lines. Koninklijke Philips NV sustains premium positioning through hospital-grade sensor calibration that extends into its consumer portfolio. Nanit competes on software-layer differentiation, offering sleep analytics subscriptions that anchor recurring revenue per installed unit.
A baby digital monitor is an electronic device transmitting audio, video, or biometric data from an infant's environment to a parent receiver, typically operating on radio frequencies between 1.9 GHz and 2.4 GHz with encrypted signal protocols to prevent interception. These devices serve the primary commercial purpose of enabling remote infant supervision while reducing parental anxiety and sudden infant death syndrome risk through real-time alerting. Smart monitors incorporating machine-learning breathing pattern analysis now command the highest margin pools as parents prioritize proactive health monitoring over passive surveillance. Wi-Fi-enabled units are expanding fastest in North American and European households where broadband penetration supports cloud-connected nursery ecosystems, while DECT-based audio monitors remain the mature, price-competitive baseline in emerging markets.
The Federal Communications Commission governs radio frequency emissions for wireless nursery devices sold in the United States, while the European Union's Radio Equipment Directive mandates CE marking and electromagnetic compatibility testing before market entry. China's Ministry of Industry and Information Technology enforces GB standards for short-range wireless devices that constrain transmit power and frequency hopping protocols. Stakeholders must monitor evolving cybersecurity mandates for internet-connected infant devices as regulatory bodies on both sides of the Atlantic draft IoT security frameworks that will reshape certification requirements and compliance costs.
Market Dynamics
Machine-learning breathing pattern analysis is electrifying competitive positioning by shifting parent preference from passive surveillance toward proactive health monitoring, forcing manufacturers to rebuild hardware-software architecture around predictive analytics rather than simple audiovisual transmission.
Growth Catalysts
- FCC radio frequency governance:The Federal Communications Commission's emission standards for wireless nursery devices create compliance clarity that accelerates product certification cycles for US-bound manufacturers.
- Urban new parent households:Dense metropolitan environments amplify demand for apartment-optimized monitors with extended range and wall-penetration signal strength.
- GB standards enforcement:China's Ministry of Industry and Information Technology transmit-power constraints are pushing domestic suppliers toward more efficient frequency-hopping protocols that reduce interference.
Market Restraints
- Semiconductor input volatility:Wi-Fi chipset and CMOS sensor pricing fluctuations compress margin pools for cloud-connected monitor producers dependent on Taiwanese foundry supply.
- Electromagnetic compatibility testing:The European Union's Radio Equipment Directive CE marking requirements impose extended certification timelines and third-party laboratory costs before market entry.
- DECT audio substitution:Mature digital enhanced cordless telecommunications monitors in emerging markets resist displacement by higher-margin smart units due to price elasticity.
Strategic Opportunities
- Software-layer sleep analytics:Subscription-based breathing and sleep pattern reporting creates recurring revenue attachment to hardware installations.
- Hospital-grade sensor calibration:Clinical validation protocols from neonatal intensive care units are migrating into consumer portfolios as premium differentiation.
- Vertically integrated Southeast Asian manufacturing:Captive production facilities enable cost control across audio and video monitor lines without contract manufacturer margin extraction.
Industry Challenges
- Cybersecurity framework compliance:Draft IoT security mandates from Atlantic regulatory bodies are reshaping certification requirements and engineering resource allocation.
- Machine-learning model training:Infant breathing pattern datasets require clinical partnership access that smaller hardware vendors struggle to secure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Digital Monitor Market |
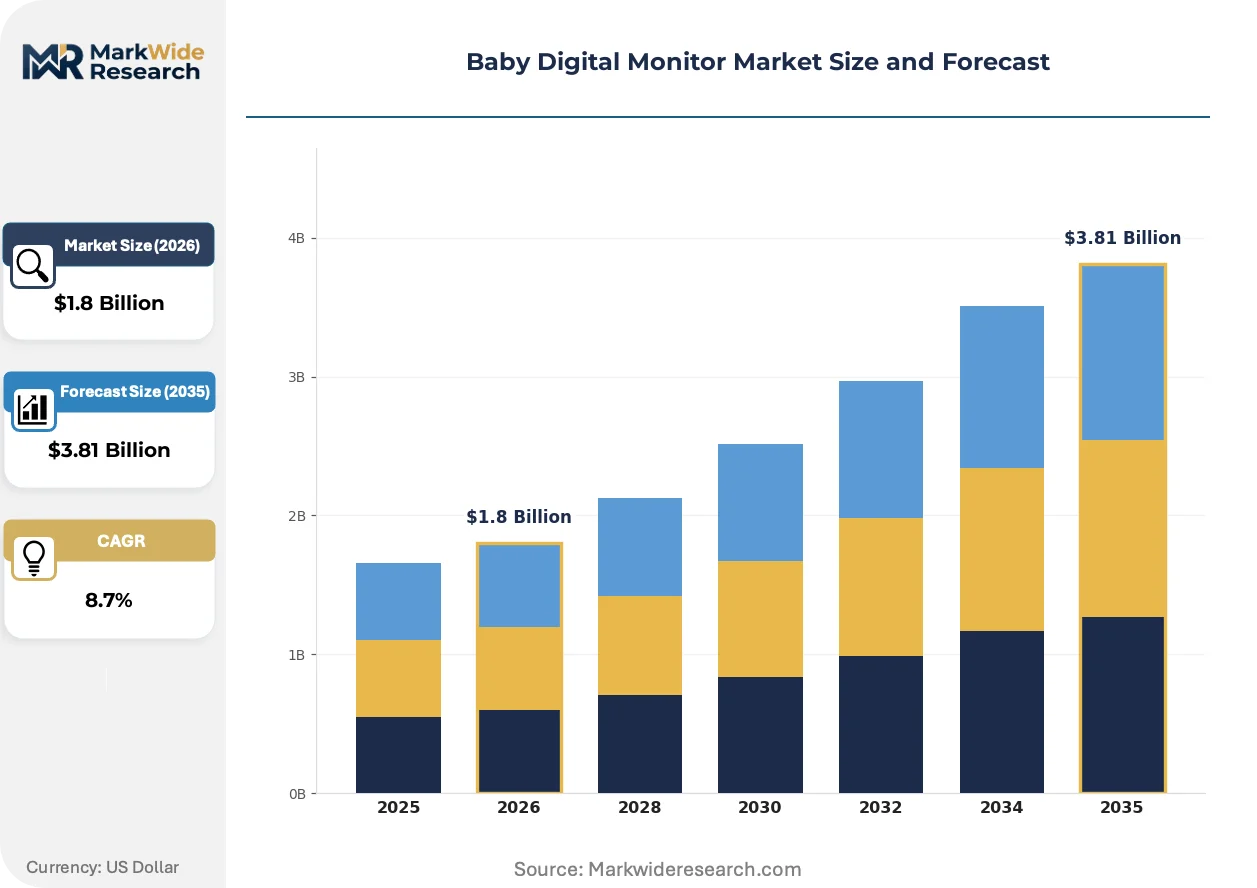
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audio Monitor, Video Monitor, Wearable Monitor, Smart Monitor Technology: Wi-Fi, Bluetooth, DECT, Infrared End User: Parents, Caregivers, Hospitals, Daycares Feature: Two-Way Audio, Night Vision, Temperature Monitoring, Motion Detection |
| Companies Covered | VTech Communications Inc., Summer Infant Inc., Samsung Electronics Co. Ltd., Motorola Mobility LLC, Koninklijke Philips NV, Nanit, Owlet Baby Care, Arlo Technologies Inc., Panasonic Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Digital Monitor Market Trends and Innovations
Product architecture is bifurcating between cloud-dependent smart ecosystems and offline privacy-preserving units, with parental data sovereignty concerns driving hardware design choices previously dominated by feature expansion alone.
Computer vision-based contactless breathing monitoring is electrifying safety assurance by eliminating wearable sensor attachment risks. First-time parents in broadband-saturated households are adopting these units fastest. The technology is compressing addressable market share for traditional movement-sensor pad configurations.
REACH substance restrictions and RoHS hazardous material limits are tightening component sourcing for European market entry. Manufacturers must reformulate solder compositions and plastic housings to maintain CE marking eligibility. Video monitor producers with Chinese supply chains face the steepest reformulation timelines.
Subscription unbundling from hardware purchase is restructuring lifetime value calculations for nursery device vendors. Direct-to-parent digital storefronts are displacing big-box retail as the primary acquisition channel. This pattern concentrates in North American and German markets where recurring payment acceptance runs highest.
Baby Digital Monitor Market Segmentation
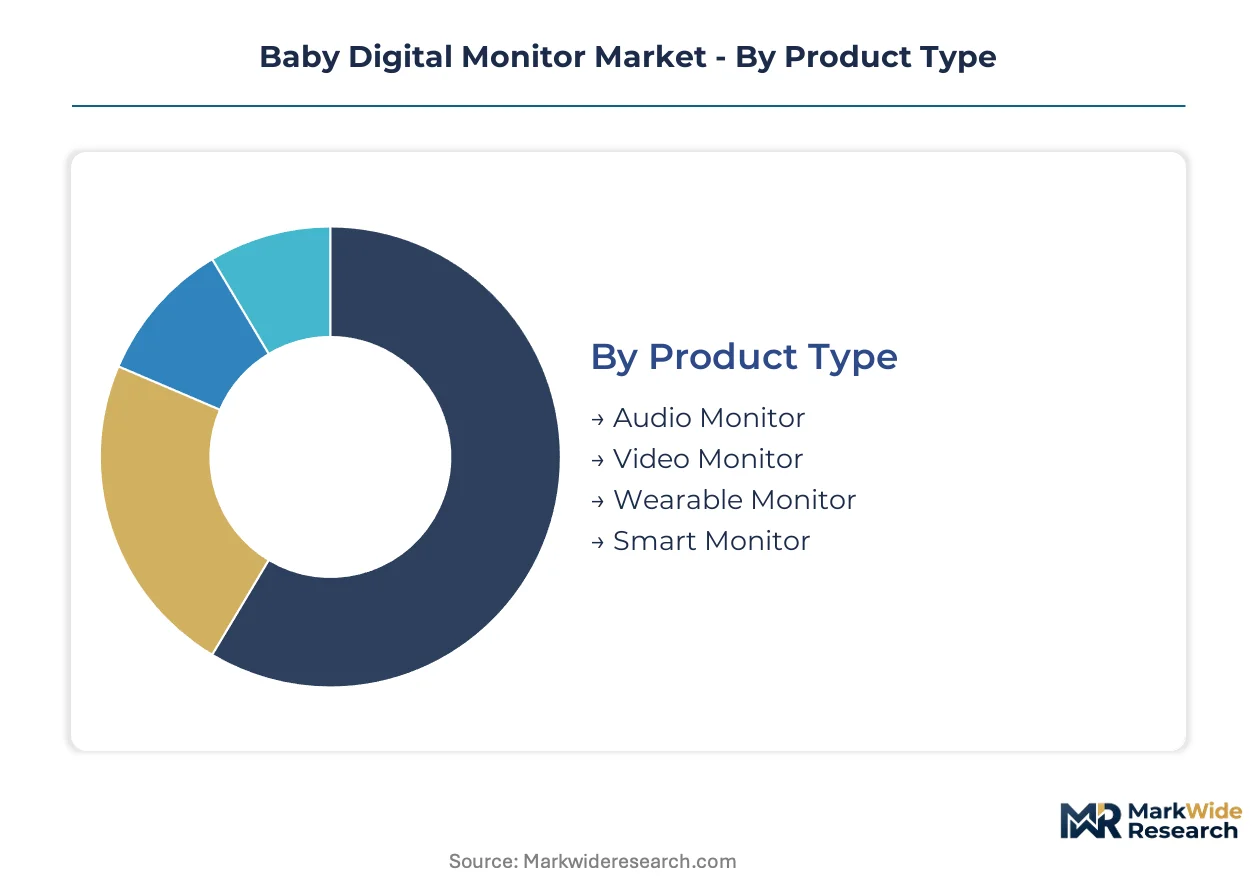
Segmentation in the baby digital monitor market reveals divergent capital requirements and margin structures across hardware architectures. Product configuration choices determine whether manufacturers compete on semiconductor economies of scale or software-layer recurring revenue attachment.
Product Type:
Capital intensity peaks in smart monitor production where machine-learning model development and cloud infrastructure dwarf hardware tooling costs. Audio monitor lines require minimal R&D fixed investment but sacrifice pricing power.
- Audio Monitor:Single-channel DECT transmission units with basic voice-activated alert functionality. Demand concentrates in emerging markets where price elasticity resists smart unit displacement. FCC emission compliance clarity accelerates certification cycles for US-bound manufacturers.
- Video Monitor:CMOS sensor-equipped units with 2.4 GHz or 5 GHz wireless transmission and encrypted signal protocols. Urban new parent households in dense metropolitan environments drive adoption of apartment-optimized configurations with extended range and wall-penetration strength.
- Wearable Monitor:Sensor-integrated garments or clips transmitting biometric data via low-energy protocols.
- Smart Monitor:Wi-Fi-enabled ecosystems with machine-learning breathing pattern analysis and subscription-based sleep analytics.
Most installed capacity flows through Video Monitor production. Expansion is steepest in Smart Monitor architectures.
Technology:
Technology selection dictates regulatory exposure and supply chain geography. Wi-Fi chipset sourcing concentrates in Taiwanese foundries, while DECT silicon offers European vendor alternatives.
- Wi-Fi:Cloud-connected transmission enabling remote access and data aggregation for predictive analytics. Broadband-saturated households in the United States and Germany adopt these units fastest as nursery ecosystems integrate with smart home platforms.
- Bluetooth:Short-range protocol for wearable-to-base-station communication with lower power consumption. Proximity-dependent range limits addressable use cases to single-room monitoring.
- DECT:Digital enhanced cordless telecommunications operating in dedicated spectrum bands with interference-resistant voice quality. Mature baseline technology maintains price competitiveness in cost-sensitive geographies.
- Infrared:Night vision illumination for video monitors operating below visible light spectrum.
Wi-Fi commands the highest margin pools. DECT retains volume leadership in emerging market penetration.
End User:
End user segmentation separates consumer discretionary purchase from institutional procurement with divergent validation requirements. Hospital and daycare channels demand clinical-grade calibration that extends engineering timelines.
- Parents:First-time and repeat buyers prioritizing anxiety reduction and SIDS risk mitigation through real-time alerting. Direct-to-parent digital storefronts displace big-box retail as primary acquisition channel in North American and German markets.
- Caregivers:Extended family members and professional nannies requiring multi-receiver compatibility.
- Hospitals:Neonatal intensive care units demanding hospital-grade sensor calibration with clinical validation protocols. CE marking and electromagnetic compatibility testing impose extended certification timelines for European market entry.
- Daycares:Multi-infant facilities requiring centralized monitoring dashboards with regulatory compliance documentation.
Parent segment absorbs the majority of unit volume. Hospital channel expansion is climbing the fastest on clinical validation migration.
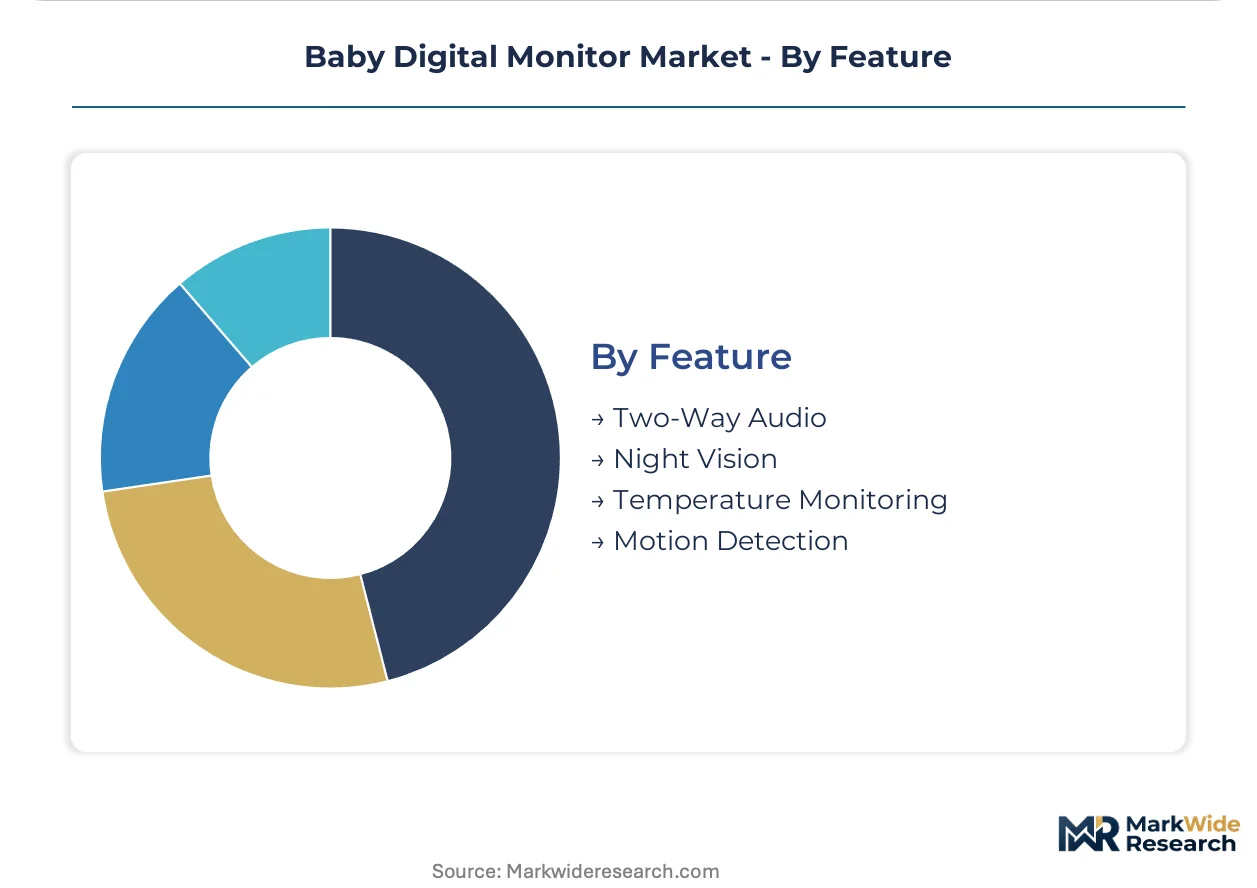
Feature:
Feature bundling determines software attach rates and lifetime value per installation. Modular architectures allow hardware-software unbundling that restructures vendor revenue recognition.
- Two-Way Audio:Full-duplex voice transmission enabling parent-to-infant communication without physical presence. Standard inclusion in mid-tier and premium product lines with minimal incremental hardware cost.
- Night Vision:Infrared LED illumination with automatic ambient light detection. Essential for video monitor competitiveness in low-light nursery environments.
- Temperature Monitoring:Environmental sensors tracking nursery climate with threshold-based alerting. Parents in climate-variable geographies prioritize this capability for overheating prevention.
- Motion Detection:Computer vision or accelerometer-based movement tracking with crib-activity logging. Contactless breathing monitoring applications are compressing addressable market share for traditional movement-sensor pad configurations.
Night Vision penetration approaches ubiquity in video units. Motion Detection with breathing analytics is gaining share fastest on proactive health monitoring preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered commercial baby monitor manufacturing in the 1980s, establishing the consumer electronics supply chains that now feed global production. Distribution networks today radiate from semiconductor fabrication clusters in East Asia and software development centers in North America and Western Europe.
United States
First-time parents in broadband-saturated metropolitan areas drive Wi-Fi-enabled smart monitor adoption fastest. FCC emission standards for wireless nursery devices create compliance clarity that accelerates product certification cycles for domestic-bound manufacturers. The San Francisco Bay Area and Greater Boston anchor machine-learning development for breathing pattern analytics.
China
MIIT transmit-power constraints under GB standards push domestic suppliers toward efficient frequency-hopping protocols that reduce signal interference. Shenzhen and Dongguan concentrate vertically integrated manufacturing for audio and video monitor exports. Parental demand concentrates in tier-one cities where smart home ecosystem penetration runs highest.
Germany
CE marking and electromagnetic compatibility testing under the EU Radio Equipment Directive impose extended certification timelines before market entry. Berlin and Munich host sleep analytics software development teams serving European-language markets. German parents exhibit highest subscription payment acceptance for recurring sleep pattern reporting.
South Korea
Seoul Capital Area households demand apartment-optimized monitors with extended range and wall-penetration signal strength for dense urban environments. MFDS-equivalent consumer electronics safety protocols align with EU standards, easing export pathway preparation. Busan-Ulsan industrial corridor supplies CMOS sensor components for video monitor assembly.
United Kingdom
London and Southeast England concentrate direct-to-parent digital storefront operations displacing big-box retail as primary acquisition channel. REACH substance restrictions and RoHS hazardous material limits tighten component sourcing for European market entry. Clinical partnerships with NHS neonatal units enable hospital-grade sensor calibration migration into consumer portfolios.
Baby Digital Monitor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software-layer differentiation, with recurring revenue attachment separating tier-one vendors from hardware-only suppliers. The vendor base stratifies into three archetypes: vertically integrated electronics conglomerates, software-native sleep analytics specialists, and contract-manufacturing-dependent brand marketers. Dominant competitive moves include backward integration into Southeast Asian production facilities and strategic licensing of machine-learning breathing detection algorithms.
Within the vertically integrated tier, VTech Communications Inc. and Samsung Electronics Co. Ltd. exemplify scale-driven manufacturing control. Koninklijke Philips NV occupies a position bridging clinical validation heritage with consumer market accessibility. Nanit represents the software-native archetype where subscription revenue models restructure lifetime value calculations per installed unit.
| Leading Market Players |
|---|
| VTech Communications Inc. |
| Summer Infant Inc. |
| Samsung Electronics Co. Ltd. |
| Motorola Mobility LLC |
| Koninklijke Philips NV |
| Nanit |
| Owlet Baby Care |
| Arlo Technologies Inc. |
| Panasonic Holdings Corporation |
| Others |
Pricing and Supply Chain Analysis
Machine-learning firmware engineers in Shenzhen and Taipei command wage premiums that widen pricing spreads between cloud-connected smart monitors and offline DECT audio units. Labor-cost differentials between these semiconductor clusters and Vietnamese assembly plants feed directly into three-tier hardware economics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates subscription-anchored smart ecosystems from single-purchase video monitors and entry-level audio devices. Price differentiation rests on CE marking tier and machine-learning calibration grade. Cost compression in Wi-Fi chipset sourcing is intensifying because Taiwanese foundry capacity allocation favors automotive silicon. Emerging-market parent households exhibit highest price sensitivity, while German and US metropolitan buyers accept recurring payment models.
Supply Chain Analysis
Direct-to-parent digital storefronts displace big-box retail for North American and German demand fulfillment. Manufacturing concentrates in China, Vietnam, and Taiwan, drawing from CMOS sensors, Wi-Fi chipsets, and lithium-polymer battery cells. Single-source vulnerability in Taiwanese foundry supply for machine-learning inference silicon threatens smart monitor production continuity. Distribution runs through Shenzhen export hubs and regional fulfillment centers in Rotterdam and Los Angeles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baby digital monitor market compounds regulatory value as the EU Radio Equipment Directive and FCC emission standards harden certification barriers that filter out low-investment competitors.
For Market Incumbents: Lock in hospital-grade sensor calibration partnerships with neonatal intensive care units before clinical validation protocols migrate fully into consumer portfolios. Deepen backward integration into Vietnamese assembly plants to offset contract manufacturer margin extraction. Software-native entrants threaten premium positioning through subscription revenue models that restructure lifetime value calculations. For New Entrants and Emerging Players: Direct-to-parent digital storefronts offer lowest customer acquisition cost entry into North American and German markets where recurring payment acceptance runs highest. Target tier-one Chinese cities where smart home ecosystem penetration concentrates demand for Wi-Fi-enabled nursery devices. Lead with contactless breathing monitoring technology that eliminates wearable sensor attachment risks and compresses legacy movement-pad market share. For Investors and Strategic Acquirers: Valuations sit cheapest among contract-manufacturing-dependent brand marketers lacking software-layer differentiation or captive production assets. Long-term viability favors vendors with machine-learning model training access through clinical partnerships. Watch FDA and EU cybersecurity framework finalization as inflection indicator for compliance cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU Radio Equipment Directive compliance unlocks premium pricing in German and UK markets. |
| Hospital System Partnership | NICU clinical validation protocols migrate into consumer portfolios as differentiation anchor. |
| Software Companion Development | Sleep analytics subscriptions restructure lifetime value per installed hardware unit. |
| Backward Integration into Assembly | Captive Vietnamese production facilities eliminate contract manufacturer margin extraction. |
| Reimbursement Strategy Formulation | Health insurer partnership for proactive SIDS risk mitigation expands addressable parent base. |
Research Methodology
Multiple input streams — neonatal clinician interviews, electronics procurement manager surveys, and regulatory filing analysis — were reconciled against customs export records and smart home platform integration disclosures. Primary dialogue with FCC certification consultants, EU notified body representatives, and Shenzhen ODM executives complemented secondary sources including CE marking databases, MIIT GB standard publications, and hospital procurement contract repositories. Bottom-up unit shipment estimates and top-down parental household penetration rates were cross-validated.
Historical smart monitor adoption curves were cross-referenced against panel input from machine-learning firmware developers and sleep analytics product managers across the projection horizon. Segmentation dimensions modeled include product architecture, transmission protocol, end-user channel, and regional regulatory cluster. CAGRs were derived from parent household formation rates, broadband penetration trajectories, and clinical validation protocol migration timelines.
Revisions become necessary when semiconductor foundry capacity reallocation, cybersecurity mandate finalization, or REACH substance restriction expansion materialize. Forecasts reflect base-case assumptions regarding certification timeline stability and machine-learning training data access continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Pregnancy Products Market
Baby Products
India Baby Care Products Market
Baby Products
United Arab Emirates Baby Care Products Market
Baby Products
Smart Baby Monitor Market
Baby Products
Baby Pacifier Thermometer Market
Baby Products
Baby Slings Market
Baby Products
Baby Pacifier Market
Baby Products
Stroller Rental Market
Baby Products
Baby Wipes Market
Baby Products
Travel Pillow Market
Baby Products
Baby Seat Liners Market
Baby Products
Feeding Bra Market
Baby Products
Baby Stroller Market
Baby Products
Potty Training Seat Market
Baby Products
Baby Cradles Market
Baby Products
Baby Sleepsuits Market