
 Fragrance Product Market | 2026-2036
Fragrance Product Market Size, Share, and Industry Trends Forecast 2026-2036
Fragrance Product Market Analysis
Grasse-based natural extract production is consolidating as artisan growers merge cooperative networks. Givaudan leverages captive sourcing of jasmine and rose absolutes across southern France. International Flavors & Fragrances anchors its position through biotechnology-derived molecules that reduce agricultural dependency. Symrise AG competes via integrated cultivation sites in Madagascar and sustainable vanilla programs.
Fragrance products are concentrated aromatic compounds dissolved in ethanol or oil carriers, typically containing 15-40% perfume oil by volume, designed to deliver olfactory identity for personal grooming and ambient scenting. Eau de Parfum commands the dominant value share due to higher oil concentration and extended wear time. Online Retail represents the fastest-expanding distribution channel as direct-to-consumer sampling models reduce trial barriers. The Unisex segment gains structural traction as gender-fluid marketing reshapes brand architecture across prestige and masstige tiers.
EU REACH and the IFRA Code of Practice govern allergen labeling and substance restrictions across European formulations. The US FDA exercises post-market surveillance without pre-approval requirements, creating divergent compliance burdens for multinational portfolios. China's NMPA and GB standards mandate animal-testing alternatives for imported cosmetics, altering registration pathways. Stakeholders must monitor regulatory divergence between jurisdictions to optimize formulation platforms and avoid market exclusion.
Market Dynamics
EU REACH compliance is tightening ingredient disclosure rules and forcing reformulation across prestige and masstige portfolios, while captive sourcing networks in Grasse and Madagascar reshape competitive moats around natural extract security.
Growth Catalysts
- Biotechnology-derived molecules:Fermentation-based aroma chemicals reduce agricultural dependency and stabilize input costs for fine fragrance houses.
- China's tier-one city premiumization:Experiential retail formats in Shanghai and Beijing drive Eau de Parfum adoption through immersive sampling environments.
- EU Green Deal alignment:Carbon footprint labeling mandates accelerate biodegradable solvent adoption across European formulation platforms.
Market Restraints
- Jasmine absolute supply concentration:Cooperative consolidation in Grasse limits spot market availability and amplifies price volatility for natural extract buyers.
- Animal-testing alternative validation costs:China's NMPA registration pathways require extended safety substantiation timelines for imported cosmetics.
- Synthetic musk substitution pressure:Galaxolide and tonalid face environmental persistence scrutiny, forcing premature reformulation cycles.
Strategic Opportunities
- Direct-to-consumer sampling models:Online Retail channel expansion reduces trial barriers through micro-format discovery kits and subscription loops.
- Gender-fluid brand architecture:Unisex segment white space allows repositioning of legacy masculine and feminine codes across Gen Z cohorts.
- Madagascar vanilla program scaling:Integrated cultivation sites offer traceability premiums for clean-label positioning in North American clean beauty.
Industry Challenges
- Perfumer training pipeline gaps:Grasse-based apprenticeship programs face enrollment shortfalls as artisan expertise retires without digital knowledge transfer systems.
- Legacy IFRA compliance layer integration:Multinational portfolios must reconcile divergent allergen thresholds across EU, US, and China regulatory stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fragrance Product Market |
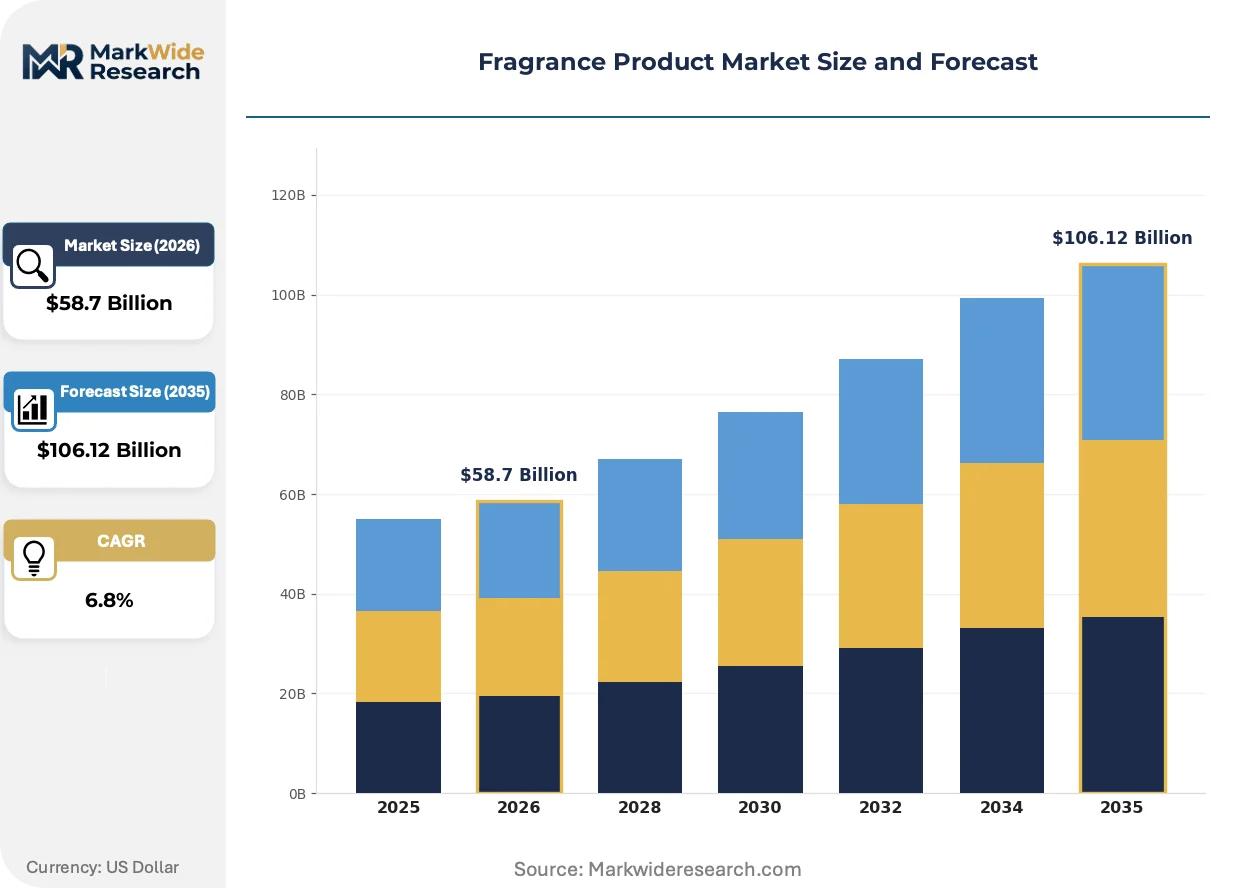
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eau de Parfum, Eau de Toilette, Perfume Oil, Solid Perfume Distribution Channel: Online Retail, Department Stores, Specialty Stores, Duty-Free Shops End User: Men, Women, Unisex, Children Form: Spray, Roll-On, Lotion, Gel |
| Companies Covered | Givaudan, International Flavors & Fragrances, Symrise AG, Firmenich SA, LVMH Moet Hennessy–Louis Vuitton, Estée Lauder Companies, Coty Inc., L'Oreal, Chanel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fragrance Product Market Emerging Trajectories
Active reformulation around biotechnology substrates and disclosure transparency is compressing traditional supply hierarchies while reshaping how fragrance houses secure competitive positioning.
Biotechnology-derived aroma molecules is consolidating production economics for fine fragrance manufacturers. Givaudan and International Flavors & Fragrances have scaled fermentation platforms for key woody and musk notes. Captive biotech capacity is consolidating margin control away from agricultural commodity markets and toward in-house molecular pipelines.
EU REACH substance restriction expansions are forcing preemptive reformulation across European prestige portfolios. The 2023 fragrance allergen labeling extension requires disclosure of over 80 additional compounds. Masstige houses with thinner R&D benches face compliance timeline compression against larger competitors with dedicated regulatory affairs teams.
Experiential retail formats are displacing traditional counter sampling in China's tier-one cities. Shanghai fragrance bars and Beijing immersive installations prioritize olfactory storytelling over transactional velocity. This behavioral pivot rewards houses with dedicated China creative studios and punishes those relying on standardized global campaign assets.
Fragrance Product Market Segmentation
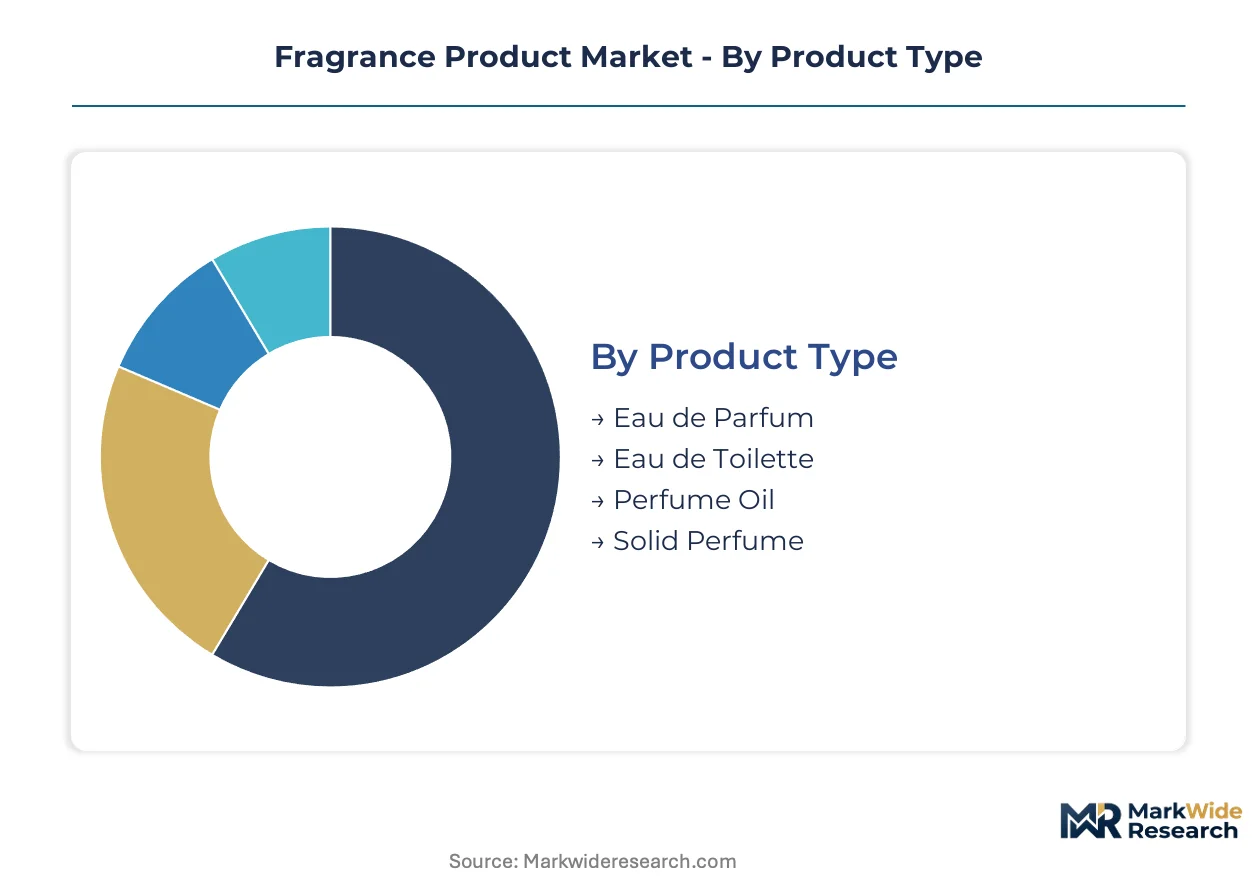
Fragrance houses configure formulation platforms and compliance pathways around concentration tiers, channel economics, and demographic targeting. Segment-specific requirements for allergen disclosure and animal-testing alternatives create divergent cost structures across portfolios.
Product Type:
Eau de Parfum and Perfume Oil carry heavier EU REACH documentation burdens due to higher oil concentrations triggering stricter allergen thresholds, while lighter formats face simpler disclosure requirements.
- Eau de Parfum:Contains 15-20% perfume oil dissolved in ethanol with fixative additives, delivering 6-8 hour wear profiles. Demand concentrates in Shanghai and Beijing experiential retail environments where immersive sampling justifies premium positioning.
- Perfume Oil:Anhydrous formulations with 20-30% pure fragrance concentrate in jojoba or fractionated coconut carriers, eliminating alcohol for sensitive skin applications. Islamic markets in the Gulf States drive adoption through alcohol-free positioning aligned with religious compliance preferences.
- Eau de Toilette:Lighter 5-15% oil concentration in ethanol-water blends, positioned for daily refreshment and workplace-appropriate sillage.
- Solid Perfume:Wax-based balms with 10-15% fragrance load, favored for travel-friendly formats and precise application control.
Leading the category by volume: Eau de Toilette. Expanding most quickly: Eau de Parfum.
Distribution Channel:
Channel selection determines sampling economics and regulatory touchpoints, with direct-to-consumer models compressing discovery timelines while physical retail maintains compliance documentation advantages for import registrations.
- Online Retail:Direct-to-consumer platforms deploy micro-format discovery kits and subscription loops to reduce trial barriers. China's tier-one cities anchor this channel's expansion through integrated social commerce and live-streaming fragrance education.
- Specialty Stores:Curated assortments with trained scent consultants and personalized layering consultations. European prestige retailers leverage these locations for EU REACH-compliant ingredient transparency storytelling.
- Department Stores:Traditional counter formats with standardized global campaign assets, facing pressure from experiential retail displacement in key growth markets.
- Duty-Free Shops:Travel retail environments capturing impulse purchases through exclusive limited editions and gift-with-purchase mechanics.
Generating highest margins: Specialty Stores. Gaining share fastest: Online Retail.
End User:
Gender-targeted positioning shapes brand architecture investments, with unisex formulations requiring reformulation of legacy masculine and feminine codes to capture Gen Z cohorts.
- Unisex:Gender-fluid marketing architectures repositioning traditional olfactive families for boundary-avoidant consumers. North American clean beauty retailers prioritize this segment for traceability premiums and minimalist ingredient storytelling.
- Women:Historically dominant segment with established floral-oriental fragrance families and heritage brand loyalty patterns.
- Men:Woody-aromatic and fougère categories facing pressure to soften traditional masculine codes for younger demographics.
- Children:Hypoallergenic formulations with reduced sensitizing compound loads, subject to stricter IFRA concentration limits.
Holding largest value share: Women. Climbing the fastest: Unisex.
Form:
Delivery mechanism selection affects solvent choice, biodegradability profiles, and packaging sustainability credentials under EU Green Deal alignment pressures.
- Spray:Aerosolized ethanol-based application dominating prestige and masstige tiers, with propellant alternatives under environmental persistence scrutiny.
- Roll-On:Direct skin contact formats with lower alcohol content, positioned for sensitive skin and travel convenience segments.
- Lotion:Emulsion-based fragrance delivery combining scent with skincare benefits, requiring additional preservative compliance layers.
- Gel:Alcohol-free hydrocolloid matrices offering controlled release and reduced evaporation rates in humid climates.
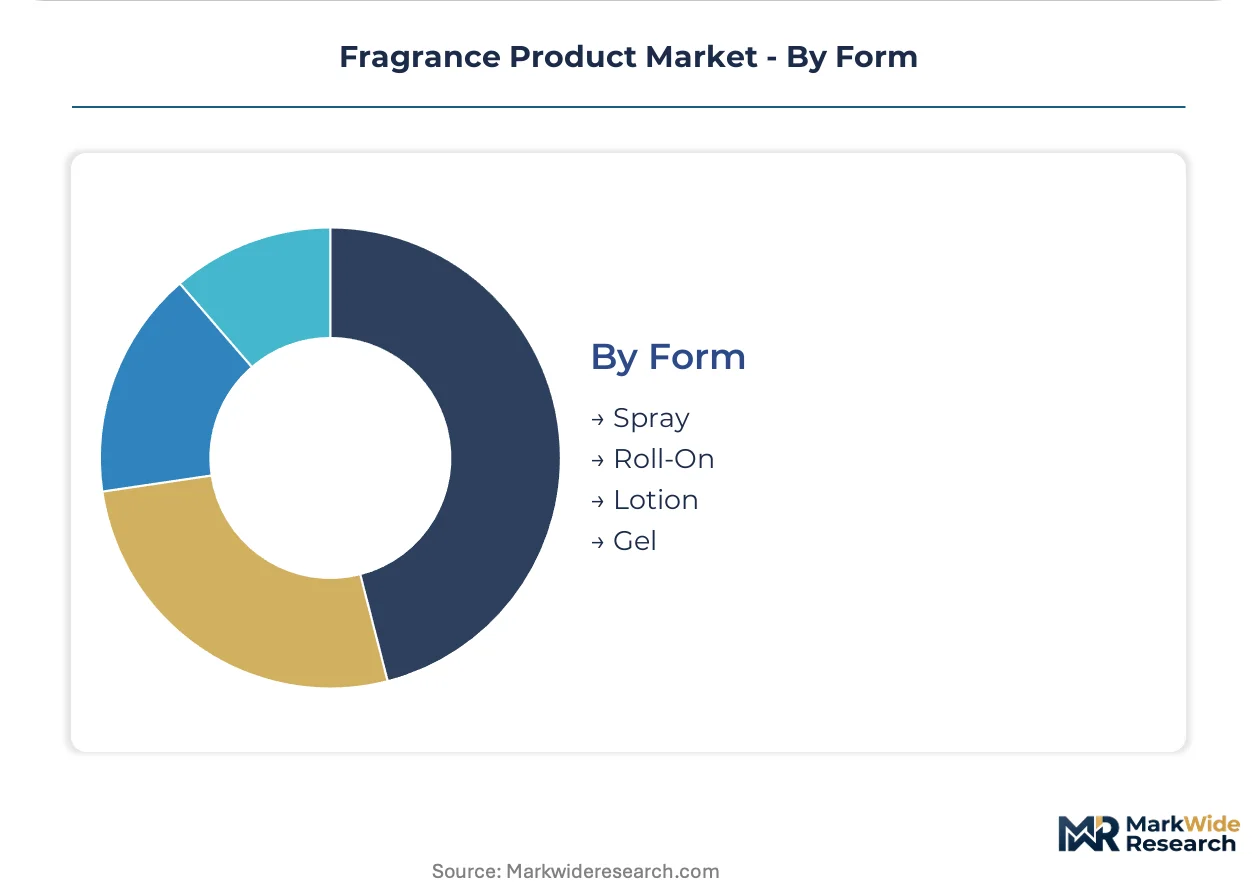
Commanding dominant volume: Spray. Showing steepest expansion trajectory: Roll-On.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grasse's jasmine and rose absolute harvests anchor French fragrance production, yet demand growth now concentrates in Asian experiential retail corridors and Gulf State prestige expansions. Regulatory divergence across EU REACH, China's NMPA, and US FDA compliance stacks reshapes formulation platform economics. Tier-one city flagship stores and integrated cultivation sites in Madagascar now determine competitive positioning.
China
Shanghai and Beijing experiential retail bars drive Eau de Parfum premiumization through immersive olfactory storytelling formats. NMPA mandates animal-testing alternatives for imported cosmetics, extending safety substantiation timelines for multinational houses. Yangtze River Delta manufacturing clusters now host dedicated China creative studios replacing standardized global campaign assets.
United States
Direct-to-consumer sampling models and subscription discovery loops compress trial barriers for online retail expansion. FDA post-market surveillance avoids pre-approval requirements, creating lighter compliance burdens than EU formulations for domestic portfolios. California clean beauty retailers prioritize unisex segment traceability premiums and minimalist ingredient disclosure.
France
Grasse cooperative consolidation limits jasmine absolute spot market availability, amplifying price volatility for natural extract buyers. EU REACH 2023 fragrance allergen labeling extensions force disclosure of over 80 additional compounds across prestige portfolios. Provence-Alpes-Côte d'Azur cultivation networks now merge artisan grower cooperatives under captive sourcing arrangements.
Germany
Masstige houses with thinner R&D benches face EU Green Deal carbon footprint labeling timeline compression against larger competitors. ECHA substance restriction expansions drive biodegradable solvent adoption across European formulation platforms. North Rhine-Westphalia distribution hubs coordinate REACH-compliant ingredient transparency storytelling for specialty retail channels.
United Arab Emirates
Prestige beauty retailers in Dubai and Abu Dhabi expand fragrance portfolios as alcohol-free perfume oil demand aligns with religious compliance preferences. MOHAP cosmetics registration pathways require extended documentation for imported formulations. Gulf State experiential retail investments now displace traditional department store counter formats for discovery-driven purchasing.
Fragrance Product Market Vendor Landscape
Global majors compete with regional champions across captive sourcing networks and biotechnology-derived molecule platforms. The vendor base stratifies into three tiers: integrated fragrance houses with fermentation capacity, luxury conglomerates with retail control, and specialty natural extract suppliers. Two dominant competitive moves now reshape positioning: backward integration into Grasse and Madagascar cultivation sites, and strategic partnerships with China-based creative studios for experiential retail localization.
Within the integrated fragrance house tier, Givaudan and International Flavors & Fragrances exemplify archetypes competing through biotechnology scale. Symrise AG occupies a position anchored by Madagascar vanilla program traceability. These three represent divergent strategic postures: captive biotech capacity versus integrated cultivation security versus clean-label sourcing premiums.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances |
| Symrise AG |
| Firmenich SA |
| LVMH Moet Hennessy–Louis Vuitton |
| Estée Lauder Companies |
| Coty Inc. |
| L'Oreal |
| Chanel |
| Others |
Supply Flow & Price Mechanics
Captive sourcing networks in Grasse and Madagascar anchor both supply security and pricing power for integrated fragrance houses, while spot-market buyers face volatile jasmine absolute costs and compressed margins.
Pricing Analysis
Service bundling separates formulation partnerships from transactional ingredient sales, with Givaudan and IFF commanding premium positioning through captive biotechnology capacity and extended R&D collaboration. Three-tier pricing structure across premium, standard, and economy levels stratifies by oil concentration and compliance documentation depth. Pricing pressure stems from EU REACH reformulation mandates forcing masstige houses to absorb regulatory consulting costs. Mass retailers exhibit highest price sensitivity, while prestige houses in Gulf States demonstrate lowest sensitivity due to traceability premiums.
Supply Chain Analysis
Return and refurbishment flows are minimal in fragrance manufacturing, though Madagascar vanilla programs incorporate cooperative quality regrading for substandard harvests. Raw material sourcing concentrates in France, Madagascar, and China, with jasmine absolute and rose essence drawing from Grasse cooperative networks. Supply chains rest on fermentation-derived aroma molecules, natural absolutes, and ethanol carriers as core inputs. Single-source vulnerability runs through jasmine cooperative consolidation limiting spot availability. Distribution runs through specialty retail channels in European prestige markets and direct-to-consumer platforms in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into cultivation sites and biotechnology fermentation capacity defines competitive positioning, with captive supply of jasmine absolutes and woody molecules emerging as the decisive upstream lever.
For Market Incumbents: Deepen captive sourcing arrangements across Madagascar vanilla programs and Grasse cooperative networks to secure natural extract availability against cooperative consolidation. Expand in-house fermentation platforms for key musk and woody notes to reduce agricultural commodity exposure. Biotechnology scale investments counter emerging fermentation specialists threatening ingredient supply dominance.
For New Entrants and Emerging Players: Gender-fluid unisex formulations represent an underserved buyer archetype with minimal legacy brand loyalty and receptive Gen Z demographics. Direct-to-consumer sampling models offer lower barrier entry than retail distribution, with micro-format discovery kits enabling subscription revenue capture before physical retail investment. North American clean beauty retailers provide most penetrable channel for traceability-positioned entrants.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated fragrance houses seeking biotechnology capacity or luxury conglomerates expanding vertical control over ingredient supply. Five-to-ten year viability favors specialists with fermentation platforms or integrated cultivation sites over pure-play natural extract traders. Monitor EU REACH substance restriction expansions as inflection indicator for reformulation service demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Fermentation Scale-Up | Givaudan's captive woody molecule production reduces agricultural input cost volatility. |
| Madagascar Cultivation Integration | Symrise's vanilla program secures traceability premiums for North American clean beauty positioning. |
| China Creative Studio Establishment | Dedicated Shanghai facilities enable experiential retail localization beyond standardized global assets. |
| Direct-to-Consumer Sampling Launch | Online retail subscription models compress discovery timelines for fragrance trial conversion. |
| EU REACH Compliance Investment | Dedicated regulatory affairs teams accelerate reformulation timelines against thinner R&D competitors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fragrance house R&D directors, Grasse cooperative managers, specialty retail buyers, regulatory affairs consultants, and China creative studio leads. Secondary sources encompassed IFRA compliance databases, ECHA substance restriction notices, NMPA registration filings, and EU customs import records. Bottom-up volume modeling triangulated against top-down value estimates from prestige retailer revenue disclosures.
Segment-level granularity modeled product type, distribution channel, end user demographic, and geographic regulatory cluster across the analysis window. CAGRs derived from historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated jasmine absolute harvest yields, fermentation capacity expansion announcements, and experiential retail format adoption curves in China's tier-one cities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU REACH substance restriction expansions, cooperative consolidation in Grasse, and China NMPA pathway modifications for animal-testing alternatives. Practitioners should monitor ECHA allergen labeling extensions and Madagascar vanilla harvest reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Global Fragrance Market
Fragrances & Perfumes
Fragrance Emulsion Market
Fragrances & Perfumes
Clean Perfume Market
Fragrances & Perfumes
Global Scented Candle Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Evaporative Diffusers Market
Fragrances & Perfumes
Gourmand Fragrance Market
Fragrances & Perfumes
Smart Fragrance Box Market
Fragrances & Perfumes
North America Perfume Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Wax Melts Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
UAE Perfume Market
Fragrances & Perfumes
Digital Fragrance Market
Fragrances & Perfumes
Global Luxury Perfumes Market
Fragrances & Perfumes
Middle East Fragrances Market