
 Digital Scent Market | 2026-2036
Digital Scent Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Scent Market Analysis
The capability gap between integrated hardware-software platforms and standalone scent module suppliers is unwinding competitive dynamics across the sector. Aromajoin Corporation leverages its proprietary cartridge architecture to dominate immersive entertainment installations. Alpha MOS SA anchors its position through laboratory-grade sensor calibration protocols that sustain premium pricing in quality assurance segments. Owlstone Inc. competes by extending silicon-based microchip fabrication expertise into miniaturized olfactory detection arrays.
Digital scent technology encompasses hardware systems that synthesize, transmit, or detect odor molecules through electronic means, typically operating with detection thresholds measured in parts-per-billion for chemical identification. The primary commercial purpose centers on enriching user immersion in virtual environments while enabling remote quality control in food and pharmaceutical manufacturing. Olfactory displays currently lead technology segment revenue due to their integration into VR headsets and cinematic installations, whereas scent-enabled devices represent the fastest-expanding category as wearable form factors shrink component costs. Among end users, entertainment occupies established margin pools through theme park and gaming contracts, while healthcare applications in wound assessment and disease screening concentrate future demand growth.
FDA oversight of medical diagnostic applications and EPA volatile organic compound emissions standards jointly shape product certification requirements and market access timelines for hardware developers. Japan's METI promotes domestic digital smell research through standardized JIS frameworks that influence component interoperability across Asian supply chains. Stakeholders must monitor regulatory divergence between consumer entertainment classifications and medical device pathways, as this boundary determines both development costs and addressable market breadth.
Market Dynamics
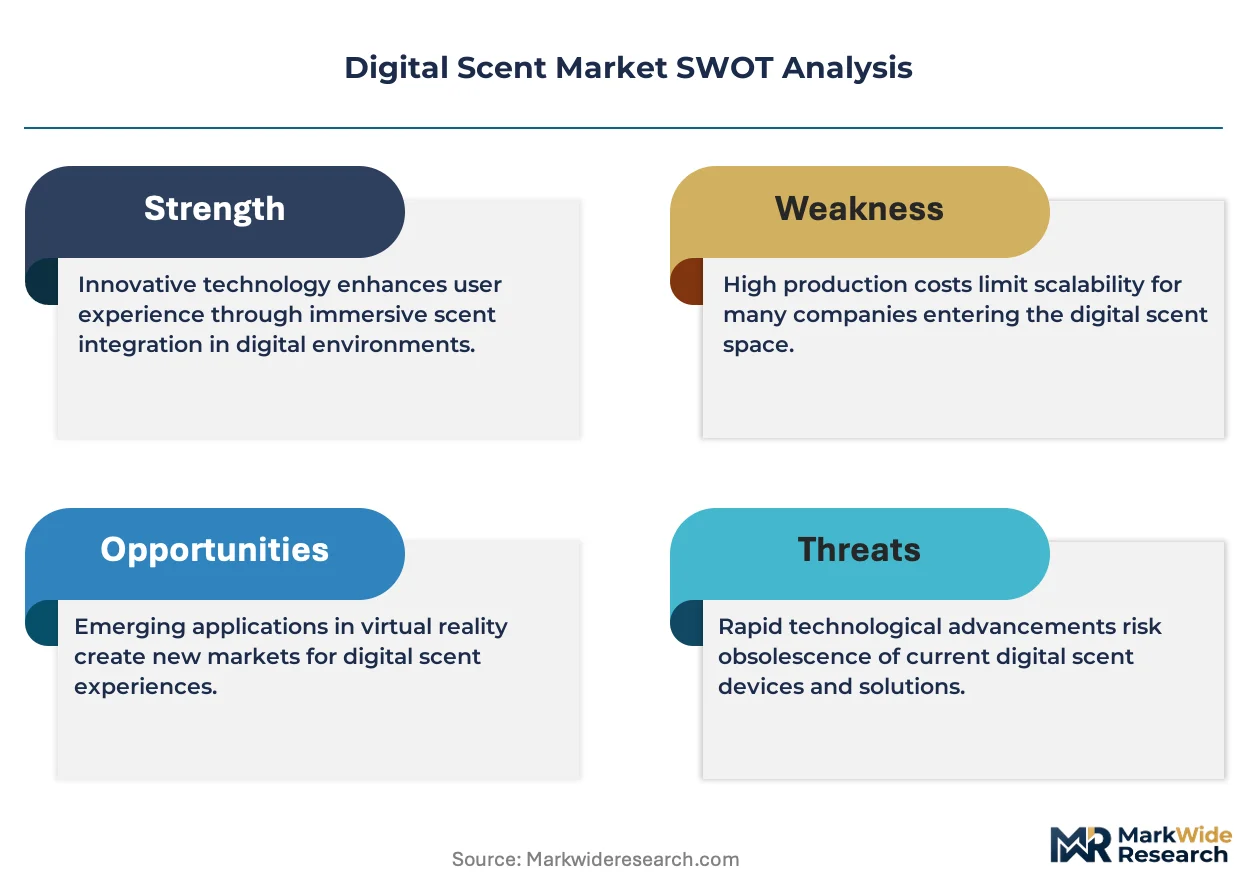
The Digital Scent Market confronts a fundamental tension between immersive entertainment budgets expanding for olfactory-enabled VR installations and tightening EPA volatile organic compound thresholds that constrain hardware emissions profiles.
Growth Catalysts
- Theme park immersive contracts:Major entertainment operators in Orlando and Tokyo are commissioning permanent scent-integrated theatrical systems for walkthrough attractions, locking in multi-year hardware procurement cycles.
- METI-backed JIS standardization:Japan's Ministry of Economy, Trade and Industry is funding cartridge interoperability protocols that reduce integration friction for Asian supply chain partners.
- Silicon microchip fabrication advances:Semiconductor foundries are applying MEMS processes to olfactory sensor arrays, collapsing unit costs for wearable form factors.
Market Restraints
- Specialized polymer feedstock concentration:Aroma-encapsulation substrates rely on three German chemical suppliers, exposing hardware manufacturers to input cost volatility and allocation risk.
- FDA diagnostic pathway friction:Medical device classification for wound-assessment applications triggers 18-24 month premarket notification timelines that deter capital deployment.
- Cross-modal substitution by haptics:Advanced force-feedback gloves in gaming are capturing immersive budget share that might otherwise flow to olfactory hardware.
Strategic Opportunities
- Underpenetrated pharmaceutical quality control:Batch consistency testing in active ingredient manufacturing remains dominated by gas chromatography, leaving white space for electronic nose deployment.
- EU CSRD supply chain disclosure:Corporate sustainability reporting mandates are creating procurement preference for scent-enabled remote inspection systems that reduce auditor travel emissions.
- Convergence of AI pattern recognition with sensor arrays:Machine learning classification of complex odor signatures is opening disease-screening applications previously requiring laboratory mass spectrometry.
Industry Challenges
- Cross-disciplinary talent scarcity:Product development teams must combine polymer chemistry, embedded systems engineering, and olfactory psychophysics expertise that rarely coexists in single labor markets.
- Legacy HVAC integration complexity:Commercial building scent diffusion requires retrofitting into existing climate control infrastructure with incompatible airflow specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Scent Market |
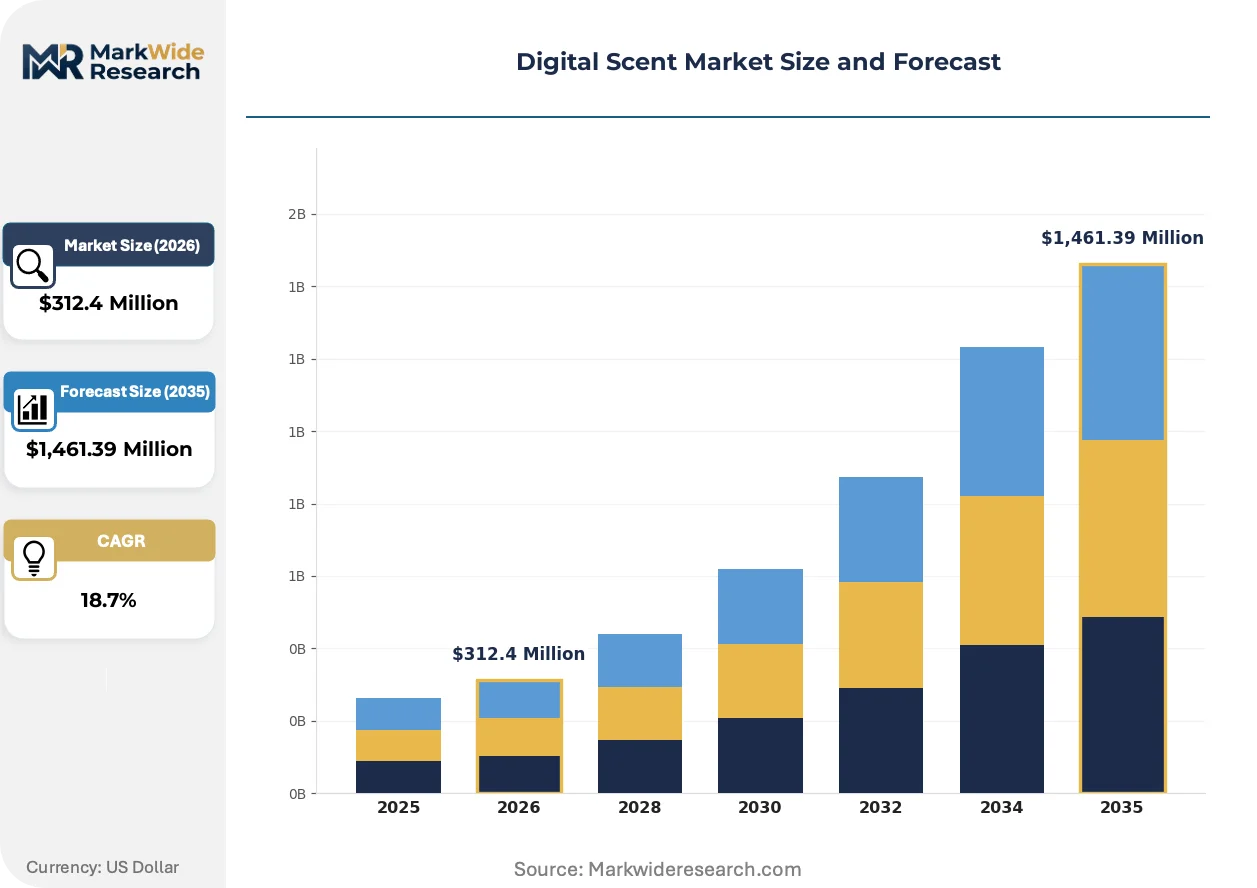
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Olfactory Displays, Scent Generators, Scent-Enabled Devices, Digital Fragrances Application: Virtual Reality, Advertising, Gaming, Marketing End User: Entertainment, Healthcare, Retail, Education Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Aromajoin Corporation, Scent Sciences Corporation, Scentcom Ltd., Electronics Sensor Technology, Sensigent, Aroma Bit, Inc., Alpha MOS SA, The eNose Company, Owlstone Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Scent Market Emerging Trajectories
Hardware architectures are splitting between closed entertainment systems and open medical platforms, while regulatory jurisdictions race to establish emissions and safety frameworks before mass consumer adoption.
Cartridge-based scent synthesis is bifurcating the hardware landscape. Proprietary locked systems dominate theme park installations where content owners demand piracy-resistant delivery. Open-architecture refillables are capturing healthcare and industrial segments where users require formulation flexibility. This split is compressing margin pools for component suppliers caught between incompatible interface standards.
EPA volatile organic compound thresholds for indoor air quality are tightening certification requirements for scent-emitting hardware sold in the United States. Manufacturers must now submit third-party emissions testing for each cartridge formulation, extending product launch timelines. Entertainment hardware vendors are responding by relocating final assembly to states with streamlined environmental permitting.
Enterprise procurement of scent-enabled quality control systems is consolidating through specialized systems integrators rather than direct manufacturer relationships. Food and pharmaceutical buyers are outsourcing sensor calibration, data interpretation, and regulatory documentation to channel partners with existing laboratory service contracts. This pattern is most visible in Japan where METI-certified integrators bundle hardware with JIS-traceable validation protocols.
Digital Scent Market Segmentation
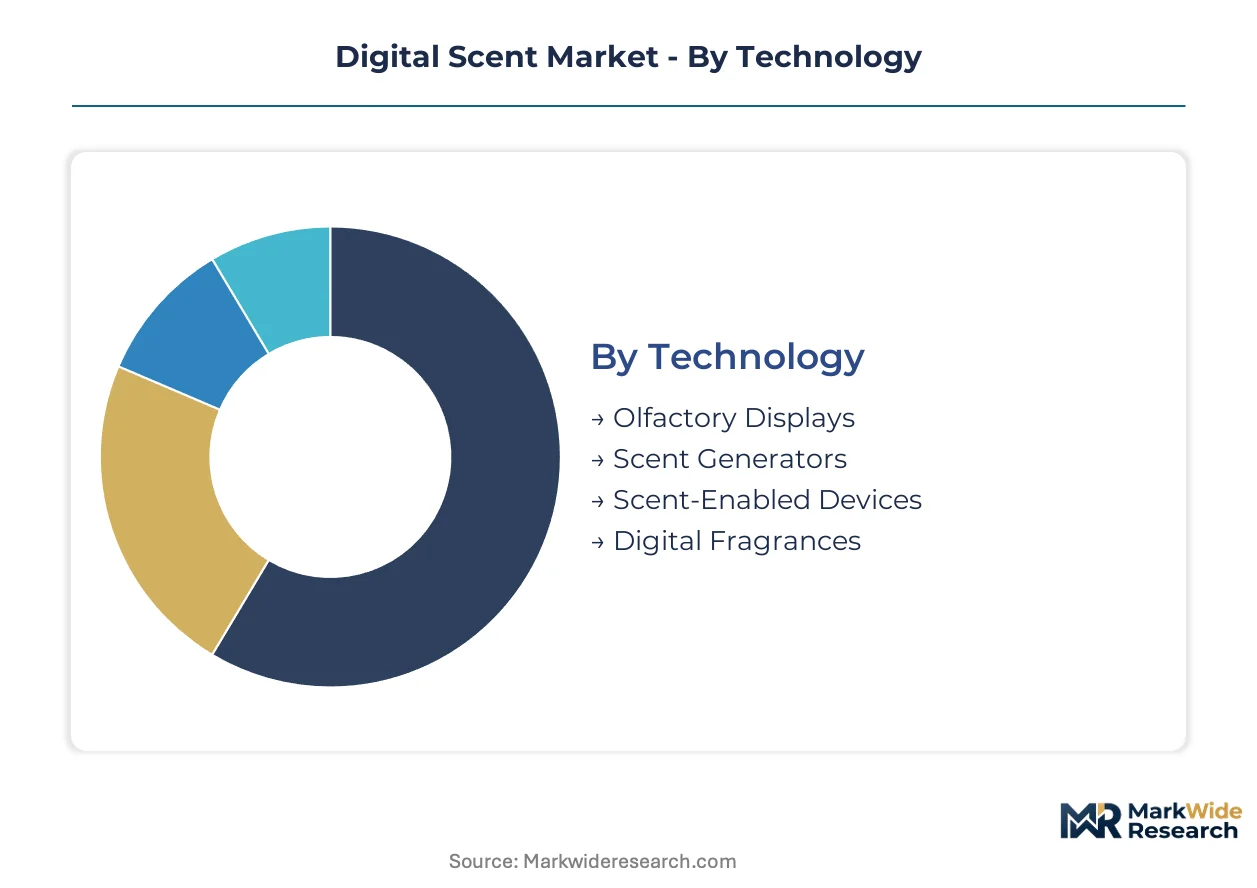
Segmentation in the Digital Scent Market reveals divergent commercial models across hardware architectures, use cases, and procurement channels. Each dimension carries distinct margin profiles, regulatory exposure, and geographic concentration that shape supplier strategy and investment prioritization.
Technology:
Domestic production clusters dominate cartridge-based systems in Japan and Germany, while semiconductor-integrated platforms draw heavily from Taiwanese and South Korean foundry capacity.
- Olfactory Displays:These systems integrate scent emission arrays with visual projection surfaces, typically operating through heated polymer substrates that release aroma molecules on thermal trigger. Demand concentrates in Orlando and Tokyo theme park installations where multi-sensory theatrical budgets justify six-figure hardware deployments. FDA emissions documentation requirements extend procurement cycles for US-based entertainment operators.
- Scent-Enabled Devices:Wearable form factors incorporating MEMS-based microchip sensors are collapsing unit costs through silicon fabrication economies. South Korean consumer electronics manufacturers are driving volume procurement for smartphone-integrated accessories.
- Scent Generators:Standalone diffusion hardware for commercial HVAC integration.
- Digital Fragrances:Software-encoded scent profiles transmitted for remote synthesis.
Olfactory Displays holds the largest share; momentum sits with Scent-Enabled Devices.
Application:
Cost tier separation runs steep between enterprise VR deployments requiring calibration certification and mass-market gaming peripherals competing on component cost.
- Virtual Reality:Headset-integrated olfactory modules demand sub-10-gram form factors with parts-per-billion detection precision. Healthcare simulation centers in the United States and Japan represent the highest-margin procurement segment, with METI-backed institutions requiring JIS-traceable validation protocols. EPA volatile organic compound thresholds constrain cartridge formulation flexibility for US clinical deployments.
- Gaming:Peripheral manufacturers compete on price points accessible to consumer budgets, with force-feedback haptics capturing immersive spend that might otherwise flow to scent hardware. Chinese and South Korean electronics assemblers dominate component supply.
- Advertising:Point-of-sale diffusion systems for retail environments.
- Marketing:Experiential campaign deployments with temporary installation requirements.
Virtual Reality commands premium pricing; Gaming expands most quickly.
End User:
Volume concentration sits with entertainment contracts, while healthcare applications concentrate future demand growth in diagnostic and therapeutic segments.
- Entertainment:Theme park operators in Orlando, Tokyo, and Singapore commission permanent scent-integrated theatrical systems. Multi-year procurement cycles lock in hardware refresh schedules. Content owners demand piracy-resistant cartridge architectures that constrain supplier margins through proprietary interface requirements.
- Healthcare:Wound assessment and disease screening applications require FDA premarket notification pathways that extend development timelines. German and Swiss pharmaceutical manufacturers are piloting electronic nose systems for batch consistency testing.
- Retail:In-store ambient scenting for customer experience management.
- Education:Training simulation for medical and hazardous material handling.
Entertainment holds the largest share; Healthcare shows the steepest expansion trajectory.
Distribution Channel:
Customer type separation distinguishes enterprise buyers requiring integration services from consumer purchasers prioritizing convenience and price transparency.
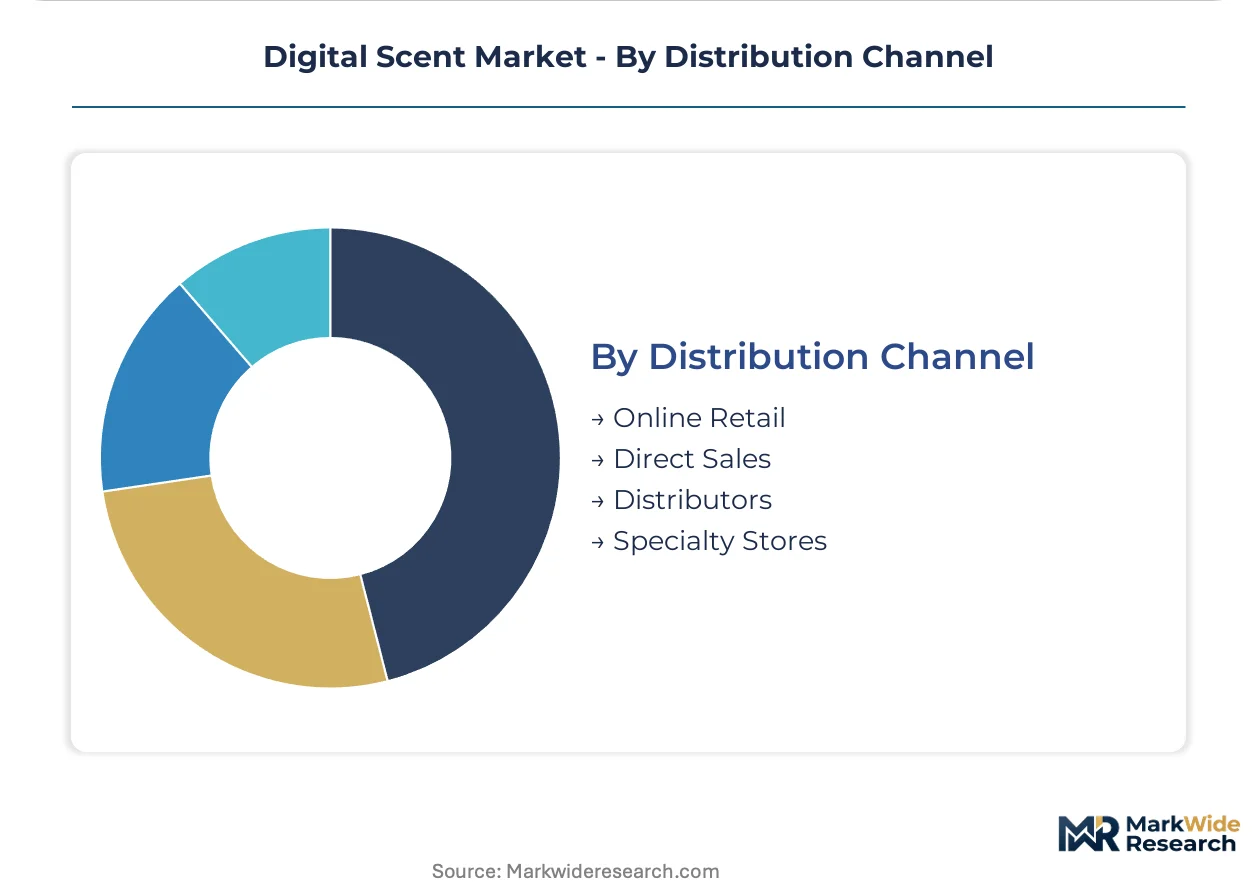
- Direct Sales:Enterprise procurement of quality control systems for food and pharmaceutical manufacturing consolidates through manufacturer relationships. Japanese METI-certified integrators bundle hardware with calibration services and regulatory documentation.
- Online Retail:Consumer-facing scent-enabled peripherals reach mass markets through platform distribution. South Korean and Chinese electronics brands dominate this channel with aggressive pricing.
- Distributors:Regional warehousing and technical support for commercial installations.
- Specialty Stores:High-touch demonstration environments for premium consumer products.
Direct Sales captures the largest share; Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for aroma-encapsulation polymers tilts trade balances toward Germany and Japan, while semiconductor-integrated scent sensors flow from Taiwanese and South Korean foundries. Export revenues concentrate in cartridge-based hardware systems where proprietary architectures command premium positioning.
United States
Orlando-based theme park operators commission permanent scent-integrated theatrical installations, locking in multi-year hardware procurement cycles. EPA volatile organic compound thresholds constrain cartridge formulation flexibility through third-party emissions testing mandates. FDA diagnostic pathway requirements extend development timelines for wound-assessment applications in Boston-area medical simulation centers.
Japan
METI-backed JIS standardization programs reduce integration friction for domestic cartridge suppliers serving immersive entertainment contracts. PMDA oversight shapes medical device classification thresholds for disease-screening hardware deployments. Tokyo and Osaka industrial clusters concentrate domestic technology commercialization through standardized interoperability protocols.
Germany
Specialized polymer feedstock suppliers in the Rhine-Ruhr region anchor aroma-encapsulation substrate production for European hardware manufacturers. ECHA REACH compliance requirements govern chemical emissions profiles for scent-emitting devices sold across EU member states. Bavarian pharmaceutical manufacturers pilot electronic nose systems for batch consistency testing in active ingredient production.
South Korea
Seoul-based consumer electronics assemblers drive volume procurement for smartphone-integrated scent-enabled accessories. MFDS medical device regulations influence diagnostic hardware certification pathways for export-oriented manufacturers. Busan-Ulsan industrial corridors concentrate MEMS-based microchip sensor fabrication through foundry partnerships with domestic semiconductor houses.
China
Guangdong and Jiangsu provinces house contract manufacturers producing gaming peripherals competing on component cost compression. NMPA medical device registration requirements create regulatory friction for diagnostic hardware market entry. Shenzhen electronics clusters dominate mass-market scent-enabled device assembly for platform distribution through online retail channels.
Digital Scent Market Vendor Landscape
Concentration sits with cartridge-architecture specialists and semiconductor-integrated sensor developers, while laboratory-grade calibration providers occupy protected premium tiers. The vendor base splits between closed entertainment systems demanding piracy-resistant delivery and open-architecture healthcare platforms requiring formulation flexibility. Two dominant competitive moves are reshaping positioning: strategic partnerships with systems integrators bundling hardware with regulatory documentation, and backward integration into specialized polymer feedstock production to secure input cost stability.
Within the cartridge-architecture tier, Aromajoin Corporation anchors proprietary entertainment installation contracts through locked system designs. Alpha MOS SA exemplifies laboratory-grade sensor calibration specialists sustaining premium pricing in quality assurance segments. Owlstone Inc. represents silicon-based microchip fabrication expertise extending into miniaturized olfactory detection arrays.
| Leading Market Players |
|---|
| Aromajoin Corporation |
| Scent Sciences Corporation |
| Scentcom Ltd. |
| Electronics Sensor Technology |
| Sensigent |
| Aroma Bit, Inc. |
| Alpha MOS SA |
| The eNose Company |
| Owlstone Inc. |
| Others |
Supply Flow & Price Mechanics
EPA volatile organic compound certification gates both supplier qualification and cartridge price differentiation simultaneously, forcing hardware vendors to absorb third-party emissions testing costs or relocate assembly to permissive jurisdictions. Entertainment operators in Orlando and Tokyo pay configured-to-order premiums for JIS-traceable validation protocols, while mass-market gaming peripherals compete on standard component pricing from Shenzhen contract manufacturers.
Pricing Analysis
Configured-to-order pricing for healthcare-grade olfactory displays commands substantial premiums over standard gaming peripherals due to FDA premarket notification documentation and METI-certified calibration services. Three-tier pricing structure across premium, standard, and economy levels separates laboratory-grade sensor arrays from entertainment installations and consumer accessories. Pricing pressure stems from force-feedback haptics capturing immersive entertainment budgets that might otherwise flow to scent hardware. Gaming segment buyers exhibit highest price sensitivity, while pharmaceutical quality control procurement shows lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Strategic stockpiling of aroma-encapsulation polymers dominates procurement behavior given concentration among three German chemical suppliers in the Rhine-Ruhr region. Hardware manufacturing draws from Taiwanese and South Korean foundries for MEMS-based microchip sensors, Japanese domestic production for cartridge architectures, and Guangdong contract assemblers for mass-market peripherals. Single-source vulnerability in specialized polymer feedstock exposes manufacturers to allocation risk during supply shocks. Distribution runs through METI-certified systems integrators in Japan and direct manufacturer relationships for enterprise quality control deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital scent technology represents a high-growth disruption as MEMS fabrication advances collapse unit costs for wearable form factors and EPA emissions frameworks reshape hardware certification requirements. Stakeholders must position across diverging entertainment and healthcare regulatory pathways.
For Market Incumbents: Secure backward integration into specialized polymer feedstock production to stabilize input costs against German supplier concentration. Lock in multi-year theme park installation contracts in Orlando and Tokyo before haptic substitution accelerates. Prioritize JIS certification investment to maintain premium positioning in METI-backed procurement channels.
For New Entrants and Emerging Players: Lead with pharmaceutical batch consistency testing applications where gas chromatography dominates and electronic nose deployment remains underpenetrated. Target EU CSRD-mandated remote inspection systems as sustainability reporting creates procurement preference for auditor-travel-reduction hardware. Pursue channel partnership with laboratory service integrators rather than direct manufacturer competition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across MEMS-integrated sensor arrays as semiconductor foundries apply standard fabrication processes. Long-term viability favors platform plays spanning hardware-software integration over standalone component suppliers. Acquisition target archetype: mid-cap specialists with FDA diagnostic pathway experience and existing JIS traceability. Watch for AI pattern recognition convergence with sensor arrays as disease-screening application inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Cartridge Interoperability Standardization | METI-backed JIS protocols reduce integration friction for Asian supply chain partners. |
| MEMS Fabrication Partnership | Taiwanese and South Korean foundries collapse unit costs for wearable olfactory sensors. |
| FDA Diagnostic Pathway Investment | Premarket notification capability opens wound-assessment and disease-screening revenue pools. |
| Polymer Feedstock Backward Integration | In-house production of aroma-encapsulation substrates mitigates German supplier concentration risk. |
| Systems Integrator Channel Alliance | METI-certified bundling of hardware with calibration services captures enterprise procurement consolidation. |
Methodological Framework
A spread of perspectives from theme park operations executives, pharmaceutical quality control directors, MEMS fabrication engineers, and EPA compliance officers converged on the working assumptions. Primary interviews combined with secondary validation from FDA 510(k) filings, METI technology roadmaps, JIS standard documentation, and semiconductor foundry capex disclosures. Bottom-up unit economics triangulated against top-down market sizing across technology segments and geographic procurement clusters.
Segmentation dimensions modeled include hardware architecture type, application use case, end-user industry vertical, and distribution channel structure across the projection horizon. CAGRs derived from installed base growth rates, replacement cycle analysis, and penetration curve modeling for immersive entertainment versus healthcare diagnostic applications. Forecast inputs incorporated EPA emissions threshold evolution, MEMS cost curves, and JIS standard adoption timelines.
Forecasts assume regulatory continuity in EPA volatile organic compound frameworks and FDA medical device classification pathways; material policy shifts would require re-modeling. Specific risk factors include haptic technology substitution acceleration, polymer feedstock supply disruption, and diagnostic reimbursement denial. Revision becomes warranted when force-feedback glove adoption crosses entertainment budget allocation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Global Fragrances and Perfumes Market
Fragrances & Perfumes
Wax Melts Market
Fragrances & Perfumes
GCC Perfume Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Digital Perfume Market
Fragrances & Perfumes
Cosmetic and Fragrance Retail Chain Market
Fragrances & Perfumes
Fragrance Diffuser Market
Fragrances & Perfumes
Middle East Fragrances Market
Fragrances & Perfumes
Scented Oil Market
Fragrances & Perfumes
Digital Fragrance Market
Fragrances & Perfumes
Home Fragrance Market
Fragrances & Perfumes
Floral Water Spray Market
Fragrances & Perfumes
North America Perfume Market
Fragrances & Perfumes
Global Luxury Perfumes Market