
 Global Luxury Perfumes Market | 2026-2036
Global Luxury Perfumes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Luxury Perfumes Market Foresight
Aftermarket service revenue from fragrance refills and personalized engraving is narrowing as brands pull these touchpoints in-house to capture lifetime customer value. LVMH Moët Hennessy Louis Vuitton leverages its Dior and Guerlain ateliers to sustain direct relationships with collectors through limited-edition releases. CHANEL anchors its exclusivity via tightly controlled distribution, while Puig competes through creative director investments at Byredo and Charlotte Tilbury.
Luxury perfumes denote high-concentration fragrance formulations, typically exceeding fifteen percent aromatic compounds in alcohol solution, crafted through multi-stage maceration and controlled aging to achieve olfactory stability and sillage projection for personal adornment. Eau de Parfum leads volume contribution due to its concentration-to-price accessibility, yet Perfume Oil commands the densest margin pool among connoisseur segments. Duty-Free Shops remain structurally significant for traveler-driven discovery, though Online Retailers are displacing them as the fastest-growing channel for repeat purchases among digitally native affluents.
EU REACH and the FDA's fragrance allergen disclosure requirements in the United States are tightening compositional transparency, compelling reformulation investments that smaller houses struggle to absorb. The EU Green Deal's chemical sustainability targets are accelerating botanical sourcing audits across European supply chains. Stakeholders must monitor how regulatory divergence between Brussels and Washington reshapes product registration costs and speed-to-market timelines for new launches.
Market Dynamics
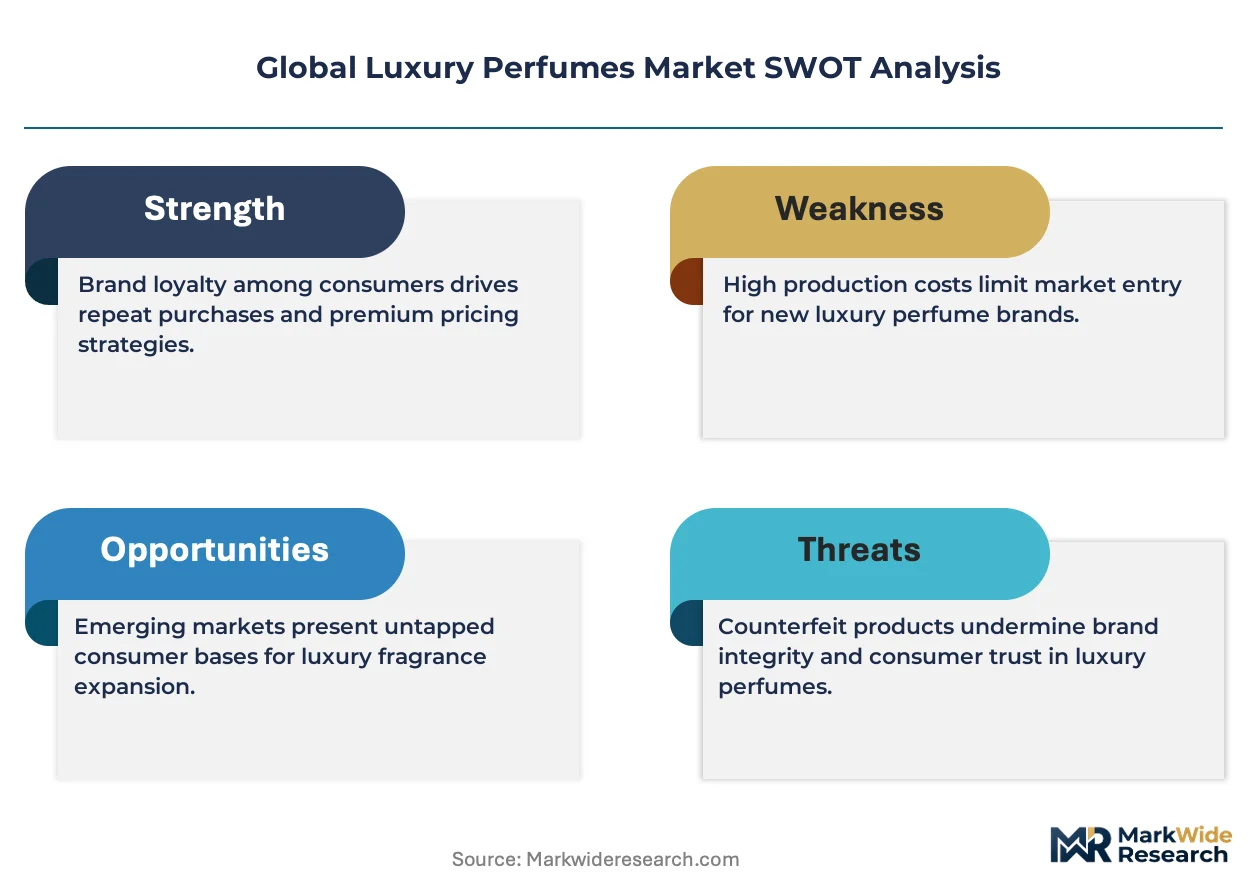
EU REACH's fragrance allergen disclosure mandates are forcing systematic reformulation of legacy compositions while houses race to preserve olfactory signatures, compressing R&D timelines and elevating compliance costs across European supply chains.
Growth Catalysts
- Asia-Pacific HNI Fragrance Wardrobe Expansion:High-net-worth individuals in Shanghai, Tokyo, and Singapore are building occasion-specific collections beyond signature scents, multiplying per-capita purchase frequency.
- REACH-Driven Clean Label Premiumization:EU allergen transparency rules are converting compliance investment into marketing differentiation for houses that achieve reformulation without sensory compromise.
- Biotechnology in Botanical Sourcing:Cell-cultured oud and sandalwood alternatives are stabilizing supply of endangered raw materials while satisfying sustainability auditing requirements under the EU Green Deal.
Market Restraints
- Natural Ingredient Price Volatility:Climate-stressed harvests in Grasse, Madagascar, and Indonesia are amplifying cost swings for jasmine absolute and ylang-ylang essential oil.
- Glass and Aluminum Supply Concentration:European specialty bottle foundries and Italian cap manufacturers operate at capacity constraints, extending lead times for limited-edition packaging.
- Reformulation Technical Limitations:Substituting oakmoss and certain musk compounds without destabilizing fragrance architecture remains chemically challenging for heritage compositions.
Strategic Opportunities
- India's Underserved Affluent Tier-Two Cities:Hyderabad, Pune, and Ahmedabad present whitespace for prestige fragrance entry as disposable income concentrates beyond Mumbai and Delhi.
- Refill Station Network Expansion:Paris, London, and New York are piloting in-boutique fragrance replenishment systems that capture lifetime value through repeat traffic.
- AI-Assisted Personalization Convergence:Machine learning algorithms combined with biometric skin chemistry analysis are enabling bespoke scent matching at scale for digitally native consumers.
Industry Challenges
- Perfumer Talent Scarcity:Master perfumer training through ISIPCA and Givaudan programs requires decade-long apprenticeship pipelines that houses struggle to accelerate.
- Multi-Jurisdiction Registration Complexity:Diverging fragrance allergen thresholds between EU REACH, FDA disclosure rules, and China's GB standards fragment product registration workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Luxury Perfumes Market |
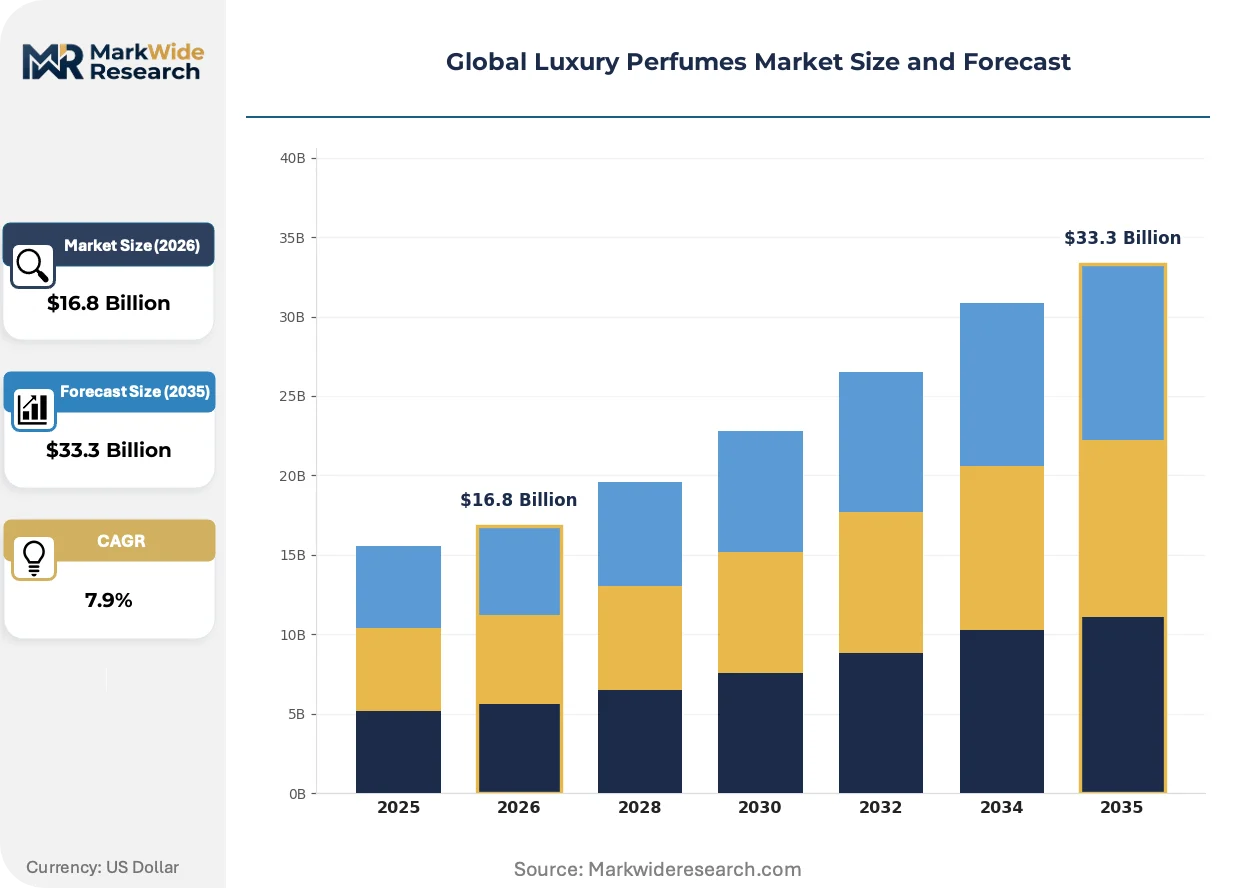
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $33.3 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eau de Parfum, Eau de Toilette, Cologne, Perfume Oil, Solid Perfume Application: Personal Fragrance, Gift, Aromatherapy, Bridal, Celebrity Endorsement End User: Men, Women, Unisex, Collectors, High-Net-Worth Individuals Distribution Channel: Department Stores, Specialty Stores, Online Retailers, Luxury Boutiques, Duty-Free Shops |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton, CHANEL, Coty Inc., The Estée Lauder Companies, Hermès International, Kering, Puig, L'Oréal Groupe, Compagnie Financière Richemont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Luxury Perfumes Market Shifts & Advancements
Digital scent technologies and biotechnological ingredient platforms are converging to reshape how fragrances are composed, tested, and experienced, compressing traditional development cycles while opening new sensory frontiers.
AI-driven molecular simulation is virtualizing the fragrance development process. Givaudan and Firmenich deploy generative algorithms to predict odor profiles from chemical structures, cutting compound screening time. Niche houses in Paris and New York adopt these platforms to accelerate limited-edition pipelines. The technology is virtualizing physical laboratory workflows and compressing the traditional 18-month development cycle into quarterly release cadences.
REACH's expanded allergen labeling requirements are restructuring European formulation practices. The regulation now mandates disclosure of over 80 fragrance sensitizers at concentrations above 0.001 percent in rinse-off products. Heritage houses face reformulation costs exceeding €500,000 per classic scent to maintain EU market access. Eau de Parfum concentrations bear the heaviest compliance burden due to higher aromatic compound loads.
Discovery commerce through live-streaming platforms is displacing traditional counter sampling. Chinese consumers on Douyin and Xiaohongshu purchase full bottles based on influencer-led scent storytelling without physical testing. This behavior compresses the consideration-to-purchase window from weeks to minutes. Tier-one cities including Shanghai, Beijing, and Shenzhen exhibit the highest conversion rates for live-commerce fragrance launches.
Global Luxury Perfumes Market Segmentation
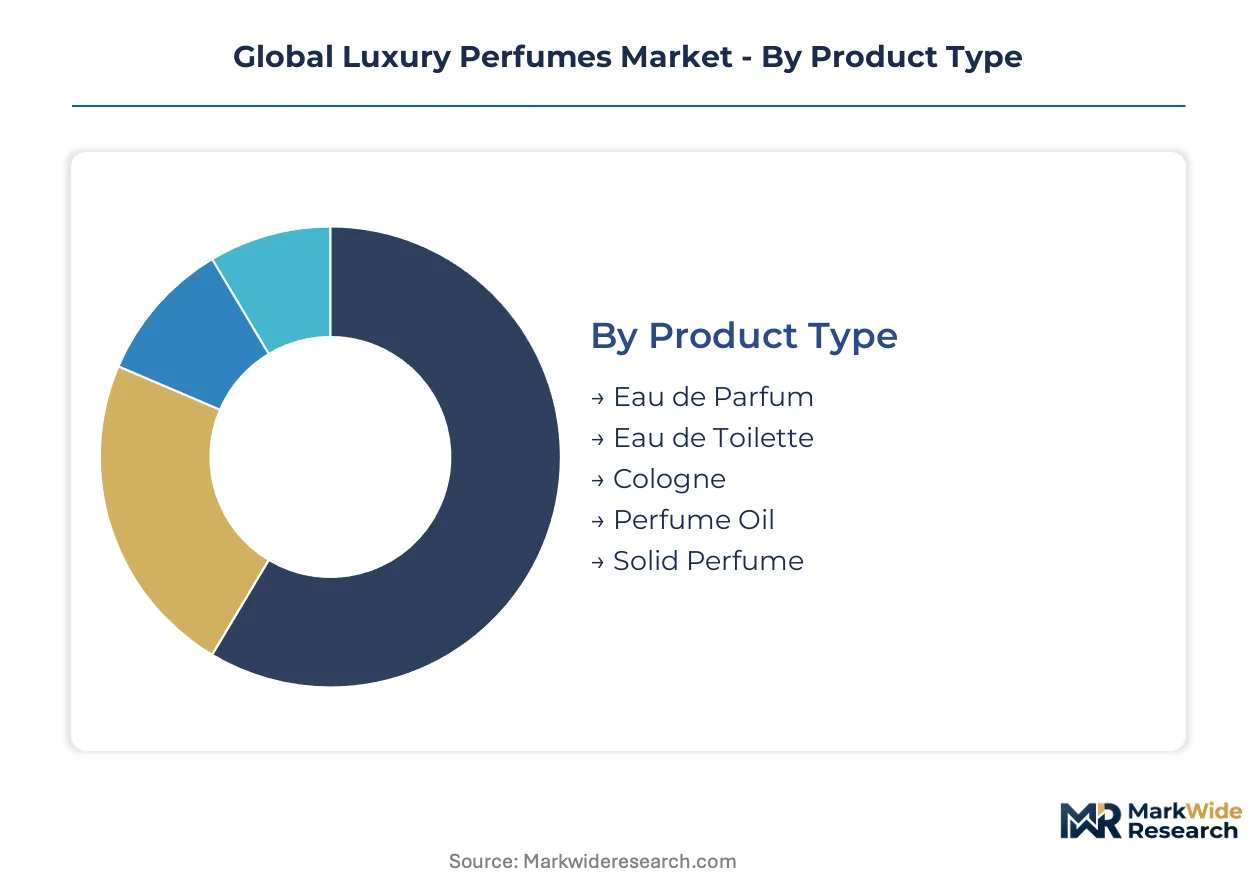
Luxury perfume segmentation reveals how concentration levels, ritual contexts, and purchase occasions fragment demand across distinct margin pools. Houses calibrate portfolio architecture across these dimensions to capture lifetime value from entry-level discovery through connoisseur collecting.
Product Type:
Concentration tiers define the technical and commercial architecture of fragrance portfolios, with alcohol-to-oil ratios determining price positioning and wear occasion.
- Eau de Parfum:Formulations carry fifteen to twenty percent aromatic compounds in alcohol solution, delivering six-to-eight hour longevity with moderate sillage projection. Shanghai and Beijing consumers treat this as the accessible entry point into prestige house ecosystems, driving volume concentration in China's tier-one cities despite compressed margins versus higher concentrations.
- Perfume Oil:Anhydrous or low-alcohol concentrates exceed twenty-five percent aromatic load, offering skin-close longevity and travel-friendly formats. Collector segments in Tokyo and Dubai absorb premium pricing for these compositions, with supply constrained by botanical sourcing audits under EU Green Deal chemical sustainability targets.
- Eau de Toilette:Lighter concentrations of five to fifteen percent aromatic compounds suit office and daytime wear contexts.
- Cologne:Traditional citrus-forward formulations at two to five percent concentration serve warm-climate markets and masculine grooming rituals.
- Solid Perfume:Wax-based carriers enable precise application and TSA-compliant portability for frequent travelers.
Eau de Parfum commands the established base. The steepest expansion runs through Perfume Oil.
Application:
Ritual and gifting contexts determine purchase timing, bottle sizing, and packaging investment levels across the fragrance calendar.
- Personal Fragrance:Daily-wear purchases dominate replenishment cycles, with consumers building occasion-specific wardrobes rather than single signature scents. Singapore and Hong Kong high-net-worth individuals now maintain separate collections for business, evening, and leisure contexts, multiplying per-capita purchase frequency.
- Gift:Seasonal and celebration-driven purchases command premium packaging investment and limited-edition releases. Lunar New Year and Valentine's Day concentrate demand in China's duty-free corridors and department store fragrance halls, with gift recipients often converting to repeat personal purchasers.
- Aromatherapy:Functional fragrance positioning targets wellness-oriented consumers seeking stress modulation and sleep support.
- Bridal:Bespoke composition services and engraved bottles capture once-in-a-lifetime purchase occasions.
- Celebrity Endorsement:Licensed fragrance lines leverage parasocial attachment to convert fan bases into fragrance buyers.
Personal Fragrance anchors recurring revenue. Gift applications drive the highest margin per transaction.
End User:
Gender positioning and collector intensity stratify demand across mass-affluent entry points and ultra-high-net-worth connoisseur segments.
- Women:Traditional category concentration in floral, oriental, and chypre families sustains volume leadership. Paris and Milan houses invest heavily in feminine blockbuster launches, though reformulation costs under EU REACH allergen disclosure rules compress margins on heritage compositions.
- Collectors:Limited-edition chasers and vintage hunters absorb ultra-premium pricing for discontinued or numbered releases. LVMH and CHANEL sustain direct relationships with this segment through atelier access and pre-release allocation, capturing lifetime value that mass-market channels cannot replicate.
- Men:Woody, aromatic, and leather fragrance families dominate masculine positioning.
- Unisex:Gender-neutral marketing expands addressable audience for niche and artistic lines.
- High-Net-Worth Individuals:Bespoke services and private consultations serve the apex of the market.
Women's fragrances represent the volume foundation. Collector segments are expanding most quickly as houses pull aftermarket services in-house.
Distribution Channel:
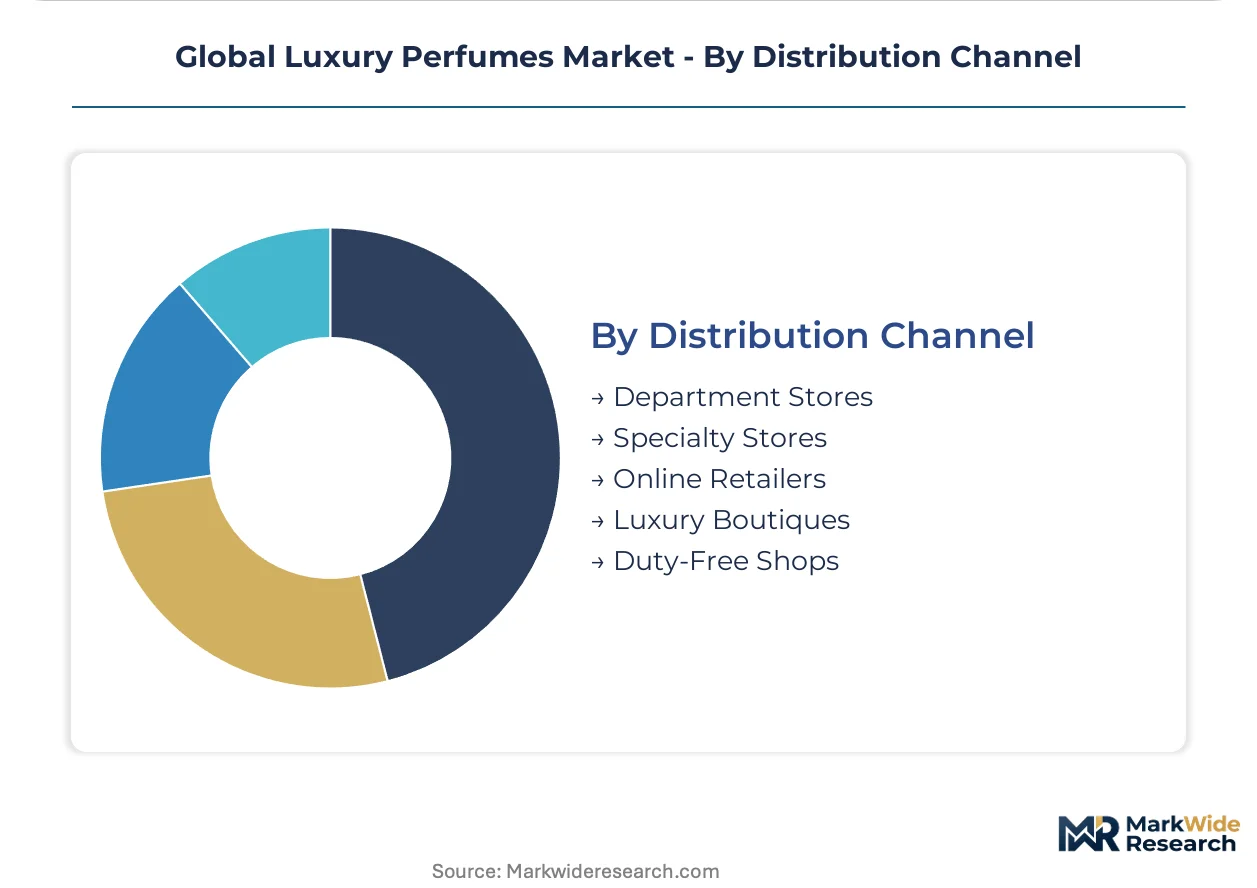
Channel mix determines discovery mechanics, margin capture, and customer data ownership for fragrance houses.
- Online Retailers:Digital-native affluents complete repeat purchases through brand.com and prestige e-commerce platforms, bypassing physical discovery. Douyin and Xiaohongshu live-streaming compresses consideration-to-purchase windows to minutes for Chinese consumers who purchase full bottles without physical testing.
- Duty-Free Shops:Traveler-driven discovery remains structurally significant for geographic expansion and tourist conversion. Dubai International and Singapore Changi serve as launch platforms for Middle East and Asia-Pacific market entry, though online channels are displacing them for replenishment purchases.
- Department Stores:Counter sampling and beauty advisor consultation sustain trial-driven acquisition.
- Specialty Stores:Curated multi-brand environments serve discovery-oriented consumers.
- Luxury Boutiques:Flagship environments enable full brand immersion and personalized services.
Department Stores command the established base. Online Retailers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese consumers in Shanghai and Beijing exhibit the lowest price elasticity for prestige fragrance, while Brazilian buyers in São Paulo remain highly sensitive to currency-driven pricing shifts. This demand-elasticity contrast shapes how houses calibrate portfolio depth versus accessibility across markets.
France
Grasse-based raw material houses supply jasmine and rose absolutes to global fragrance compounders, with harvest volatility under climate stress amplifying input cost swings. ECHA REACH enforcement mandates allergen disclosure thresholds that heritage maisons navigate through systematic reformulation programs. Paris ateliers concentrate limited-edition production and collector relationship management for LVMH and CHANEL.
United States
New York and Los Angeles consumers drive discovery commerce through TikTok and Instagram, converting parasocial influencer attachment into full-bottle purchases without physical testing. FDA fragrance allergen disclosure rules diverge from EU thresholds, fragmenting product registration workflows for houses launching simultaneously across both markets. Miami serves as the primary gateway for Latin American tourist purchasing and duty-free conversion.
China
Shanghai, Beijing, and Shenzhen consumers treat Eau de Parfum as accessible entry points into prestige brand ecosystems, multiplying per-capita purchase frequency through occasion-specific wardrobe building. SAMR and GB standards on cosmetic labeling impose disclosure requirements distinct from EU REACH, complicating harmonized product development. Hainan duty-free corridors concentrate traveler-driven discovery and Lunar New Year gifting volume.
Japan
Tokyo collectors absorb ultra-premium pricing for Perfume Oil concentrations and limited-edition releases, sustaining dense margin pools despite compressed volume. METI chemical management frameworks align partially with EU sustainability auditing, reducing registration friction for European houses entering the market. Osaka and Nagoya retail clusters specialize in personalized engraving and atelier services for connoisseur segments.
United Arab Emirates
Dubai and Abu Dhabi consumers blend traditional oud preferences with Western prestige house adoption, creating hybrid demand for concentrated oil formats. MOHAP cosmetic registration requirements mandate local testing protocols that extend launch timelines for new market entrants. Dubai International Airport duty-free operations remain structurally significant for Middle East market entry and tourist conversion.
Global Luxury Perfumes Market Competitive Landscape
Capability concentration sits with heritage ateliers possessing master perfumer apprenticeships and controlled raw material sourcing; scale advantage sits with diversified beauty conglomerates with cross-category marketing infrastructure. The market structures around three tiers: vertically integrated luxury groups with captive fragrance-to-fashion ecosystems, independent creative houses competing through artistic director investments, and multi-brand beauty portfolios leveraging shared distribution. Dominant competitive moves include direct-to-consumer channel capture and biotechnology partnerships for sustainable ingredient substitution.
Within the vertically integrated tier, LVMH Moët Hennessy Louis Vuitton and CHANEL exemplify archetypes of atelier-controlled exclusivity and tightly managed distribution. Puig occupies a position between creative independence and scale, anchoring the specialist-acquisition strategy visible across mid-size houses. These three entities represent distinct competitive postures: captive ecosystem depth, scarcity-driven brand equity, and creative-director-led portfolio expansion.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton |
| CHANEL |
| Coty Inc. |
| The Estée Lauder Companies |
| Hermès International |
| Kering |
| Puig |
| L'Oréal Groupe |
| Compagnie Financière Richemont |
| Others |
Supply & Pricing Matrix
EU REACH allergen disclosure mandates function as a regulatory chokepoint that simultaneously compresses R&D timelines and widens pricing spreads between heritage reformulations and clean-label native launches, forcing supply chain reconfiguration toward audited botanical sources and captive atelier production.
Pricing Analysis
Fragrance refill and personalized engraving services drive lifetime value capture as houses pull these touchpoints in-house from third-party providers. Three-tier pricing structure across prestige, niche, and entry-level concentrations separates collector-grade Perfume Oil from mass-accessible Eau de Parfum. Pricing pressure stems from climate-stressed harvest volatility in Grasse and Madagascar, which amplifies input cost swings for jasmine absolute. Brazilian buyers in São Paulo exhibit the highest price sensitivity to currency shifts, while Shanghai consumers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Givaudan, Firmenich, and Symrise hold concentrated capacity for fragrance compound production across Switzerland, France, and the United States. Grasse-derived jasmine and rose absolutes, Madagascan ylang-ylang, and Indonesian patchouli constitute critical botanical dependencies. Single-source vulnerability concentrates in European specialty glass foundries and Italian cap manufacturers operating at capacity constraints. Distribution runs through duty-free corridors at Dubai International and Singapore Changi for discovery, with brand.com displacing physical channels for replenishment among digitally native affluents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Live-streaming commerce platforms are reconfiguring fragrance discovery as a platform-economics inflection, with Douyin and Xiaohongshu algorithmic distribution creating new interoperability between influencer storytelling and direct purchase conversion.
For Market Incumbents: Harden atelier-controlled exclusivity by accelerating master perfumer apprenticeship pipelines at ISIPCA and Givaudan programs to counter talent scarcity. Deepen backward integration into cell-cultured oud and sandalwood alternatives through biotechnology partnerships, insulating supply from EU Green Deal sustainability auditing disruptions and climate-stressed harvest volatility. For New Entrants and Emerging Players: Establish a beachhead in India's tier-two cities—Hyderabad, Pune, and Ahmedabad—where prestige fragrance penetration lags disposable income concentration. Target occasion-specific wardrobe building among Asia-Pacific high-net-worth individuals through AI-assisted personalization platforms that bypass the decade-long perfumer training bottleneck. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated luxury groups with captive fragrance-to-fashion ecosystems over standalone creative houses. Acquisition targets should display controlled raw material sourcing and direct-to-consumer channel ownership. Watch for regulatory divergence between EU REACH and China's GB standards as the signal indicating which houses can sustain multi-jurisdiction registration scale.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Partnership for Sustainable Ingredients | Cell-cultured alternatives stabilize endangered raw material supply under EU Green Deal audits. |
| Direct-to-Consumer Channel Capture | Brand.com platforms displace duty-free for replenishment among digitally native affluents. |
| AI-Assisted Personalization Platform Launch | Machine learning algorithms compress bespoke scent matching to scale for connoisseur segments. |
| Refill Station Network Expansion | In-boutique replenishment systems capture lifetime value through repeat traffic in Paris and London. |
| Master Perfumer Apprenticeship Acceleration | ISIPCA and Givaudan program investments counter talent scarcity constraining heritage houses. |
Research Methodology
A standing panel of master perfumers, fragrance house R&D directors, luxury retail buyers, and duty-free procurement managers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from ECHA REACH filings, customs trade data for botanical imports, and SEC disclosures from listed beauty conglomerates. Bottom-up volume modeling across concentration tiers and top-down value reconciliation anchored the analytical framework.
Scenario-bracketing around regulatory implementation timelines and climate stress harvest outcomes bounded the projection range. Segmentation dimensions included product concentration level, application context, end-user collector intensity, and distribution channel mix. CAGRs derived from trend-line extrapolation of per-capita purchase frequency and pricing evolution, with inputs from live-streaming commerce conversion data and biometric personalization technology adoption curves.
Sensitivities concentrate around EU-China regulatory divergence, biotechnology scale-up timelines for cultivated ingredients, and live-streaming platform algorithm shifts. Quarterly review of REACH enforcement patterns, Hainan duty-free corridor traffic, and refill station pilot performance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Fragrance Diffuser Market
Fragrances & Perfumes
Saudi Arabia E-Commerce Cosmetics and Fragrances Market
Fragrances & Perfumes
North America Perfume Market
Fragrances & Perfumes
Kuwait Perfume Market
Fragrances & Perfumes
Digital Scent Market
Fragrances & Perfumes
Global Scented Candle Market
Fragrances & Perfumes
Gourmand Fragrance Market
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
UAE Perfume Market
Fragrances & Perfumes
Middle East Fragrances Market
Fragrances & Perfumes
Smart Fragrance Box Market
Fragrances & Perfumes
GCC Perfume and Fragrance Market
Fragrances & Perfumes
Organic Perfumes Market
Fragrances & Perfumes
Clean Perfume Market
Fragrances & Perfumes
Digital Fragrance Market