
 Digital Content Creator Market | 2026-2036
Digital Content Creator Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Content Creator Market Outlook
Revenue-sharing and platform-native monetization tools are narrowing the capital barrier for independent creators who previously required external production financing. WebFX leverages its full-service agency model to anchor enterprise clients seeking end-to-end creator campaign management. Viral Nation differentiates through talent representation and brand safety technology that sustains its position in high-stakes sponsorship markets. Single Grain competes by specializing in performance-driven content strategies for technology and SaaS verticals.
A digital content creator produces and distributes original media across internet platforms, typically employing video encoding standards such as H.264 or H.265, adaptive bitrate streaming, and algorithm-optimized metadata tagging to maximize reach and engagement. The primary commercial purpose is audience monetization through advertising, direct payments, or brand partnerships that convert attention into measurable business outcomes. Video format dominates platform economics because advertisers allocate premium budgets to sight-sound-motion inventory that outperforms static alternatives in engagement metrics. Subscription monetization now captures the most favorable margin pools as recurring revenue reduces creator dependence on volatile algorithmic distribution and seasonal advertising cycles.
The Federal Trade Commission in the United States enforces endorsement disclosure rules that shape how creators structure sponsored content and brand partnerships. The European Union's Digital Services Act and GDPR compliance requirements impose content moderation and data handling standards that increase operational complexity for cross-border creators. India's Information Technology Rules mandate traceability and grievance mechanisms that affect platform-creator contractual relationships. Stakeholders must monitor how fragmented regulatory frameworks across these jurisdictions will force platform business models and creator compliance tools to evolve in parallel.
Market Dynamics
Enterprise marketing departments now drive demand concentration as they reallocate budgets from traditional advertising toward creator-led campaigns, fundamentally altering how content production capital flows through the ecosystem.
Growth Catalysts
- FTC Endorsement Disclosure Enforcement:Clearer sponsored content rules reduce brand legal exposure, accelerating enterprise adoption of structured creator partnerships over informal influencer arrangements.
- Short-Form Video Encoding Advances:H.265 and AV1 compression standards slash bandwidth costs for creators distributing high-resolution content on mobile-first platforms.
- India Platform Ecosystem Scale:Massive user bases on domestic short-video applications create concentrated demand pools that attract global brand investment and localize supply chains.
Market Restraints
- Cross-Border Compliance Fragmentation:Simultaneous adherence to GDPR data handling, FTC disclosure mandates, and India's IT Rules grievance mechanisms inflates operational overhead for multi-jurisdiction creators.
- Algorithmic Distribution Volatility:Platform recommendation engine opacity forces creators to maintain redundant content pipelines, elevating production burn rates without guaranteed reach.
- Subscription Fatigue Thresholds:Audience willingness to maintain multiple creator patronage memberships faces hard limits as macroeconomic pressure concentrates disposable spending.
Strategic Opportunities
- EU Digital Services Act Compliance Tools:Mandatory content moderation transparency creates demand for specialized software that creators and agencies can monetize as subscription services.
- B2B SaaS Vertical Expansion:Technology sector procurement of creator-produced educational and thought leadership content remains underpenetrated relative to consumer-facing verticals.
- Live Commerce Integration:Convergence of real-time streaming infrastructure with embedded checkout technology opens transactional revenue streams beyond advertising and sponsorship.
Industry Challenges
- Cross-Functional Talent Scarcity:Creators capable of simultaneously managing video production, data analytics, and brand partnership negotiation command premium rates that strain independent operator economics.
- Platform Dependency Risk:Revenue concentration on single algorithmic feeds exposes creators to catastrophic income disruption from policy changes or account enforcement actions without recourse.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Content Creator Market |
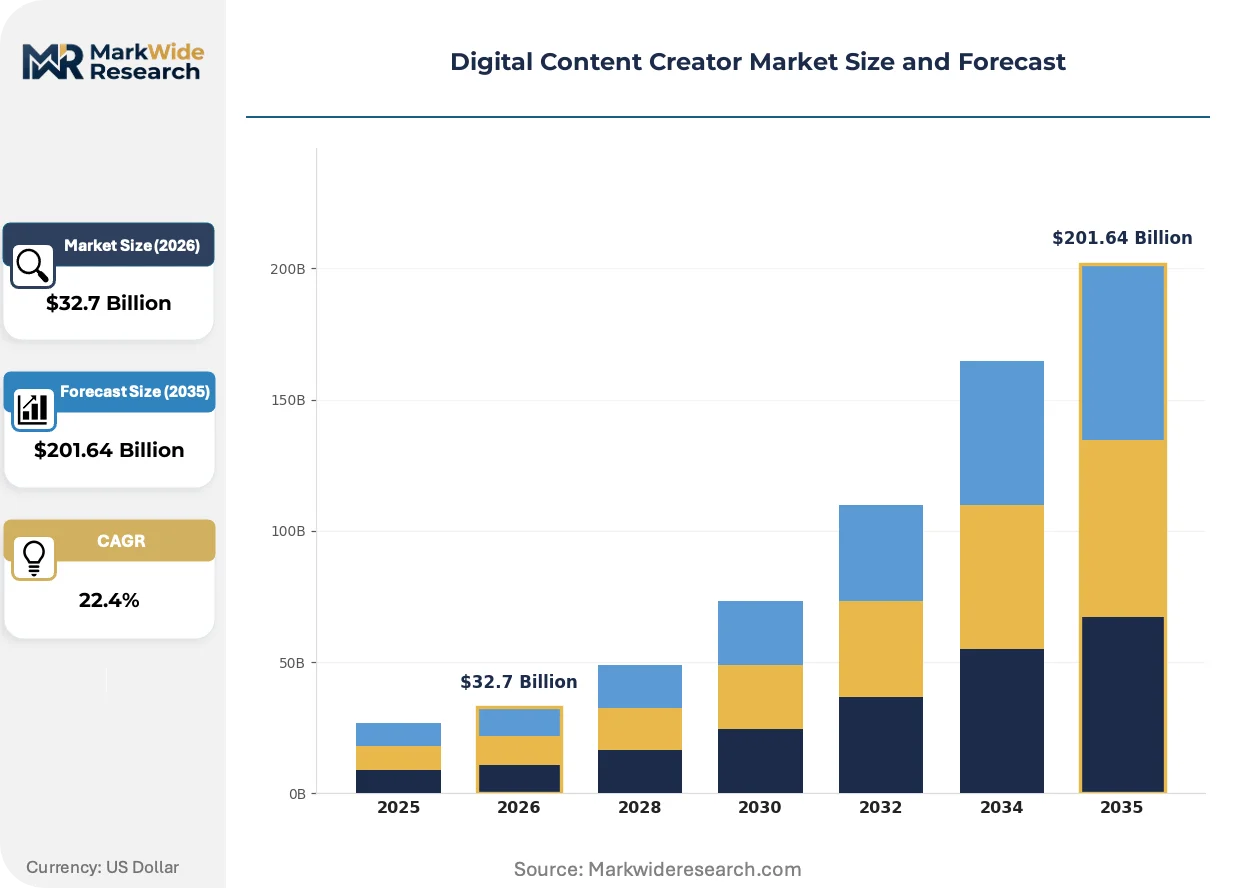
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $201.64 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: YouTube, Instagram, TikTok, Twitch Content Format: Video, Blog, Podcast, Infographic Content Subject: Lifestyle, Education, Technology, Gaming Monetization Strategy: Ad Revenue, Sponsorship, Merchandise, Subscription |
| Companies Covered | WebFX, Animalz, SeriesX Marketing, Viral Nation, Column Five, Single Grain, Siege Media, Wooshii, Brafton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Content Creator Market Strategic Shifts
Generative artificial intelligence tools now permeate content production workflows, compressing creation timelines and forcing fundamental reassessment of what skills retain scarcity value in creator labor markets.
AI-powered video editing suites with automated captioning, B-roll insertion, and multi-platform reformatting capabilities are rendering obsolete the traditional post-production specialist role that previously required dedicated human labor. Mid-tier creators operating without studio backing now adopt these tools at accelerating velocity, collapsing the quality gap between independent and professionally produced content. The structural consequence compresses pricing power for production agencies while elevating creator margins and output frequency.
The European Union's Digital Services Act mandates algorithmic transparency and systematic risk assessments for large platforms, imposing documentation burdens that reshape creator-platform contractual relationships. Platforms must now disclose recommendation system parameters and provide appeal mechanisms for content demotion, altering how creators strategize distribution. Cross-border creators operating under EU jurisdiction face the steepest compliance adaptation costs, driving consolidation toward representation by agencies with dedicated regulatory functions.
Enterprise procurement of creator services now emphasizes performance-guaranteed contracts with defined engagement or conversion metrics rather than flat-fee sponsorship arrangements. Marketing departments increasingly bypass traditional media buying intermediaries to contract creators directly through self-serve platform tools or specialized talent marketplaces. This behavioral shift concentrates most visibly in technology and SaaS verticals where attribution infrastructure supports rigorous outcome measurement.
Digital Content Creator Market Segmentation
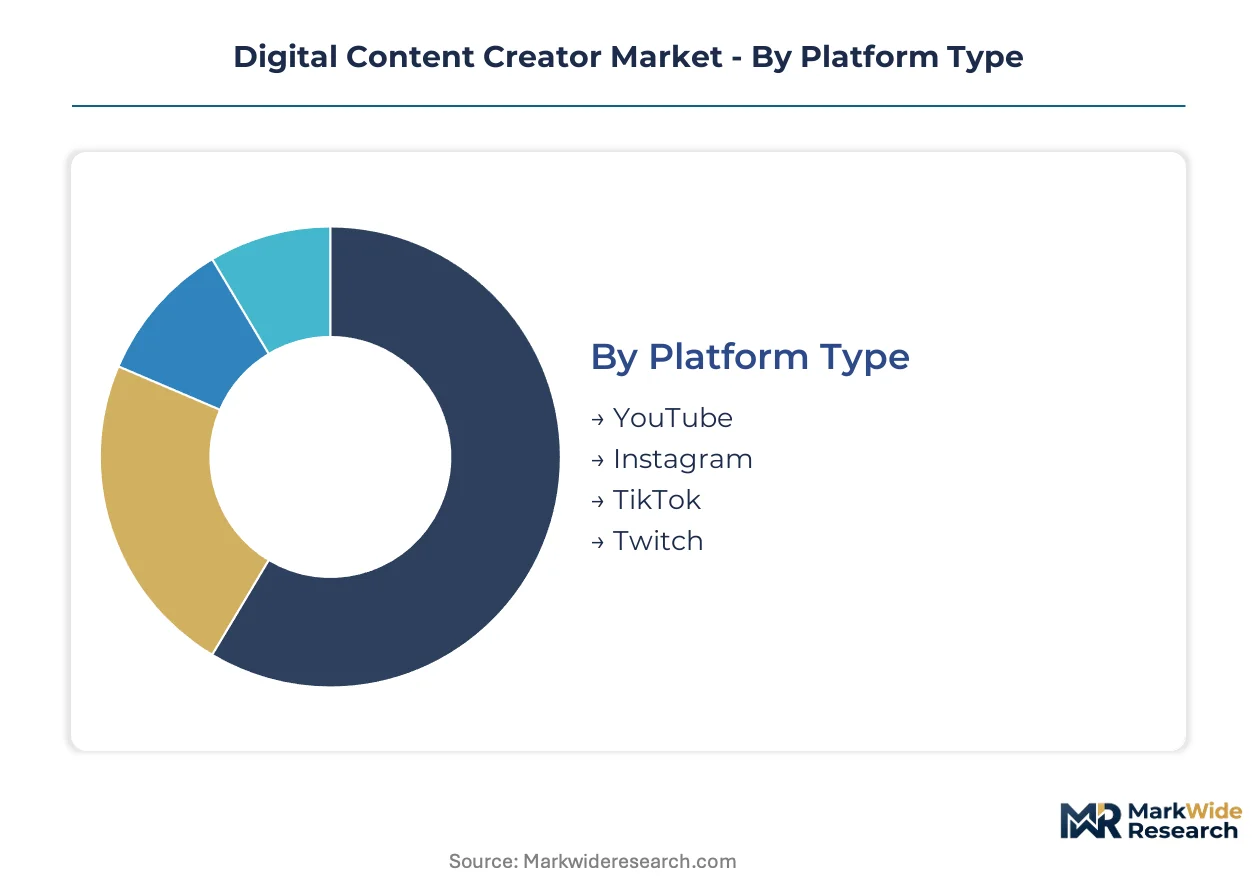
Content creator economics diverge sharply across platform algorithms, format production costs, and monetization mechanics. Understanding these segment boundaries clarifies where capital flows concentrate and which creator archetypes capture sustainable margin pools.
Platform Type:
Cost tier determines creator entry barriers and revenue stability across distribution infrastructure investments.
- YouTube:Long-form video hosting with established Partner Program revenue sharing and search-indexed discoverability. Enterprise advertisers in the United States allocate premium CPM budgets to pre-roll inventory that supports higher production-value content. The FTC endorsement disclosure rules apply most stringently to sponsored integrations on this platform.
- TikTok:Short-form vertical video optimized for algorithmic distribution without follower-gated reach. Creator Fund payouts remain volatile, driving Indian creators toward live commerce and brand partnership diversification. The platform's opacity around recommendation parameters forces redundant content pipeline investments.
- Instagram:Visual-first feed and Reels hybrid with integrated shopping infrastructure. Fashion and lifestyle verticals concentrate here due to native product tagging and checkout features.
- Twitch:Live streaming platform with subscription and direct payment monetization. Gaming content dominates, supported by real-time audience interaction tools.
YouTube commands the established base. The steepest expansion runs through TikTok.
Content Format:
Application determines production resource requirements and advertiser valuation premiums.
- Video:Sight-sound-motion inventory commanding premium CPM rates from brand advertisers seeking engagement metrics. H.265 and AV1 compression standards reduce bandwidth costs for creators distributing high-resolution content. Education and technology verticals in India drive demand concentration.
- Podcast:Audio-native format with lower production overhead and intimate audience relationship dynamics. Host-read sponsorships generate higher conversion rates than pre-produced spots.
- Blog:Text-based content with search-engine dependency and affiliate monetization pathways. Long-form written analysis retains value in B2B SaaS verticals.
- Infographic:Visual data presentation optimized for shareability and social platform distribution. Lower production costs attract resource-constrained independent creators.
Video commands the established base. Podcasts are gaining share fastest.
Content Subject:
Customer type shapes monetization pathway viability and partnership negotiation leverage.
- Gaming:Live streaming and recorded gameplay with embedded sponsorship and esports tournament revenue. Young male demographics attract hardware and energy drink brand investment. Platform dependency risk concentrates on Twitch and YouTube Gaming.
- Education:Tutorial and skill-development content with direct course sales and subscription monetization. Technology sector procurement of creator-produced educational content remains underpenetrated.
- Lifestyle:Personal vlogging and routine documentation with merchandise and brand partnership revenue. Instagram and TikTok serve as primary distribution channels.
- Technology:Product review and software tutorial content with affiliate and sponsorship monetization. Attribution infrastructure supports rigorous outcome measurement for SaaS verticals.
Lifestyle commands the established base. Education shows the steepest expansion trajectory.
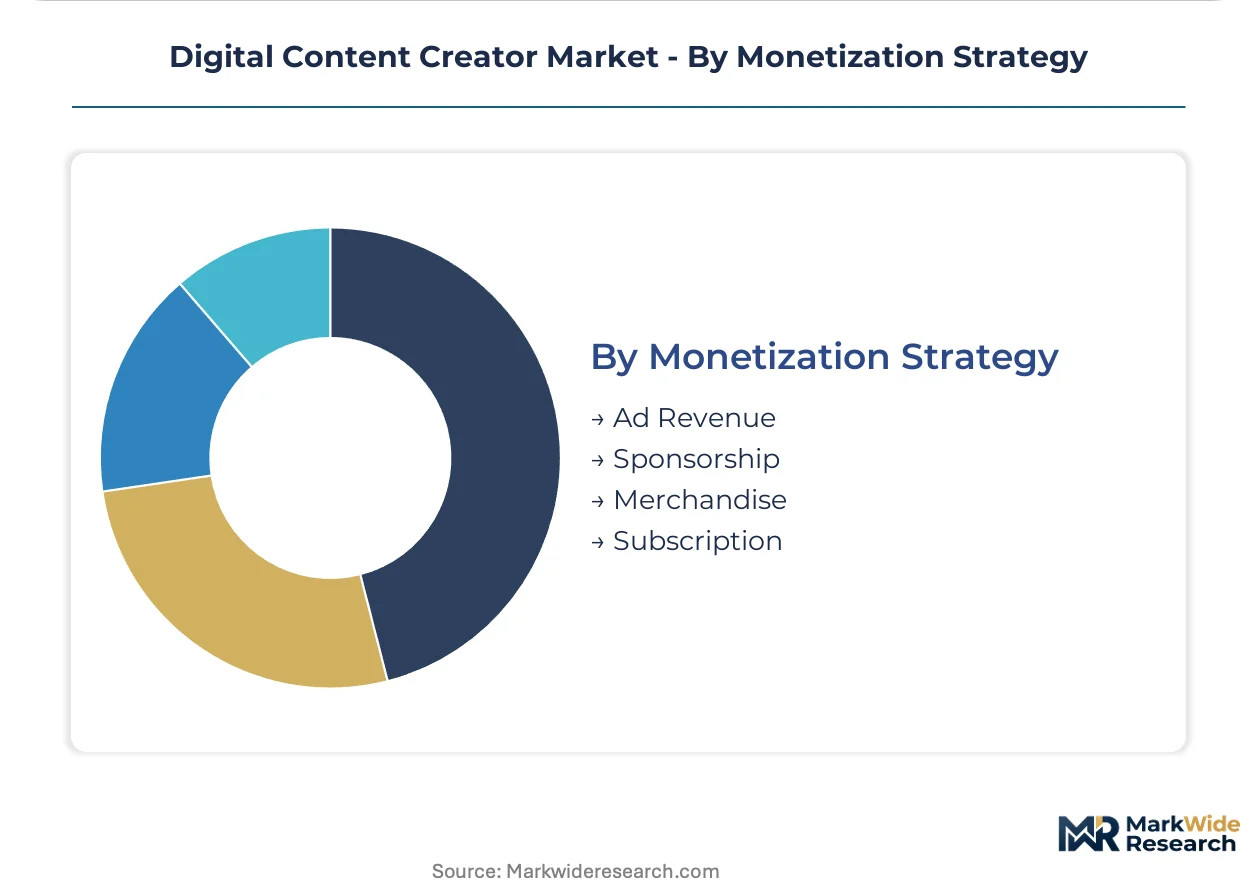
Monetization Strategy:
Margin structure and revenue predictability differentiate creator business model sustainability.
- Subscription:Recurring revenue through platform memberships or direct patronage services. Reduces dependence on algorithmic distribution volatility and seasonal advertising cycles. Subscription fatigue thresholds limit audience willingness to maintain multiple memberships.
- Sponsorship:Direct brand partnership contracts with flat-fee or performance-guaranteed structures. Enterprise marketing departments increasingly emphasize defined engagement or conversion metrics.
- Ad Revenue:Platform-shared advertising income tied to viewership metrics. YouTube Partner Program and TikTok Creator Fund represent primary vehicles.
- Merchandise:Direct product sales through integrated e-commerce tools. Live commerce integration opens transactional revenue streams beyond advertising.
Ad revenue commands the established base. Subscription climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Creator monetization rates in India undercut equivalent inventory costs in the United States by a factor of three to five, concentrating brand procurement attention on South Asian supply pools while North American creators defend premium positioning through compliance infrastructure and attribution technology.
United States
Enterprise marketing departments in technology and SaaS verticals drive concentrated demand for performance-guaranteed creator contracts. FTC endorsement disclosure enforcement shapes how sponsored content structures legal exposure for brands. Los Angeles and New York anchor production infrastructure where agencies bundle talent representation with brand safety technology.
India
Domestic short-form video platforms achieve massive user scale that attracts global brand investment into localized supply chains. Information Technology Rules mandate traceability and grievance mechanisms affecting platform-creator contractual relationships. Mumbai and Bangalore concentrate creator ecosystems where live commerce integration opens transactional revenue streams beyond advertising.
Germany
B2B SaaS verticals procure creator-produced educational content with rigorous outcome measurement infrastructure. GDPR compliance requirements impose content moderation and data handling standards increasing operational complexity for cross-border creators. Berlin hosts agency operations specializing in EU Digital Services Act compliance tools as subscription services.
United Kingdom
Podcast and audio-native formats retain value in financial services and professional education verticals with intimate audience relationship dynamics. Ofcom regulations alongside GDPR create layered compliance frameworks for creators distributing across European markets. London concentrates premium talent representation firms serving multinational brand procurement.
Brazil
Lifestyle and entertainment verticals concentrate creator activity on visual-first platforms with integrated shopping infrastructure. ANVISA oversight affects health and wellness content categories where supplement and fitness brand partnerships concentrate. São Paulo anchors production infrastructure serving Portuguese-language demand across Latin American markets.
Digital Content Creator Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying discrete services. The vendor base fragments across full-service agencies, talent representation firms, and performance-focused boutiques. Three archetypes dominate: end-to-end campaign managers, talent-centric safety enablers, and vertical-specialized performance optimizers. Competitive moves concentrate on strategic partnerships bundling compliance technology with creative execution, plus geographic expansion capturing emerging platform ecosystems.
Within the full-service agency tier, WebFX anchors enterprise client relationships through integrated campaign management. Viral Nation occupies a position in high-stakes sponsorship markets through talent representation combined with brand safety infrastructure. Single Grain exemplifies vertical specialization, concentrating performance-driven strategies for technology and SaaS procurement departments. These three represent distinct strategic postures rather than overlapping service configurations.
| Leading Market Players |
|---|
| WebFX |
| Animalz |
| SeriesX Marketing |
| Viral Nation |
| Column Five |
| Single Grain |
| Siege Media |
| Wooshii |
| Brafton |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Indian short-form video production compresses creator rates while elevating platform-side margin capture, forcing suppliers toward algorithmic diversification and buyers toward performance-guaranteed contracting structures. This utilization imbalance propagates through enterprise procurement decisions in the United States and compliance-heavy European markets.
Pricing Analysis
The customization-premium spread between configured-to-order creator campaigns and standard sponsorship packages widens as enterprise buyers demand attribution-integrated deliverables. Pricing stratifies across premium, standard, and economy tiers defined by production value, compliance infrastructure, and measurement sophistication. Cost compression in the Indian supply pool intensifies because algorithmic distribution volatility forces redundant content pipeline investments. SaaS vertical procurement departments exhibit lowest price sensitivity due to rigorous outcome measurement requirements, while lifestyle brand marketers face highest sensitivity amid subscription fatigue thresholds.
Supply Chain Analysis
Extended payment terms from enterprise marketing departments strain creator cash flows, accelerating adoption of supply-chain finance facilities and platform-native revenue-sharing advances. Production capacity concentrates in India, the United States, and Germany, with Mumbai, Los Angeles, and Berlin anchoring regional infrastructure. The supply chain draws from cloud encoding services, talent representation networks, and brand safety technology vendors. Single-platform dependency creates catastrophic income disruption risk from account enforcement actions. Distribution runs through platform-native algorithms, agency-mediated enterprise contracts, and direct-to-brand talent marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative artificial intelligence tools threaten to commoditize mid-tier production quality, forcing incumbents to defend substitutability through compliance infrastructure and attribution technology differentiation.
For Market Incumbents: Pre-empt AI-driven quality compression by embedding FTC disclosure automation and EU Digital Services Act compliance tools into campaign management workflows. Consolidate talent representation relationships in India to secure rate advantages before platform algorithm changes redistribute reach. Vertical integration into brand safety technology sustains pricing power against automated content alternatives. For New Entrants and Emerging Players: B2B SaaS verticals in Germany and the United Kingdom represent the most penetrable entry point given underpenetrated educational content procurement and rigorous outcome measurement infrastructure. Technology sector procurement departments bypass traditional media intermediaries, creating direct contracting opportunities. A performance-guaranteed go-to-market angle with defined engagement metrics differentiates against flat-fee legacy arrangements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-augmented production workflows, compressing barriers for independent creators while elevating agency-scale compliance technology investments. Acquisition targets should demonstrate cross-functional talent management capabilities spanning video production, data analytics, and regulatory navigation. Monitor EU Digital Services Act enforcement patterns as signal for compliance-tool monetization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Technology Integration | EU Digital Services Act mandates create subscription revenue streams for automated moderation tools. |
| Live Commerce Infrastructure | Real-time streaming checkout convergence opens transactional revenue beyond advertising in Indian markets. |
| Performance-Guaranteed Contracting | Attribution-integrated deliverables defend pricing power against AI-commoditized mid-tier production. |
| Cross-Border Talent Representation | Multi-jurisdiction compliance capabilities capture enterprise procurement shifting from informal influencer arrangements. |
| Vertical Specialization Expansion | Technology and SaaS sector penetration remains underdeveloped relative to consumer-facing verticals. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of platform disclosure filings, regulatory enforcement databases, and talent marketplace transaction records. Primary interviews engaged creator economy platform executives, enterprise marketing procurement leads, talent representation agency principals, and compliance technology vendors. Secondary sources encompassed FTC enforcement actions, EU Digital Services Act implementation guidance, India's Information Technology Rules documentation, and platform Partner Program policy disclosures. Bottom-up creator income modeling and top-down enterprise spend allocation triangulated market sizing.
Forecast inputs incorporate platform user growth trajectories, algorithmic distribution parameter changes, and monetization tool rollout schedules across the analysis window. Segmentation dimensions modeled include platform type, content format, subject vertical, and monetization strategy alongside regional regulatory cluster differentiation. CAGRs derive from cohort-based creator income progression curves and enterprise marketing budget reallocation elasticity estimates. AI adoption velocity and live commerce infrastructure deployment pace inform scenario-weighted projections.
Practitioners should monitor regulatory enforcement intensity, platform algorithm transparency mandates, and generative AI quality thresholds for early signals requiring forecast reassessment. Macroeconomic pressure on discretionary subscription spending, cross-border compliance fragmentation escalation, or breakthrough AI production capabilities would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Art App Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Photographic Services Market
Digital Media
Global Streaming Media Device Market
Digital Media
Digital Media Switchers Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market
Digital Media
Cognitive Media Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
US Animation, Vfx and Post Production Market
Digital Media
Video Production Market
Digital Media
Europe Anime Merchandising Market
Digital Media
Mobile Entertainment Market
Digital Media
Online Gambling Market
Digital Media
Anime Market
Digital Media
Global Virtual Goods Market
Digital Media
VFX Market