
 Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market | 2026-2036
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market Outlook
Transit authorities and municipal governments is unwinding legacy static contracts in favor of programmatic DOOH networks. JCDecaux leverages its airport and street furniture concessions across Frankfurt and Paris to sustain premium inventory control. Ströer SE & Co. KGaA anchors Germany's roadside digital billboard expansion through exclusive Autobahn-adjacent leases. Focus Media dominates elevator and in-building screen networks in Shanghai and Shenzhen, occupying high-frequency residential and commercial touchpoints.
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising encompasses networked digital display systems deployed in public and semi-public environments, typically operating at 500–3,000 nits brightness with IP65-rated enclosures for outdoor durability, designed to deliver targeted commercial messaging to audiences in transit, retail, or communal spaces. LED technology leads outdoor installations due to superior luminance and energy efficiency versus LCD alternatives, while projection systems remain niche for temporary event activations. The application segment shows fastest structural growth in transportation hubs where dwell-time analytics enable real-time audience measurement, and retail environments where proximity-triggered content drives measurable footfall conversion.
Germany's Federal Cartel Office and Germany's state media authorities enforce advertising content standards that restrict certain product categories from DOOH placement, while China's SAMR oversees data privacy in programmatic ad platforms serving mainland screens. The EU AI Act, applicable to Germany, will classify automated content personalization systems used in DOOH networks, imposing transparency obligations on algorithmic decision-making. Stakeholders must monitor evolving cross-border data governance as programmatic platforms aggregate audience metrics across Singapore, Japan, and German inventories.
Market Dynamics
Programmatic buying platforms are consolidating inventory access across Asia-Pacific and Germany, compressing the traditional direct-sales model that static outdoor advertising relied upon for decades. This shift forces operators to restructure yield management around real-time bidding algorithms rather than fixed-rate contracts.
Growth Catalysts
- EU Digital Services Act implementation:Germany's alignment with Brussels-mandated transparency rules is accelerating audit-ready programmatic infrastructure investment across DOOH networks.
- Transportation hub dwell-time analytics:Seoul's subway authority and Sydney's transit operators are deploying sensor-integrated screens that measure audience attention spans, enabling dynamic pricing models.
- LED luminance efficiency gains:Outdoor installations now achieve 3,000 nits at 40% lower energy draw than 2019 baselines, reducing operational cost barriers for 24/7 roadside deployments.
Market Restraints
- Autobahn-adjacent lease concentration:Ströer SE & Co. KGaA's exclusive roadside concessions in Germany limit competitive entry for premium highway inventory.
- Copper and rare-earth input volatility:LED driver components and power supply units face price instability tied to Chinese processing capacity constraints.
- GB standards compliance for mainland China:MIIT-mandated electromagnetic interference testing adds 8-12 week certification delays for imported display hardware.
Strategic Opportunities
- Tier-two Chinese corridor expansion:Chengdu, Hangzhou, and Wuhan municipal governments are issuing smart city tenders with embedded DOOH requirements for urban renewal districts.
- EU AI Act transparency obligations:Algorithmic content personalization systems in German networks will require disclosure protocols, creating first-mover advantage for compliant platform vendors.
- Elevator screen network saturation gaps:Residential high-rise penetration in Shenzhen and Guangzhou remains below 60%, offering expansion runway for in-building operators.
Industry Challenges
- Programmatic talent scarcity:DOOH operators lack sufficient data science capacity to manage real-time bidding algorithms alongside legacy sales teams.
- IP65 enclosure refurbishment cycles:Outdoor display housings require 5-7 year replacement intervals, straining capital allocation for network maintenance.
- Cross-border data governance fragmentation:SAMR, Japan's Personal Information Protection Commission, and Germany's state media authorities impose conflicting audience metric retention rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market |
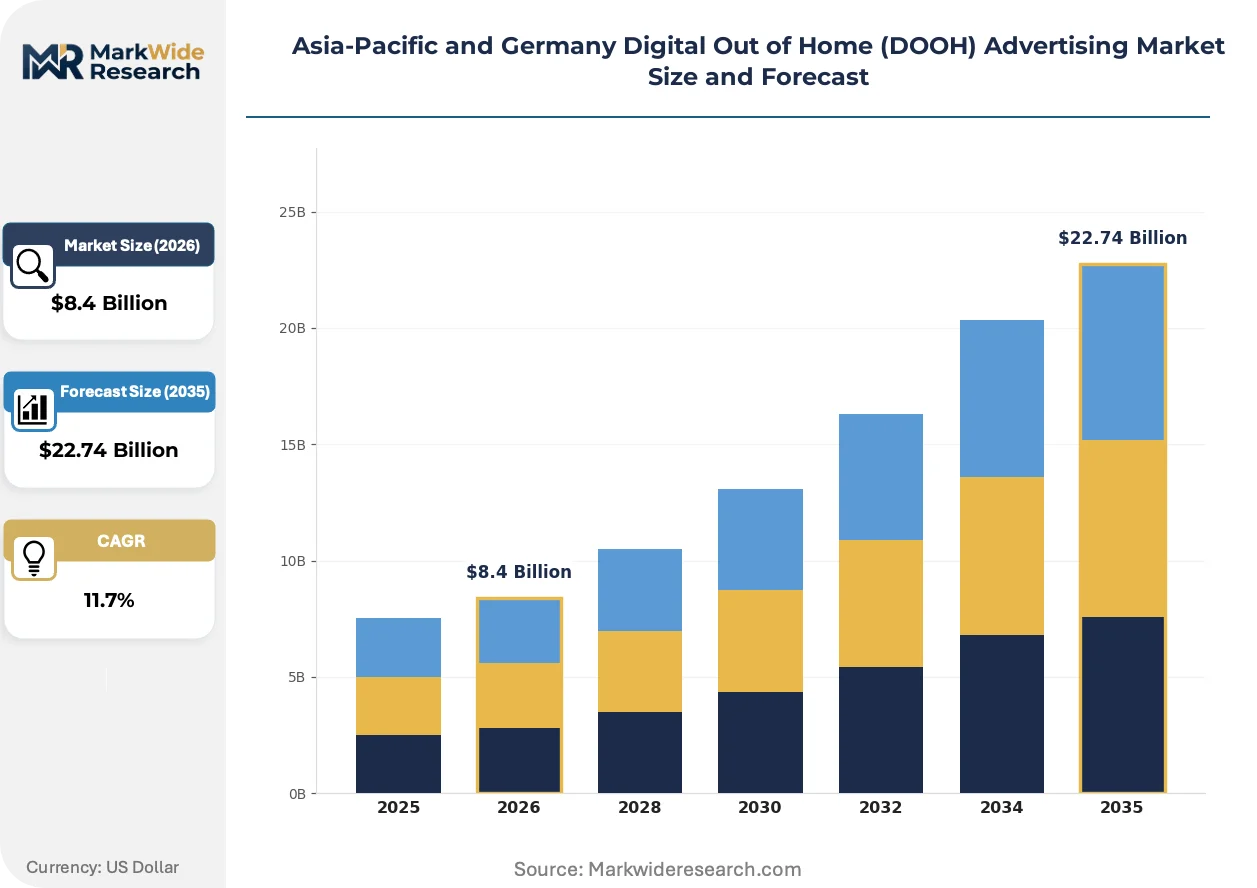
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Billboards, Screens, Kiosks, Transit Displays Technology: LED, LCD, Projection, 3D Displays Application: Retail, Transportation, Public Spaces, Events Customer Type: Advertisers, Agencies, Brands, Startups |
| Companies Covered | Outfront Media Inc., Lamar Advertising Company, JCDecaux, Broadsign International LLC., Focus Media, Stroer SE & Co. KGaA, oOh!media Limited, Daktronics Inc., Clear Channel Outdoor Holdings, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market Strategic Shifts
Measurement infrastructure is overtaking hardware deployment as the primary investment priority across Asia-Pacific and Germany DOOH networks. Operators now compete on audience verification capabilities rather than screen count alone.
Computer vision-based attention measurement is supplanting traditional traffic-count metrics as the currency for inventory valuation. JCDecaux and municipal transit authorities in Frankfurt and Paris are piloting gaze-tracking sensors that feed directly into programmatic exchanges. This technology compresses the gap between impression delivery and verified engagement, enabling outcome-based pricing models that static billboards cannot replicate.
Germany's Federal Cartel Office is enforcing stricter scrutiny of exclusive concession agreements for street furniture and airport terminals, following 2023 precedent cases in Berlin and Hamburg. This regulatory pressure is fragmenting previously consolidated inventory pools and forcing incumbents to defend market position through service differentiation rather than contractual lock-in. Smaller programmatic platforms are gaining footholds in secondary German cities where concession renewal cycles create entry windows.
Agency buying desks are consolidating DOOH spend through centralized trading desks, displacing the legacy model of local market direct relationships. This concentration shift is most visible in China's tier-one cities where multinational brands now execute Shanghai and Shenzhen campaigns through Singapore-based regional hubs. The compression of local operator influence is reshaping commission structures and creative adaptation workflows across the Asia-Pacific corridor.
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market Segmentation
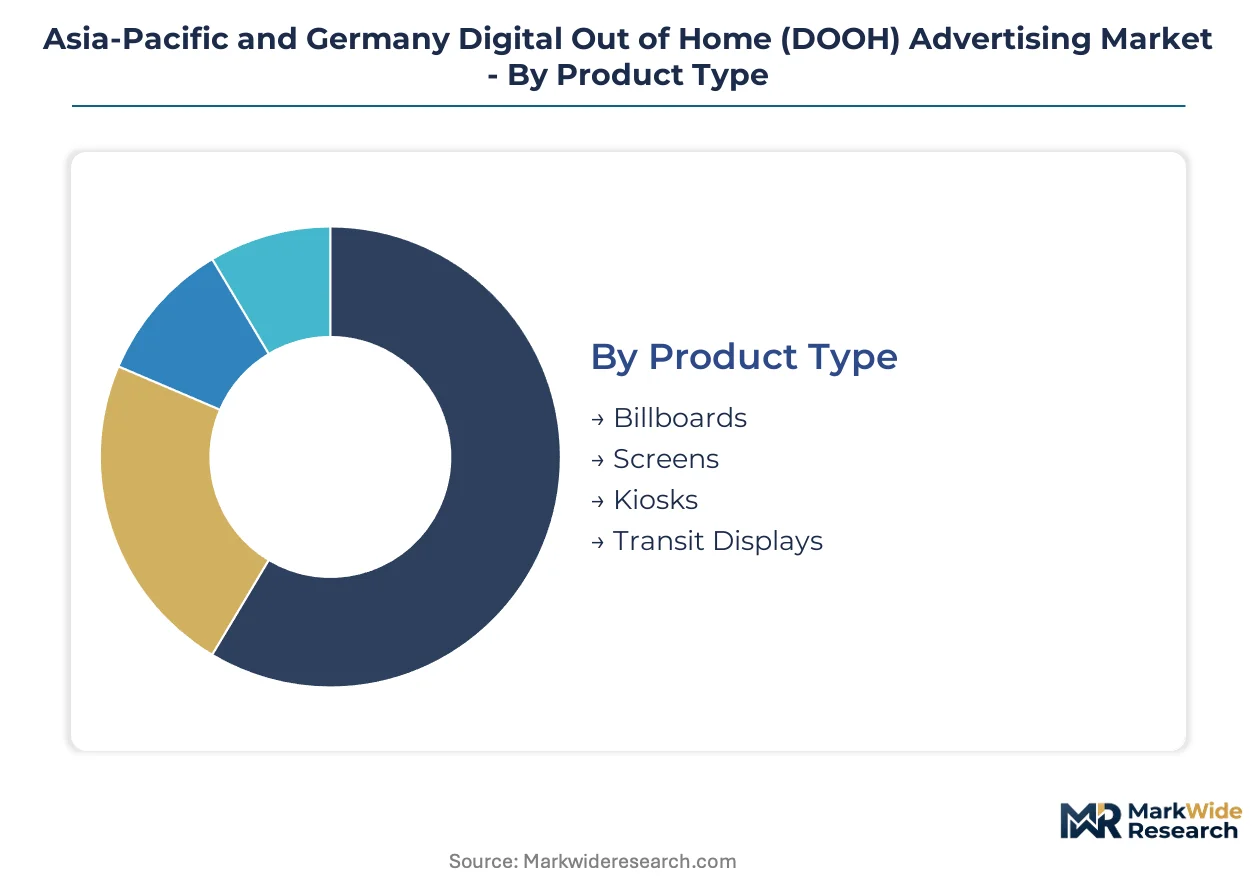
DOOH procurement flows through distinct channel architectures where hardware specifications, programmatic capabilities, and regulatory compliance intersect. Segmentation reveals how inventory monetization differs across display formats and buyer profiles.
Product Type:
Channel economics vary sharply by physical format, with roadside inventory commanding premium rates against in-venue alternatives.
- Billboards:Large-format LED installations mounted along highways and arterial roads, typically 14x48 feet or larger. Ströer SE & Co. KGaA's Autobahn-adjacent network in Germany and JCDecaux's airport concessions anchor premium pricing here. Energy efficiency gains in 3,000-nit LED modules have compressed operating costs for 24/7 roadside deployments.
- Screens:Medium-format displays deployed in retail environments, transit corridors, and commercial buildings. Focus Media's elevator and lobby networks in Shanghai and Shenzhen concentrate demand, where dwell-time analytics enable dynamic content rotation based on audience density.
- Kiosks:Interactive touchscreen units with wayfinding and transactional capabilities. Municipal smart city tenders in Sydney and Seoul embed these into street furniture procurement, though hardware maintenance cycles strain operator capital.
- Transit Displays:Platform-mounted and vehicle-integrated screens serving subway, bus, and rail passengers. Seoul's subway authority and Sydney's transit operators are expanding sensor-integrated deployments that feed attention metrics into programmatic exchanges.
Billboards dominate installed base. Screens are where expansion concentrates.
Technology:
Hardware selection tracks luminance requirements and procurement budgets across outdoor versus indoor deployment contexts.
- LED:Dominates outdoor installations through superior brightness (500–3,000 nits) and energy efficiency versus alternatives. China's MIIT-mandated electromagnetic interference testing adds certification delays for imported driver components.
- LCD:Prevails in indoor retail and transit environments where ambient light is controlled. Panel supply concentration among Korean and Taiwanese manufacturers creates procurement vulnerability during component shortages.
- Projection:Niche temporary activations for events and pop-up retail. Limited by ambient light interference and shorter equipment lifespan.
- 3D Displays:Lenticular and glasses-free systems piloting in premium transit corridors and flagship retail. Hardware cost and content production complexity constrain scale.
LED commands outdoor volume. 3D Displays are climbing the fastest.
Application:
End-use context determines measurement infrastructure investment and pricing model sophistication.
- Retail:In-store, mall, and proximity-triggered displays driving footfall conversion. China's tier-one metropolitan corridors concentrate programmatic buying platform investment here.
- Transportation:Airport, subway, and roadside inventory where dwell-time analytics enable real-time audience verification. Germany's Federal Cartel Office scrutiny of exclusive concessions is fragmenting previously consolidated inventory pools.
- Public Spaces:Street furniture and municipal deployments integrating smart city infrastructure. Berlin and Hamburg precedent cases are reshaping concession renewal terms.
- Events:Temporary installations for sports, concerts, and trade shows. Projection systems find viable deployment here despite limited permanence.
Transportation dominates yield per impression. Retail is gaining share fastest.
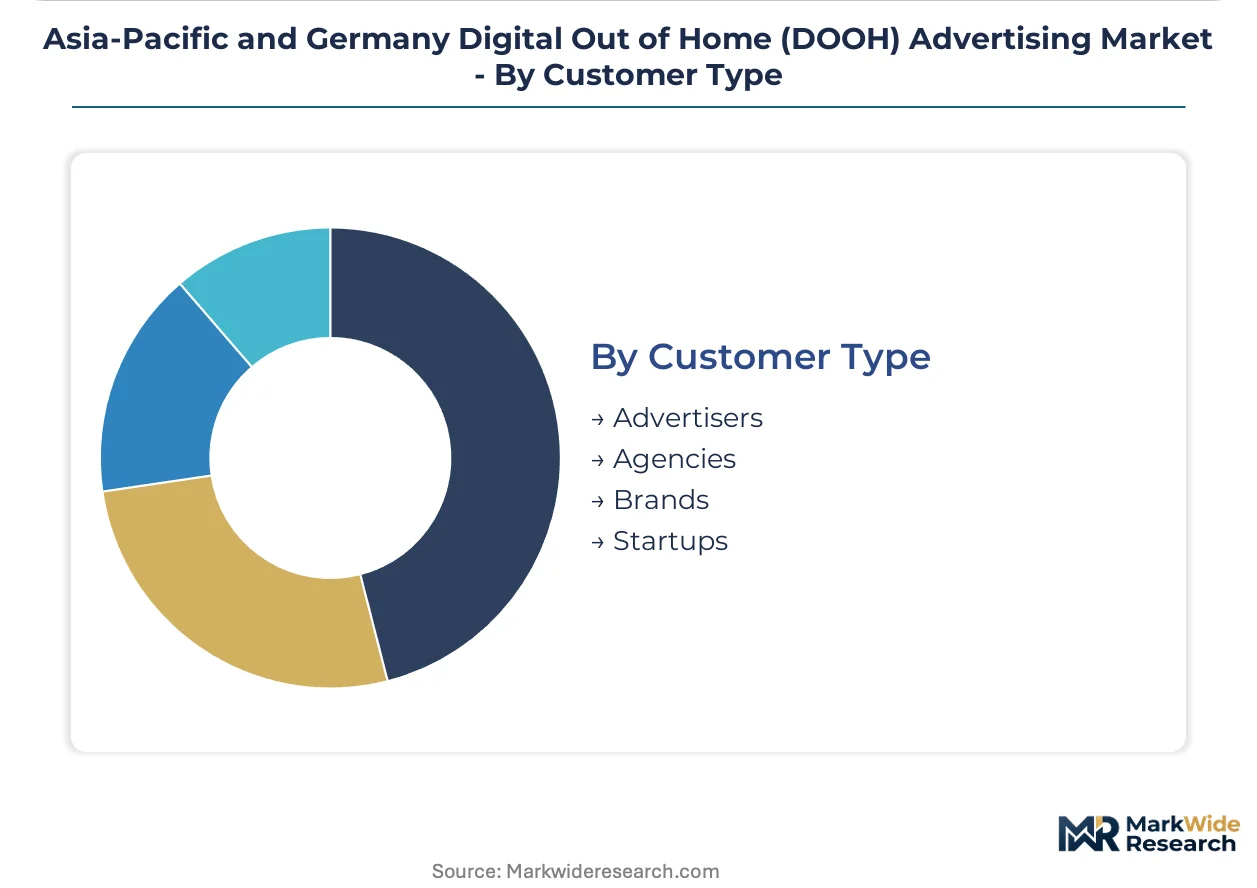
Customer Type:
Buyer sophistication determines contract structure, with centralized trading desks displacing local direct relationships.
- Advertisers:Direct brand procurement of premium inventory, particularly in airport and flagship retail contexts. Multinational brands now execute regional campaigns through Singapore-based hubs.
- Agencies:Consolidated buying desks managing DOOH spend across Asia-Pacific and German markets. This concentration compresses local operator influence and reshapes commission structures.
- Brands:Consumer goods and automotive companies prioritizing outcome-based metrics over impression volume. Computer vision-based attention measurement is supplanting traffic-count currency.
- Startups:Emerging programmatic platforms gaining footholds in secondary German cities and China's tier-two corridors. Talent scarcity in data science capacity constrains competitive positioning.
Agencies dominate transaction volume. Startups are where competitive entry concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agency buying desks concentrate procurement through Singapore-based regional hubs, displacing legacy local-operator relationships across the Asia-Pacific corridor while German municipal authorities fragment previously consolidated concession pools.
China
Tier-one metropolitan corridors in Shanghai and Shenzhen drive programmatic platform investment, with elevator screen networks penetrating high-frequency residential touchpoints. SAMR oversees data privacy compliance for mainland programmatic ad platforms serving urban displays. Chengdu and Hangzhou municipal governments issue smart city tenders embedding DOOH requirements into urban renewal districts.
Germany
Autobahn-adjacent roadside inventory commands premium rates through exclusive lease structures, while airport and street furniture concessions face Federal Cartel Office scrutiny. The EU AI Act imposes transparency obligations on algorithmic content personalization systems deployed in DOOH networks. Berlin and Hamburg precedent cases reshape concession renewal terms, creating entry windows for smaller programmatic platforms.
Australia
Sydney transit operators expand sensor-integrated screen deployments measuring audience attention spans for dynamic pricing models. The country's state media authorities enforce advertising content standards restricting certain product categories from DOOH placement. Melbourne and Brisbane follow Sydney's procurement template for smart city infrastructure integration.
South Korea
Seoul's subway authority pioneers dwell-time analytics infrastructure feeding attention metrics directly into programmatic exchanges. The country's Personal Information Protection Commission governs audience metric retention rules for cross-border data aggregation. Busan and Incheon transit authorities replicate Seoul's sensor-integrated deployment model.
Japan
Tokyo and Osaka concentrate demand for computer vision-based attention measurement systems supplanting traditional traffic-count metrics. METI oversees industrial standards for display hardware deployed in public environments. Nagoya and Fukuoka municipal governments evaluate smart city tenders incorporating DOOH into transit infrastructure renewal.
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market Competitive Environment
Player mix skews toward diversified outdoor media conglomerates with legacy concession portfolios, interspersed with specialized programmatic technology vendors and regional in-building network operators. Market structure reflects tiered consolidation where premium inventory control rests with established concession holders while software layers fragment across competing buying platforms. Three archetypes dominate: infrastructure-heavy concession operators, pure-play programmatic enablers, and vertically integrated in-building specialists. Competitive dynamics center on concession renewal timing and yield management algorithm deployment.
Among diversified media conglomerates, JCDecaux and Ströer SE & Co. KGaA exemplify the concession-anchored archetype, leveraging exclusive lease structures to maintain premium inventory access. Focus Media occupies a distinct position within the in-building specialist tier, concentrating elevator and lobby screen networks across Chinese metropolitan corridors. These three entities represent divergent strategic paths through the market: international concession portability, domestic roadside dominance, and high-frequency residential penetration.
| Leading Market Players |
|---|
| Outfront Media Inc. |
| Lamar Advertising Company |
| JCDecaux |
| Broadsign International LLC. |
| Focus Media |
| Stroer SE & Co. KGaA |
| oOh!media Limited |
| Daktronics Inc. |
| Clear Channel Outdoor Holdings, Inc. |
| Others |
Value Chain & Pricing Dynamics
LED module manufacturing scale in Shenzhen and Seoul anchors price floors across Asia-Pacific and German DOOH networks, with 3,000-nit outdoor displays commanding premium positioning against indoor LCD alternatives while copper and rare-earth processing capacity constraints compress margins on driver components.
Pricing Analysis
Cost-plus contracts with copper and rare-earth indexation dominate procurement agreements for LED driver assemblies, with three-tier pricing structure across premium, standard, and economy levels separating airport concession inventory from roadside billboards and in-building screens. Certification under China's GB standards and Germany's CE marking requirements adds compliance premiums to imported hardware. Pricing pressure stems from programmatic platform consolidation compressing operator yield management. Agency buying desks show lowest price sensitivity for verified attention metrics, while municipal tender participants face acute budget constraints.
Supply Chain Analysis
Inventory cycles for IP65-rated enclosures stretch 8-12 weeks due to MIIT-mandated electromagnetic interference testing, with supply concentrating in China, South Korea, and Taiwan for LED modules, LCD panels, and driver electronics respectively. Copper windings, rare-earth phosphors, and aluminum heat sinks constitute critical input dependencies. Single-source vulnerability runs through Chinese rare-earth processing capacity. Distribution runs through concession operators holding exclusive municipal leases and programmatic platforms aggregating fragmented inventory pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
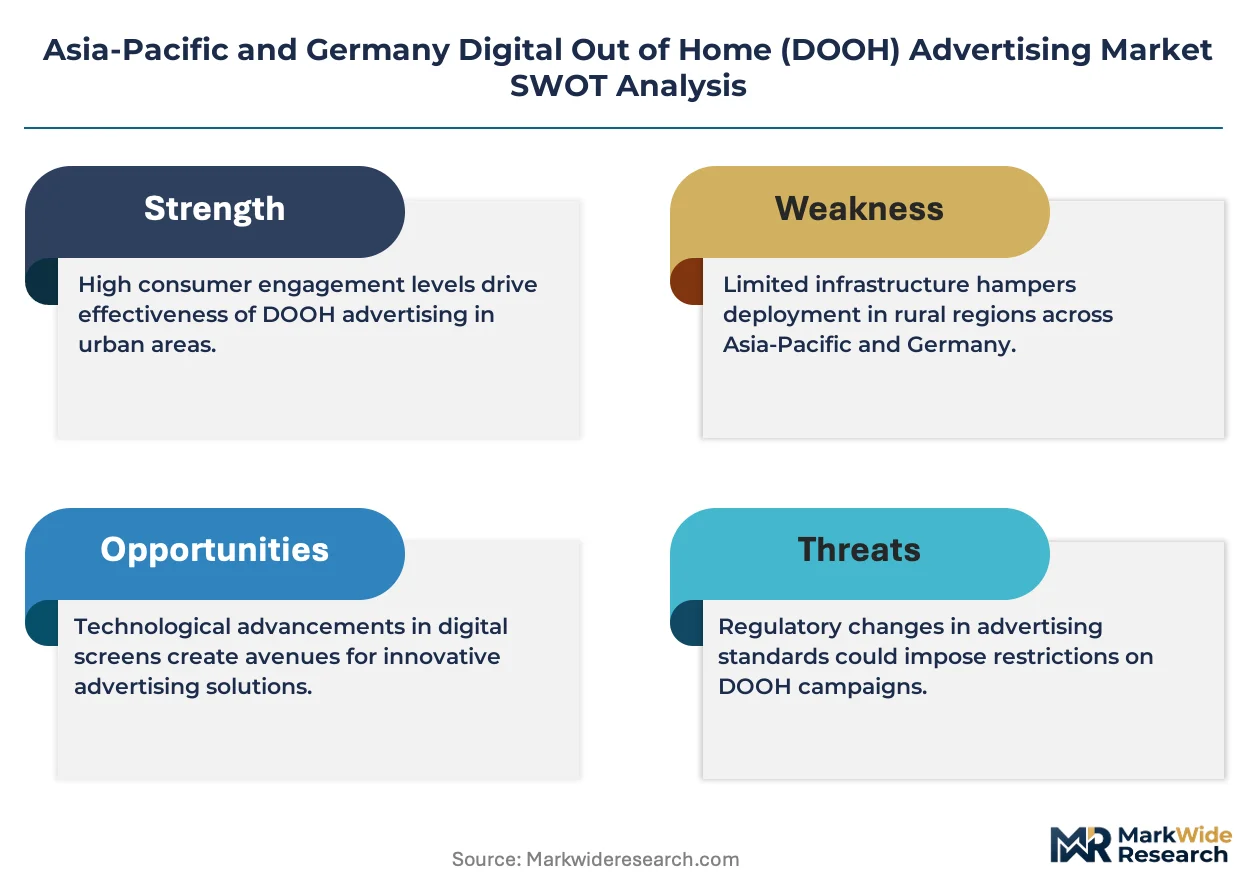
Asia-Pacific and German DOOH markets sit in early-cycle expansion as programmatic infrastructure penetrates legacy static contracts, with tier-two Chinese corridor tenders and EU AI Act compliance requirements accelerating platform investment timelines.
For Market Incumbents: Secure exclusive concession renewals in German secondary cities before Federal Cartel Office scrutiny fragments inventory pools, and deepen backward integration into LED module assembly to offset rare-earth price volatility. Threats concentrate in sensor-integrated attention measurement systems that commoditize premium inventory differentiation. For New Entrants and Emerging Players: Differentiate on algorithmic transparency tools addressing EU AI Act disclosure obligations for German network operators, targeting tier-two Chinese municipal tenders in Chengdu and Wuhan where incumbent penetration remains below tier-one saturation. Go-to-market leverage rests with compliant platform-as-a-service offerings. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among elevator screen network operators with captive building access and programmatic yield management capabilities. Five-to-ten year viability favors vertical integration into sensor hardware alongside software layers. Watch concession renewal timing in Berlin and Hamburg as inflection signals for German market entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Programmatic Platform Integration | Enables real-time bidding across JCDecaux and Ströer inventory pools in Frankfurt and Berlin. |
| Sensor Hardware Backward Integration | Captures dwell-time analytics revenue streams currently outsourced to third-party measurement vendors. |
| EU AI Act Compliance Certification | Creates first-mover positioning for algorithmic transparency tools in German DOOH networks. |
| Tier-Two Chinese Corridor Expansion | Locks in municipal smart city tenders ahead of Focus Media saturation in Chengdu and Wuhan. |
| Concession Renewal Pre-emption | Secures exclusive Autobahn-adjacent and airport terminal inventory before regulatory fragmentation accelerates. |
Study Parameters
A standing panel of programmatic platform engineers, municipal procurement officers, transit authority technology directors, and outdoor media sales executives provided ongoing calibration across primary interview cycles, with secondary validation drawing from MIIT certification databases, EU Digital Services Act implementation trackers, municipal tender documentation, and SEC filings of listed outdoor media conglomerates. Bottom-up screen deployment counts triangulated against top-down advertising spend estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning display format, technology type, application context, and customer archetype. CAGRs derived from installed base expansion rates and yield-per-improvement trajectories. Forecast inputs incorporated LED energy efficiency curves, programmatic adoption S-curves, and concession renewal cycle timing.
Decision-makers should treat outputs as directional under assumptions of sustained municipal smart city investment and stable rare-earth supply channels; material deviation in Chinese processing capacity or EU regulatory enforcement stringency would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Professional Dubbing Services Market
Digital Media
Secondary Ticket Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
APAC DOOH Market
Digital Media
VFX Market
Digital Media
India Webtoons Market
Digital Media
Middle East and Africa Animation Market
Digital Media
ACGN Subculture Market
Digital Media
Global Playout Automation and Channel in a Box Market
Digital Media
Global Digital Painting Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Global Location-Based Entertainment Market
Digital Media
Stock Music Software Market
Digital Media
Photographic Services Market
Digital Media
Art App Market