
 Video Production Market | 2026-2036
Video Production Market Size, Share, and Industry Trends Forecast 2026-2036
Video Production Market Analytics
Subscription-based post-production workflows are recalibrating how studios monetize creative output. Crisp Video leverages cloud-rendered delivery models to serve mid-market corporate clients without on-premise infrastructure. Levitate Media anchors its position through specialized animation pipelines for healthcare and technology verticals. BLARE Media differentiates via broadcast-grade live production capabilities that command premium retainers from sports and entertainment networks.
Video production encompasses the end-to-end creation of moving image content, spanning conceptualization, principal photography, editorial finishing, color grading, and multi-platform mastering at resolutions up to 4K and beyond, serving commercial communication, entertainment distribution, and organizational training purposes. Pre-production services constitute the largest revenue pool as brands invest heavily in scripted concept development and storyboarding before committing to shoot days. Post-production is expanding fastest as AI-assisted editing, automated transcription, and real-time collaboration tools compress delivery timelines for social media content and commercial spots. Live streaming technology commands elevated margins due to specialized hardware requirements and technical director expertise for flawless event execution.
The Federal Communications Commission enforces closed captioning and accessibility standards that shape technical deliverables for broadcast-bound content, while the European Union's General Data Protection Regulation imposes consent frameworks on productions capturing identifiable individuals. The EU AI Act introduces disclosure mandates for synthetically generated or manipulated video, compelling producers to maintain provenance documentation. Stakeholders must monitor evolving platform-specific content moderation policies and synthetic media labeling requirements as regulatory fragmentation between jurisdictions intensifies compliance complexity.
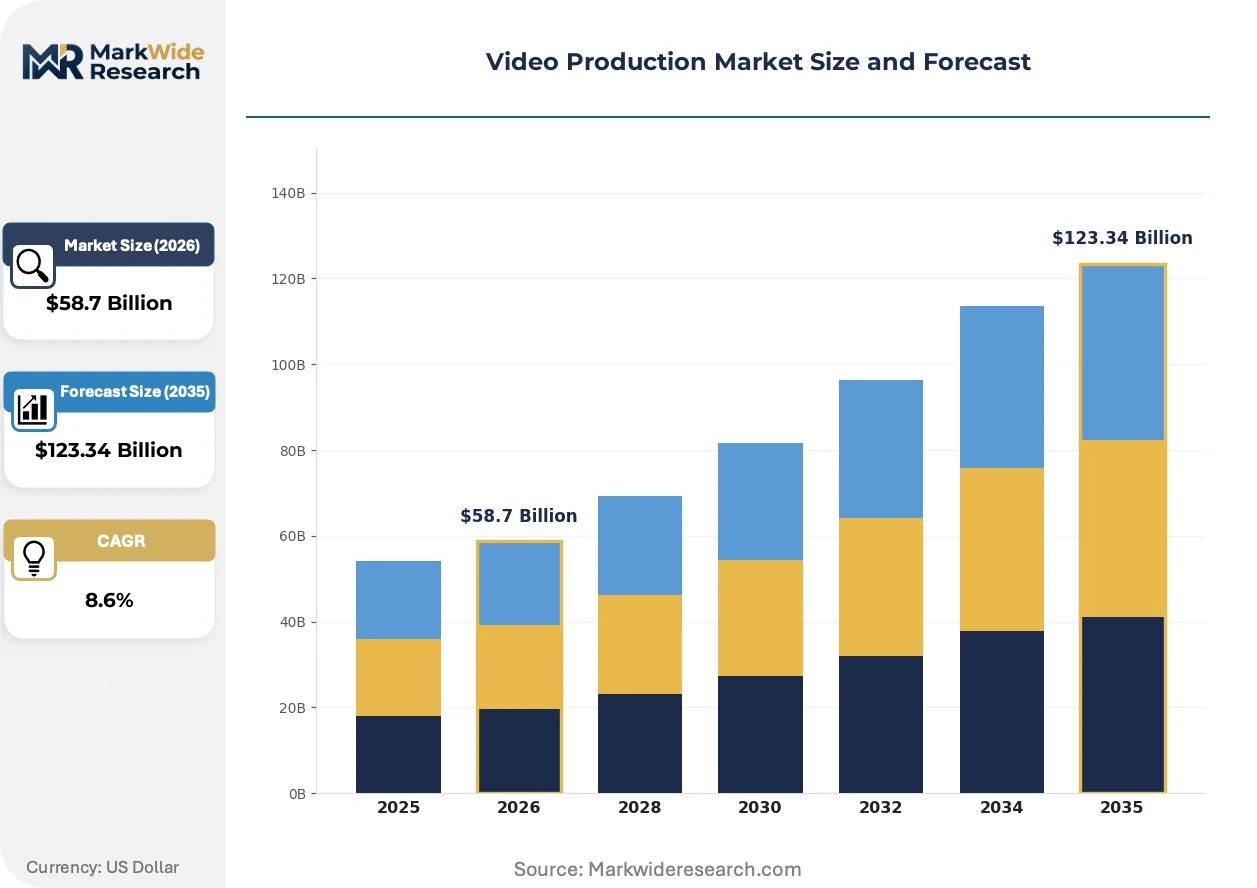
Market Dynamics
Cloud-rendered delivery models are compressing production timelines while synthetic media disclosure mandates under the EU AI Act and emerging US frameworks force studios to rebuild provenance documentation workflows from pre-production through distribution.
Growth Catalysts
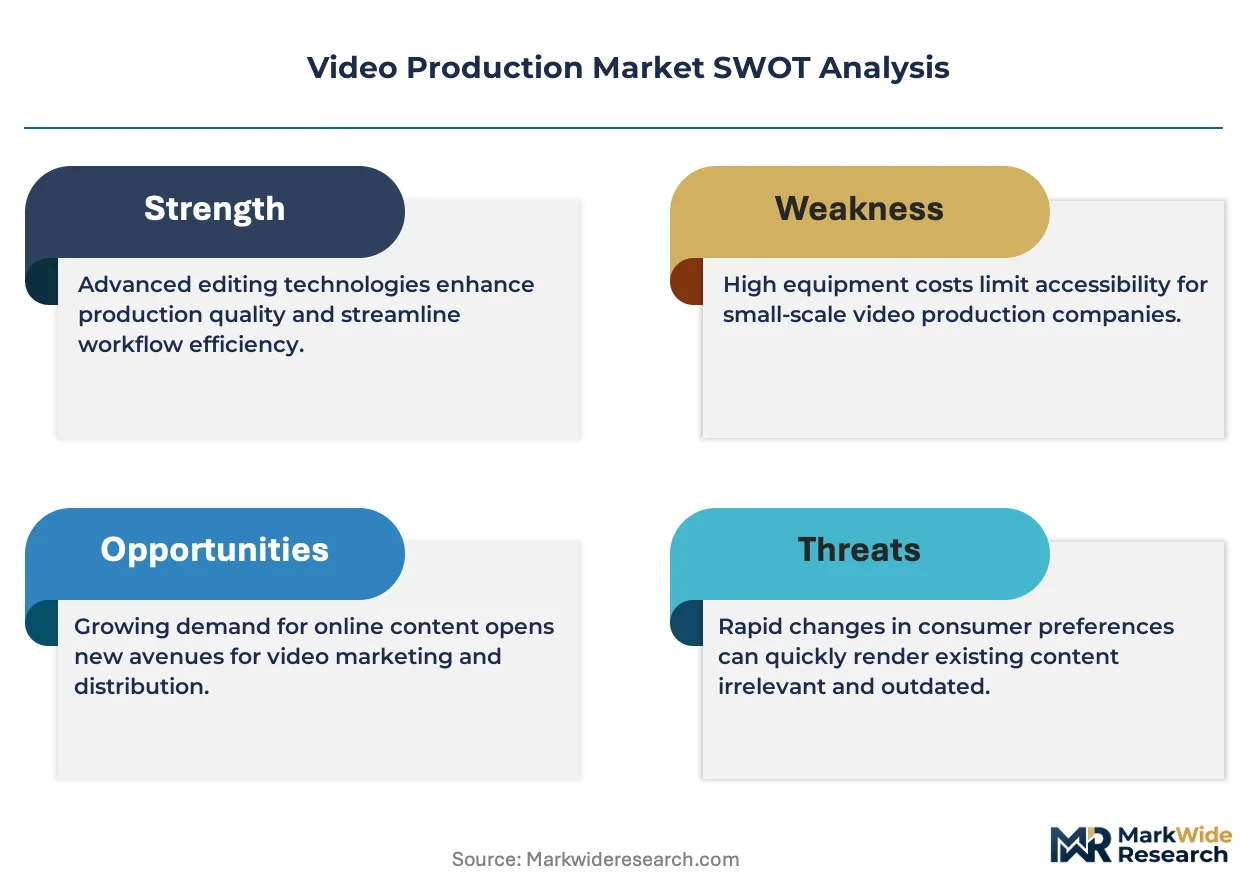
- Streaming platform commissioning:OTT services commission original content at unprecedented scale, creating sustained demand for end-to-end production services across entertainment and corporate verticals.
- AI-assisted post-production tools:Automated transcription, real-time collaboration platforms, and machine learning-driven editing compress delivery timelines for social media and commercial content.
- Regional language content surge:India's OTT market drives demand for localized production capabilities across Hindi, Tamil, Telugu, and Malayalam content categories.
Market Restraints
- Specialized hardware cost concentration:Live streaming infrastructure requires broadcast-grade cameras, switching hardware, and redundant connectivity that locks out smaller entrants.
- Regulatory fragmentation:Divergent synthetic media labeling requirements between the EU AI Act, FCC disclosure frameworks, and platform-specific policies multiply compliance overhead.
- Technical talent scarcity:Technical director expertise for flawless live event execution remains concentrated among experienced operators in major production hubs.
Strategic Opportunities
- Healthcare and technology vertical specialization:Animation pipelines tailored to medical device visualization and enterprise software demonstration command premium pricing and recurring engagements.
- Mid-market corporate subscription models:Cloud-rendered delivery without on-premise infrastructure opens addressable market among regional brands and mid-sized enterprises.
- Accessibility mandate expansion:FCC closed captioning enforcement and evolving ADA requirements create sustained demand for certified transcription and audio description services.
Industry Challenges
- Cross-functional talent integration:Studios struggle to align cinematographers, colorists, and AI tool operators within unified creative workflows.
- Provenance documentation systems:EU AI Act disclosure mandates require new metadata infrastructure from capture through distribution, forcing legacy asset management rebuilds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Production Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $123.34 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pre-production, Production, Post-production, Distribution Technology: 4K, VR, Animation, Live Streaming Client Type: Cinemas, Broadcasting Networks, Corporates, Independent Creators Content Type: Documentaries, Commercials, Training Videos, Social Media Content |
| Companies Covered | Crisp Video, Lemonlight, Thrive Internet Marketing Agency, Sandwich, Levitate Media, BLARE Media, Clay Media Group, Zero One Digital Media, New Evolution Video, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Production Market Evolving Landscape
Generative video tools are forcing studios to restructure creative workflows around synthetic media provenance, while regulatory disclosure mandates and shifting buyer procurement models reshape competitive positioning across production tiers.
Neural rendering engines are electrifying virtual production stages by replacing physical sets with real-time LED volume environments. Major entertainment networks and automotive advertisers deploy these systems for location-agnostic shooting. This technology is electrifying cost structures by eliminating travel logistics while enabling same-day iteration on backgrounds and lighting.
The EU AI Act introduces mandatory labeling for synthetically generated or manipulated video content, compelling producers to maintain chain-of-custody documentation from capture through distribution. Post-production houses must now embed provenance metadata at every processing stage. European broadcasters and streaming platforms are rebuilding asset management infrastructure to comply with disclosure audits.
Corporate buyers now unbundle production services rather than purchasing end-to-end packages, selecting specialized vendors for pre-production concept development, principal photography, and editorial finishing separately. This fragmentation favors boutiques with vertical expertise over full-service studios. The shift is most visible in North American technology and financial services verticals where procurement teams negotiate component-level contracts.
Video Production Market Segmentation
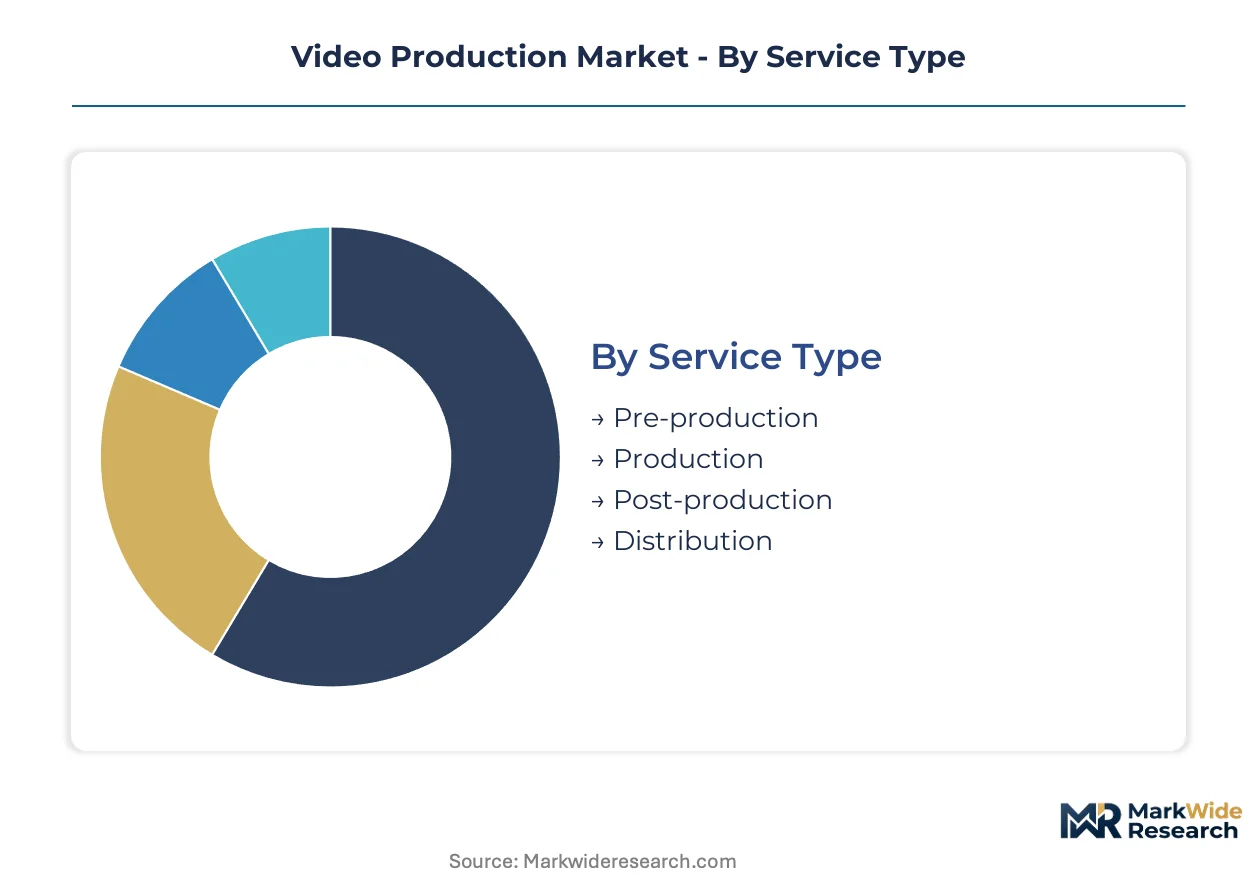
Video production segmentation reveals divergent margin profiles across the value chain, with service type determining infrastructure intensity and technology choice dictating talent specialization requirements. Client type and content format together shape pricing power and contract duration in distinct ways.
Service Type:
Pre-production commands premium pricing through creative IP ownership, while distribution scales through volume-based platform relationships.
- Pre-production:Script development, storyboarding, and location scouting establish creative direction before capital-intensive shoot days commence. Demand concentrates among streaming platforms commissioning original series in India, where regional language content requires culturally embedded concept development teams.
- Production:Principal photography, set construction, and on-set technical direction consume the largest share of physical infrastructure spend. Mature deployment sits with broadcast networks maintaining owned studio facilities. Newer deployment is concentrated in virtual production stages using LED volumes for location-agnostic shooting.
- Post-production:Editorial finishing, color grading, VFX integration, and multi-platform mastering compress delivery timelines through AI-assisted tools.
- Distribution:Multi-platform encoding, metadata embedding, and rights-managed delivery pipelines serve OTT services and broadcasters with divergent technical specifications.
Post-production houses are gaining share fastest as AI tools compress editorial timelines for social media content.
Technology:
Resolution specifications and immersive formats split the market between broadcast compliance requirements and experimental brand experiences.
- 4K:Ultra-high-definition acquisition and delivery at 3840×2160 resolution has become standard for streaming platform originals and commercial advertising. Demand concentrates in corporate training verticals where crisp detail supports technical product demonstration.
- VR:Stereoscopic 360-degree capture and real-time rendered environments enable immersive training simulations and experiential marketing activations. Healthcare providers in the United States deploy these systems for surgical training and patient education modules.
- Animation:2D and 3D motion graphics, character animation, and medical visualization pipelines require specialized software expertise and render farm infrastructure.
- Live Streaming:Real-time encoding, redundant connectivity, and technical director oversight for flawless event execution commands elevated margins due to non-repeatable performance risk.
Animation pipelines for healthcare and technology verticals show the steepest expansion trajectory as brands seek explainers for complex products.
Client Type:
Procurement sophistication varies sharply between institutional buyers with component-level vendor unbundling and creators seeking end-to-end convenience.
- Cinemas:Theatrical exhibition requires DCI-compliant mastering, immersive audio formats, and large-format projection specifications. Exhibition chains in India commission localized trailers and regional language dubbing for blockbuster releases.
- Broadcasting Networks:Linear television and cable operators demand closed captioning compliance under FCC mandates, specific aspect ratios, and interstitial packaging standards.
- Corporates:Enterprise communications, product marketing, and internal training departments increasingly subscribe to cloud-rendered delivery models without on-premise infrastructure investment.
- Independent Creators:Solo producers and small collectives leverage platform-native editing tools and royalty-free asset libraries for direct-to-audience distribution.
Corporate procurement teams unbundle services most aggressively, selecting separate vendors for concept development, production, and finishing.
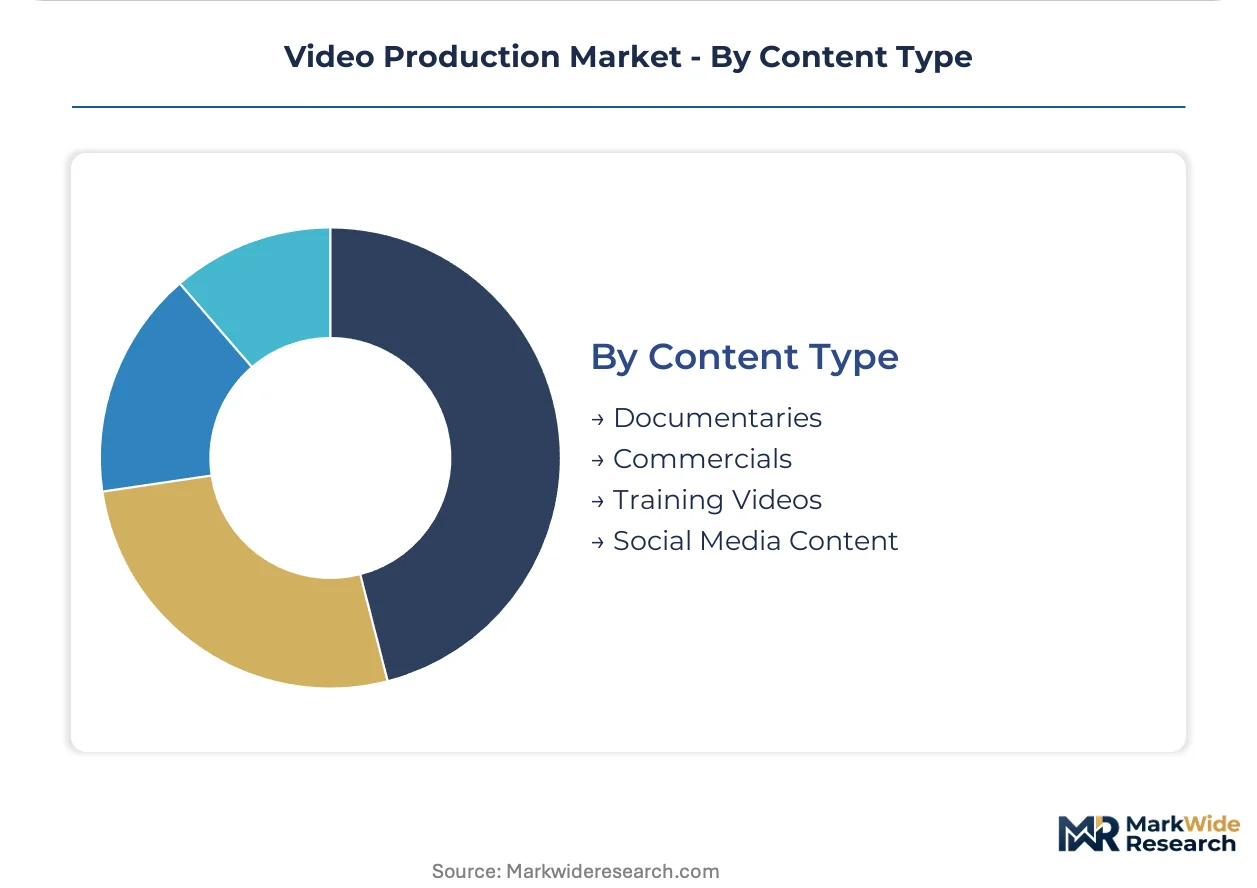
Content Type:
Format selection determines crew size, shoot duration, and post-production complexity in predictable patterns.
- Documentaries:Non-fiction storytelling combining archival research, verité shooting, and journalistic fact-checking requires extended production timelines and legal clearance workflows. Public broadcasters in Europe commission these formats under CSRD-aligned sustainability storytelling mandates.
- Commercials:Brand-funded spots for television, digital pre-roll, and cinema exhibition demand compressed timelines and celebrity talent coordination. Automotive advertisers deploy virtual production stages for rapid background iteration across campaign variants.
- Training Videos:Instructional content for employee onboarding, compliance certification, and technical skill transfer prioritizes clarity over production polish.
- Social Media Content:Platform-native vertical formats, algorithm-optimized pacing, and rapid turnaround requirements favor automated transcription and template-driven editing workflows.
Social media content generation is expanding most quickly as brands maintain always-on posting calendars across multiple platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors commercial production activity through its concentration of studio facilities, post-production houses, and talent representation infrastructure serving entertainment and advertising verticals.
United States
Streaming platform commissioning from Netflix, Disney+, and Amazon Prime Video sustains demand for premium scripted content across Los Angeles, Atlanta, and New York production corridors. The FCC enforces closed captioning standards under the Twenty-First Century Communications and Video Accessibility Act. Atlanta's Pinewood Studios complex hosts major franchise productions leveraging Georgia's tax incentive framework.
India
Regional language content creation surges across Hindi, Tamil, Telugu, and Malayalam categories as JioCinema, SonyLIV, and ZEE5 expand original programming slates. The Ministry of Information and Broadcasting oversees content certification through the Central Board of Film Certification. Mumbai's Film City and Hyderabad's Ramoji Film City operate at capacity serving OTT commissioning cycles.
Germany
Corporate video production and industrial documentation services concentrate in Munich and Hamburg serving automotive and engineering exporters. The EU AI Act mandates synthetic media disclosure for manipulated video content distributed within European markets. Cologne's MediaPark cluster houses broadcast production facilities for RTL Group and ProSiebenSat.1.
United Kingdom
High-end drama and documentary production attracts inward investment from US streaming platforms through London's Soho post-production district and Manchester's Space Studios. Ofcom regulates broadcast standards including accessibility requirements for on-demand services. Pinewood Studios and Shepperton Studios maintain stages for international franchise productions.
South Korea
K-content global expansion drives demand for K-drama and variety show production serving Netflix and domestic platform TVING. The Korea Communications Standards Commission enforces content rating and distribution regulations. Seoul's Sangam-dong digital media city concentrates virtual production stages and VFX facilities.
Video Production Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a fragmented vendor base where full-service studios, specialized boutiques, and platform-native creators occupy distinct competitive tiers. The market structure favors vertical specialists over integrated houses as corporate procurement teams unbundle pre-production, principal photography, and editorial finishing. Three archetypes dominate: cloud-rendered subscription services, healthcare-technology animation specialists, and broadcast-grade live production operators. Competitive moves center on M&A for capability stacking and geographic expansion into regional language production hubs.
Within the cloud-rendered tier, Crisp Video exemplifies asset-light delivery models serving mid-market corporate clients without infrastructure ownership. Levitate Media occupies the vertical specialization position through healthcare and technology animation pipelines. BLARE Media anchors the premium live production segment with broadcast-grade capabilities for sports and entertainment networks.
| Leading Market Players |
|---|
| Crisp Video |
| Lemonlight |
| Thrive Internet Marketing Agency |
| Sandwich |
| Levitate Media |
| BLARE Media |
| Clay Media Group |
| Zero One Digital Media |
| New Evolution Video |
| Others |
Value Network & Pricing Analysis
Cloud-rendered delivery infrastructure compresses fixed-cost barriers for mid-market corporate clients while broadcast-grade live production hardware anchors premium pricing tiers for sports and entertainment networks. Technical director expertise scarcity in major production hubs concentrates margin power among established operators commanding retainer-based relationships.
Pricing Analysis
Uptime guarantees for flawless live event execution anchor value-based pricing for broadcast-grade productions, while subscription SaaS tiers dominate corporate post-production workflows. Three-tier pricing structure across premium, standard, and economy levels separates enterprise virtual production stages from regional cloud-rendered services and independent creator toolkits. Price differentiation hinges on certification level for FCC closed captioning compliance and vertical specialization depth. Cost compression in mid-market corporate segments intensifies because procurement teams unbundle services and negotiate component-level contracts. Independent creators exhibit highest price sensitivity, while streaming platforms commissioning original series demonstrate lowest sensitivity due to content exclusivity premiums.
Supply Chain Analysis
Asset refurbishment and hardware redeployment flows from broadcast network upgrade cycles feed secondary equipment markets serving emerging regional production hubs. Manufacturing concentrates in Japan for broadcast-grade camera sensors, Germany for precision lighting systems, and Taiwan for LED volume display panels. Raw material dependencies span rare earth elements for display phosphors, high-purity aluminum for heat-dissipating chassis, and specialized optical glass for cinema lenses. Single-source vulnerability in professional camera sensor fabrication creates supply chain risk for premium acquisition tiers. Distribution runs through authorized dealer networks for broadcast hardware and direct platform APIs for cloud-rendered software tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical director talent scarcity in live production creates a supply-constrained market structure that sustains premium pricing for broadcast-grade operators despite cloud-rendered compression elsewhere.
For Market Incumbents: Anticipate synthetic media disclosure mandates forcing provenance documentation infrastructure rebuilds across European operations. Defend margin position through backward integration into LED volume stage ownership in Atlanta and London production corridors. Prioritize certification investment for EU AI Act compliance ahead of platform-specific policy fragmentation. For New Entrants and Emerging Players: FCC closed captioning enforcement expansion in the United States opens a window for certified transcription and audio description boutiques. Target mid-market corporate subscription models in India where regional language content demand outstrips localized production capacity. Pursue vertical specialization in healthcare animation pipelines where technical complexity deters generalist competition. For Investors and Strategic Acquirers: Major streaming platform commissioning announcements for regional language slates are the leading indicator that India's production infrastructure will experience capacity bottlenecks. Position for long-term viability by acquiring cloud-rendered delivery platforms with established mid-market corporate relationships rather than asset-heavy stage operators. Monitor EU AI Act audit enforcement timelines as the signal for provenance documentation technology valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Provenance Documentation Infrastructure Build | EU AI Act compliance mandates chain-of-custody metadata systems from capture through distribution for European broadcasters. |
| Regional Language Production Capacity Expansion | JioCinema and SonyLIV commissioning cycles in Mumbai and Hyderabad strain existing facility utilization rates. |
| Healthcare Animation Pipeline Acquisition | Medical device visualization and surgical training content commands premium pricing and recurring enterprise engagements. |
| Cloud-Rendered Delivery Platform Integration | Mid-market corporate procurement teams favor subscription models eliminating on-premise infrastructure capital requirements. |
| Live Production Technical Director Talent Retention | Flawless event execution expertise concentration in Los Angeles and New York sustains premium retainer pricing power. |
Research Methodology
Document review covered SEC filings from streaming platform operators, FCC enforcement action records, and EU regulatory implementation guidance, complemented by interviews with post-production house technical directors, corporate video procurement managers, broadcast network production executives, and OTT platform commissioning leads. Secondary validation drew from trade association membership data, equipment manufacturer shipment reports, and platform content spend disclosures. Bottom-up service provider revenue estimates triangulated against top-down streaming content investment flows.
Historical production volume patterns cross-referenced against panel input from production facility operators informed the analytical framework across the analysis window. Segmentation dimensions modeled include service type, resolution specification, client procurement sophistication, and regional regulatory cluster. CAGRs derived from trend extrapolation of streaming commissioning cycles and technology adoption curves for AI-assisted editorial tools. Forecast inputs incorporated virtual production stage deployment rates and synthetic media disclosure compliance cost estimates.
The model assumes a particular technology adoption path for neural rendering engines; alternative pathways for LED volume standardization would alter the outlook for location-agnostic shooting demand. Forecasts reflect assumptions about regulatory enforcement timing and platform content moderation policy convergence. Practitioners should monitor EU AI Act audit implementation schedules and FCC closed captioning penalty escalations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Middle East Media and Entertainment Market
Digital Media
Global Digital Painting Market
Digital Media
Global Playout Automation and Channel in a Box Market
Digital Media
Europe Inflight Entertainment and Connectivity Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
India Webtoons Market
Digital Media
Anime Merchandising Market
Digital Media
Multichannel Network Market
Digital Media
Social TV Market
Digital Media
Professional Dubbing Services Market
Digital Media
Music Rights Management Market
Digital Media
Africa Animation Market
Digital Media
Anime Streaming Tool Market
Digital Media
Naruto Around Market
Digital Media
Visual Effects (VFX) Market
Digital Media
3D Anaglyph Glasses Market