
 Digital Media Switchers Market | 2026-2036
Digital Media Switchers Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Media Switchers Market Analysis
Live event production is expanding as a dominant demand vertical for digital media switchers, displacing traditional fixed-installation broadcasting studios as the fastest-growing buyer category. Blackmagic Design leverages aggressive price-performance positioning to compete across indie film and mid-tier live event segments. Sony Corporation sustains technology leadership in 4K and 8K switching platforms through deep R&D investment in image processing chipsets. Ross Video anchors North American broadcast infrastructure with specialized production switcher lines tailored to regional sports networks.
Digital media switchers route, process, and transition multiple video and audio signals through hardware or software-defined architectures, with modern units handling uncompressed 12G-SDI at data rates up to 12 Gbps for 4K60 workflows. These devices serve as the central nervous system of live production environments, enabling real-time source selection, layering, and distribution to broadcast transmitters or streaming endpoints. IP switchers represent the fastest-expanding technology segment as facilities migrate from baseband SDI to SMPTE ST 2110 packet-based infrastructures, while HDMI switchers occupy the highest-volume tier in corporate and education deployments where cost sensitivity dominates procurement. Cloud-based switching platforms are displacing hardware-only solutions in distributed production scenarios, though hybrid architectures retain the largest margin pool by combining on-premise reliability with remote accessibility.
The FCC governs broadcast transmission standards in the United States, while the EU AI Act and CE marking frameworks shape product compliance requirements for switchers deployed in European media facilities. EMA and national regulators across member states enforce electromagnetic compatibility and safety certifications that determine market access for imported switching hardware. Stakeholders must monitor the pace of IP standardization versus legacy SDI persistence, as this technical transition dictates replacement cycles and vendor selection criteria across end-user verticals.
Market Dynamics
The migration from baseband SDI to SMPTE ST 2110 IP-based workflows constitutes the dominant structural force reshaping procurement patterns and vendor selection criteria across broadcast and live event verticals.
Growth Catalysts
- FCC Broadcast Spectrum Repack:The United States spectrum reallocation mandates infrastructure refresh cycles, accelerating switcher replacement demand among terrestrial broadcasters upgrading transmission chains.
- Live Event Production Surge:Corporate conferences, esports tournaments, and touring concerts now require broadcast-grade switching capabilities previously reserved for fixed studios.
- Cloud-Native Production:Distributed remote production models reduce on-site hardware footprints while expanding addressable production volume for regional sports and entertainment clients.
Market Restraints
- Semiconductor Supply Concentration:Advanced FPGA and image processing chipsets depend on concentrated Asian foundry capacity, creating procurement lead time volatility for high-end switcher manufacturers.
- Legacy Infrastructure Lock-In:Installed base of 3G-SDI routers and copper cabling imposes steep retrofit costs on facilities weighing IP migration timing.
- Specialized Engineering Talent Scarcity:Deep expertise in uncompressed IP video timing, PTP synchronization, and network fabric configuration remains concentrated among a narrow pool of broadcast systems integrators.
Strategic Opportunities
- India Broadcast Modernization:TRAI-mandated digitization and expanding regional language channels create greenfield demand for IP-native switcher deployments in Mumbai, Delhi, and Bengaluru production hubs.
- AI-Assisted Production:Machine learning-driven camera tracking, automated switching, and real-time highlight generation converge with traditional hardware to reduce operator headcount in cost-sensitive venues.
- EU Green Deal Alignment:Energy efficiency certification and circular economy requirements favor modular, upgradeable switcher architectures over monolithic replacement cycles.
Industry Challenges
- Multi-Vendor Interoperability:Incomplete ST 2110 implementation variations across manufacturers force extensive on-site integration testing before facility commissioning.
- Cybersecurity Hardening:IP-connected production infrastructure exposes live broadcasts to network intrusion risks, requiring continuous security patching and segmented network architecture expertise.
- Compressed Certification Timelines:CE marking and electromagnetic compatibility validation for new 8K-capable switcher lines strain engineering resources during product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Media Switchers Market |
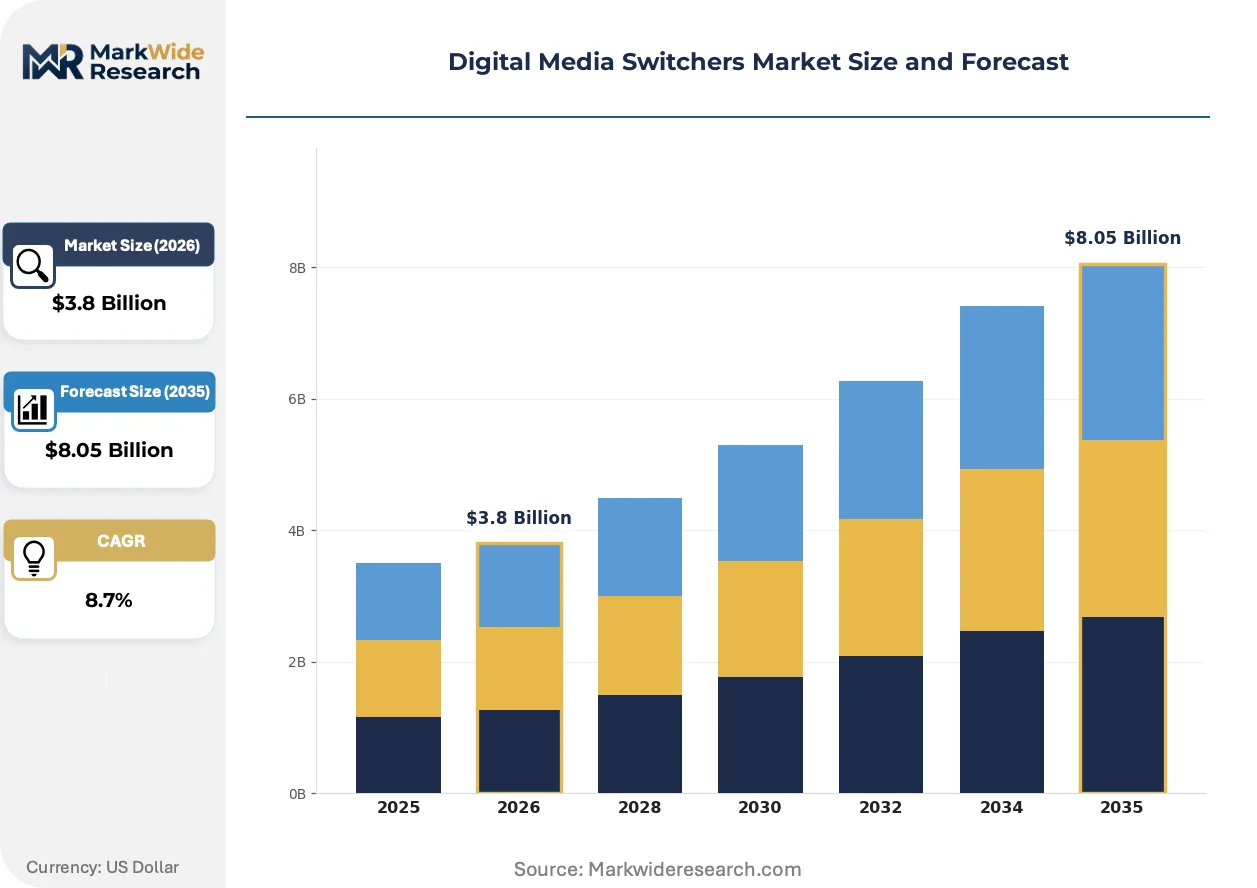
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDMI Switchers, SDI Switchers, IP Switchers, Audio Switchers Technology: Analog, Digital, Hybrid, Cloud-Based End User: Broadcasting, Corporate, Education, Entertainment Application: Live Events, Broadcasting Studios, Conference Rooms, Control Rooms |
| Companies Covered | Sony Corporation, Panasonic Corporation, Ross Video, Grass Valley, Blackmagic Design, Evertz Microsystems, Crestron Electronics, Extron Electronics, Kramer Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Media Switchers Market Emerging Trajectories
Three interconnected developments are compressing product lifecycles and redistributing value capture across hardware, software, and service layers in digital media switching.
Software-defined switching is electrifying traditional hardware-centric business models. Virtualized production switchers running on commercial off-the-shelf servers now handle 4K60 workflows with latency profiles matching dedicated silicon. Mid-tier live event producers in Las Vegas and London are deploying these configurations for rapid format reconfiguration between corporate presentations and concert broadcasts. The technology is electrifying margin pressure on established hardware vendors while opening subscription revenue streams for cloud-native entrants.
REACH substance restrictions and RoHS recast directives in Europe are tightening material compliance requirements for switching hardware. Manufacturers must document supply chain provenance for flame retardants, heavy metals, and conflict minerals across multi-tier supplier networks. Broadcast equipment destined for Frankfurt, Paris, and Amsterdam media facilities now faces extended qualification periods as vendors requalify component substitutions to maintain CE marking validity.
Esports venues and houses of worship are consolidating procurement authority into centralized technical directors who specify switcher ecosystems across multiple locations. This buyer concentration favors vendors offering unified control surfaces, shared configuration libraries, and remote diagnostic access. The pattern is most pronounced in Texas, Georgia, and North Carolina where multi-site church networks and collegiate esports programs standardize on single-vendor switching infrastructure to reduce training overhead and spare parts inventory.
Digital Media Switchers Market Segmentation
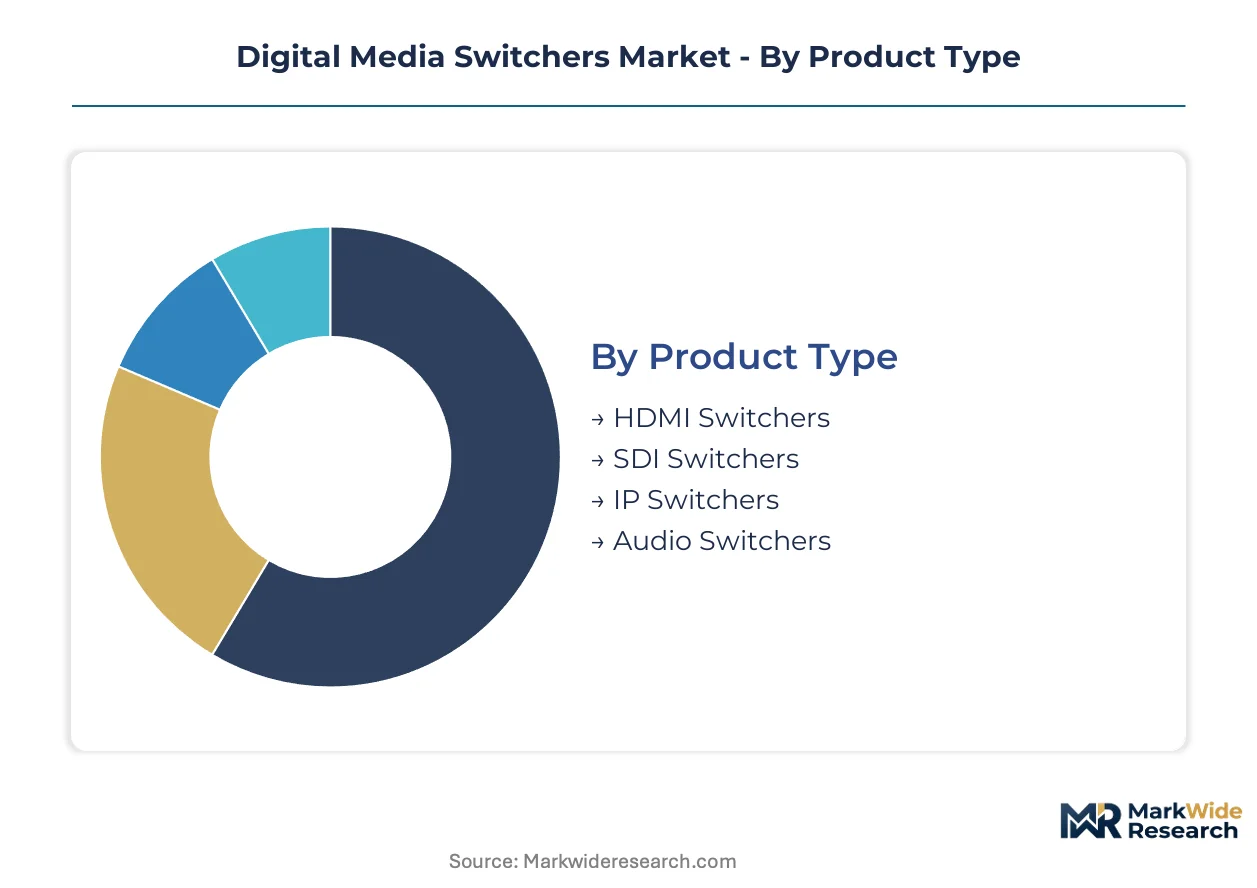
Digital media switchers fragment across signal formats, processing architectures, and deployment contexts that dictate engineering specifications and procurement budgets. Each segmentation axis reveals distinct vendor positioning strategies and replacement cycle dynamics that shape competitive outcomes across live production environments.
Product Type:
Signal format specifications determine bandwidth capacity, cable infrastructure requirements, and interoperability boundaries across installation types.
- IP Switchers:SMPTE ST 2110 packet-based routing handles uncompressed video over standard Ethernet fabrics with microsecond-level timing precision. Demand concentrates in United States sports broadcasting hubs where remote production models require campus-scale signal distribution without dedicated coaxial plant.
- SDI Switchers:Serial digital interface architectures remain dominant in legacy broadcast facilities, processing 12G-SDI at 12 Gbps for 4K60 workflows through dedicated copper or fiber infrastructure. Mature installed bases in European terrestrial broadcast centers impose steep retrofit costs that delay migration timing.
- HDMI Switchers:Consumer-derived connectivity dominates corporate AV and education deployments where cost sensitivity overrides broadcast-grade reliability requirements.
- Audio Switchers:Dedicated audio routing systems serve discrete channel management in post-production suites and live sound reinforcement applications.
Mature deployment sits with SDI Switchers. Newer deployment is concentrated in IP Switchers.
Technology:
Processing architecture choices separate hardware-dependent reliability from software-driven flexibility in production workflow design.
- Cloud-Based:Virtualized switching instances running on commercial servers enable distributed production with centralized control, reducing on-site hardware footprints for regional sports and entertainment clients. Adoption accelerates fastest among mid-tier live event producers seeking rapid format reconfiguration between corporate presentations and concert broadcasts.
- Hybrid:Architectures combine on-premise processing cores with remote accessibility layers, capturing the largest margin pool by balancing reliability requirements against operational flexibility demands.
- Digital:All-digital signal paths eliminate analog conversion stages, standard in facilities built since the HD transition.
- Analog:Legacy composite and component switching persists only in museum archive access and specific retrofit-constrained installations.
Volume concentration favors Hybrid systems. Steepest expansion trajectory belongs to Cloud-Based platforms.
End User:
Buyer organizational types impose distinct procurement authority structures, technical staffing levels, and budget cycle constraints.
- Broadcasting:Terrestrial, cable, and satellite operators mandate 99.999% availability with redundant signal paths, driving premium-tier procurement of hardened hardware platforms. Spectrum repack mandates in the United States accelerate infrastructure refresh cycles among major network affiliates.
- Corporate:Enterprise AV departments standardize switcher ecosystems across headquarters, regional offices, and event spaces to reduce training overhead and spare parts inventory. Procurement authority concentrates in technical directors overseeing multi-site deployments in Texas, Georgia, and North Carolina.
- Entertainment:Touring concerts, esports tournaments, and theatrical productions prioritize rapid load-in/load-out and compact transport footprints.
- Education:K-12 and university technology departments face severe budget constraints that favor HDMI-based solutions over broadcast-grade alternatives.
Revenue concentration remains with Broadcasting. Gaining share fastest is Corporate vertical expansion into broadcast-quality capabilities.
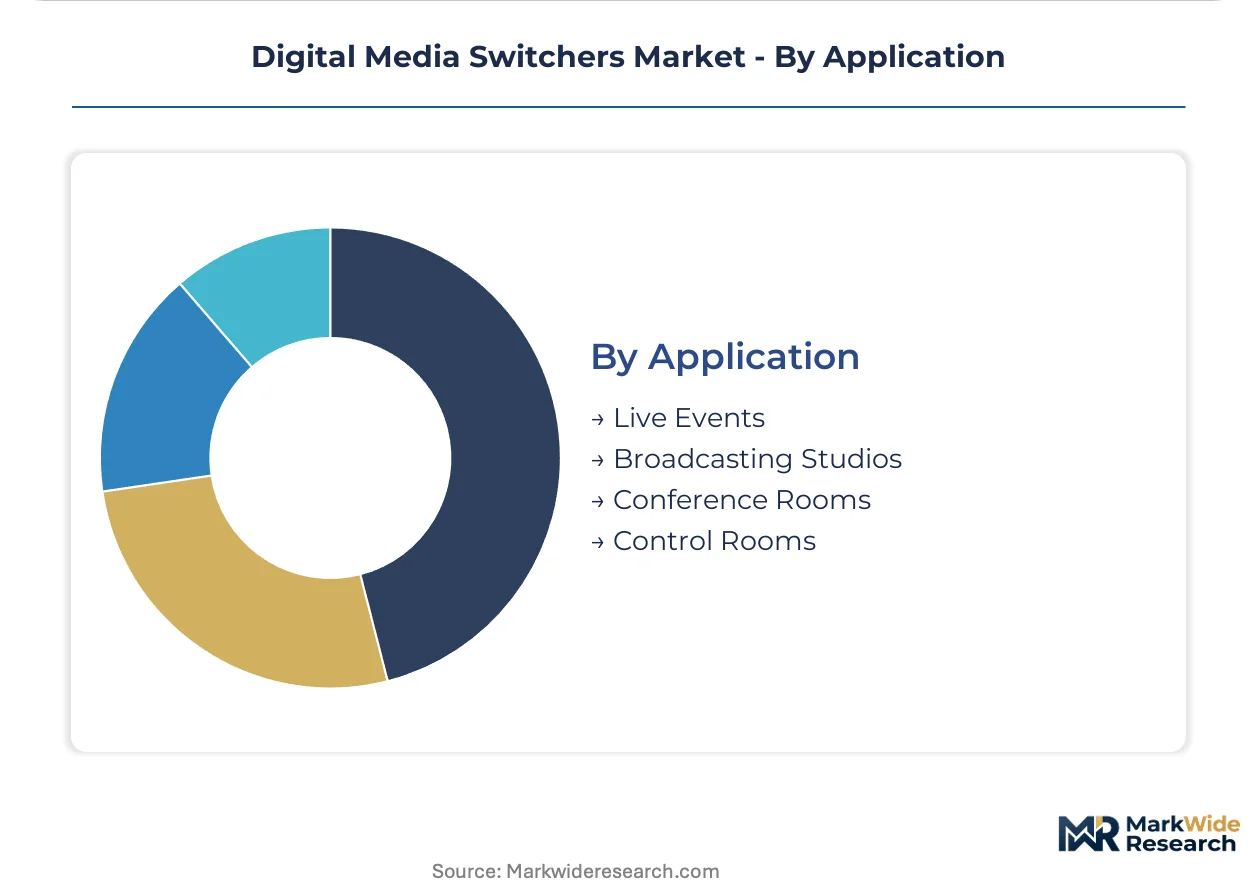
Application:
Physical deployment contexts dictate environmental hardening requirements, operator skill levels, and integration complexity with surrounding infrastructure.
- Live Events:Temporary installations demand rapid deployment, compact transport, and intuitive operation by rotating technical crews. Esports venues and touring concert productions in Las Vegas and London drive demand for software-reconfigurable platforms.
- Broadcasting Studios:Fixed facilities prioritize signal path redundancy, precise timing synchronization, and deep integration with playout automation systems. Major sports broadcasting hubs in the United States anchor procurement volume for premium-tier hardware.
- Control Rooms:Security, transportation, and utility operations require 24/7 reliability with specialized alarm integration and multi-year service agreements.
- Conference Rooms:Huddle spaces and boardrooms prioritize automated source detection and consumer-grade usability over manual switching precision.
Fixed infrastructure investment centers on Broadcasting Studios. Climbing the fastest is Live Events production scaling to broadcast-grade capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Dubai Media City concentrate broadcast equipment manufacturing and regional distribution hubs for digital media switchers. Tax incentives and customs exemptions in these zones attract component suppliers and systems integrators serving adjacent production markets. The geographic spread of demand reflects divergent infrastructure maturity and regulatory pacing across national broadcast markets.
United States
Major sports broadcasting hubs in Los Angeles, New York, and Atlanta drive premium-tier switcher procurement for 4K and 8K live production workflows. FCC broadcast spectrum repack mandates accelerate infrastructure refresh cycles among terrestrial network affiliates. Corporate AV clusters in Texas and Georgia standardize multi-site switching ecosystems to reduce training overhead.
Germany
Frankfurt and Munich media facilities anchor European demand for IP-native ST 2110 switching platforms as public broadcasters modernize playout infrastructure. REACH substance restrictions and RoHS recast directives tighten material compliance requirements for switching hardware. Industrial broadcast integrators in Bavaria specialize in automotive sector live event production systems.
Japan
Tokyo metropolitan broadcasters and Osaka-based production houses sustain demand for high-reliability hardware platforms with 99.999% availability specifications. METI industrial policy supports domestic semiconductor and image processing chipset development for broadcast equipment. Nagoya manufacturing corridors supply precision timing components for PTP-synchronized IP video networks.
India
TRAI-mandated digitization and expanding regional language channels create greenfield demand in Mumbai, Delhi, and Bengaluru production hubs. BIS certification requirements and PLI scheme incentives shape vendor selection for broadcast infrastructure tenders. Local systems integrators in Hyderabad specialize in cost-optimized HDMI-to-IP gateway deployments for education and corporate verticals.
United Kingdom
London post-production suites and Manchester regional broadcast centers drive hybrid cloud-premise switching adoption for distributed production models. CE marking frameworks and electromagnetic compatibility validation determine market access for imported switching hardware. Bristol creative technology clusters incubate software-defined virtualized switching startups targeting mid-tier live event producers.
Digital Media Switchers Market Vendor Landscape
Top-tier vendors anchor premium broadcast infrastructure, while mid-tier specialists compete on price-performance for live event and corporate AV segments. The vendor base stratifies across three tiers: hardened hardware platforms for terrestrial broadcasters, software-reconfigurable systems for touring productions, and cloud-native virtualized instances for distributed remote workflows. Two dominant competitive moves define current positioning: strategic partnerships between hardware manufacturers and cloud infrastructure providers, and portfolio diversification into adjacent audio routing and signal processing categories.
Within the premium-tier broadcast infrastructure segment, Sony Corporation and Ross Video occupy positions exemplifying deep R&D investment in image processing architectures. Blackmagic Design represents aggressive price-performance positioning across indie film and mid-tier live event segments. Panasonic Corporation anchors diversified electronics conglomerate participation spanning professional broadcast, corporate AV, and consumer imaging product lines.
| Leading Market Players |
|---|
| Sony Corporation |
| Panasonic Corporation |
| Ross Video |
| Grass Valley |
| Blackmagic Design |
| Evertz Microsystems |
| Crestron Electronics |
| Extron Electronics |
| Kramer Electronics |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up broadcast equipment specialists concentrate ownership across mid-tier switcher manufacturers, tightening pricing discipline through portfolio-wide procurement leverage while feeding supply consolidation into fewer approved vendor lists. This ownership pattern compresses margins for component suppliers and amplifies price coordination across corporate AV and live event distribution channels.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent procurement premiums from spot-inventory discounts across FPGA and image processing chipset tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FCC-compliant broadcast-grade hardware commanding substantial premiums over uncertified corporate AV alternatives. Price differentiation stems from volume scale and customization level, with enterprise multi-site contracts extracting deeper discounts than single-venue theatrical deployments. Cost compression in mid-tier live event segments is intensifying because Blackmagic Design's aggressive price-performance positioning forces legacy vendors to absorb margin erosion or cede share.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and BIS certification requirements are reshaping sourcing patterns for switcher assembly destined for Mumbai and Delhi production hubs. Manufacturing concentrates in China, Taiwan, and Japan, with advanced FPGA and image processing chipsets drawing from concentrated Asian foundry capacity. Raw material dependencies center on precision timing components, high-bandwidth connectors, and specialized thermal management substrates. Single-source vulnerability in semiconductor supply creates procurement lead time volatility for high-end switcher manufacturers. Distribution runs through Shenzhen Special Economic Zone hubs and Dubai Media City regional distribution centers serving adjacent production markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Media Switchers Market functions as a cost-of-compliance story where FCC broadcast spectrum repack mandates and EU CE marking frameworks erect formidable barrier-to-entry moats favoring incumbents with established certification pipelines and regulatory affairs infrastructure.
For Market Incumbents: Anchor premium-tier positioning through deep R&D investment in 8K image processing chipsets and PTP-synchronized IP video timing, defending against software-defined virtualized switching entrants by emphasizing 99.999% availability specifications that cloud-native platforms struggle to match. Certification investment in REACH substance compliance and RoHS recast directives preserves CE marking validity across European media facilities, locking out uncertified challengers from Frankfurt and Munich procurement cycles.
For New Entrants and Emerging Players: Capture white-space opportunity in India's TRAI-mandated digitization wave, where greenfield IP-native switcher deployments in Bengaluru and Hyderabad production hubs lack entrenched vendor relationships and favor cost-optimized HDMI-to-IP gateway solutions. Target mid-tier live event producers in Las Vegas and London seeking rapid format reconfiguration between corporate presentations and concert broadcasts, deploying software-reconfigurable platforms on subscription SaaS tiers to bypass capital-intensive hardware manufacturing barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor software-defined virtualized switching specialists in Bristol and London creative technology clusters, where hybrid cloud-premise architectures attract venture backing amid broadcast infrastructure refresh delays. Long-term viability hinges on IP standardization pace versus legacy SDI persistence, with acquisition targets demonstrating ST 2110 implementation maturity and multi-vendor interoperability testing capabilities positioned for consolidation premiums. The signal to watch is semiconductor supply lead time normalization, which would release pent-up replacement demand and revalue hardware-dependent revenue streams.
| Strategic Initiative | Industry Significance |
|---|---|
| ST 2110 IP-Native Platform Development | Enables campus-scale signal distribution for United States sports broadcasting hubs migrating from baseband SDI. |
| AI-Assisted Production Integration | Machine learning-driven camera tracking reduces operator headcount in cost-sensitive esports venues and houses of worship. |
| Modular Upgradeable Architecture Design | EU Green Deal alignment favors circular economy compliance over monolithic replacement cycles in Frankfurt media facilities. |
| Cloud Infrastructure Partnership | Strategic alliances between hardware manufacturers and hyperscalers unlock distributed remote production for regional sports networks. |
| Multi-Site Corporate AV Standardization | Unified control surfaces reduce training overhead across Texas, Georgia, and North Carolina church network deployments. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with broadcast systems integrators, live event technical directors, corporate AV procurement managers, and semiconductor supply specialists with validation against FCC spectrum repack documentation, EU CE marking frameworks, and TRAI digitization mandates. Bottom-up and top-down triangulation cross-referenced vendor shipment data, facility installation records, and procurement budget disclosures from major sports broadcasting hubs and corporate AV clusters.
Granularity-level modeling disaggregated projections across signal format specifications, processing architecture choices, buyer organizational types, and physical deployment contexts, with additional dimensioning by regional regulatory cluster and infrastructure maturity tier. CAGRs derived from replacement cycle analysis, technology transition pacing, and vertical demand elasticity. Industry-specific forecast inputs incorporated semiconductor supply lead time volatility and IP standardization adoption curves across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to multi-vendor ST 2110 interoperability completion, cybersecurity hardening requirements, and specialized engineering talent scarcity in uncompressed IP video timing. Forecasts reflect assumptions regarding spectrum repack completion timelines and cloud-native platform reliability maturation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Middle East Media and Entertainment Market
Digital Media
Europe Animation Market
Digital Media
Latin America Inflight Entertainment and Connectivity Market
Digital Media
Stock Music Software Market
Digital Media
Asia-Pacific Webtoons Market
Digital Media
Video Content Management Market
Digital Media
Stream Hosting Market
Digital Media
Cognitive Media Market
Digital Media
Playout Solutions Market
Digital Media
VFX Market
Digital Media
Digital Video Advertising Market
Digital Media
Media and Entertainment Market
Digital Media
Middle East and Africa Inflight Entertainment and Connectivity Market
Digital Media
Africa Animation Market
Digital Media
Global Playout Automation and Channel in a Box Market
Digital Media
Digital Video Content Market