
 Cognitive Media Market | 2026-2036
Cognitive Media Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Media Market Intelligence
Subscription-based access to machine learning models and APIs is consolidating the cognitive media landscape, shifting focus from software sales to continuous service delivery. Microsoft Corporation leverages its Azure cloud to offer a suite of cognitive services for content analysis. Google LLC competes through its deep AI research and integration into its advertising platforms. Adobe specializes in creative workflows, embedding AI features into its media production software.
Cognitive media applies artificial intelligence, specifically deep neural networks and natural language processing, to interpret, generate, and modify media content automatically. The technology's primary commercial purpose is enabling hyper-personalization, automating complex content creation, and analyzing audience sentiment at a massive scale. Within applications, personalized advertising and interactive entertainment command significant investment. Cloud-based deployment models overwhelmingly dominate the market, offering superior scalability and reduced upfront costs for e-commerce platforms and marketing agencies.
Regulatory frameworks such as the EU's GDPR and the proposed AI Act, alongside China's regulations on algorithmic recommendations, directly influence data handling and model transparency requirements. These rules compel technology developers to build explainable AI systems and secure explicit user consent for personal data processing. Vendor selection will increasingly hinge on the ability to demonstrate robust compliance with these evolving ethical and legal standards governing automated media.
Market Dynamics
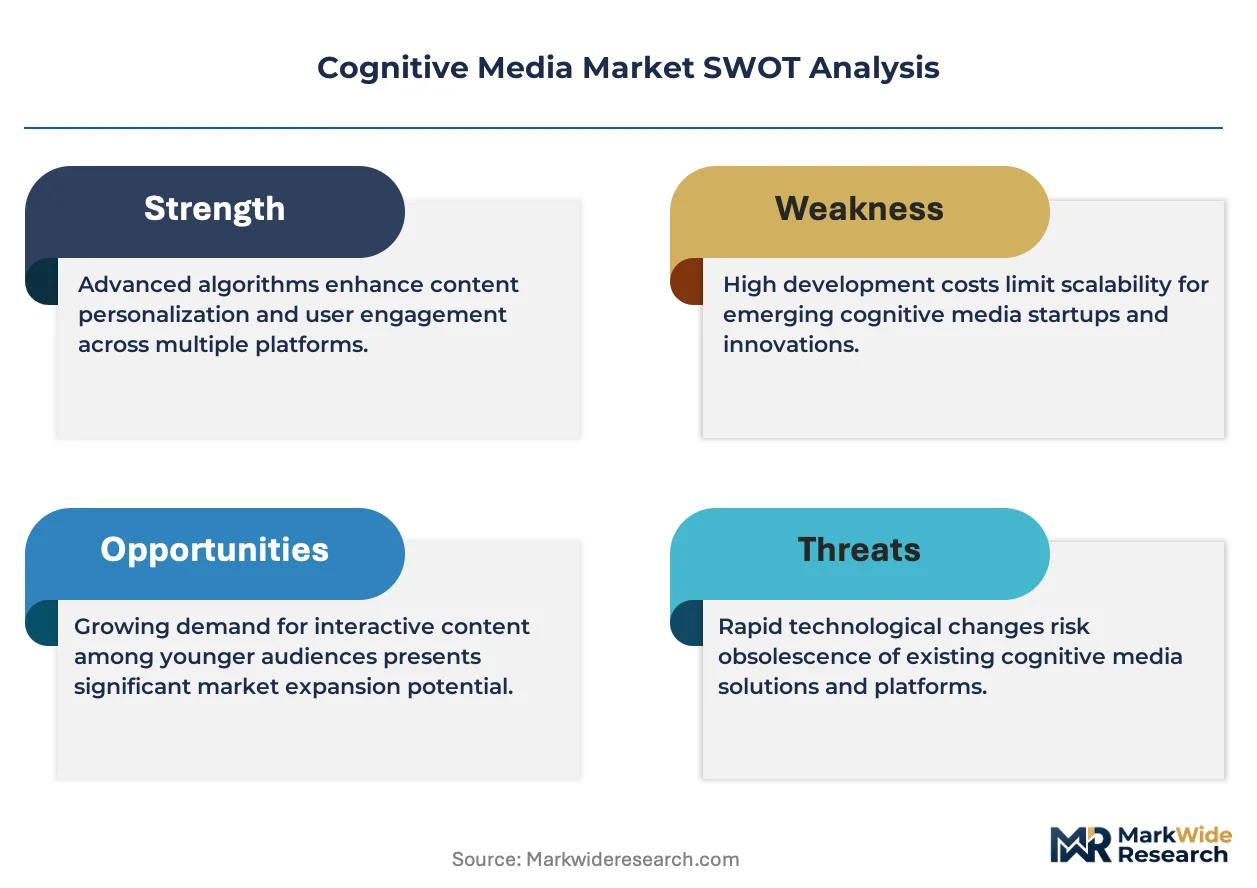
The central dynamic shaping the cognitive media market is the collision between enterprise demand for hyper-personalization and the rising global mandate for algorithmic transparency, exemplified by regulations like the EU AI Act and China's rules on recommendation engines.
Growth Catalysts
- E-commerce Integration:Demand from online retail and advertising technology sectors for automated content moderation and personalized ad creation is a primary catalyst, improving user engagement and conversion rates on major platforms.
- Cloud Service Accessibility:The proliferation of scalable, API-driven cognitive services on public clouds like Microsoft Azure and Google Cloud lowers the technical and financial barriers for smaller companies to deploy advanced AI.
- Generative AI Progress:Rapid advancements in deep neural network architectures, particularly large language models and diffusion models, unlock new capabilities for high-quality, automated media generation, expanding the technology's addressable applications.
Market Restraints
- High Computational Costs:Training and operating state-of-the-art deep learning models requires access to vast, expensive GPU clusters, presenting a significant cost barrier that concentrates market power among large, well-capitalized technology firms.
- Regulatory Fragmentation:Divergent and sometimes conflicting data privacy and AI governance laws, such as Europe's GDPR and various state-level rules in the United States, create significant compliance complexity and legal risks for vendors.
- Explainability Deficit:The inherent "black-box" nature of many complex neural networks makes it difficult to provide the model transparency and explainability required by emerging regulations, hindering adoption in risk-averse industries.
Strategic Opportunities
- Synthetic Data Generation:Creating high-fidelity, privacy-compliant synthetic datasets for model training presents a significant opportunity to bypass restrictions on personal data usage, creating a new market for data-as-a-service providers.
- Ethical AI Auditing Services:The implementation of frameworks like the EU AI Act creates a new market for third-party services that can audit cognitive media algorithms for fairness, bias, and transparency to ensure regulatory compliance.
- Hyper-Local Content Automation:Applying cognitive media to automate the generation of localized marketing copy, community news, and business reporting for specific geographic or niche vertical markets remains a largely underpenetrated field.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of MLOps engineers and AI researchers with cross-disciplinary expertise in both deep learning and media ethics constrains the pace of product innovation and secure deployment.
- Content Provenance and Watermarking:Developing and standardizing robust technical methods to invisibly watermark and authenticate AI-generated content is a critical operational challenge for preventing misuse and combating sophisticated misinformation at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Media Market |
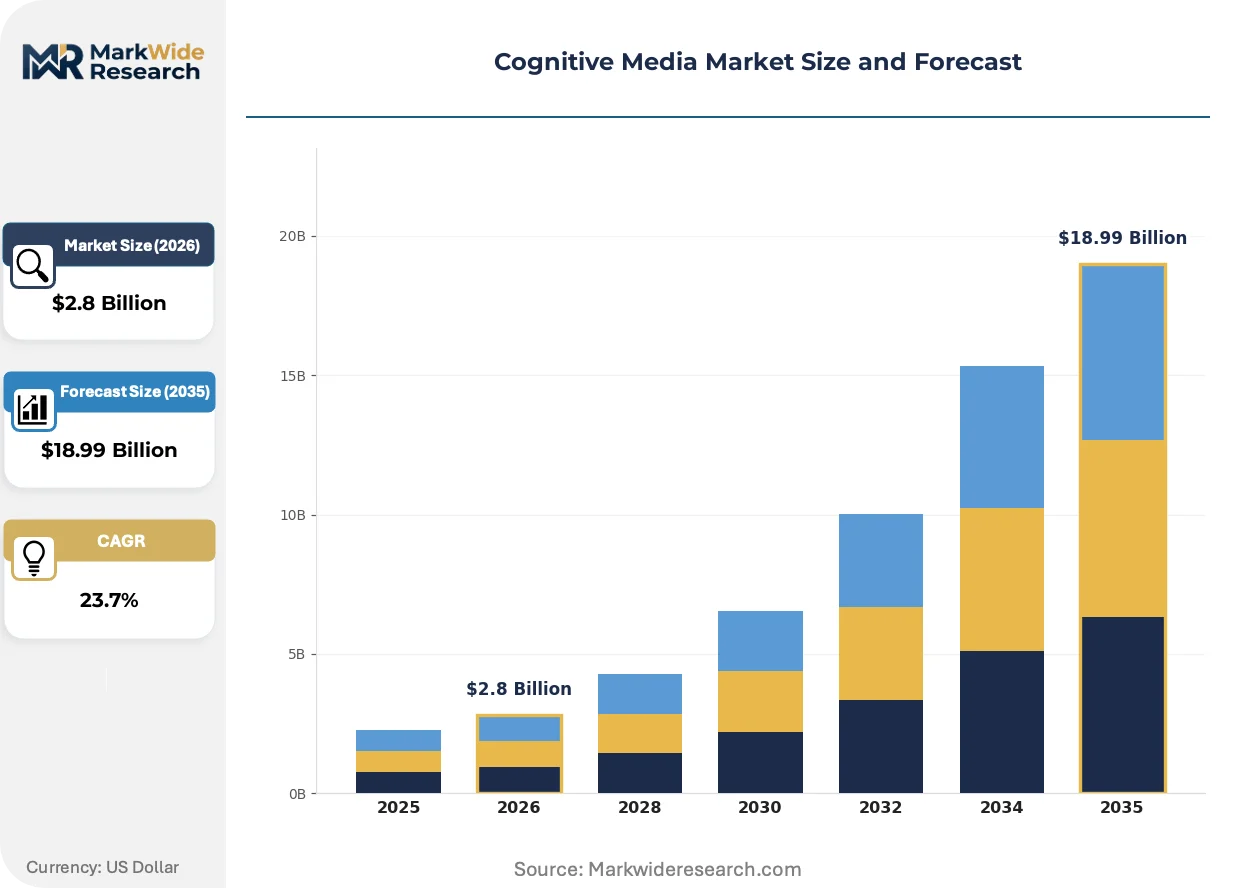
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $18.99 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Natural Language Processing, Computer Vision, Speech Recognition, Machine Learning, Neural Networks Application: Content Creation, Sentiment Analysis, Personalized Advertising, Interactive Entertainment, Brand Monitoring End User: Media Publishers, Marketing Agencies, E-commerce Platforms, Research Firms, Educational Institutions Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Microsoft Corporation, Google LLC, Amazon Web Services, IBM Corporation, Salesforce, Adobe, NVIDIA, Baidu, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Media Market Strategic Shifts & Innovations
The industrialization of creative AI is actively reshaping the market. Abstract research concepts are being productized into accessible, API-driven tools, shifting the competitive landscape from bespoke development projects toward scalable, continuous service delivery models offered by major cloud providers.
Generative models, including diffusion and transformer-based architectures, create novel, high-fidelity media from simple text or data inputs. Creative agencies, game developers, and corporate marketing departments are rapidly adopting these systems. This technology is electrifying the content production pipeline, compressing project timelines and altering the economics of media creation.
China's regulations on algorithmic recommendation services, enforced by the Cyberspace Administration of China, represent a significant policy shift. These rules require platforms to offer users clear options to disable personalization and mandate algorithmic transparency filings with the government. This directly impacts e-commerce and social media companies, which must re-engineer their systems to comply.
Consumption-based pricing for AI model APIs is displacing traditional perpetual software licenses. This model disrupts enterprise sales cycles, favoring cloud platform vendors who provide flexible, pay-as-you-go access to a suite of cognitive services. The shift is most visible among marketing technology startups and digital agencies in North America and Europe that prioritize operational agility.
Cognitive Media Market Segmentation
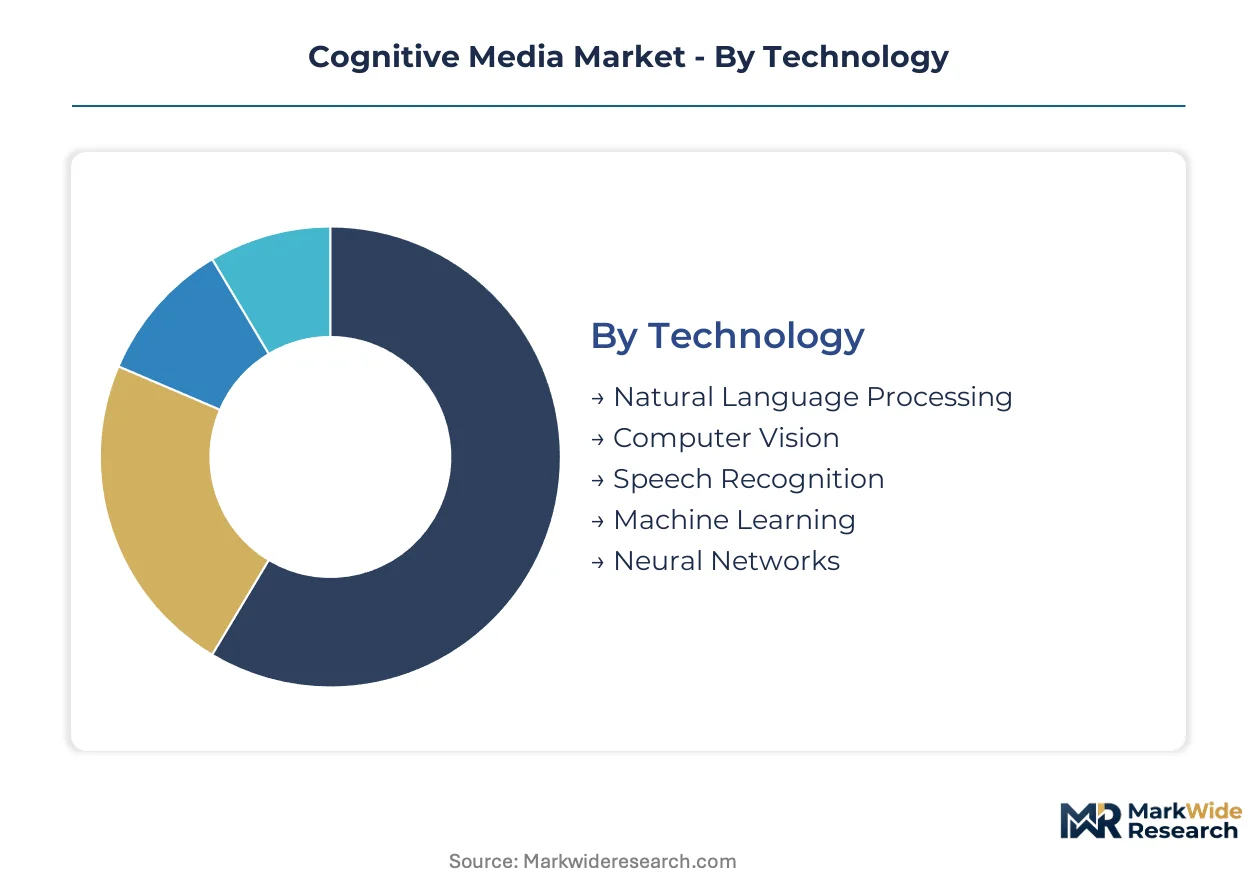
Understanding the distinct components of the cognitive media market reveals the varied technological demands and application priorities across industries. This segmentation provides clarity on where innovation is concentrating and how different user groups leverage advanced AI capabilities for content creation and analysis.
Technology:
The regulatory landscape for AI technologies often imposes specific compliance burdens, requiring developers to ensure explainability and fairness, particularly for models deployed in regulated sectors under frameworks like the EU AI Act.
- Natural Language Processing:This technology processes and understands human language, enabling tasks such as text generation, sentiment analysis, and content summarization. Demand for NLP is high in marketing agencies and e-commerce platforms seeking to automate customer interaction and personalized content delivery.
- Machine Learning:Machine learning algorithms enable systems to learn from data, identify patterns, and make predictions or decisions without explicit programming. Its application is critical for developing adaptive recommendation engines and optimizing content delivery across diverse user bases in China and Europe.
- Computer Vision:This segment allows machines to interpret and understand visual information from images and videos, facilitating object recognition, facial detection, and visual content moderation.
- Neural Networks:These are computational models inspired by the human brain, forming the foundation for deep learning and enabling complex pattern recognition and generative AI capabilities.
- Speech Recognition:This technology converts spoken language into text, vital for transcribing audio content, enabling voice commands, and enhancing accessibility features in media applications.
Leading the category by volume: Natural Language Processing. Growing fastest: Machine Learning.
Application:
The market's application segments delineate the primary commercial uses for cognitive media solutions, highlighting areas of significant investment and operational impact for businesses.
- Personalized Advertising:This application tailors ad content and placement to individual user preferences and behaviors, leveraging AI to maximize engagement and conversion rates. E-commerce platforms in North America and Asia-Pacific are heavily investing in this area to optimize customer journeys.
- Content Creation:This segment involves using AI to automatically generate text, images, video, or audio, streamlining the production workflow for marketing campaigns and digital media. Creative agencies and media publishers are adopting these tools to accelerate content pipelines and reduce costs.
- Sentiment Analysis:This application uses NLP to determine the emotional tone behind text, voice, or visual content, providing insights into public opinion and brand perception.
- Interactive Entertainment:This segment integrates cognitive media into gaming, virtual reality, and other immersive experiences to create more dynamic and responsive user interactions.
- Brand Monitoring:This application employs AI to track and analyze mentions of a brand across various media channels, identifying trends and managing reputation.
The largest application area is Personalized Advertising. The application expanding most quickly is Content Creation.
End User:
Customer types for cognitive media solutions reveal the diverse industries benefiting from AI-driven content and analysis tools, reflecting varied operational needs and digital maturity levels.
- E-commerce Platforms:These platforms utilize cognitive media for personalized product recommendations, automated customer service, and efficient content moderation. Demand from e-commerce giants in China and the United States drives significant market expansion.
- Marketing Agencies:Agencies deploy cognitive media for generating ad copy, analyzing campaign performance, and creating hyper-personalized content for diverse client portfolios. These firms prioritize solutions that offer agility and scalability through cloud services.
- Media Publishers:Publishers use AI for content summarization, automated news generation, and audience engagement analysis to optimize distribution and readership.
- Research Firms:These firms leverage cognitive media for large-scale data analysis, trend identification, and automated report generation, enhancing their analytical capabilities.
- Educational Institutions:Institutions apply cognitive media for personalized learning content, intelligent tutoring systems, and automated assessment tools to improve student outcomes.
E-commerce Platforms command the largest share of cognitive media adoption. Marketing Agencies are demonstrating the steepest expansion trajectory.
Deployment:
Deployment models for cognitive media solutions define how the technology is delivered and accessed, influencing scalability, cost efficiency, and data security for end-users.
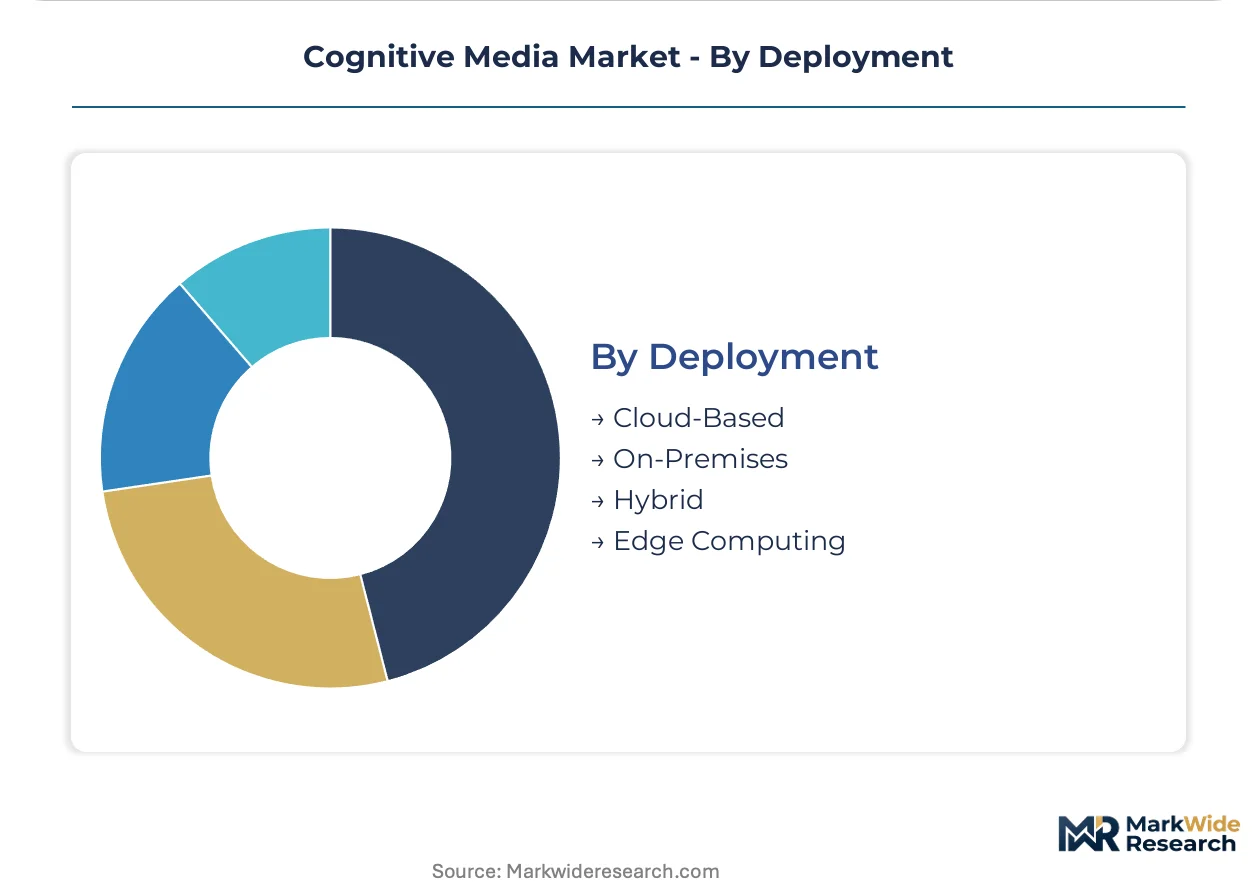
- Cloud-Based:These solutions are hosted and delivered over the internet by third-party providers, offering superior scalability, reduced infrastructure costs, and flexible access. Cloud-based deployment overwhelmingly dominates the market, particularly for e-commerce and marketing agencies.
- Edge Computing:This model processes data closer to the source of generation, reducing latency and bandwidth usage, which is crucial for real-time interactive media and autonomous systems. Investment in edge computing for cognitive media is growing in applications requiring immediate local processing.
- On-Premises:These solutions are installed and operated within an organization's own infrastructure, providing maximum control over data and security. Certain highly regulated industries or those with strict data sovereignty requirements still prefer on-premises deployments.
- Hybrid:This model combines elements of both cloud and on-premises deployments, allowing organizations to manage sensitive data locally while leveraging cloud resources for scalability.
The most prevalent deployment model is Cloud-Based. Edge Computing is rapidly gaining market traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cognitive media market exhibits a distinct production-vs-consumption divide, with advanced economies driving innovation and emerging markets becoming significant adoption hubs. Regulatory frameworks, such as the EU AI Act and China's algorithmic transparency rules, significantly influence market development and technology deployment across various regions. This interplay between technological advancement and policy shapes localized demand for cognitive media solutions.
China
Demand for personalized advertising and content creation solutions is immense, driven by China's vast digital consumer base. The Cyberspace Administration of China enforces strict regulations on algorithmic recommendations, requiring platforms to offer user control. Major technology hubs like Beijing and Shenzhen are centers for AI research and application development, benefiting from substantial government support.
United States
E-commerce platforms and marketing agencies in the United States lead investment in personalized advertising and content automation. State-level data privacy laws, such as the California Consumer Privacy Act, necessitate careful data handling and model transparency. Silicon Valley and other tech clusters such as Seattle and Boston concentrate expertise in deep learning and cloud-based cognitive services.
Germany
Enterprise demand for automated content moderation and ethical AI auditing services is growing in Germany, particularly in regulated industries. The EU AI Act strongly influences development standards for fairness and explainability across the European Union. Munich and Berlin are emerging as key innovation centers for AI applications, focusing on industrial and media sectors.
India
The Indian market shows strong growth in personalized advertising and content creation, fueled by a rapidly expanding internet user base. Government initiatives, including the National Strategy for Artificial Intelligence, promote AI adoption across various sectors. Technology hubs like Bengaluru and Hyderabad are experiencing significant activity in AI development and service delivery.
France
French marketing agencies and media publishers are increasingly adopting cognitive media for content creation and sentiment analysis. France actively contributes to the development of European AI regulations, emphasizing ethical AI and data protection. Paris and Grenoble host a vibrant ecosystem of AI startups and research institutions, fostering innovation in creative AI applications.
Cognitive Media Market Key Industry Players
Top-tier vendors anchor the cognitive media market, offering comprehensive cloud-based AI services, while specialized startups target niche applications with innovative point solutions. The market exhibits a tiered structure, with a few dominant technology giants providing foundational infrastructure and numerous smaller players building application-specific services. Strategic archetypes include cloud platform providers, AI-native solution developers, and media production software integrators. Dominant competitive moves include continuous service innovation and strategic partnerships to expand ecosystem reach.
Within the cloud platform tier, Microsoft Corporation and Google LLC exemplify the strategy of integrating cognitive services into broader enterprise cloud offerings. Adobe represents a specialist in creative workflows, embedding AI features directly into its media production software suite. These companies anchor market segments by providing scalable infrastructure and developer tools that enable a wide range of cognitive media applications across industries.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Amazon Web Services |
| IBM Corporation |
| Salesforce |
| Adobe |
| NVIDIA |
| Baidu |
| Accenture |
| Others |
Cost & Logistics Intelligence
The industrialization of creative AI, productized into accessible API-driven tools, simultaneously reshapes cost economics and concentrates the supply of foundational models among major cloud providers. This shift impacts both the cost structure for deploying cognitive media solutions and the competitive landscape for service delivery.
Pricing Analysis
Pricing pressure intensifies in the cognitive media market as the cost of foundational AI models becomes more standardized through cloud services. Subscription-based access to machine learning models and APIs dominates the pricing structure, favoring continuous service delivery over perpetual licenses. Price differentiation stems from customization levels and integration complexity into existing enterprise systems. High computational costs for training advanced models contribute to a premium for cutting-edge generative AI, yet consumption-based pricing models mitigate upfront expense. Marketing technology startups in North America are highly price-sensitive, while large e-commerce platforms prioritize performance and scalability.
Supply Chain Analysis
China's regulations on algorithmic recommendations and Europe's EU AI Act mandates are reshaping sourcing decisions for AI compliance tools. The supply of advanced cognitive media capabilities concentrates significantly in the United States and China, driven by major technology firms and extensive AI research. Key component dependencies include specialized GPU clusters for model training and vast, curated datasets for performance. Regulatory fragmentation across diverse jurisdictions creates a structural risk for vendors operating globally. Cloud-based API access forms the dominant distribution model for cognitive media services, reaching end-users globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cognitive media market is a cost-of-compliance story, with the EU AI Act creating a significant barrier-to-entry moat for technology providers demonstrating robust ethical AI and transparency. This regulatory environment necessitates strategic adjustments across all market participants.
For Market Incumbents:
Lock in existing enterprise clients by deepening cloud platform integrations and offering comprehensive compliance-as-a-service packages. Mitigate the threat of specialized AI startups by investing in explainable AI research and development, ensuring models meet emerging regulatory standards. Consolidate market share through strategic acquisitions of ethical AI auditing firms to bolster internal capabilities. Leverage scale to absorb rising computational costs and offer more competitive, consumption-based pricing models to retain large customers.
For New Entrants and Emerging Players:
Capture market share by targeting the underpenetrated field of hyper-local content automation, offering tailored solutions for specific geographic or niche vertical markets. Develop specialized synthetic data generation services to bypass restrictions on personal data usage, creating a new market for data-as-a-service providers. The marketing technology startup segment in Europe presents a penetrable opportunity for compliance-first AI solutions. A strong go-to-market angle involves demonstrating clear ROI through reduced compliance risk and enhanced data privacy.
For Investors and Strategic Acquirers:
Exit pathways concentrate in AI-native solution developers specializing in ethical AI auditing and synthetic data generation, offering long-term viability within a 5-10 year window. These firms provide critical tools for navigating the evolving regulatory landscape. The acquisition target archetype should focus on companies with proprietary explainable AI frameworks or robust data anonymization technologies. A key signal to watch as an inflection indicator is the widespread adoption of AI ethics certifications by major technology providers, signaling market maturation and regulatory enforcement.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate Ethical AI Auditing | Ensures compliance with frameworks like the EU AI Act, building trust with regulated industries. |
| Develop Synthetic Data Solutions | Bypasses privacy restrictions for model training, accelerating AI development for sensitive applications. |
| Expand Cloud-Based API Offerings | Lowers deployment barriers for smaller firms, driving broader market adoption of cognitive media. |
| Invest in Explainable AI Research | Addresses the "black-box" deficit, crucial for regulatory approval and risk-averse industry uptake. |
| Target Hyper-Local Content Automation | Unlocks new revenue streams by serving niche markets with tailored, AI-generated media. |
Research Approach
Regulatory filings, academic AI research papers, and industry association reports formed the secondary backbone, providing foundational market data and technological context. This was triangulated with primary interviews conducted with CTOs, marketing directors, compliance officers, and AI researchers across the cognitive media ecosystem. Both bottom-up and top-down approaches were utilized to validate market size estimates and growth projections.
A bottom-up analytical lens informed the granular segmentation across technology, application, end-user, deployment, and regional regulatory compliance levels over the projection horizon. Compound annual growth rates were derived from historical data analysis and future trend extrapolation, incorporating expert insights from primary interviews. Key industry-specific forecast inputs included AI model training costs and the anticipated spending on regulatory compliance solutions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rapid AI technological advancements, evolving global AI regulations, and geopolitical shifts impacting data flows. The forecasts reflect assumptions regarding market dynamics and technological progression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Photographic Services Market
Digital Media
Photography Services Market
Digital Media
Digital Distribution Market
Digital Media
Da Vinci Systems Market
Digital Media
Digital Video Advertising Market
Digital Media
Europe Inflight Entertainment and Connectivity Market
Digital Media
Europe Professional Audio Video (Proav) Market
Digital Media
Digital Content Creator Market
Digital Media
Middle East and Africa Animation Market
Digital Media
In Flight Entertainment Market
Digital Media
Professional Dubbing Services Market
Digital Media
Blockchain in Media and Entertainment Market
Digital Media
Digital Effects Services Market
Digital Media
China Webtoons Market
Digital Media
Europe Online Gambling Market
Digital Media
Middle East Gaming Market