
 Global Online Movie Ticketing Services Market | 2026-2036
Global Online Movie Ticketing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Movie Ticketing Services Market Foresight
North American theater chains are rebalancing their digital infrastructure investments toward proprietary mobile ecosystems. Fandango leverages studio partnerships to sustain premium content access. BookMyShow anchors South Asian market penetration through localized payment rails.
Online movie ticketing services encompass cloud-based reservation platforms that integrate real-time seat inventory APIs, dynamic pricing algorithms, and multi-channel payment gateways to facilitate advance purchases for theatrical exhibition. These systems reduce box office congestion, optimize auditorium utilization, and generate first-party audience data for distributors. Mobile apps command the dominant transaction volume due to push-notification marketing and biometric authentication integration. Digital wallets within the payment method segment capture expanding share as tokenization standards reduce checkout friction. Corporate customer types represent a developing margin pool through bulk entertainment procurement contracts.
The US Federal Trade Commission monitors subscription billing transparency in online ticketing, while India's Reserve Bank of India enforces two-factor authentication for digital wallet transactions affecting platform architecture. The EU Digital Services Act imposes algorithmic accountability requirements on recommendation engines that drive film discovery. Stakeholders must track evolving data localization mandates that determine where transaction records and user profiles must reside.
Market Dynamics
India's Reserve Bank of India mandates for UPI integration are forcing platform architecture redesigns across emerging market ticketing ecosystems, compressing checkout friction and accelerating mobile wallet dominance over card-based rails.
Growth Catalysts
- Biometric authentication protocols:Facial recognition and fingerprint verification reduce transaction abandonment rates at payment gateways. Theatrical exhibitors in Southeast Asia deploy these systems to capture mobile-first consumer segments.
- India's UPI mandate:The Reserve Bank of India's interoperability requirements for digital wallets create standardized payment rails that lower platform onboarding costs for regional multiplex chains.
- Dynamic pricing algorithms:Real-time demand-adjusted seat pricing optimizes auditorium utilization rates during off-peak exhibition windows. Cloud-based inventory APIs enable this capability at scale.
Market Restraints
- Data localization mandates:Transaction record storage requirements in multiple jurisdictions fragment platform infrastructure costs. Compliance with India's data residency rules duplicates server architecture investments.
- Legacy POS integration:Theater chains operating proprietary box office systems resist API standardization, creating interoperability friction for third-party ticketing platforms.
- Studio windowing restrictions:Exclusive theatrical release contracts limit advance booking windows, compressing the temporal value of reservation platform data capture.
Strategic Opportunities
- Corporate entertainment procurement:Bulk ticket purchasing contracts for enterprise employee benefit programs represent underpenetrated margin pools. Platforms integrating expense management APIs capture this demand.
- Southeast Asian multiplex digitization:Theater construction booms in Indonesia, Vietnam, and the Philippines create greenfield platform deployment opportunities without legacy system displacement costs.
- EU Digital Services Act compliance:Algorithmic accountability requirements for recommendation engines create competitive differentiation for platforms investing in transparent film discovery systems.
Industry Challenges
- Payment tokenization complexity:PCI-DSS compliance for card-not-present transactions requires specialized engineering talent scarce in emerging market development centers.
- Real-time inventory synchronization:Seat-level API accuracy demands sub-second latency tolerances that strain cloud infrastructure during blockbuster release spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Movie Ticketing Services Market |
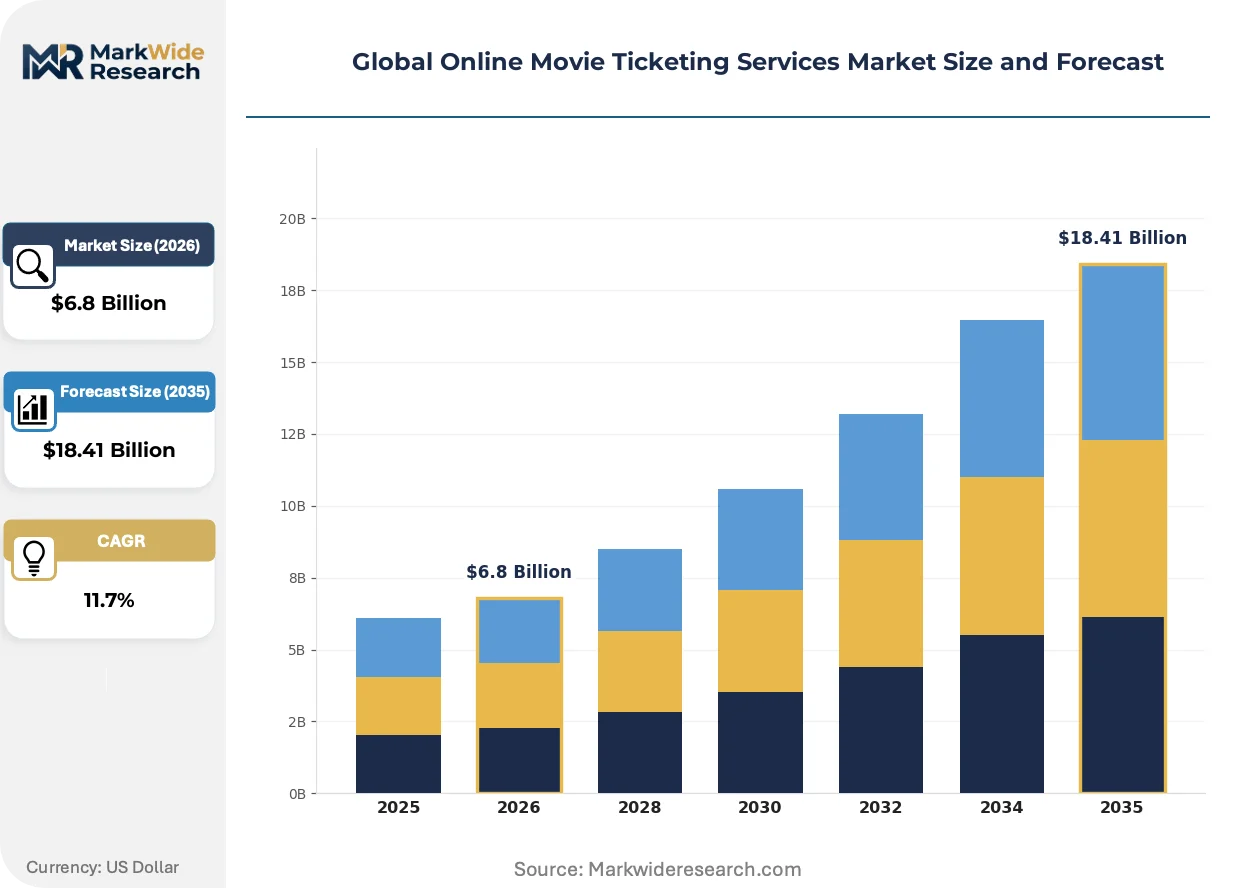
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $18.41 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Apps, Websites, Kiosks, Call Centers Customer Type: Individuals, Corporates, Groups, Families Payment Method: Credit/Debit Cards, Digital Wallets, Bank Transfers, Cash Event Type: Movies, Festivals, Premieres, Screenings |
| Companies Covered | Fandango, BookMyShow, Atom Tickets, Cinemark Holdings, PVR Limited, Cineplex, INOX Leisure Limited, VOX Cinemas, Movietickets.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Movie Ticketing Services Market Shifts & Advancements
Mobile-native ticketing architectures are displacing web-first platforms as push-notification marketing and biometric checkout reshape consumer expectations for theatrical discovery and purchase completion.
Embedded finance partnerships between ticketing platforms and digital wallet providers are expanding into subscription bundling models that combine theatrical access with streaming service credits. Southeast Asian consumers adopt these hybrid offerings faster than standalone ticketing apps. The structural consequence is platform revenue diversification beyond per-transaction fees into recurring subscription economics.
The EU Digital Services Act imposes algorithmic accountability requirements on film recommendation engines that drive theatrical discovery. Platforms must disclose ranking parameters and provide non-personalized alternatives. European exhibitors face compliance costs that favor larger platform operators with dedicated regulatory technology teams.
Corporate procurement departments now unbundle entertainment benefits from traditional insurance brokers, contracting directly with ticketing platforms for volume-based seat allocations. This channel shift bypasses legacy group sales intermediaries. The phenomenon concentrates in India's technology sector and North American professional services firms seeking employee retention tools.
Global Online Movie Ticketing Services Market Segmentation
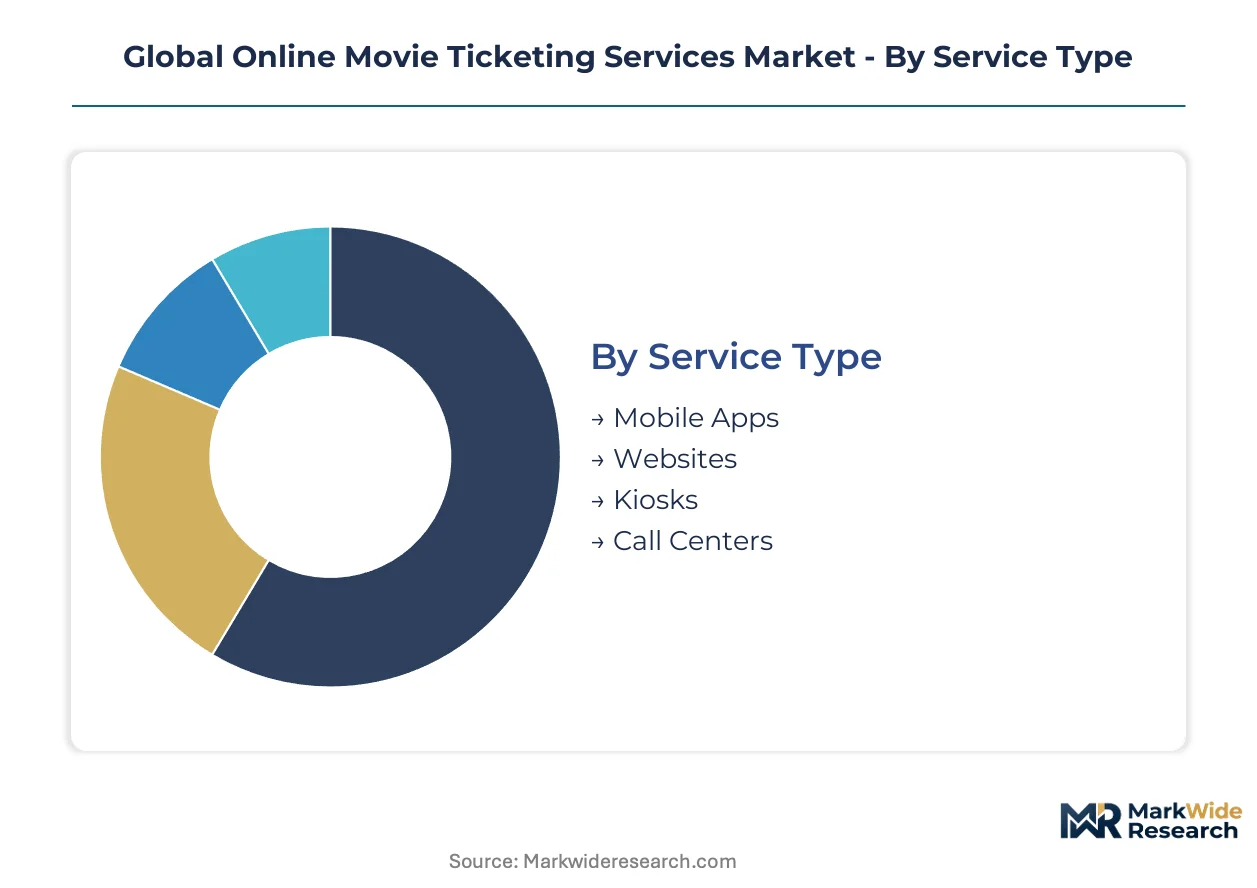
Online movie ticketing platforms architect their technology stacks and partnership strategies around distinct user behaviors and transaction modalities. Segmentation reveals where infrastructure investments concentrate and which revenue streams command platform development priorities.
Service Type:
Standardization dominates mobile and web channels, while kiosks and call centers retain customization for venue-specific requirements and accessibility mandates.
- Mobile Apps:Native iOS and Android applications integrate biometric authentication, push-notification marketing, and real-time seat inventory APIs. Demand concentrates in India and Southeast Asia where smartphone penetration outpaces desktop access, with UPI wallet integration driving transaction completion rates above card-based alternatives.
- Websites:Responsive web platforms serve corporate procurement workflows and cross-device cart persistence. North American theater chains favor proprietary web ecosystems that capture first-party audience data for studio partnership negotiations.
- Kiosks:On-premise touchscreen terminals reduce box office congestion at high-traffic multiplexes. Deployment concentrates in legacy theater chains with limited mobile adoption among older demographics.
- Call Centers:Voice-assisted booking retains relevance for accessibility compliance and group sales coordination. Volume is steepest in markets with limited digital literacy or strict corporate expense policy requirements.
Most installed capacity flows through Mobile Apps. Expansion is steepest in Kiosks as Southeast Asian multiplex construction digitizes without legacy system displacement.
Customer Type:
Margin structure varies sharply: individuals drive transaction volume, while corporates and groups yield contracted pricing with lower per-unit acquisition costs.
- Individuals:Single-ticket purchasers responding to dynamic pricing and personalized recommendation engines. This segment generates the highest per-transaction marketing spend and churns most frequently across competing platforms.
- Corporates:Enterprise entertainment procurement contracts for employee benefit programs. India's technology sector and North American professional services firms unbundle these benefits from traditional insurance brokers, contracting directly with platforms for volume-based seat allocations.
- Groups:Organized bookings for educational institutions, religious organizations, and community events. Demand clusters around festival programming and documentary screenings with limited theatrical windows.
- Families:Multi-ticket purchases with concession bundling and child-ticket pricing algorithms. Southeast Asian markets show fastest adoption of family subscription packages combining theatrical access with streaming credits.
Individual transactions dominate platform revenue. Corporate contracts are climbing the fastest as HR departments weaponize entertainment benefits for retention.
Payment Method:
Cost tier separates tokenized digital rails from high-friction cash handling, with regulatory mandates reshaping geographic deployment priorities.
- Credit/Debit Cards:PCI-DSS compliant card-not-present transactions with 3D Secure authentication. Remains dominant in North America and Europe despite checkout abandonment from multi-step verification flows.
- Digital Wallets:Tokenized payments through platform-integrated wallets and third-party providers. India's RBI-mandated UPI interoperability creates standardized rails that compress onboarding costs for regional multiplex chains.
- Bank Transfers:Direct account debits for high-value corporate bookings and subscription renewals. Concentrates in markets with mature real-time payment infrastructure and low card penetration.
- Cash:Pay-at-venue options for kiosk and call center transactions. Retains share in cash-preferred economies and among unbanked populations, though platform architecture treats this as a fulfillment cost center.
Digital Wallets capture the steepest share gains. Card volumes remain largest in absolute terms but face compression from biometric-enabled wallet adoption.
Event Type:
Application logic diverges between recurring theatrical releases and time-bound special events with constrained inventory and premium pricing elasticity.
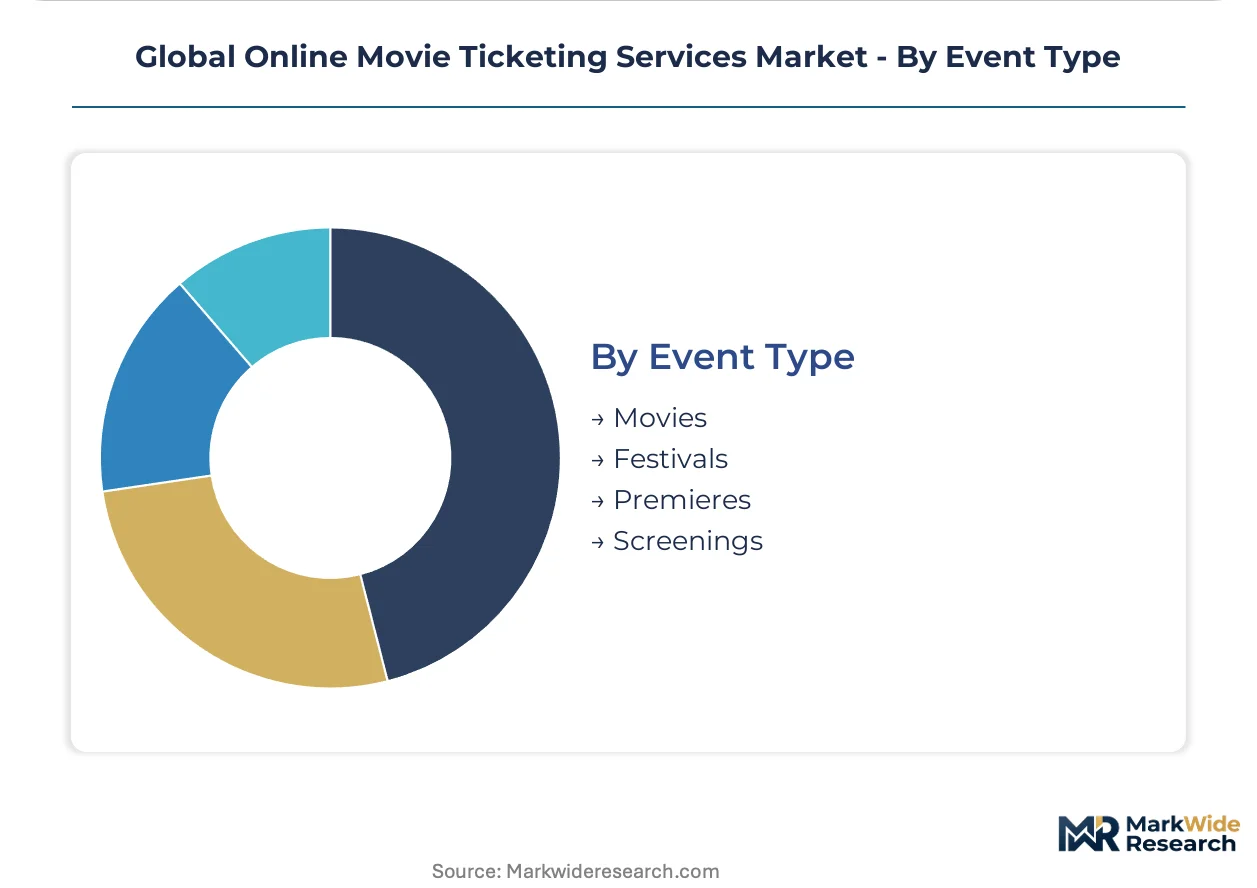
- Movies:Standard theatrical releases with advance booking windows tied to studio windowing contracts. Inventory APIs synchronize seat-level availability across exhibitor POS systems with sub-second latency requirements.
- Festivals:Curated programming with pass-based access and venue-hopping credentials. Demand surges concentrate in Berlin, Cannes, and Busan, with platform specialization around multi-venue credential management.
- Premieres:Limited-access screenings with invitation-only or premium-tier pricing. Studio partnerships determine platform access rights, creating competitive differentiation for Fandango and comparable tier-one operators.
- Screenings:One-time events including Q&A sessions, restoration premieres, and alternative content. Corporate sponsorship integration and nonprofit partnership tools distinguish specialized platform offerings.
Standard movie bookings generate the highest transaction frequency. Festival infrastructure is expanding most quickly as event programmers digitize credential distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform operators arbitrage compliance costs across jurisdictions, concentrating server infrastructure in data-residency-friendly locations while routing transactions through regulatory-light corridors. India's UPI mandate and the EU's algorithmic accountability requirements create divergent cost structures that reshape geographic deployment priorities.
United States
The FTC monitors subscription billing transparency, forcing disclosure architectures that increase platform compliance overhead. Fandango leverages studio partnerships to sustain premium content access rights. Los Angeles-based content negotiations determine windowing terms that compress advance booking data capture for reservation platforms.
India
The RBI's UPI interoperability requirements create standardized payment rails that lower onboarding costs for regional multiplex chains. Mumbai anchors South Asian market penetration through localized payment infrastructure. Bangalore's technology sector drives corporate entertainment procurement contracts that bypass traditional insurance brokers.
Germany
The EU Digital Services Act imposes algorithmic accountability requirements on film recommendation engines. Berlin-based exhibitors face compliance costs that favor larger platform operators with dedicated regulatory technology teams. Munich's corporate procurement departments unbundle entertainment benefits for direct platform contracting.
United Arab Emirates
VOX Cinemas operates across Gulf markets where cash-preferred economies retain kiosk and call center transaction volume. Dubai's entertainment infrastructure investments digitize without legacy system displacement costs. Abu Dhabi's regulatory framework permits data routing through regional cloud infrastructure.
Indonesia
Jakarta's theater construction boom creates greenfield platform deployment opportunities. The central bank's real-time payment infrastructure enables digital wallet adoption ahead of card penetration. Surabaya and Bandung multiplex expansions digitize seat inventory APIs without proprietary POS integration friction.
Global Online Movie Ticketing Services Market Competitive Landscape
United States platforms anchor one tier; Indian specialists hold emerging market penetration through payment rail localization. The vendor base stratifies across studio-affiliated aggregators, exhibitor-owned proprietary systems, and independent mobile-first challengers. Three archetypes dominate: content-access gatekeepers, payment-integrated regional platforms, and corporate procurement specialists. M&A activity concentrates on API standardization capabilities; geographic expansion targets Southeast Asian greenfield multiplex construction.
Within the content-access tier, Fandango exemplifies studio partnership leverage for premium window rights. BookMyShow anchors South Asian positioning through RBI-mandated UPI integration and localized payment infrastructure. Atom Tickets occupies the mobile-native challenger position, representing biometric authentication and push-notification marketing specialization. These three entities illustrate how competitive positioning diverges across regulatory environments and consumer payment preferences.
| Leading Market Players |
|---|
| Fandango |
| BookMyShow |
| Atom Tickets |
| Cinemark Holdings |
| PVR Limited |
| Cineplex |
| INOX Leisure Limited |
| VOX Cinemas |
| Movietickets.com |
| Others |
Supply & Pricing Matrix
Mobile-native ticketing architectures compress checkout friction while simultaneously redistributing platform infrastructure costs toward cloud-native serverless deployments. This technology transition concentrates supply-side power among hyperscale cloud providers in the United States, India, and Germany, forcing regional platform operators to arbitrage data residency compliance against compute economics.
Pricing Analysis
Per-transaction fees dominate platform revenue models, with premium-mid-economy pricing differentiation separating white-glove corporate procurement contracts from individual consumer purchases. Price differentiation rests on integration depth with exhibitor POS systems and UPI wallet tokenization certification levels. Cost compression in the individual consumer tier intensifies as biometric-enabled checkout reduces payment gateway abandonment. Corporate buyers exhibit lowest price sensitivity due to bulk entertainment benefit budgets, while cash-preferred kiosk users in Southeast Asian markets drive highest per-unit acquisition costs.
Supply Chain Analysis
Direct-to-exhibitor API channels handle real-time seat inventory synchronization, bypassing legacy distributor intermediaries. Cloud infrastructure concentrates in the United States, India, and Ireland to satisfy data localization mandates while optimizing latency for Southeast Asian multiplex construction. Platform operations draw from payment gateway providers, biometric authentication SDK vendors, and studio content licensing systems. Single-source vulnerability in UPI rail certification creates supply chain risk for Indian market entrants. Distribution runs through mobile app stores and white-label kiosk hardware partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
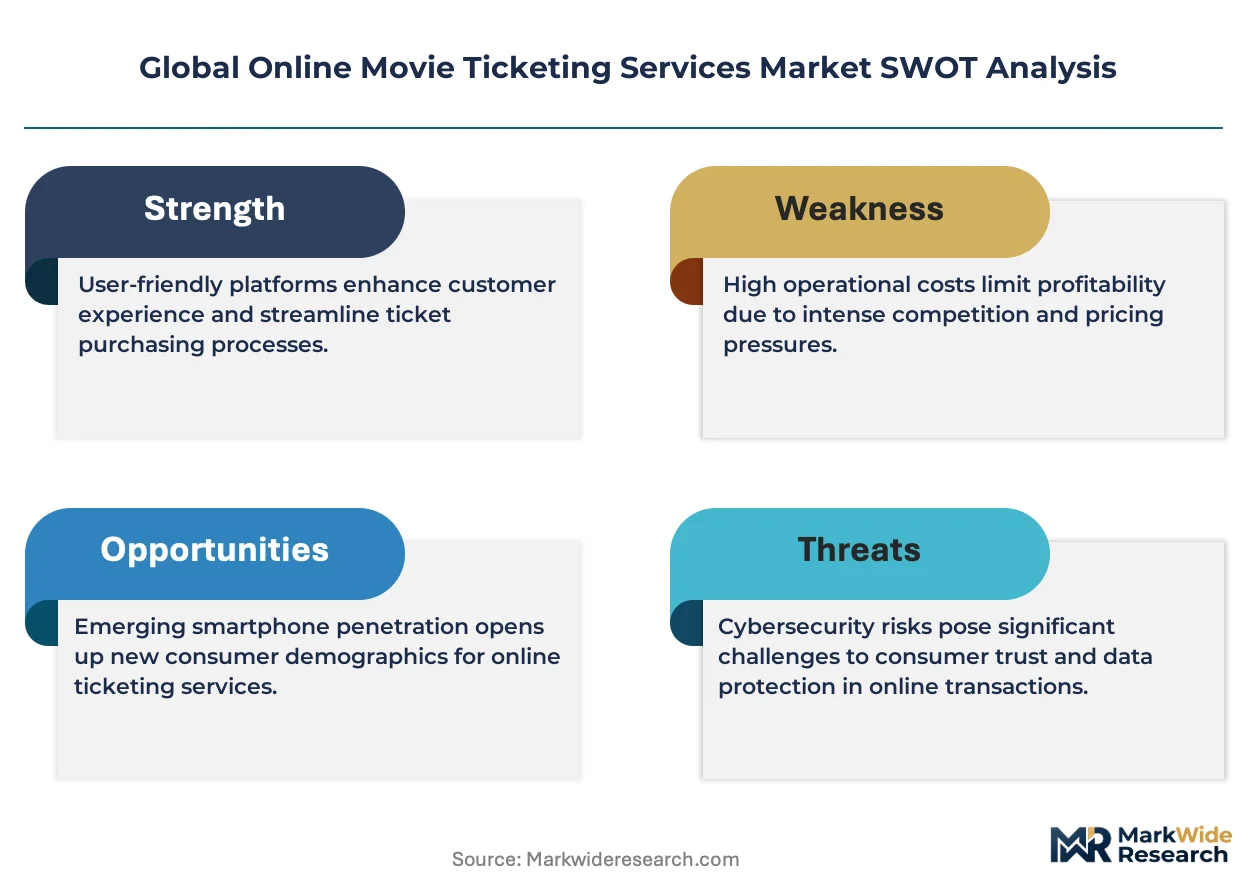
Margin expansion in online movie ticketing services is accelerating through embedded finance partnerships that bundle theatrical access with streaming credits, compressing customer acquisition costs while lifting lifetime value.
For Market Incumbents: Extend proprietary mobile ecosystem investments to capture first-party audience data for studio partnership negotiations. Deepen UPI wallet integration in India to defend against atomized regional challengers. Consolidate API standardization capabilities through targeted acquisitions of POS interoperability specialists. For New Entrants and Emerging Players: Begin with greenfield multiplex deployments in Indonesia and Vietnam where legacy system displacement costs are absent. Target corporate entertainment procurement contracts in Bangalore and Munich where HR departments unbundle benefits from traditional brokers. Deploy expense management API integration as the primary go-to-market wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among mobile-native challengers with biometric authentication specialization and Southeast Asian market presence. Long-term viability over the projection horizon favors platforms with regulatory technology teams capable of EU Digital Services Act compliance. Monitor RBI payment rail certification timelines as the critical inflection signal for Indian market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance Partnership | Bundles theatrical access with streaming credits, diversifying revenue beyond per-transaction fees. |
| Biometric Authentication Deployment | Reduces checkout abandonment rates at payment gateways through fingerprint and facial recognition protocols. |
| UPI Rail Certification Investment | Secures RBI-mandated interoperability for standardized payment rails across Indian multiplex chains. |
| Corporate Procurement API Integration | Captures volume-based seat allocations from technology sector HR departments unbundling entertainment benefits. |
| Regulatory Technology Team Buildout | Enables EU Digital Services Act compliance for algorithmic accountability on film recommendation engines. |
Research Methodology
Coverage spans North America, South Asia, Southeast Asia, and Western Europe, with primary inputs from each region triangulated against secondary validation. Platform engineering directors, multiplex chain procurement officers, payment gateway compliance leads, and studio distribution executives provided structured interviews. Secondary sources include SEC filings from listed theater chains, RBI circulars on UPI interoperability, EU Digital Services Act regulatory texts, and App Annie mobile transaction data. Bottom-up seat-level transaction modeling reconciles with top-down market sizing from cloud infrastructure spend disclosures.
Rate-of-change decomposition separates mobile app adoption velocity from kiosk deployment rates and corporate contract penetration. Segmentation dimensions include service type, customer archetype, payment method, and event category, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derive from logistic diffusion curves fitted to smartphone penetration data and multiplex construction pipelines. Industry-specific forecast inputs incorporate RBI payment rail expansion timelines and EU algorithmic accountability implementation schedules.
Several conditions sit outside the modeled scope, including studio windowing contract renegotiations, geopolitical disruptions to cloud infrastructure routing, and unanticipated biometric authentication protocol vulnerabilities. Forecasts reflect assumptions about UPI adoption curves and Southeast Asian multiplex construction completion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Video Player Market
Digital Media
North America Photographic Services Market
Digital Media
Animation and VFX Market
Digital Media
US Animation, Vfx and Post Production Market
Digital Media
North America Online Gambling Market
Digital Media
Sports Broadcasting Technology Market
Digital Media
Asia-Pacific Animation Market
Digital Media
Pro AV Market
Digital Media
Da Vinci Systems Market
Digital Media
Mexico Webtoons Market
Digital Media
Adult Entertainment Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Animation Services Market
Digital Media
LED Stadium Screens Market
Digital Media
Photographic Services Market
Digital Media
United States Online Gambling Market