
 Digital Audio Market | 2026-2036
Digital Audio Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Audio Market Insights
Solid-state storage is recalibrating product economics across digital audio hardware and software bundles. Apple Inc. leverages vertical integration across silicon, operating systems, and streaming platforms to control end-to-end audio delivery. Sony Corporation anchors its position through manufacturing scale in professional and consumer audio equipment. Adobe Inc. differentiates via creative software specialization that spans audio editing, video production, and cloud collaboration.
Digital audio encompasses electronically encoded sound signals processed, stored, and transmitted through analog-to-digital conversion at standard sampling rates such as 44.1 kHz or 48 kHz with 16-bit or 24-bit depth. Its primary commercial purpose spans music streaming, podcast distribution, audiobook delivery, broadcast production, and interactive gaming soundscapes. Streaming services occupy the largest value pool among product types, while podcasts represent the fastest-expanding segment driven by advertising monetization and creator tooling. Cloud-based deployment leads among deployment modes as latency and bandwidth constraints diminish, though hybrid architectures persist among enterprise studios requiring local processing for uncompressed workflows.
The FCC governs broadcast and internet transmission standards affecting streaming quality and accessibility in the United States, while the EU AI Act introduces transparency obligations for algorithmic content recommendation systems that curate audio feeds. ISO standards for audio file formats and metadata interoperability shape cross-platform compatibility and market access for hardware and software vendors. Stakeholders must monitor evolving royalty frameworks and platform governance rules that will determine creator economics and distributor margins.
Market Dynamics
Cloud-based audio production tools are collapsing the capital barrier between amateur creators and professional-grade output, redistributing value capture from hardware manufacturers toward platform operators and subscription software providers.
Growth Catalysts
- Smart speaker penetration:United States households now treat voice-activated devices as primary audio consumption endpoints, expanding addressable hours for streaming services and interactive audio content.
- FCC net neutrality framework:Stable transmission standards enable streaming infrastructure investments without bandwidth throttling risk, supporting quality-of-service guarantees for lossless audio delivery.
- Podcast advertising monetization:Dynamic ad insertion technology and programmatic buying platforms attract brand budgets previously allocated to broadcast radio, funding creator ecosystem expansion.
Market Restraints
- Royalty rate volatility:Copyright board determinations in major jurisdictions create unpredictable cost structures for streaming platforms negotiating mechanical and performance rights.
- Supply concentration in NAND flash:Solid-state storage component sourcing clusters among Korean and Taiwanese semiconductor fabricators, exposing hardware manufacturers to geographic supply disruption.
- Latency constraints in uncompressed workflows:Professional studios requiring real-time monitoring of multitrack recordings cannot fully migrate to cloud architectures, fragmenting vendor addressable markets.
Strategic Opportunities
- India creator economy expansion:Vernacular-language podcast production and regional music streaming remain underpenetrated relative to smartphone penetration, offering first-mover platform advantages.
- EU AI Act transparency mandates:Algorithmic recommendation disclosure requirements create compliance service opportunities for audio analytics vendors and metadata management specialists.
- Spatial audio convergence:Immersive format adoption across gaming, virtual reality, and automotive cabin systems opens cross-platform licensing revenue for content owners with multichannel master archives.
Industry Challenges
- Audio engineering talent scarcity:Educational pipeline gaps in immersive mixing and interactive audio implementation delay enterprise adoption of next-generation production formats.
- Legacy broadcast integration complexity:Radio stations and terrestrial networks face technical debt burdens when bridging IP-based streaming workflows with existing transmitter infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Audio Market |
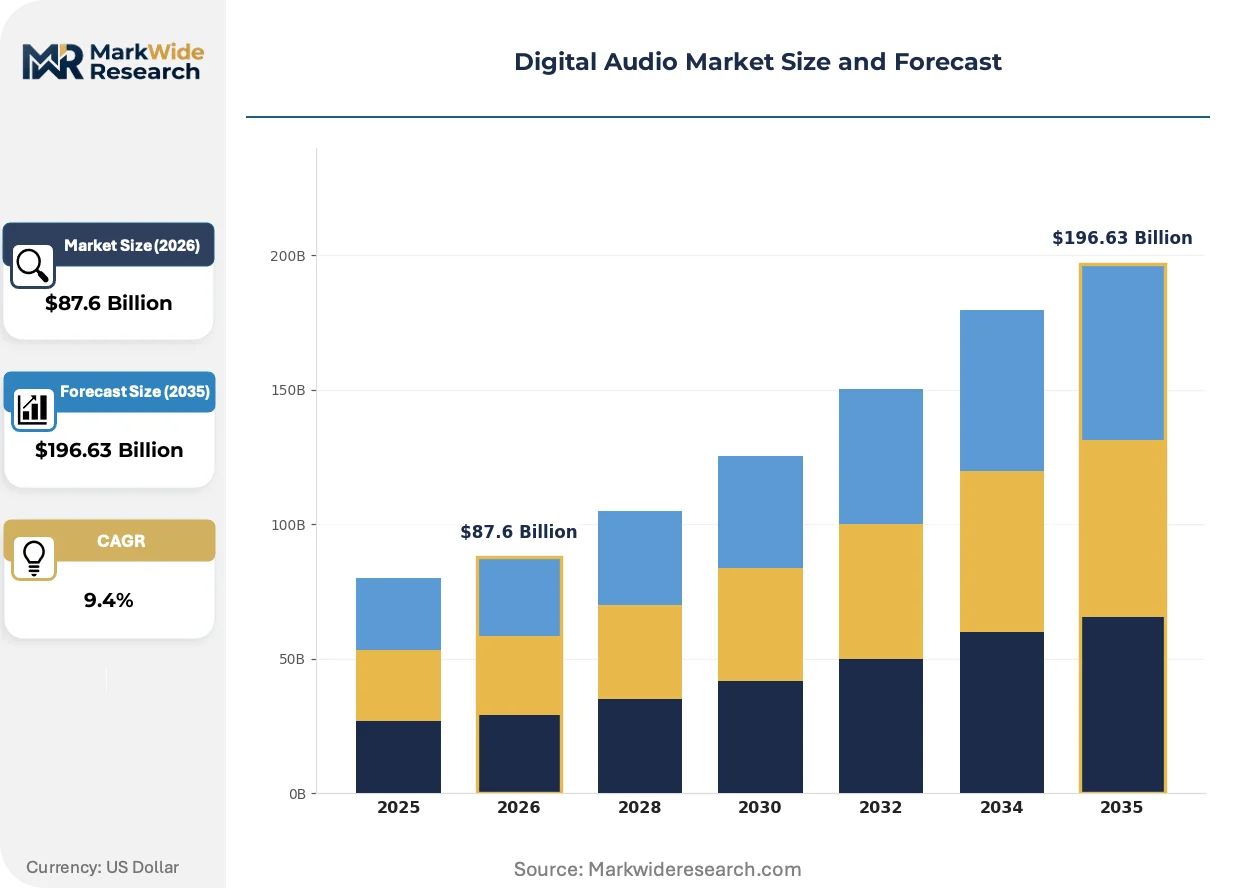
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Streaming Services, Digital Downloads, Audiobooks, Podcasts End User: Consumers, Businesses, Educational Institutions, Content Creators Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Applications Device Type: Smart Speakers, Mobile Devices, PCs, Gaming Consoles |
| Companies Covered | Apple Inc., Avid Technology, Inc., Yamaha Corporation, Adobe Inc., Steinberg Media Technologies GmbH, Native Instruments GmbH, Ableton AG, PreSonus Audio Electronics, Inc., Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Audio Market Trends and Innovations
Artificial intelligence is restructuring audio production workflows from capture through distribution, compressing production timelines while expanding personalization capabilities at consumer endpoints.
Generative audio synthesis is electrifying content creation economics. Machine learning models trained on licensed music corpora now enable rapid production of royalty-free background tracks and sound design elements. Advertising agencies and independent video producers adopt these tools to eliminate clearance delays and unpredictable licensing costs. The technology is electrifying competitive positioning among production music libraries, forcing incumbents to differentiate through human-curated editorial quality or exclusive artist relationships.
The EU AI Act introduces algorithmic transparency obligations affecting streaming platform operations. Content recommendation systems must disclose when automated curation influences user exposure to audio content, with audit trail requirements for training data provenance. Music streaming services operating across European Union member states face compliance architecture investments to document editorial versus algorithmic playlist construction, particularly impacting mood- and activity-based personalized feeds.
Creator procurement patterns favor subscription-based tool access over perpetual license ownership. Independent podcasters and musicians now evaluate software vendors primarily on cloud collaboration features and integrated distribution pipelines rather than discrete feature comparisons. This behavioral shift concentrates purchasing authority among platform operators bundling production, hosting, and monetization functions, visible most acutely in North American and Western European markets where solo creator entrepreneurship dominates new entrant growth.
Digital Audio Market Segmentation
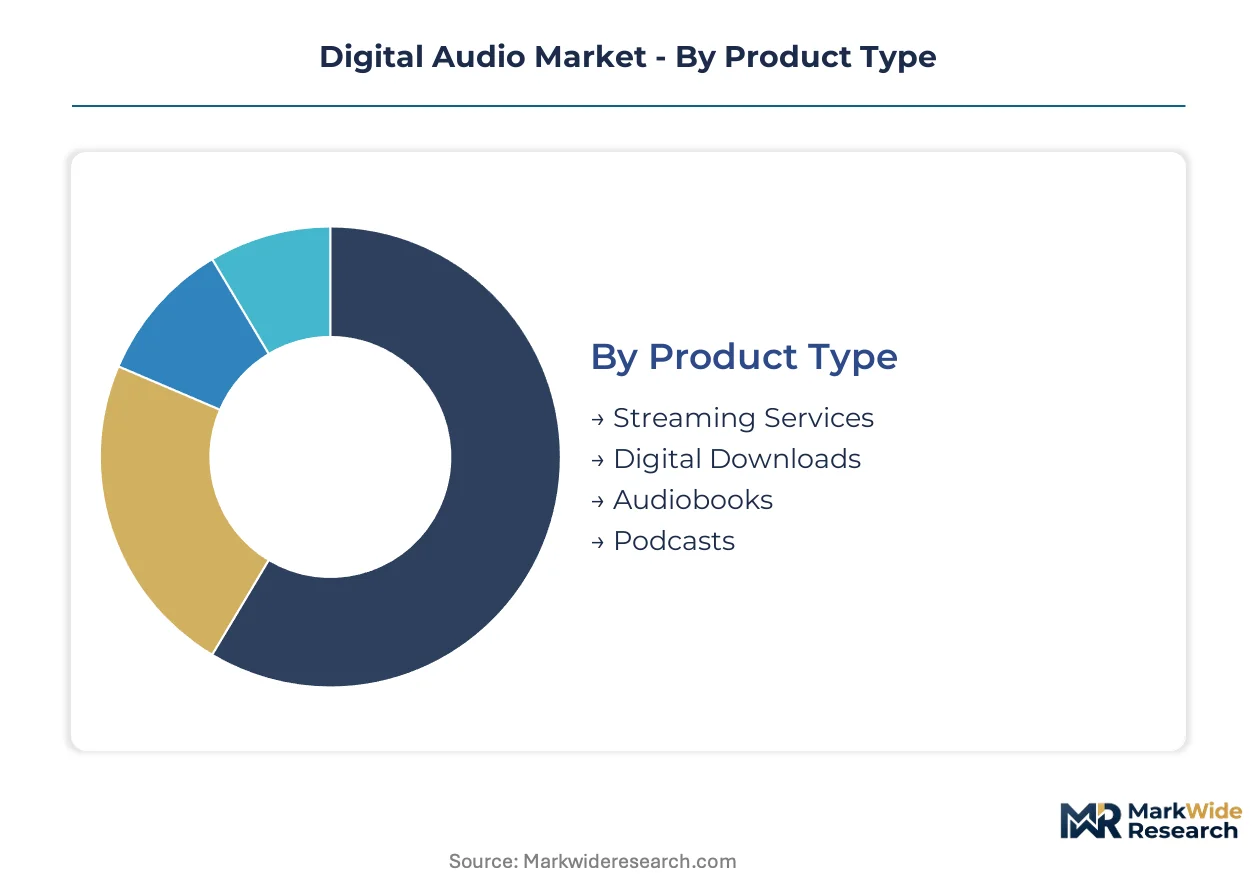
Digital audio market segmentation reveals how consumption patterns, infrastructure requirements, and creator economics fragment across distinct value pools. Each dimension exposes different margin structures and vendor addressability.
Product Type:
Upgrade cycles vary dramatically across product categories, with streaming subscriptions renewing monthly while hardware-dependent formats trigger replacement decisions measured in years.
- Streaming Services:Cloud-delivered audio catalogs accessed through subscription or ad-supported models. Demand clusters in the United States where smart speaker density and mobile data affordability sustain the highest per-user revenue figures. FCC net neutrality enforcement stabilizes bandwidth economics for lossless tier delivery.
- Podcasts:Episodic spoken-word content distributed through RSS feeds or platform-native applications. Advertising monetization via dynamic insertion technology attracts brand budgets migrating from broadcast radio, with creator tooling lowering production barriers for independent publishers.
- Audiobooks:Narrated long-form literature delivered through dedicated platforms or bundled subscriptions. Library lending integration and commute-time consumption patterns shape regional penetration variance.
- Digital Downloads:Permanent file ownership models declining as streaming substitution accelerates. Niche persistence among audiophile collectors and offline-accessibility requirements in bandwidth-constrained geographies.
Volume placements concentrate in Streaming Services; the faster expansion belongs to Podcasts.
End User:
Customer procurement authority shifts between IT departments, individual creators, and household decision-makers depending on use case complexity.
- Consumers:Individual listeners accessing audio through personal subscriptions or free-tier advertising. Smartphone ownership and commute patterns determine addressable hours and platform selection criteria.
- Content Creators:Podcasters, musicians, and producers requiring production, distribution, and monetization tooling. Cloud collaboration features and integrated analytics now dominate vendor evaluation over discrete feature comparisons.
- Businesses:Corporate licensing for background music, internal communications, and customer-facing audio environments. Compliance requirements around public performance rights create procurement friction.
- Educational Institutions:Universities and K-12 systems deploying audiobook libraries and lecture-capture systems. Accessibility mandates and language-learning applications sustain institutional budget allocation.
Revenue concentration sits with Consumers; Content Creators are climbing the fastest as solo entrepreneurship expands.
Deployment:
Latency tolerance and data sovereignty requirements partition workloads between edge, cloud, and intermediate architectures.
- Cloud-Based:Fully remote processing and storage eliminating local infrastructure requirements. Professional studios requiring real-time multitrack monitoring retain hybrid configurations despite bandwidth improvements.
- Mobile Applications:Native smartphone and tablet clients optimized for offline caching and cellular data efficiency. Download management and adaptive bitrate streaming differentiate platform technical performance.
- Hybrid:Local processing for uncompressed source material with cloud rendering and distribution for finished content. Enterprise studios balancing collaboration requirements against latency constraints.
- On-Premises:Dedicated hardware installations for broadcast facilities and high-security environments. Legacy integration complexity with existing transmitter infrastructure sustains deployment despite cloud migration pressure.
Volume placements concentrate in Cloud-Based; Mobile Applications are gaining share fastest through emerging market smartphone penetration.
Device Type:
Replacement cycles and average selling price dispersion create tiered margin exposure across hardware categories.
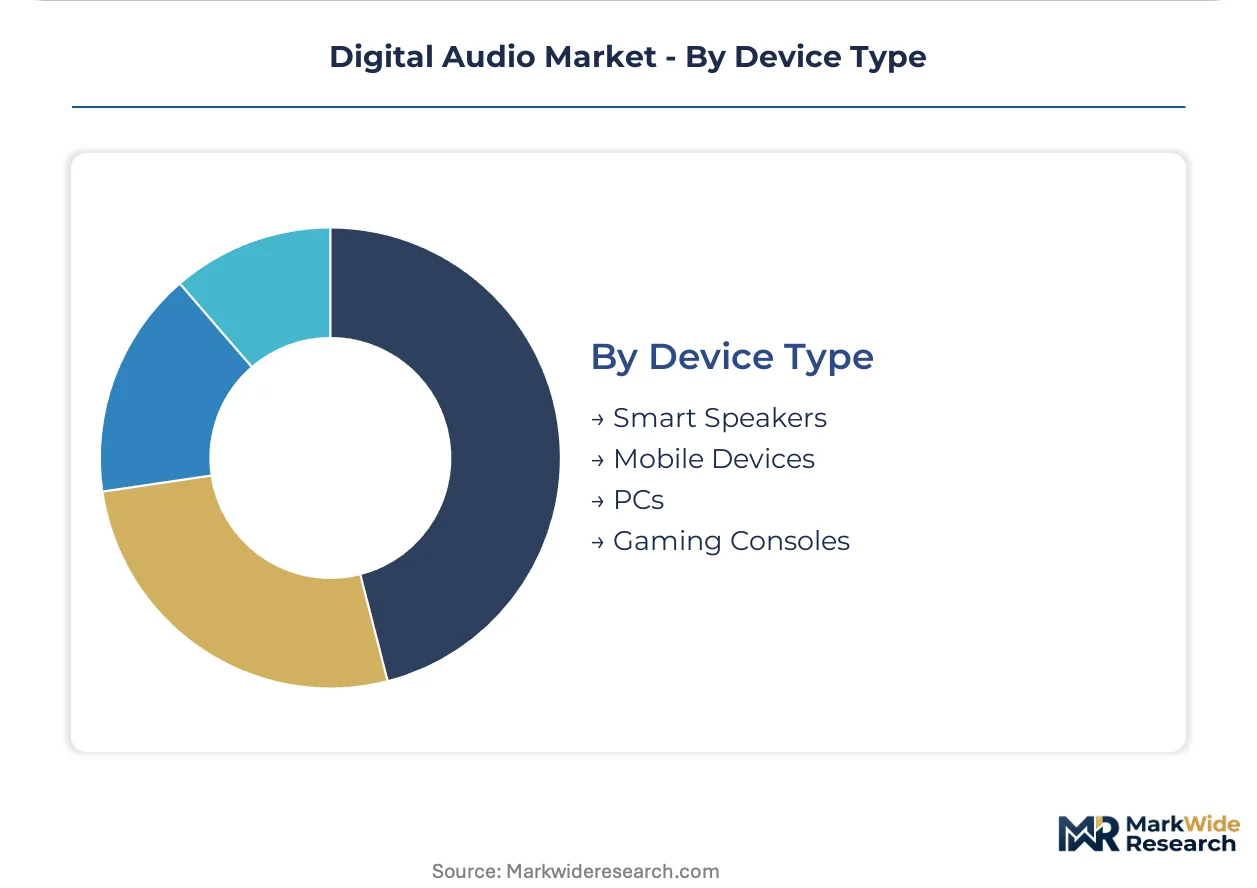
- Mobile Devices:Smartphones and tablets serving as primary audio consumption endpoints. OEM pre-installation agreements and operating system integration determine platform distribution leverage.
- Smart Speakers:Voice-activated home devices treating audio as the dominant interaction modality. United States household penetration leads globally, expanding addressable hours for streaming services and interactive content.
- PCs:Desktop and laptop workstations for production workflows and lossless playback. Creator tooling and gaming audio applications sustain relevance against mobile substitution.
- Gaming Consoles:Integrated entertainment systems with spatial audio and voice chat requirements. In-game music licensing and streaming app integration expand use cases beyond core gaming.
Volume placements concentrate in Mobile Devices; Smart Speakers are expanding most quickly through residential ecosystem lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Bangalore concentrate contract manufacturing for audio hardware, while tax incentives in Ireland and Singapore attract streaming platform regional headquarters.
United States
Smart speaker penetration in American households exceeds any other major economy, creating dense addressable hours for streaming services and interactive audio content. The FCC's net neutrality framework stabilizes bandwidth economics for lossless audio delivery without throttling risk. Los Angeles and Nashville anchor professional music production clusters where cloud-based collaboration tools displace legacy studio infrastructure.
China
Domestic music streaming subscriber bases rival any single-country market globally, with short-form audio integration driving platform engagement metrics. MIIT standards for audio codec interoperability shape hardware-software bundle requirements for consumer electronics exports. Shenzhen's special economic zone concentrates original design manufacturing for smart speakers and wireless earbuds supplying global brands.
Germany
Professional audio equipment demand clusters around broadcast production and enterprise conferencing applications, with engineering-intensive specifications dominating procurement criteria. The EU AI Act's transparency mandates for algorithmic recommendation systems impose compliance architecture investments on streaming services operating across member states. Berlin's startup ecosystem incubates creator tooling ventures targeting podcast production and electronic music workflows.
India
Vernacular-language podcast production and regional music streaming remain underpenetrated relative to smartphone penetration, offering first-mover platform advantages in creator economy tooling. TRAI regulations on over-the-top content delivery shape data pricing and platform accessibility for audio streaming. Bengaluru's technology corridor hosts engineering centers for global audio software vendors and domestic streaming platform operators.
Japan
High-resolution audio format adoption persists among consumer segments with legacy loyalty to physical media quality signifiers, sustaining premium hardware replacement cycles. METI initiatives for content export promotion support domestic audio IP licensing into gaming and animation verticals. Tokyo's Shibuya and Shinjuku districts concentrate voice acting studios and immersive audio production facilities serving regional entertainment markets.
Digital Audio Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with streaming platforms consolidating around subscription scale while production tool vendors fragment across specialization niches. The vendor base organizes into three strategic archetypes: vertically integrated technology conglomerates controlling silicon-to-consumer delivery, creative software specialists bundling audio with adjacent production workflows, and professional hardware manufacturers anchoring studio infrastructure procurement. Competitive moves concentrate on M&A for creator platform consolidation and strategic partnerships for spatial audio format licensing.
Within the creative software archetype, Adobe Inc. and Avid Technology, Inc. exemplify vendors bundling audio editing with video production and cloud collaboration capabilities. Apple Inc. represents the vertically integrated model, controlling silicon design, operating systems, and streaming platform distribution. Sony Corporation and Yamaha Corporation anchor the professional hardware tier, with manufacturing scale spanning consumer electronics and studio-grade equipment categories.
| Leading Market Players |
|---|
| Apple Inc. |
| Avid Technology, Inc. |
| Yamaha Corporation |
| Adobe Inc. |
| Steinberg Media Technologies GmbH |
| Native Instruments GmbH |
| Ableton AG |
| PreSonus Audio Electronics, Inc. |
| Sony Corporation |
| Others |
Pricing and Supply Chain Analysis
EU AI Act transparency mandates for algorithmic content recommendation systems gate qualified supply for streaming platform operators and tiered access to premium-tier pricing for compliance-ready vendors. Hardware manufacturers face parallel sustainability certification requirements for solid-state storage components that stratify supplier qualification and contract eligibility.
Pricing Analysis
Lead-time-driven pricing separates spot inventory discounts from premium rates for expedited solid-state storage procurement. Three-tier pricing structure across premium, standard, and economy levels reflects NAND flash quality grades and ISO-certified manufacturing origins. Price differentiation stems from certification level and volume scale commitments. Cost compression in economy-tier hardware intensifies because Korean and Taiwanese fabricators consolidate supply. Independent podcasters exhibit highest price sensitivity; enterprise studios with uncompressed workflow requirements show least sensitivity due to latency tolerance thresholds.
Supply Chain Analysis
NAND flash supply rests on Korean and Taiwanese semiconductor fabricators with secondary concentration in Japanese specialty chemical producers for photoresist and etching materials. Solid-state storage hardware draws from Chinese contract manufacturing clusters and Vietnamese assembly facilities. Single-source vulnerability in advanced node fabrication exposes hardware manufacturers to geographic disruption. Distribution runs through OEM direct procurement for tier-one streaming platforms and specialized audio retailers for professional studio equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based audio production tools are displacing legacy studio infrastructure, compressing capital barriers and redistributing value capture from hardware manufacturers toward platform operators.
For Market Incumbents: To counter generative audio synthesis entrants, Adobe Inc. and Avid Technology should deepen backward integration into cloud rendering infrastructure and acquire creator platform specialists with integrated distribution pipelines. Certification investment in EU AI Act compliance architecture preserves European market access against algorithmic transparency enforcement. For New Entrants and Emerging Players: Vernacular-language podcast tooling in India offers lowest competitive density relative to smartphone penetration growth. Target regional music streaming production workflows in Bengaluru and Mumbai technology corridors with mobile-first collaboration features and integrated monetization analytics as the primary go-to-market angle. For Investors and Strategic Acquirers: FCC net neutrality framework stability is the leading indicator that streaming infrastructure economics will support platform margin expansion across the analysis window. Acquisition candidates include mid-cap creator tooling vendors with cloud-native architectures and established distribution partnerships with major streaming platforms. Spatial audio format licensing consolidation signals inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundling production, hosting, and monetization concentrates purchasing authority among North American solo creators. |
| Acquisition of Specialist Firm | Creator platform consolidation eliminates redundant distribution pipelines and captures advertising revenue share. |
| Geographic Expansion | India vernacular podcast tooling addresses underpenetrated supply relative to smartphone ownership density. |
| Strategic Partnership | Spatial audio licensing agreements with gaming and automotive OEMs unlock cross-platform royalty streams. |
| Product Launch | EU AI Act-compliant recommendation transparency tools capture compliance service revenue from streaming operators. |
Research Methodology
SEC filings, FCC regulatory dockets, and EU AI Act implementation guidance formed the secondary backbone, supplemented by customs records for NAND flash trade flows and streaming platform subscriber disclosures. Primary interviews with audio engineering directors, podcast production leads, platform procurement officers, and semiconductor supply chain managers combined with secondary validation through bottom-up and top-down triangulation.
Bottom-up modeling segmented volume and value across streaming services, podcasts, audiobooks, and digital downloads by deployment mode, end user, and device type, with spatial audio format adoption tracked as a technology-crossing dimension. CAGRs were derived from installed base growth rates and average revenue per user trajectories over the projection horizon, incorporating smart speaker penetration curves and cloud collaboration feature adoption as industry-specific inputs.
Inputs from platform operator financial disclosures and semiconductor supply chain databases were available through the study window; gaps in independent creator revenue reporting introduce uncertainty bands around podcast monetization forecasts. Forecasts reflect documented assumptions regarding bandwidth infrastructure investment continuity and copyright board royalty determinations. Regulatory enforcement timing for algorithmic transparency mandates and NAND flash supply concentration shifts warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Radio and Audio Media
Audio Mixing Console Market
Radio and Audio Media
Latin America Soundbar Market
Radio and Audio Media
Global 3D Audio Market
Radio and Audio Media
Microphone Market
Radio and Audio Media
FM Transmitters Market
Radio and Audio Media
Audiobooks Market
Radio and Audio Media
Global Professional Audio Market
Radio and Audio Media
Podcast Advertising Market
Radio and Audio Media
Radio Advertising Market
Radio and Audio Media
Voice Over New Radio Market
Radio and Audio Media
Podcast Hosting Services Market
Radio and Audio Media
Podcasting Market
Radio and Audio Media
Internet Radio Market
Radio and Audio Media
Podcast Market
Radio and Audio Media
Traditional Radio Advertising Market