
 Photographic Services Market | 2026-2036
Photographic Services Market Size, Share, and Industry Trends Forecast 2026-2036
Photographic Services Market Analytics
Corporate buyer concentration is pivoting as mid-market brands fragment their photography spend across on-demand platforms rather than locking into single-studio retainers. Getty Images leverages its archival depth to sustain enterprise licensing dominance. Snappr competes through algorithmic matching that anchors gig-economy supply to same-day commercial shoots. Shutterfly Inc. differentiates by controlling end-to-end production from capture to personalized print fulfillment.
Photographic services encompass commissioned image capture, post-production processing, and deliverable distribution across digital and physical formats, typically employing full-frame sensors with 35-50 megapixel resolution and RAW workflows to ensure latitude for color grading and retouching. The primary commercial purpose centers on brand asset creation, personal milestone documentation, and editorial content generation. Wedding services occupy the largest revenue pool within service type segmentation due to perennial demand and premium pricing tolerance, while commercial photography represents the fastest-expanding segment as direct-to-consumer brands escalate visual content production. Digital delivery mode leads volume metrics, though photo book and premium print formats retain disproportionate margin contribution.
ISO certification requirements for color management and the FTC's truth-in-advertising standards shape service-level compliance for commercial photography deployed in consumer marketing. The EU's GDPR imposes consent protocols on portrait and event photography involving identifiable subjects, particularly affecting cross-border assignment workflows. Stakeholders must monitor how generative AI training data licensing disputes reshape copyright frameworks and client contract structures.
Market Dynamics
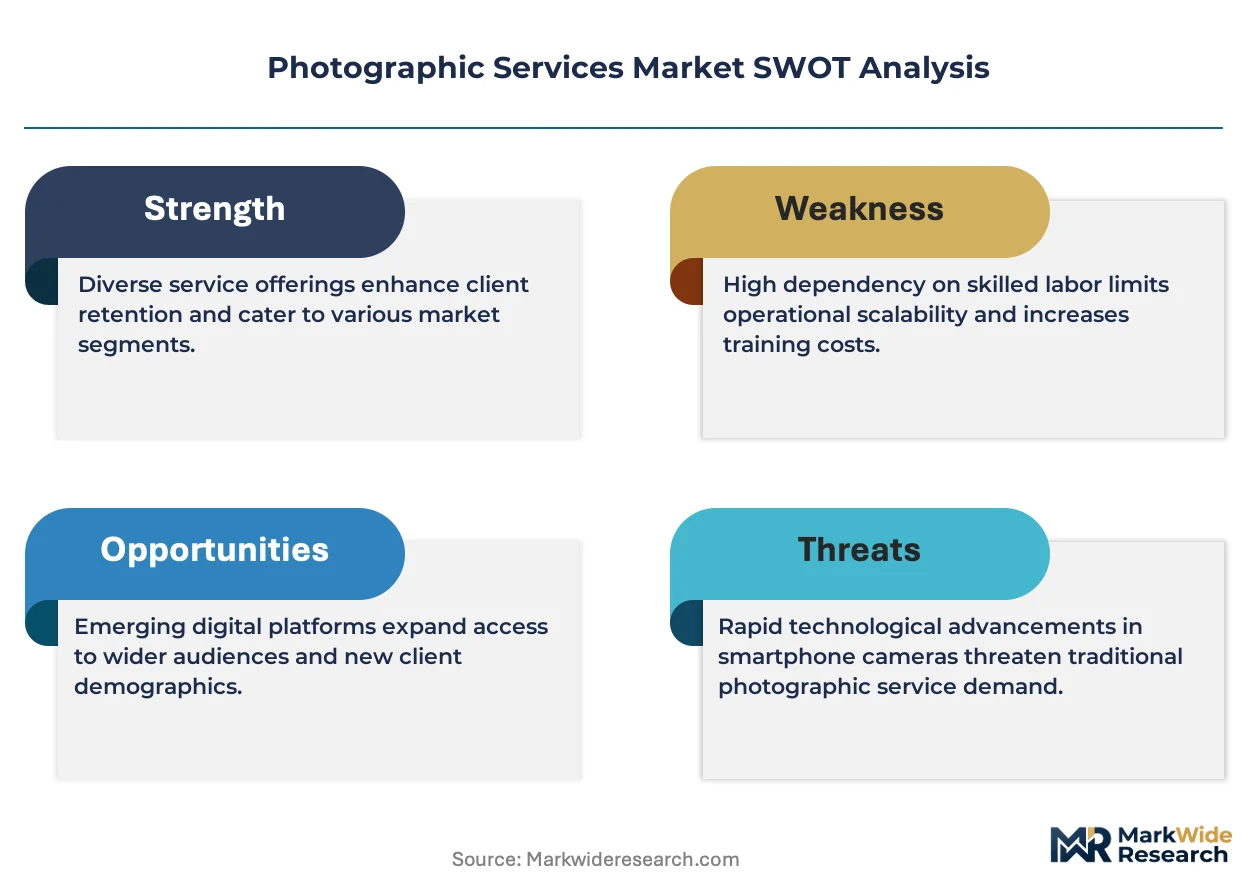
AI-powered editing platforms are compressing post-production timelines from days to hours, forcing traditional studios to restructure pricing models and talent deployment around automated workflows rather than manual retouching labor.
Growth Catalysts
- FTC Truth-in-Advertising Standards:Commercial photography demand rises as direct-to-consumer brands require compliant visual assets for digital campaigns, mandating accurate product representation across e-commerce channels.
- RAW Workflow Standardization:Full-frame sensor adoption at 35-50 megapixel resolution enables extensive color grading latitude, allowing photographers to deliver single-capture assets for multi-platform distribution.
- Los Angeles Studio Cluster:Concentrated post-production talent pools and equipment rental infrastructure reduce assignment mobilization costs for entertainment and brand clients.
Market Restraints
- GDPR Consent Protocols:Cross-border event photography faces operational friction as EU data protection rules impose documentation requirements on portrait shoots involving identifiable subjects.
- Specialized Retoucher Supply:Advanced color grading and compositing expertise concentrates in premium metropolitan markets, creating talent access bottlenecks for mid-market service providers.
- Generative AI Substitution:Synthetic image platforms threaten commodity product photography segments as brands test algorithmic visual generation for basic catalog assets.
Strategic Opportunities
- India Event Documentation:Rising disposable incomes in tier-2 cities drive premium wedding photography penetration where professional capture remains underutilized relative to Western markets.
- ISO Color Management Certification:Studios achieving standardized color accuracy credentials can command premium positioning in commercial brand procurement evaluations.
- Drone Capture + 3D Photogrammetry:Converging aerial platforms and spatial mapping software open real estate and architectural visualization contracts previously requiring separate vendor relationships.
Industry Challenges
- AI Training Data Licensing:Copyright frameworks remain unsettled regarding photographer portfolio use in generative model development, complicating client contract indemnification clauses.
- Legacy Print Fulfillment Integration:Studios maintaining darkroom or premium press capabilities face technical debt as digital-first workflows dominate deliverable specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photographic Services Market |
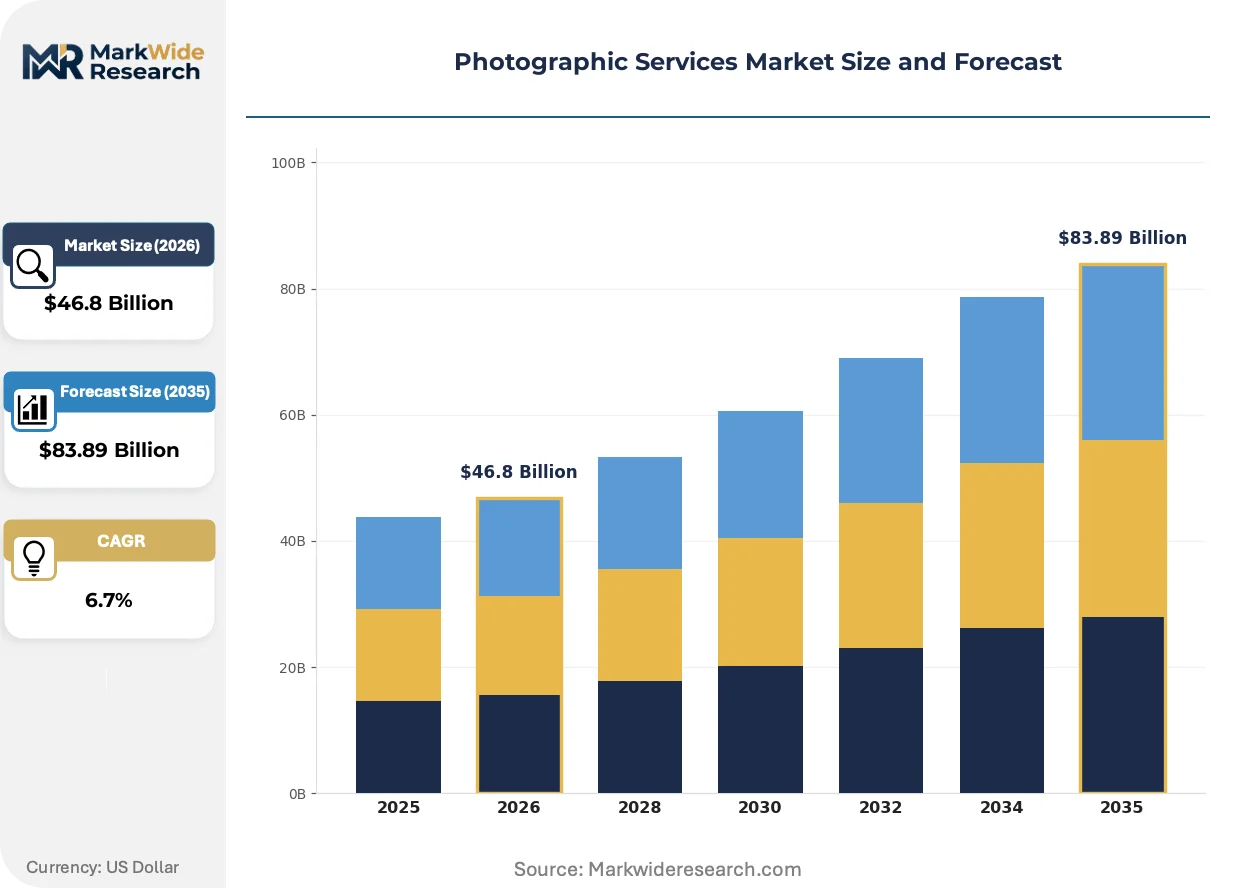
| Market Size in 2026 | $46.8 Billion |
| Market Size in 2035 | $83.89 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wedding, Portrait, Commercial, Event Delivery Mode: Digital, Print, Online Gallery, Photo Book Client Type: Individuals, Businesses, Non-profits, Agencies Equipment Type: DSLR, Mirrorless, Film, Studio Lighting |
| Companies Covered | Studio Alice Co Ltd., Cherry Hill Programs Inc., Getty Images, Visual China Group Co., Pic Solve, Shutterfly Inc., Mom365, Snappr, Lifetouch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photographic Services Market Evolving Landscape
Computational photography and cloud-based collaboration tools are dissolving traditional boundaries between capture, processing, and delivery phases, enabling real-time client feedback loops that reshape project economics.
Cloud-native post-production platforms are unifying RAW processing, collaborative annotation, and final asset distribution within single browser-based environments. Mid-market brand marketing teams adopt these tools to eliminate file transfer bottlenecks and version control errors. The technology is unifying previously fragmented vendor relationships into integrated platform subscriptions that bundle editing software with delivery infrastructure.
EU GDPR enforcement actions against event photographers operating without documented consent protocols have intensified compliance investments across cross-border assignment workflows. The regulation mandates explicit subject authorization for identifiable portrait use in commercial contexts. Wedding and corporate event segments in Germany and France now embed consent capture into pre-shoot logistics, with some studios deploying mobile apps for real-time documentation.
Brand procurement departments are fragmenting annual photography budgets across on-demand platform marketplaces rather than locking into single-studio retainers. Same-day booking algorithms displace traditional agency relationships for routine product and lifestyle shoots. Direct-to-consumer apparel brands in New York and Los Angeles demonstrate the most aggressive adoption, treating visual content as continuously refreshed inventory rather than campaign-level investment.
Photographic Services Market Segmentation
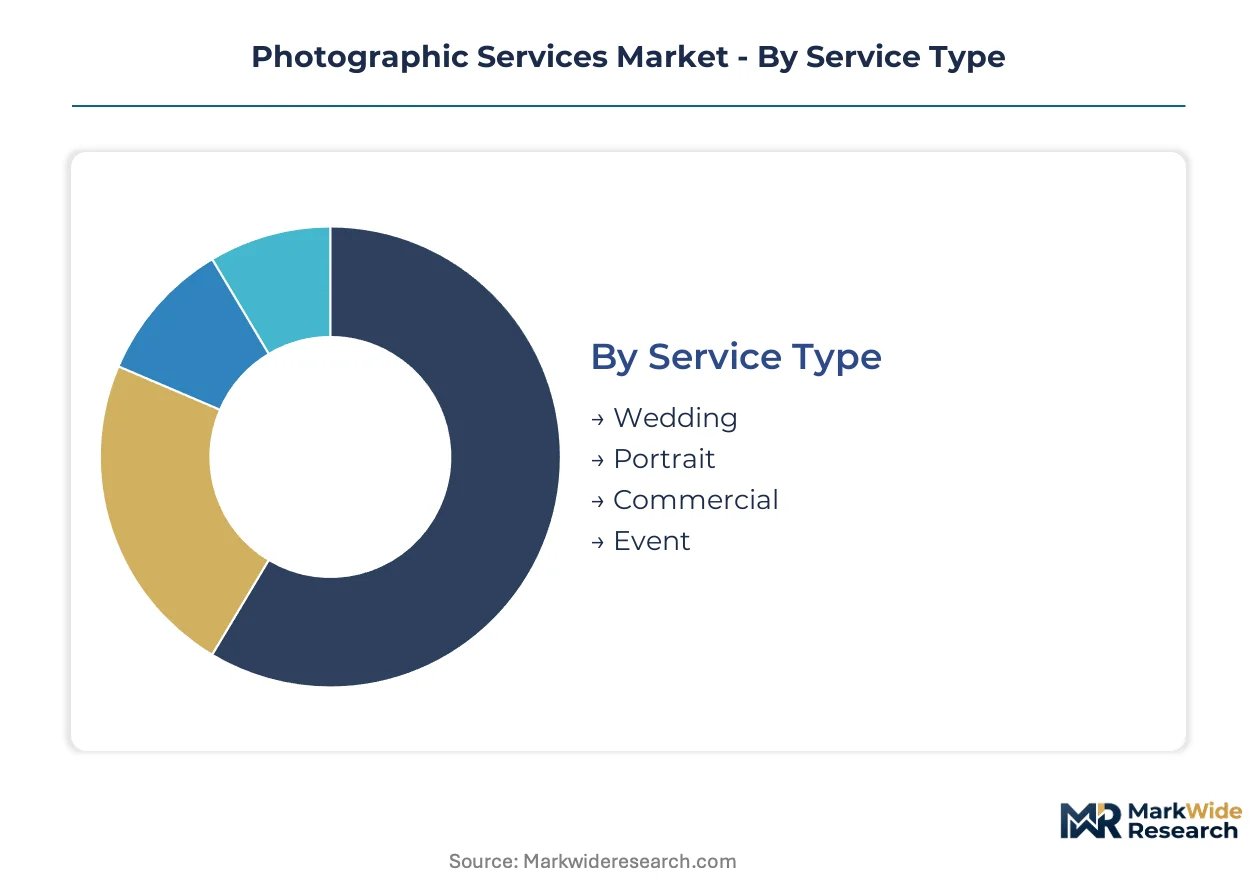
Photographic services fragment across four distinct dimensions that determine pricing architecture, talent specialization, and technology deployment. Each segmentation axis reveals divergent margin profiles and competitive intensity patterns.
Service Type:
Replacement cycles in commercial photography accelerate as brand clients refresh visual assets quarterly rather than annually, compressing project timelines and retainer structures.
- Wedding:Multi-day coverage packages combine ceremony documentation with pre-wedding shoots and album production, commanding premium pricing tolerance in tier-1 metropolitan markets. Revenue concentrates in Los Angeles and New York studio clusters where destination wedding demand intersects with high-net-worth clientele.
- Commercial:Brand asset creation for e-commerce and digital campaigns employs full-frame RAW workflows at 35-50 megapixel resolution to enable extensive post-production latitude. Direct-to-consumer apparel brands in the United States escalate procurement volume as FTC truth-in-advertising standards mandate accurate product representation.
- Portrait:Professional headshot and personal milestone documentation utilizes controlled studio lighting or environmental settings depending on client specifications.
- Event:Corporate gatherings and institutional functions require rapid turnaround delivery modes with same-day editing capabilities for social media deployment.
Wedding services sit at the top of the volume ranking, with Commercial climbing the fastest as marketing procurement fragments across on-demand platforms.
Delivery Mode:
Cost tier differentiation separates infrastructure-heavy physical formats from margin-light digital distribution, reshaping studio capital allocation decisions.
- Digital:Cloud-native distribution platforms enable real-time client collaboration and version control, dominating volume metrics across all client categories. Mid-market brand marketing teams adopt browser-based environments that unify RAW processing with collaborative annotation.
- Photo Book:Premium press production and binding services retain disproportionate margin contribution despite lower unit volume, particularly in wedding and milestone documentation segments.
- Print:Individual enlargements and fine art reproductions serve gallery and residential decoration markets with specialized substrate and finishing options.
- Online Gallery:Password-protected client portals with integrated ordering systems streamline proof selection and print fulfillment logistics.
Digital delivery commands the highest volume position, with Photo Book maintaining the steepest margin expansion trajectory.
Client Type:
Application requirements diverge sharply between personal documentation needs and institutional procurement protocols with compliance documentation.
- Businesses:Corporate marketing departments and direct-to-consumer brands require ISO-certified color management and documented consent protocols for commercial usage rights. GDPR compliance investments intensify for cross-border event assignments involving EU identifiable subjects.
- Agencies:Creative and media buying intermediaries aggregate photography demand across multiple brand accounts, leveraging volume for preferred vendor rates.
- Individuals:Personal milestone and family documentation clients prioritize emotional resonance and archival permanence over technical specifications.
- Non-profits:Institutional storytelling and fundraising asset creation operates under constrained budgets with mission-driven usage requirements.
Businesses generate the largest revenue pool, with Agencies expanding most quickly as procurement centralizes through intermediary relationships.
Equipment Type:
Technology maturity curves separate established DSLR ecosystems from rapidly advancing mirrorless platforms, creating divergent depreciation and training investment profiles.
- Mirrorless:Compact form factors with advanced autofocus algorithms and silent shutter modes dominate new equipment procurement in event and documentary segments. Sony and Canon full-frame mirrorless systems lead professional adoption curves in the United States.
- DSLR:Optical viewfinder reliability and extensive lens library compatibility sustain deployment in controlled studio environments where battery longevity matters.
- Film:Analog capture persists in fine art and select wedding markets for distinctive grain structure and deliberate shooting pace.
- Studio Lighting:Strobe and continuous LED systems with wireless triggering enable precise exposure control for commercial product and portrait applications.
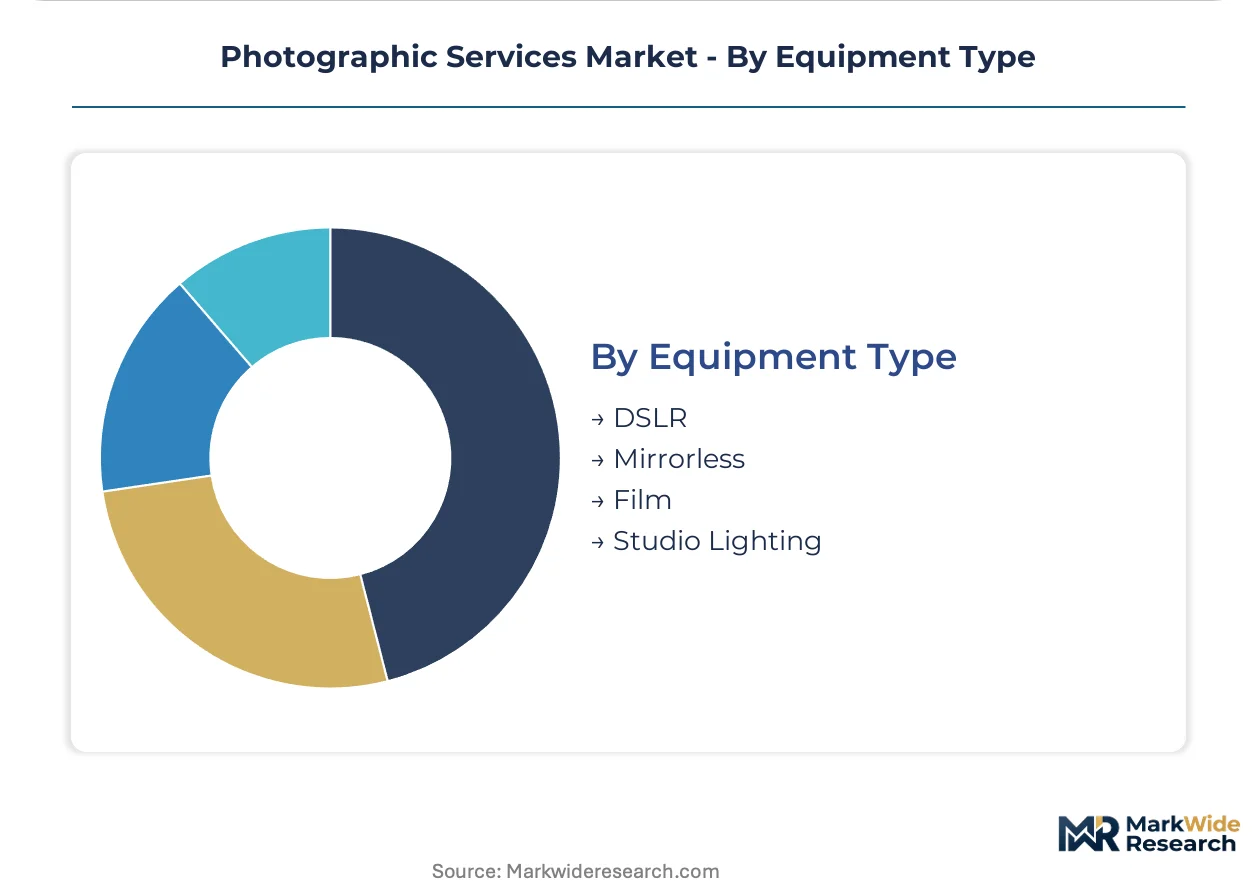
Mirrorless systems lead current volume rankings, with Studio Lighting investment climbing fastest as computational photography demands expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Post-production talent clusters concentrate in Los Angeles and New York, anchoring commercial photography workflows for entertainment and brand clients. Equipment rental infrastructure and color grading specialists reduce mobilization costs for high-value assignments. These metropolitan hubs export technical standards and pricing benchmarks to secondary markets.
United States
Direct-to-consumer brands in Los Angeles and New York escalate procurement volume for e-commerce visual assets. FTC truth-in-advertising standards mandate accurate product representation across digital campaigns. Studio clusters in Brooklyn and Silver Lake concentrate post-production talent and computational photography expertise.
Germany
Corporate event documentation and commercial brand procurement drive service demand in Berlin and Munich. GDPR consent protocols impose documentation requirements on portrait shoots involving identifiable subjects. Frankfurt studios specialize in ISO-certified color management for automotive and industrial brand clients.
United Kingdom
Editorial content generation and fashion brand campaigns sustain commercial photography volume in London. CNIL-aligned consent frameworks affect cross-border assignment workflows for EU-facing projects. Soho and Shoreditch post-production houses cluster around advertising agency demand.
India
Rising disposable incomes in tier-2 cities drive premium wedding photography penetration where professional capture remains underutilized. BIS standards influence equipment import and studio certification protocols. Mumbai and Delhi studio clusters concentrate destination wedding specialists and celebrity portrait services.
Japan
Corporate headshot and personal milestone documentation sustain steady service demand in Tokyo and Osaka. METI guidelines shape digital content licensing frameworks for commercial usage. Shibuya and Shinjuku districts host compact studio networks optimized for rapid-turnaround portrait workflows.
Photographic Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service categories. Market structure fragments between archival licensing platforms, on-demand gig-economy marketplaces, and vertically integrated production-to-fulfillment operators. Three archetypes dominate: content libraries with historical depth, algorithmic matching platforms for rapid deployment, and end-to-end production controllers. Competitive moves center on platform technology licensing and geographic expansion through localized talent acquisition.
Within the archival licensing tier, Getty Images and Visual China Group occupy positions defined by historical depth and territorial licensing rights. Shutterfly Inc. anchors the integrated production-fulfillment archetype, controlling capture-to-print workflows for personal milestone segments. Snappr exemplifies the on-demand marketplace model, algorithmically matching commercial clients with gig-economy photographers for same-day deployment.
| Leading Market Players |
|---|
| Studio Alice Co Ltd. |
| Cherry Hill Programs Inc. |
| Getty Images |
| Visual China Group Co. |
| Pic Solve |
| Shutterfly Inc. |
| Mom365 |
| Snappr |
| Lifetouch |
| Others |
Value Network & Pricing Analysis
Vertical integration into end-to-end production workflows anchors pricing power for studios controlling capture through personalized print fulfillment, while outsourced gig-economy platforms compete on speed rather than margin retention. Shutterfly's captive supply of album manufacturing and Snappr's algorithmic matching represent divergent supply architectures that reshape competitive economics across service tiers.
Pricing Analysis
Capacity additions in India's tier-2 cities are reshaping price floors for wedding photography as professional capture penetration expands faster than premium pricing discipline. Three-tier pricing structure across premium, standard, and economy levels dominates service packaging, with ISO-certified color management and RAW workflow expertise driving differentiation. Cost compression in commodity product photography intensifies as generative AI platforms displace basic catalog assignments. Direct-to-consumer apparel brands demonstrate highest price sensitivity, while destination wedding clients in Los Angeles and New York show lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from corporate procurement departments mandate multi-studio qualification for brand asset campaigns, fragmenting annual budgets across platform marketplaces rather than single-vendor retainers. Equipment manufacturing concentrates in Japan, Germany, and China, with Sony and Canon mirrorless systems anchoring professional adoption curves. Raw workflows draw from sensor components, cloud storage infrastructure, and color calibration hardware. Single-source vulnerability persists in specialized retoucher talent pools concentrated in premium metropolitan markets. Distribution runs through browser-based collaboration platforms unifying processing, annotation, and final asset delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FTC truth-in-advertising standards operate as a regulatory compounder, mandating accurate product representation that sustains demand for compliant commercial photography across e-commerce channels.
For Market Incumbents: Cement archival depth and enterprise licensing relationships against generative AI substitution threats in commodity segments. Deepen backward integration into cloud-native post-production platforms to capture recurring subscription revenue. Prioritize ISO color management certification investment to defend premium positioning in brand procurement evaluations. For New Entrants and Emerging Players: Begin with drone capture and 3D photogrammetry services for real estate visualization, a segment where technical barriers remain modest and vendor relationships are unconsolidated. India's tier-2 wedding markets offer the most penetrable geography, with professional capture underutilized relative to Western benchmarks. Deploy mobile consent-capture apps as a go-to-market angle to streamline GDPR compliance for cross-border event assignments. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-market studios lack capital to transition from legacy print fulfillment toward digital-first workflows. Long-term viability favors vertically integrated operators controlling end-to-end production or platform-based marketplaces with algorithmic supply matching. Target acquisition archetype: regional studios with established local brand relationships but underinvested technology infrastructure. Watch generative AI training data licensing dispute resolutions as the signal for copyright framework clarity that would shift competitive positioning materially.| Strategic Initiative | Industry Significance |
|---|---|
| ISO Color Management Certification | Frankfurt and Los Angeles studios leverage standardized credentials to command premium brand procurement positioning. |
| Cloud-Native Platform Integration | Browser-based environments unify RAW processing with collaborative annotation, eliminating file transfer bottlenecks for mid-market clients. |
| Drone + 3D Photogrammetry Capability Buildout | Aerial platforms and spatial mapping software open architectural visualization contracts previously requiring separate vendor relationships. |
| Mobile Consent Capture Technology | Real-time GDPR documentation via smartphone apps reduces operational friction for cross-border event photography in Germany and France. |
| Algorithmic Supply Matching Investment | Same-day booking platforms displace traditional agency relationships for routine product shoots in New York and Los Angeles. |
Research Methodology
Bottom-up client-type modeling reconciled against top-down equipment procurement tracking forms the analytical core of this study. Primary interviews with commercial photography studio owners, brand marketing procurement leads, post-production house technical directors, and gig-economy platform operators combined with secondary validation from SEC filings of publicly traded service providers, FTC enforcement action databases, EU GDPR regulatory guidance documents, and equipment manufacturer shipment disclosures. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of service type revenue trajectories and delivery mode volume shifts informed projection frameworks across the modeling period. Segmentation dimensions include service type, delivery mode, client category, and equipment technology tier, with CAGRs derived from regression analysis of disclosed market participant growth rates and inferred capacity expansion patterns. Forecast inputs incorporate RAW workflow adoption curves and cloud platform subscription growth as technology diffusion proxies.
Several conditions sit outside the modeled scope, including unresolved generative AI copyright litigation outcomes and potential EU regulatory expansion beyond current GDPR consent protocols. Forecasts reflect assumptions regarding continued corporate marketing budget allocation toward visual content production and stable equipment import tariff environments. Deviation in FTC enforcement intensity or rapid synthetic image quality advancement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Digital Entertainment in the Home Market
Digital Media
Entertainment Transcription Market
Digital Media
Drone Wedding Photography Market
Digital Media
United Kingdom Webtoons Market
Digital Media
3D Anaglyph Glasses Market
Digital Media
Global Music Video Production Market
Digital Media
Global Playout Automation and Channel in a Box Market
Digital Media
ACGN Subculture Market
Digital Media
LED Stadium Screens Market
Digital Media
Global Animation Market
Digital Media
Photography Services Market
Digital Media
Saudi Arabia Webtoons Market
Digital Media
In Flight Entertainment Market
Digital Media
Art App Market
Digital Media
Middle East and Africa Animation Market
Digital Media
Mexico Webtoons Market