
 Middle East Movies and Entertainment Market | 2026-2036
Middle East Movies and Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Movies and Entertainment Market Intelligence
Saudi Arabia's General Entertainment Authority licensing reforms is shifting theatrical exhibition economics across the Gulf. MBC Group leverages its vertically integrated studio-to-broadcast pipeline to dominate Arabic-language content creation. beIN Media Group anchors premium sports and entertainment rights acquisition across North Africa and the Levant. StarzPlay Arabia competes through flexible subscription tiers and regional payment integration.
Movies and entertainment in the Middle East encompass audio-visual content production, distribution, and exhibition spanning theatrical release, broadcast transmission, and over-the-top digital delivery, with production workflows typically involving 4K digital cinematography, regional language dubbing, and compliance editing for cultural content standards. The sector's commercial purpose centers on audience monetization through ticket sales, advertising placement, subscription fees, and licensing arrangements across multiple territories. Streaming platforms represent the fastest-growing distribution channel as fiber broadband penetration deepens and mobile data costs decline, while theatrical exhibition is rebuilding capacity in Saudi Arabia following regulatory liberalization. Feature films and television series command the largest share of production investment, though documentary content is gaining state funding support for heritage and tourism narratives.
The General Entertainment Authority of Saudi Arabia, the UAE's National Media Council, and Egypt's Supreme Council for Media Regulation each enforce content classification, licensing, and foreign ownership rules that shape market access and local production quotas. These frameworks incentivize domestic co-production structures and limit direct distribution by platforms lacking regional operational entities. Stakeholders must monitor evolving censorship protocols and subsidy eligibility as Gulf states compete to establish content hubs through zone-based incentives and infrastructure investment.
Market Dynamics
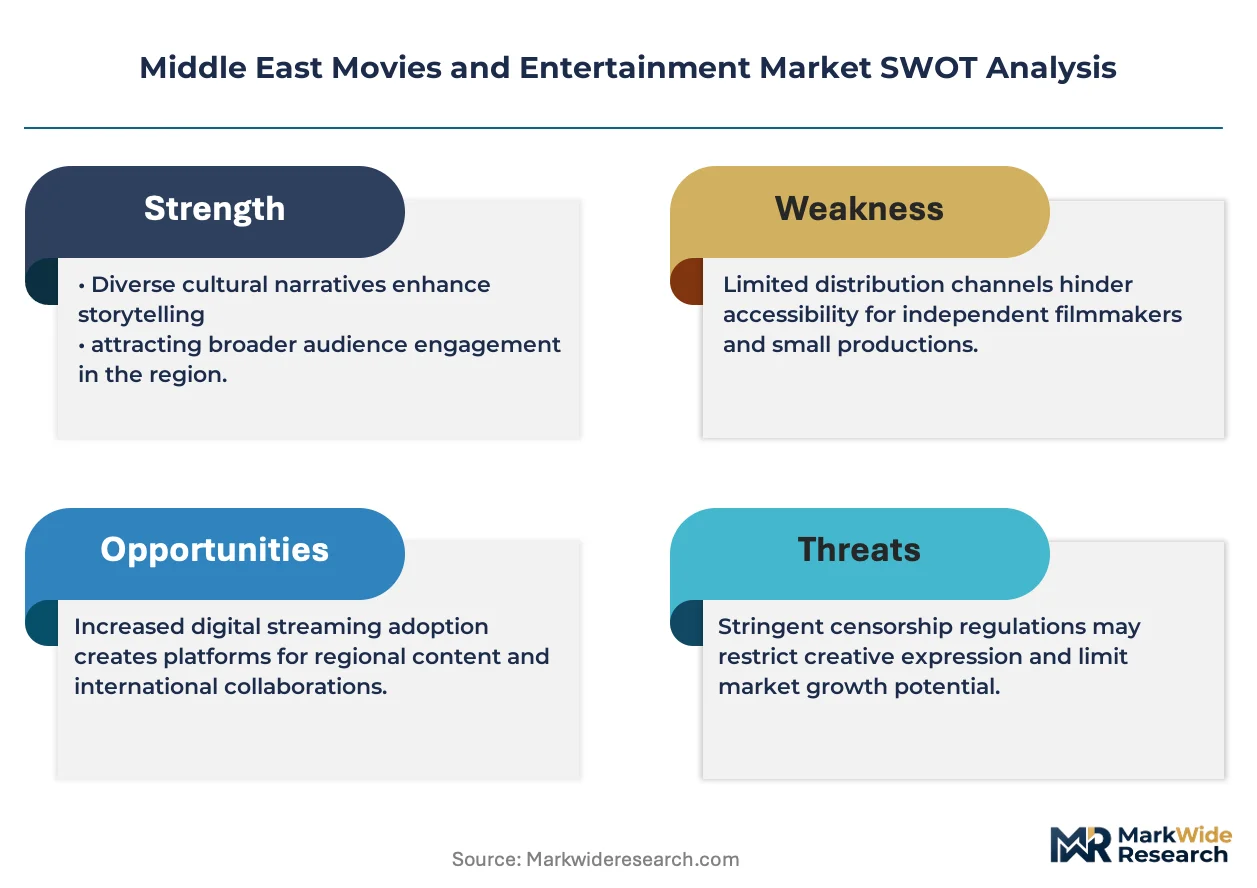
Saudi Arabia's General Entertainment Authority licensing reforms are compressing theatrical exhibition buildout timelines while streaming platforms capture youth viewership through mobile-first distribution. This dual-channel expansion is restructuring content investment priorities across Gulf production houses.
Growth Catalysts
- Localization mandates:Saudi Arabia's content quota requirements for streaming platforms are accelerating Arabic-language production capacity. Domestic studios secure preferential licensing terms.
- Fiber broadband rollout:UAE and Qatar infrastructure investments are enabling 4K streaming adoption. Young adult demographics drive subscription growth through smartphone delivery.
- Cinema construction subsidies:Saudi film fund programs reduce capital barriers for multiplex development. Exhibition operators receive operational support for regional expansion.
Market Restraints
- Content compliance costs:Cultural editing requirements across Gulf regulators extend post-production timelines. Foreign distributors face classification uncertainty.
- Production talent concentration:Experienced Arabic-language crews cluster in Egypt and Lebanon. Saudi and UAE studios compete for limited director and cinematographer pools.
- Import licensing friction:Foreign platform operators without regional entities face distribution restrictions. Operational establishment requirements delay market entry.
Strategic Opportunities
- Saudi theatrical underpenetration:Screen density remains below regional benchmarks. Premium format and family-oriented venues capture underserved demand.
- Tourism content integration:Heritage documentary production aligns with national diversification objectives. State funding supports location-based storytelling.
- Mobile payment convergence:Regional fintech integration enables flexible subscription tiers. Unbanked demographics access content through carrier billing.
Industry Challenges
- Post-production capacity gaps:Visual effects and dubbing facilities face skill shortages. Training pipelines lag behind production volume growth.
- Cross-border licensing complexity:Territory-specific rights fragmentation complicates regional distribution. Content windows vary across North Africa and Levant markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Movies and Entertainment Market |
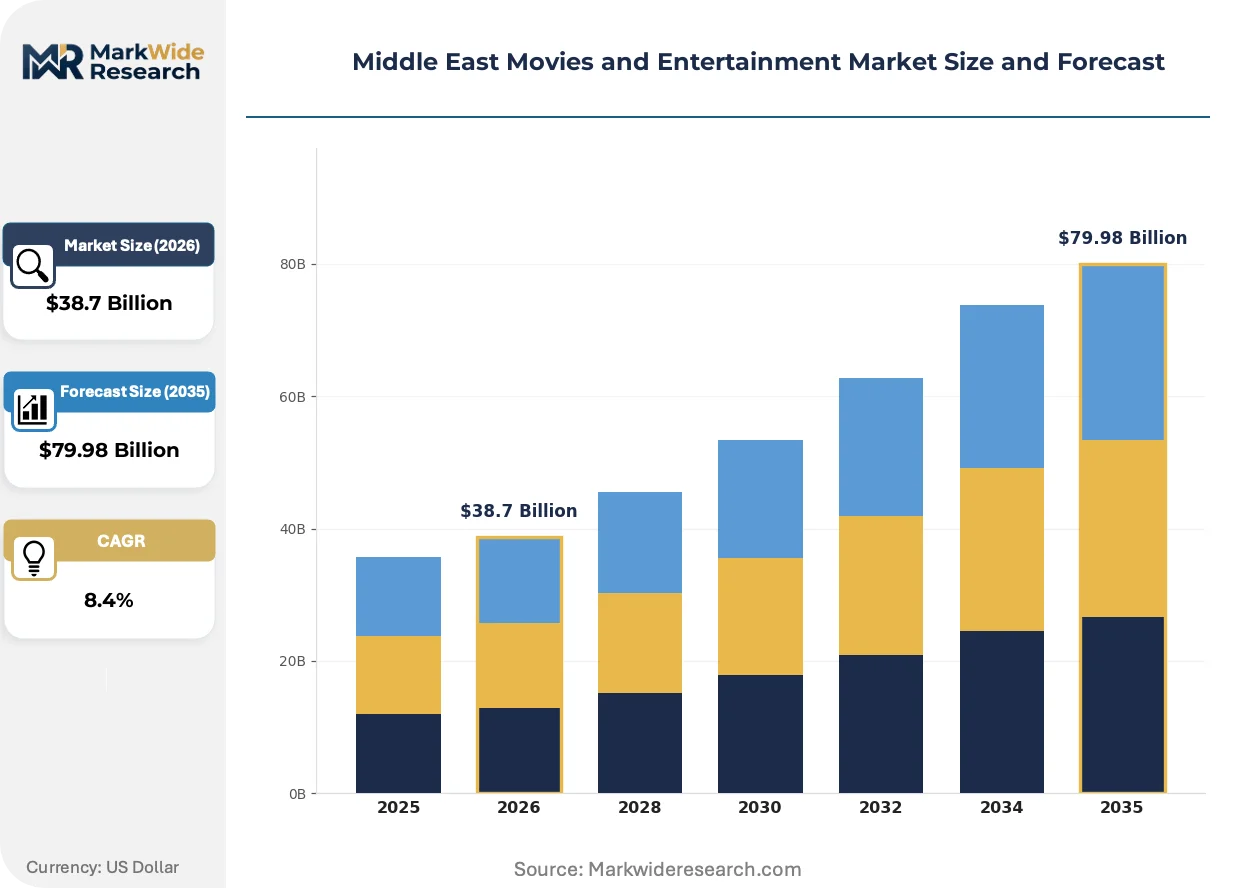
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Feature Films, Short Films, Documentaries, Television Series Distribution Channel: Theater, Streaming Platforms, Broadcast TV, DVD/Blu-ray Target Audience: Children, Teenagers, Adults, Families Production Budget: Low-budget, Mid-budget, High-budget, Blockbuster |
| Companies Covered | Orbit Showtime Network, Arab Media Group, MBC Group, StarzPlay Arabia, Al Jazeera Media Network, Rotana Group, Abu Dhabi Media, twofour54, beIN Media Group, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Movies and Entertainment Market Strategic Shifts & Innovations
Digital distribution infrastructure is overtaking legacy broadcast architecture across Middle East entertainment markets. Three convergent forces are compressing traditional value chains while expanding addressable audiences.
Cloud-native streaming encoding is overtaking satellite-dependent broadcast transmission for premium content delivery. Saudi and UAE platform operators deploy edge computing nodes to reduce latency. Mobile network operators bundle zero-rated video access to capture subscriber stickiness.
Saudi Arabia's General Entertainment Authority content classification framework is tightening theatrical and streaming release protocols. Foreign distributors must establish local operational entities to secure licensing approval. Compliance editing requirements extend post-production schedules for international titles targeting Gulf markets.
Young adult viewers in Saudi Arabia and the UAE are fragmenting attention across short-form mobile content and long-form streaming series. Traditional broadcast television loses primetime share to on-demand platforms. Subscription fatigue drives demand for flexible, non-contract payment models through regional fintech integration.
Middle East Movies and Entertainment Market Segmentation
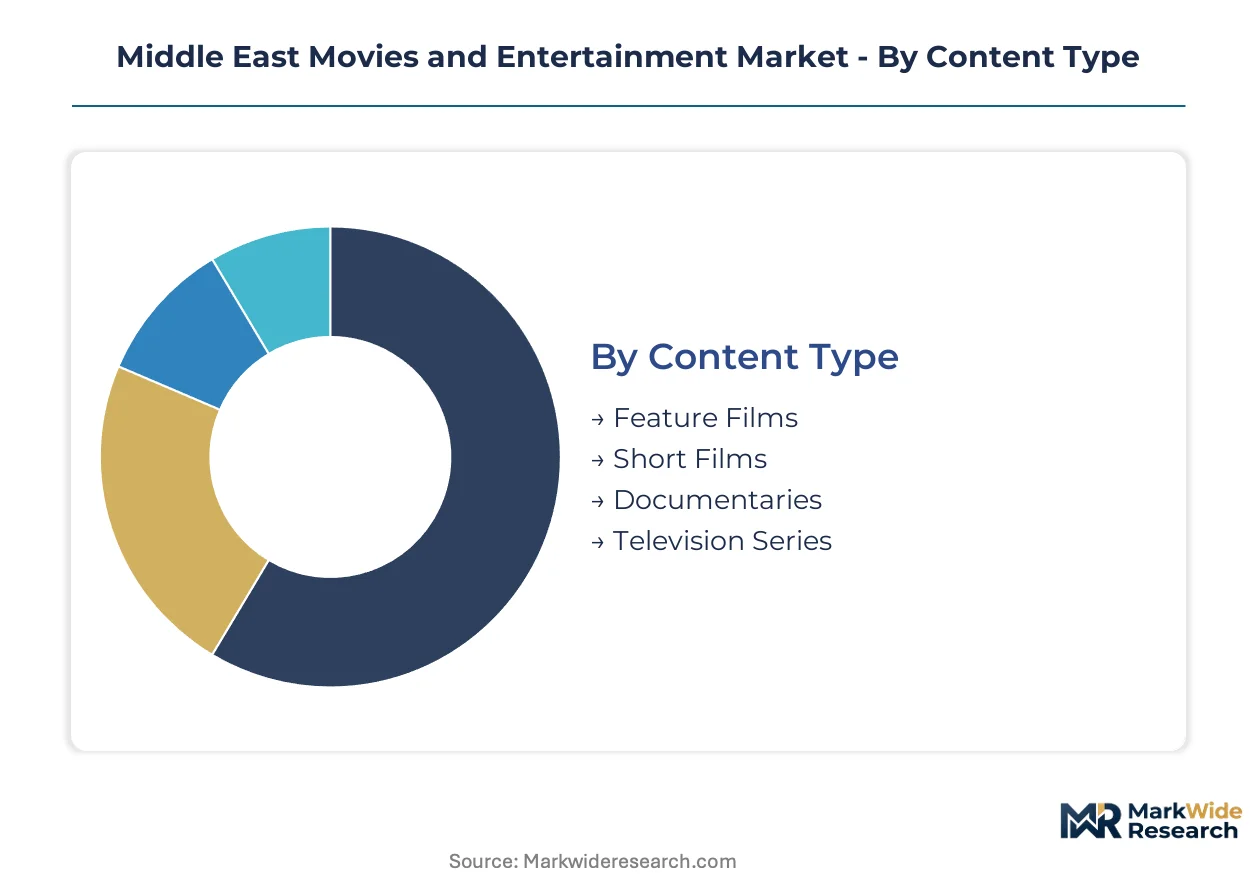
Content classification across the Middle East entertainment sector determines regulatory pathways, financing access, and platform licensing terms. Saudi Arabia's General Entertainment Authority mandates distinct compliance protocols for theatrical versus streaming releases. Production houses calibrate investment thresholds against distribution channel requirements and audience demographic targeting.
Content Type:
Standalone theatrical releases demand complete post-production workflows, while television series integrate episodic delivery systems with broadcast scheduling constraints.
- Feature Films:Full-length narrative productions typically exceed 90 minutes and require theatrical classification from national regulators. Saudi Arabia's emerging multiplex sector absorbs the majority of Gulf theatrical premieres, though streaming day-and-date releases are compressing traditional windows.
- Television Series:Episodic content spanning multiple seasons dominates Arabic-language production volume. MBC Group and Shahid VIP anchor commissioning demand across Ramadan scheduling cycles and year-round streaming catalogs.
- Documentaries:Heritage and tourism-aligned productions secure state funding through national film funds. Egypt's documentary infrastructure supplies technical crews for Gulf-financed projects.
- Short Films:Festival circuit entries and platform anthology content serve as talent development pipelines. Regional film festivals in Dubai and Jeddah provide distribution visibility.
Volume placements concentrate in Television Series; the faster expansion belongs to Documentaries.
Distribution Channel:
Cost tier segmentation separates capital-intensive theatrical infrastructure from variable-cost digital delivery systems.
- Streaming Platforms:Subscription video-on-demand services deploy regional encoding nodes for 4K delivery. StarzPlay Arabia and Shahid VIP compete through localized payment integration and Arabic-original commissioning.
- Theater:Multiplex exhibition requires physical infrastructure investment and GEA licensing compliance. Saudi screen density remains below UAE and Lebanese benchmarks despite accelerated construction timelines.
- Broadcast TV:Satellite transmission retains reach advantages for older demographics and rural markets. beIN Media Group controls premium sports and entertainment rights across North Africa and the Levant.
- DVD/Blu-ray:Physical media persists in collector markets and territories with limited broadband penetration. Distribution concentrates through retail partnerships in Egypt and Jordan.
Revenue gravity sits with Streaming Platforms; theatrical exhibition is climbing the fastest.
Target Audience:
Customer type segmentation aligns content rating systems with family viewing patterns and youth mobile consumption habits.
- Families:Cross-generational content faces the strictest cultural compliance requirements. Saudi and UAE regulators mandate specific editing protocols for theatrical family releases.
- Adults:Mature-themed productions access broader creative latitude on streaming platforms. Subscription tiers differentiate adult-oriented catalogs from family bundles.
- Teenagers:Mobile-first short-form and serialized content captures fragmented attention. Regional platforms deploy vertical video formats for this demographic.
- Children:Educational and entertainment content triggers co-viewing requirements and advertising restrictions. State broadcasters maintain dedicated children's channels.
Commissioning volume favors Adults; the steepest expansion trajectory belongs to Teenagers.
Production Budget:
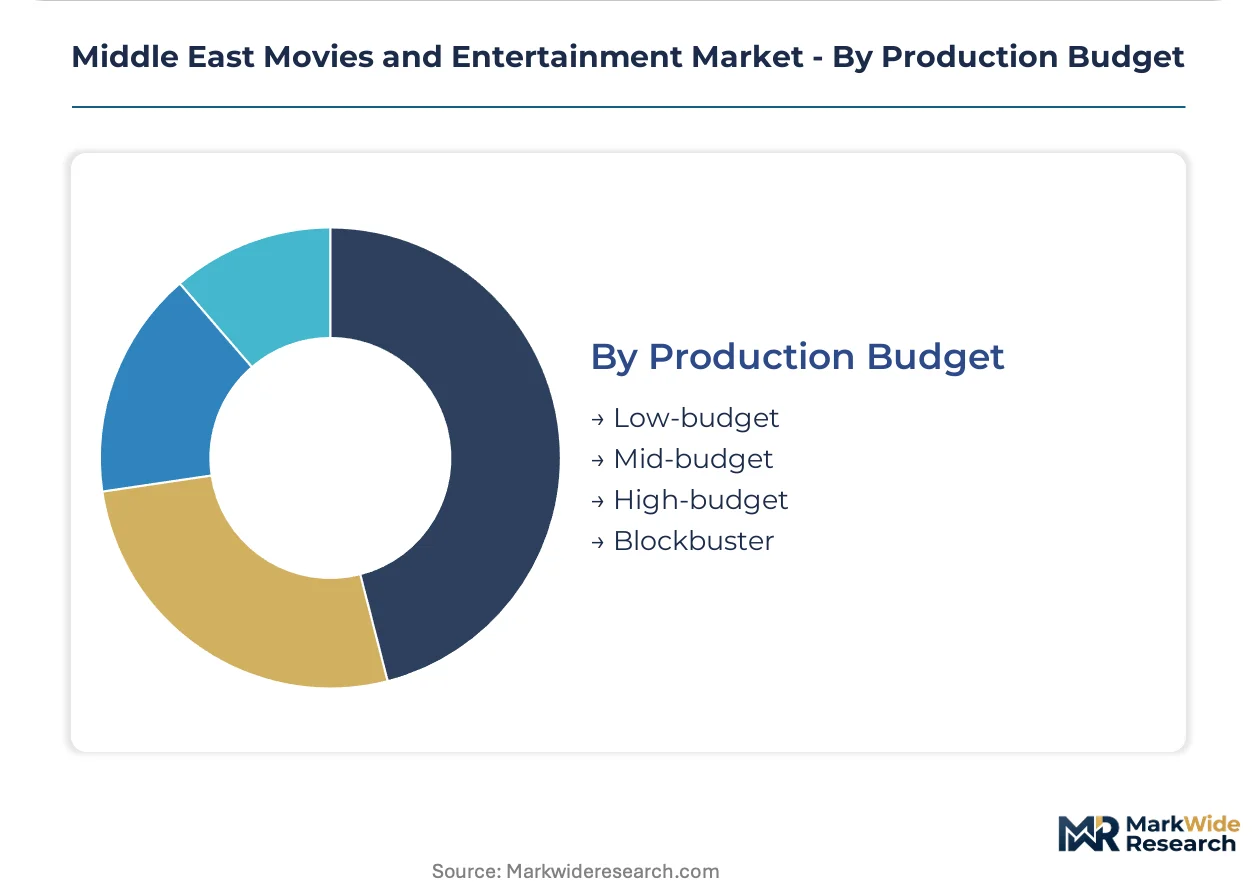
Margin structure differentiates blockbuster tentpoles with regional co-financing from agile low-budget productions accessing streaming direct-to-platform deals.
- Blockbuster:Productions exceeding high-budget thresholds require theatrical distribution guarantees and multinational co-production structures. Saudi film fund equity participation anchors several Gulf-financed blockbusters.
- High-budget:Premium productions qualify for festival premieres and territory-by-territory presales. Dubai and Abu Dhabi production incentives attract international location shoots.
- Mid-budget:Commercial Arabic-language features dominate theatrical slates in Egypt and Lebanon. These productions balance star talent costs against predictable genre formulas.
- Low-budget:Emerging director projects and streaming-commissioned content minimize risk through limited location requirements. Saudi and UAE film funds provide development grants for this tier.
Investment concentration rests in Mid-budget; Blockbuster production is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Egypt and Lebanon while consumption growth concentrates in Saudi Arabia and the UAE. This geographic split shapes talent migration patterns and co-financing structures across the Gulf. Regulatory divergence between content creation hubs and emerging exhibition markets complicates regional distribution strategies.
Saudi Arabia
Multiplex construction and streaming platform localization drive investment flows into Riyadh and Jeddah. The General Entertainment Authority mandates operational establishment for foreign distributors seeking theatrical release licenses. NEOM's production zone development anchors inbound co-production structures with European and Asian studios.
United Arab Emirates
Dubai and Abu Dhabi compete for international location shoots through production incentive frameworks. twofour54's media zone infrastructure supplies post-production facilities for Gulf-financed projects. The National Media Council enforces content classification protocols that streaming platforms must integrate into distribution workflows.
Egypt
Cairo's technical crew base supplies Arabic-language production talent for Saudi and UAE commissioning demand. The Supreme Council for Media Regulation maintains foreign ownership caps on broadcast and theatrical distribution entities. Giza's studio complexes face equipment upgrade pressures to meet 4K delivery standards from Gulf clients.
Qatar
beIN Media Group's sports rights portfolio anchors Doha's position in premium content acquisition. The national communications regulator imposes platform licensing requirements that affect streaming service market entry. Education City's documentary production initiatives align with heritage tourism narrative funding.
Lebanon
Beirut's director and cinematographer pool supplies talent for regional productions despite domestic economic instability. Banking sector restrictions complicate production financing flows to Lebanese production houses. The city's post-production facilities maintain competitive cost positions for Gulf clients seeking visual effects work.
Middle East Movies and Entertainment Market Key Industry Players
The competitive structure tilts toward vertically integrated media conglomerates with broadcast-to-streaming pipelines. Market concentration reflects regulatory barriers that favor established regional operators with local operational entities. Three archetypes dominate: state-affiliated broadcasters with streaming extensions, independent streaming platforms with flexible subscription models, and production zone operators with infrastructure rental revenue. Competitive moves center on exclusive content commissioning and strategic partnerships with international studios for co-production rights.
Within the integrated broadcaster tier, MBC Group and beIN Media Group exemplify archetypes combining linear channels with subscription streaming platforms. StarzPlay Arabia occupies a position among independent streaming specialists competing through payment integration rather than owned content libraries. These three entities represent distinct strategic postures: MBC Group anchors Arabic-original production volume, beIN Media Group controls premium sports rights leverage, and StarzPlay Arabia targets price-sensitive demographics through carrier billing partnerships.
| Leading Market Players |
|---|
| Orbit Showtime Network |
| Arab Media Group |
| MBC Group |
| StarzPlay Arabia |
| Al Jazeera Media Network |
| Rotana Group |
| Abu Dhabi Media |
| twofour54 |
| beIN Media Group |
| Others |
Cost & Logistics Intelligence
Sovereign-backed film fund programs in Saudi Arabia and production zone operators in the UAE anchor supply-side financing structures that simultaneously compress content acquisition costs and elevate compliance-related pricing premiums for foreign distributors lacking local operational entities.
Pricing Analysis
Cost-down pressure on mid-budget theatrical releases accelerates because Saudi multiplex operators negotiate volume-based licensing terms with domestic studios receiving preferential fund equity participation. Three-tier pricing structure across premium format, standard theatrical, and economy streaming tiers differentiates content access by delivery channel and cultural compliance tier. Price differentiation traces to General Entertainment Authority classification requirements and fiber broadband infrastructure quality. Teenage mobile viewers exhibit highest price sensitivity through carrier billing preference; blockbuster theatrical audiences show lowest sensitivity given limited screen density.
Supply Chain Analysis
General Entertainment Authority licensing mandates and National Media Council content classification protocols gate supply chain participation for foreign streaming platforms and theatrical distributors. Production talent concentrates in Egypt, Lebanon, and the UAE, with Cairo's technical crews and Beirut's director pool feeding Gulf commissioning demand. Raw material dependencies span 4K digital cinematography equipment, regional language dubbing facilities, and visual effects rendering infrastructure. Single-source vulnerability sits with Egyptian crew availability given banking sector restrictions on Lebanese production financing. Distribution runs through vertically integrated broadcaster-streaming pipelines, satellite transmission for rural reach, and edge-computing nodes for urban 4K delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's content quota mandates for streaming platforms construct a cost-of-compliance barrier that rewards established operators with local operational entities while extracting market entry premiums from foreign distributors lacking General Entertainment Authority licensing infrastructure.
For Market Incumbents: Lock in Arabic-original production capacity through exclusive talent agreements with Cairo and Beirut director pools before Saudi film fund subsidies attract competing commissioning demand. Secure multiplex expansion rights in secondary Saudi cities ahead of screen density normalization. Vertical integration into post-production facilities addresses visual effects skill shortages threatening delivery timelines. For New Entrants and Emerging Players: Capture documentary production white-space aligned with Saudi and UAE heritage tourism funding priorities, where state financing reduces commercial risk and compliance editing requirements are lighter than theatrical releases. Target mobile-first teenage demographics through regional fintech payment integration rather than competing for premium sports rights against entrenched broadcasters. Go-to-market angle: carrier-billed micro-subscription tiers for unbanked populations. For Investors and Strategic Acquirers: Distressed-cycle entries favor Lebanese post-production facilities with competitive visual effects cost positions and established Gulf client relationships despite domestic banking restrictions. Long-term viability hinges on Saudi screen density reaching UAE benchmarks and streaming platform localization mandates persisting. Watch for General Entertainment Authority licensing reform signals that could accelerate foreign platform market entry and compress incumbent pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Arabic-Original Content Commissioning | MBC Group and Shahid VIP anchor Ramadan scheduling cycles with exclusive series production. |
| Multiplex Infrastructure Buildout | Saudi film fund subsidies reduce capital barriers for regional exhibition operators expanding screen density. |
| Mobile Payment Integration | StarzPlay Arabia captures unbanked demographics through carrier billing partnerships with regional telecom operators. |
| Production Zone Development | NEOM and twofour54 attract inbound co-production structures with European and Asian studios seeking location incentives. |
| Heritage Documentary Funding | State film funds in Saudi Arabia and Qatar finance tourism-aligned storytelling with reduced commercial risk exposure. |
Research Approach
Trade publications covering Gulf media regulation, Saudi General Entertainment Authority licensing bulletins, and UAE National Media Council classification frameworks formed the secondary backbone. Primary interviews with streaming platform commissioning executives, multiplex exhibition operators, Cairo-based production house managers, and Beirut post-production facility directors validated demand assumptions. Customs data on 4K cinematography equipment imports and fiber broadband penetration statistics from national communications regulators supplied infrastructure indicators. Bottom-up project pipelines and top-down media consumption surveys were triangulated against fund disbursement records.
Bottom-up modeling tracked individual production budgets across feature film, television series, and documentary categories, while top-down analysis calibrated total addressable audience against subscription pricing and theatrical ticket yield. Segmentation dimensions spanned content type, distribution channel, target audience demographic, and production budget tier. CAGRs were derived from fitted growth curves against platform subscriber data and screen construction timelines. Forecast inputs incorporated General Entertainment Authority licensing velocity and mobile data cost trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Saudi content quota enforcement intensity and Egyptian crew migration patterns. Forecasts reflect documented assumptions on regulatory stability and infrastructure investment continuity. A model refresh is warranted upon material change in General Entertainment Authority foreign distributor licensing protocols or Lebanese banking sector resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Digital Content Market
Digital Media
Information Short Video Market
Digital Media
LED Stadium Screens Market
Digital Media
Anime Merchandising Market
Digital Media
Media Gateway Market
Digital Media
Entertainment Transcription Market
Digital Media
Latin America Inflight Entertainment and Connectivity Market
Digital Media
Global Playout Automation and Channel in a Box Market
Digital Media
Naruto Around Market
Digital Media
North America Webtoons Market
Digital Media
Digital Media Market
Digital Media
Japan Webtoons Market
Digital Media
Saudi Arabia Webtoons Market
Digital Media
Adult Animation Market
Digital Media
Mexico Webtoons Market
Digital Media
Digital Content Creator Market