
 APAC Media and Entertainment Market | 2026-2036
APAC Media and Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Media and Entertainment Market Insights
Market Dynamics
South Korean production studios and Japanese anime houses is consolidating around cloud-based rendering pipelines and pan-Asian distribution networks. ByteDance Ltd. leverages its algorithmic recommendation engine to sustain engagement across Southeast Asian markets. Tencent Holdings Ltd. anchors its position through gaming-to-streaming cross-promotion and exclusive sports rights. Sony Group Corporation differentiates via premium hardware-software integration across PlayStation and Crunchyroll ecosystems.
Segmentation and Technology
APAC media and entertainment encompasses the creation, aggregation, and monetization of audio-visual content delivered through theatrical exhibition, broadcast transmission, and internet protocol-based streaming platforms operating across diverse linguistic and regulatory environments. The sector relies on content delivery networks with sub-50 millisecond latency thresholds, digital rights management protocols, and adaptive bitrate streaming to serve fragmented device ecosystems from low-bandwidth mobile handsets to 8K home theater systems. Streaming now commands the dominant revenue pool within content type segmentation, while ad-supported service models outpace subscription growth in price-sensitive South Asian markets. Cloud-based technology infrastructure is displacing on-premise broadcast playout systems as terrestrial networks in Indonesia and the Philippines accelerate IP migration.
Regulatory Environment
India's TRAI oversees tariff frameworks for cable and direct-to-home platforms, while China's SAMR enforces antitrust scrutiny against platform exclusivity arrangements. South Korea's KCC mandates domestic content quotas for streaming services, and Australia's ACMA imposes gambling advertising restrictions on live sports broadcasts. Stakeholders must monitor evolving data localization mandates and content takedown protocols as these directly determine capital allocation for regional server infrastructure and compliance staffing.
Market Dynamics
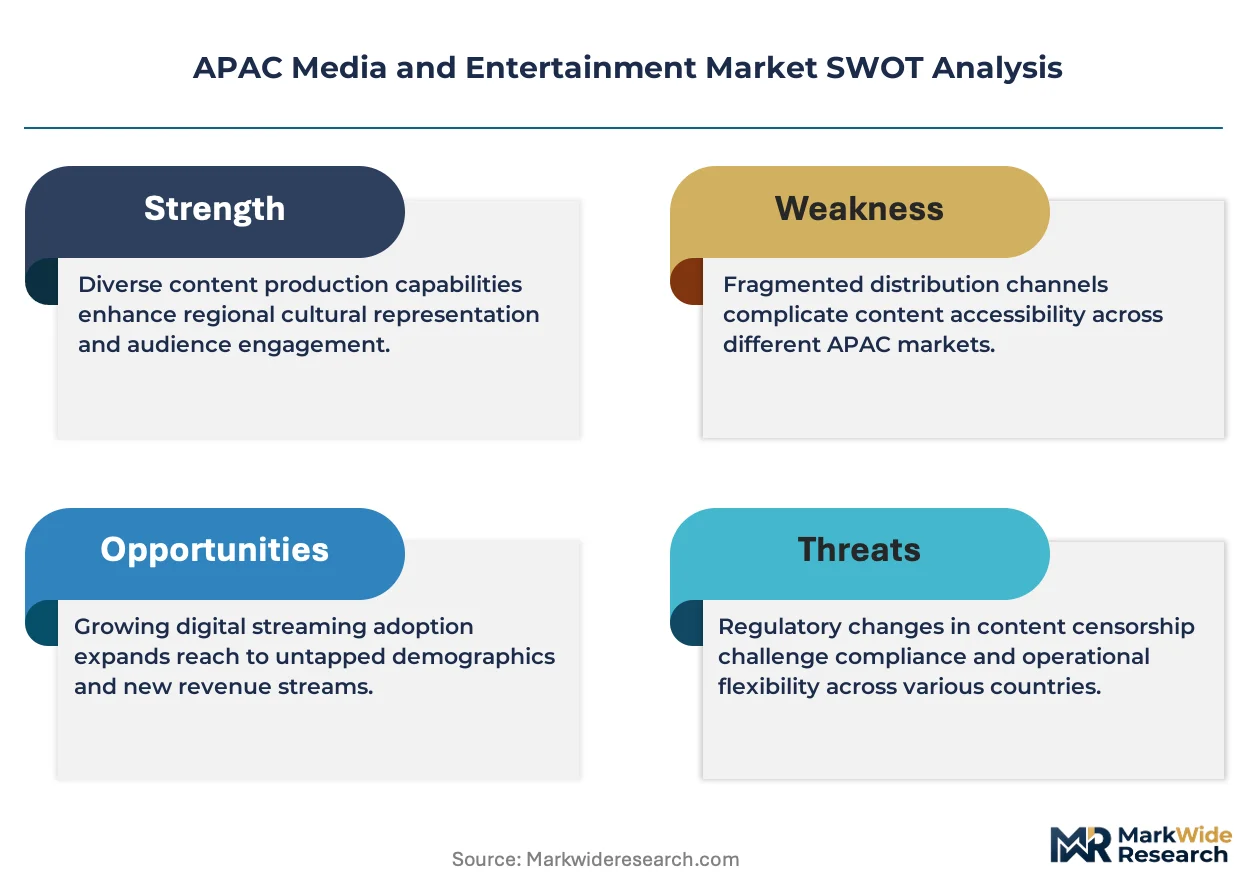
Cloud-based rendering infrastructure is consolidating production workflows across APAC media hubs, compressing post-production timelines while India's BIS digital content standards and China's MIIT cloud computing guidelines impose new compliance layers on platform architecture decisions.
Growth Catalysts
- 5G network densification:South Korea's KCC spectrum allocation enables sub-50 millisecond latency for live streaming, expanding addressable markets for real-time interactive content formats.
- Regional-language content corridors:India's PLI scheme for audiovisual production attracts capital to Tamil, Telugu, and Marathi content ecosystems beyond Hindi-centric output.
- Cross-border IP licensing frameworks:ASEAN's consolidated copyright enforcement protocols reduce legal friction for pan-Asian distribution of Japanese anime and South Korean drama formats.
Market Restraints
- Data localization mandates:China's SAMR server location requirements force redundant infrastructure investment, elevating opex for streaming platforms operating across multiple APAC jurisdictions.
- Content quota compliance costs:South Korea's KCC domestic production minimums strain acquisition budgets for foreign-owned platforms seeking market entry.
- Terrestrial broadcast legacy:Indonesia and Philippines maintain analog transmission obligations that delay full IP migration and fragment addressable audiences.
Strategic Opportunities
- Vietnam's underpenetrated streaming base:Ad-supported models outpace subscription growth in this price-sensitive market, creating white space for localized platform launches.
- Gaming-to-streaming convergence:Tencent's cross-promotion architecture demonstrates how interactive entertainment IP migrates to passive viewing formats.
- Australia's ACMA gambling advertising restrictions:Sports broadcasters pivot to sponsorship integration and branded content, opening alternative monetization channels.
Industry Challenges
- Cloud-native talent scarcity:Broadcast engineers with IP workflow expertise command premium compensation in Jakarta, Manila, and Bangkok markets.
- Multi-DRM integration complexity:Platforms must reconcile Google's Widevine, Apple's FairPlay, and Microsoft PlayReady across fragmented device ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Media and Entertainment Market |
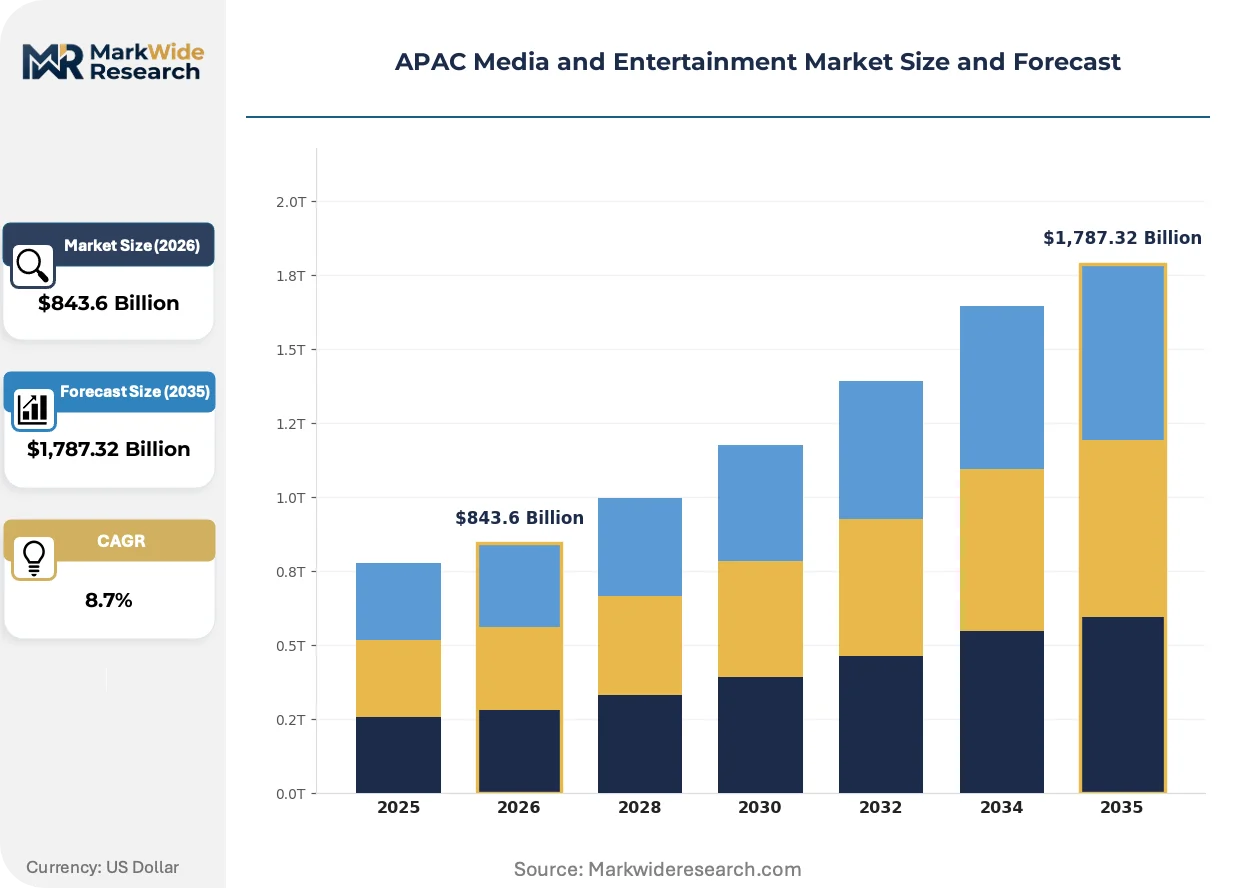
| Market Size in 2026 | $843.6 Billion |
| Market Size in 2035 | $1,787.32 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Film, Television, Streaming, Music Distribution Channel: Theater, Online, TV, Radio Service Type: Subscription, Pay-Per-View, Ad-Supported, Freemium Technology: Virtual Reality, Augmented Reality, 4K, Cloud-Based |
| Companies Covered | Apple Inc., ByteDance Ltd., Tencent Holdings Ltd., Netflix Inc., Alibaba Group Holding Ltd., Alphabet Inc., Sony Group Corporation, The Walt Disney Company, Amazon.com Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Media and Entertainment Market Trends and Innovations
Algorithmic personalization and edge computing architectures are compressing the distance between content creation and consumption, while regulatory pressure on platform market power forces structural adjustments to exclusivity arrangements and data handling protocols.
AI-driven content recommendation engines analyze viewer behavior patterns to surface hyper-localized programming. Southeast Asian platforms deploy these systems to match Indonesia's 700+ language variants with appropriate subtitle and dubbing assets. ByteDance's algorithmic infrastructure is integrating generative preview clips that auto-assemble highlight reels from long-form content, reducing marketing production cycles from days to hours.
China's SAMR antitrust scrutiny targets platform exclusivity arrangements that lock content behind single-service walls. The enforcement action fragments previously consolidated streaming rights, forcing studios to pursue multi-platform windowing strategies. Japanese anime houses now negotiate shorter exclusivity periods, accelerating content circulation across competing services.
Ad-supported tiers displace pure subscription models in South Asian price-sensitive segments. Indian consumers gravitate toward platforms offering regional-language advertising at lower monthly rates than premium ad-free alternatives. This behavioral pivot pressures average revenue per user metrics while expanding total addressable audience pools for advertisers targeting tier-2 and tier-3 city clusters.
APAC Media and Entertainment Market Segmentation
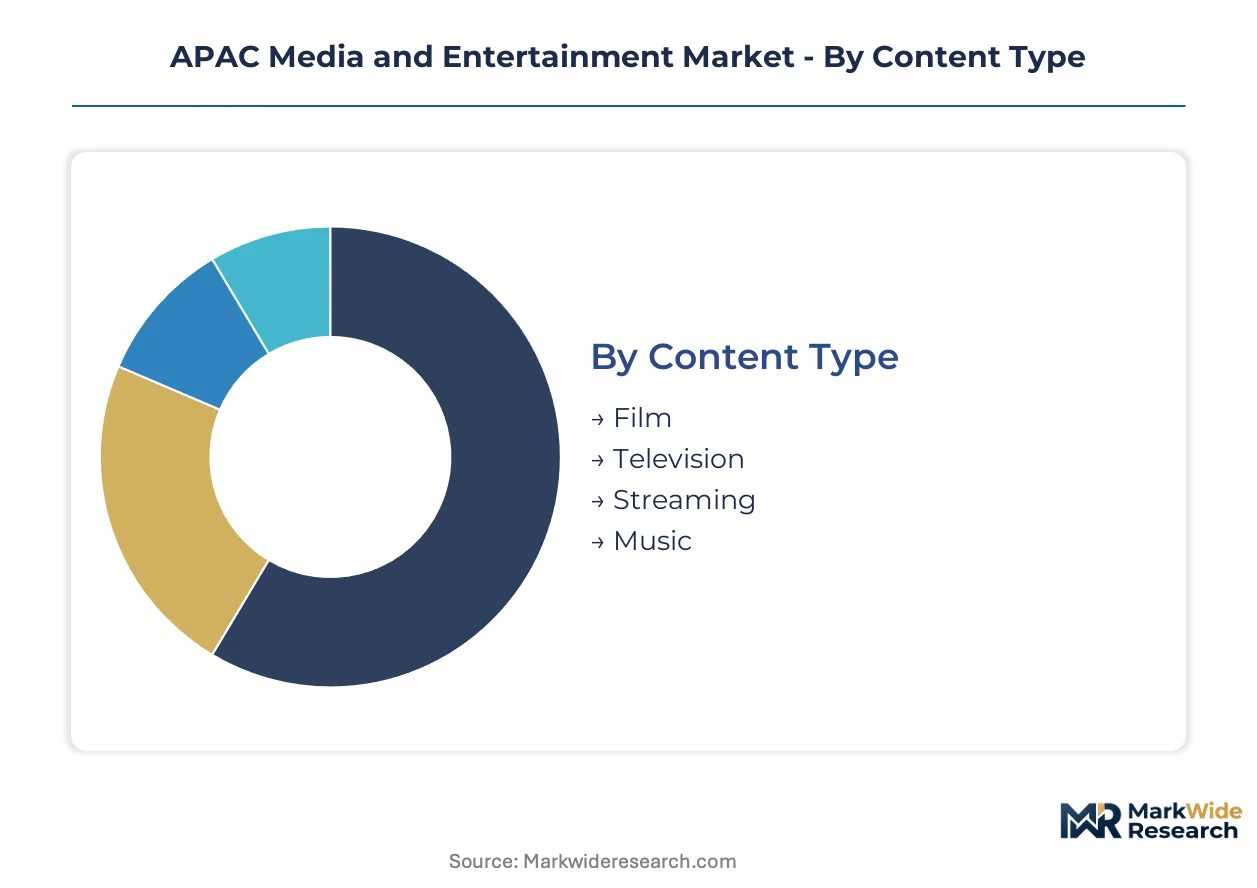
Content type and distribution channel decisions determine capital allocation across APAC's fragmented linguistic markets, where regulatory compliance costs vary dramatically by delivery mechanism. Service type selection directly shapes subscriber acquisition economics in price-sensitive South Asian corridors versus premium North Asian markets.
Content Type:
Production budget thresholds and localization requirements drive buyer prioritization across formats with vastly different cost structures and export potential.
- Film:Theatrical releases command premium windowing strategies with 90-day exclusivity periods before streaming migration. South Korean studios leverage this format for pan-Asian theatrical distribution through consolidated exhibition networks in Japan, Thailand, and Vietnam.
- Television:Linear broadcast maintains residual strength in Indonesia and Philippines where terrestrial obligations persist, though IP migration accelerates. India's regional-language serial production concentrates in Tamil Nadu and Maharashtra, feeding both domestic broadcast and international diaspora markets.
- Streaming:Over-the-top platforms capture dominant revenue share through original content commissioning and exclusive sports rights aggregation.
- Music:Audio streaming services monetize through bundled telco partnerships and short-form video synchronization licensing across Southeast Asian markets.
Streaming leads on scale; film leads on momentum through theatrical recovery and premium windowing economics.
Distribution Channel:
Regulatory friction and infrastructure maturity create sharp performance divergences across delivery mechanisms in this region-specific market.
- Theater:Exhibition networks in South Korea and Japan operate at near-full digitization with integrated concession and merchandise revenue streams. India's multiplex penetration in tier-2 cities expands addressable audiences for regional-language releases beyond metropolitan centers.
- Online:Mobile-first consumption dominates Southeast Asian markets where low-bandwidth adaptive streaming serves fragmented device ecosystems. Content delivery networks with sub-50 millisecond latency thresholds enable real-time interactive formats in South Korea's 5G-densified corridors.
- TV:Direct-to-home satellite maintains subscriber bases in rural India and Australia's remote territories where terrestrial coverage gaps persist.
- Radio:Terrestrial broadcast retains advertising relevance for commuter audiences in dense metropolitan clusters across Japan and Australia.
Online distribution commands volume concentration; theatrical exhibition delivers margin expansion through premium pricing power.
Service Type:
Price sensitivity gradients and payment infrastructure maturity determine monetization model viability across national markets.
- Subscription:Recurring revenue models concentrate in Australia, Japan, and South Korea where credit card penetration supports seamless billing. India's price-tiered plans accommodate family sharing and mobile-only access to expand addressable bases.
- Pay-Per-View:Transactional video-on-demand captures live sports and day-and-date theatrical releases where exclusive rights justify premium pricing. Boxing and cricket events drive peak usage in Philippines and Indian metropolitan markets.
- Ad-Supported:Free-tier streaming expands fastest in Vietnam, Indonesia, and India's tier-2 cities where advertiser demand for regional-language inventory outpaces supply. This model sacrifices average revenue per user for total audience scale.
- Freemium:Tiered conversion funnels balance acquisition costs against lifetime value in competitive Southeast Asian markets where multi-homing behavior is prevalent.
Subscription generates revenue concentration; ad-supported models gain share fastest through Southeast Asian market penetration.
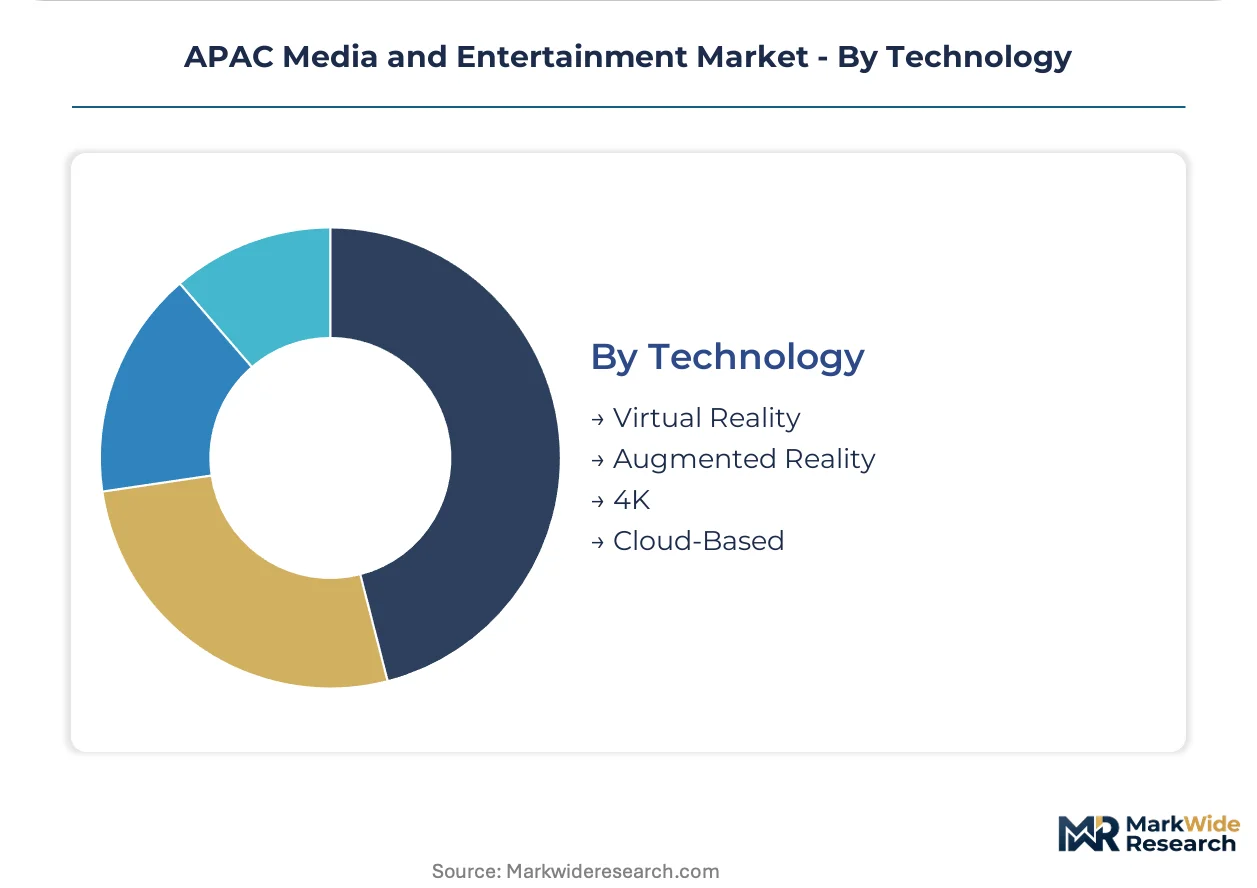
Technology:
Infrastructure investment cycles and content production pipeline readiness dictate deployment sequencing across immersive and cloud-native formats.
- Virtual Reality:Location-based entertainment venues in Tokyo, Seoul, and Shanghai deploy VR experiences for multiplayer gaming and virtual concert attendance. Hardware cost barriers limit home adoption despite 5G-enabled streaming capabilities.
- Augmented Reality:Mobile AR filters and interactive advertising integrate with short-form video platforms across Southeast Asian markets. Japanese anime houses experiment with AR-enabled merchandise and character overlays for fan engagement.
- 4K:Ultra-high-definition production pipelines concentrate in South Korean drama houses and Japanese anime studios serving premium streaming tiers. Bandwidth constraints restrict 4K adoption in Indonesia and Philippines outside fiber-connected metropolitan zones.
- Cloud-Based:Rendering farms and playout systems displace on-premise infrastructure as India's BIS digital content standards and China's MIIT cloud computing guidelines reshape platform architecture decisions.
Cloud-based infrastructure dominates deployment scale; virtual reality carries the steepest expansion trajectory through location-based entertainment investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT cloud computing guidelines and India's BIS digital content standards are tightening compliance requirements simultaneously, while South Korea's K-content export ecosystem and Japan's anime production corridors drive divergent growth trajectories across the region.
China
SAMR antitrust scrutiny targets platform exclusivity arrangements, fragmenting previously consolidated streaming rights and forcing multi-platform windowing strategies. MIIT cloud computing guidelines impose data localization mandates that elevate operational expenditure for cross-border service delivery. Beijing and Shanghai production clusters pivot toward shorter exclusivity periods to accelerate content circulation.
India
Regional-language content production concentrates in Tamil, Telugu, and Marathi corridors beyond Hindi-centric output, expanding addressable audiences for streaming platforms. TRAI tariff frameworks govern cable and direct-to-home platform pricing, while BIS digital content standards reshape platform architecture decisions. Maharashtra and Tamil Nadu production hubs attract PLI scheme capital for audiovisual infrastructure.
South Korea
KCC domestic content quotas mandate minimum production thresholds for streaming services seeking market entry, straining acquisition budgets for foreign-owned platforms. 5G network densification enables sub-50 millisecond latency for live streaming and real-time interactive formats. Seoul production studios consolidate around cloud-based rendering pipelines serving pan-Asian distribution networks.
Japan
Anime houses negotiate shorter exclusivity periods under regulatory pressure, accelerating content circulation across competing services. METI industrial policy supports location-based entertainment venues deploying VR experiences in Tokyo and Osaka. Kyoto and Saitama animation clusters experiment with AR-enabled merchandise and character overlays for fan engagement.
Vietnam
Ad-supported streaming models outpace subscription growth in this price-sensitive market, creating white space for localized platform launches with regional-language advertising inventory. The country's national media regulator imposes content takedown protocols that determine compliance staffing levels. Ho Chi Minh City and Hanoi production corridors develop short-form video synchronization licensing for telco partnerships.
APAC Media and Entertainment Market Competitive Landscape
South Korean and Japanese producers anchor one tier; Chinese and Indian specialists hold distinct positions in platform technology and regional content aggregation. The market structure consolidates around algorithmic recommendation engines, cloud-based infrastructure providers, and cross-media IP holders. Three archetypes dominate: vertically integrated conglomerates with gaming-to-streaming pipelines, hardware-software ecosystem players, and algorithm-native short-form platforms. Competitive moves concentrate on exclusive sports rights aggregation and pan-Asian distribution network expansion.
Among China-based technology conglomerates, ByteDance Ltd. and Tencent Holdings Ltd. exemplify the algorithm-native and gaming-to-streaming archetypes respectively. Sony Group Corporation anchors the hardware-software integration tier through its position across console and anime streaming ecosystems. These three entities occupy positions that represent the dominant strategic vectors in regional competition: recommendation-driven engagement, interactive-to-passive IP migration, and premium ecosystem lock-in.
| Leading Market Players |
|---|
| Apple Inc. |
| ByteDance Ltd. |
| Tencent Holdings Ltd. |
| Netflix Inc. |
| Alibaba Group Holding Ltd. |
| Alphabet Inc. |
| Sony Group Corporation |
| The Walt Disney Company |
| Amazon.com Inc. |
| Others |
Pricing and Supply Chain Analysis
Ad-supported versus subscription tier divergence splits APAC streaming economics along regional income gradients, compressing margins in Southeast Asian markets while premium hardware-software bundles sustain pricing power in Japan and South Korea. This bifurcation traces directly to cloud infrastructure deployment patterns, where data localization mandates in China and India force redundant capital expenditure that platforms recover through tiered service architectures.
Pricing Analysis
Distributor margins for theatrical exhibition networks absorb 40-55 percent of gross ticket revenue in consolidated South Korean and Japanese markets, while direct-to-platform licensing deals bypass traditional windowing in India's price-sensitive corridors. Three-tier pricing structure across premium, standard, and economy levels aligns with device capability segmentation—4K HDR tiers command 2.5-3x mobile-only rates. Cost compression in ad-supported tiers is intensifying because regional-language advertising inventory undersupplies demand from FMCG brands targeting Vietnam and Indonesia. Subscription models face highest price sensitivity in India's tier-2 cities, where family-sharing plans reduce effective per-user revenue below standalone mobile tiers.
Supply Chain Analysis
Cloud rendering capacity rests on hyperscaler infrastructure concentrated in Singapore, Tokyo, and Sydney availability zones, with edge nodes proliferating in Jakarta, Manila, and Bangkok to meet sub-50 millisecond latency thresholds. Content delivery networks draw from submarine cable landings and terrestrial fiber backbones, while original production pipelines depend on camera equipment from Japanese manufacturers and post-production software from US-based vendors. Single-source vulnerability concentrates in China's SAMR-mandated server localization requirements, which tether cross-border platforms to domestic cloud providers with limited interoperability. Distribution runs through direct ISP partnerships in Southeast Asian mobile-first markets, circumventing traditional broadcast distribution entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APAC media and entertainment functions as a stable compounder anchored by insatiable demand for regional-language content and infrastructure-led platform expansion. Regulatory fragmentation across MIIT, TRAI, and KCC jurisdictions creates persistent compliance moats that favor capital-rich incumbents.
For Market Incumbents: Extend exclusive sports rights aggregation into emerging cricket and esports formats before foreign platforms secure KCC quota compliance. Defend against ByteDance's algorithmic engagement engines by commissioning hyper-localized short-form preview content that reduces marketing production cycles. Vertical integration into cloud rendering farms in Tamil Nadu and Maharashtra production corridors secures cost advantages as BIS standards displace on-premise infrastructure. For New Entrants and Emerging Players: Tier-2 Indian city clusters with Marathi and Telugu language dominance present the most penetrable white space, where advertiser demand for regional inventory exceeds platform supply. Vietnam's underpenetrated streaming base offers comparable entry economics through ad-supported models that sacrifice ARPU for audience scale. Go-to-market execution should prioritize telco bundling partnerships that embed subscription costs in mobile data plans, reducing payment friction in cash-preferred corridors. For Investors and Strategic Acquirers: Consolidation pressure builds where cloud-native talent scarcity in Jakarta, Manila, and Bangkok markets forces acquirers to buy capabilities rather than build them. Long-term viability favors platforms with demonstrated cross-border IP licensing frameworks and K-content or anime export pipelines. Watch for SAMR enforcement actions that fragment exclusivity arrangements as the inflection signal—accelerated multi-platform windowing indicates studio bargaining power shifts that compress platform margins.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Sports Rights Aggregation | Cricket and esports licensing in India and Philippines locks in subscriber retention against churn. |
| Cloud Rendering Farm Deployment | Tamil Nadu and Maharashtra infrastructure investments align with PLI scheme capital attraction. |
| Regional-Language Content Commissioning | Telugu and Marathi original production expands addressable audiences beyond Hindi-centric output. |
| Algorithmic Personalization Investment | ByteDance-style recommendation engines reduce marketing production cycles from days to hours. |
| Multi-DRM Integration Partnership | Widevine-FairPlay-PlayReady reconciliation across fragmented device ecosystems reduces subscriber friction. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with streaming platform executives, broadcast engineers, content licensing directors, and telco partnership leads with secondary validation from TRAI tariff orders, MIIT cloud computing guidelines, KCC spectrum allocations, and SEC filings from listed entertainment conglomerates. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from content production database aggregation.
Segment-weighting approaches distributed value across content type, distribution channel, service type, and technology deployment dimensions, with regional regulatory clusters treated as distinct modeling units. CAGRs derived from trend extrapolation of 5G densification curves, PLI scheme capital deployment trajectories, and cross-border IP licensing velocity. Forecast inputs incorporated cloud infrastructure opex inflation from data localization mandates and ad-supported tier adoption elasticity in price-sensitive markets.
Underlying measurement precision varies by segment; streaming subscription data carries tighter precision than theatrical exhibition estimates where informal ticketing persists. Forecasts reflect assumptions about regulatory enforcement continuity and infrastructure deployment timelines. Material deviation in SAMR antitrust intensity, KCC quota enforcement, or submarine cable capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Middle East and Africa Inflight Entertainment and Connectivity Market
Digital Media
Adult Entertainment Market
Digital Media
Germany Animation, VFX and Post Production Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Latin America Inflight Entertainment and Connectivity Market
Digital Media
Asia Pacific Photography Service Market
Digital Media
North America Webtoons Market
Digital Media
Playout Solutions Market
Digital Media
Media and Entertainment Market
Digital Media
US Webtoons Market
Digital Media
United States Sports Betting Market
Digital Media
Anime Merchandising Market
Digital Media
Mexico Webtoons Market
Digital Media
Stream Hosting Market
Digital Media
Adult Animation Market
Digital Media
Multichannel Network Market