
 Stock Music Software Market | 2026-2036
Stock Music Software Market Size, Share, and Industry Trends Forecast 2026-2036
Stock Music Software Market Insights
The stock music software market is restructuring around a widening gap between premium curated catalogs and mass-commodity audio pools. Epidemic Sound dominates the subscription tier through exclusive artist networks and direct licensing control. Artlist competes on unlimited download models that anchor creator loyalty. Audio Network leverages broadcast-grade metadata standards to sustain premium pricing against cheaper alternatives.
Stock music software encompasses digital platforms for licensing pre-recorded audio tracks, loops, and sound effects through cloud delivery, typically supporting 44.1 kHz/16-bit minimum resolution and embedding standardized ISRC and cue sheet metadata for broadcast compliance. The technology serves commercial media production by reducing clearance time from weeks to minutes. Subscription-based delivery models capture the largest revenue pool by locking in recurring revenue from high-volume users. Music licensing segments carry the highest margins due to complex rights management and exclusivity premiums. DAW plugins represent the fastest-growing product type as producers integrate stock audio directly into native workflows.
The US Copyright Office and EU copyright directives shape royalty structures and platform liability across North America and Europe. The FCC's broadcast standards and EBU loudness specifications (R 128) enforce technical compliance that filters non-certified providers from professional workflows. Stakeholders must monitor evolving AI-generated music regulations and platform licensing terms as synthetic content floods distribution channels.
Market Dynamics
Generative audio synthesis is compressing production timelines and collapsing the traditional value chain between composition and distribution, forcing platforms to rebuild licensing frameworks around synthetic content provenance.
Growth Catalysts
- EU Copyright Directive Article 17:Platform liability rules in Europe accelerate demand for pre-cleared audio catalogs that eliminate rights ambiguity for user-generated content uploads.
- Cloud-native DAW integration:Real-time audio streaming directly into Ableton Live and Logic Pro workflows eliminates download friction and embeds stock libraries into production habits.
- South Korean gaming exports:Seoul-based studios driving triple-A mobile game production consume broadcast-grade sound effects at volume, pulling premium catalog investment.
Market Restraints
- Composer royalty rate volatility:Streaming platform payment structures create unpredictable income streams for exclusive artist networks, destabilizing catalog refresh rates.
- US Copyright Office registration backlogs:Processing delays for sound recording claims extend clearance timelines for original compositions, undermining the speed advantage of stock licensing.
- AI-generated audio substitution:Synthetic music tools from text-to-audio models threaten demand for human-composed loops in commercial advertising segments.
Strategic Opportunities
- Indian creator economy expansion:YouTube and Instagram growth in Mumbai and Bangalore drives demand for affordable regional-language audio assets with localized metadata.
- US Inflation Reduction Act content incentives:Domestic film and television production tax credits expand soundstage construction, increasing need for compliant music licensing infrastructure.
- Spatial audio for AR/VR:Ambisonic format adoption in metaverse platforms creates premium pricing tiers for immersive sound design assets.
Industry Challenges
- ISRC metadata standardization gaps:Inconsistent unique identifier assignment across distributor platforms complicates royalty tracking and creates attribution disputes.
- Legacy broadcast workflow integration:Television networks running Pro Tools HDX systems require custom cue sheet export formats that delay SaaS platform deployment.
- Cross-border rights clearance complexity:Mechanical reproduction rights vary by territory, forcing platforms to maintain parallel licensing structures for sync and master use.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stock Music Software Market |
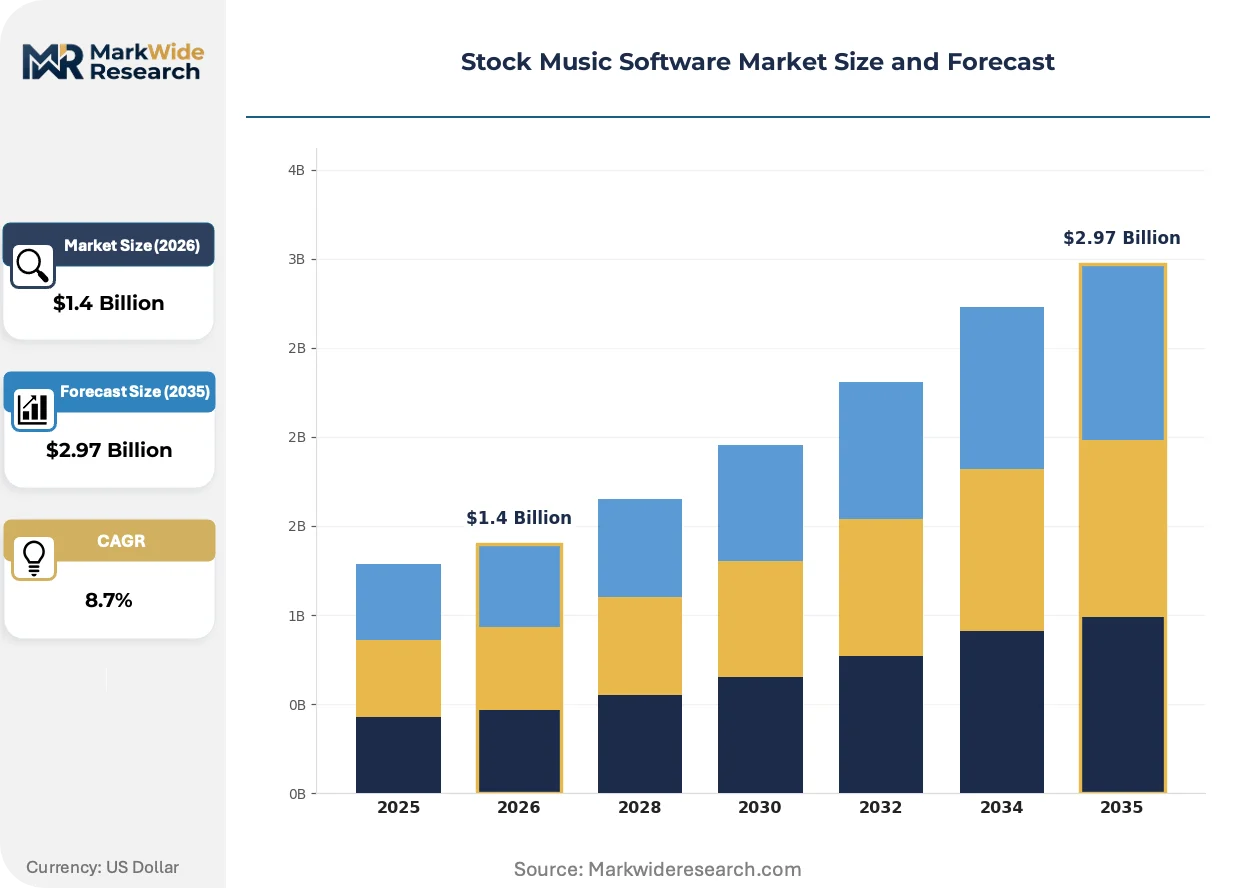
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loop Libraries, Sound Effects, Music Licensing, DAW Plugins Delivery Model: Subscription-Based, Pay-Per-Track, Free Downloads, Bundled Offers End User: Content Creators, Advertising Agencies, Filmmakers, Game Developers Pricing Model: Freemium, Tiered Pricing, One-Time Purchase, Enterprise Licensing |
| Companies Covered | Epidemic Sound, Artlist, Audio Network, Shutterstock Music, AudioJungle (Envato), PremiumBeat, Pond5, Soundstripe, Musicbed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stock Music Software Market Trends and Innovations
Audio procurement is fragmenting across three simultaneous revolutions: synthetic composition tools, embedded workflow delivery, and compliance-driven metadata standards that together redefine how producers source and deploy licensed sound.
Neural audio generation is rewriting the economics of background music production. Text-to-music models from OpenAI and Google now produce broadcast-ready instrumentals in under thirty seconds. Advertising agencies in London and New York are piloting these tools for rush campaigns, compressing what required human composers and clearance lawyers into automated workflows. The structural consequence is a bifurcation between commodity audio pools and premium human-composed exclusives.
REACH chemical substance restrictions and the EU AI Act are reshaping hardware and software compliance obligations for audio technology vendors. The AI Act's transparency requirements for synthetic content force platforms to embed provenance metadata into every generated track. German broadcasters operating under ARD and ZDF standards now demand machine-readable certificates of origin, filtering out non-compliant providers from RFP processes.
Subscription fatigue among freelance video editors is fragmenting purchasing patterns across micro-licensing and tiered credit systems. Individual creators on Fiverr and Upwork increasingly prefer per-track purchases over recurring commitments, reversing the SaaS consolidation of the past decade. This behavioral shift is most visible in the United States, where gig-economy production volumes exceed corporate accounts, and platforms are unbundling unlimited download tiers into usage-based pricing.
Stock Music Software Market Segmentation
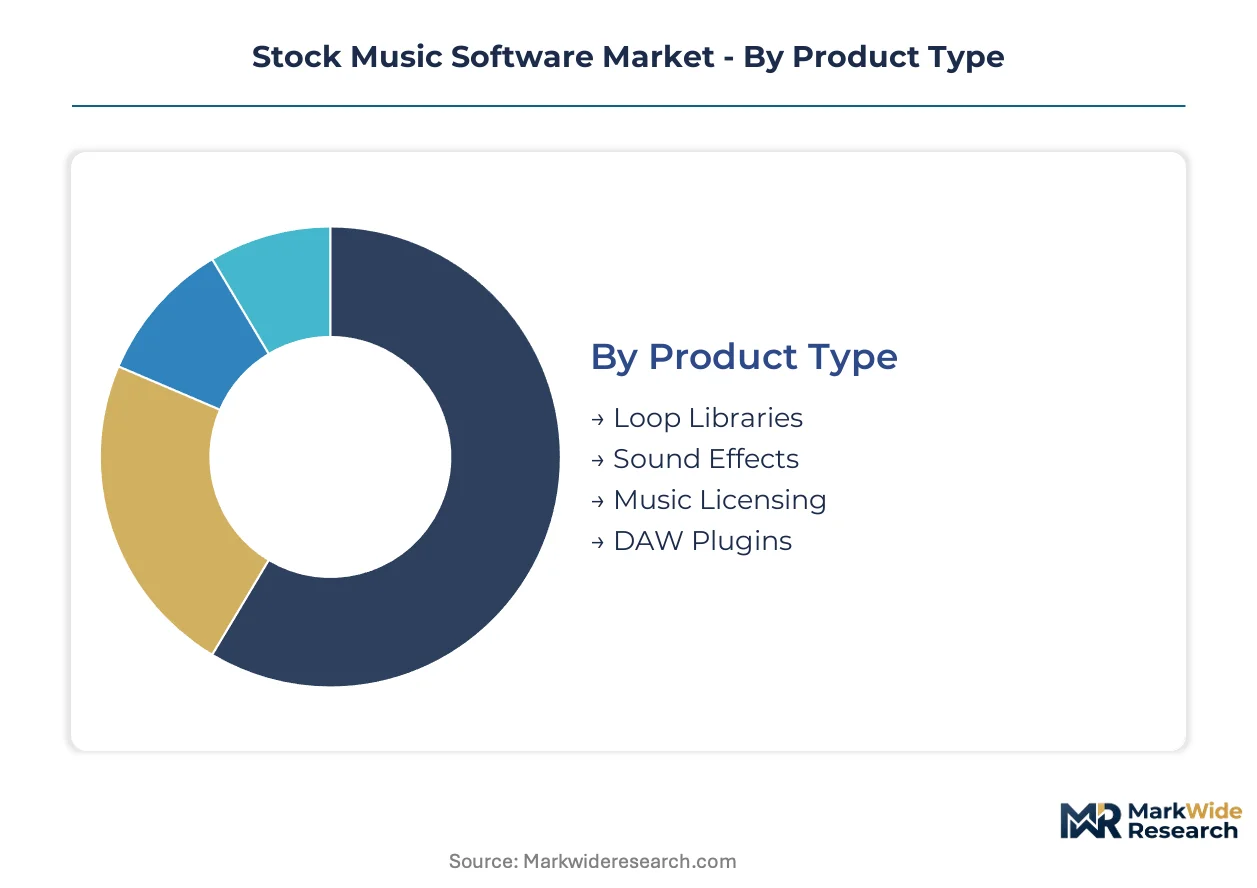
Stock music software vendors architect product portfolios around distinct technical integration points and procurement workflows. Segment boundaries reflect how deeply audio assets embed into production pipelines versus standalone access patterns.
Product Type:
Integration depth separates standalone browser-based libraries from native DAW extensions that eliminate context-switching during composition workflows.
- Music Licensing:Pre-cleared sync and master rights for commercial tracks, typically delivered at 48 kHz/24-bit for broadcast compliance. Advertising agencies in Germany and the United States consume these assets for campaign clearance speed, though composer royalty volatility destabilizes exclusive catalog refresh rates.
- DAW Plugins:Native extensions for Ableton Live, Logic Pro, and Pro Tools that stream audio directly into arrangement timelines. Seoul-based game studios and Los Angeles post-production houses drive adoption as embedded procurement reduces download friction and embeds libraries into habitual workflows.
- Loop Libraries:Rhythmic and melodic building blocks for electronic music production, delivered as WAV or REX2 files with tempo-synced metadata.
- Sound Effects:Foley and designed audio elements for film, television, and interactive media, often bundled with descriptive metadata for rapid search.
Music licensing leads volumes today; DAW plugins are gaining share fastest.
Delivery Model:
Cost tier structures separate predictable recurring commitments from variable usage-based procurement that matches freelance income volatility.
- Subscription-Based:Unlimited download tiers with monthly or annual billing cycles, locking in recurring revenue from high-volume production houses. Content creators across YouTube and Instagram in Mumbai and Bangalore prefer these models for budget predictability, though subscription fatigue among gig-economy editors is fragmenting purchasing patterns toward micro-licensing alternatives.
- Pay-Per-Track:Individual asset purchases without recurring commitment, priced per resolution tier and usage rights scope. Freelance video editors on Fiverr and Upwork in the United States increasingly favor this flexibility over SaaS consolidation.
- Free Downloads:Limited-quality assets with attribution requirements, serving as funnel entry points for premium conversion.
- Bundled Offers:Pre-packaged collections tied to specific genres, moods, or production genres, often discounted against à la carte pricing.
Subscription-based delivery commands the largest revenue pool; pay-per-track is expanding most quickly among independent creators.
End User:
Application specialization drives feature differentiation between high-frequency content mills and premium campaign producers with exacting compliance requirements.
- Content Creators:Individual YouTubers, podcasters, and social media producers requiring rapid, affordable clearance for high upload volumes. This segment concentrates in the United States and India, where platform monetization incentives accelerate demand for regional-language audio assets with localized metadata.
- Game Developers:Interactive media studios requiring adaptive music systems and spatial audio formats for immersive environments. South Korean exports of triple-A mobile titles pull premium catalog investment in broadcast-grade sound effects.
- Advertising Agencies:Creative shops producing campaign audio with tight turnaround timelines and brand safety requirements.
- Filmmakers:Independent and studio productions requiring cue sheet automation and PRO registration support for theatrical and streaming distribution.
Content creators dominate transaction volumes today; game developers are climbing the fastest on per-seat spending growth.
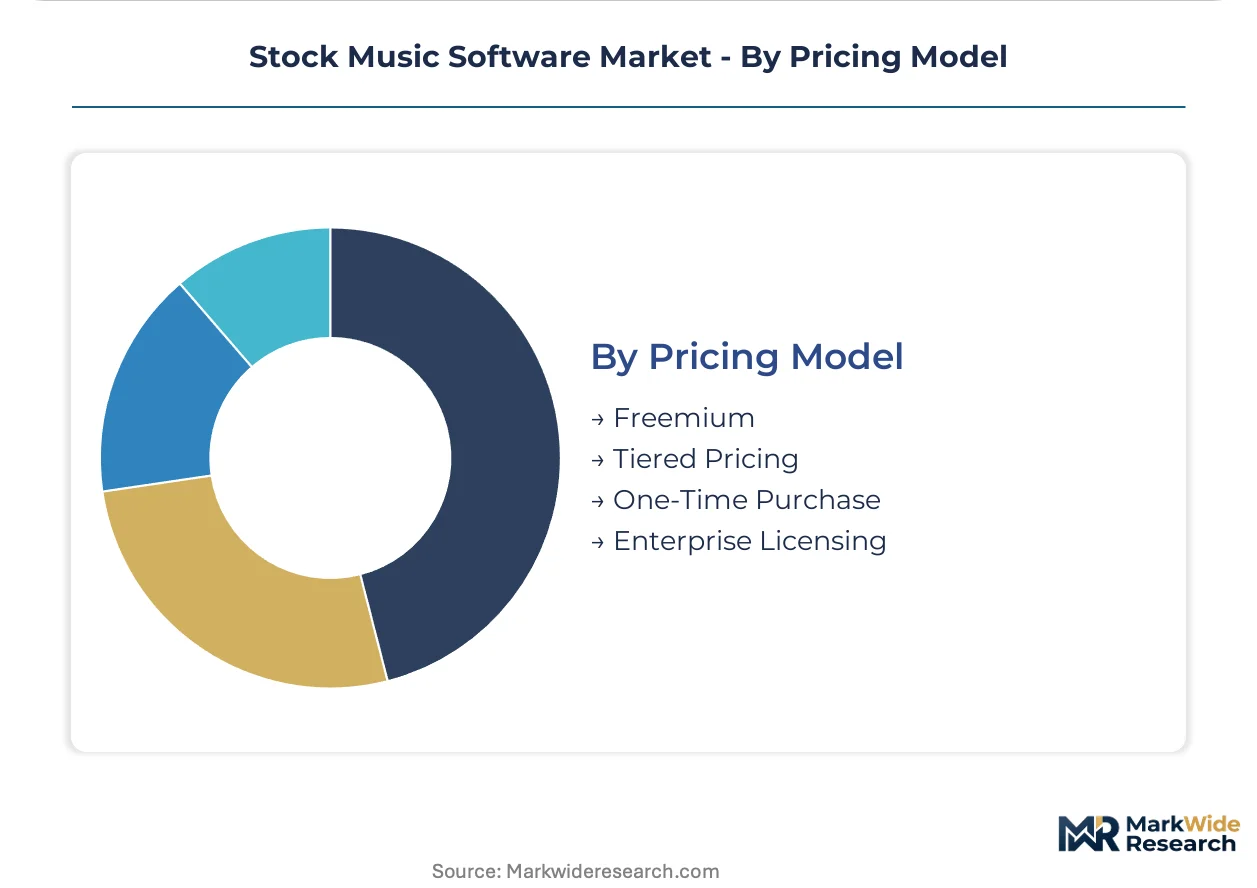
Pricing Model:
Customer type and maturity determine whether vendors capture value through tiered feature gates, usage scaling, or enterprise negotiation.
- Tiered Pricing:Three-level differentiation across personal, professional, and studio tiers with graduated rights packages and audio quality specifications. This structure aligns procurement cost with production scale, though mid-tier positioning requires careful calibration against both freemium conversion and enterprise discount pressure.
- Enterprise Licensing:Custom negotiations for media conglomerates and broadcast networks with volume guarantees, indemnification clauses, and dedicated account management. Domestic film production tax credits under the US Inflation Reduction Act expand soundstage construction, increasing need for compliant music licensing infrastructure at this tier.
- Freemium:Zero-cost entry with premium unlocks for commercial rights, higher resolution, or expanded catalog access.
- One-Time Purchase:Perpetual licenses for specific asset collections, increasingly rare as vendors prioritize recurring revenue models.
Tiered pricing leads adoption today; enterprise licensing shows the steepest expansion trajectory as consolidation among media buyers concentrates purchasing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates subscription revenue from freelance creators, while South Korea pulls premium catalog investment through triple-A game studio demand. Germany enforces broadcast-grade metadata standards that filter non-compliant providers. India and the United Kingdom round out demand centers with diverging creator economy and advertising agency procurement patterns.
United States
YouTube and Instagram monetization incentives drive individual creator demand for rapid audio clearance. The FCC enforces broadcast standards that professional workflows must meet. Los Angeles post-production houses integrate DAW-native streaming to eliminate download friction.
Germany
ARD and ZDF broadcasters demand machine-readable certificates of origin for synthetic content. The EU AI Act transparency requirements reshape platform compliance obligations. Berlin-based advertising agencies pilot generative audio tools while maintaining premium human-composed catalog subscriptions.
South Korea
Seoul-based mobile game studios consume broadcast-grade sound effects at volume for export titles. The national copyright framework supports rapid rights clearance for interactive media. Busan-Ulsan development clusters anchor adaptive music system procurement.
India
Mumbai and Bangalore content creators seek regional-language audio assets with localized metadata. The country's national media regulator shapes platform licensing terms for user-generated content. Domestic production volumes on YouTube exceed corporate accounts, fragmenting purchasing patterns toward pay-per-track models.
United Kingdom
London advertising agencies compress campaign timelines through pre-cleared sync rights. The national copyright office maintains sound recording registration standards. Post-production facilities in Soho demand cue sheet automation for theatrical and streaming distribution.
Stock Music Software Market Competitive Landscape
Top-tier vendors anchor subscription-based delivery with exclusive artist networks, while mid-tier competitors compete on unlimited download models and metadata sophistication. The market structure concentrates around three strategic archetypes: premium curated catalogs, mass-commodity audio pools, and workflow-integrated plugin providers. Dominant competitive moves include exclusive licensing control and native DAW integration partnerships.
Within the premium curated catalog tier, Epidemic Sound and Artlist exemplify divergent approaches to creator retention. Audio Network occupies a position among broadcast-grade specialists serving advertising agencies with compliance-driven metadata standards. These three companies represent the strategic spectrum from exclusive artist control to unlimited download anchoring to premium rights management infrastructure.
| Leading Market Players |
|---|
| Epidemic Sound |
| Artlist |
| Audio Network |
| Shutterstock Music |
| AudioJungle (Envato) |
| PremiumBeat |
| Pond5 |
| Soundstripe |
| Musicbed |
| Others |
Pricing and Supply Chain Analysis
Composer talent clusters in Los Angeles, Stockholm, and Seoul generate labor-cost differentials that widen pricing spreads between premium exclusive catalogs and mass-commodity audio pools. Royalty rate volatility for exclusive artist networks destabilizes cost structures, forcing platforms to tier subscription pricing around clearance speed and metadata sophistication rather than audio quality alone.
Pricing Analysis
Bundled unlimited-download subscriptions anchor the high end while unbundled pay-per-track models capture price-sensitive freelance editors. Three-tier pricing separates enterprise licensing with indemnification clauses from professional tiers with broadcast metadata and personal tiers with attribution requirements. Cost compression in the mid-market intensifies because AI-generated audio tools substitute human-composed loops for rush advertising campaigns. Gig-economy video editors on Fiverr and Upwork exhibit highest price sensitivity; broadcast networks running Pro Tools HDX systems show least.
Supply Chain Analysis
Warehouse-distribution layers for audio assets have dissolved entirely as cloud-native delivery replaces physical media logistics. Supply concentrates in the United States, Sweden, and South Korea where exclusive composer networks and broadcast-grade mastering facilities cluster. Raw material dependencies rest on proprietary metadata schemas, ISRC registration infrastructure, and DAW integration SDKs. Single-source vulnerability sits with dominant cloud infrastructure providers hosting streaming audio delivery. Distribution runs through API-first platforms embedded directly into Ableton Live, Logic Pro, and Pro Tools workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as content creator volumes across streaming platforms institutionalize recurring licensing spend. The underlying demand driver is irreversible: professional and amateur producers alike require instantaneous clearance to maintain upload cadence.
For Market Incumbents: Anticipate generative audio substitution by locking exclusive composer networks through revenue-share guarantees that stabilize catalog refresh rates. Invest in backward integration into AI training data licensing to control synthetic content provenance. Defend against mid-tier unlimited-download competitors by deepening DAW-native integration partnerships that embed procurement into habitual workflows.
For New Entrants and Emerging Players: Regional-language content creators in Mumbai and Bangalore represent an underserved buyer archetype with localized metadata requirements that incumbent Western platforms neglect. White-space targets include affordable per-track micro-licensing for Indian YouTube channels and spatial audio assets for Seoul-based AR/VR studios. The most penetrable entry point is pay-per-track models with regional payment methods.
For Investors and Strategic Acquirers: Cloud-native DAW platform operators are the most active acquirer in this space as they seek to verticalize audio procurement into composition workflows. Long-term viability hinges on exclusive catalog control and metadata infrastructure that satisfies EU AI Act transparency requirements. The signal to watch is composer royalty rate stabilization agreements that predict sustainable exclusive network expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Artist Network Expansion | Locks differentiated catalog supply against AI-generated audio substitution in advertising segments. |
| DAW-Native Plugin Development | Embeds procurement into Ableton Live and Logic Pro workflows, reducing customer churn. |
| AI Provenance Metadata Infrastructure | Satisfies EU AI Act transparency requirements for German ARD and ZDF broadcaster compliance. |
| Regional Language Catalog Localization | Captures Mumbai and Bangalore creator economy growth with culturally specific audio assets. |
| Spatial Audio Format Investment | Creates premium pricing tiers for ambisonic assets serving Seoul-based AR/VR game studios. |
Research Methodology
Multiple input streams — executive interviews at stock music platforms, composer guild representatives, and broadcast network music supervisors — were reconciled against secondary validation from SEC filings, EU copyright directive implementation reports, and DAW integration partnership announcements. Primary fieldwork captured procurement workflow preferences across advertising agencies in London, post-production houses in Los Angeles, and game studios in Seoul. Secondary sources included FCC broadcast standards documentation, EBU R 128 loudness specifications, and cloud infrastructure capex disclosures. Bottom-up transaction volume estimates triangulated against top-down addressable creator economy spend.
Data-stream reconciliation applied across the analysis window modeled segmentation by delivery model, end-user archetype, integration depth, and regional regulatory cluster. CAGRs derived from compound growth assumptions applied to disclosed subscriber counts and average revenue per user benchmarks. Industry-specific forecast inputs incorporated YouTube and Instagram monetization incentive trajectories, South Korean gaming export volumes, and EU Copyright Directive Article 17 implementation timelines.
Underlying measurement precision varies by segment; subscription-based delivery and enterprise licensing carry tighter precision than emerging AI-generated audio categories. Forecasts reflect documented assumptions around composer royalty rate stability and platform liability rule evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Volumetric Video Market
Digital Media
Digital Media Switchers Market
Digital Media
Media Coding Service Market
Digital Media
Animation and VFX Market
Digital Media
Animation Services Market
Digital Media
South Korea Webtoons Market
Digital Media
Global ACGN Market
Digital Media
IP in Media and Entertainment Market
Digital Media
Online Entertainment Market
Digital Media
Entertainment Market
Digital Media
Anime Streaming Tool Market
Digital Media
Asia-Pacific Webtoons Market
Digital Media
Digital Media Production Software Market
Digital Media
Europe Anime Merchandising Market
Digital Media
Pro AV Market
Digital Media
Playout Solutions Market