
 APAC Animation, VFX and Post Production Market | 2026-2036
APAC Animation, VFX and Post Production Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Animation, VFX and Post Production Market Insights
ISO/IEC 27001 certification for digital content security is redrawing vendor qualification standards across major studio procurement. Animal Logic leverages its Sydney-based infrastructure to anchor premium feature animation pipelines for Hollywood clients. DNEG competes on scale in Mumbai and Chennai, where its workforce concentration controls episodic VFX cost structures. Technicolor Creative Studios navigates fragmented client demands across advertising, gaming, and streaming verticals without dominant geographic lock-in.
Animation, VFX and post production encompass the creation, manipulation, and finishing of moving image content through digital frame generation, optical compositing, and color grading pipelines operating at 4K to 8K resolution. The primary purpose is delivering finished visual media for theatrical exhibition, broadcast transmission, and over-the-top streaming distribution. Visual effects services lead revenue contribution where feature film and high-end episodic budgets sustain premium per-shot economics. Game developer clients represent the fastest-growing client type as real-time engine integration blurs pre-rendered and interactive production workflows. Post production for commercials remains mature with compressed turnaround cycles limiting margin expansion.
India's BIS content localization mandates and South Korea's MFDS digital health visualization standards shape technical compliance requirements for cross-border deliverables. Japan's METI content export subsidies and China's SAMR anti-monopoly scrutiny of platform exclusivity deals alter market access conditions for independent studios. Stakeholders must monitor how generative AI training data regulations across Australia, Singapore, and Japan reshape copyright liability and talent contracting structures.
Market Dynamics
Real-time engine integration is compressing production timelines across APAC animation pipelines, forcing traditional render farms to coexist with Unreal Engine and Unity workflows while talent pools retool for hybrid technical competencies.
Growth Catalysts
- Streaming platform commissioning acceleration:Netflix, Disney+, and regional platforms in India and Southeast Asia are greenlighting animated series at volumes that sustain dedicated production facilities in Mumbai and Bengaluru.
- South Korea's immersive technology tax credits:The Ministry of Economy and Finance offers refundable credits for virtual production stages, attracting co-productions from Hollywood studios seeking cost arbitrage.
- Japan's METI digital content export subsidies:These grants cover localization and marketing costs for anime distributors targeting non-Asian markets, expanding addressable audience bases.
Market Restraints
- Render compute cost volatility:GPU and cloud instance pricing fluctuations squeeze project margins for mid-tier VFX houses in Chennai and Kuala Lumpur.
- ISO/IEC 27001 certification concentration:Only studios with Sydney, Singapore, or Tokyo infrastructure meet major studio security mandates, excluding smaller facilities from premium tier work.
- Generative AI training data liability ambiguity:Unclear copyright frameworks across Australia, Japan, and Singapore delay adoption of AI-assisted inbetweening and rotoscoping tools.
Strategic Opportunities
- Indonesia's underpenetrated production base:Jakarta's emerging talent pipeline and lower labor costs offer first-mover advantages for episodic animation capacity.
- Game engine convergence with broadcast:Real-time compositing for live sports graphics and virtual sets creates new revenue streams for post houses with Unreal technical directors.
- China's SAMR platform exclusivity scrutiny:Reduced vertical integration by streaming platforms may open commissioning opportunities for independent studios previously locked out.
Industry Challenges
- Pipeline TD skill scarcity:Shortage of technical directors fluent in both legacy Maya pipelines and real-time engine scripting limits hybrid production scaling.
- 4K to 8K deliverable infrastructure:Color grading suites and review infrastructure require capital outlays that strain independent post houses in secondary cities.
- BIS localization compliance timelines:India's mandatory dubbing and subtituring standards compress delivery schedules for international co-productions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Animation, VFX and Post Production Market |
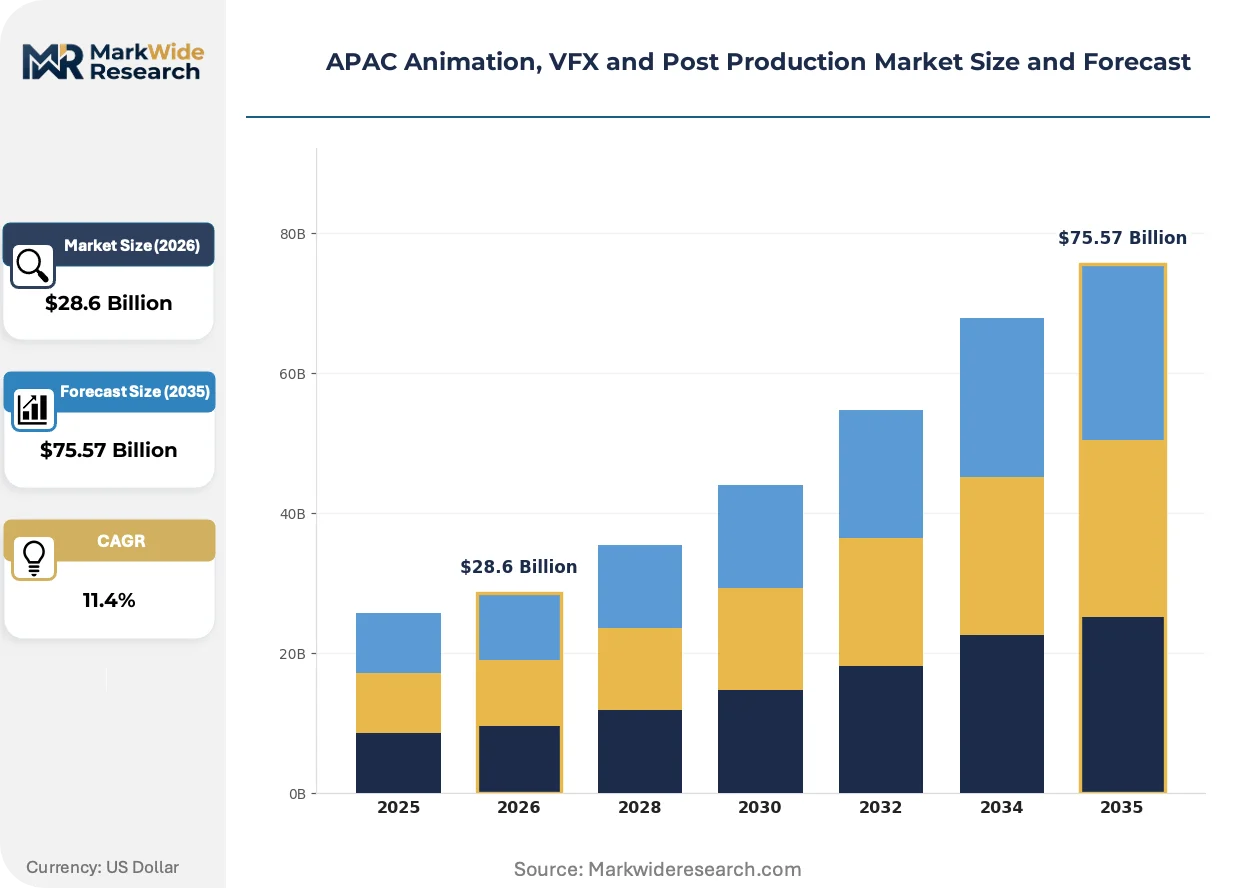
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
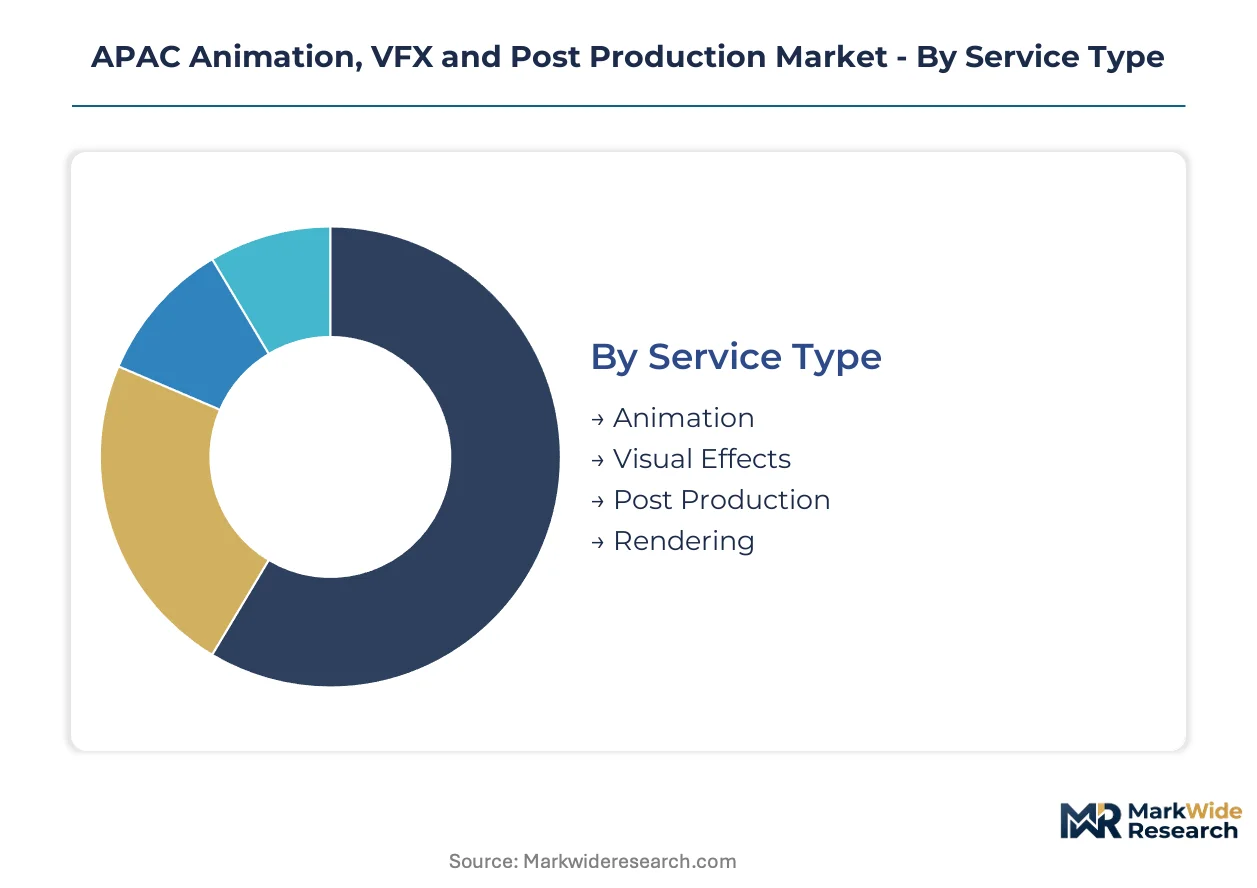
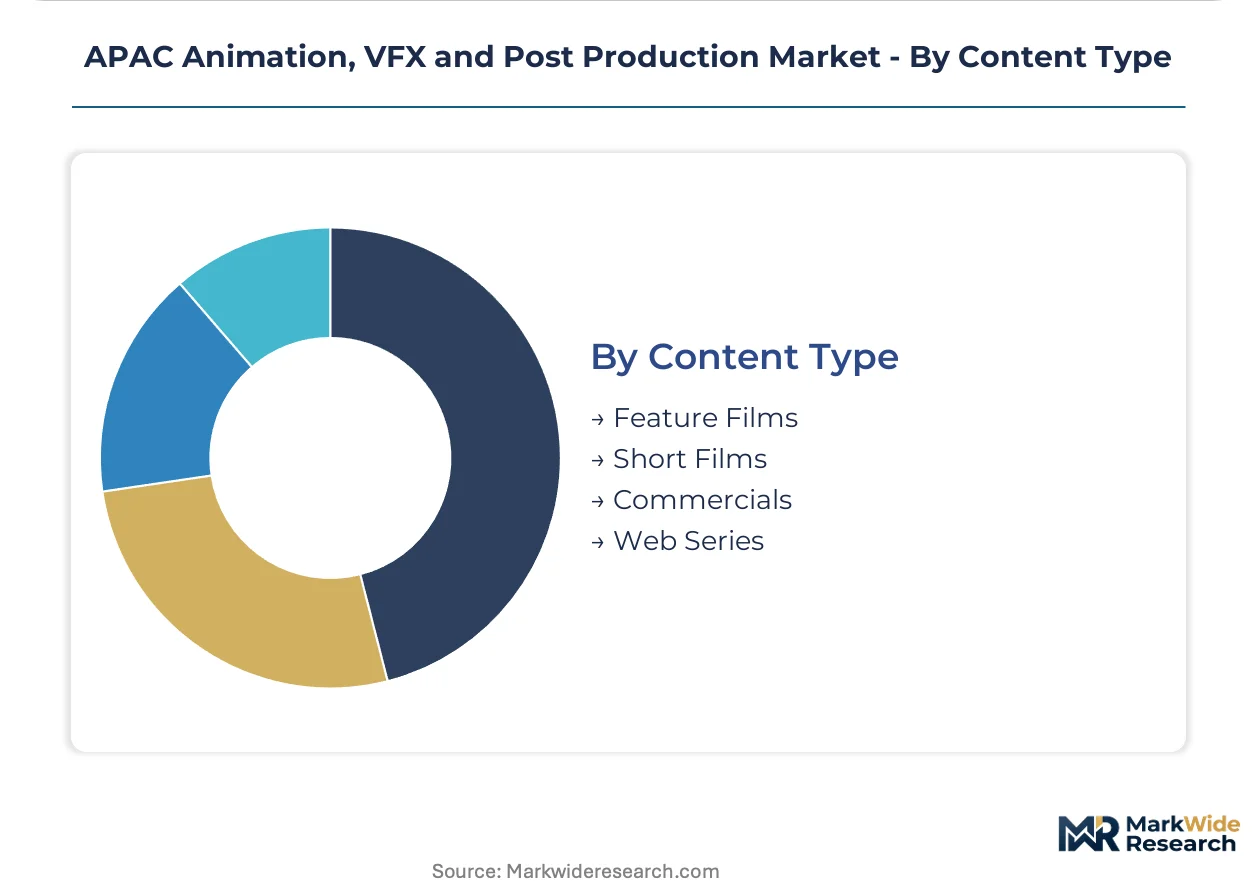
| Segmentation | Service Type: Animation, Visual Effects, Post Production, Rendering Client Type: Film Studios, Game Developers, Advertising Agencies, TV Networks Technology: 3D Animation, Motion Capture, Compositing, VR Production Content Type: Feature Films, Short Films, Commercials, Web Series |
| Companies Covered | Makuta Effects Pvt. Ltd., Animal Logic, DNEG, Technicolor Creative Studios, Framestore, Studio Ghibli, Moving Picture Company, Scanline VFX, Rodeo FX, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Animation, VFX and Post Production Market Trends and Innovations
Virtual production stages are proliferating across APAC facilities, displacing location shoots and demanding new competencies in LED volume operation, camera tracking, and real-time cinematography that reshape hiring patterns and equipment procurement.
Neural radiance fields (NeRF) for volumetric capture is miniaturizing asset creation workflows. Boutique VFX shops in Seoul and Taipei are adopting NeRF-based photogrammetry to generate 3D environments from sparse image sets without dedicated scanning stages. This compression of capture infrastructure is enabling smaller facilities to bid on premium environment work previously requiring dedicated volume stages.
Japan's METI content security guidelines for international co-productions are mandating watermarking and access logging standards that exceed legacy MPAA protocols. Studios in Tokyo must now deploy forensic tracking on all pre-release materials shared with offshore vendors. The compliance burden falls heaviest on mid-size animation houses without dedicated information security officers, driving consolidation toward larger integrated groups.
Commissioning patterns from streaming platforms are fragmenting across shorter pilot cycles and direct-to-series orders that bypass traditional development slates. Buyers in Singapore and Bangkok now demand animatics and previs deliverables within eight-week windows that compress pre-production planning. This velocity shift favors facilities with in-house storyboard and editorial departments in Manila and Ho Chi Minh City over pure execution houses.
APAC Animation, VFX and Post Production Market Segmentation
Segmentation in APAC animation, VFX and post production reveals how margin pools concentrate across service tiers and client sophistication levels. Technical capability gaps between premium and standard tiers are widening as real-time engines and generative AI reshape production economics.
Service Type:
Margin pools concentrate in visual effects and premium animation where per-shot economics sustain specialized talent retention.
- Visual Effects:Optical compositing, particle simulation, and digital environment creation for feature films and high-end episodic content. Demand concentrates in Mumbai and Chennai where DNEG and Indian mid-tier houses compete on scale for Hollywood streaming commissions, constrained by ISO/IEC 27001 certification requirements that exclude smaller facilities from premium tier work.
- Animation:Digital frame generation through 2D vector pipelines, 3D rigging, and character performance systems. Japanese studios in Tokyo anchor anime production for international export under METI subsidy programs, while Indian facilities in Bengaluru handle episodic series for Disney+ Hotstar and regional platforms.
- Post Production:Color grading, editorial finishing, and deliverable mastering at 4K to 8K resolution. Facilities in Sydney and Singapore command premium rates for theatrical distribution compliance.
- Rendering:Cloud and on-premise compute farms for final frame generation. GPU pricing volatility squeezes margins for houses in Kuala Lumpur and Jakarta without long-term cloud contracts.
The dominant share belongs to Visual Effects, while Animation is closing the gap fastest through streaming platform volume commitments.
Client Type:
Cost tier stratification separates enterprise studios with dedicated vendor relationships from project-based buyers negotiating spot rates.
- Film Studios:Major theatrical distributors and streaming platform content divisions commissioning feature-length animation and VFX-heavy productions. Hollywood co-productions favor South Korean facilities accessing immersive technology tax credits for virtual production stages.
- Game Developers:Interactive entertainment publishers integrating real-time engine assets with pre-rendered cinematic sequences. This segment is expanding most quickly as Unreal Engine and Unity workflows blur distinctions between game and linear production pipelines.
- Advertising Agencies:Commercial production houses demanding compressed turnaround cycles for brand campaigns. Post houses in Bangkok and Manila compete on speed rather than margin.
- TV Networks:Broadcasters and regional streaming platforms commissioning episodic animation and live-action VFX. India's BIS localization mandates compress delivery schedules for international co-productions.
Film Studios retain the largest contract values, though Game Developers show the steepest expansion trajectory through engine convergence.
Technology:
Application focus determines capital intensity, with motion capture and VR production requiring specialized infrastructure investments.
- 3D Animation:Polygonal modeling, rigging, and keyframe performance systems for character-driven content. Facilities across Beijing and Shanghai anchor China's production axis for domestic theatrical releases.
- Motion Capture:Optical and inertial tracking for performance-driven character animation. South Korean volumes in Seoul attract Hollywood productions seeking cost arbitrage on virtual production stages.
- Compositing:Layer-based and node-based image integration for live-action and CG element merging. Talent scarcity in hybrid Nuke-Blender pipelines limits scaling in secondary cities.
- VR Production:Stereoscopic rendering and interactive environment creation for immersive distribution. Boutique shops in Taipei adopt NeRF-based photogrammetry to miniaturize asset creation workflows.
3D Animation holds established volume leadership, while Motion Capture gains share fastest through virtual production adoption.
Content Type:
Maturity curves separate established formats with predictable delivery standards from emerging categories with evolving technical specifications.
- Feature Films:Theatrical and streaming platform releases demanding 4K to 8K deliverables with HDR color pipelines. Animal Logic's Sydney infrastructure anchors premium Hollywood animation pipelines.
- Web Series:Direct-to-streaming episodic content with compressed production schedules and platform-specific technical requirements. Commissioning velocity from Netflix and regional platforms favors Manila and Ho Chi Minh City facilities with integrated storyboard departments.
- Commercials:Brand advertising content with rapid turnaround cycles limiting margin expansion. Post production for this segment remains mature across Singapore and Bangkok.
- Short Films:Festival and platform-commissioned content serving as talent development pipelines. Independent studios in Jakarta leverage lower labor costs for pilot production.
Feature Films command the highest per-minute production values, though Web Series demonstrates the most rapid volume acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai-Bengaluru production corridor anchors India's animation infrastructure through dedicated fiber links connecting cloud render farms to Hollywood studio review suites. This digital backbone sustains 24-hour production cycles across time zones.
India
Streaming platform commissioning from Disney+ Hotstar and Netflix India drives facility expansion in Mumbai and Bengaluru. BIS mandates dubbing and subtituring standards for all imported content, compressing delivery schedules for international co-productions. Chennai houses DNEG's largest workforce concentration outside London, controlling episodic VFX cost structures for Hollywood clients.
China
Domestic theatrical releases and platform exclusivity deals fuel demand across Beijing and Shanghai production axes. SAMR scrutiny of vertical integration by streaming platforms alters market access for independent studios previously locked out of commissioning. The Yangtze River Delta cluster concentrates 3D animation capacity for domestic feature films.
Japan
Anime export demand to non-Asian markets accelerates under METI digital content promotion policies covering localization and marketing grants. Tokyo studios deploy forensic watermarking and access logging exceeding legacy MPAA protocols for international co-productions. The Kanto region anchors premium feature animation pipelines serving Hollywood clients.
South Korea
Virtual production stage investments attract Hollywood co-productions seeking cost arbitrage through immersive technology tax credits from the Ministry of Economy and Finance. Seoul volumes specialize in motion capture and LED stage operation for real-time cinematography. The Busan-Ulsan corridor develops secondary capacity for episodic content.
Australia
Sydney infrastructure commands premium rates for theatrical distribution compliance and ISO/IEC 27001-certified digital content security. Animal Logic leverages this facility base for Hollywood feature animation pipelines. The Pacific fiber link to Los Angeles enables synchronous review sessions with West Coast studio executives.
APAC Animation, VFX and Post Production Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with public entities accessing capital markets for render farm expansion while private houses retain operational flexibility. The vendor base stratifies between ISO/IEC 27001-certified premium facilities and uncertified execution houses excluded from major studio procurement. Three archetypes dominate: scale-driven episodic specialists, premium feature animation anchors, and diversified post-production integrators. Competitive moves center on M&A for certification acquisition and strategic partnerships for real-time engine integration.
Among premium-tier animation houses, Animal Logic occupies a position exemplifying Sydney-based infrastructure deployment for Hollywood theatrical pipelines. DNEG represents the scale-driven archetype through workforce concentration in Mumbai and Chennai serving episodic VFX demand. Technicolor Creative Studios sits within the diversified integrator tier, navigating fragmented client demands across advertising, gaming, and streaming verticals without dominant geographic lock-in.
| Leading Market Players |
|---|
| Makuta Effects Pvt. Ltd. |
| Animal Logic |
| DNEG |
| Technicolor Creative Studios |
| Framestore |
| Studio Ghibli |
| Moving Picture Company |
| Scanline VFX |
| Rodeo FX |
| Others |
Pricing and Supply Chain Analysis
Eighteen-week pilot-to-animatic cycles compress inventory buffers across Mumbai and Manila facilities, concentrating pricing power with studios possessing integrated storyboard departments while squeezing margin recovery for pure-execution houses dependent on spot-rate cloud rendering.
Pricing Analysis
Volume-discount tiering structures separate ISO/IEC 27001-certified premium facilities in Sydney and Singapore from uncertified execution houses in Chennai and Kuala Lumpur. Pricing stratifies across premium, standard, and economy tiers where certification grade and per-shot VFX complexity drive differentiation. Cost compression in mid-tier episodic work is intensifying because GPU instance pricing volatility erodes project margins. Advertising agencies in Bangkok demonstrate highest price sensitivity through compressed turnaround demands, while Hollywood co-productions accessing South Korean tax credits show lowest sensitivity to per-shot rates.
Supply Chain Analysis
Just-in-time render farm provisioning dominates facility planning, with studios avoiding capital-intensive on-premise GPU clusters in favor of elastic cloud contracts that scale with commissioning velocity. Supply concentrates in India, South Korea, and Australia where talent pipelines and certification infrastructure anchor production capacity. Raw material dependencies center on NVIDIA A100/H100 GPU allocations, LED volume stage components, and optical motion capture systems. Single-source vulnerability in cloud instance provisioning from hyperscalers creates supply chain risk during demand spikes. Distribution runs through platform-direct commissioning relationships that bypass traditional aggregator intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI inbetweening tools threaten labor-intensive animation workflows, forcing incumbents to defend substitution through capability differentiation rather than cost competition alone.
For Market Incumbents: Fortify certification moats by accelerating ISO/IEC 27001 acquisition for secondary facilities in Bengaluru and Jakarta, locking out mid-tier competitors from premium Hollywood streaming commissions. Deepen backward integration into real-time engine technical direction, capturing hybrid pipeline margins as Unreal Engine and Unity workflows displace legacy Maya render farms.
For New Entrants and Emerging Players: Lead with NeRF-based volumetric capture services in Taipei and Seoul, exploiting miniaturized asset creation workflows that bypass dedicated scanning stage investments. Indonesia's underpenetrated production base offers first-mover advantages for episodic animation capacity serving Southeast Asian platform commissioning. Position through direct-to-streaming pilot development partnerships that compress traditional development slates.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because certification concentration and real-time engine capital requirements favor scaled integrated groups over fragmented independent studios. Target mid-size animation houses in Tokyo lacking dedicated information security officers, where METI compliance burdens drive distressed acquisition opportunities. Watch generative AI training data liability clarity across Australia, Japan, and Singapore as the signal for accelerated AI-assisted production adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 27001 Certification Acquisition | Unlocks premium tier Hollywood studio procurement previously restricted to Sydney and Singapore facilities. |
| Real-Time Engine Technical Direction Investment | Captures hybrid pipeline margins as Unreal Engine workflows displace traditional render farm economics. |
| Virtual Production Stage Buildout | Accesses South Korean immersive technology tax credits attracting Hollywood co-production cost arbitrage. |
| NeRF-Based Photogrammetry Capability | Enables boutique VFX shops to bid on premium environment work without dedicated volume stage capital. |
| Integrated Storyboard Department Expansion | Meets eight-week animatic delivery windows demanded by Singapore and Bangkok streaming platform buyers. |
Research Methodology
The analysis maps visual effects, animation, post production, and rendering sub-sectors, each validated through studio operations executives, streaming platform content commissioners, post house technical directors, and cloud infrastructure procurement leads. Primary interviews with these stakeholders combined with secondary validation against SEC filings from listed production groups, BIS and METI regulatory documentation, and hyperscaler capex disclosures. Bottom-up facility capacity modeling and top-down platform commissioning value triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projection outputs across the modeling period. The analytical framework segmented by service type, client sophistication tier, technology application, and content format, with CAGRs derived from fitted growth curves against historical commissioning velocity. Real-time engine adoption rates and generative AI regulatory clarity served as industry-specific forecast inputs alongside streaming platform content budget trajectories.
The analysis sits within stated boundaries; outcomes outside sustained streaming platform commissioning acceleration or resolved AI training data liability frameworks would require recalibration. Forecasts reflect documented assumptions regarding tax credit continuity and cloud pricing stabilization. Revision becomes warranted when GPU supply constraints or platform exclusivity enforcement crosses thresholds altering facility economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Online Movie Market
Digital Media
Europe Professional Audio Video (Proav) Market
Digital Media
Global Animation Market
Digital Media
VFX Market
Digital Media
Asia-Pacific Webtoons Market
Digital Media
Secondary Ticket Market
Digital Media
Global Transport Media Market
Digital Media
Online Gambling Market
Digital Media
Wedding Photography Market
Digital Media
Indonesia Digital Media Market
Digital Media
Media and Entertainment Market
Digital Media
Webcomics Market
Digital Media
Digital Audio Workstation (DAW) Market
Digital Media
Information Short Video Market
Digital Media
US Animation, Vfx and Post Production Market
Digital Media
Europe Anime Merchandising Market