
 Independent Music Publishing Market | 2026-2036
Independent Music Publishing Market Size, Share, and Industry Trends Forecast 2026-2036
Independent Music Publishing Market Insights
Digital audio formats are broadening the addressable catalog value for independent publishers, replacing physical-media royalty structures with streaming-centric models. Kobalt leverages proprietary royalty-tracking technology to capture transparent payment flows for songwriters. BMG Rights Management anchors its competitive position through direct artist relationships and in-house creative services. Reservoir Media specializes in catalog acquisitions across vintage and contemporary repertoires.
Independent music publishing encompasses the acquisition, administration, and monetization of musical compositions outside major label ownership structures, with core functions including mechanical licensing, performance rights registration, and synchronization clearance for audiovisual media. The primary commercial purpose centers on maximizing royalty yield across streaming, broadcast, live performance, and film or television placement channels. Licensing and royalty collection services dominate revenue contribution due to recurring payment structures and scale economies in rights administration. Digital platforms as a distribution channel represent the fastest-expanding segment, though direct deals with streaming services and music supervisors command premium margin pools.
Copyright Office regulations in the United States and the Mechanical Licensing Collective framework reshape how publishers register works and collect digital mechanical royalties, creating compliance-driven demand for administrative services. The EU Copyright Directive and its Article 17 provisions alter platform liability for unlicensed content, affecting how European publishers negotiate with streaming services. Stakeholders must monitor evolving AI training data licensing disputes and fractional ownership tokenization models that could restructure catalog valuation methodologies.
Market Dynamics
AI-generated composition tools are forcing publishers to reconstruct copyright frameworks from first principles, destabilizing traditional ownership verification and royalty attribution systems that governed analog-era licensing.
Growth Catalysts
- Mechanical Licensing Collective:The MLC framework in the United States mandates centralized digital mechanical royalty collection, creating compliance-driven demand for administrative services among independent publishers.
- Streaming platform expansion:Audio and video streaming services are scaling original content production, intensifying sync licensing needs for independent catalogs across film, television, and gaming verticals.
- Fractional ownership tokenization:Blockchain-based catalog investment platforms are democratizing music asset access, attracting non-traditional capital into publishing rights markets.
Market Restraints
- Copyright Office registration backlogs:Processing delays for work registrations in the United States create clearance bottlenecks that stall licensing negotiations and royalty distributions.
- Input cost concentration:Metadata standardization and rights-data verification services concentrate among a handful of specialized technology vendors, limiting publisher negotiating leverage.
- AI training data ambiguity:Unclear legal precedent around machine learning ingestion of copyrighted compositions creates liability exposure for publishers licensing to technology platforms.
Strategic Opportunities
- Emerging market streaming penetration:Brazil, Mexico, and Indonesia exhibit underdeveloped independent publishing infrastructure relative to streaming subscriber growth, creating first-mover positioning potential.
- EU Copyright Directive Article 17:Platform liability provisions in Europe are shifting negotiation power toward rights-holders, enabling improved revenue-share terms for independent publishers.
- Cross-reality sync placement:Virtual production and immersive media formats are generating new licensing categories for spatial audio and interactive composition uses.
Industry Challenges
- Legacy rights-data fragmentation:Decades of paper-based registration and multiple inheritance chains create title ambiguity that blocks clean licensing.
- AI attribution skill scarcity:Publishers lack sufficient technical personnel to evaluate generative output originality and manage corresponding rights conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Independent Music Publishing Market |
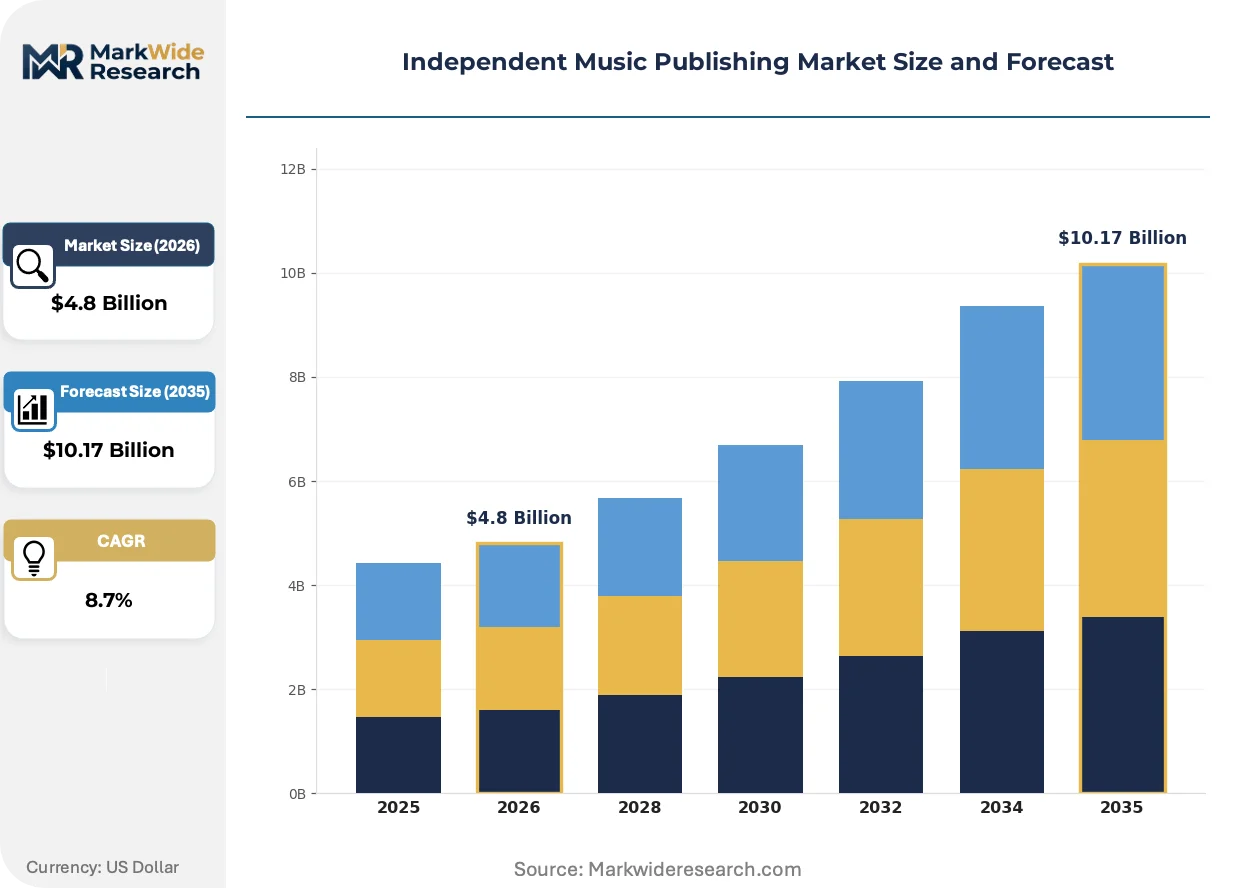
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Licensing, Administration, Royalty Collection, Sync Placement Distribution Channel: Digital Platforms, Direct Deals, Traditional Media, Performance Rights Organizations Customer Type: Independent Artists, Labels, Songwriters, Music Supervisors Genre: Pop, Rock, Hip-Hop, Folk |
| Companies Covered | Kobalt, BMG Rights Management, Peermusic, Songs Music Publishing, Concord Music Publishing, Round Hill Music, Primary Wave Music, Big Machine Music, Reservoir Media, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Independent Music Publishing Market Trends and Innovations
Distributed ledger systems and automated composition platforms are converging to restructure how musical works are created, registered, and monetized across the publishing value chain.
Generative AI composition tools are rewriting the boundaries between human-authored and machine-assisted musical works. Music supervisors at streaming platforms and advertising agencies are piloting these systems for rapid prototyping of temp tracks and production music. The technology is rewriting clearance workflows as publishers develop new contractual language to address split authorship and training-data provenance.
The EU Copyright Directive and its Article 17 implementation are reshaping platform liability architecture across European markets. Streaming services now face direct responsibility for unlicensed content uploads, accelerating proactive licensing negotiations with independent publishers. Germany and France are witnessing the most aggressive compliance restructuring as platforms deploy content-recognition systems to satisfy national regulator demands.
Direct licensing arrangements between publishers and streaming platforms are displacing traditional collective administration for digital mechanical rights. Mid-tier independent publishers in the United States are negotiating direct deals with audio streaming services to capture higher effective rates and faster payment cycles. This pattern is most visible in Nashville, Los Angeles, and New York where publisher concentration enables bilateral bargaining power.
Independent Music Publishing Market Segmentation
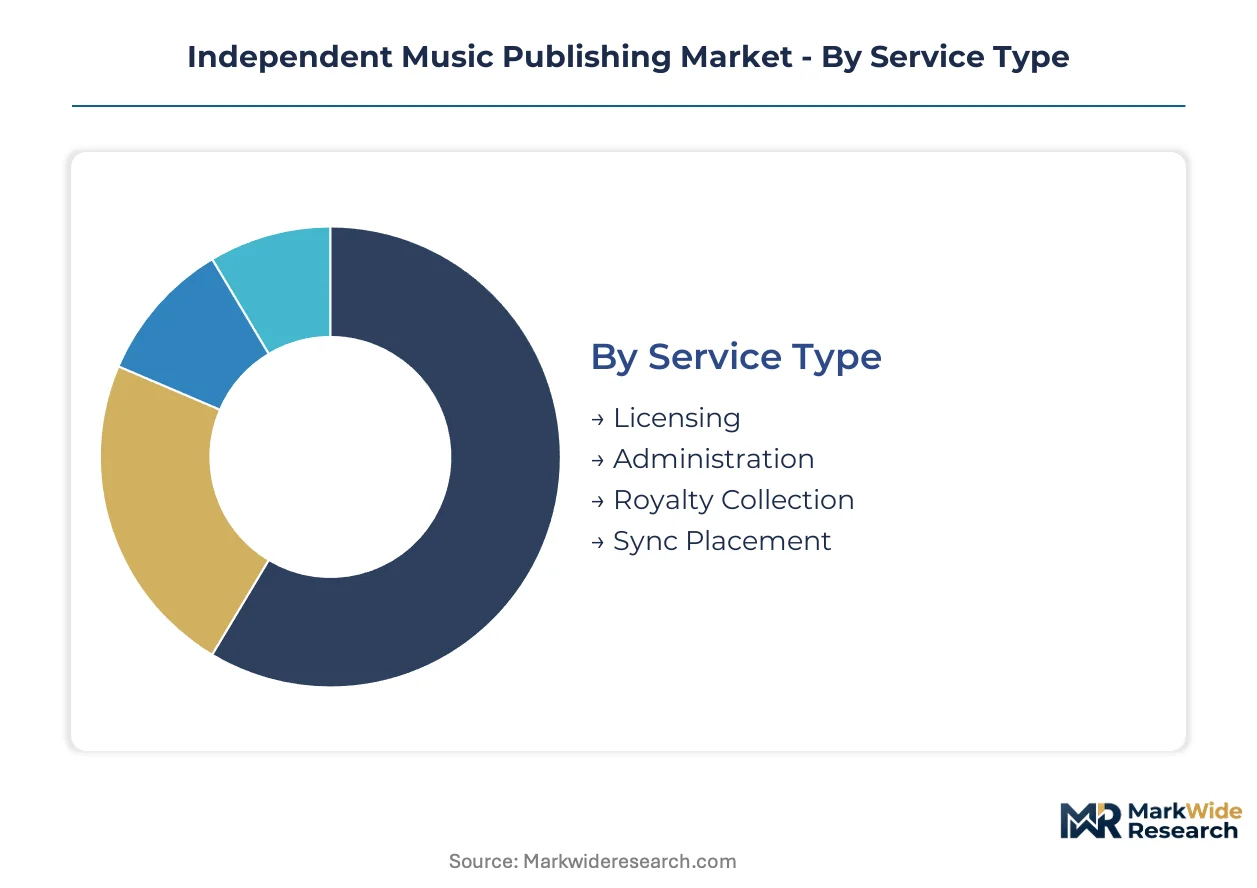
Segmentation in independent music publishing reveals how revenue pools concentrate across service functions, distribution pathways, and creator categories. Publishers calibrate resource allocation by matching internal capabilities against segment-specific margin profiles and contractual complexity.
Service Type:
Service type segmentation tracks how publishers upgrade legacy administration contracts toward higher-margin licensing and placement functions as catalog depth matures.
- Licensing:Mechanical, performance, and synchronization rights clearance for streaming platforms, broadcast networks, and audiovisual productions. Demand concentrates in the United States where the Mechanical Licensing Collective mandates centralized digital mechanical collection, forcing publishers to rebuild compliance infrastructure.
- Administration:Copyright registration, royalty tracking, and rights-data maintenance across multiple territories. Catalog owners in Nashville and Los Angeles favor administration-only deals that preserve creative control while outsourcing operational burden.
- Royalty Collection:Aggregated claims processing across PROs, streaming services, and international sub-publishers. European publishers leverage this service to navigate fragmented collective management organization networks.
- Sync Placement:Direct negotiation with music supervisors for film, television, advertising, and gaming placements. Gaming verticals in Japan and South Korea drive specialized demand for interactive composition clearances.
Licensing sits at the top of the volume ranking, with Sync Placement climbing the fastest.
Distribution Channel:
Channel segmentation reflects cost-tier stratification between technology-enabled direct access and intermediated traditional pathways.
- Digital Platforms:Streaming service integrations, UGC platform licensing, and algorithmic playlist placement. Brazil and Mexico exhibit underdeveloped publisher infrastructure relative to streaming subscriber growth, creating first-mover positioning potential.
- Direct Deals:Bilateral agreements between publishers and streaming services or music supervisors that bypass collective administration. Mid-tier publishers in New York negotiate these arrangements to capture improved rates and accelerated payment cycles.
- Traditional Media:Broadcast television, radio, and physical media licensing through established PRO relationships. Germany maintains robust traditional media channels despite platform shift acceleration.
- Performance Rights Organizations:Collective licensing for public performance royalties in venues, retail, and transportation. French publishers navigate SACEM's centralized framework alongside emerging direct licensing alternatives.
Digital Platforms command the largest revenue share, with Direct Deals gaining share fastest as bilateral bargaining power concentrates.
Customer Type:
Customer segmentation maps publisher capability requirements across creator maturity levels and commercial sophistication.
- Independent Artists:Self-releasing musicians requiring full-stack publishing services from registration to sync placement. This segment concentrates in urban creative clusters where artist development infrastructure supports early-career rights management.
- Labels:Independent record labels seeking bundled publishing administration for roster artists. Labels in London prioritize integrated rights management that aligns master and composition licensing strategies.
- Songwriters:Composers and lyricists focused on maximizing royalty yield across multiple exploitation channels. Nashville's songwriter density creates specialized demand for transparent royalty tracking technology.
- Music Supervisors:Audiovisual production professionals sourcing cleared compositions for specific scene requirements. Supervisors at streaming platforms in Los Angeles drive demand for rapid-clearance catalog access.
Independent Artists generate the highest transaction volume, with Music Supervisors expanding most quickly as original content production scales.
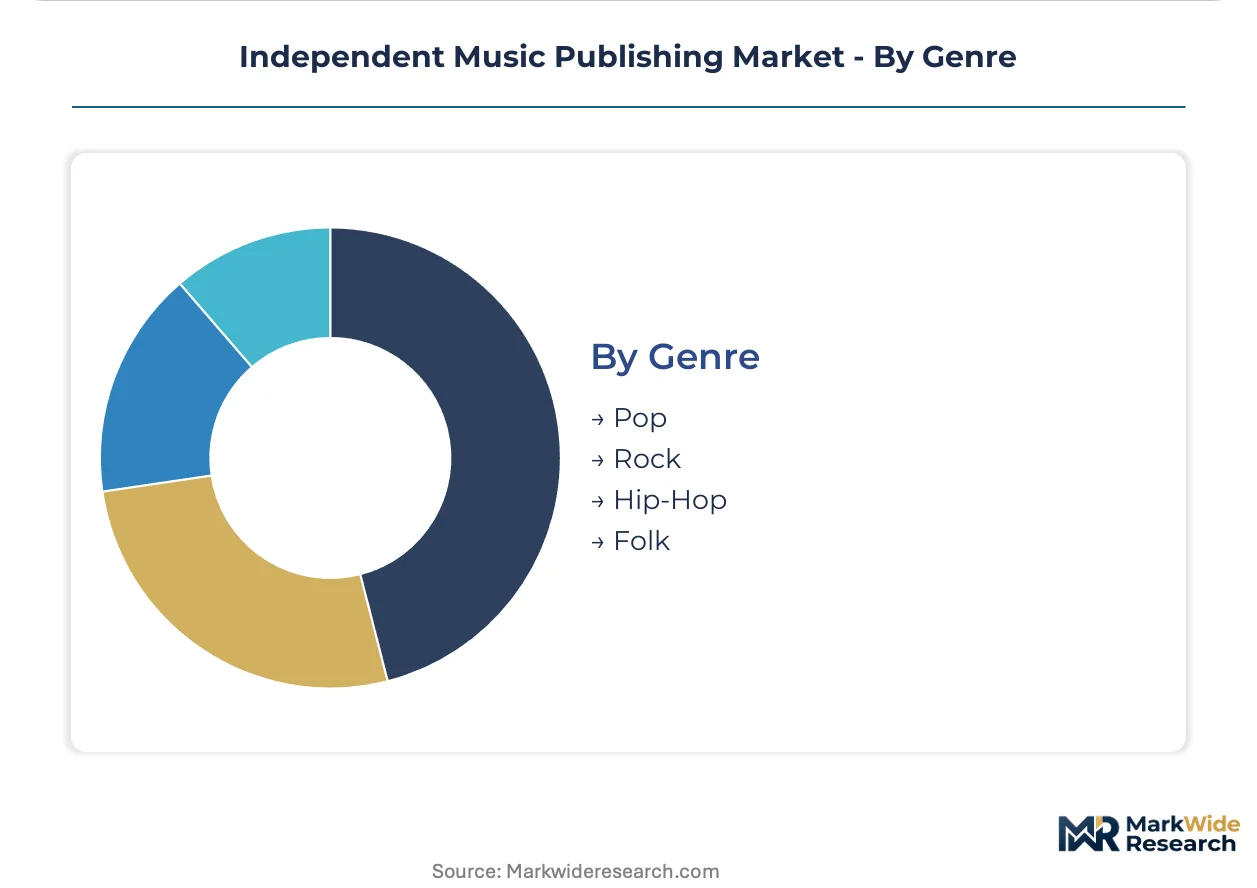
Genre:
Genre segmentation aligns catalog investment with streaming consumption patterns and sync licensing demand cycles.
- Pop:Commercially dominant genre with highest streaming velocity and broadest sync applicability. Pop catalogs command premium valuations in catalog acquisition markets.
- Rock:Mature genre with strong legacy catalog value and persistent film and television placement demand. Classic rock repertoires anchor vintage acquisition strategies.
- Hip-Hop:Streaming-native genre with complex sampling clearance requirements and high UGC platform penetration. Hip-Hop's production methodology creates specialized administration complexity around derivative works.
- Folk:Niche genre with concentrated sync demand for documentary, independent film, and authentic brand positioning. Folk catalogs attract investment from publishers specializing in alternative repertoire depth.
Pop dominates catalog valuations, with Hip-Hop showing the steepest expansion trajectory as streaming consumption patterns evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nashville's songwriter density and Los Angeles' sync licensing infrastructure anchor the United States as the dominant market for independent music publishing, with mechanical licensing frameworks and streaming platform headquarters concentrating administrative and commercial activity in these urban clusters.
United States
The Mechanical Licensing Collective mandates centralized digital mechanical royalty collection, forcing publishers to rebuild compliance infrastructure around federal copyright registration systems. Nashville's songwriter density creates specialized demand for transparent royalty tracking technology, while Los Angeles music supervisors drive rapid-clearance catalog access for streaming platform productions.
Germany
Robust traditional media channels persist alongside platform shift acceleration, with GEMA's collective management framework coexisting with emerging direct licensing alternatives. The EU Copyright Directive's Article 17 implementation accelerates proactive licensing negotiations as streaming services deploy content-recognition systems to satisfy national regulator demands from the Federal Network Agency.
United Kingdom
Independent record labels in London prioritize integrated rights management that aligns master and composition licensing strategies across bundled publishing administration. The Intellectual Property Office maintains copyright registration frameworks while PRS for Music administers performance royalties, creating dual-track administrative pathways for publishers.
Brazil
Underdeveloped independent publishing infrastructure relative to streaming subscriber growth creates first-mover positioning potential for administrative service providers. ECAD's centralized performance rights framework manages collective licensing while digital platform expansion outpaces local publisher capacity, generating demand for international sub-publishing partnerships.
Japan
Gaming verticals drive specialized demand for interactive composition clearances, with JASRAC's long-standing collective management structure facing pressure from direct licensing arrangements. Tokyo's concentration of music production for interactive media creates distinct sync placement workflows that diverge from Western film and television licensing patterns.
Independent Music Publishing Market Competitive Landscape
Global majors compete with regional champions across technology-enabled royalty administration and direct artist relationship models. The vendor base stratifies between scale-driven catalog aggregators, technology-forward administrative platforms, and creative-services specialists. Three archetypes dominate: proprietary technology developers, direct-relationship publishers, and catalog acquisition specialists. Competitive moves concentrate on portfolio diversification through vintage repertoire purchases and bilateral streaming platform negotiations that bypass collective administration.
Within the technology-forward tier, Kobalt exemplifies proprietary royalty-tracking infrastructure, while BMG Rights Management occupies a position emphasizing direct artist relationships and in-house creative services. Reservoir Media represents the catalog acquisition specialist archetype, focusing on vintage and contemporary repertoire purchases. These three companies anchor distinct strategic positions that other competitors must navigate or replicate.
| Leading Market Players |
|---|
| Kobalt |
| BMG Rights Management |
| Peermusic |
| Songs Music Publishing |
| Concord Music Publishing |
| Round Hill Music |
| Primary Wave Music |
| Big Machine Music |
| Reservoir Media |
| Others |
Pricing and Supply Chain Analysis
Royalty-rate benchmark indices from the Mechanical Licensing Collective cascade through independent publisher cost structures, compressing margins for administration-only providers while amplifying pricing power for vertically integrated catalog owners with direct streaming platform relationships.
Pricing Analysis
Input-cost pass-through from metadata standardization vendors and rights-data verification services intensifies pricing pressure across mid-tier administration contracts. Three-tier pricing structure across premium, standard, and economy levels separates full-stack creative publishers from technology-enabled administrators and bare-bones collection agents. Price differentiation hinges on proprietary royalty-tracking infrastructure and speed-to-payment capabilities. Independent artists exhibit highest price sensitivity due to cash-flow constraints, while music supervisors at streaming platforms prioritize clearance velocity over cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with concentrated metadata technology vendors in the United States and specialized sub-publishing networks in Germany and France. Raw material dependencies span copyright registration systems, performance rights organization databases, and content-recognition technology licenses. Supply chain risk centers on Copyright Office processing backlogs that stall title clearance and royalty distribution. Distribution runs through bilateral direct deals with streaming platforms and collective administration via PROs and the Mechanical Licensing Collective.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in independent music publishing rests on technology-enabled cost reduction in rights-data verification and the premium-tier shift toward direct platform licensing that bypasses collective administration overhead.
For Market Incumbents: Deploy proprietary royalty-tracking infrastructure as the primary defensive lever against technology-enabled entrants. Consolidate through vintage catalog acquisitions in Nashville and Los Angeles to deepen sync placement capabilities. Fortify bilateral streaming platform relationships before Article 17 compliance restructuring in Europe shifts negotiation power toward rights-holders. For New Entrants and Emerging Players: Self-releasing independent artists in Brazil, Mexico, and Indonesia represent the most penetrable buyer archetype given underdeveloped local publishing infrastructure relative to streaming subscriber growth. Target administrative service bundling for labels in London seeking integrated master-composition rights alignment. Pursue white-label technology licensing to established regional publishers lacking in-house data capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with catalog acquisition specialists holding vintage rock and hip-hop repertoires with unexploited sync potential. Long-term viability favors publishers with direct platform relationships and proprietary data infrastructure over pure administration plays. Monitor AI training data licensing dispute resolutions as the critical inflection signal for rights-valuation methodologies.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Platform Licensing | Bilateral agreements with Spotify and Apple Music bypass Mechanical Licensing Collective overhead and accelerate payment cycles. |
| Vintage Catalog Acquisition | Classic rock and hip-hop repertoires anchor sync placement pipelines for streaming platform original content production. |
| Proprietary Technology Development | In-house royalty-tracking systems differentiate transparent payment flows from opaque collective administration competitors. |
| Geographic Expansion | First-mover positioning in Brazil and Indonesia captures streaming subscriber growth ahead of local publisher capacity. |
| AI Rights Framework Investment | Early contractual language development for generative authorship splits protects future catalog valuation integrity. |
Research Methodology
Direct dialogue with music publishing executives, copyright administration specialists, streaming platform licensing directors, and independent artist managers grounded the qualitative foundation. Secondary validation drew from Copyright Office registration databases, Mechanical Licensing Collective disbursement reports, PRO financial disclosures, and streaming platform regulatory filings. Bottom-up catalog valuation models and top-down market sizing approaches were triangulated to cross-verify segment estimates.
Market value and volume trajectories across the projection horizon reflect segmented modeling by service type, distribution channel, customer category, and genre classification. CAGRs were derived from historical royalty flow analysis and forward-looking streaming platform content budget projections. Key forecast inputs include streaming subscriber penetration curves, sync licensing demand from gaming and virtual production verticals, and regulatory implementation timelines for EU Copyright Directive Article 17.
Underlying measurement precision varies by segment; licensing and sync placement carry tighter precision than administration due to more visible transaction flows. Forecasts reflect assumptions around streaming platform content investment continuity and mechanical royalty rate stability. AI-generated composition legal frameworks and fractional ownership tokenization adoption represent material uncertainty factors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Virtual Musical Instruments Market
Music
Traditional Chinese Instruments Market
Music
Global Stock Music Market
Music
Music Production Software Market
Music
Music Publishing Market
Music
Music Distribution Services Market
Music
Traditional Music Market
Music
Musical Groups and Artists Market
Music
Discography Market
Music
Global Free Music Making Software Market
Music
Global in-Store Music Service Market
Music
United States Live Music Market
Music
Europe Independent Artist Market
Music
Electronic Dance Music (EDM) Market
Music
Music Synthesizers Market
Music
Vinyl Records Market