
 Digital Content Locker Market | 2026-2036
Digital Content Locker Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Content Locker Market Outlook
Enterprise-grade encryption standards are reorganizing competitive dynamics in the Digital Content Locker Market. Quadient leverages its parcel logistics heritage to anchor secure handoff protocols for digital-physical content bridges. Cleveron specializes in automated retrieval interfaces that sustain premium positioning among Nordic educational consortia. KEBA dominates industrial-grade access control, extending its automation pedigree into API-governed content vaults for manufacturing enterprises.
A digital content locker is a secure, access-controlled repository system that encrypts stored assets using AES-256 or equivalent protocols, with authentication layers spanning biometric, token-based, and federated identity verification. Its primary commercial purpose is to enable organizations to distribute, monetize, or internally manage digital assets while maintaining audit trails and rights management. Cloud-Based and SaaS solution types are capturing the fastest expansion as organizations abandon capital-intensive on-premise infrastructure, though Hybrid deployments retain margin concentration among regulated European enterprises. Media Companies and Educational Institutions represent the deepest end-user pools, with the former driving API Integration access methods for content syndication pipelines and the latter favoring Mobile App interfaces for student-facing distribution.
The EU AI Act and GDPR impose strict data residency and algorithmic transparency mandates on content locker providers operating across Europe, while the FCC's broadband privacy frameworks shape US deployment architectures for cloud-based repositories. ISO 27001 certification has become a de facto market-access filter, with procurement teams at German universities and American healthcare networks treating it as non-negotiable. Stakeholders must monitor how emerging quantum-resistant encryption standards will force platform rebuilds before regulatory deadlines crystallize.
Market Dynamics
Enterprise migration from on-premise vaults to API-governed cloud repositories is compressing deployment timelines and forcing vendors to rearchitect authentication layers around zero-trust principles.
Growth Catalysts
- GDPR Article 32 mandates:German healthcare networks and universities must demonstrate encryption-at-rest and access logging, driving procurement of certified locker platforms.
- Automated retrieval interfaces:Nordic educational consortia are replacing manual content distribution with self-service kiosks and mobile credentialing systems.
- Biometric authentication modules:Manufacturing enterprises in Bavaria and Baden-Württemberg are integrating fingerprint and facial recognition into shop-floor content access workflows.
Market Restraints
- Quantum-resistant cryptography R&D costs:Vendors face substantial engineering investment to migrate AES-256 foundations to post-quantum algorithms before regulatory deadlines.
- Cloud infrastructure concentration:Hyperscale provider dominance in Frankfurt and Dublin data centers creates single-point-of-failure exposure for EU-resident content vaults.
- Legacy archival system entrenchment:Mittelstand enterprises with decades of tape-based records resist forklift migrations despite compliance pressures.
Strategic Opportunities
- EU AI Act algorithmic transparency requirements:Locker platforms that embed automated audit trails for AI-generated content gain preferential positioning in public-sector tenders.
- Mobile-first student distribution:Universities in Lower Saxony and North Rhine-Westphalia are abandoning desktop portals for smartphone-native content delivery.
- Digital-physical content bridges:Parcel logistics integration enables secure handoff protocols for credentials, licenses, and certified documents requiring physical verification.
Industry Challenges
- ISO 27001 certification timelines:Six-to-twelve-month audit cycles delay market entry for emerging vendors targeting German procurement frameworks.
- Federated identity integration complexity:Universities operate fragmented Shibboleth, SAML, and OIDC environments that resist standardized locker authentication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Content Locker Market |
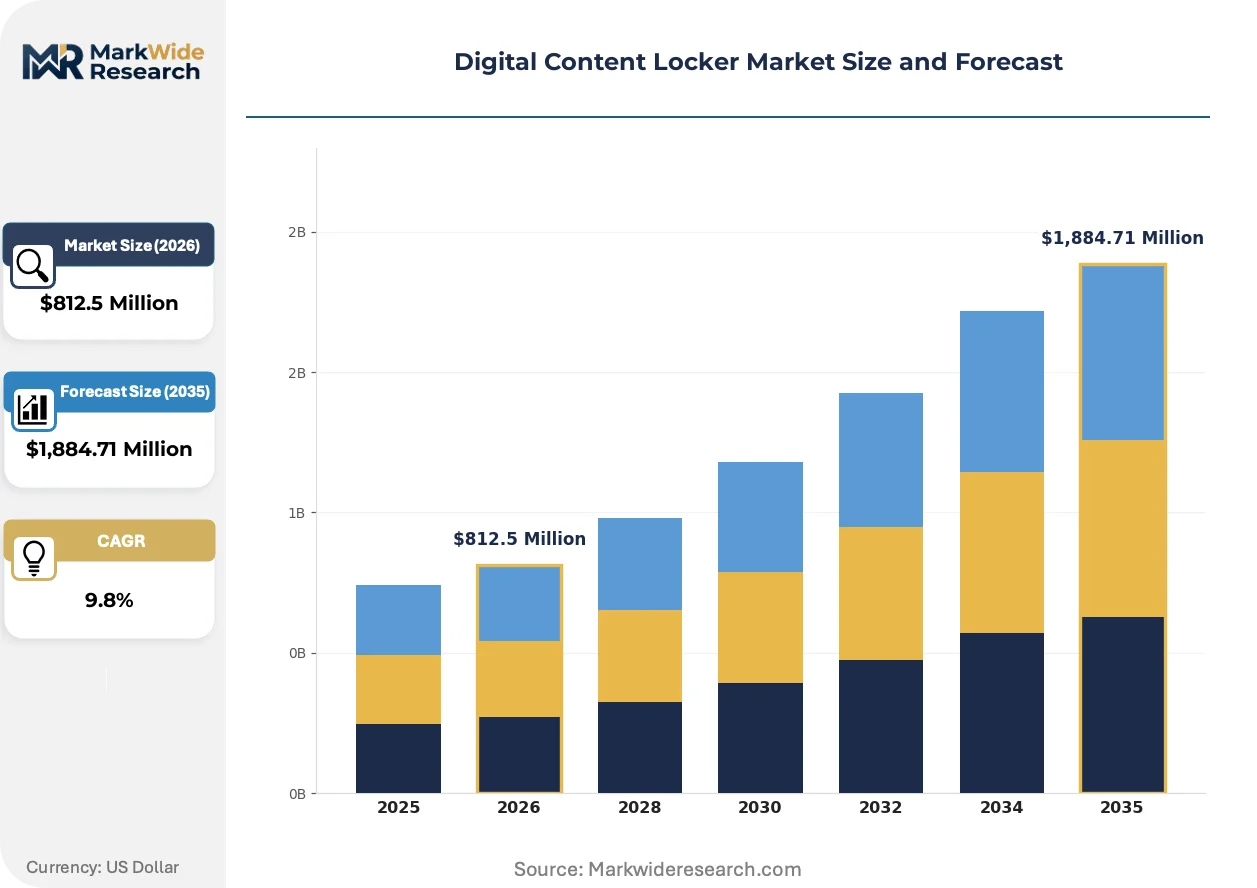
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,884.71 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-Based, On-Premise, Hybrid, SaaS End User: Media Companies, Educational Institutions, Enterprises, Individual Users Deployment Model: Public Cloud, Private Cloud, Edge Computing, Mobile Access Method: Web-Based, Mobile App, API Integration, Desktop Client |
| Companies Covered | Quadient, TZ Limited, Luxer One, Cleveron, InPost, KEBA, American Locker, Florence Corporation, LockTec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Content Locker Market Strategic Shifts
Zero-trust architecture is displacing perimeter-based security models across content locker deployments, with authentication granularity extending to individual document-level access policies.
Edge computing nodes are miniaturizing content delivery infrastructure. Media companies operating syndication pipelines are deploying micro-vaults at ISP points-of-presence to reduce latency for streaming assets. This topology is miniaturizing the traditional centralized repository model into geographically distributed cell structures.
The EU AI Act's risk-classification framework is compelling locker vendors to implement automated content provenance tracking. Platforms must now log training data origins and model versioning for AI-generated assets stored in educational and enterprise vaults. German universities are piloting these capabilities ahead of enforcement deadlines.
Subscription fatigue among educational IT directors is fragmenting procurement into modular, best-of-breed selections. Institutions in Hamburg and Berlin are unbundling storage, authentication, and analytics components rather than accepting monolithic SaaS suites. This pattern concentrates purchasing power with specialized vendors offering API-first architectures.
Digital Content Locker Market Segmentation
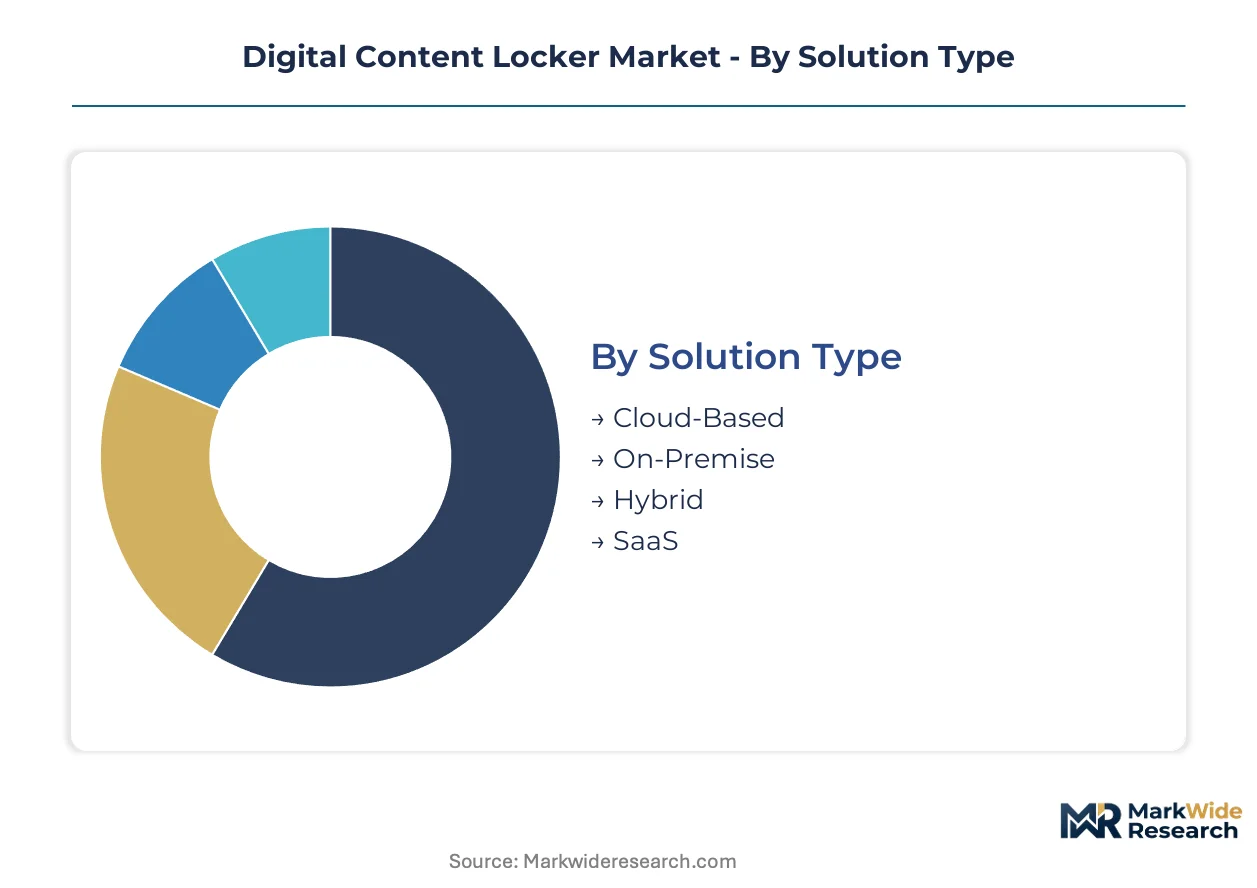
Segmentation in the Digital Content Locker Market reveals how encryption standards, deployment architectures, and access modalities fragment procurement decisions across regulated industries. Buyers prioritize compliance certification over feature breadth, forcing vendors to align platform configurations with sector-specific audit requirements.
Solution Type:
Cloud-Based and SaaS deployments face intensifying substitution pressure from hybrid architectures as GDPR Article 32 and EU AI Act mandates harden data residency requirements.
- Cloud-Based:Multi-tenant architectures with AES-256 encryption-at-rest dominate procurement at German universities and Nordic educational consortia seeking rapid deployment without capital expenditure. Frankfurt and Dublin hyperscale regions concentrate infrastructure, creating latency advantages for Western European end-users but single-point-of-failure exposure under CSRD disclosure requirements.
- SaaS:Subscription licensing with API-first modular construction enables Hamburg and Berlin institutions to unbundle storage from authentication components. Procurement teams favor this flexibility amid budget fragmentation, though vendor lock-in risks persist around proprietary encryption key management.
- On-Premise:Air-gapped vaults retain preference among Bavarian manufacturing enterprises with classified intellectual property.
- Hybrid:Split architectures combining local encryption nodes with cloud burst capacity satisfy Mittelstand enterprises navigating legacy tape migration constraints.
Cloud-Based retains volume leadership; SaaS holds the steepest expansion curve.
End User:
Cost tier stratification separates enterprise procurement frameworks from individual subscription economics, with educational institutions occupying a mid-tier negotiation position between volume scale and budget rigidity.
- Educational Institutions:Universities in Lower Saxony and North Rhine-Westphalia drive mobile-first distribution requirements, replacing desktop portals with smartphone-native delivery. GDPR compliance audits and student data protection mandates elevate ISO 27001 certification to non-negotiable status in German procurement tenders.
- Media Companies:Syndication pipelines demand API Integration access methods with edge-computing micro-vaults deployed at ISP points-of-presence. Latency-sensitive streaming assets require geographically distributed cell structures rather than centralized repositories.
- Enterprises:Manufacturing workflows in Baden-Württemberg integrate biometric authentication modules for shop-floor content access.
- Individual Users:Consumer-grade encryption with federated identity options captures freelance creators and independent professionals.
Enterprises retain volume leadership; Educational Institutions hold the steepest expansion curve.
Deployment Model:
Application-critical workloads concentrate in private and edge configurations where latency and data sovereignty override public cloud cost efficiencies.
- Edge Computing:Miniaturized micro-vaults at network peripheries reduce round-trip latency for media streaming and industrial IoT content delivery. German automotive suppliers deploy these nodes for real-time access to CAD files and quality documentation without central repository bottlenecks.
- Private Cloud:Single-tenant infrastructure satisfies healthcare networks under GDPR Article 32 and German federal data protection requirements. Procurement teams at university hospitals mandate dedicated encryption key custody and audit trail isolation from multi-tenant environments.
- Public Cloud:Shared infrastructure dominates non-regulated commercial use cases with elastic scaling requirements.
- Mobile:Smartphone-native vaults with offline synchronization address field workforce distribution needs.
Private Cloud retains volume leadership; Edge Computing holds the steepest expansion curve.
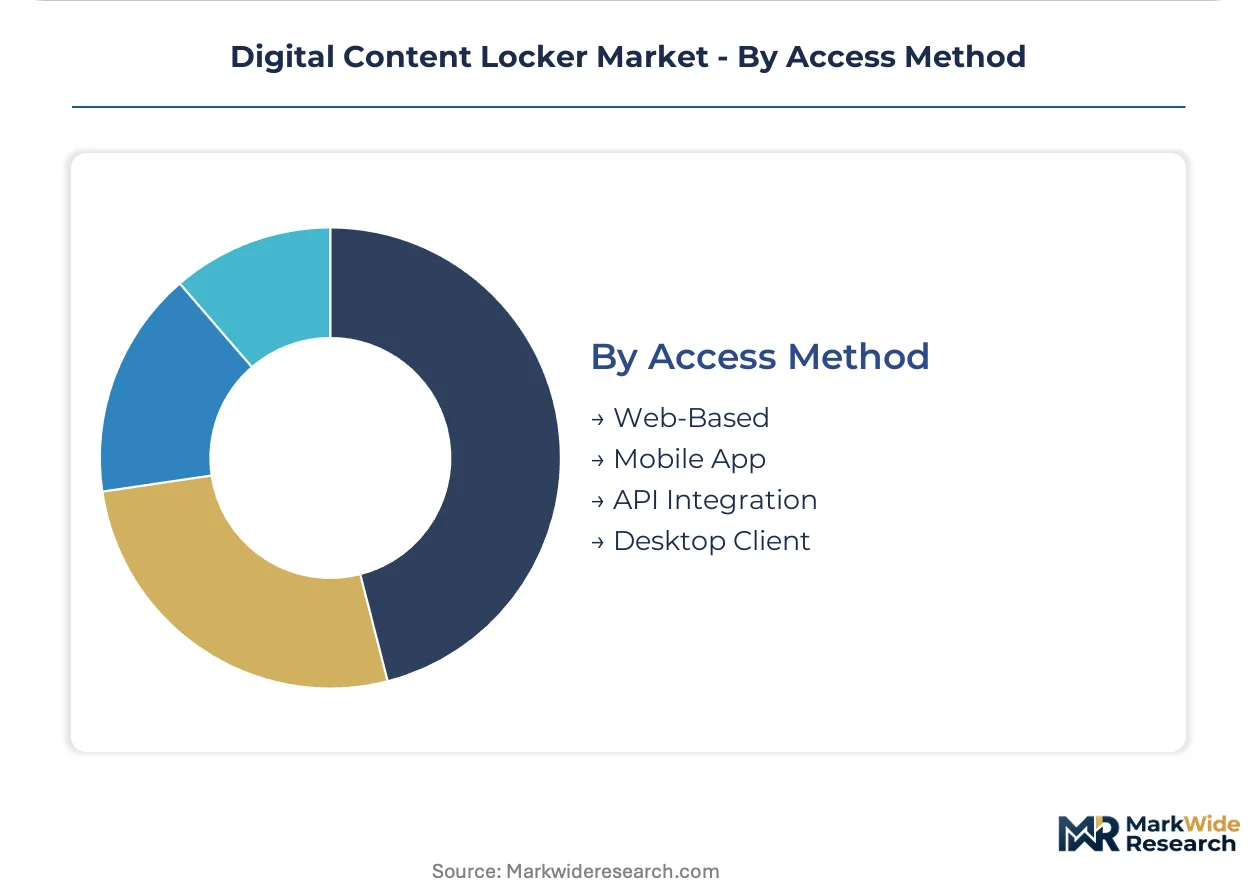
Access Method:
Customer type differentiation separates developer-centric API consumption from end-user-facing mobile and web interfaces, with integration complexity driving procurement specialization.
- API Integration:Programmatic access enables content syndication pipelines and automated retrieval interfaces at Nordic educational consortia. Manufacturing enterprises embed these endpoints into ERP and MES workflows for document lifecycle management without manual handoff.
- Mobile App:Native iOS and Android clients with biometric unlock and offline caching dominate student-facing distribution at German universities. IT directors prioritize single-sign-on compatibility with fragmented Shibboleth and OIDC identity environments.
- Web-Based:Browser access with token-based authentication serves administrative and occasional-use scenarios.
- Desktop Client:Thick-application encryption with local key generation persists among creative professionals handling large media assets.
Web-Based retains volume leadership; API Integration holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center concentration in Frankfurt and Dublin concentrates cloud-based locker infrastructure, while regulatory fragmentation across jurisdictions forces vendors to architect region-specific compliance modules. German procurement frameworks now treat ISO 27001 certification as non-negotiable, diverting vendor investment toward audit-ready European deployments.
United States
Healthcare networks and media syndication pipelines drive API-first locker procurement, with FCC broadband privacy frameworks shaping cloud repository architectures. HIPAA compliance mandates encrypt patient-facing content vaults at university hospitals in Boston and Houston. The Pacific Northwest technology corridor anchors development of zero-trust authentication modules for enterprise content distribution.
Germany
GDPR Article 32 encryption-at-rest requirements compel Mittelstand manufacturers and Lower Saxony universities to replace tape-based archival systems. The EU AI Act's algorithmic transparency mandates force locker platforms to embed automated audit trails for AI-generated educational content. Bavarian automotive suppliers deploy edge-computing micro-vaults for real-time CAD file access without central repository bottlenecks.
United Kingdom
London-based media companies demand low-latency content syndication through ISP point-of-presence deployments, fragmenting procurement toward edge-native architectures. The Information Commissioner's Office enforces data residency requirements that complicate cross-border content vault operations. Southeast England educational consortia pilot mobile-first student distribution platforms ahead of national rollout.
France
CNIL guidance on automated decision-making shapes locker platform design for AI-generated content in Parisian publishing houses. Healthcare networks under ANSM oversight mandate dedicated encryption key custody for patient data vaults. The Île-de-France region concentrates vendor development of biometric authentication modules for enterprise content access workflows.
Japan
METI industrial digitization programs accelerate shop-floor content locker deployment at Nagoya automotive suppliers and Osaka electronics manufacturers. JIS standards for information security management systems create certification barriers for foreign platform vendors. The Kanto corridor anchors development of API-governed content vaults integrated with ERP and MES manufacturing workflows.
Digital Content Locker Market Competitive Environment
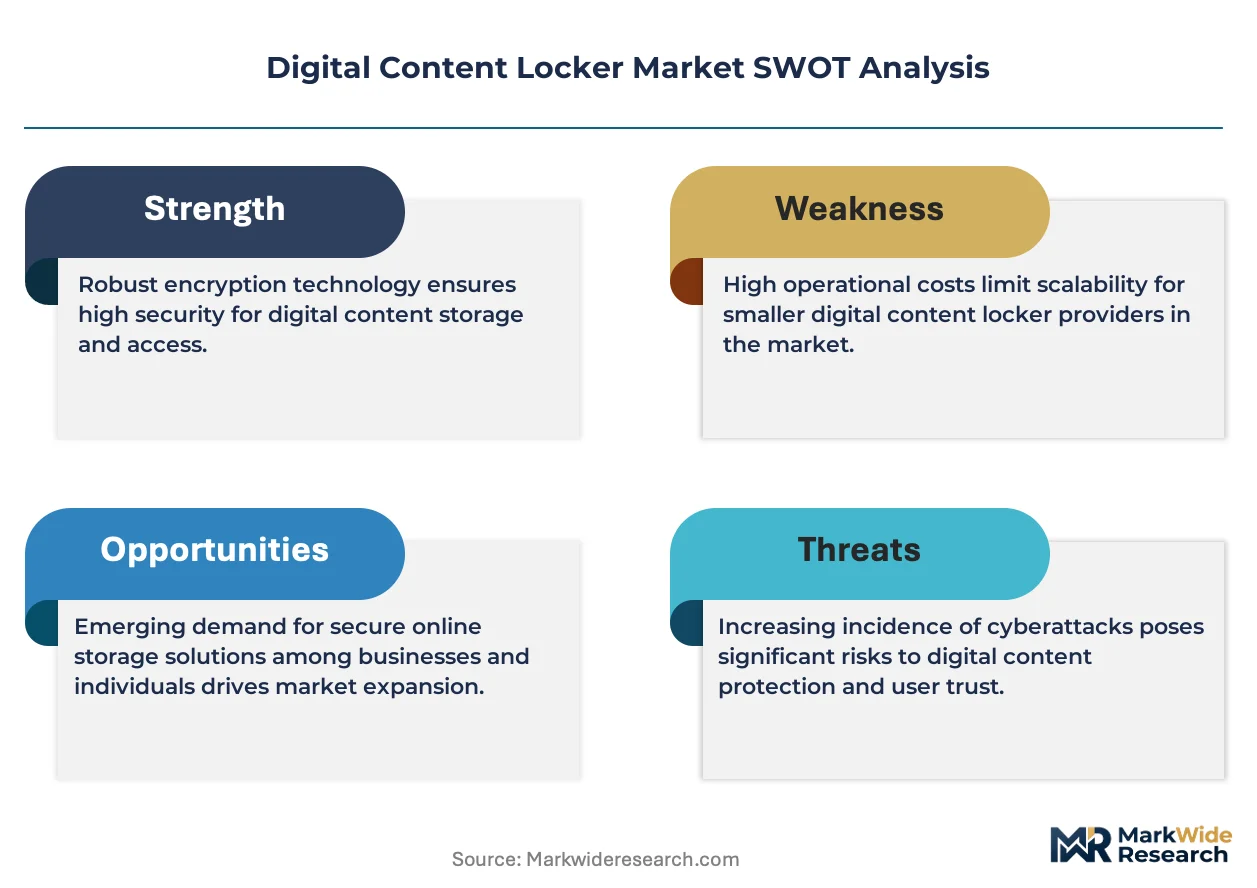
Technology leadership and cost leadership are held by different player archetypes, with premium-tier vendors commanding margin concentration through specialized authentication modules while scale-driven competitors compress pricing in standardized cloud deployments. The vendor base organizes around three strategic archetypes: logistics heritage platforms extending into digital-physical content bridges, industrial automation specialists repurposing access control systems, and modular SaaS providers unbundling storage from authentication components. M&A activity concentrates among logistics-adjacent players seeking last-mile credential verification capabilities, while technology licensing partnerships proliferate as vendors race to embed quantum-resistant encryption foundations.
Within the logistics-heritage tier, Quadient leverages parcel handoff protocols to anchor secure digital-physical content bridges, while InPost occupies a position bridging automated retrieval interfaces with consumer-facing credential distribution. Cleveron exemplifies the Nordic educational specialist archetype, with automated kiosk systems sustaining premium positioning among consortia replacing manual content distribution. KEBA represents the industrial automation vector, extending its manufacturing access control pedigree into API-governed content vaults for Bavarian and Baden-Württemberg enterprises. TZ Limited, Luxer One, American Locker, Florence Corporation, and LockTec GmbH populate mid-market and regional specialist segments where localized compliance expertise and fragmented identity integration capabilities determine competitive viability.
| Leading Market Players |
|---|
| Quadient |
| TZ Limited |
| Luxer One |
| Cleveron |
| InPost |
| KEBA |
| American Locker |
| Florence Corporation |
| LockTec GmbH |
| Others |
Value Chain & Pricing Dynamics
Hyperscale infrastructure concentration across Frankfurt and Dublin data centers compresses marginal costs for cloud-native locker platforms while elevating price floors for on-premise and hybrid alternatives. German universities and Mittelstand enterprises absorb these scale differentials through procurement frameworks that weight ISO 27001 certification premiums against operational expenditure flexibility.
Pricing Analysis
GDPR Article 32 and EU AI Act mandates dictate the pricing tier structure across the Digital Content Locker Market. Three-tier pricing structure across premium, standard, and economy levels separates certified hybrid deployments with dedicated encryption key custody from multi-tenant SaaS subscriptions and basic cloud repositories. Price differentiation centers on audit trail granularity and biometric authentication module inclusion. Cost compression in the standard tier is intensifying because Nordic educational consortia are unbundling storage from authentication components. Educational institutions exhibit highest price sensitivity due to fragmented IT budgets, while Bavarian automotive suppliers demonstrate lowest sensitivity given classified IP protection requirements.
Supply Chain Analysis
Hardware inventory cycles for biometric authentication modules and edge-computing nodes currently stretch delivery timelines for manufacturing enterprises in Baden-Württemberg. Component sourcing draws from Taiwan for semiconductor-grade encryption processors, Germany for industrial automation subsystems, and Ireland for hyperscale data center infrastructure. Raw material dependencies span rare earth elements for biometric sensors, specialized alloys for kiosk enclosures, and high-grade silicon for secure enclave chips. Single-source vulnerability concentrates in Taiwan-based encryption processor foundries. Distribution runs through direct vendor-to-enterprise contracts for large deployments, with channel partners handling mid-market educational procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Content Locker Market functions as a service-attach opportunity where recurring authentication and compliance audit subscriptions expand faster than hardware locker deployments. Managed encryption key custody and automated GDPR reporting modules now capture margin concentration previously reserved for physical infrastructure.
For Market Incumbents: Shield installed base relationships by embedding quantum-resistant cryptography R&D ahead of regulatory deadlines, preventing substitution by modular SaaS entrants. Vertical integration into biometric sensor supply chains secures component availability against Taiwan foundry concentration. Prioritize ISO 27001 certification maintenance as non-negotiable table stakes in German procurement frameworks. For New Entrants and Emerging Players: Anchor in mobile-first student distribution platforms across Lower Saxony and North Rhine-Westphalia universities, where legacy desktop portal incumbents retain technical debt. API-first architectures with unbundled storage and authentication components penetrate procurement teams frustrated by monolithic SaaS suite pricing. Partner with Nordic educational consortia piloting automated retrieval kiosks to establish reference deployments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized vendors with logistics heritage extending into digital-physical content bridges over pure-play software platforms. Long-term viability hinges on quantum-resistant encryption migration capabilities and EU AI Act compliance automation. Monitor post-quantum algorithm standardization announcements from NIST as inflection indicator for platform rebuild investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Encryption Migration | NIST post-quantum standards adoption forces AES-256 platform rebuilds before EU regulatory deadlines crystallize. |
| API-First Modular Unbundling | Hamburg and Berlin institutions fragment procurement toward best-of-breed storage and authentication components. |
| Edge Computing Micro-Vault Deployment | German automotive suppliers deploy ISP point-of-presence nodes for real-time CAD file access without latency bottlenecks. |
| Biometric Authentication Integration | Bavarian manufacturing workflows embed fingerprint and facial recognition for shop-floor content access security. |
| Digital-Physical Content Bridge Extension | Quadient leverages parcel logistics heritage to anchor secure handoff protocols for credential and license verification. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with platform engineering leads, university IT procurement directors, Mittelstand compliance officers, and biometric systems integrators; and secondary validation through SEC filings of listed logistics-heritage vendors, hyperscaler capex disclosures, EU regulatory documentation on GDPR Article 32 and AI Act implementation, and German federal procurement tender databases. Bottom-up segment sizing triangulated against top-down market boundary estimates.
Across the analysis window, the forecasting framework modeled deployment architecture splits between cloud-native and hybrid configurations, end-user concentration across educational and enterprise verticals, access method evolution from web-based to API-first consumption, and geographic adoption patterns shaped by data residency mandates. CAGRs derived from segment-level growth rate reconciliation with aggregate market boundary constraints. Quantum-resistant cryptography R&D timelines and EU AI Act enforcement phasing served as scenario-weighting inputs.
Decision-makers should treat outputs as directional under assumptions of sustained GDPR enforcement stringency and stable hyperscale infrastructure concentration; material deviation in regulatory timelines or supply chain geography would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Digital Content Creator Market
Digital Media
China Webtoons Market
Digital Media
Global Music Video Production Market
Digital Media
Adult Entertainment Market
Digital Media
Volumetric Video Market
Digital Media
Global Streaming Media Device Market
Digital Media
Europe Location-Based Entertainment Market
Digital Media
Mexico Webtoons Market
Digital Media
Stock Music Software Market
Digital Media
Digital Content Market
Digital Media
Wedding Photography Market
Digital Media
Global ACGN Market
Digital Media
Da Vinci Systems Market
Digital Media
Anime Market
Digital Media
United States Sports Betting Market
Digital Media
APAC DOOH Market