
 Global 3D Gaming Console Market | 2026-2036
Global 3D Gaming Console Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Gaming Console Market Analysis
Subscription-based access to cloud gaming libraries is hardening into the dominant commercial model for the industry. Sony Group Corp. leverages its PlayStation Plus infrastructure to lock in recurring revenue across hybrid consoles and streaming endpoints. Microsoft Corp. anchors its competitive stance through Xbox Game Pass, which extends software reach beyond proprietary hardware. Nintendo Co. Ltd. navigates this shift more cautiously, sustaining demand through exclusive first-party IP rather than broad subscription bundling.
A 3D gaming console is an interactive entertainment system engineered to render stereoscopic or spatially immersive visuals through specialized GPUs, high-refresh displays, and depth-sensing peripherals, serving both consumer leisure and professional esports applications. Home consoles retain the largest installed base and margin pool due to premium pricing and accessory ecosystems, while virtual reality systems represent the fastest-expanding technology segment as headset weights drop and field-of-view angles widen. Motion sensing technology has matured into a standard feature across hybrid consoles rather than a premium differentiator.
FCC equipment authorization in the United States, CE marking under EU radio equipment directives, and METI technical standards in Japan each dictate electromagnetic compatibility and safety thresholds that manufacturers must clear before market entry. These frameworks lengthen product development cycles but also erect compliance barriers that favor incumbents with established certification pipelines. Stakeholders must weigh whether backward compatibility investments or native next-generation architectures offer superior returns as platform transitions accelerate.
Market Dynamics
Cloud gaming infrastructure is compressing hardware upgrade cycles while elevating software subscription economics above discrete console sales, forcing incumbents to restructure revenue models around recurring access rather than one-time hardware transactions.
Growth Catalysts
- VR Display Resolution Advancements:Micro-OLED and pancake lens architectures are reducing headset weight below 300 grams while expanding field-of-view beyond 110 degrees, removing physical barriers to extended play sessions.
- FCC Equipment Authorization Pathways:Streamlined electromagnetic compatibility certification for 60 GHz mmWave wireless peripherals is accelerating accessory ecosystem expansion in the United States.
- Esports Broadcasting Infrastructure:Dedicated 3D spectator modes and volumetric capture studios are creating parallel revenue streams from content licensing beyond direct consumer hardware sales.
Market Restraints
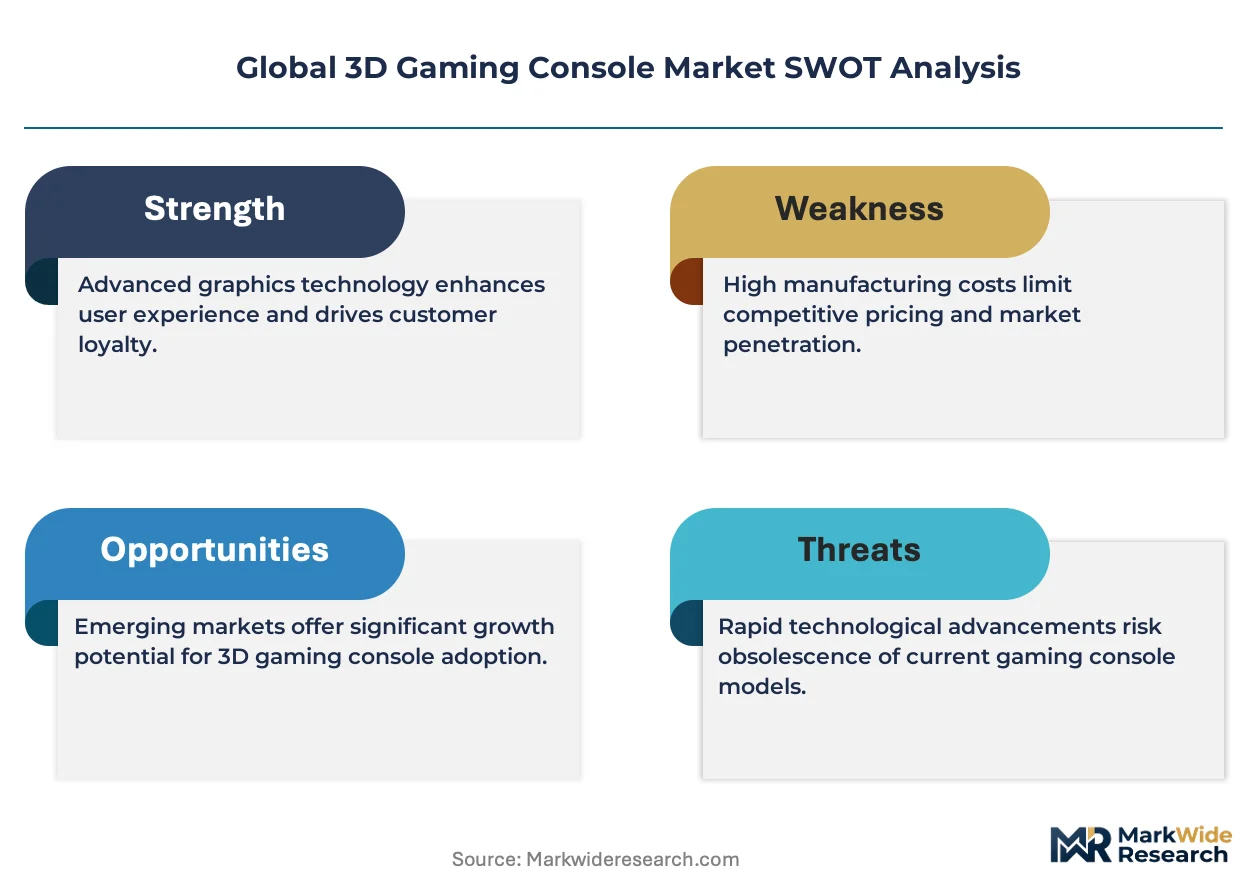
- Advanced GPU Wafer Supply:Concentration of leading-edge semiconductor fabrication in Taiwan creates input cost volatility and allocation risk for console SoC procurement.
- METI Technical Standards Compliance:Japan's radio equipment safety thresholds require localized RF shielding redesigns that extend product development timelines by four to six months.
- Mobile Cloud Gaming Substitution:5G-enabled smartphone streaming is capturing casual session time that previously defaulted to dedicated console hardware.
Strategic Opportunities
- India Market Underpenetration:Localized payment integration and Hindi-language voice interfaces remain undeveloped in a market with 450 million smartphone gamers seeking premium experiences.
- Healthcare Rehabilitation Applications:Prescription gamification for stroke recovery and physical therapy is creating reimbursement pathways through Medicare and private insurers in the United States.
- EU Energy Efficiency Mandates:Ecodesign requirements for standby power consumption below 0.5 watts are favoring ARM-based architectures that extend battery life in hybrid portable systems.
Industry Challenges
- Volumetric Content Pipeline Talent:Shortage of engineers proficient in neural radiance fields and real-time photogrammetry is constraining first-party exclusive development timelines.
- Backward Compatibility Certification:Legacy title emulation requires per-game licensing renegotiation and performance validation that consumes QA resources disproportionate to commercial return.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Gaming Console Market |
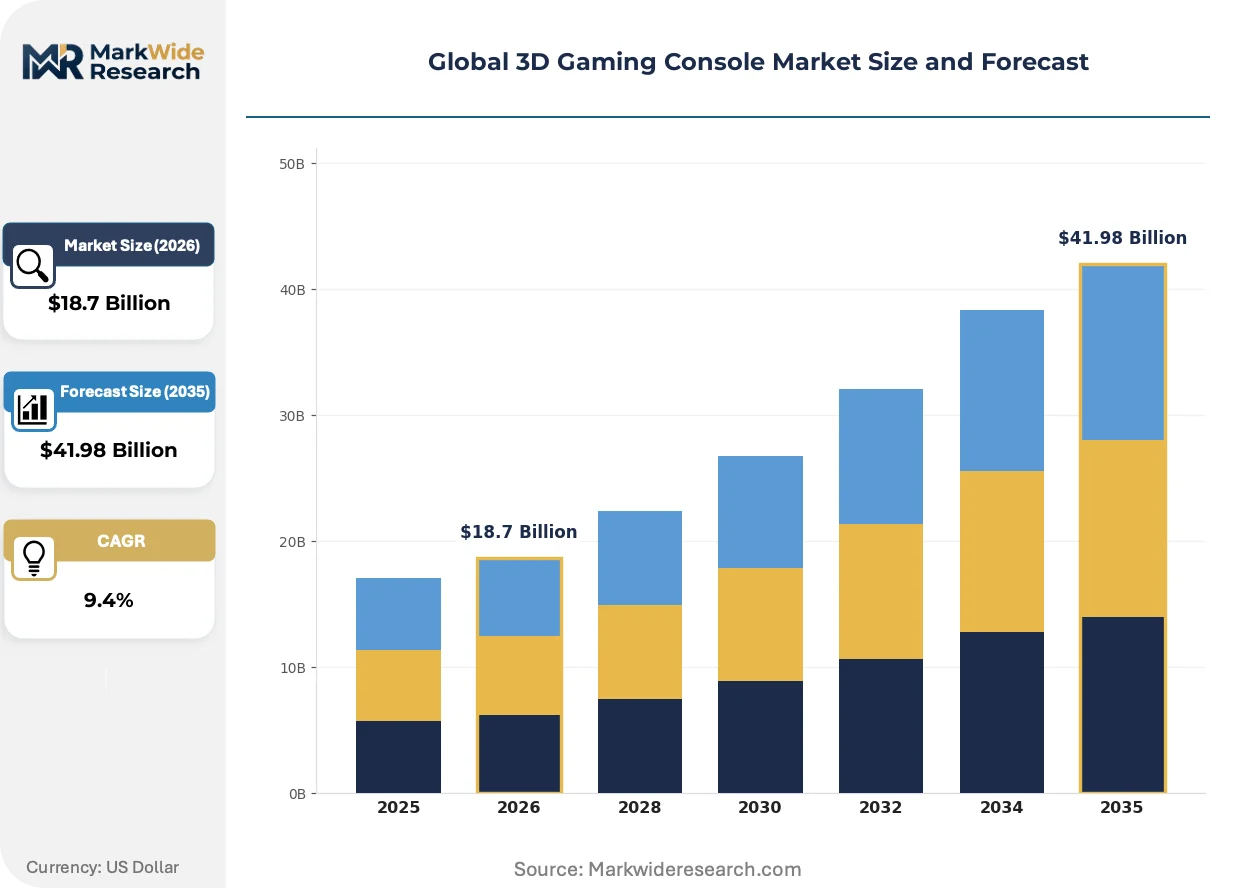
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Consoles, Home Consoles, Hybrid Consoles, Streaming Devices Technology: Augmented Reality, Virtual Reality, Motion Sensing, Cloud Gaming End User: Casual Gamers, Professional Gamers, Families, Educational Institutions Distribution Channel: Online Retail, Specialty Stores, Mass Merchants, Direct Sales |
| Companies Covered | Sega Sammy Holdings Inc., Atari Inc., Sony Group Corp., Meta Platforms Inc., Valve, Microsoft Corp., Logitech International SA, Razer, Nintendo Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Gaming Console Market Emerging Trajectories
Real-time neural rendering and haptic feedback standardization are converging to redefine sensory fidelity benchmarks, while regulatory pressure on energy consumption is forcing silicon architecture trade-offs between performance and efficiency.
AI-driven upscaling silicon is automating resolution reconstruction from lower internal render targets, allowing 4K output on thermally constrained mobile chipsets. Nintendo and Valve are integrating these tensor cores into handheld form factors previously limited to 720p native rendering. This compression of visual quality per watt is automating the displacement of discrete desktop-class GPUs in portable segments.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon-based cooling solutions in high-performance console manufacturing. Manufacturers are pivoting to vapor chamber and liquid metal thermal interfaces to maintain clock speeds under tighter environmental constraints. Premium home console SKUs face the steepest redesign requirements to maintain boost frequencies without prohibited refrigerants.
Subscription fatigue is fragmenting library access across multiple competing services rather than consolidating around single-platform ownership. Casual players in South Korea and Japan are rotating between Sony, Microsoft, and regional cloud providers monthly rather than maintaining continuous annual commitments. This churn pattern is compressing customer lifetime value calculations and forcing retention spending toward exclusive content windows rather than infrastructure scale.
Global 3D Gaming Console Market Segmentation
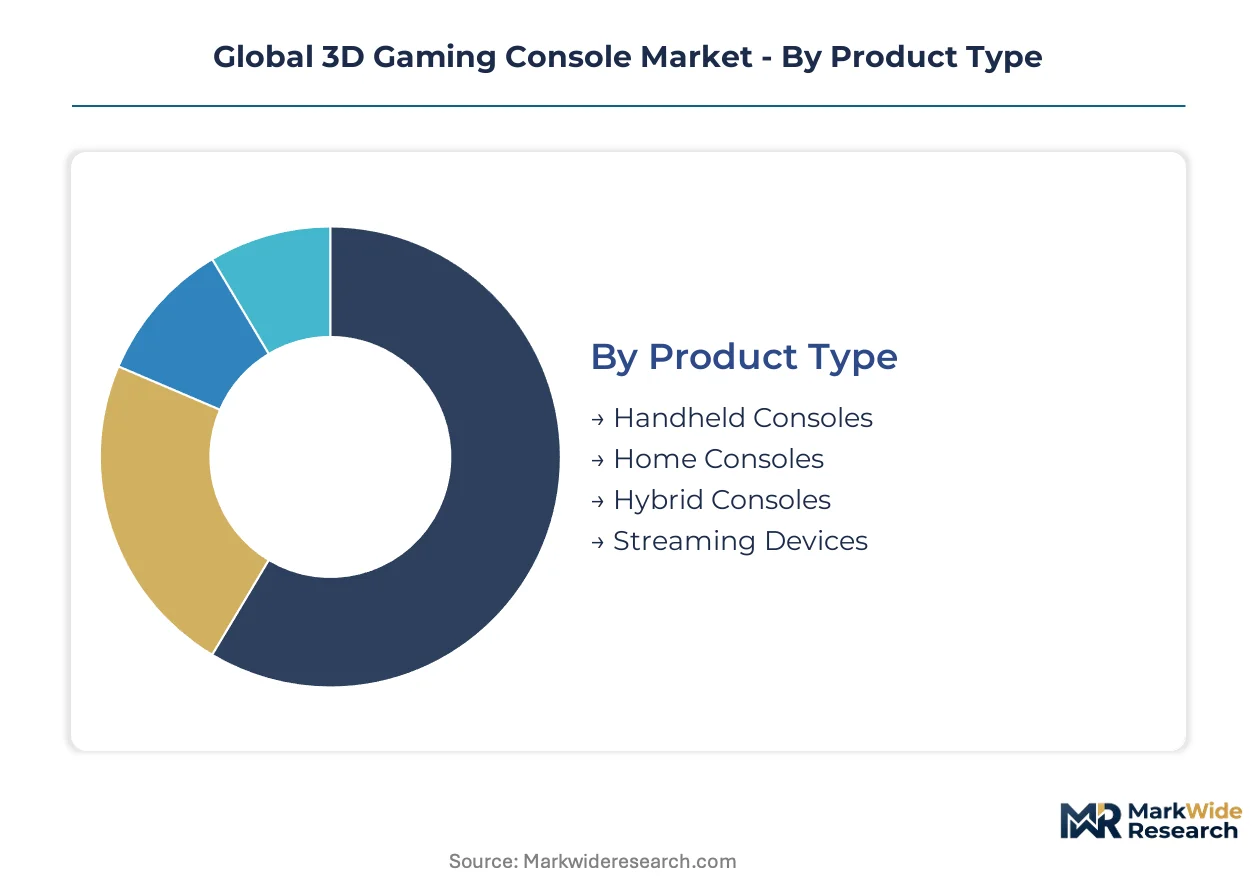
Segmentation in the 3D gaming console market reveals how hardware form factors, immersive technologies, user demographics, and channel economics create distinct competitive battlegrounds. Each dimension carries unique margin profiles and regulatory exposure that shape manufacturer resource allocation.
Product Type:
Purchase decisions hinge on portability requirements versus performance thresholds, with price elasticity varying dramatically across living-room, mobile, and dual-mode use cases.
- Home Consoles:Stationary systems deploy discrete GPUs with thermal budgets exceeding 200 watts, enabling native 4K rendering and ray-traced lighting. Demand concentrates in the United States and Japan where broadband infrastructure supports 100GB+ title downloads and living-room entertainment centers remain culturally central.
- Hybrid Consoles:Dockable portable architectures switch between battery-constrained 720p handheld output and 1080p docked television display through dynamic power scaling. Families in South Korea and urban Japan prioritize these for commute-to-couch flexibility, driving Nintendo's persistent SKU dominance in this bracket.
- Handheld Consoles:Pure-portable devices with fixed 5-7 inch OLED panels and ARM-based SoCs target price-sensitive younger demographics.
- Streaming Devices:Low-latency codec decoders paired with controller peripherals access cloud-rendered streams without local GPU investment.
Home consoles lead on scale; hybrid consoles lead on momentum.
Technology:
Immersion depth determines hardware bill-of-materials and certification complexity, with spatial computing tiers demanding divergent optical and sensor investments.
- Virtual Reality:Head-mounted displays integrate micro-OLED panels with pancake lens stacks and inside-out tracking cameras, requiring FCC authorization for 60 GHz wireless link bands in the United States. Professional gamers and simulation enthusiasts in Japan drive replacement cycles as field-of-view expands past 110 degrees.
- Cloud Gaming:Edge-rendered video streams eliminate local silicon requirements, shifting value capture toward subscription platforms and datacenter operators. Casual gamers across India and Southeast Asia access AAA libraries through 5G smartphones without console hardware expenditure, compressing addressable market definitions for traditional OEMs.
- Augmented Reality:Passthrough camera overlays blend synthetic assets with physical environments through depth-sensing time-of-flight modules.
- Motion Sensing:Inertial measurement units and depth cameras translate physical gesture into input commands, now standard across hybrid controller arrays.
Cloud gaming scales fastest in user count; VR climbs fastest in revenue per user.
End User:
Session length, content genre preference, and peripheral willingness-to-pay diverge sharply across demographic cohorts, fragmenting marketing spend and exclusive title development.
- Casual Gamers:Intermittent players averaging under five weekly hours favor free-to-play mobile ports and family-friendly Nintendo franchises. South Korean commuters and Indian smartphone-first users dominate this cohort, with cloud streaming substituting for hardware purchases.
- Professional Gamers:Esports competitors and content creators demand sub-10ms input latency, 240Hz refresh rates, and tournament-legal controller standardization. The United States hosts the largest concentration of sponsored teams and streaming infrastructure investment.
- Families:Multi-account household systems prioritize parental controls, local multiplayer titles, and durable hardware warranties.
- Educational Institutions:Schools and universities deploy VR labs for STEM visualization and medical training simulations, accessing institutional procurement channels.
Casual gamers dominate installed base; professional gamers dominate accessory attach rates.
Distribution Channel:
Channel selection determines margin retention, inventory risk allocation, and post-sale service obligation intensity, with digital acceleration reshaping physical retail economics.
- Online Retail:E-commerce platforms capture the majority of hardware transactions in the United States and South Korea, with Amazon and regional marketplaces bundling extended warranties and trade-in programs. Direct-to-consumer logistics from Shenzhen manufacturing clusters compress landed costs.
- Specialty Stores:Gaming-focused retailers provide hands-on demo stations, midnight launch events, and used-game resale ecosystems. Japan's dense urban retail culture sustains higher physical channel share than Western markets.
- Mass Merchants:Big-box retailers rely on console hardware as traffic drivers with thin margins, monetizing through high-margin accessory and software attach.
- Direct Sales:Manufacturer-owned stores and websites capture full retail margin while controlling brand presentation and first-party accessory bundling.
Online retail leads on volume velocity; specialty stores lead on experiential differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands premium hardware margins through entrenched console culture, while India captures attention through smartphone-first cloud adoption at vastly lower price points.
United States
FCC equipment authorization for 60 GHz mmWave wireless peripherals accelerates accessory ecosystem expansion. The Inflation Reduction Act's domestic manufacturing incentives nudge assembly toward Arizona and Texas facilities. Esports broadcasting infrastructure concentrates in Los Angeles and Atlanta, driving volumetric capture studio investment.
Japan
METI technical standards for radio equipment safety extend product development timelines by four to six months for RF shielding redesigns. Tokyo and Osaka anchor the world's densest specialty retail culture, sustaining hands-on demo stations and midnight launch events. Professional gamers and simulation enthusiasts drive VR headset replacement cycles as field-of-view specifications widen.
South Korea
Commute-to-couch flexibility fuels hybrid console demand among urban families in Seoul and Busan. 5G infrastructure density enables mobile cloud gaming substitution for dedicated hardware purchases. Casual players rotate between multiple subscription services monthly, compressing customer lifetime value calculations.
China
MIIT certification requirements for wireless equipment create localized compliance barriers for foreign OEMs. Shenzhen manufacturing clusters compress direct-to-consumer logistics costs for online retail channels. Domestic cloud gaming platforms capture casual session time through smartphone-first distribution.
Germany
EU F-Gas Regulation phase-down schedules restrict hydrofluorocarbon cooling solutions, forcing vapor chamber thermal redesigns. Ecodesign standby power mandates below 0.5 watts favor ARM-based architectures in portable systems. Berlin and Munich host institutional VR lab procurement for STEM visualization applications.
Global 3D Gaming Console Market Vendor Landscape
Top-tier vendors anchor platform ecosystems through proprietary hardware-software integration, while mid-tier specialists occupy peripheral and accessory niches. The market structure reflects concentrated control over core console architectures alongside fragmented competition in controllers, headsets, and input devices. Two strategic archetypes dominate: integrated platform operators bundling subscription services with proprietary silicon, and component specialists extracting margin from attach-rate economics. Competitive moves center on exclusive content windowing and backward compatibility investments that extend platform lock-in.
Among platform-integrated conglomerates, Sony Group Corp., Microsoft Corp., and Nintendo Co. Ltd. exemplify divergent responses to cloud gaming disruption. Sony leverages PlayStation Plus infrastructure for recurring revenue across hybrid endpoints. Microsoft anchors competitive positioning through Xbox Game Pass extension beyond proprietary hardware. Nintendo sustains demand through exclusive first-party intellectual property rather than broad subscription bundling.
| Leading Market Players |
|---|
| Sega Sammy Holdings Inc. |
| Atari Inc. |
| Sony Group Corp. |
| Meta Platforms Inc. |
| Valve |
| Microsoft Corp. |
| Logitech International SA |
| Razer |
| Nintendo Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Micro-OLED panel yield improvements in South Korean fabrication facilities are compressing bill-of-materials costs for VR headsets while simultaneously concentrating display supply among three dominant suppliers, creating asymmetric pricing power that favors integrated platform operators over peripheral specialists.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for leading-edge GPU silicon, forcing console OEMs toward three-tier pricing structure across premium, standard, and economy levels differentiated by thermal envelope and storage configuration. Certification tier under FCC equipment authorization and METI technical standards commands measurable brand premium. Cost compression in entry-level streaming devices is intensifying because ARM-based SoC commoditization erodes hardware differentiation. Casual gamers in India exhibit highest price sensitivity; professional esports competitors in the United States show lowest.
Supply Chain Analysis
Refurbishment flows for legacy console hardware create secondary market liquidity that buffers new-unit demand volatility, with certified pre-owned programs extending platform ecosystem reach. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States; final assembly clusters in China and Mexico. Advanced packaging substrates and gallium nitride power components constitute critical input dependencies. Single-source vulnerability in CoWoS advanced packaging capacity presents structural risk. Distribution runs through direct-to-consumer online channels and mass merchant retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global 3D Gaming Console Market reads as a late-cycle quality story where premium specifications—micro-OLED resolution, haptic fidelity, neural rendering capability—now determine purchase decisions rather than base hardware accessibility.
For Market Incumbents: Cement platform lock-in through exclusive content windowing and backward compatibility certification investments that extend customer lifetime value. Threat from cloud gaming substitution demands defensive response. Vertical integration into custom silicon design offers sustainable margin protection against ARM-based commodity alternatives.
For New Entrants and Emerging Players: FCC streamlined authorization pathways for 60 GHz wireless peripherals in the United States open a window for accessory ecosystem specialists to capture attach-rate economics without platform infrastructure investment. White-space targets include prescription gamification hardware for healthcare rehabilitation and Hindi-language voice interface development for India's smartphone-first gamer base. Go-to-market through institutional procurement channels for educational VR labs bypasses consumer marketing spend intensity.
For Investors and Strategic Acquirers: Valuations sit cheapest among component specialists with captive thermal interface and haptic feedback IP. Long-term viability hinges on recurring revenue attachment rather than discrete hardware cycles. Acquisition target archetype: mid-cap peripheral manufacturers with established certification pipelines and direct-to-consumer logistics infrastructure. Signal to watch: Medicare reimbursement pathway expansion for prescription gamification devices.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Xbox Game Pass and PlayStation Plus infrastructure extension beyond proprietary hardware captures recurring revenue across endpoints. |
| Product Launch | Hybrid console architectures with dynamic power scaling address commute-to-couch flexibility demands in South Korean and Japanese urban markets. |
| Strategic Partnership | Volumetric capture studio alliances with esports broadcasters create parallel content licensing revenue beyond direct hardware sales. |
| Acquisition of Specialist Firm | Neural radiance fields engineering talent scarcity makes real-time photogrammetry studios attractive targets for first-party exclusive development acceleration. |
| Geographic Expansion | Localized payment integration and voice interface development unlocks India's 450 million smartphone gamer base for premium experience conversion. |
Methodological Framework
Direct dialogue with console platform executives, semiconductor procurement leads at OEMs, esports tournament operators, and specialty retail category managers grounds qualitative assessment, cross-referenced against SEC 10-K filings, FCC equipment authorization databases, METI technical standard submissions, and hyperscaler cloud gaming capex disclosures. Bottom-up unit economics triangulate with top-down market sizing across hardware shipments and subscription attach rates.
Segmentation-level projections across product type, immersive technology tier, end-user demographic, and distribution channel structure the analytical framework over the projection horizon. CAGRs derive from installed base replacement cycles, cloud subscriber conversion assumptions, and regional broadband infrastructure penetration curves. Forecast inputs incorporate VR headset weight reduction trajectories and EU F-Gas Regulation thermal design constraint timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Taiwan semiconductor supply disruption scenarios or accelerated Medicare reimbursement for healthcare gamification applications. Practitioners should monitor cloud gaming subscriber churn patterns in South Korea and Japan, plus FCC authorization velocity for 60 GHz wireless peripherals, for early demand inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
South Korea Subscription-Based Gaming Market
Gaming
China Gaming Headsets Market
Gaming
H5 Games Market
Gaming
MMORPG Gaming Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
Online Casino Market
Gaming
GCC Gaming Headsets Market
Gaming
Arcade Games Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
Connected Game Console Market
Gaming
North America Gaming Hardware and Accessories Market
Gaming
VR Gaming Market
Gaming
VR Melee Games Market
Gaming
Global Online Adventure Games Market
Gaming
Gaming Hardware Market
Gaming
Mobile Gaming Market