
 Global Professional Audio Market | 2026-2036
Global Professional Audio Market Size, Share, and Industry Trends Forecast 2026-2036
Global Professional Audio Market Foresight
Neodymium magnet substitution for ferrite cores is repositioning loudspeaker motor economics, reducing driver weight by roughly half while preserving flux density. JBL Professional leverages vertical integration in transducer manufacturing to control raw magnet supply chains. Meyer Sound differentiates through proprietary beam-steering DSP platforms that command premium positioning in installed sound. L-Acoustics dominates touring rental networks, with its K-series enclosures anchoring rider specifications for major global productions.
Professional audio encompasses engineered sound reinforcement, recording, and broadcast systems operating across line-level signal chains from twenty hertz to twenty kilohertz, with loudspeaker sensitivity ratings typically exceeding ninety decibels at one watt per meter. Microphones and networked technology segments are expanding fastest, as Dante/AES67 protocol adoption displaces analog snake runs in live production and broadcast infrastructure. Mixers and amplifiers retain mature margin pools in fixed installations, though digital console price compression is squeezing mid-tier manufacturers. Wireless technology faces spectrum reallocation headwinds, pushing demand toward frequency-agile systems with automated coordination.
FCC spectrum auctions in the United States and Ofcom clearance sales in the United Kingdom are forcing wireless microphone operators into narrower UHF bands, accelerating hardware refresh cycles. CE marking under the EU Radio Equipment Directive and RED cybersecurity provisions govern market access for networked audio devices across Europe. Stakeholders must monitor regulatory spectrum decisions in multiple jurisdictions while calibrating R&D bets between analog reliability and digital interoperability architectures.
Market Dynamics
The EU F-Gas Regulation is forcing amplifier manufacturers to abandon fluorinated refrigerants in cooling systems, triggering a wholesale redesign of thermal management architectures while live touring schedules drive parallel demand for lighter, networked systems.
Growth Catalysts
- Neodymium magnet adoption:Ferrite core substitution in loudspeaker motors halves driver weight without sacrificing flux density, enabling compact line array deployments in mid-sized venues across Germany and the United States.
- Dante/AES67 protocol standardization:Networked audio infrastructure displaces analog snake runs in broadcast and live production, reducing cabling mass and signal degradation over distance.
- Resurgent touring economics:Live event production companies in Nashville, London, and Berlin are expanding rental inventories to capture reopened festival circuits and arena residency schedules.
Market Restraints
- Rare earth supply concentration:Neodymium processing capacity clusters in China, exposing transducer manufacturers to export quota volatility and price spikes.
- Spectrum scarcity:FCC auctions and Ofcom clearance sales compress available UHF bands for wireless microphone operation, forcing premature hardware obsolescence.
- Amplifier thermal redesign costs:F-Gas compliance necessitates alternative cooling architectures that increase bill-of-materials complexity for Class D and Class AB designs.
Strategic Opportunities
- Immersive audio installations:Object-based mixing formats are penetrating cinema and themed entertainment venues in the United Arab Emirates and Saudi Arabia, creating demand for high-channel-count processors.
- Software-defined DSP platforms:Beam-steering algorithms and room correction tools converge with cloud-based configuration management, enabling remote system tuning for installed sound contractors.
- EU Green Deal procurement incentives:Public venue tenders in France and the Netherlands now weight lifecycle carbon metrics, favoring repairable, modular loudspeaker designs over sealed disposable enclosures.
Industry Challenges
- RF coordination expertise gap:Frequency-agile wireless system deployment requires specialized spectrum engineering skills that rental houses and venue staff increasingly lack.
- Legacy analog integration friction:Dante-native installations must interoperate with existing copper infrastructure in renovated theaters and houses of worship, complicating signal path verification.
- CE marking cybersecurity compliance:The EU Radio Equipment Directive's RED provisions mandate network security documentation that stretches certification timelines for networked audio device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Professional Audio Market |
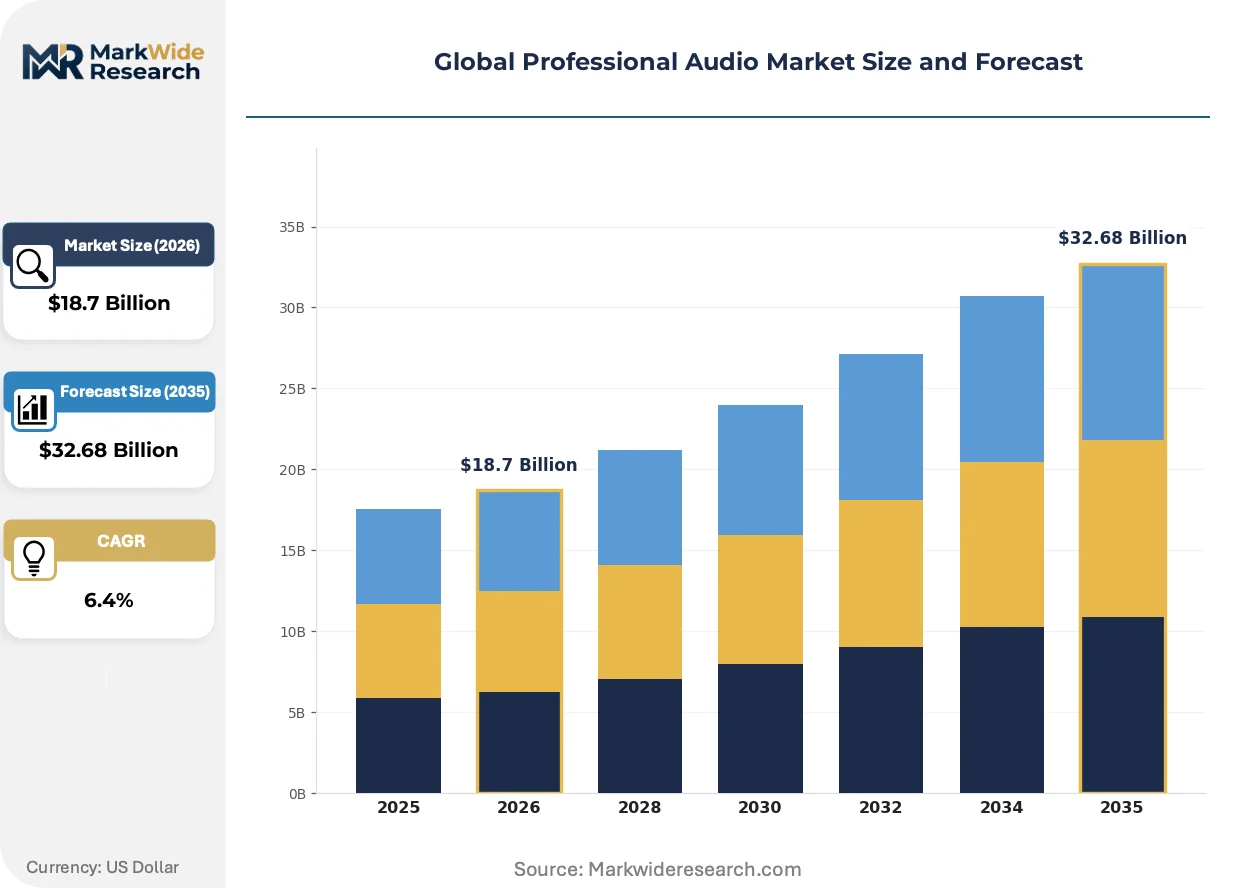
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microphones, Mixers, Amplifiers, Speakers Application: Live Events, Studios, Broadcast, Conferences End User: Musicians, Event Organizers, Broadcasters, Educational Institutions Technology: Analog, Digital, Wireless, Networked |
| Companies Covered | JBL Professional, QSC, L-Acoustics, Electro-Voice, Shure Incorporated, Meyer Sound, Yamaha Corporation, Allen & Heath, d&b audiotechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Professional Audio Market Shifts & Advancements
Networked audio protocols and software-defined signal processing are collapsing traditional hardware boundaries, while regulatory pressure on materials and spectrum forces architectural bets on modularity and frequency agility.
Audio-over-IP transport is overtaking copper-based snake systems in live production environments. Festival staging companies in the United Kingdom and touring operators in the United States are deploying redundant Dante networks for main and monitor feeds. This shift compresses physical infrastructure costs while raising cybersecurity exposure that manufacturers must address through encrypted control plane implementations.
The EU F-Gas Regulation is accelerating heat pipe and liquid cooling adoption in high-power amplification. Manufacturers serving installed sound markets in Germany and France are engineering sealed thermal systems that eliminate refrigerant dependence entirely. Compliance investments favor larger firms with captive thermal engineering capabilities, pressuring mid-tier amplifier specialists to outsource or exit the segment.
Rental fleet operators are compressing equipment refresh cycles to capture spectrum-compliant wireless inventory before further UHF reallocations. Major production services in London and Los Angeles are retiring 470-694 MHz systems ahead of regulatory deadlines, redirecting capital toward 1.9 GHz and 2.4 GHz adaptive solutions. This behavior concentrates procurement leverage with frequency-agile platform vendors who can guarantee multi-territory compliance.
Global Professional Audio Market Segmentation
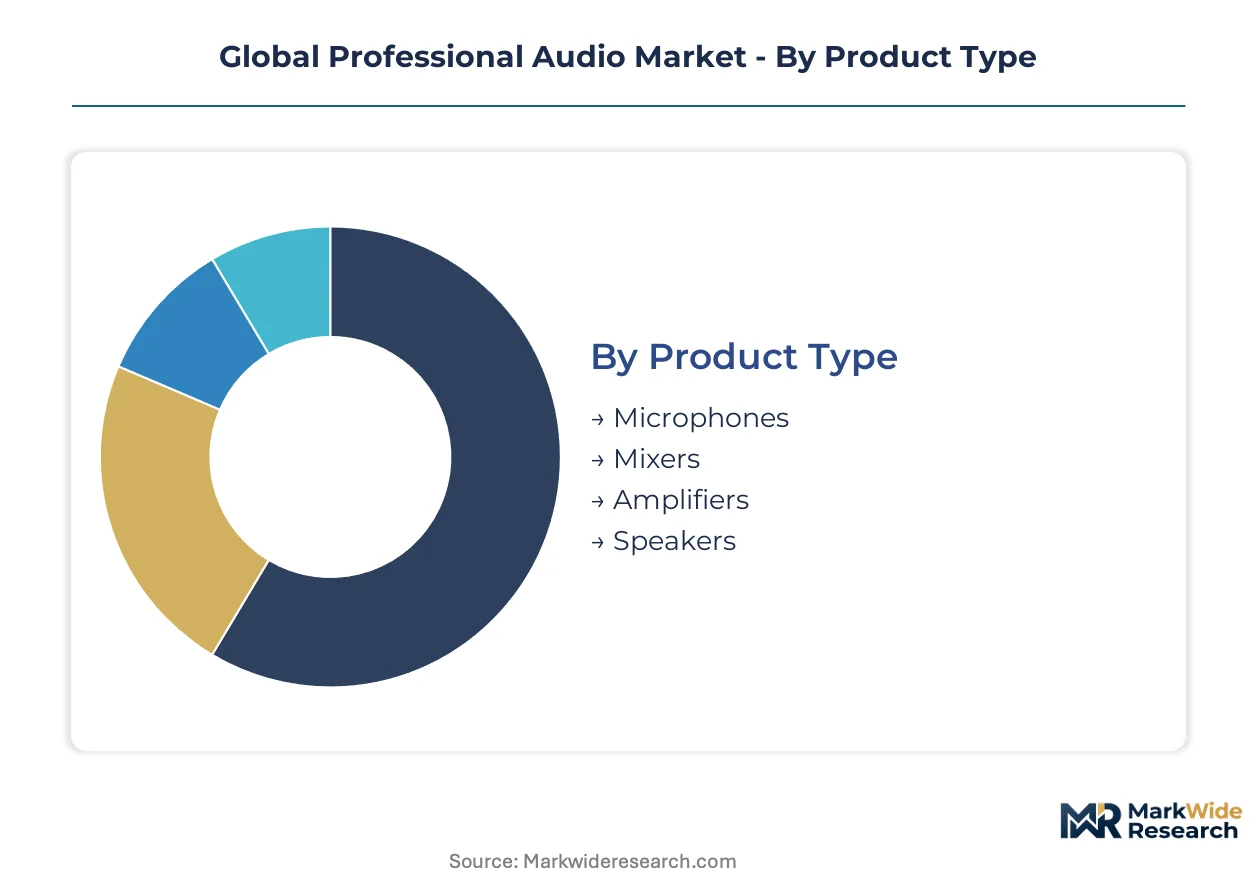
Professional audio procurement patterns diverge sharply across use cases, with touring operators prioritizing ruggedized portability while broadcast engineers demand pristine signal fidelity. Understanding these segment boundaries clarifies where component manufacturers should concentrate R&D investment versus where systems integrators capture margin.
Product Type:
Cost tier differentiation separates commodity transducer suppliers from precision electronics specialists serving distinct buyer budgets.
- Speakers:Enclosure designs span point-source boxes to complex line arrays with neodymium motor assemblies. Rental houses in Germany and the United States are standardizing on modular, flyable systems that reduce truck pack volume. Demand concentrates in touring infrastructure where weight reduction directly cuts freight expenditure.
- Microphones:Transducer capsules convert acoustic pressure to electrical signals through condenser, dynamic, or ribbon architectures. Broadcasters in London and Nashville are refreshing inventories with RF-shielded models as spectrum congestion intensifies. This segment is expanding most quickly as content production volume multiplies across streaming platforms.
- Mixers:Control surfaces manage gain staging, EQ, and routing across analog or digital signal paths.
- Amplifiers:Power electronics drive loudspeaker loads with Class D efficiency gains displacing linear topologies in new installations.
Volume sits with Speakers; growth tilts toward Microphones.
Application:
Maturity gradients separate established installed-base markets from emerging deployment categories with divergent replacement cycles.
- Live Events:Temporary sound reinforcement for festivals, concerts, and corporate presentations demands rapid deployment and strike capability. Production companies in Berlin and Los Angeles are expanding rental fleets to capture reopened touring schedules. This application carries the steepest expansion trajectory as experiential entertainment spending rebounds.
- Broadcast:Controlled-environment audio capture and distribution requires redundant signal paths and broadcast-standard clocking. Networked audio-over-IP infrastructure is displacing copper in London and New York facilities. Regulatory pressure on wireless spectrum is accelerating hardware refresh timelines.
- Studios:Recording and mixing environments prioritize acoustic isolation and monitoring accuracy.
- Conferences:Corporate and institutional meeting spaces integrate voice reinforcement with video collaboration systems.
Broadcast commands the largest installed base; Live Events is climbing the fastest.
End User:
Technical sophistication and procurement scale separate institutional buyers from individual operators.
- Event Organizers:Festival promoters and venue operators contract production services or maintain captive audio departments. Large-scale operators in the United Arab Emirates and Saudi Arabia are specifying immersive audio formats for new entertainment infrastructure. Capital deployment concentrates in markets with public venue investment programs.
- Broadcasters:Television networks and streaming platforms operate centralized technical facilities with standardized signal chains. Public broadcasters in Germany and France are weighting lifecycle carbon metrics in tender evaluations. This buyer category demands multi-territory compliance documentation.
- Musicians:Individual performers and ensembles purchase portable reinforcement for rehearsal and small-venue performance.
- Educational Institutions:Universities and conservatories maintain teaching facilities and performance venues with hybrid installed-portable inventories.
Broadcasters anchor procurement volume; Event Organizers are gaining share fastest.
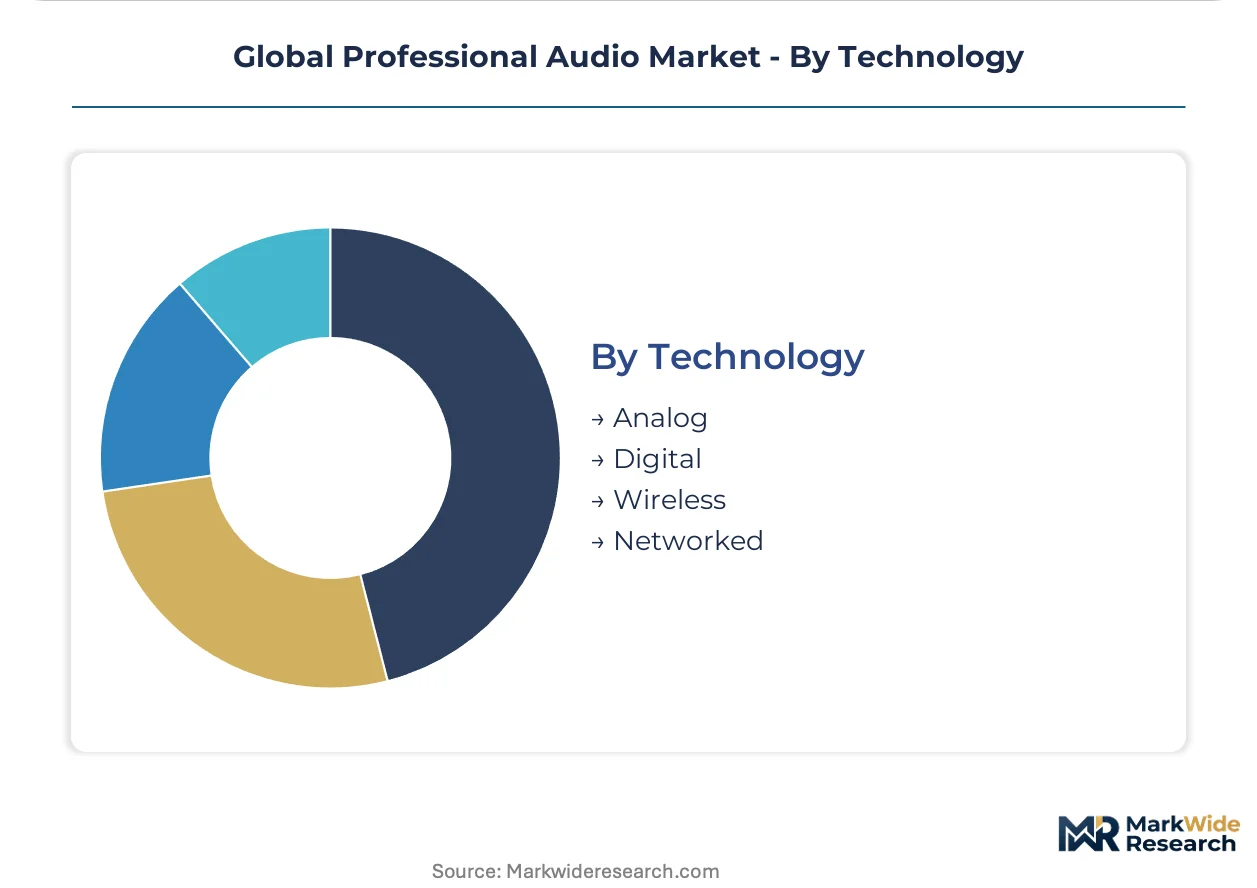
Technology:
Architecture choices determine interoperability boundaries and long-term obsolescence risk for capital-intensive installations.
- Networked:Dante/AES67 protocol transport enables packet-switched audio distribution over standard Ethernet infrastructure. Festival staging in the United Kingdom and touring operations in the United States are deploying redundant networks for main and monitor feeds. Signal routing flexibility is displacing copper snake systems in greenfield projects.
- Wireless:Radio-frequency transmission liberates performers from cable tethers across UHF and emerging 1.9 GHz bands. FCC auctions and Ofcom clearance sales are compressing available spectrum, forcing migration to frequency-agile platforms. Hardware obsolescence risk is accelerating replacement cycles among rental operators.
- Digital:Discrete-time signal processing enables recallable configurations and integrated dynamics control.
- Analog:Continuous-time circuitry persists in critical paths where latency and conversion artifacts are unacceptable.
Digital retains the largest installed footprint; Networked is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates professional audio procurement through Messe Frankfurt's exhibition infrastructure and Berlin's dense club ecosystem. The United States, United Kingdom, China, and Japan each anchor distinct demand centers shaped by touring economics, broadcast standards, and manufacturing specialization.
Germany
Festival circuits and installed venue infrastructure drive loudspeaker and amplifier demand across the country. The EU F-Gas Regulation mandates elimination of fluorinated refrigerants from cooling systems, forcing thermal architecture redesigns. Messe Frankfurt and Berlin anchor procurement activity, with rental houses standardizing on modular flyable systems to reduce truck pack volume.
United States
Resurgent arena residencies and touring schedules expand rental fleet procurement in Nashville and Los Angeles. FCC spectrum auctions compress available UHF bands for wireless microphone operation, accelerating hardware obsolescence. Production services in these cities are retiring legacy systems and redirecting capital toward frequency-agile platforms.
United Kingdom
Broadcast facility upgrades and festival staging operations sustain networked audio infrastructure demand. Ofcom clearance sales force wireless operators into narrower spectrum bands, triggering premature replacement cycles. London production services are deploying redundant Dante networks for main and monitor feeds in live environments.
China
Domestic manufacturing capacity for neodymium magnet processing underpins transducer supply chains serving global markets. Export quota volatility on rare earth materials exposes loudspeaker motor producers to price spikes. Industrial clusters in processing regions concentrate magnet refinement capabilities that feed downstream driver assembly.
Japan
Precision electronics manufacturing and broadcast engineering standards sustain demand for high-fidelity signal processing equipment. METI industrial policy supports advanced audio technology development through targeted funding programs. Tokyo technical facilities maintain centralized signal chains with networked audio-over-IP infrastructure displacing legacy copper systems.
Global Professional Audio Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with loudspeaker and electronics production showing divergent consolidation patterns. The vendor base organizes around three archetypes: vertically integrated transducer manufacturers controlling magnet supply chains, DSP platform developers commanding premium positioning through proprietary beam-steering algorithms, and touring-focused rental network operators standardizing rider specifications. Dominant competitive moves include captive supply chain integration for rare earth materials and accelerated refresh cycles to capture spectrum-compliant wireless inventory.
Among vertically integrated specialists, JBL Professional and Meyer Sound exemplify contrasting strategic positions. JBL Professional represents the transducer manufacturing archetype with in-house magnet supply chain control. Meyer Sound occupies a position within the DSP platform tier, differentiating through proprietary signal processing architectures. L-Acoustics anchors the touring rental network vector, with enclosure specifications penetrating major global production rider requirements.
| Leading Market Players |
|---|
| JBL Professional |
| QSC |
| L-Acoustics |
| Electro-Voice |
| Shure Incorporated |
| Meyer Sound |
| Yamaha Corporation |
| Allen & Heath |
| d&b audiotechnik |
| Others |
Supply & Pricing Matrix
Touring rental house procurement concentration in Germany and the United States anchors transactional pricing for loudspeaker enclosures and amplifier systems, with volume commitments commanding standard-tier positioning while boutique broadcast installations absorb premium markups for certified precision electronics.
Pricing Analysis
Volume procurement by festival staging operators concentrates in standard-tier line arrays and networked amplifiers, while broadcast facility upgrades sustain premium pricing for RF-shielded microphones and redundant Dante processors. Price differentiation rests on certification grade and after-sales service bundling rather than raw performance metrics. Cost compression in mid-tier digital consoles is intensifying because of Asian manufacturing scale, squeezing regional specialists. Corporate AV integrators exhibit highest price sensitivity; touring rental houses prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Singapore orchestrate hub-and-spoke fulfillment to rental houses and broadcast integrators across Europe and Asia-Pacific. Magnet processing clusters in China, driver assembly in Mexico, and precision electronics in Japan constitute the tripartite sourcing base. Neodymium, ferrite cores, and DSP chipsets represent critical input dependencies. Single-source vulnerability in rare earth refining exposes transducer manufacturers to export quota disruptions. Distribution runs through authorized dealer networks with direct-to-rental-house accounts for high-volume touring accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The professional audio sector sits in a protocol-transition phase where Dante/AES67 networked infrastructure displaces legacy copper snake systems, forcing architectural bets on digital interoperability over analog reliability.
For Market Incumbents: To counter frequency-agile wireless entrants from Asian electronics manufacturers, JBL Professional and Meyer Sound should deepen backward integration into magnet supply chains and accelerate RF-shielded microphone R&D. Captive neodymium sourcing insulates margin structures from Chinese export volatility. Certification investment for EU RED cybersecurity compliance preserves European market access against mid-tier challengers.
For New Entrants and Emerging Players: Direct-to-rental-house digital platforms offer the lowest-friction entry vector for software-defined DSP tools and cloud-based room correction services. White-space targets include immersive audio processors for Middle Eastern entertainment infrastructure and frequency-agile wireless systems for compressed UHF bands. The most penetrable segment is mid-sized venue installed sound, where legacy analog integration friction creates deployment gaps.
For Investors and Strategic Acquirers: The window for entry favors DSP platform developers with proprietary beam-steering algorithms and touring-network rental operators with standardized rider penetration. Long-term viability hinges on protocol dominance rather than hardware manufacturing scale. The signal to monitor is FCC and Ofcom spectrum auction outcomes, which will determine obsolescence velocity for legacy wireless inventory and consolidation timing among rental houses.
| Strategic Initiative | Industry Significance |
|---|---|
| Neodymium Supply Agreement | Backward integration into Chinese magnet processing secures flux density for lightweight line array motors. |
| Dante Certification Program | Networked audio protocol compliance opens procurement channels to BBC and German public broadcaster tenders. |
| Frequency-Agile Wireless Launch | Adaptive RF platforms capture rental house refresh cycles ahead of FCC 600 MHz clearance deadlines. |
| Immersive Audio Processor Development | Object-based mixing formats penetrate Saudi entertainment infrastructure and UAE cinema deployments. |
| Thermal Architecture Redesign | F-Gas-compliant heat pipe systems preserve German and French installed sound market access. |
Research Methodology
Independent corroboration across rental house procurement directors, broadcast facility engineers, and amplifier thermal design specialists underwrites the qualitative findings in this study. Primary interviews with touring production managers, venue technical directors, and wireless RF coordination consultants supplied forward-looking demand signals. Secondary validation drew from FCC spectrum auction records, EU F-Gas Regulation implementation guidance, and customs data on neodymium magnet trade flows. Bottom-up equipment shipment analysis and top-down entertainment industry expenditure estimates were cross-referenced for triangulation.
Rate-of-change decomposition across the projection horizon isolates volume effects from mix-shift and pricing dynamics. Segmentation dimensions modeled include product category, application use case, end-user archetype, and technology architecture. CAGRs were derived from fitted trend extrapolation moderated by regulatory inflection points and technology substitution elasticities. Industry-specific forecast inputs incorporate touring schedule density indices and wireless spectrum reallocation timelines.
The model holds under stable regulatory enforcement of EU F-Gas and RED provisions; deviation in rare earth export quotas or accelerated UHF band clearance would shift replacement cycle assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Radio and Audio Media
Podcast Market
Radio and Audio Media
Audiobooks Market
Radio and Audio Media
Digital Audio Market
Radio and Audio Media
Global 3D Audio Market
Radio and Audio Media
Radio Advertising Market
Radio and Audio Media
Traditional Radio Advertising Market
Radio and Audio Media
FM Transmitters Market
Radio and Audio Media
Podcast Hosting Services Market
Radio and Audio Media
Voice Over New Radio Market
Radio and Audio Media
Podcasting Market
Radio and Audio Media
Microphone Market
Radio and Audio Media
Internet Radio Market
Radio and Audio Media
Latin America Soundbar Market
Radio and Audio Media
Audio Mixing Console Market
Radio and Audio Media
Podcast Advertising Market