
 Diethyl Ketone Market | 2026-2036
Diethyl Ketone Market Size, Share, and Industry Trends Forecast 2026-2036
Diethyl Ketone Market Outlook
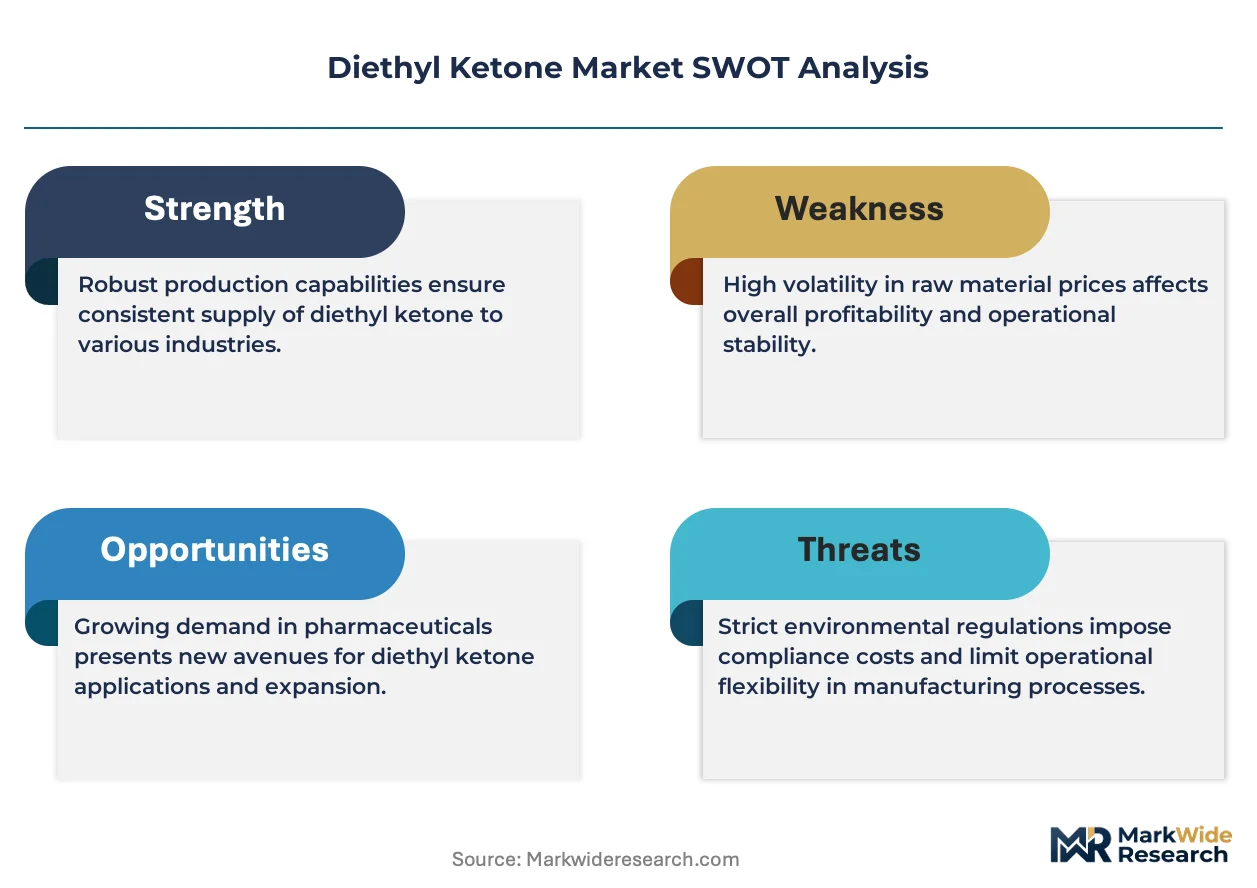
Asset-light leasing arrangements for specialty chemical production equipment is narrowing the capital barrier for mid-scale entrants. BASF SE leverages its integrated European petrochemical network to secure feedstock cost advantages. Alkyl Amines Chemicals Limited anchors its position through backward integration into amine chemistry. Eastman Chemical Company differentiates via proprietary purification technologies that meet pharmaceutical-grade specifications.
Diethyl ketone, also known as 3-pentanone, is a symmetrical dialkyl ketone with the molecular formula C5H10O and a boiling point of 101 degrees Celsius, manufactured primarily through ketonization of propionic acid or dehydrogenation of 3-pentanol over copper-chromite catalysts. It functions as a high-boiling aprotic solvent and chemical intermediate in coatings, adhesives, and pharmaceutical synthesis. The solvent product type dominates volume consumption in industrial coatings applications where slower evaporation rates improve flow and leveling properties. Pharmaceutical-grade intermediate demand is expanding fastest as CDSCO oversight of active pharmaceutical ingredient manufacturing intensifies purity requirements. Chemical reagent sales occupy stable niche positions in analytical laboratories and academic research institutions.
EPA hazardous air pollutant standards under the Clean Air Act constrain solvent emissions from coatings and adhesives operations, pushing formulators toward lower-VOC alternatives or recovery systems. REACH registration requirements in Europe mandate comprehensive toxicological dossiers for diethyl ketone imports above one tonne annually, elevating compliance costs for non-EU suppliers. China's MEE enforces GB standards on volatile organic compound content in industrial coatings, reshaping regional formulation practices. Stakeholders must monitor evolving solvent exemption lists and bio-based ketone development timelines to anticipate substitution risks.
Market Dynamics
Pharmaceutical-grade purity mandates from CDSCO and tightening VOC emissions frameworks across multiple jurisdictions are compressing the supplier base toward integrated producers with captive purification capabilities.
Growth Catalysts
- Active pharmaceutical ingredient synthesis:CDSCO oversight of API manufacturing in India is elevating solvent purity specifications, pulling demand toward pharmaceutical-grade diethyl ketone with documented batch traceability.
- Industrial coatings formulation:Slower-evaporation solvent systems in automotive and protective coatings are preserving diethyl ketone's position in high-build applications where flow control outweighs flash-speed requirements.
- REACH registration compliance:Comprehensive toxicological dossier requirements for imports above one tonne annually are filtering out marginal European suppliers, consolidating volume with established registrants.
Market Restraints
- Propionic acid feedstock volatility:Ketonization economics hinge on petrochemical-derived propionic acid pricing, exposing margins to naphtha and ethylene cycle swings without long-term offtake hedging.
- MEE GB standards enforcement:China's volatile organic compound content limits in industrial coatings are forcing reformulation away from conventional ketone solvents toward exempt compounds or waterborne systems.
- Methyl ethyl ketone substitution:Lower-cost MEK with comparable solvency parameters is displacing diethyl ketone in cost-sensitive adhesive and coating applications where evaporation rate differentials are tolerable.
Strategic Opportunities
- Biobased ketone development:Fermentation-derived pentanone platforms from agricultural feedstocks are opening pathways to renewable content claims for sustainability-mandated coatings procurement.
- Maharashtra chemical belt concentration:Demand clustering near Mumbai's manufacturing infrastructure creates geographic arbitrage for solvent distributors with established tankage and rail connectivity.
- Asset-light equipment leasing:Specialty chemical production equipment leasing arrangements are lowering capital barriers for mid-scale entrants seeking pharmaceutical-grade certification without full greenfield investment.
Industry Challenges
- Pharmaceutical-grade certification timelines:CDSCO and ICH Q3C residual solvent guideline compliance requires extended stability studies and method validation, stretching product qualification cycles to 18-24 months.
- Copper-chromite catalyst supply concentration:Dehydrogenation route dependence on specialized catalyst manufacturers with limited geographic dispersion creates single-source vulnerability for 3-pentanol-based producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diethyl Ketone Market |
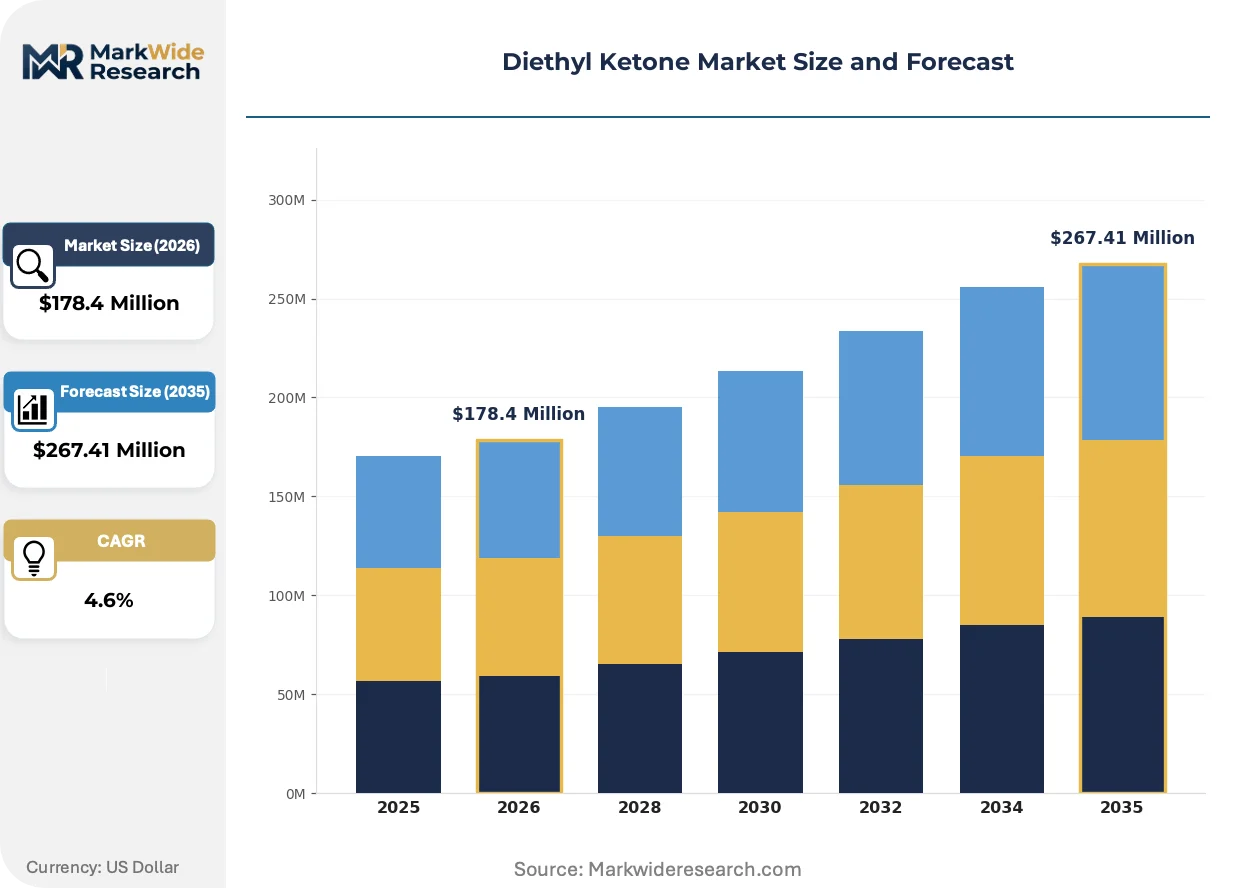
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $267.41 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Intermediate, Chemical Reagent, Additive Application: Coatings, Adhesives, Pharmaceuticals, Cleaning Agents End User: Manufacturing, Cosmetics, Food & Beverage, Textile Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Caffaro Industrie S.p.A, Alkyl Amines Chemicals Limited, BASF SE, Hubei Norna Technology Co. Ltd., Jiangsu Hengxing New Material Technology Co. Ltd., BSM Chemical Co. Ltd., Jeevan Chemicals Private Limited, Eastman Chemical Company, Shanghai Pearlk Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diethyl Ketone Market Strategic Shifts
Process intensification and regulatory chemistry are compressing traditional manufacturing economics while opening differentiated positioning through purity tiering and renewable feedstock claims.
Membrane-based solvent recovery systems are achieving 95%+ recovery rates in coatings operations, cutting virgin solvent purchases by half for integrated facilities. Large automotive OEM paint shops in Germany and the US are deploying these units at scale. This technology is rendering obsolete the open-loop solvent consumption model that sustained historical diethyl ketone volume growth.
REACH authorization requirements for Substances of Very High Concern are expanding the compliance burden for ketone importers into the European Economic Area. ECHA's 2024-2025 work program targets additional solvent substances for restriction evaluation. Pharmaceutical intermediate suppliers are responding by accelerating registration dossier updates and substituting where technically feasible.
Formulators are unbundling solvent specifications from incumbent supplier relationships, issuing multi-source qualification mandates to de-risk concentration exposure. Tier-one coatings manufacturers in Maharashtra and Guangdong are running parallel supplier trials. This pattern is most pronounced in India, where CDSCO audit schedules have made dual-source API-grade solvent sourcing a procurement priority.
Diethyl Ketone Market Segmentation
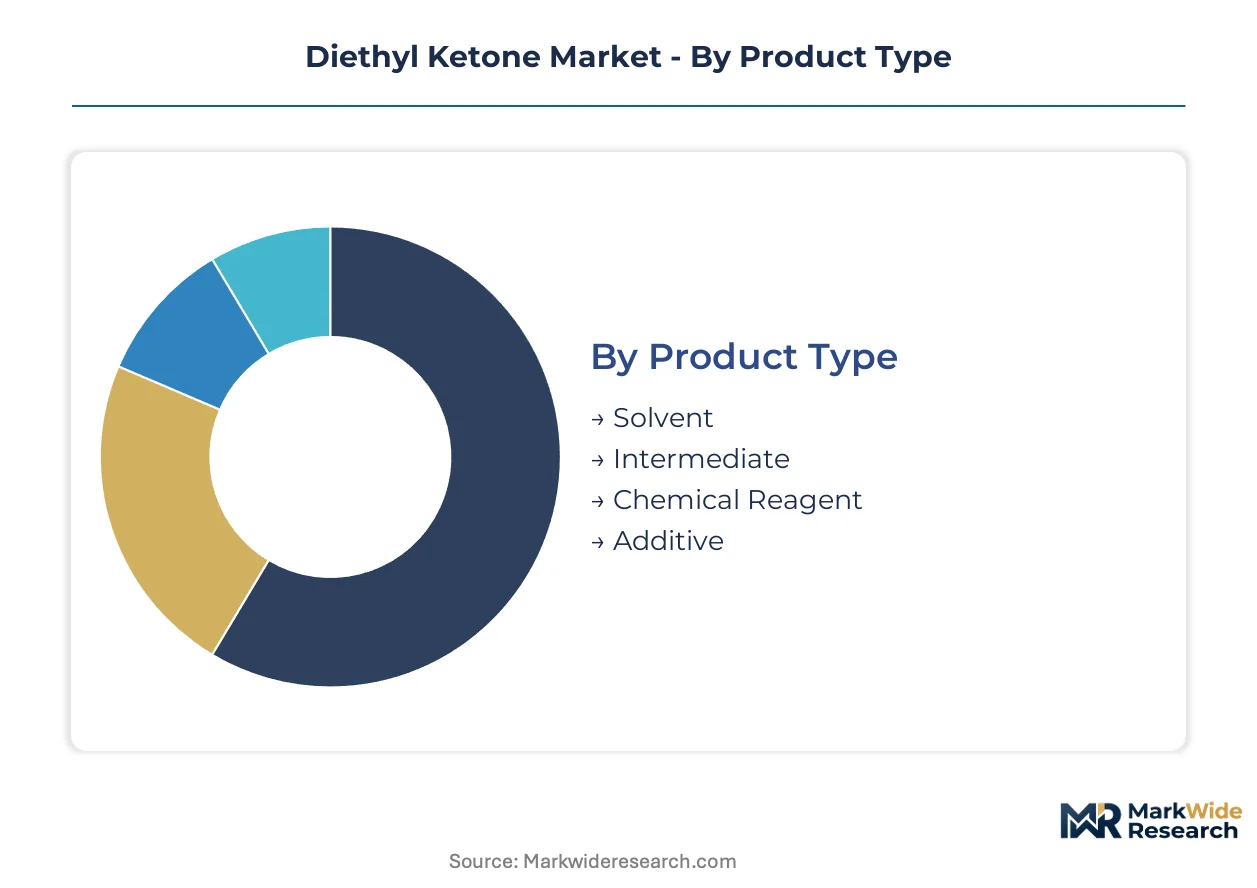
Diethyl ketone's versatility across solvent, intermediate, and reagent functions creates distinct demand profiles that reward suppliers with tiered purification capabilities. Segmentation reveals how regulatory chemistry and end-use specifications fragment the addressable market into purity-grade and application-specific tiers.
Product Type:
Use-case spectrum spans industrial bulk consumption through analytical precision requirements, with purity thresholds determining pricing architecture.
- Solvent:High-boiling aprotic solvent with 101°C boiling point serves industrial coatings and adhesive formulations where slower evaporation improves flow properties. Maharashtra's chemical manufacturing belt near Mumbai concentrates demand for automotive and protective coatings applications where CDSCO-registered suppliers command procurement preference.
- Intermediate:Pharmaceutical-grade material with documented batch traceability supports active pharmaceutical ingredient synthesis under tightening CDSCO oversight. API manufacturers in India are expanding purchases as ICH Q3C residual solvent guidelines elevate purity mandates.
- Chemical Reagent:Analytical-grade material for laboratory and academic research institutions occupies stable niche demand with lower volume sensitivity.
- Additive:Functional component in specialty formulations requiring controlled release or compatibility enhancement in limited industrial applications.
The dominant share belongs to Solvent, while Intermediate is closing the gap fastest.
Application:
Cost tier segmentation separates commodity industrial consumption from premium pharmaceutical-grade requirements.
- Coatings:Automotive OEM paint shops in Germany deploy membrane-based recovery systems achieving 95%+ solvent recovery, cutting virgin purchases. EPA hazardous air pollutant standards under the Clean Air Act constrain emissions, pushing reformulation toward recovery-integrated operations.
- Adhesives:Industrial bonding applications utilize diethyl ketone's solvency parameters for high-performance pressure-sensitive and structural adhesive formulations.
- Pharmaceuticals:CDSCO audit schedules have made dual-source API-grade solvent sourcing a procurement priority for Indian formulators.
- Cleaning Agents:Precision degreasing and electronic cleaning applications require controlled evaporation profiles in semiconductor and aerospace maintenance.
Coatings retains volume leadership, though Pharmaceuticals demonstrates the steepest expansion trajectory as purity premiums widen.
End User:
Customer type concentration varies by certification burden, with regulated sectors demanding documented supply chain integrity.
- Manufacturing:Chemical processing and industrial production facilities represent the foundational demand base for standard-grade material.
- Cosmetics:Personal care formulations requiring residual solvent control under REACH registration compliance for European market access.
- Food & Beverage:Limited applications in flavoring and extraction processes subject to national food safety authority oversight.
- Textile:Dyeing and finishing operations in Guangdong manufacturing clusters face China's MEE GB standards on volatile organic compound content.
Manufacturing commands the largest share, while Cosmetics is gaining share fastest on sustainability-mandated procurement expansion.
Distribution Channel:
Supply concentration patterns favor established tankage and rail connectivity in chemical manufacturing clusters.
- Direct Sales:Integrated producers with captive purification capabilities supply pharmaceutical-grade material under long-term offtake agreements with API manufacturers.
- Distributors:Solvent distributors with established Maharashtra and Gujarat infrastructure capture geographic arbitrage in India's chemical belt.
- Online:Digital procurement platforms serve small-volume laboratory and research customers with standardized reagent grades.
- Retail:Limited specialty chemical retailers handle analytical-grade quantities for academic and institutional buyers.
Distributors hold the dominant position, while Direct Sales is expanding most quickly as qualification cycles extend and dual-source mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO oversight of active pharmaceutical ingredient manufacturing in India is elevating solvent purity specifications across multiple jurisdictions. Germany's automotive OEM paint shops deploy membrane-based recovery systems achieving 95% solvent recovery. China's MEE enforces GB standards on volatile organic compound content in industrial coatings.
India
Pharmaceutical-grade diethyl ketone demand from API manufacturers is accelerating as CDSCO audit schedules make dual-source solvent sourcing a procurement priority. The Maharashtra chemical manufacturing belt near Mumbai concentrates automotive and protective coatings applications where CDSCO-registered suppliers command preference. Gujarat's solvent distributors with established tankage and rail connectivity capture geographic arbitrage in India's chemical belt.
China
Guangdong manufacturing clusters face tightening MEE GB standards on volatile organic compound content in textile dyeing and finishing operations. SAMR oversight of chemical imports above one tonne annually elevates compliance costs for non-registered suppliers. Yangtze River Delta coatings formulators are reformulating away from conventional ketone solvents toward exempt compounds or waterborne systems.
Germany
Large automotive OEM paint shops deploy membrane-based solvent recovery systems achieving 95% recovery rates, cutting virgin diethyl ketone purchases by half for integrated facilities. ECHA's 2024-2025 work program targets additional solvent substances for restriction evaluation under REACH authorization requirements. Bavaria's chemical processing infrastructure supports pharmaceutical-grade material demand under comprehensive toxicological dossier mandates.
United States
EPA hazardous air pollutant standards under the Clean Air Act constrain solvent emissions from coatings and adhesives operations, pushing formulators toward recovery-integrated operations. Texas Gulf Coast petrochemical networks supply propionic acid feedstock for ketonization routes, exposing margins to naphtha and ethylene cycle swings. Southeast automotive assembly plants utilize slower-evaporation solvent systems in high-build coatings applications.
Diethyl Ketone Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated petrochemical conglomerates with captive feedstock positions anchor the upper tier through cost-secured supply chains. Mid-scale regional formulators occupy the middle tier through geographic proximity to chemical manufacturing clusters. Specialty distributors with established tankage infrastructure serve fragmented laboratory and research demand at the base. Competitive moves center on backward integration into amine chemistry and proprietary purification technology licensing.
Within the integrated multinational tier, BASF SE anchors European supply through its petrochemical network, while Eastman Chemical Company exemplifies the purification-technology specialist archetype. Alkyl Amines Chemicals Limited represents the backward-integrated regional player with captive amine chemistry capabilities. Among Asia-Pacific fabricators, Hubei Norna Technology Co. Ltd. and Jiangsu Hengxing New Material Technology Co. Ltd. occupy positions within China's specialty chemical manufacturing corridor. Caffaro Industrie S.p.A. sits within the European heritage chemical producer archetype.
| Leading Market Players |
|---|
| Caffaro Industrie S.p.A |
| Alkyl Amines Chemicals Limited |
| BASF SE |
| Hubei Norna Technology Co. Ltd. |
| Jiangsu Hengxing New Material Technology Co. Ltd. |
| BSM Chemical Co. Ltd. |
| Jeevan Chemicals Private Limited |
| Eastman Chemical Company |
| Shanghai Pearlk Chemical Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Maharashtra's chemical manufacturing belt near Mumbai concentrates solvent production capacity, giving CDSCO-registered suppliers leverage over pharmaceutical-grade pricing while naphtha-linked feedstock costs transmit volatility through ketonization economics.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and industrial-grade material, with ICH Q3C compliance commanding substantial premiums over standard solvent tiers. Three-tier pricing structure across pharmaceutical, industrial, and reagent grades reflects documented batch traceability requirements and CDSCO audit readiness. Cost compression in industrial coatings applications is intensifying because methyl ethyl ketone substitution erodes volume premiums. Adhesive formulators exhibit highest price sensitivity, while API manufacturers prioritize supply security over unit economics.
Supply Chain Analysis
Export-control scrutiny on copper-chromite catalyst technology limits catalyst supply diversification, concentrating dehydrogenation route dependence on specialized manufacturers with constrained geographic dispersion. Propionic acid feedstock draws from Texas Gulf Coast and European petrochemical networks, while finished material sources from India, China, and Germany. Single-source vulnerability in catalyst supply creates structural risk for 3-pentanol-based producers. Distribution runs through established tankage and rail infrastructure in chemical manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diethyl ketone market exhibits cyclical recovery characteristics as naphtha and ethylene feedstock costs normalize from peak volatility, restoring ketonization route margins.
For Market Incumbents: Build regulatory certification moats through CDSCO and REACH dossier investments that marginal entrants cannot replicate within 18-24 month qualification cycles. Secure long-term propionic acid offtake agreements to hedge feedstock volatility exposure. Expand membrane-based solvent recovery system partnerships with automotive OEM paint shops to lock in virgin material demand. For New Entrants and Emerging Players: Gujarat's underpenetrated solvent distribution infrastructure offers geographic white-space for tankage-equipped entrants seeking Maharashtra spillover demand. Target analytical-grade reagent segments where qualification barriers remain lower than pharmaceutical tiers. Pursue asset-light equipment leasing arrangements to bypass greenfield capital requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors purification-technology specialists with proprietary separation capabilities over commodity ketonization operators. Long-term viability hinges on bio-based pentanone platform development timelines. Watch fermentation-derived solvent cost parity as the inflection signal for renewable substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Chemistry | Alkyl Amines Chemicals Limited anchors feedstock security through captive propionic acid supply. |
| Pharmaceutical-Grade Certification Investment | CDSCO audit schedules make dual-source API-grade solvent sourcing mandatory for Indian formulators. |
| Membrane Recovery System Deployment | German automotive OEM paint shops achieve 95% solvent recovery, cutting virgin diethyl ketone purchases. |
| Biobased Ketone Platform Development | Fermentation-derived pentanone from agricultural feedstocks opens renewable content claims for sustainability procurement. |
| Maharashtra-Gujarat Distribution Expansion | Tankage and rail connectivity in India's chemical belt captures geographic arbitrage for solvent distributors. |
Study Parameters
The analysis maps solvent-grade, intermediate-grade, and reagent-grade segments, each validated through procurement leads at API manufacturers, coatings formulators, and laboratory distributors. Primary interviews with plant managers at ketonization facilities, downstream OEM procurement teams, and specialty chemical distributors combined with secondary validation from CDSCO filings, REACH registration databases, and customs trade data. Bottom-up volume triangulation against top-down petrochemical feedstock consumption estimates anchored market sizing.
Assumptions held propionic acid pricing correlation to naphtha and ethylene cycles fixed while varying CDSCO enforcement intensity and MEE GB standards adoption rates across the projection horizon. Segmentation dimensions modeled include purity tier, end-use application, and regional regulatory cluster. CAGRs derived from weighted average of historical ketone solvent demand elasticity and projected pharmaceutical synthesis expansion. Industry-specific inputs incorporated ICH Q3C residual solvent guideline revision timelines and membrane recovery technology penetration curves.
Practitioners should monitor propionic acid feedstock volatility and bio-based ketone cost parity for early signals of margin compression or substitution acceleration. Forecasts reflect assumptions regarding CDSCO audit schedule intensity and REACH authorization expansion scope. Material shifts in copper-chromite catalyst supply availability or MEE GB standards enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
Ethyl Levulinate Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
4-Tert-Amylphenol Market
Organic Chemicals
Terephthalic Aldehyde Market
Organic Chemicals
Benzethonium Chloride Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
Synthetic Camphor Market
Organic Chemicals
Aminophenol Market
Organic Chemicals
Anthracene Market
Organic Chemicals
Soy Chemicals Market
Organic Chemicals
Acetylacetone Market
Organic Chemicals
Global Glycolic Acid Market
Organic Chemicals
Europe Cycloalkanes Market