
 Ethyl Levulinate Market | 2026-2036
Ethyl Levulinate Market Size, Share, and Industry Trends Forecast 2026-2036
Ethyl Levulinate Market Intelligence
China is narrowing its dependence on imported specialty esters through domestic fermentation-based capacity additions for ethyl levulinate. Bedoukian Research Inc. leverages captive fragrance compound expertise to anchor North American supply relationships. Beijing Lys Chemicals Co., Ltd sustains cost-competitive chemical synthesis routes for Asian industrial buyers. Axxence Aromatic GmbH differentiates through European distribution control and technical service depth for flavor applications.
Ethyl levulinate is an ethyl ester of levulinic acid, typically produced via acid-catalyzed esterification of biomass-derived levulinic acid with ethanol, yielding a colorless liquid with a fruity odor profile and solvent properties suited to fragrance formulation and polymer additive systems. The compound serves primarily as a bio-based solvent and intermediate bridging petrochemical replacement demand with renewable feedstock utilization. Solvent-grade material leads volume consumption due to established incorporation in personal care and cleaning formulations, while biofuels represents the fastest-expanding category as blenders seek oxygenate additives with favorable emissions profiles. Chemical synthesis dominates current manufacturing throughput, though fermentation routes are gaining investment intensity as yield improvements reduce unit costs.
EPA biofuel blending mandates and REACH substance registration requirements in the European Union create dual compliance obligations for producers seeking cross-border market access. FDA food contact and FEMA GRAS determinations govern incorporation into flavor and beverage applications, constraining supplier qualification pools. China's SAMR chemical registration framework and evolving GB standards for bio-based industrial products add further territorial complexity. Stakeholders must monitor catalysis technology cost curves and regional certification reciprocity agreements to optimize manufacturing location decisions against evolving compliance burdens.
Market Dynamics
REACH substance registration requirements and EPA biofuel blending mandates are converging to reshape formulation procurement, compelling suppliers to dual-certify production assets across Atlantic markets while fermentation-based capacity narrows cost gaps with chemical synthesis routes.
Growth Catalysts
- REACH Compliance:European fragrance houses accelerate substitution of petrochemical solvents with bio-based esters to meet ECHA registration deadlines for downstream personal care formulations.
- EPA Oxygenate Mandates:US fuel blenders incorporate ethyl levulinate as a renewable oxygenate additive to satisfy Renewable Fuel Standard volume obligations and reduce particulate emissions profiles.
- Fermentation Yield Improvements:Advances in strain engineering and downstream separation are compressing unit production costs for biomass-derived levulinic acid feedstock.
Market Restraints
- Feedstock Cost Volatility:Corn stover and sugarcane bagasse prices fluctuate with agricultural commodity cycles, squeezing margin predictability for fermentation-based producers.
- Substitution Pressure:Ethyl acetate and n-butyl acetate maintain entrenched positions in industrial coating applications due to established supply chains and lower spot pricing.
- Regulatory Fragmentation:Divergent SAMR chemical registration timelines in China versus FDA food contact determinations in the US extend product qualification cycles for cross-border suppliers.
Strategic Opportunities
- Pharmaceutical Solvent Expansion:GMP-grade ethyl levulinate production for active pharmaceutical ingredient synthesis remains underdeveloped relative to personal care penetration.
- EU Green Deal Alignment:Carbon border adjustment mechanisms and renewable content mandates create preferential market access for bio-based ester producers with certified supply chains.
- Direct-to-Blender Distribution:Biofuel producers are bypassing traditional chemical distributors to contract directly with regional fuel terminals for oxygenate supply.
Industry Challenges
- Specialized Catalysis Talent:Scarcity of process chemists with expertise in solid acid esterification and heterogeneous catalysis constrains scale-up velocity for fermentation-based assets.
- Multi-Jurisdiction Certification:Simultaneous pursuit of FEMA GRAS status, REACH registration, and SAMR filing creates documentation burdens that delay commercial launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethyl Levulinate Market |
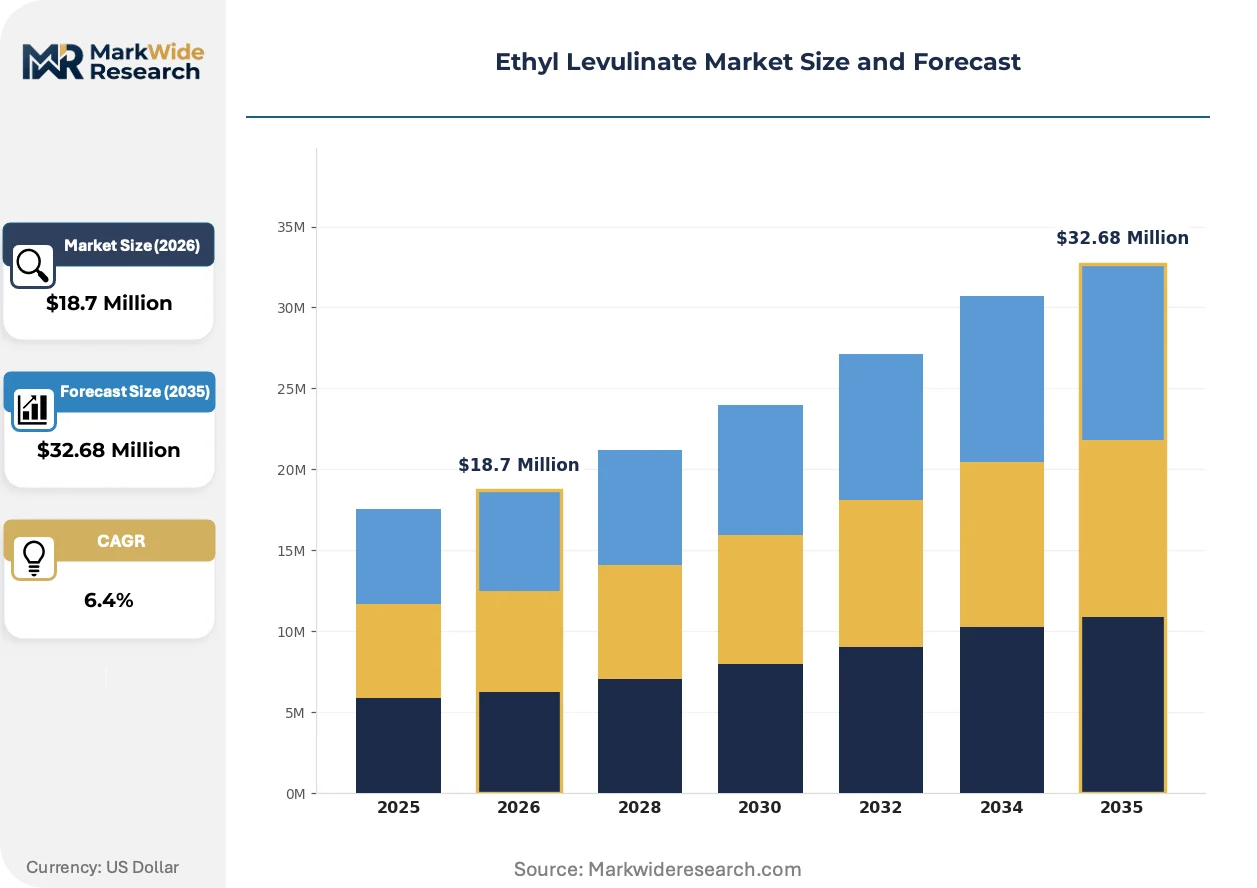
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $32.68 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Additives, Intermediates, Biofuels End User: Chemical Industry, Food and Beverage, Cosmetics, Pharmaceuticals Technology: Fermentation, Chemical Synthesis, Extraction, Catalysis Form: Liquid, Powder, Concentrate, Emulsion |
| Companies Covered | Bedoukian Research Inc., Berjé Inc, Advanced Biotech, Fleurchem Inc, Oakwood Products, Inc., Axxence Aromatic GmbH, Beijing Lys Chemicals Co., Ltd, Vigon International, LLC, Alfa Aesar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethyl Levulinate Market Strategic Shifts & Innovations
Manufacturing technology for ethyl levulinate is bifurcating between legacy acid-catalyzed processes and emerging biological routes, with regulatory compliance and carbon accounting now driving adoption velocity more than unit economics alone.
Solid acid catalyst systems is migrating from homogeneous sulfuric acid configurations to heterogeneous zeolite and sulfonated carbon structures. Fragrance compounders in Germany and the United States are piloting these systems to eliminate neutralization waste streams and reduce water intensity. This migration from conventional liquid-phase esterification is compressing environmental compliance costs while enabling continuous-flow reactor designs that improve throughput consistency.
REACH authorization requirements for substances of very high concern are extending disclosure obligations through downstream supply chains. European formulators now demand full mass-balance documentation for bio-based content claims, forcing raw material suppliers to implement chain-of-custody certification. Specialty chemical distributors are responding by consolidating supplier panels to those with pre-verified ECHA dossiers, privileging incumbent registrants over new market entrants.
Compounders are consolidating procurement volumes with fewer qualified suppliers capable of delivering multi-jurisdiction regulatory packages. Personal care multinationals have reduced their approved ester vendor lists by half over the past qualification cycle, preferring integrated producers with captive fermentation and esterification assets. This concentration is most pronounced in Germany and the United States, where downstream customers prioritize supply security over spot-price minimization.
Ethyl Levulinate Market Segmentation
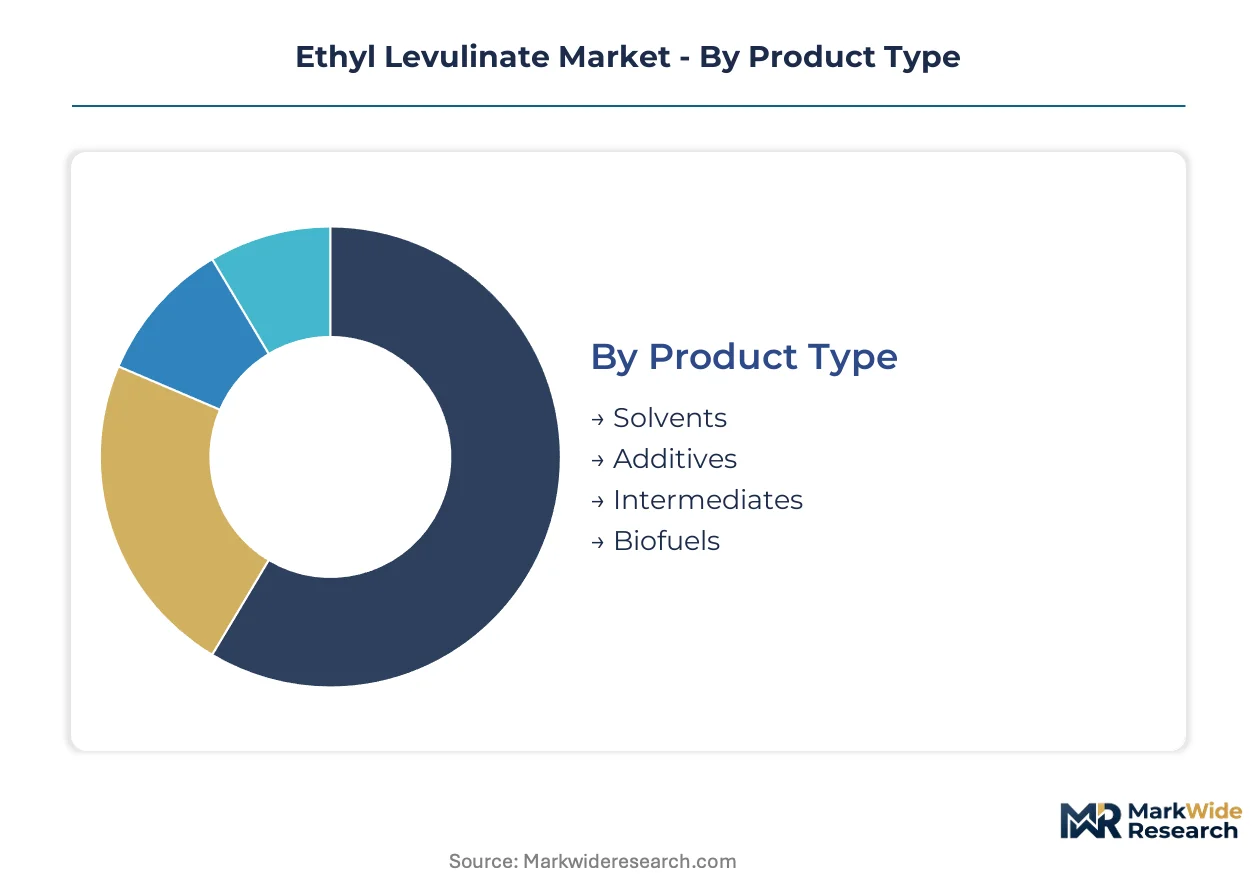
Ethyl levulinate's functional versatility across solvent, fuel, and chemical intermediate roles necessitates granular segmentation. Procurement patterns diverge sharply between fragrance houses seeking odor-grade purity and fuel blenders prioritizing oxygenate performance. Regulatory compliance requirements further stratify supplier qualification by end-use application.
Product Type:
Mature solvent applications anchor volume, while emerging biofuel categories reshape competitive investment priorities.
- Solvents:Colorless liquid with fruity odor profile serves personal care and cleaning formulations. Fragrance compounders in Germany specify this grade for REACH-compliant perfume dilution, driven by ECHA registration deadlines for downstream cosmetic products.
- Biofuels:Renewable oxygenate additive blends with conventional diesel and gasoline stocks. US fuel terminals contract directly with producers to satisfy EPA Renewable Fuel Standard obligations while reducing particulate emissions.
- Additives:Polymer plasticizers and coating modifiers leverage ethyl levulinate's compatibility with bio-based resin systems.
- Intermediates:Chemical synthesis feedstock for levulinic acid derivative production in pharmaceutical and agrochemical value chains.
Solvents handles the majority of throughput; biofuels is the fastest mover on share.
End User:
Customer procurement sophistication ranges from commodity chemical buyers to GMP-validated pharmaceutical specifiers.
- Chemical Industry:Bulk ester consumption for industrial coating and adhesive formulations. Specialty chemical clusters in the United States concentrate blending operations for regional manufacturing customers.
- Cosmetics:Fragrance and personal care applications demand odor-grade material with full mass-balance documentation. European formulators now require ECHA-registered suppliers with verified bio-based content claims.
- Food and Beverage:FEMA GRAS status governs incorporation into flavor compounds and beverage applications, constraining supplier pools to qualified registrants.
- Pharmaceuticals:GMP-grade production for active pharmaceutical ingredient synthesis remains underdeveloped relative to personal care penetration, presenting white-space opportunity.
Chemical Industry absorbs the dominant procurement volume; Pharmaceuticals climbs the fastest as validation protocols mature.
Technology:
Manufacturing cost curves diverge between legacy acid-catalyzed assets and fermentation-based capacity additions.
- Chemical Synthesis:Acid-catalyzed esterification of biomass-derived levulinic acid with ethanol dominates current throughput. Homogeneous sulfuric acid configurations face migration pressure from heterogeneous zeolite systems that eliminate neutralization waste.
- Fermentation:Strain engineering advances compress unit production costs for biomass-derived feedstock. China's domestic capacity additions narrow dependence on imported specialty esters through fermentation-based routes.
- Catalysis:Solid acid and heterogeneous catalyst development enables continuous-flow reactor designs with improved throughput consistency.
- Extraction:Downstream separation and purification technologies for fermentation broth processing.
Chemical Synthesis retains the production base; Fermentation gains share fastest as yield improvements reduce unit economics gaps.
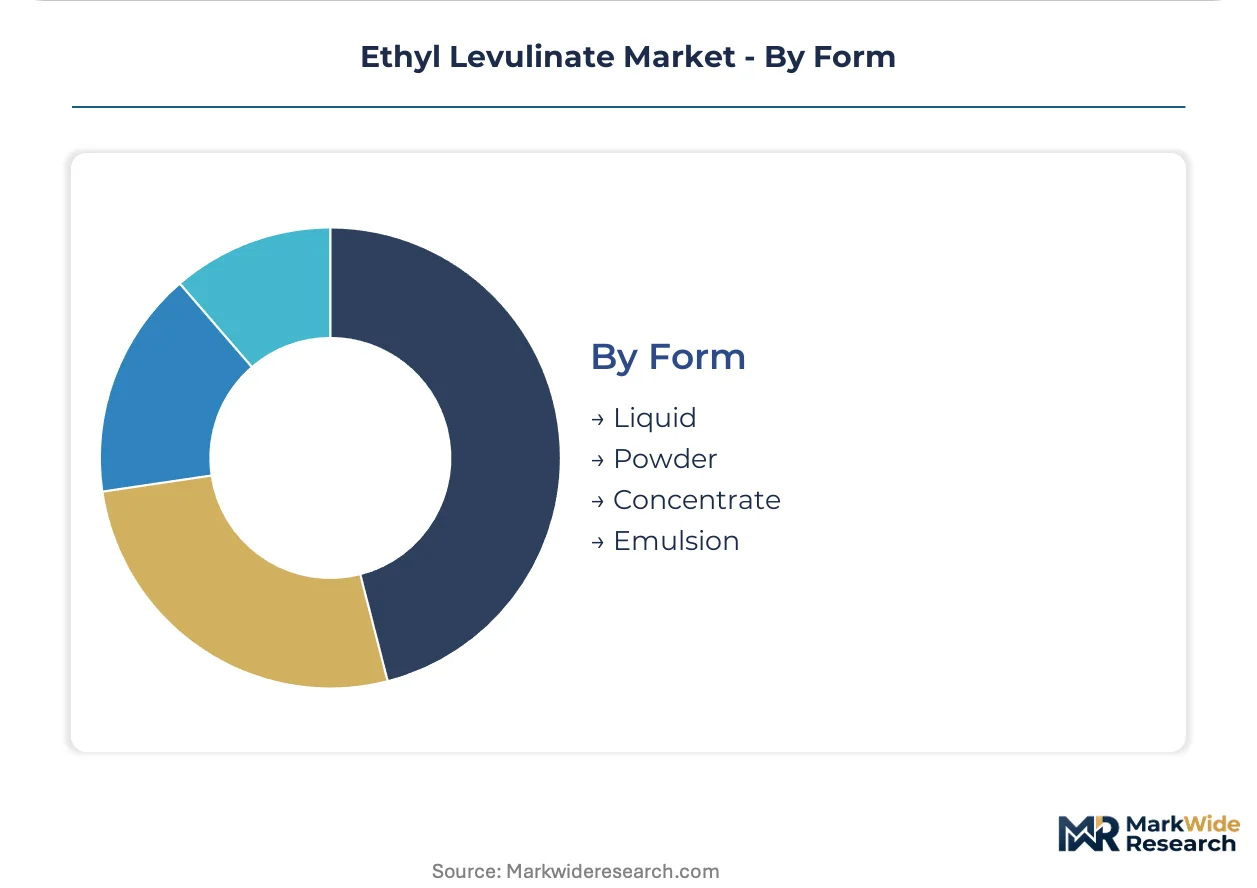
Form:
Physical state determines logistics configuration and downstream handling infrastructure requirements.
- Liquid:Standard commercial presentation in bulk tanker and drum packaging. Fragrance houses and fuel blenders both specify liquid delivery for direct incorporation into formulation or blending operations.
- Concentrate:High-purity grades for pharmaceutical and specialized cosmetic applications requiring precise dilution control.
- Powder:Solid-state derivatives for polymer additive systems and controlled-release formulations.
- Emulsion:Aqueous dispersions for water-based coating and personal care emulsion products.
Liquid commands the logistics infrastructure; Concentrate expands most quickly as pharmaceutical validation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA biofuel mandates in the United States anchor the dominant geography for ethyl levulinate procurement, while REACH registration deadlines in Germany and SAMR chemical frameworks in China create parallel compliance architectures that reshape supplier qualification across Atlantic and Pacific markets.
United States
Fuel blenders at Gulf Coast terminals contract directly with producers for renewable oxygenate supply to satisfy Renewable Fuel Standard obligations. EPA enforcement of particulate emissions standards accelerates incorporation of bio-based esters into diesel and gasoline stocks. Houston and Baton Rouge specialty chemical clusters concentrate downstream blending operations for personal care and industrial coating customers.
Germany
Fragrance houses in the Cologne-Düsseldorf corridor accelerate substitution of petrochemical solvents with bio-based esters ahead of ECHA registration deadlines. REACH authorization requirements for substances of very high concern extend disclosure obligations through cosmetic supply chains. BASF and Evonik adjacent chemical parks in Ludwigshafen and Marl enable integrated esterification and downstream formulation.
China
Domestic fermentation-based capacity additions narrow dependence on imported specialty esters for industrial solvent applications. SAMR chemical registration timelines and evolving GB standards for bio-based industrial products constrain cross-border supplier entry. Yangtze River Delta chemical clusters in Jiangsu and Zhejiang provinces concentrate cost-competitive synthesis operations for Asian coating and adhesive manufacturers.
India
Personal care formulators in Maharashtra and Gujarat expand procurement of bio-based fragrance solvents as export-oriented cosmetic production scales. CDSCO pharmaceutical regulations and BIS industrial standards create dual compliance pathways for solvent-grade versus GMP-grade material. Mumbai-Pune chemical corridor hosts downstream blending operations for regional pharmaceutical and fragrance compounders.
Japan
Flavor and fragrance specialists in the Osaka-Kobe industrial zone source ethyl levulinate for FEMA GRAS-compliant beverage and cosmetic applications. METI bio-economy initiatives and JIS standards for renewable chemical content steer procurement toward mass-balance-certified suppliers. Chubu region catalysis research institutes pilot heterogeneous zeolite systems for continuous-flow esterification.
Ethyl Levulinate Market Key Industry Players
Capability concentration sits with integrated fermentation-and-esterification specialists; scale advantage sits with established fragrance compounders with captive solvent demand. The vendor base stratifies across three tiers: research-intensive aroma houses with proprietary formulation expertise, commodity chemical distributors with regional logistics networks, and emerging bio-based producers with backward integration into levulinic acid feedstock. Dominant competitive moves include capacity expansion in fermentation-based assets and strategic partnerships between fragrance houses and fuel terminal operators for oxygenate supply.
Among North American aroma specialists, Bedoukian Research Inc. and Berjé Inc occupy positions within the fragrance-house tier, leveraging captive compound expertise to anchor supply relationships. Beijing Lys Chemicals Co., Ltd represents the cost-competitive synthesis archetype for Asian industrial buyers. Axxence Aromatic GmbH exemplifies European distribution control with technical service depth for flavor applications.
| Leading Market Players |
|---|
| Bedoukian Research Inc. |
| Berjé Inc |
| Advanced Biotech |
| Fleurchem Inc |
| Oakwood Products, Inc. |
| Axxence Aromatic GmbH |
| Beijing Lys Chemicals Co., Ltd |
| Vigon International, LLC |
| Alfa Aesar |
| Others |
Cost & Logistics Intelligence
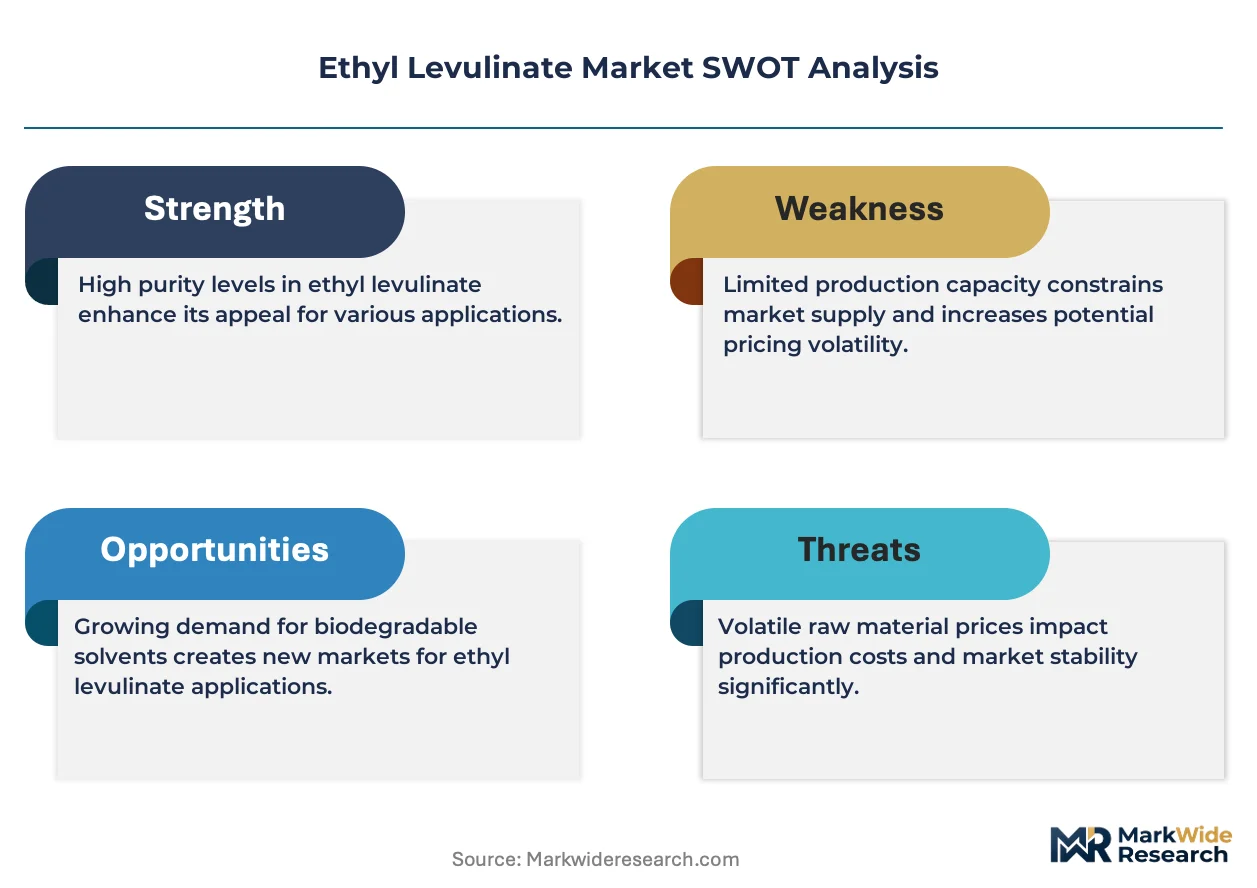
Feedstock cost volatility in corn stover and sugarcane bagasse markets compresses margin predictability for fermentation-based producers while simultaneously widening spreads between chemical synthesis and biological route pricing tiers. This agricultural commodity exposure forces buyers to dual-source across technology types and concentrates supply relationships with integrated producers capable of absorbing input fluctuations.
Pricing Analysis
Contract pricing for solvent-grade material runs 15-25% below odor-grade specifications in Germany and the United States, with fragrance houses absorbing premiums for REACH-registered mass-balance documentation. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated pharmaceutical grades from industrial solvent and fuel oxygenate categories. Cost compression in standard-grade solvent tiers is intensifying because Chinese fermentation capacity additions narrow cost gaps with legacy acid-catalyzed routes. Fuel blenders at US Gulf Coast terminals exhibit highest price sensitivity due to spot-market oxygenate alternatives, while European cosmetics formulators prioritize supply security over unit cost minimization.
Supply Chain Analysis
Toll esterification capacity concentrates with German chemical parks in Ludwigshafen and Marl, US Gulf Coast specialty clusters around Houston and Baton Rouge, and Yangtze River Delta synthesis operations in Jiangsu and Zhejiang provinces. Production draws from biomass-derived levulinic acid feedstock, solid acid catalyst systems, and ethanol supply agreements anchored in regional biofuel mandates. Single-source vulnerability sits with heterogeneous zeolite catalyst supply chains where specialized process chemist scarcity constrains scale-up velocity. Distribution runs through integrated fragrance compounders with captive solvent demand and direct terminal contracts for fuel oxygenate offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as downstream procurement consolidation creates tiered supplier qualification gaps, with personal care multinationals halving approved ester vendor lists while fermentation-based capacity additions open mid-market entry points.
For Market Incumbents: Build regulatory moat through simultaneous FEMA GRAS, REACH registration, and SAMR filing completion ahead of emerging bio-based producers. Consolidate supplier panels with fragrance houses by offering multi-jurisdiction compliance packages that extend disclosure obligations through downstream cosmetic supply chains. Capacity addition in German chemical parks adjacent to BASF and Evonik infrastructure reinforces supply security positioning against Chinese fermentation cost competition. For New Entrants and Emerging Players: Build out pharmaceutical-grade solvent production where GMP validation protocols remain underdeveloped relative to personal care penetration. Target direct-to-blender distribution relationships with US fuel terminals seeking renewable oxygenate supply outside traditional chemical distributor networks. White-space concentration sits with certified bio-based ester production for EU Green Deal carbon border adjustment alignment. For Investors and Strategic Acquirers: Integrated fermentation-and-esterification specialists with captive levulinic acid feedstock offer acquisition exposure to bio-based chemical substitution tailwinds. Long-term viability centers on yield improvement trajectories compressing unit economics gaps with chemical synthesis routes. Signal to watch is ECHA registration deadline acceleration forcing downstream formulators to consolidate procurement with pre-verified dossier holders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Levulinic Acid Feedstock | Captive biomass-derived feedstock supply insulates margin volatility from agricultural commodity cycles. |
| Multi-Jurisdiction Regulatory Certification | Simultaneous REACH, FEMA GRAS, and SAMR filing completion opens procurement access to consolidated vendor panels. |
| Heterogeneous Catalysis Scale-Up | Solid acid zeolite systems eliminate neutralization waste streams and enable continuous-flow reactor throughput gains. |
| Direct Terminal Oxygenate Contracts | Bypassing chemical distributors captures margin from EPA Renewable Fuel Standard compliance demand at fuel blenders. |
| GMP-Grade Pharmaceutical Validation | Active pharmaceutical ingredient solvent specifications remain underpenetrated relative to personal care applications. |
Research Approach
The analysis maps solvent-grade, biofuel oxygenate, and pharmaceutical-grade production tiers, each validated through fragrance compounder procurement leads, fuel terminal blending managers, and pharmaceutical process development directors. Primary interviews with plant managers at German chemical parks, US Gulf Coast specialty chemical clusters, and Yangtze River Delta synthesis operations combined with secondary validation from ECHA registration databases, EPA Renewable Fuel Standard compliance filings, and SAMR chemical registration timelines. Trade data from customs records and Cefic sector reports anchored bottom-up capacity estimates against top-down demand aggregation from personal care and fuel blending end-use markets.
Forecast assumptions held regulatory compliance timelines and fermentation yield improvement trajectories as variable inputs while fixing agricultural commodity price cycles and petrochemical substitution elasticity parameters across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry application, manufacturing technology route, and regional production hub clustering. CAGRs derived from capacity expansion announcements, ECHA registration deadline schedules, and EPA biofuel mandate volume obligations. Industry-specific inputs incorporated strain engineering advancement rates for biological routes and heterogeneous catalyst adoption curves for continuous-flow esterification systems.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese fermentation specialists or accelerated REACH authorization timelines would shift outcomes beyond modeled ranges. Quarterly review of ECHA dossier submission rates, EPA renewable volume obligation enforcement actions, and agricultural commodity price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Chloroacetyl Chloride Market
Organic Chemicals
Phenolic Board Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
Organic Hydrosols Market
Organic Chemicals
North America Cycloalkanes Market
Organic Chemicals
Triethylene Glycol Market
Organic Chemicals
Alanine Market
Organic Chemicals
Methyl Isobutyl Ketone (MIBK) Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
Global Pseudocumene Market
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
Aliphatic Amines Market