
 Acetylacetone Market | 2026-2036
Acetylacetone Market Size, Share, and Industry Trends Forecast 2026-2036
Acetylacetone Market Analysis
Specialty solvent purification is reconfiguring margin pools across the acetylacetone value chain, shifting profitability from commodity-grade bulk sales toward pharmaceutical and electronic-grade refinement. BASF SE leverages its integrated Ludwigshafen complex to sustain captive acetylacetone supply for captive metal complex derivatives. Daicel Corporation anchors high-purity output for Asian semiconductor and pharmaceutical customers through dedicated distillation assets. Wacker Chemie AG differentiates via silicon-acetylacetone hybrid chemistry for coatings and electronics applications.
Acetylacetone (pentane-2,4-dione) is a β-diketone liquid with a boiling point of 140°C and density of 0.98 g/cm³, manufactured primarily through acetone condensation with acetic anhydride or isopropenyl acetate routes, serving as a versatile chelating agent and reaction intermediate across organic synthesis and materials science. The metal complexes segment commands premium pricing due to stringent purity thresholds in pharmaceutical and electronics end uses, while the solvents category remains volume-heavy but margin-constrained by commodity competition. Catalyst applications represent the fastest-expanding demand pool, driven by polymerization and fine chemical process intensification across Asian manufacturing bases.
China's SAMR enforces GB standards for chemical purity and labeling that dictate import eligibility and domestic production licensing, while the EPA in the United States monitors acetylacetone under TSCA for environmental release thresholds affecting plant siting decisions. The EU REACH framework imposes registration burdens and substance evaluation protocols that shape exporter compliance costs and market access timelines. Stakeholders must monitor evolving pharmaceutical-grade certification requirements and solvent recovery mandates as the primary determinants of competitive positioning in regional supply negotiations.
Market Dynamics
Pharmaceutical-grade purification requirements are compressing commodity-grade margins while concentrating value capture among distillation-capable producers serving FDA and NMPA-certified supply chains.
Growth Catalysts
- GB Standard 2025 Revisions:China's SAMR is tightening residual solvent limits in active pharmaceutical ingredient manufacturing, redirecting procurement toward high-purity acetylacetone grades.
- Semiconductor Metal Complex Demand:Advanced node fabrication requires ultra-high-purity metal acetylacetonate precursors for atomic layer deposition processes.
- Acetone Condensation Process Intensification:Continuous-flow reactor adoption is reducing energy intensity and enabling modular capacity expansion at Asian manufacturing bases.
Market Restraints
- Acetone Price Volatility:Feedstock cost swings from propylene supply disruptions compress margin predictability for non-integrated producers.
- East China Supply Concentration:Jiangsu and Zhejiang provinces host over 60 percent of regional fine chemical capacity, creating geographic vulnerability to environmental enforcement actions.
- REACH Registration Burden:ECHA substance evaluation protocols impose compliance costs and timeline uncertainty for exporters serving EU pharmaceutical customers.
Strategic Opportunities
- Indian CDSCO Pathway Expansion:Domestic pharmaceutical manufacturing incentives under PLI schemes are creating demand for import-substituted high-purity solvent supply.
- Solid-State Battery Electrolyte Precursors:Lithium acetylacetonate complexes are emerging as critical inputs for next-generation energy storage chemistries.
- EU Green Deal Solvent Recovery Mandates:Circular economy requirements for pharmaceutical manufacturing waste streams favor suppliers with closed-loop purification capabilities.
Industry Challenges
- Pharmaceutical-Grade Certification Timelines:FDA and NMPA validation protocols for new production facilities extend 18-24 months, freezing capacity responsiveness.
- Acetic Anhydride Supply Security:Integration complexity with legacy carbonylation-based feedstock systems constrains rapid process switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetylacetone Market |
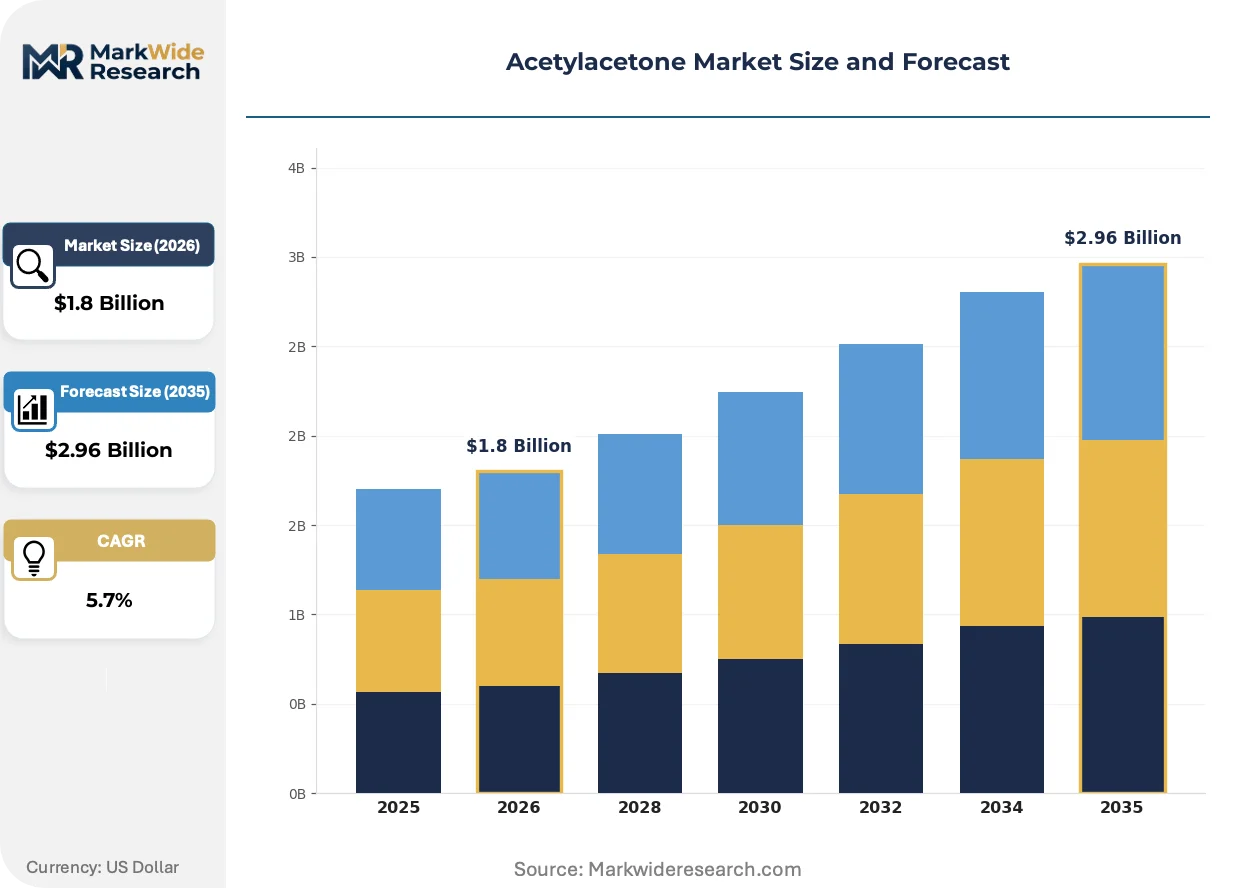
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetylacetone, Metal Complexes, Derivatives, Solvents Application: Chemical Synthesis, Catalysts, Pharmaceuticals, Coatings End User: Chemical Industry, Automotive, Electronics, Food and Beverage Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Daicel Corporation, Wacker Chemie AG, BASF SE, Merck KGaA, XINAOTE, Anhui Wotu Chemical, Chiping Huahao Chemical, Yuanji Chemical, Fubore Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetylacetone Market Emerging Trajectories
Hybrid chemistries and regulatory-driven purity stratification are fragmenting the acetylacetone value chain into distinct technology-performance tiers with diverging margin profiles.
Silicon-acetylacetonate hybrid materials are hybridizing conventional metal complex chemistry with organosilicon functionality for advanced coatings and electronics applications. Semiconductor equipment manufacturers and specialty coating formulators are adopting these materials at accelerating rates for barrier and adhesion-promoting layers. This technology convergence is hybridizing previously separate supply chains and compressing qualification timelines for multi-functional precursors.
REACH substance evaluation protocols under ECHA are tightening impurity disclosure requirements for acetylacetone destined for pharmaceutical and electronics end uses. The industrial consequence is a bifurcation between registered premium grades and unregistered commodity volumes with restricted market access. EU-based pharmaceutical manufacturers are responding by consolidating supplier lists around pre-registered, audit-ready producers with established safety data packages.
Specification-driven procurement contracts are displacing spot-market purchasing for pharmaceutical-grade acetylacetone as residual solvent liability concentrates with API manufacturers. Direct supplier-auditor relationships are replacing distributor intermediation for high-purity grades in North American and European supply chains. This channel restructuring is most visible in East China, where Jiangsu-based producers are establishing dedicated export logistics for certified pharmaceutical customers.
Acetylacetone Market Segmentation
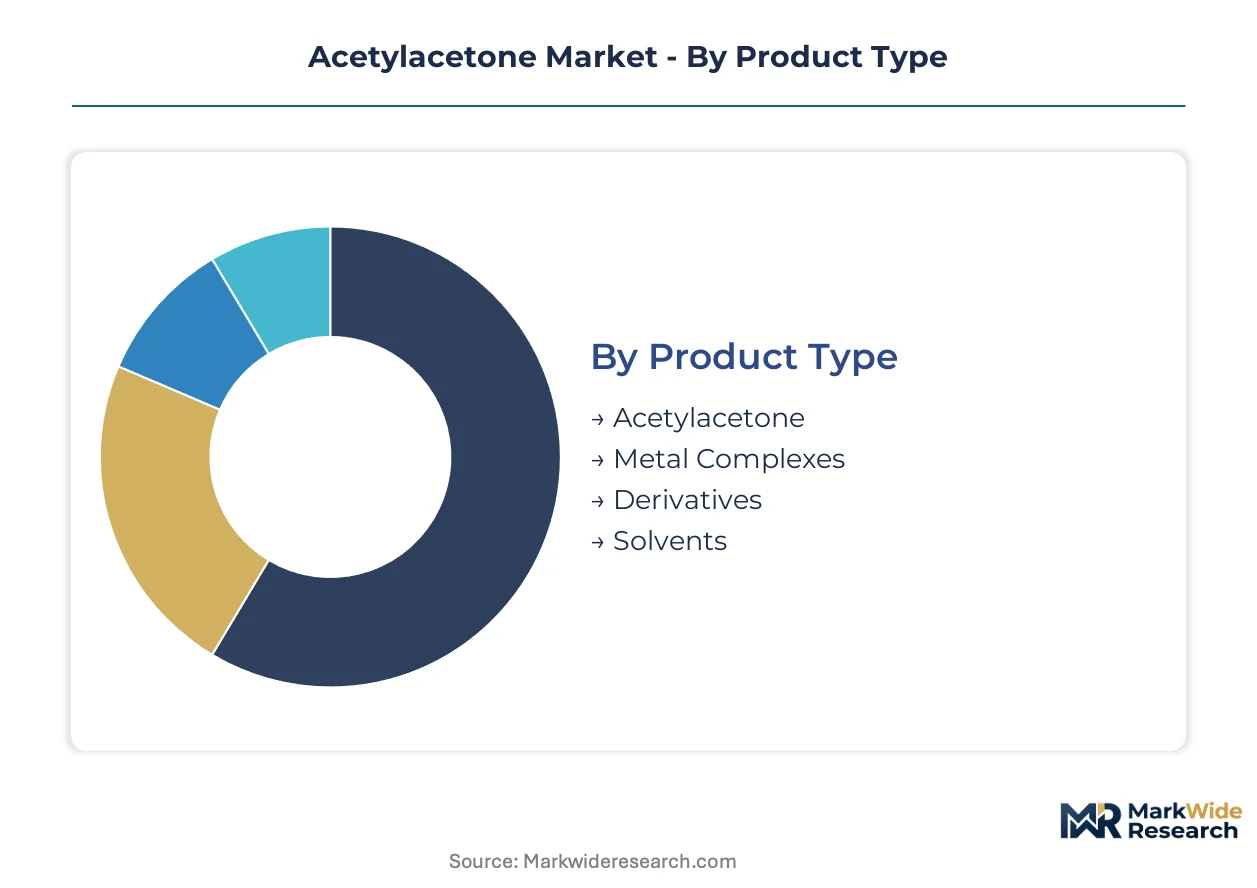
Acetylacetone's functional versatility creates distinct commercial segments with diverging margin profiles and technical requirements. Each segmentation dimension reveals how value capture concentrates among producers capable of meeting certification thresholds for pharmaceutical and electronics end uses.
Product Type:
After-sales service intensity varies sharply across product types, with pharmaceutical-grade acetylacetone demanding continuous analytical support and regulatory documentation while commodity solvents require minimal technical engagement.
- Metal Complexes:Ultra-high-purity metal acetylacetonates serve as atomic layer deposition precursors in semiconductor fabrication. Demand concentrates at Korean and Taiwanese foundries where advanced node production requires sub-ppm impurity specifications. NMPA certification timelines extend supplier relationships into multi-year technical partnerships.
- Acetylacetone:The β-diketone base chemical functions as chelating agent and reaction intermediate across organic synthesis. Pharmaceutical manufacturers in Jiangsu and Zhejiang provinces drive procurement of high-purity grades following SAMR's tightening of residual solvent standards.
- Derivatives:Functionalized acetylacetonate variants include silicon-hybrid materials for coatings and electronics applications.
- Solvents:Technical-grade material supports industrial cleaning and extraction processes with lower purity thresholds.
By volume, solvents lead. By growth pace, metal complexes are ahead.
Application:
Application segments stratify by cost tier, with pharmaceutical and semiconductor applications commanding premium pricing against commodity chemical synthesis volumes.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis employs acetylacetone as chelating agent for metal-containing drug compounds. FDA and NMPA validation protocols enforce documentation burdens that freeze out unregistered suppliers.
- Catalysts:Polymerization and fine chemical process intensification drives fastest-expanding demand across Asian manufacturing bases. Ziegler-Natta and metallocene systems utilize acetylacetonate ligands for stereoselective control.
- Chemical Synthesis:Intermediate production for agrochemicals and specialty chemicals represents volume-heavy, margin-constrained consumption.
- Coatings:Metal complex additives enhance UV resistance and adhesion in automotive and industrial finishes.
By revenue contribution, pharmaceuticals dominates. By expansion trajectory, catalyst applications climb the fastest.
End User:
End user segments map to customer type, with electronics and automotive manufacturers imposing stringent audit requirements versus chemical industry spot purchasing.
- Electronics:Semiconductor and display manufacturers procure ultra-high-purity metal complexes for thin-film deposition. Korean and Japanese equipment makers specify precursor purity down to parts-per-billion levels.
- Chemical Industry:Fine chemical and agrochemical producers represent the largest volume consumption for synthesis and catalysis applications.
- Automotive:Coatings formulators utilize metal acetylacetonates for corrosion-resistant finishes and clearcoat stabilization.
- Food and Beverage:Limited application in packaging materials and processing equipment cleaning with strict migration limits.
By procurement scale, chemical industry leads. By specification intensity, electronics sets the pace.
Distribution Channel:
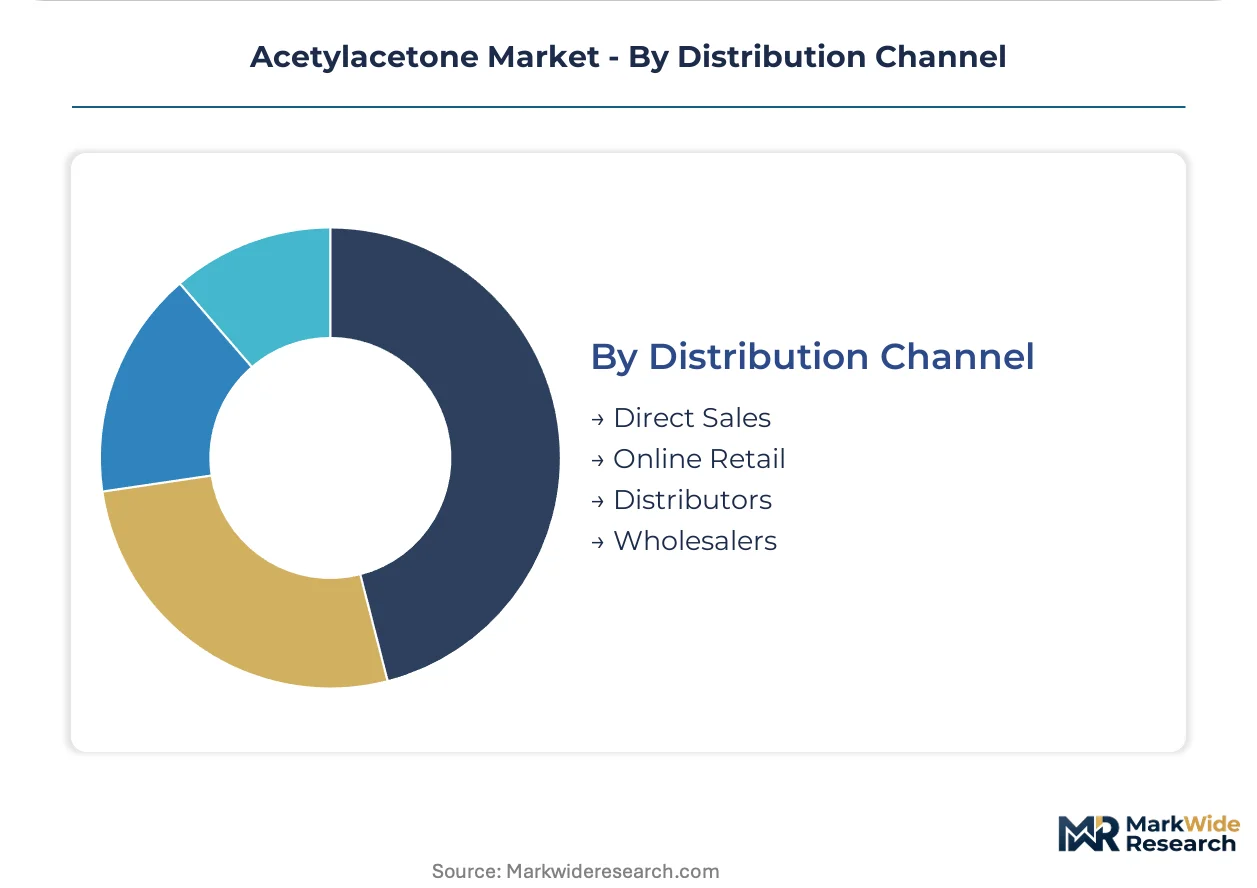
Channel structure reflects supply concentration, with certified pharmaceutical grades consolidating around direct supplier relationships while commodity volumes flow through distributor networks.
- Direct Sales:Pharmaceutical and electronics manufacturers establish dedicated supply agreements with audit-ready producers. Jiangsu-based exporters maintain dedicated logistics for NMPA-certified customers.
- Distributors:Regional chemical distributors handle technical-grade material for smaller synthesis operations and industrial users.
- Wholesalers:Bulk volume aggregation serves commodity solvent demand with minimal technical support.
- Online Retail:Emerging channel for laboratory-scale quantities and research-grade material.
By transaction value, direct sales captures the majority. By coverage breadth, distributors extend reach furthest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers in China exhibit the lowest price elasticity, accepting substantial premiums for NMPA-certified grades, while industrial solvent buyers in Southeast Asia remain highly price-sensitive, driving procurement toward technical-grade imports from Jiangsu and Zhejiang exporters.
China
Semiconductor foundries in Hsinchu and Taichung drive ultra-high-purity metal acetylacetonate consumption for atomic layer deposition at advanced nodes. SAMR's GB 2025 residual solvent revisions redirect API manufacturers toward certified high-purity supply chains. Jiangsu and Zhejiang provinces concentrate over sixty percent of domestic fine chemical capacity, with environmental enforcement actions periodically disrupting regional output.
Germany
Specialty chemical conglomerates in Ludwigshafen and Leverkusen sustain captive acetylacetone production for metal complex derivatives and coatings applications. ECHA's REACH substance evaluation protocols impose registration burdens that filter out unregistered commodity suppliers. The country's industrial chemical clusters maintain integrated supply chains linking acetic anhydride feedstock through to pharmaceutical-grade refinement.
United States
Pharmaceutical API manufacturers in New Jersey and Massachusetts procure high-purity acetylacetone under FDA-validated supply agreements with extended certification timelines. EPA monitoring under TSCA shapes plant siting decisions and environmental release compliance strategies. The Gulf Coast petrochemical corridor provides acetone feedstock integration for domestic producers serving electronics and coatings end users.
India
CDSCO-registered pharmaceutical formulators in Maharashtra and Gujarat expand domestic manufacturing under PLI scheme incentives, creating import-substitution demand for high-purity solvents. The national pharmaceutical regulator tightens residual solvent standards in alignment with ICH Q3C guidelines. Andhra Pradesh's emerging bulk drug parks attract acetylacetone suppliers establishing dedicated distribution for certified pharmaceutical customers.
Japan
Semiconductor equipment manufacturers in Tokyo and Osaka specify metal acetylacetonate precursors at parts-per-billion purity thresholds for display and logic chip fabrication. METI's chemical management frameworks enforce stringent impurity disclosure for electronics-grade materials. The Chubu region's materials science clusters integrate acetylacetone derivatives into advanced barrier coatings for flexible electronics substrates.
Acetylacetone Market Vendor Landscape
Capability concentration sits with integrated chemical conglomerates possessing pharmaceutical-grade distillation assets; scale advantage sits with regional acetone condensation operators serving commodity solvent demand. The market structure bifurcates between audit-ready producers capturing premium pharmaceutical and electronics contracts, and unregistered bulk suppliers competing on price in technical-grade segments. Three archetypes dominate: integrated multinational chemical groups with captive feedstock integration, Asian specialist refiners focused on high-purity export grades, and regional commodity producers serving domestic industrial demand. Competitive dynamics center on certification timeline acceleration and strategic partnerships with API manufacturers seeking supply security.
Among German-based chemical conglomerates, BASF SE exemplifies the integrated archetype through its Ludwigshafen complex operations, while Merck KGaA occupies a position within the high-purity materials tier serving pharmaceutical and laboratory end users. Daicel Corporation represents the Asian specialist refiners, anchoring high-purity output for semiconductor and pharmaceutical customers through dedicated production assets. These three companies illustrate how geographic origin and corporate structure map to distinct competitive positioning across the value chain's premium segments.
| Leading Market Players |
|---|
| Daicel Corporation |
| Wacker Chemie AG |
| BASF SE |
| Merck KGaA |
| XINAOTE |
| Anhui Wotu Chemical |
| Chiping Huahao Chemical |
| Yuanji Chemical |
| Fubore Industrial |
| Others |
Supply Flow & Price Mechanics
East China's Jiangsu and Zhejiang production clusters concentrate over sixty percent of global fine chemical capacity for acetylacetone, anchoring margin capture downstream among pharmaceutical-grade refiners capable of NMPA and FDA certification. This geographic lock-in forces buyers into long-term offtake contracts or spot-market vulnerability.
Pricing Analysis
After-sales analytical support and regulatory documentation contracts drive lifetime value for pharmaceutical-grade acetylacetone suppliers. Three-tier pricing structure across pharmaceutical-grade, electronic-grade, and technical-grade levels separates certified producers from commodity competitors. Cost compression in technical-grade solvents is intensifying because acetone feedstock volatility from propylene supply disruptions squeezes non-integrated operators. Industrial solvent buyers in Southeast Asia exhibit highest price sensitivity, while semiconductor foundries in South Korea accept substantial premiums for parts-per-billion purity specifications.
Supply Chain Analysis
Export-control scrutiny over dual-use chemical precursors limits technology transfer for continuous-flow reactor designs. China, Germany, and the United States anchor global supply, with Ludwigshafen and Gulf Coast complexes maintaining captive acetic anhydride integration. Feedstock draws from acetone carbonylation systems and isopropenyl acetate routes, both tethered to propylene value chain volatility. Single-source vulnerability concentrates in East China environmental enforcement zones. Distribution runs through direct supplier relationships for certified grades and regional chemical distributors for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acetylacetone sits in early-cycle expansion as solid-state battery electrolyte precursors and advanced node semiconductor fabrication create new demand pools beyond traditional pharmaceutical chelation.
For Market Incumbents: Build certification moats through NMPA and FDA validation protocol acceleration. Expand distillation capacity in Andhra Pradesh bulk drug parks to capture Indian CDSCO-registered pharmaceutical formulator demand. Consolidate supplier-auditor relationships before channel restructuring completes in North American and European markets. For New Entrants and Emerging Players: India's Maharashtra and Gujarat pharmaceutical corridors offer underpenetrated white-space for import-substituted high-purity solvent supply. Target EU Green Deal solvent recovery mandates by establishing closed-loop purification capabilities for pharmaceutical manufacturing waste streams. Enter through technical partnerships with API manufacturers seeking supply security against East China environmental disruption. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Asian specialist refiners possessing dedicated distillation assets but lacking integrated feedstock control. Five-to-ten year viability hinges on certification timeline acceleration and hybrid chemistry R&D positioning. Watch for NMPA facility validation completions as inflection indicators for capacity-responsive premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Anhydride | Ludwigshafen-style captive feedstock control insulates margin from propylene volatility. |
| Pharmaceutical-Grade Certification Investment | NMPA and FDA validation protocols freeze out unregistered commodity competitors. |
| Continuous-Flow Reactor Adoption | Modular capacity expansion at Asian manufacturing bases reduces energy intensity. |
| Long-term Supply Agreement with Foundries | Korean and Taiwanese semiconductor producers lock in sub-ppm impurity specifications. |
| Joint Venture for Solid-State Battery Precursors | Lithium acetylacetonate complexes address next-generation energy storage chemistry demand. |
Methodological Framework
A standing panel of pharmaceutical procurement directors, fine chemical plant managers, semiconductor materials engineers, and regulatory affairs specialists provided ongoing calibration against trade flows and capacity announcements. Primary fieldwork combined structured interviews with downstream API manufacturers and upstream acetone suppliers, validated against customs data, SEC 10-K filings, and ECHA registration databases. Bottom-up volume estimates from individual production facilities triangulated against top-down consumption models by end-use industry.
Scenario-bracketing around GB 2025 residual solvent revisions, REACH substance evaluation timelines, and semiconductor node transition cadences bounded the projection range. Segmentation dimensions modeled include product grade tier, end-use application, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating pharmaceutical manufacturing incentives and electronics fabrication capacity buildouts.
Practitioners should monitor NMPA facility certification completions, East China environmental enforcement actions, and acetone-propylene spread volatility for early signals of forecast revision. Material shifts in solid-state battery commercialization timelines or REACH registration burden escalation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Cyclic Ketones Market
Organic Chemicals
Aminophenol Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Terephthalic Aldehyde Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
Pentachlorophenol Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
Humic Acid Market
Organic Chemicals
Benzethonium Chloride Market
Organic Chemicals
Soy Chemicals Market
Organic Chemicals
Organic Matting Agent Market
Organic Chemicals
2-Methylbutanoic Acid Market
Organic Chemicals
Dimethylformamide (DMF) Market
Organic Chemicals
Organic Peroxide Market
Organic Chemicals
2,5-Dimethyl-2,4-Hexadiene Market