
 Europe Cycloalkanes Market | 2026-2036
Europe Cycloalkanes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cycloalkanes Market Insights
Belgium's Antwerp petrochemical hub is reconfiguring cycloalkane storage and blending infrastructure to serve northwest European demand. INEOS Group Holdings S.A. leverages its Grangemouth and Lavéra integrated sites to sustain captive cyclohexane supply for nylon precursor chains. BASF SE anchors Ludwigshafen's cycloalkane derivative output through backward integration into caprolactam production. Haltermann Carless Group GmbH specializes in high-purity solvent grades for pharmaceutical extraction across German and Swiss manufacturing zones.
Cycloalkanes are saturated cyclic hydrocarbons with general formula CnH2n, typically produced via catalytic hydrogenation of aromatic feedstocks or petroleum fractionation, valued for their chemical stability and selective solvency in industrial processes. Cyclohexane dominates product type volumes as the principal feedstock for adipic acid and caprolactam manufacturing, though methylcyclopentane gains traction in specialized solvent applications requiring lower freezing points. Among end users, the chemical industry occupies the largest demand share for intermediate conversion, while pharmaceutical applications represent the fastest-expanding margin pool driven by stringent purity certifications.
EMA pharmaceutical solvent guidelines and REACH Annex XVII restrictions on volatile organic compound emissions shape product specifications and market access conditions for cycloalkane suppliers operating across EU member states. The EU Green Deal's chemical sector decarbonization targets are forcing producers to document carbon intensity through supply chains or risk exclusion from public procurement frameworks. Stakeholders must monitor the interplay between F-Gas Regulation phase-down timelines and emerging bio-based cycloalkane pilot projects before committing to long-term capacity decisions.
Market Dynamics
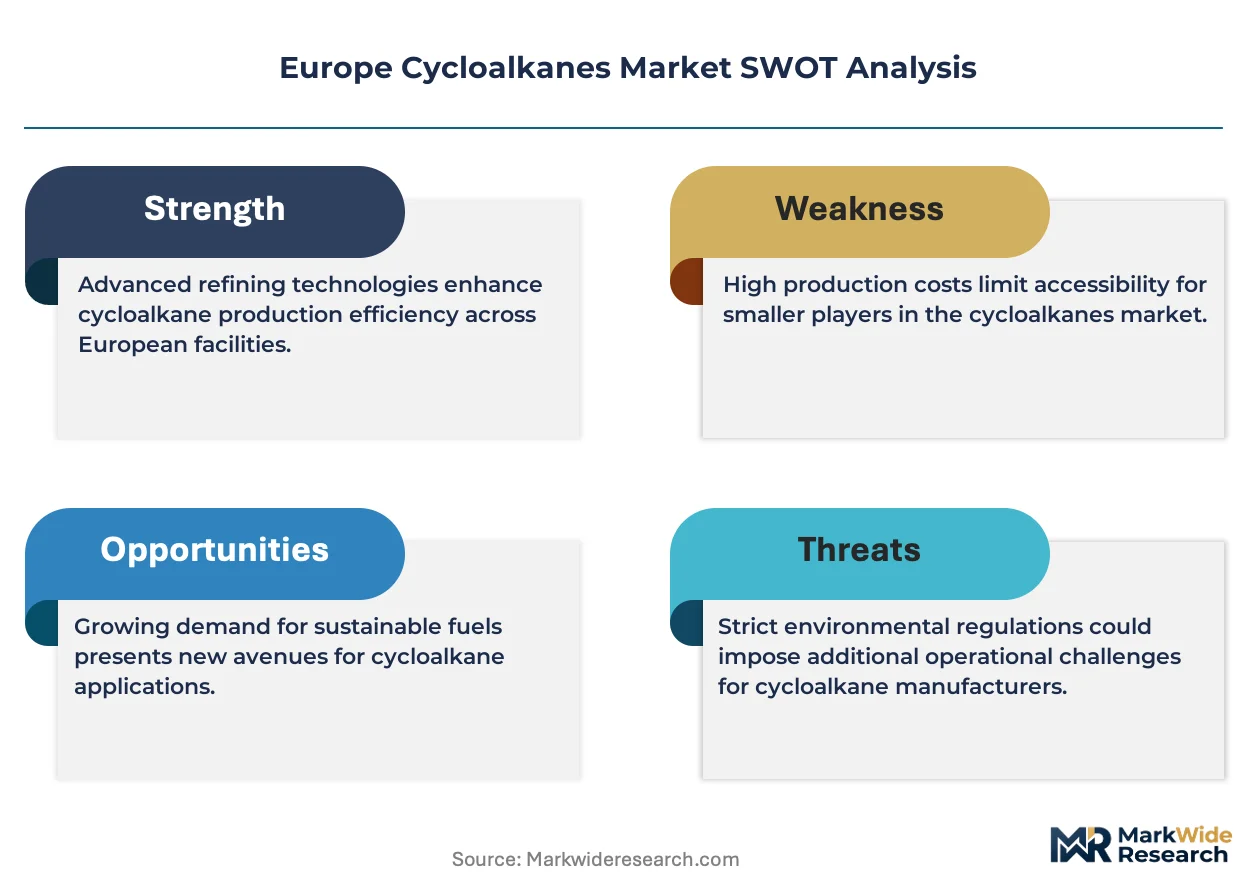
REACH Annex XVII volatile organic compound restrictions and the EU Green Deal's chemical sector decarbonization mandates are forcing cycloalkane producers to reconfigure hydrogenation processes and document carbon intensity across captive and merchant supply chains.
Growth Catalysts
- Pharmaceutical solvent demand:EMA pharmaceutical solvent guidelines are tightening purity specifications for cyclohexane used in active ingredient extraction across German and Swiss manufacturing zones.
- REACH compliance premiums:Registration requirements are filtering out non-compliant importers and consolidating demand around certified European producers with established substance dossiers.
- Nylon precursor chains:Caprolactam and adipic acid manufacturers in the Rhine-Ruhr corridor are expanding cycloalkane offtake for polymer intermediate production.
Market Restraints
- Benzene feedstock volatility:Catalytic hydrogenation economics remain tethered to aromatic feedstock pricing swings from Rotterdam refinery output.
- F-Gas Regulation phase-down:Cooling-dependent storage infrastructure faces retrofit costs as hydrofluorocarbon refrigerant restrictions tighten across EU member states.
- Bio-based substitution pressure:Emerging pilot projects for sugar-derived cycloalkanes threaten to displace petrochemical routes in sustainability-sensitive procurement frameworks.
Strategic Opportunities
- High-purity pharmaceutical grades:Solvent specifications for peptide synthesis and chromatography applications command margin premiums in Belgian and German markets.
- Port of Antwerp storage expansion:Northwest European hub infrastructure investments enable just-in-time delivery contracts for chemical industry buyers.
- CSRD supply chain disclosure:Corporate Sustainability Reporting Directive mandates create service revenue streams for carbon accounting and lifecycle documentation providers.
Industry Challenges
- Specialized process engineering talent:Catalytic hydrogenation expertise scarcity constrains capacity expansion timelines for merchant producers.
- Multi-jurisdiction certification lag:EMA, Swissmedic, and national competent authority solvent-grade approvals require 18-24 month validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cycloalkanes Market |
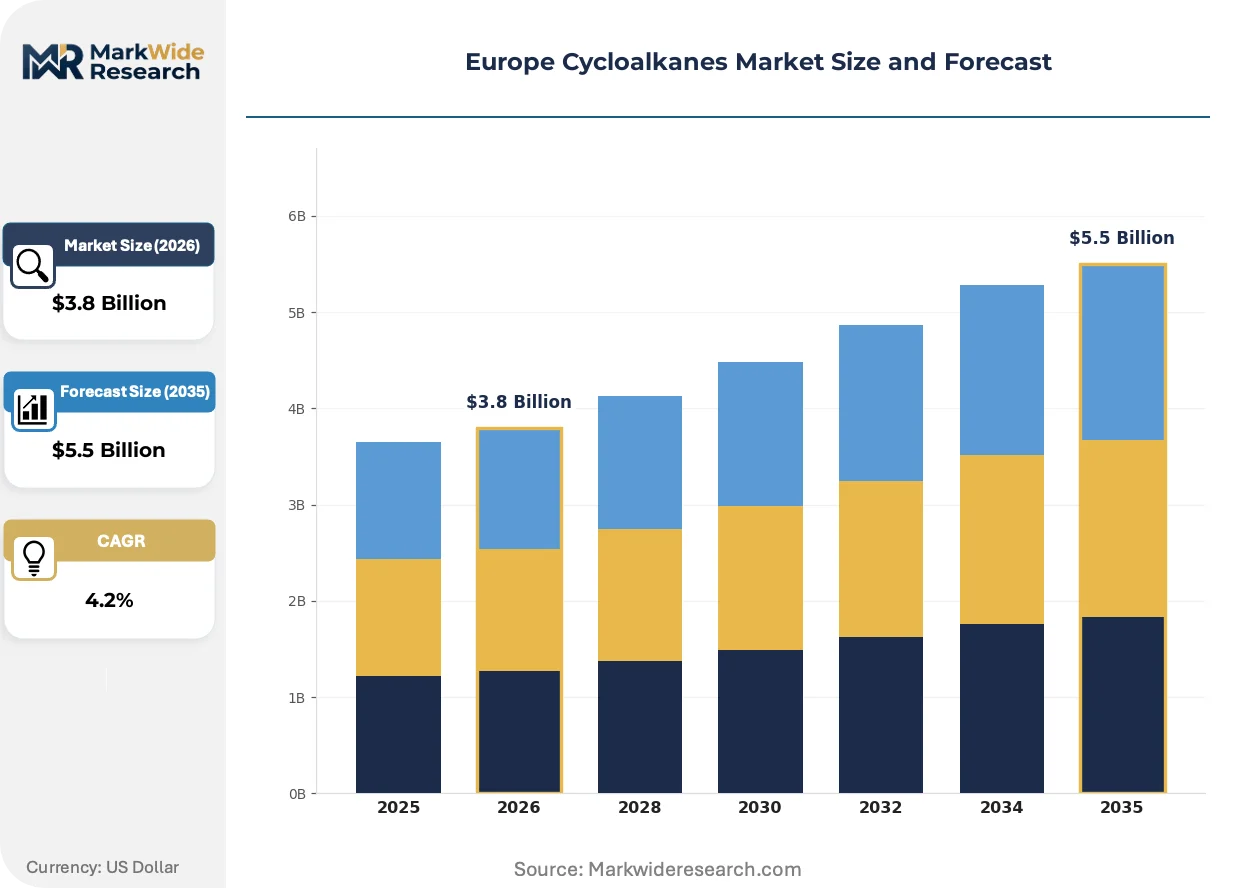
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyclohexane, Methylcyclopentane, Cyclooctane, Limiting Compound Application: Solvent, Chemical Intermediate, Fuel Additive, Rubber Manufacturing End User: Chemical Industry, Petrochemical Industry, Automotive, Pharmaceuticals Distribution Channel: Direct Sales, Online Sales, Distributors, Wholesalers |
| Companies Covered | INEOS Group Holdings S.A., BASF SE, ExxonMobil Chemical Company, Chevron Phillips Chemical Company LLC, Royal Dutch Shell plc, TotalEnergies SE, LyondellBasell Industries Holdings B.V., Haltermann Carless Group GmbH, SABIC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cycloalkanes Market Trends and Innovations
Digital process control systems and bio-based feedstock trials are reshaping how cycloalkane producers manage yield optimization and regulatory compliance across European manufacturing assets.
Advanced process analytical technology is virtualizing quality control workflows in cyclohexane hydrogenation units. Pharmaceutical manufacturers in Basel and Ludwigshafen are adopting real-time purity monitoring to compress batch release timelines. This virtualization is compressing the gap between production and certification, enabling same-day solvent dispatch for time-sensitive synthesis campaigns.
EU Green Deal chemical sector decarbonization targets are mandating scope 3 emissions disclosure from naphtha crackers through derivative processors. ECHA is coordinating standardized carbon footprint methodologies for hydrogenated aromatics. Specialty chemical distributors in the Netherlands and Germany are pre-positioning low-carbon certified inventory to capture public procurement preference margins.
Consolidated buying desks at multinational pharmaceutical and polymer producers are unbundling solvent procurement from logistics contracts. Direct producer relationships are displacing merchant intermediaries for volume cycloalkane offtake in the Rhine-Ruhr and Antwerp clusters. This concentration is most visible among German caprolactam manufacturers securing captive-adjacent supply through backward-integrated sourcing agreements.
Europe Cycloalkanes Market Segmentation
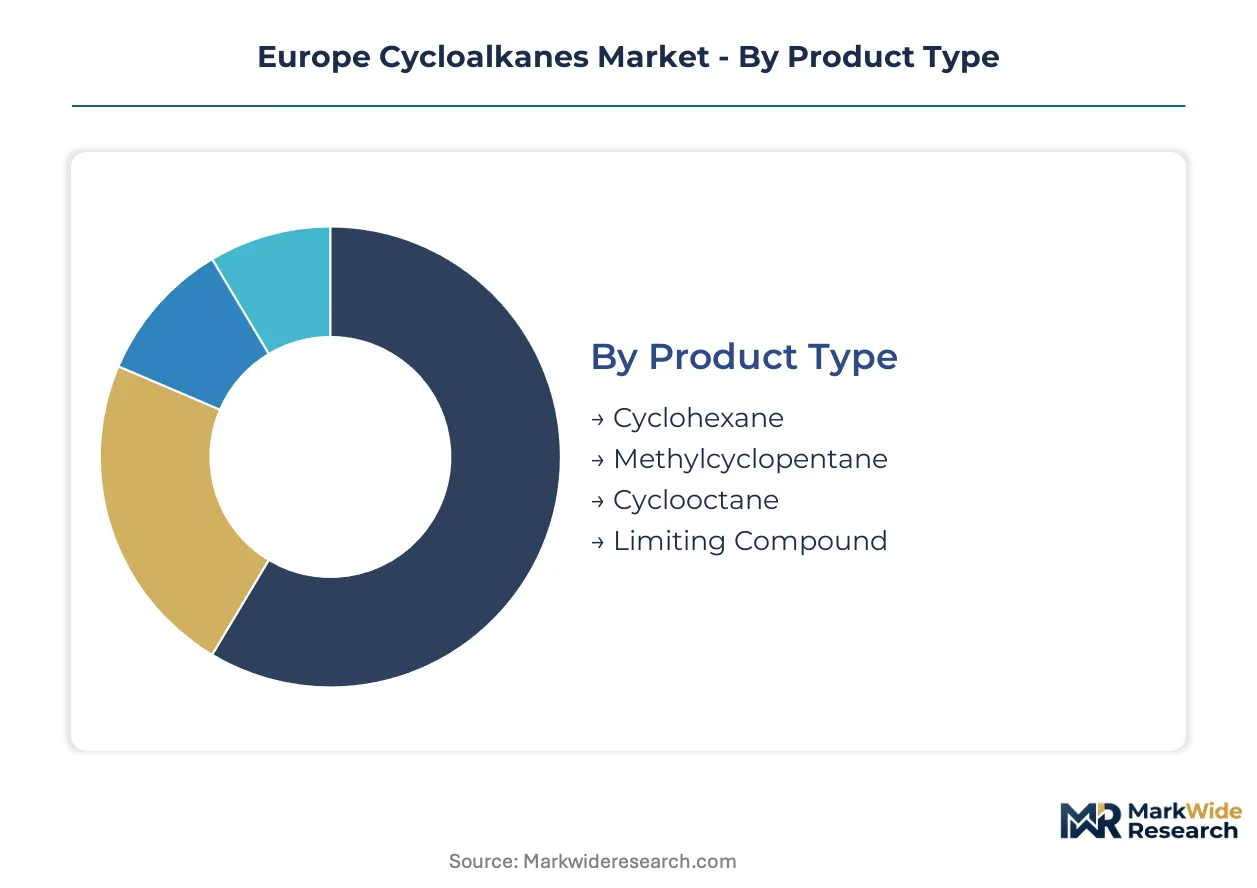
Cycloalkane procurement patterns across Europe fragment along purity grades, captive supply arrangements, and regulatory certification tiers. Producers must align product specifications with end-use validation requirements spanning REACH dossiers to EMA pharmaceutical solvent guidelines.
Product Type:
Cost tier differentiation separates commodity hydrogenation outputs from high-purity solvent grades commanding certification premiums.
- Cyclohexane:The principal hydrogenation output from benzene feedstock, cyclohexane serves as the dominant feedstock for adipic acid and caprolactam manufacturing across the Rhine-Ruhr corridor. BASF SE and INEOS Group Holdings S.A. maintain captive-adjacent supply arrangements for nylon precursor chains in Ludwigshafen and Grangemouth.
- Methylcyclopentane:This branched cycloalkane offers lower freezing points than cyclohexane, expanding its utility in specialized solvent applications for pharmaceutical extraction processes. Swiss and German manufacturers in Basel and Ludwigshafen are rotating methylcyclopentane into peptide synthesis workflows where thermal stability requirements differ from standard cyclohexane protocols.
- Cyclooctane:Larger ring structure enables specialized polymerization catalysis applications with niche demand concentration in Belgian chemical intermediate production.
- Limiting Compound:Trace impurity control specifications for pharmaceutical-grade certification drive purification investment at Haltermann Carless Group GmbH facilities.
Cyclohexane holds installed capacity. Methylcyclopentane is rotating up the share rankings.
Application:
Application segmentation tracks how cycloalkane functionality maps to process chemistry requirements across European manufacturing zones.
- Solvent:Pharmaceutical-grade solvent specifications demand sub-ppm impurity thresholds for active ingredient extraction and chromatography applications. EMA guidelines and Swissmedic requirements enforce 18-24 month validation cycles for solvent-grade approvals, consolidating demand around certified producers with established substance dossiers.
- Chemical Intermediate:Caprolactam and adipic acid manufacturers in the Rhine-Ruhr corridor and Port of Antwerp cluster absorb the largest volume offtake for nylon-6 and nylon-6,6 precursor production. REACH compliance premiums filter non-compliant importers from this intermediate supply chain.
- Fuel Additive:Limited penetration in European markets due to F-Gas Regulation phase-down constraints on storage infrastructure and EU Green Deal decarbonization mandates favoring alternative fuel pathways.
- Rubber Manufacturing:Cycloalkane-derived process oils face substitution pressure from bio-based alternatives in sustainability-sensitive procurement frameworks.
Solvent applications are climbing the fastest. Chemical intermediate demand maintains volume leadership.
End User:
Customer type concentration shapes contract structures, with consolidated buying desks at multinationals unbundling procurement from logistics.
- Chemical Industry:Polymer intermediate manufacturers dominate volume offtake through backward-integrated sourcing agreements. Direct producer relationships are displacing merchant intermediaries for volume cycloalkane procurement in northwest European clusters.
- Petrochemical Industry:Integrated naphtha crackers and hydrogenation units at INEOS Grangemouth and Lavéra sites sustain captive supply configurations with minimal external merchant exposure.
- Automotive:Nylon component suppliers for under-the-hood applications represent a downstream derivative demand node rather than direct cycloalkane procurement.
- Pharmaceuticals:Peptide synthesis and chromatography applications command the steepest margin premiums, with real-time purity monitoring enabling same-day solvent dispatch for time-sensitive synthesis campaigns in Basel and Ludwigshafen.
Chemical industry buyers hold contracted volume. Pharmaceutical end users are gaining share fastest on margin contribution.
Distribution Channel:
Channel structure reflects supply chain concentration in the Rhine-Ruhr corridor and Port of Antwerp hub infrastructure.
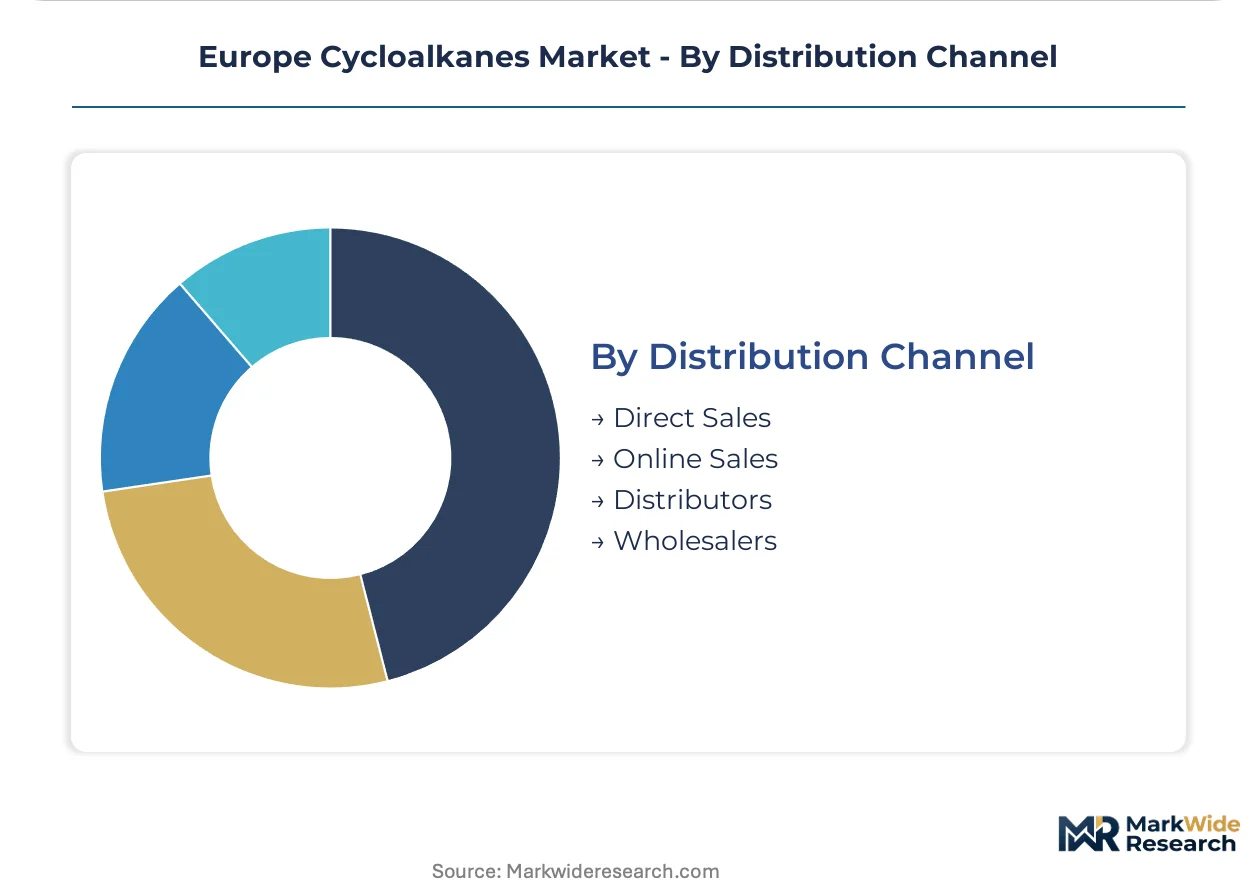
- Direct Sales:Backward-integrated caprolactam manufacturers and pharmaceutical multinationals negotiate direct producer relationships for volume offtake, compressing intermediary margins. CSRD supply chain disclosure mandates create documentation service revenue streams alongside direct contracts.
- Distributors:Specialty chemical distributors in the Netherlands and Germany pre-position low-carbon certified inventory to capture public procurement preference margins under EU Green Deal frameworks.
- Wholesalers:Bulk storage and blending infrastructure at Antwerp serves smaller chemical processors without captive hydrogenation capacity.
- Online Sales:Limited to standardized solvent grades with established certification documentation, primarily serving research-scale pharmaceutical and academic procurement.
Direct sales channels hold relationship density. Distributor networks are rotating up the share rankings on sustainability certification services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance mandates from ECHA anchor demand consolidation across northwest European chemical corridors. Germany and Belgium absorb the largest cycloalkane volumes through integrated nylon precursor and pharmaceutical solvent supply chains.
Germany
BASF SE and specialty distributors anchor cyclohexane demand for caprolactam production in Ludwigshafen. The EU Green Deal's chemical sector decarbonization targets force scope 3 emissions documentation across Rhine-Ruhr hydrogenation assets. Real-time purity monitoring systems in Basel-adjacent manufacturing zones compress pharmaceutical batch release timelines.
Belgium
Port of Antwerp petrochemical infrastructure enables just-in-time cycloalkane delivery contracts for chemical industry buyers. REACH Annex XVII volatile organic compound restrictions filter non-compliant importers from northwest European supply chains. INEOS Group Holdings S.A. leverages Lavéra-integrated hydrogenation capacity to sustain captive-adjacent supply configurations.
Netherlands
Rotterdam refinery output volatility shapes benzene feedstock economics for catalytic hydrogenation operators. CSRD supply chain disclosure mandates create carbon accounting service revenue streams for specialty chemical distributors. Dutch distributors pre-position low-carbon certified inventory to capture public procurement preference margins.
Switzerland
Swissmedic pharmaceutical solvent guidelines enforce 18-24 month validation cycles for cycloalkane grade approvals. Basel peptide synthesis manufacturers rotate methylcyclopentane into workflows where thermal stability requirements diverge from standard protocols. Haltermann Carless Group GmbH extends high-purity solvent distribution into Swiss manufacturing zones.
France
TotalEnergies SE and integrated petrochemical operators sustain cycloalkane output from Lavéra and Normandy refining complexes. F-Gas Regulation phase-down timelines impose retrofit costs on cooling-dependent storage infrastructure. EMA pharmaceutical solvent guidelines tighten purity specifications for active ingredient extraction across French manufacturing sites.
Europe Cycloalkanes Market Competitive Landscape
Capability concentration sits with integrated petrochemical majors; scale advantage sits with merchant hydrogenation specialists. The vendor base stratifies across three tiers: backward-integrated polymer producers, high-purity solvent specialists, and regional distributors. Strategic moves center on captive supply consolidation and sustainability certification pre-positioning.
Among integrated chemical majors, INEOS Group Holdings S.A. and BASF SE exemplify the captive-adjacent archetype through Grangemouth and Ludwigshafen hydrogenation assets. Haltermann Carless Group GmbH occupies a position within the high-purity solvent tier, serving pharmaceutical extraction demand across German and Swiss manufacturing corridors.
| Leading Market Players |
|---|
| INEOS Group Holdings S.A. |
| BASF SE |
| ExxonMobil Chemical Company |
| Chevron Phillips Chemical Company LLC |
| Royal Dutch Shell plc |
| TotalEnergies SE |
| LyondellBasell Industries Holdings B.V. |
| Haltermann Carless Group GmbH |
| SABIC |
| Others |
Pricing and Supply Chain Analysis
Rhine-Ruhr barge freight corridors transmit Rotterdam benzene price volatility directly into cyclohexane hydrogenation economics, compressing margins for merchant producers while amplifying backward-integrated players' cost advantages across pharmaceutical and polymer precursor tiers.
Pricing Analysis
Geographic price spreads widen between Antwerp hub deliveries and Swiss inland destinations, reflecting certification-grade premiums for EMA-compliant solvent batches. Pricing stratifies across pharmaceutical-grade, polymer-intermediate, and technical solvent tiers, with purity thresholds and REACH dossier completeness as primary differentiation drivers. Cost compression in technical grades intensifies as Rotterdam refinery output volatility feeds into benzene feedstock economics. Polymer intermediate buyers exhibit lowest price sensitivity due to captive supply arrangements, while research-scale pharmaceutical procurement shows highest elasticity.
Supply Chain Analysis
Extended payment terms from Belgian and German distributors to hydrogenation operators stretch working capital cycles, favoring integrated majors with balance-sheet depth over merchant specialists. Supply concentrates in Germany, Belgium, and the Netherlands, with feedstock dependencies on Rotterdam refinery benzene, North Sea naphtha, and Russian-origin aromatic alternatives pre-sanctions. Single-source vulnerability runs through the Rotterdam-Antwerp pipeline corridor for benzene feedstock. Distribution runs through direct producer relationships for volume chemical industry offtake, with specialty distributors serving pharmaceutical validation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon accounting and lifecycle documentation services attach to core cycloalkane supply contracts at faster expansion rates than base chemical volumes, as CSRD mandates force disclosure depth across Belgian and German manufacturing zones.
For Market Incumbents: Pre-empt bio-based cycloalkane substitution threats by securing pilot-scale fermentation partnerships or lignocellulosic feedstock offtake agreements before public procurement frameworks harden sustainability criteria. Deepen backward integration into hydrogenation catalyst supply and real-time purity monitoring systems to defend margin position against merchant competitors. For New Entrants and Emerging Players: Pursue high-purity pharmaceutical solvent certification as the most penetrable tier, exploiting 18-24 month EMA validation backlogs that constrain incumbent capacity allocation. Target Swiss and German peptide synthesis manufacturers with methylcyclopentane thermal stability advantages over standard cyclohexane protocols, leveraging direct technical sales engagement to bypass established distributor relationships. For Investors and Strategic Acquirers: High-purity solvent specialists with established EMA dossiers and Antwerp storage infrastructure represent the most defensible acquisition archetype in a five-to-ten-year decarbonization transition. Monitor bio-based cycloalkane pilot project yield announcements as the critical inflection signal for petrochemical route obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogenation Assets | Captive benzene-to-cyclohexane conversion at Ludwigshafen and Grangemouth insulates margin from Rotterdam price volatility. |
| Pharmaceutical-Grade Certification Investment | EMA and Swissmedic solvent dossiers command premium positioning in Basel and Ludwigshafen peptide synthesis supply chains. |
| Port of Antwerp Storage Expansion | Blending infrastructure investments enable just-in-time delivery contracts for Rhine-Ruhr chemical industry buyers. |
| Carbon Intensity Documentation Services | CSRD-compliant scope 3 emissions tracking creates recurring revenue streams alongside core cycloalkane supply contracts. |
| Bio-Based Feedstock Pilot Partnerships | Sugar-derived cycloalkane trials with EU Green Deal funding secure positioning for sustainability-sensitive public procurement frameworks. |
Research Methodology
Initial hypotheses were tested against primary input from hydrogenation plant managers, pharmaceutical procurement leads at Basel and Ludwigshafen manufacturers, specialty chemical distributors in Rotterdam and Antwerp, and EMA regulatory affairs specialists, then refined through secondary validation against Cefic industry statistics, ECHA REACH registration databases, SEC filings from integrated petrochemical majors, and EU customs trade flow records, with bottom-up capacity assessments triangulated against top-down demand aggregation.
Demand-supply-balance modeling across the projection horizon segmented cycloalkane markets by purity grade tier, end-use application, captive versus merchant supply configuration, and regional production hub concentration, with CAGRs derived from elasticity-adjusted volume projections and value evolution tracking certification premium capture, incorporating benzene feedstock price forecasting and F-Gas Regulation phase-down timelines as industry-specific inputs.
Sensitivities concentrate around Rotterdam refinery output disruptions, REACH Annex XVII expansion scope, and bio-based cycloalkane pilot yield breakthroughs. Forecasts reflect documented assumptions on regulatory enforcement intensity and hydrogenation capacity commissioning schedules. Macroeconomic contraction, regulatory acceleration beyond current EU Green Deal targets, or commercial-scale bio-based process viability would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Organic Peroxide Market
Organic Chemicals
Organocatalyst Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
Aminophenol Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Organic Polysulfide Market
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
Chlorinated Isocyanurates Market
Organic Chemicals
High Purity Metal Organics Market
Organic Chemicals
Synthetic Camphor Market
Organic Chemicals
North America Organic Acid Market
Organic Chemicals
Terephthalic Aldehyde Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
Global Biphenyl Market