
 Global Glycolic Acid Market | 2026-2036
Global Glycolic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glycolic Acid Market Analysis
A shift from single-source chloroacetic acid feedstock toward multi-source procurement is rebalancing supply security across the glycolic acid value chain. The Chemours Company leverages its fluorochemical heritage to sustain high-purity acid output for electronics etching. CABB Group GmbH anchors European supply through integrated chlorination chemistry at its German sites. Zhonglan Industry Co., Ltd. competes on cost-position via captive caustic soda and chlorine access in China's chemical corridor.
Glycolic acid, the smallest alpha-hydroxy acid with molecular formula C₂H₄O₃ and a molecular weight of 76.05 g/mol, derives primarily from chloroacetic acid hydrolysis or catalytic oxidation of ethylene glycol; its dual hydroxyl and carboxyl functionality enables keratolytic action in dermatology and chelating performance in industrial cleaning. Cosmetic grade commands premium positioning due to stringent heavy-metal limits and microbial specifications demanded by skin care and hair care formulators, while pharmaceutical grade sees accelerating qualification timelines as dental products and chemical peel applications expand in regulated markets. Industrial grade occupies volume leadership but faces margin compression from substitute organic acids in metal finishing and textile processing.
EPA oversees discharge thresholds for glycolic acid manufacturing effluents under Clean Water Act permits, while REACH registration mandates toxicological dossiers for industrial-grade imports into Europe; China's MEE enforces dual carbon goals that tighten energy-intensity benchmarks for chloroacetic acid-based production routes. FDA monograph compliance shapes pharmaceutical grade specifications for dental products sold in the United States. Stakeholders must monitor feedstock cost volatility and regulatory divergence between cosmetic and industrial purity standards to secure position.
Market Dynamics
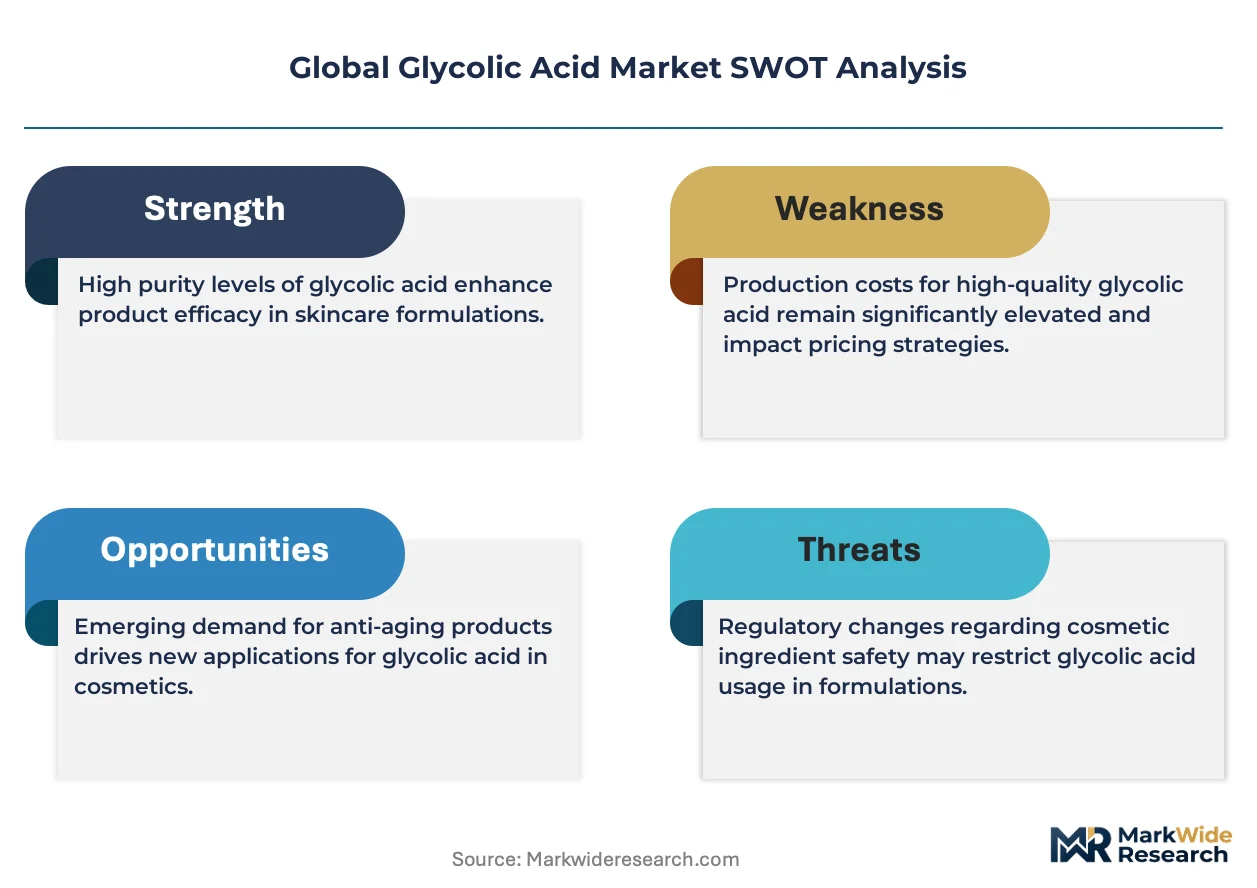
Feedstock concentration in China's Shandong province and tightening REACH purity thresholds in Europe are bifurcating competitive advantage between cost-positioned Asian producers and specification-driven Western suppliers.
Growth Catalysts
- REACH compliance escalation:ECHA's tightened purity dossiers for industrial-grade imports force incumbent suppliers to upgrade purification trains, creating qualification barriers that protect premium-positioned European producers.
- Electronics etching demand:Semiconductor fabs in Taiwan and South Korea specify sub-ppm metal content for wafer cleaning applications, pulling high-purity acid volumes away from commodity cosmetic and industrial channels.
- Dual hydroxyl-carboxyl functionality:Glycolic acid's unique molecular architecture enables keratolytic performance unmatched by lactic or citric acid alternatives in professional dermatology settings.
Market Restraints
- Chloroacetic acid cost volatility:Acetic acid and chlorine feedstock swings transmit directly to glycolic acid manufacturing economics, compressing margin visibility for non-integrated producers.
- Shandong supply concentration:Overreliance on a single Chinese province for chloroacetic acid feedstock exposes the value chain to localized environmental enforcement actions and energy-rationing events.
- Catalytic oxidation substitution:Ethylene glycol-based production routes achieve lower carbon intensity but require precious metal catalysts that face supply security concerns from South African and Russian platinum group metal flows.
Strategic Opportunities
- Brazilian pharmaceutical qualification:ANVISA's expanding monograph for dental products creates first-mover advantage for producers willing to navigate extended regulatory timelines in Latin America's largest market.
- Biodegradable polymer feedstock:Polyglycolic acid demand from medical suture and packaging applications opens volume offtake channels distinct from traditional cosmetic and industrial segments.
- Green chemistry procurement mandates:EU Green Deal requirements for bio-based content in public-sector cleaning contracts favor fermentation-derived glycolic acid pathways over petrochemical routes.
Industry Challenges
- Analytical chemist scarcity:Heavy-metal testing at ppb levels and microbial enumeration for cosmetic-grade certification require specialized talent pools concentrated in Basel, Shanghai, and New Jersey corridor.
- Legacy chlorination asset retrofit:European producers face stranded asset risk as MEE-style dual carbon benchmarks diffuse globally, forcing capital allocation toward electrochemical or enzymatic process development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glycolic Acid Market |
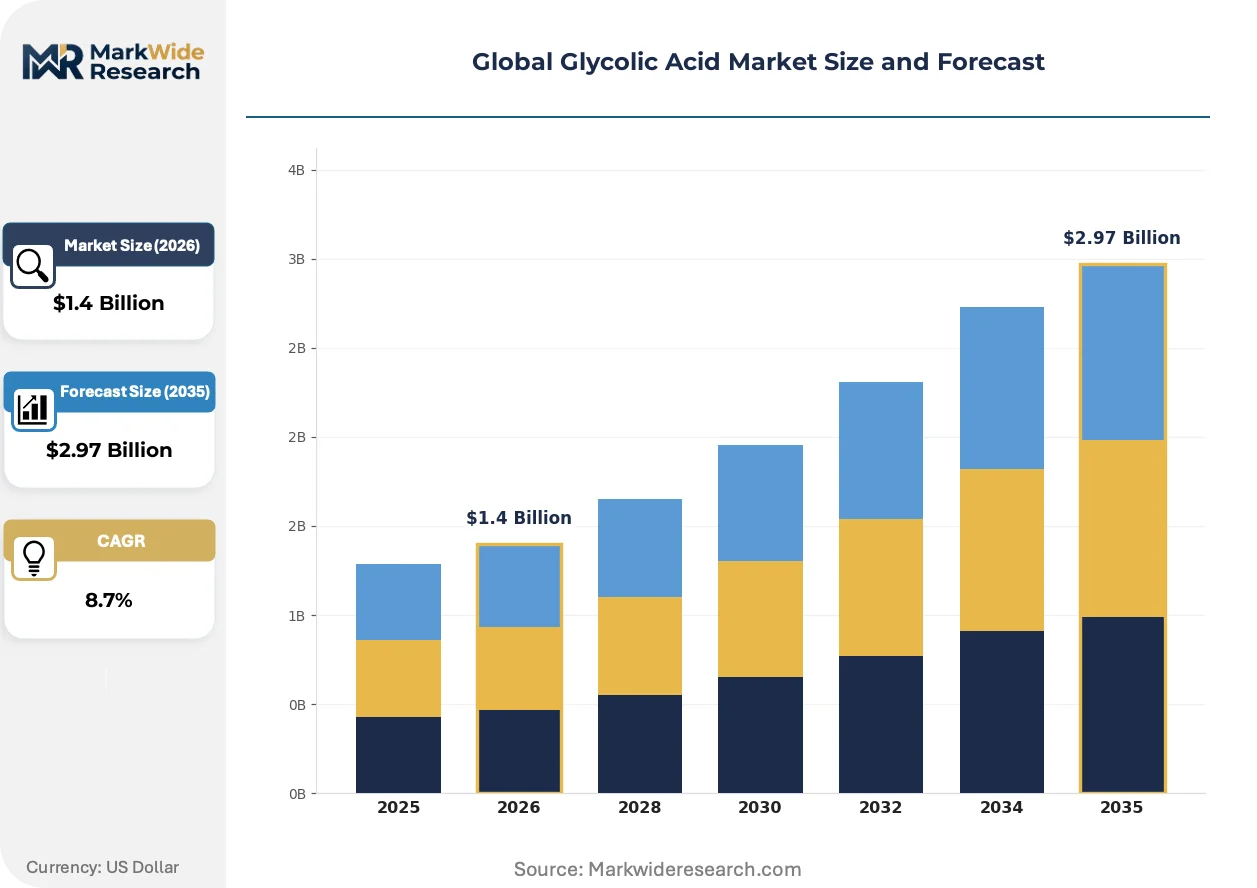
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Industrial Grade, Pharmaceutical Grade, Food Grade Application: Skin Care, Hair Care, Dental Products, Chemical Peels End User: Manufacturers, Distributors, Retailers, Consumers Packaging Type: Bulk Packaging, Retail Packaging, Sachets, Bottles |
| Companies Covered | The Chemours Company, China Petrochemical Corporation, CABB Group GmbH, Zhonglan Industry Co., Ltd., Water Chemical Co., Ltd., Avid Organics, Saanvi Corp, CrossChem LP, Shandong Xinhua Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glycolic Acid Market Emerging Trajectories
Process chemistry innovation and regulatory differentiation are fragmenting what was historically a commodity alpha-hydroxy acid market into distinct specification tiers with divergent margin structures.
Membrane electrodialysis purification is rewriting quality economics for electronics-grade material. Taiwanese semiconductor chemical suppliers deploy this technology to achieve sub-100 ppb sodium and potassium specifications demanded by 3nm node wafer processing. The capital intensity of this approach is compressing viable supply base to fluorochemical heritage producers with existing high-purity infrastructure.
REACH Annex XVII restrictions on perfluorinated substances are redirecting formulation R&D toward glycolic acid in industrial cleaning applications previously served by fluorosurfactants. German metal finishing operations now specify glycolic acid-based derusting formulations to preempt regulatory obsolescence. This substitution pattern is most pronounced in automotive supply chains subject to OEM sustainability scorecards.
Direct-to-clinic distribution is disintermediating traditional cosmetic ingredient wholesalers for professional peel applications. South Korean dermatology chains now contract directly with Zhonglan Industry and CABB Group for certified pharmaceutical-grade volumes, bypassing regional distributors. This channel compression is visible across Seoul's Gangnam district aesthetic clinic clusters where treatment volume concentration supports container-load procurement economics.
Global Glycolic Acid Market Segmentation
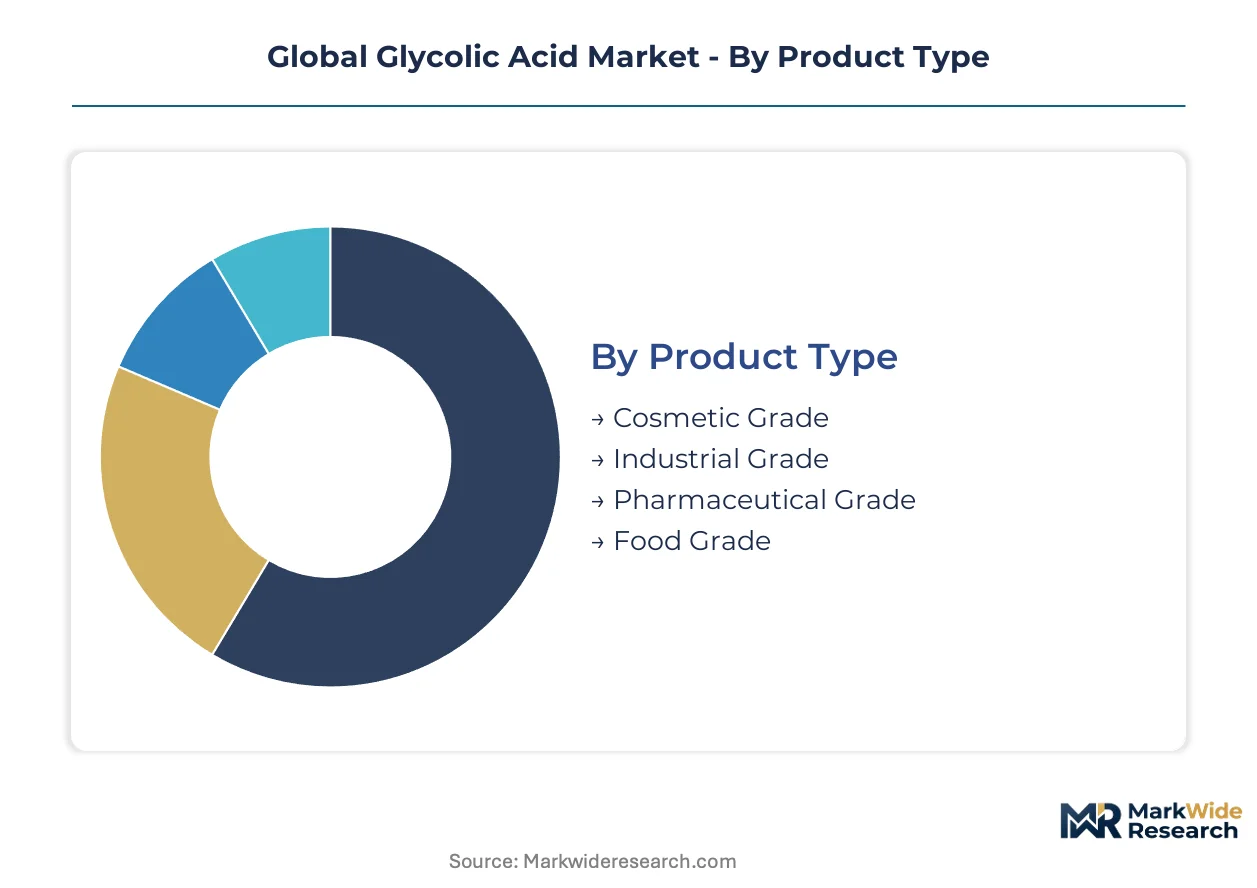
Glycolic acid's molecular versatility creates distinct value tiers where purity thresholds, regulatory pathways, and end-use performance requirements fragment what suppliers can offer. Buyers select grades based on certification burden rather than chemical identity alone.
Product Type:
Cost tier determines accessible applications and margin structure across the value chain.
- Cosmetic Grade:Heavy-metal limits below 10 ppm and microbial specifications per ISO 16128 define this segment. South Korean formulators in Seoul's Gangnam district drive qualification timelines for professional peel applications.
- Industrial Grade:Metal finishing and textile processing absorb volume here, though REACH Annex XVII compliance on perfluorinated substance alternatives is redirecting formulation R&D from fluorosurfactants. German automotive supply chains now specify glycolic acid-based derusting to satisfy OEM sustainability scorecards.
- Pharmaceutical Grade:FDA monograph compliance for dental products and ANVISA qualification timelines in Brazil shape commercial access.
- Food Grade:FSSAI and FDA food additive regulations govern permissible applications in flavoring and pH adjustment.
Volume sits with Industrial Grade; growth tilts toward Cosmetic Grade.
Application:
End-use performance requirements dictate formulation concentration and delivery mechanism.
- Skin Care:Keratolytic action at 5-10% concentration in daily-use products and 20-70% in professional settings. Taiwanese dermatology chains contract directly with producers for certified pharmaceutical-grade volumes.
- Chemical Peels:Professional dermatology settings demand pH-buffered systems with neutralization protocols. Direct-to-clinic distribution is disintermediating traditional cosmetic ingredient wholesalers.
- Hair Care:Scalp exfoliation and cuticle smoothing applications at lower active concentrations.
- Dental Products:Enamel etching and caries prevention formulations under FDA and EMA pharmaceutical device frameworks.
Professional applications command premium positioning; mass-market skin care delivers scale.
End User:
Procurement scale and technical capability separate viable supply relationships.
- Manufacturers:Integrated personal care and pharmaceutical compounders with in-house analytical laboratories for incoming raw material verification.
- Distributors:Regional chemical traders managing inventory risk on specification-grade material with certificate-of-analysis documentation.
- Retailers:Private-label skincare brands sourcing pre-formulated concentrates rather than pure acid.
- Consumers:Direct purchase of low-concentration over-the-counter products through e-commerce channels.
Manufacturers anchor volume commitments; retailer private-label expansion is climbing fastest.
Packaging Type:
Supply chain position and handling infrastructure determine format economics.
- Bulk Packaging:ISO tank containers and IBC totes for chloroacetic acid-integrated producers serving industrial-scale offtake.
- Retail Packaging:Amber glass and fluoropolymer-lined bottles preserving stability for cosmetic and pharmaceutical channels.
- Sachets:Single-use professional peel envelopes with pre-measured active loads.
- Bottles:Standard HDPE and PET formats for consumer-facing skin care and hair care products.
Bulk Packaging dominates tonnage; sachet formats in professional peels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chloroacetic acid feedstock clusters in Shandong province anchor glycolic acid manufacturing economics across Asia, while REACH compliance in Europe and FDA monograph enforcement in North America fragment specification requirements by geography.
China
Shandong province concentrates chloroacetic acid output that feeds glycolic acid hydrolysis routes. MEE enforces dual carbon goals tightening energy-intensity benchmarks for chemical producers. Qingdao and Weifang industrial corridors host integrated chlor-alkali complexes with captive caustic soda supply.
Germany
Industrial-grade demand from automotive metal finishing absorbs volume as REACH Annex XVII restricts perfluorinated substance alternatives. ECHA's tightened purity dossiers protect domestic producers through qualification barriers. CABB Group's integrated chlorination chemistry at Lampertheim and Gersthofen anchors European supply security.
United States
Electronics etching specifications from Taiwanese and South Korean semiconductor fabs pull high-purity acid volumes through specialty chemical distributors. EPA Clean Water Act permits govern discharge thresholds for manufacturing effluents. Gulf Coast petrochemical infrastructure supports ethylene glycol-based catalytic oxidation routes.
South Korea
Seoul's Gangnam district aesthetic clinic clusters drive cosmetic-grade qualification timelines for professional peel applications. MFDS pharmaceutical device frameworks govern dental product formulations. Direct-to-clinic procurement patterns disintermediate traditional cosmetic ingredient wholesalers.
Brazil
ANVISA's expanding pharmaceutical monograph for dental products creates regulatory pathway complexity for imported grades. São Paulo and Rio de Janeiro manufacturing bases absorb industrial-grade volumes for textile processing applications. Extended qualification timelines favor established suppliers with local technical service presence.
Global Glycolic Acid Market Vendor Landscape
Global majors compete with regional champions across specification tiers, with fluorochemical heritage producers and integrated chlor-alkali operators occupying distinct competitive positions. Market structure fragments across three archetypes: specification-driven Western suppliers with high-purity infrastructure, cost-positioned Asian producers with captive feedstock access, and specialty distributors serving qualified pharmaceutical channels. Dominant competitive moves include purification technology licensing for electronics-grade certification and backward integration into chloroacetic acid production.
Within the fluorochemical heritage tier, The Chemours Company represents specification-driven positioning for sub-ppm metal content applications. Among German integrated chemical producers, CABB Group GmbH exemplifies European supply anchoring through chlorination chemistry assets. Chinese cost-positioned producers include Zhonglan Industry Co., Ltd., which occupies a position tied to captive caustic soda and chlorine access in Shandong province.
| Leading Market Players |
|---|
| The Chemours Company |
| China Petrochemical Corporation |
| CABB Group GmbH |
| Zhonglan Industry Co., Ltd. |
| Water Chemical Co., Ltd. |
| Avid Organics |
| Saanvi Corp |
| CrossChem LP |
| Shandong Xinhua Pharmaceutical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between electronics-grade sub-ppm specifications and commodity cosmetic material manifests in divergent pricing architectures and supply chain configurations. REACH purity escalation in Europe and semiconductor fab qualification timelines in Taiwan and South Korea create protected premium tiers, while Shandong-based chloroacetic acid feedstock clusters anchor economy-grade output for mass-market personal care.
Pricing Analysis
Certificate-of-analysis bundling separates qualified pharmaceutical-grade supply from unbundled industrial commodity transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and analytical warranty scope. Price differentiation hinges on heavy-metal testing at ppb thresholds and microbial enumeration protocols. Cost compression in industrial-grade channels is intensifying because substitute organic acids displace glycolic acid in metal finishing applications. Mass-market cosmetic formulators exhibit highest price sensitivity; semiconductor chemical buyers prioritize specification compliance over unit economics.
Supply Chain Analysis
Analytical chemist scarcity in Basel, Shanghai, and New Jersey corridor constrains quality assurance capacity for specification-grade output. Manufacturing concentrates in China, Germany, and the United States. Chloroacetic acid feedstock draws from Shandong province chlor-alkali complexes, while ethylene glycol oxidation routes rest on Gulf Coast petrochemical infrastructure. Single-source vulnerability in South African and Russian platinum group metal flows threatens catalytic oxidation economics. Distribution runs through specialty chemical distributors for qualified pharmaceutical channels and bulk tank operators for industrial offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is mounting as REACH compliance costs and purification technology capital requirements force sub-scale producers toward exit. ECHA dossier escalation and membrane electrodialysis infrastructure demands favor integrated players with existing high-purity assets.
For Market Incumbents: Cement specification leadership through backward integration into chloroacetic acid production and membrane electrodialysis capacity addition in Taiwan or South Korea. CABB Group and Chemours heritage positions in fluorochemical purification create defendable moats against emerging Asian entrants. Channel control through direct-to-clinic distribution in Seoul's Gangnam district aesthetic clusters reinforces margin capture. For New Entrants and Emerging Players: The premium-economy price-point gap in Brazilian pharmaceutical-grade supply creates white-space opportunity. ANVISA qualification timelines and extended regulatory pathways favor first-movers with local technical service presence. Target fermentation-derived glycolic acid pathways to capture EU Green Deal bio-based procurement mandates in public-sector cleaning contracts. Go-to-market through specialty distributors serving qualified dental product channels. For Investors and Strategic Acquirers: Re-rating potential sits with fluorochemical heritage producers given electronics etching demand pull from 3nm node semiconductor fabs. Five-to-ten year viability favors specification-driven Western suppliers with existing sub-ppm infrastructure over cost-positioned Asian commodity players. Signal to watch: Taiwanese semiconductor chemical supplier qualification timelines for membrane electrodialysis-certified volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chloroacetic Acid | Captive feedstock supply from Shandong chlor-alkali complexes insulates margin from acetic acid and chlorine volatility. |
| Membrane Electrodialysis Capacity Buildout | Taiwanese semiconductor fabs specify sub-100 ppb sodium and potassium for 3nm wafer processing applications. |
| ANVISA Pharmaceutical Qualification | Brazilian dental product monograph expansion creates regulatory pathway for imported pharmaceutical-grade volumes. |
| Fermentation-Derived Production Transition | EU Green Deal bio-based content mandates in public cleaning contracts favor non-petrochemical glycolic acid routes. |
| Direct-to-Clinic Distribution Establishment | Seoul Gangnam aesthetic clinic clusters support container-load procurement economics bypassing regional wholesalers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant managers at chlor-alkali complexes, procurement leads at personal care OEMs, technical R&D directors, and distribution channel partners combined with secondary validation from ECHA REACH dossiers, FDA monograph submissions, SEC 10-K disclosures, and Cefic chemical industry reports. Bottom-up grade-by-grade volume builds and top-down market sizing triangulated across data sources.
Granularity-level modeling tracked grade tier, end-use industry, packaging format, and regional production hub dimensions throughout the forecast period. CAGRs derived from segment-level growth trajectory analysis and cross-referenced against feedstock cost elasticity assumptions. Forecast inputs incorporated chloroacetic acid feedstock price volatility bands and semiconductor fab capacity expansion pipelines for electronics-grade demand.
Inputs from ECHA registration databases and ANVISA filing records were available through the study window; gaps in real-time Shandong province environmental enforcement action data introduce uncertainty bands around Chinese supply assumptions. Forecasts reflect documented assumptions on dual carbon goal implementation intensity and platinum group metal supply security. Material deviation in REACH Annex XVII expansion scope or Taiwanese semiconductor node transition timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
Organic Coating Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
2,5-Dimethyl-2,4-Hexadiene Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
Acetic Acid Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
Organocatalyst Market
Organic Chemicals
Aspartic Acid Market
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
Asia-Pacific Organic Acid Market
Organic Chemicals
North America Humic Acid Market
Organic Chemicals
North America Organic Acid Market
Organic Chemicals
North America Biphenyl Market