
 Chloro -Dimethylsilane (CAS 1066-35-9) Market | 2026-2036
Chloro -Dimethylsilane (CAS 1066-35-9) Market Size, Share, and Industry Trends Forecast 2026-2036
Chloro -Dimethylsilane (CAS 1066-35-9) Market Analysis
Chinese organosilane production is decoupling from legacy petrochemical feedstock dependencies. Wacker Chemie AG anchors its European supply position through backward integration into silicon metal refining. Shin-Etsu Chemical Co., Ltd. dominates ultra-high-purity grades for electronics applications. Evonik Industries differentiates via specialized surface treatment formulations.
Chloro-dimethylsilane is a reactive organosilicon compound with formula (CH3)2SiHCl, manufactured through direct synthesis of methyl chloride with silicon-copper alloy at elevated temperatures. The compound serves as a critical intermediate for silicone polymerization and surface modification chemistry. Purity Grade commands premium positioning due to stringent semiconductor industry specifications, while Industrial Grade sustains volume throughput in construction sealants. Surface Treatments represents the fastest-growing application segment as electronics miniaturization drives atomic-layer deposition demand.
EPA oversight governs chlorosilane emissions and workplace exposure limits in United States manufacturing facilities. REACH registration requirements in the European Union mandate full toxicological dossiers for import volumes exceeding one tonne annually. China's MEE enforces dual carbon goals that constrain energy-intensive chlorosilane furnace operations. Stakeholders must monitor evolving purity standards at the intersection of semiconductor fabrication and environmental compliance.
Market Dynamics
Semiconductor fabrication node shrinkage below 3nm is forcing purity specification escalation across chlorosilane supply chains, compressing qualified supplier pools while amplifying contract duration premiums for certified volumes.
Growth Catalysts
- Atomic-layer deposition protocols:Chipmakers in Taiwan and South Korea now specify sub-ppb metallic impurity thresholds for precursor chemicals, pulling ultra-high-purity chloro-dimethylsilane into mainstream procurement.
- MEE dual carbon enforcement:China's Ministry of Ecology and Environment carbon intensity caps are shuttering legacy furnace operations, consolidating output among integrated producers with captive renewable energy.
- Yangtze River Delta clustering:Chemical infrastructure co-location around Shanghai-Ningbo ports reduces logistics friction for electronics-grade material, concentrating demand pull in a 200-kilometer radius.
Market Restraints
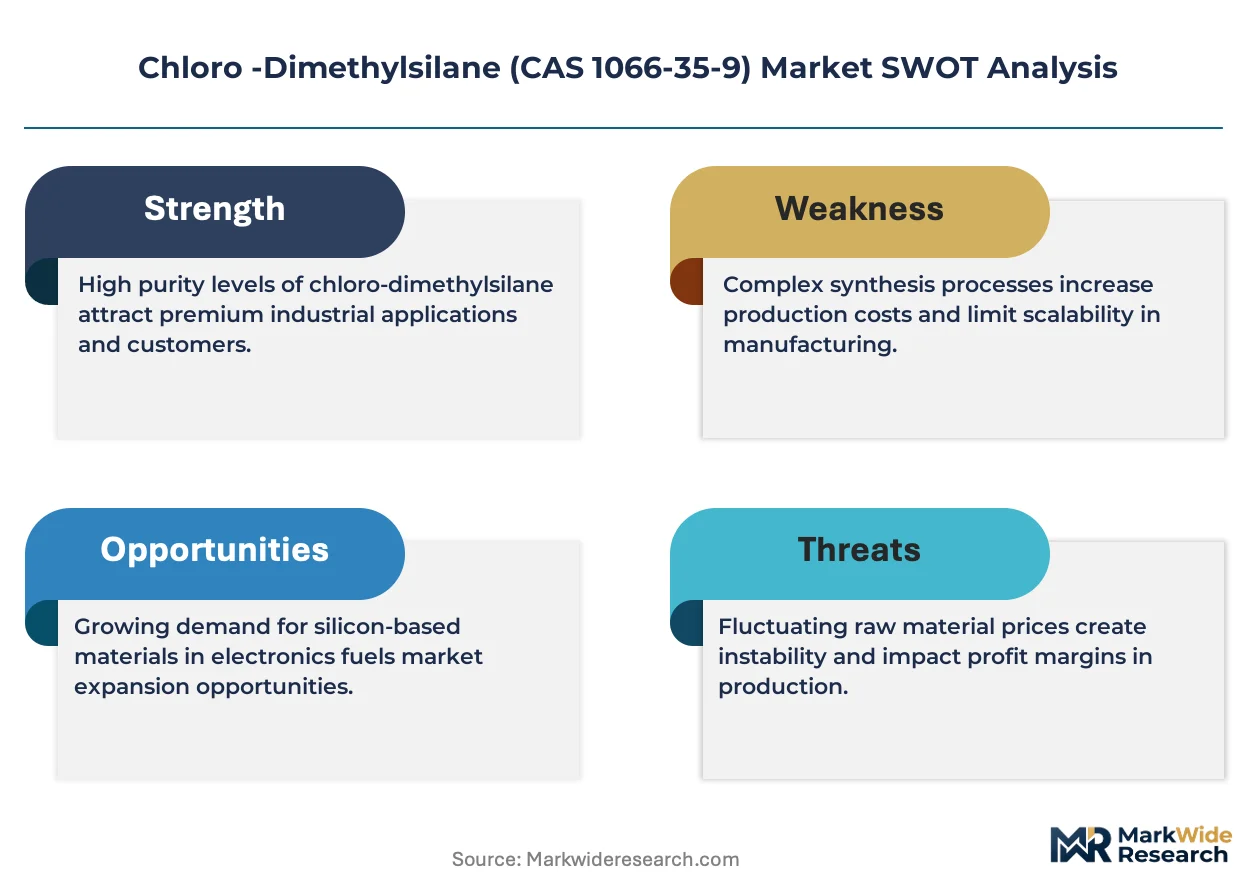
- Silicon metal cost volatility:Ferrosilicon and metallurgical-grade silicon price swings transmit directly to chlorosilane feedstock economics, squeezing margin predictability for non-integrated producers.
- Qilu and Zhejiang supply concentration:Over half of China's organosilane capacity sits in two provincial jurisdictions, exposing buyers to simultaneous weather and policy disruption risks.
- REACH registration friction:ECHA's full toxicological dossier requirements for import volumes above one tonne annually create compliance cost barriers for specialty grade market entry.
Strategic Opportunities
- Indian semiconductor fabrication:Gujarat and Tamil Nadu greenfield fabs under the PLI scheme will require localized high-purity precursor supply, opening import substitution partnerships.
- Silane-amine hybrid surface treatments:Convergence of chloro-dimethylsilane with amino-functional chemistry enables next-generation moisture barrier coatings for flexible electronics substrates.
- Direct-to-fab distribution:Bypassing regional distributors through ISO-tank direct delivery to semiconductor chemical handling facilities captures margin and reduces contamination risk.
Industry Challenges
- Semiconductor-grade analytical chemist scarcity:ICP-MS and gas chromatography expertise for sub-ppb validation remains concentrated among a handful of contract laboratories, extending qualification timelines.
- Legacy equipment retrofit costs:Existing distillation infrastructure requires stainless-steel replacement and inert atmosphere upgrades to meet current electronics purity specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chloro -Dimethylsilane (CAS 1066-35-9) Market |
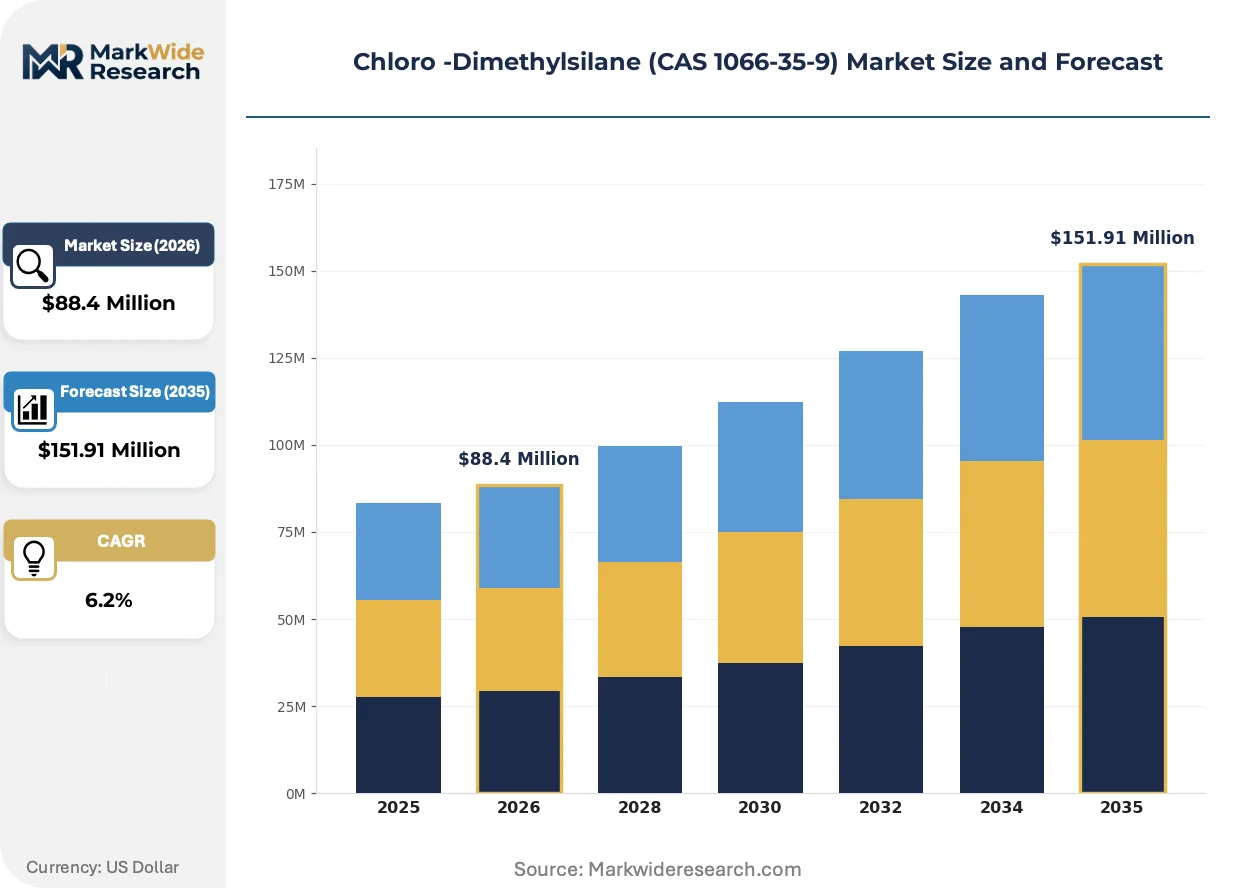
| Market Size in 2026 | $88.4 Million |
| Market Size in 2035 | $151.91 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purity Grade, Technical Grade, Industrial Grade, Research Grade Application: Silicone Production, Surface Treatments, Adhesives, Sealants End User: Chemical Manufacturers, Coatings Industry, Electronics Manufacturers, Construction Sector Distribution Channel: Direct Sales, Distributors, Online Retail, Chemical Suppliers |
| Companies Covered | Shanghai Chuqing Organosilane, PCC Group, Dow Corning, Jiande Zhiyou Silicone Materials, Evonik Industries, Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Gelest, Inc., Momentive Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chloro -Dimethylsilane (CAS 1066-35-9) Market Emerging Trajectories
Chloro-dimethylsilane applications are bifurcating between commodity industrial sealants and precision semiconductor precursors, with technology investment concentrating at the high-purity extreme where specification rigor creates defendable positioning.
Plasma-enhanced chemical vapor deposition precursors are expanding into 3D NAND stack fabrication, where memory manufacturers Samsung and SK Hynix now consume organosilanes at volumes previously reserved for logic chip production. This consumption scale is compressing spot market availability for industrial-grade material and forcing construction sealant formulators toward longer-term contract structures.
REACH Annex XVII restrictions on persistent organic pollutants are tightening impurity disclosure requirements for chlorosilane imports into EU member states, compelling Asian exporters to invest in third-party certification infrastructure. German chemical distributors now demand batch-level CoA documentation that exceeds prior customs clearance standards, filtering smaller traders from the supply base.
Specification-driven vendor consolidation is concentrating procurement authority among semiconductor foundry chemical management teams, displacing traditional distributor relationships. TSMC and Intel direct material qualification programs now bypass regional intermediaries entirely, sourcing chloro-dimethylsilane through approved producer lists in Japan and Germany. This channel compression is most visible in Dresden and Hsinchu, where fab-site chemical storage investments accompany direct supply agreements.
Chloro -Dimethylsilane (CAS 1066-35-9) Market Segmentation
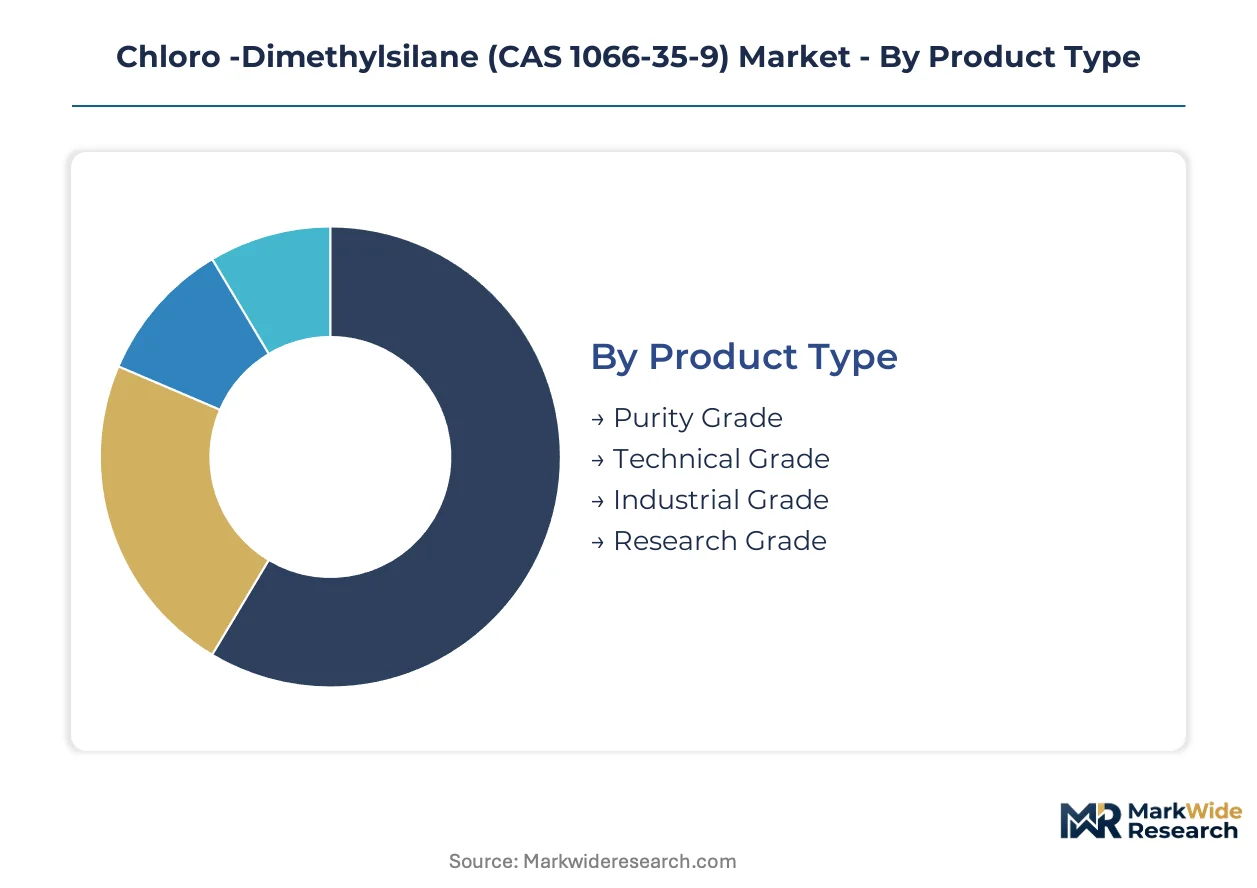
Chloro-dimethylsilane procurement patterns diverge sharply between precision-driven semiconductor fabs and cost-sensitive construction formulators. Specification stringency creates tiered supplier relationships that resist cross-segment arbitrage. Understanding these fault lines reveals where margin pools concentrate and where commoditization pressures bite hardest.
Product Type:
Customization intensity spans from semiconductor-grade molecular precision to bulk industrial tolerance bands.
- Purity Grade:Sub-ppb metallic impurity specifications govern atomic-layer deposition precursors for sub-3nm logic nodes. TSMC and Intel qualification programs demand dedicated production trains with stainless-steel distillation and inert atmosphere packaging. Contract premiums reflect certification maintenance costs and limited qualified supplier pools.
- Industrial Grade:Construction sealant manufacturers drive volume throughput with relaxed organochloride tolerances. Procurement concentrates among integrated silicone polymer producers with captive chlorosilane capacity, squeezing standalone merchant suppliers on feedstock cost pass-through.
- Technical Grade:Intermediate purity band serving specialty coatings and automotive adhesives with moderate moisture sensitivity requirements.
- Research Grade:Small-batch production for academic and early-stage materials development with batch-level analytical documentation.
Most installed capacity flows through Industrial Grade. Expansion is steepest in Purity Grade.
Application:
End-use differentiation tracks interface complexity — bulk polymerization versus monolayer surface control.
- Surface Treatments:Atomic-layer deposition and plasma-enhanced chemical vapor deposition precursors for 3D NAND stack fabrication. Samsung and SK Hynix consumption volumes now rival logic chip demand, compressing spot availability and forcing construction formulators toward contract structures.
- Silicone Production:Backbone intermediate for polydimethylsiloxane manufacturing via hydrolysis and condensation routes. Wacker Chemie and Shin-Etsu backward integration into silicon metal refining secures cost position against merchant market volatility.
- Adhesives:Moisture-cure silane crosslinkers for automotive and electronics assembly with moderate purity requirements.
- Sealants:Construction-grade formulations with lowest specification barriers and highest price elasticity.
Volume leadership sits with Silicone Production. Value capture is climbing fastest in Surface Treatments.
End User:
Buyer sophistication ranges from integrated chemical engineering to formulation-dependent downstream industries.
- Electronics Manufacturers:Direct procurement authority now resides with foundry chemical management teams at TSMC and Intel, displacing traditional distributor relationships through approved producer lists in Japan and Germany.
- Chemical Manufacturers:Integrated silicone polymer producers with captive chlorosilane synthesis and distillation infrastructure.
- Coatings Industry:Specialty automotive and industrial finish formulators with batch consistency requirements and moderate volume scale.
- Construction Sector:Price-sensitive bulk consumers with limited specification leverage and high substitution elasticity.
Contract duration extends longest with Electronics Manufacturers. Margin compression is most severe in Construction Sector.
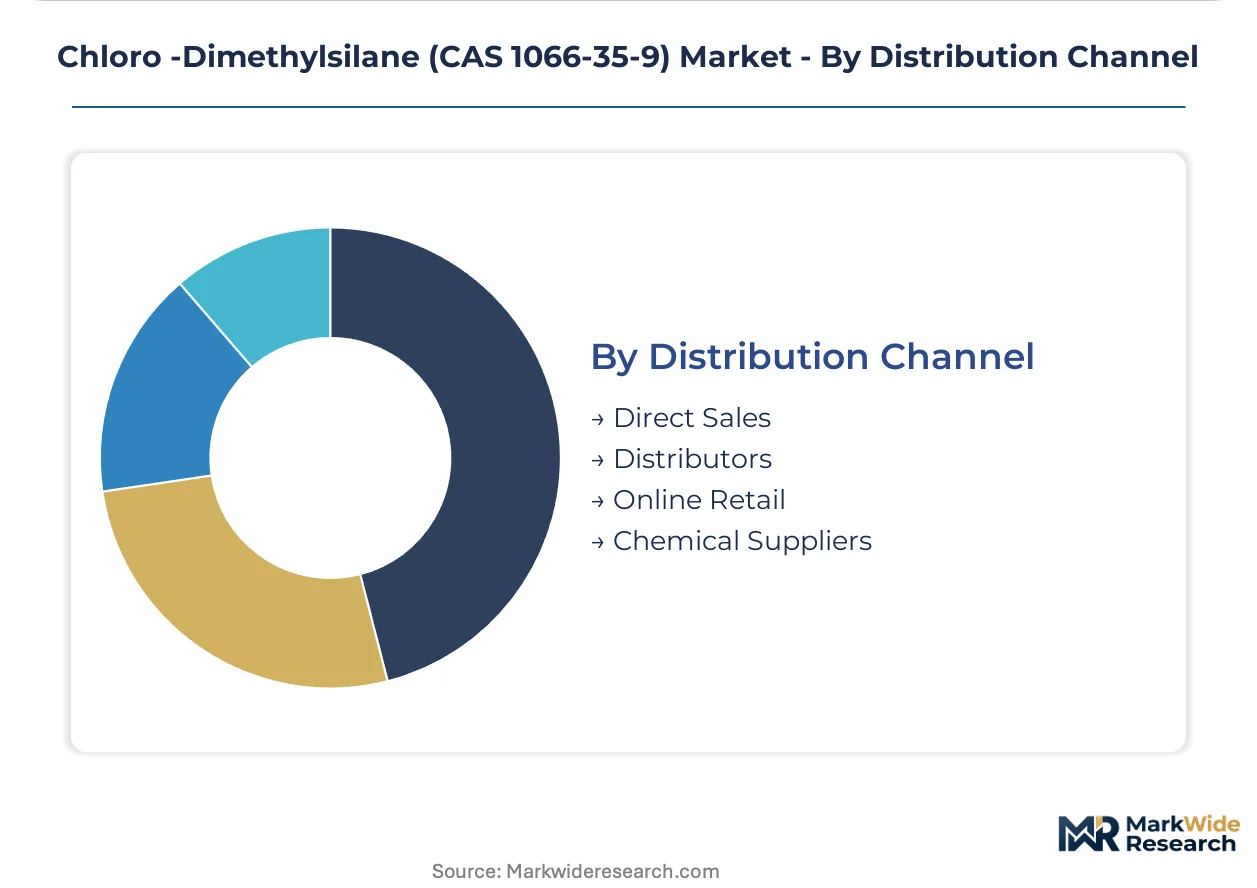
Distribution Channel:
Channel selection reflects contamination risk tolerance and procurement technical capability.
- Direct Sales:ISO-tank delivery bypassing regional distributors to semiconductor chemical handling facilities in Dresden and Hsinchu. Captures margin and reduces particulate exposure during transfer operations.
- Distributors:German chemical intermediaries now demand batch-level CoA documentation exceeding prior customs clearance standards, filtering smaller traders from EU supply bases.
- Chemical Suppliers:Established merchant relationships for industrial-grade volume with standardized packaging and logistics.
- Online Retail:Research-grade and small-laboratory procurement with credit-card transaction scale and limited technical support.
Revenue concentration is highest in Direct Sales. Channel development investment is flowing toward Distributors for REACH compliance infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting chloro-dimethylsilane production toward jurisdictions with lower carbon compliance costs, while semiconductor demand concentrates in East Asian manufacturing clusters. Producers in China leverage MEE dual carbon enforcement gaps to undercut European REACH-compliant supply, even as purity specifications tighten for electronics-grade material.
China
MEE carbon intensity caps are shuttering legacy furnace operations in Shandong and Zhejiang provinces, consolidating output among integrated producers with captive renewable energy. The Yangtze River Delta chemical cluster around Shanghai-Ningbo ports now handles the majority of electronics-grade exports, with direct ISO-tank delivery to semiconductor fabs displacing traditional distributor channels.
Germany
REACH Annex XVII restrictions on persistent organic pollutants compel full toxicological dossiers for chlorosilane imports exceeding one tonne annually, filtering smaller traders from the supply base. Wacker Chemie anchors European supply through backward integration into silicon metal refining, while Dresden fab-site chemical storage investments accompany direct supply agreements with semiconductor foundries.
United States
EPA emissions oversight and OSHA workplace exposure limits govern domestic manufacturing, though semiconductor-grade consumption outpaces local production capacity. Texas and Arizona fab construction under the CHIPS Act is pulling high-purity precursor imports from Japan and Germany, with chemical management teams at Intel and TSMC bypassing regional intermediaries entirely.
Japan
METI industrial policy supports ultra-high-purity organosilane development for sub-3nm logic node fabrication, with Shin-Etsu Chemical dominating qualified supplier pools for atomic-layer deposition precursors. Nagoya and Kumamoto industrial corridors concentrate distillation infrastructure with stainless-steel replacement and inert atmosphere upgrades meeting sub-ppb metallic impurity thresholds.
South Korea
Samsung and SK Hynix 3D NAND stack fabrication now consumes organosilane volumes previously reserved for logic chip production, compressing spot market availability for industrial-grade material. Busan-Ulsan chemical handling facilities receive direct ISO-tank deliveries from Japanese and German producers, with foundry chemical management teams controlling procurement authority through approved producer lists.
Chloro -Dimethylsilane (CAS 1066-35-9) Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty surface treatment formulations and regional import substitution partnerships. The vendor base stratifies across integrated silicone polymer producers with captive chlorosilane synthesis, merchant suppliers dependent on spot silicon metal pricing, and ultra-high-purity specialists serving semiconductor qualification programs. Three archetypes dominate: backward-integrated chemical conglomerates, purity-focused Japanese specialists, and regional Chinese merchant producers. Competitive moves concentrate on capacity consolidation under carbon compliance pressure and direct-to-fab distribution channel compression.
Among German chemical conglomerates, Wacker Chemie AG and Evonik Industries exemplify divergent strategic positions—Wacker anchoring supply through upstream silicon metal control, Evonik differentiating via specialized formulation chemistry. Shin-Etsu Chemical Co., Ltd. occupies the premium-tier vector for ultra-high-purity grades, representing the Japanese specialist archetype that dominates qualified supplier pools for sub-ppb semiconductor specifications. These three entities collectively illustrate how specification rigor creates defendable positioning at the high-purity extreme while feedstock cost volatility squeezes non-integrated merchant producers.
| Leading Market Players |
|---|
| Shanghai Chuqing Organosilane |
| PCC Group |
| Dow Corning |
| Jiande Zhiyou Silicone Materials |
| Evonik Industries |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Gelest, Inc. |
| Momentive Performance Materials |
| Others |
Supply Flow & Price Mechanics
Silicon metal cost volatility transmits directly through chloro-dimethylsilane pricing tiers, with ferrosilicon and metallurgical-grade silicon swings compressing margin predictability for non-integrated merchant producers while backward-integrated conglomerates capture feedstock cost advantages at the premium purity extreme.
Pricing Analysis
Distributor margin compression is accelerating as semiconductor foundry chemical management teams at TSMC and Intel bypass regional intermediaries entirely. Three-tier pricing structure across premium, standard, and economy levels separates sub-ppb Purity Grade for atomic-layer deposition from Industrial Grade construction sealants. Cost compression in the merchant supplier tier is intensifying because silicon metal spot pricing transmits directly to non-integrated producers without captive refining. Construction Sector buyers exhibit highest price sensitivity, while Electronics Manufacturers accept contract premiums for certified volumes.
Supply Chain Analysis
Photoresist-grade chlorosilane supply rests on Japanese specialty chemical producers with stainless-steel distillation infrastructure meeting sub-ppb metallic impurity thresholds. Manufacturing concentrates in China, Japan, and Germany, with raw material dependencies spanning silicon-copper alloy, methyl chloride, and high-purity hydrogen. Single-source vulnerability runs through the Yangtze River Delta cluster where over half of China's organosilane capacity sits in Shandong and Zhejiang provinces. Distribution runs through direct ISO-tank delivery to semiconductor chemical handling facilities displacing traditional merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chloro-dimethylsilane demand functions as a regulatory compounder where REACH Annex XVII restrictions on persistent organic pollutants tighten impurity disclosure requirements and filter smaller traders from EU supply bases.
For Market Incumbents: Acquire stainless-steel distillation assets with inert atmosphere packaging capabilities to defend semiconductor-grade positioning. Consolidate output among integrated producers with captive renewable energy as China's MEE dual carbon enforcement shutters legacy furnace operations. Certification investment in third-party batch-level CoA documentation exceeds prior customs clearance standards and filters merchant competitors from German distribution channels.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian semiconductor fabrication opens import substitution partnerships under Gujarat and Tamil Nadu greenfield fab construction. Technical Grade coatings for automotive adhesives present the most penetrable segment with moderate purity requirements and limited qualified supplier pools. Direct-to-fab distribution through ISO-tank delivery captures margin and reduces contamination risk versus regional distributor relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where carbon compliance costs shutter legacy furnace operations and concentrate output among integrated producers with captive renewable energy. Long-term viability favors backward-integrated chemical conglomerates with upstream silicon metal control and downstream silicone polymerization capacity. Watch for MEE enforcement intensity in Shandong and Zhejiang provinces as inflection indicator for Chinese supply consolidation pace.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Metal Refining | Wacker Chemie anchors European supply position through captive metallurgical-grade silicon production. |
| Long-term Supply Agreement with Foundry Chemical Teams | Direct procurement contracts with TSMC and Intel displace regional distributor relationships entirely. |
| Green Manufacturing Transition to Renewable Energy | China's MEE dual carbon goals constrain energy-intensive furnace operations favoring integrated producers. |
| Capacity Expansion in Yangtze River Delta Cluster | Shanghai-Ningbo port infrastructure co-location reduces logistics friction for electronics-grade material exports. |
| Joint Venture for Indian Import Substitution | Gujarat and Tamil Nadu greenfield fabs under PLI scheme require localized high-purity precursor supply partnerships. |
Methodological Framework
Coverage spans East Asia, Europe, and North America, with primary inputs from each region combined through bottom-up and top-down triangulation. Primary interviews engaged plant managers at chlorosilane synthesis facilities, procurement leads at downstream silicone polymer producers, distribution channel partners in German chemical intermediaries, and technical R&D directors for semiconductor precursor qualification. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings for integrated chemical conglomerates, and ECHA REACH registration databases.
Segmentation granularity modeled purity grade tiers, end-use industries spanning electronics manufacturing and construction, packaging formats from ISO-tank to specialized inert atmosphere containers, and regional production hubs across the Yangtze River Delta, Nagoya-Kumamoto corridor, and German industrial clusters. CAGRs were derived through demand-side buildup from semiconductor fab capacity expansion and supply-side capacity accounting for MEE-enforced furnace closures. Industry-specific forecast inputs included atomic-layer deposition precursor consumption rates for sub-3nm logic node fabrication and 3D NAND stack layer counts.
Caveats apply where MEE enforcement intensity, REACH registration friction, or silicon metal price volatility could materially shift the outlook. Forecasts reflect assumptions around qualification timeline stability for sub-ppb purity certification and carbon compliance cost pass-through rates. A small set of named triggers warrants ongoing watch: dual carbon policy implementation pace in China, semiconductor node shrinkage below 2nm specification escalation, and ferrosilicon supply disruptions from major producing regions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Heterocyclic and Fluoro Organic Compounds Market
Organic Chemicals
Bromobenzene Market
Organic Chemicals
Alanine Market
Organic Chemicals
Mercaptopropionic Acid Market
Organic Chemicals
Europe Cycloalkanes Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
Ethyl Levulinate Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
High Purity Metal Organics Market
Organic Chemicals
Europe Organic Acid Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
Organic Coating Market
Organic Chemicals
Organic Peroxide Market
Organic Chemicals
Dimethyl Carbonate Market