
 Aminophenol Market | 2026-2036
Aminophenol Market Size, Share, and Industry Trends Forecast 2026-2036
Aminophenol Market Analytics
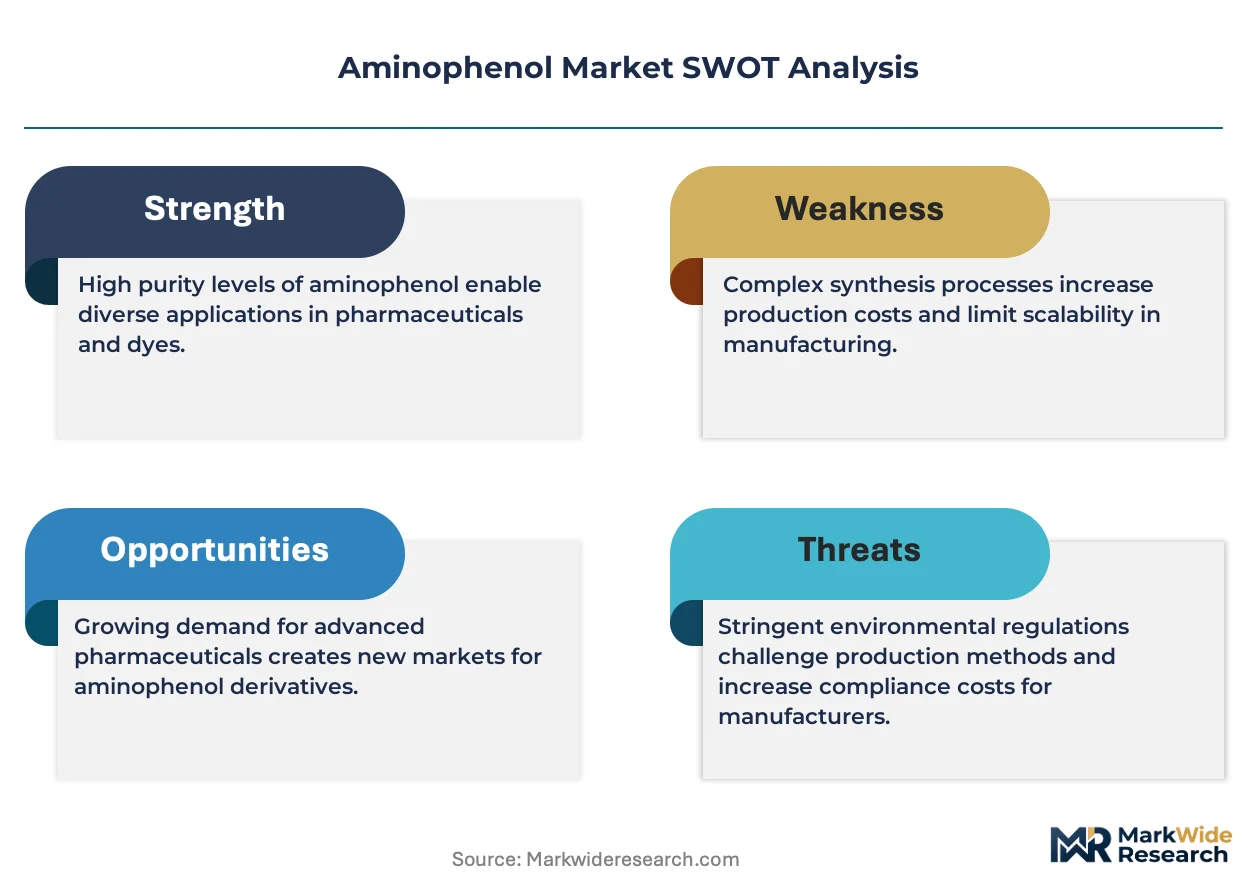
The EU Green Deal is broadening the addressable market for high-purity aminophenol as European pharmaceutical buyers enforce stricter carbon-footprint criteria across chemical supply chains. Wego Chemical Group leverages its North American distribution network to serve contract manufacturers facing these compliance deadlines. Taixing Yangzi Pharm Chemical Co., Ltd. anchors the Asia-Pacific supply base with dedicated 4-aminophenol capacity for analgesic API producers. Anhui Bayi Chemical Industry Co. Ltd. differentiates through integrated nitrobenzene-to-aminophenol production that sustains cost discipline amid volatile feedstock markets.
Aminophenol denotes a family of aromatic amines with hydroxyl and amino substituents positioned at ortho, meta, or para locations on the benzene ring; 4-aminophenol, the para isomer, dominates industrial output due to its role as the direct precursor to paracetamol and its melting point specification near 187 degrees Celsius. Pharmaceutical applications command the largest value share within the application dimension, reflecting chronic disease prevalence and over-the-counter analgesic consumption patterns across mature healthcare systems. Dye and photographic chemical segments retain stable offtake but face substitution pressure from digital imaging technologies and azo-free colorant preferences.
EPA oversight of phenol derivative emissions shapes manufacturing site selection and wastewater treatment capital allocation for US-based producers. REACH registration requirements and the EU F-Gas Regulation indirectly influence aminophenol demand through downstream refrigeration and HVAC chemical linkages. China's MEE enforces stricter effluent standards on fine chemical parks, raising compliance costs for export-oriented manufacturers. Stakeholders must weigh regulatory divergence across these jurisdictions when locating capacity expansions or qualifying alternative suppliers.
Market Dynamics
Pharmaceutical procurement consolidation and API localization mandates are compressing traditional aminophenol supply chains, forcing intermediate producers to qualify under multiple national purity regimes simultaneously.
Growth Catalysts
- India's PLI scheme:Domestic API production incentives accelerate captive aminophenol consumption by contract manufacturers serving export markets.
- REACH compliance deadlines:European pharmaceutical buyers enforce stricter carbon-footprint criteria across chemical supply chains, expanding the addressable market for high-purity grades.
- Chronic disease prevalence:Sustained offtake of paracetamol-containing formulations drives steady intermediate demand from analgesic API producers.
Market Restraints
- Nitrobenzene price volatility:Feedstock cost swings compress margins for non-integrated producers lacking captive reduction capacity.
- China MEE effluent standards:Stricter wastewater requirements on fine chemical parks raise compliance costs for export-oriented manufacturers.
- Digital imaging substitution:Photographic chemical offtake faces structural decline as silver halide processing retreats from commercial applications.
Strategic Opportunities
- EU Green Deal procurement criteria:Carbon-accounted supply chains create premium positioning for producers with verified Scope 3 reductions.
- Continuous flow hydrogenation:Process intensification technologies enable smaller-footprint production at pharmaceutical-grade specifications.
- Brazil ANVISA localization:Import substitution policies incentivize regional aminophenol capacity to serve Latin American API manufacturing.
Industry Challenges
- Multinational pharmacopeia alignment:Reconciling USP, EP, and IP specification differences extends qualification timelines for new supply sources.
- Specialized hydrogenation engineering:Scarcity of process safety expertise for high-pressure catalytic reduction limits workforce scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aminophenol Market |
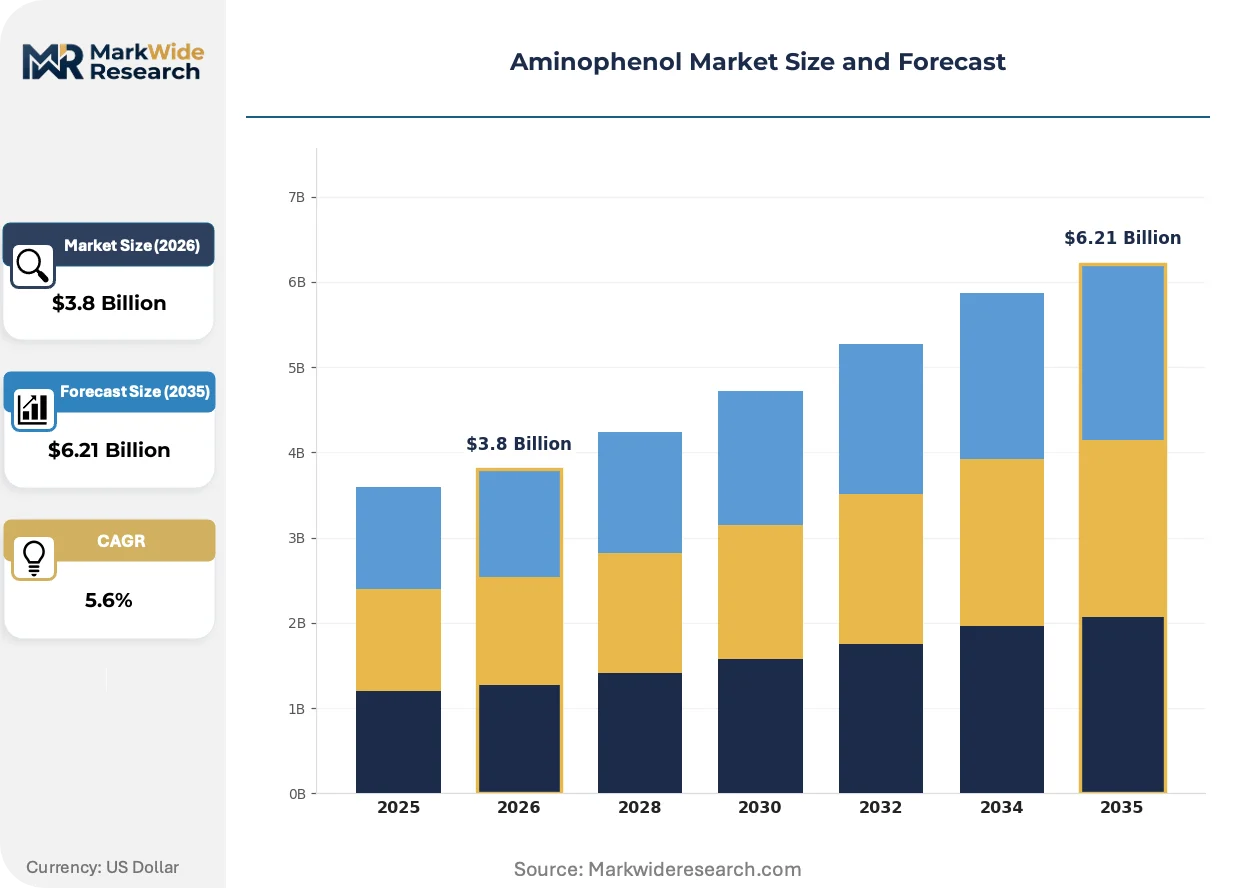
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4-Aminophenol, 2-Aminophenol, 3-Aminophenol, 5-Aminophenol Application: Pharmaceuticals, Dyes, Photographic Chemicals, Agrochemicals Form: Powder, Crystals, Granules, Liquid End User: Chemical Manufacturers, Pharmaceutical Companies, Research Institutions, Educational Organizations |
| Companies Covered | Wego Chemical Group, Loba Chemie, Taixing Yangzi Pharm Chemical Co., Ltd., CDH Fine Chemicals, Anhui Bayi Chemical Industry Co. Ltd., Parchem, Glentham Life Sciences Ltd., Liaoning Shixing Pharmaceutical & Chemical Co., Ltd., Ascent Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aminophenol Market Evolving Landscape
Process intensification and regulatory digitization are compressing traditional batch manufacturing timelines while fragmenting procurement authority across sustainability, quality, and cost functions.
Continuous flow reactor technology is modularizing aminophenol synthesis by replacing conventional stirred-tank hydrogenation with compact skid-mounted units. Pharmaceutical contract manufacturers in India and Germany are piloting these systems to reduce solvent inventory and thermal hazard exposure. The technology is modularizing capital deployment, enabling mid-scale producers to enter regulated supply chains without billion-dollar integrated sites.
REACH registration dossier updates and the EU F-Gas Regulation are tightening traceability requirements for chemical intermediates with downstream refrigeration linkages. Aminophenol producers must now document substance volume tracking and environmental fate data beyond traditional purity certificates. European pharmaceutical buyers are responding by consolidating qualified supplier lists to those with complete SCIP database entries.
Specification-driven procurement is fragmenting traditional spot-market purchasing for aminophenol intermediates. Large API manufacturers now maintain parallel qualification tracks for carbon-intensity, pharmacopeia grade, and security-of-supply metrics, displacing price-only tendering. This behavioral shift is most visible among German and Swiss generics producers restructuring their intermediate sourcing committees.
Aminophenol Market Segmentation
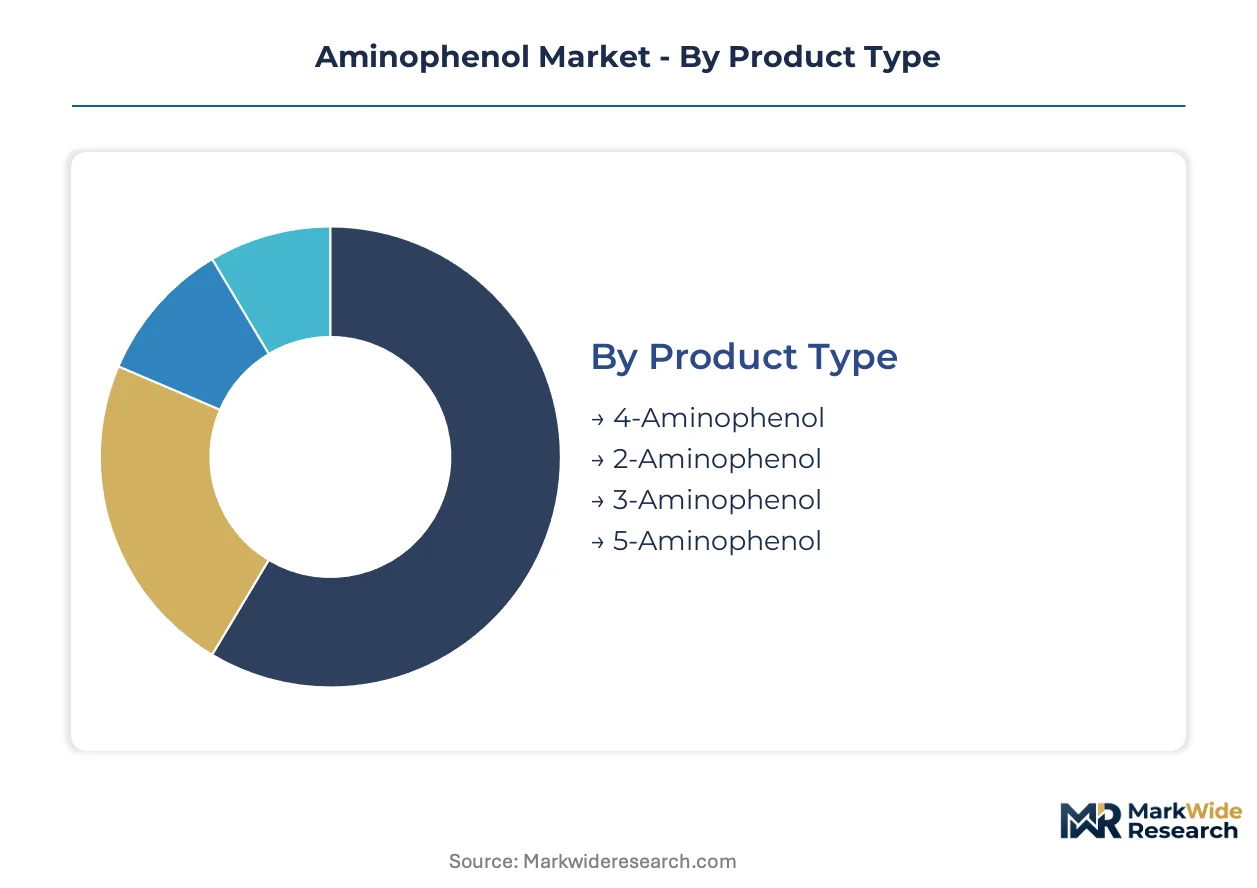
Aminophenol procurement patterns diverge sharply across product isomers and application verticals, with pharmaceutical-grade specifications commanding qualification protocols that exclude commodity-grade suppliers. Understanding these segment boundaries enables intermediate producers to align hydrogenation capacity with the purity regimes demanded by specific end-use customers.
Product Type:
Replacement cycles for aminophenol intermediates track patent cliffs and API manufacturing relocations, with paracetamol precursor demand resetting every seven to ten years as production licenses transfer between regions.
- 4-Aminophenol:The para isomer serves as the direct precursor to paracetamol synthesis, requiring melting point specifications near 187 degrees Celsius and residual nitrobenzene levels below 10 ppm. Indian contract manufacturers under the PLI scheme now absorb the majority of export-grade volumes, displacing traditional European merchant market offtake.
- 2-Aminophenol:Ortho positioning of functional groups enables dye intermediate synthesis and corrosion inhibitor formulations, with demand concentrating in Chinese textile chemical clusters facing MEE effluent compliance deadlines. The isomer trades at modest premiums to commodity 4-aminophenol due to smaller batch production economics.
- 3-Aminophenol:Meta-substituted aminophenol finds niche application in hair dye formulations and specialized pharmaceutical intermediates where regioselectivity controls downstream reaction pathways.
- 5-Aminophenol:Less common industrial isomer serving agrochemical precursor markets and select photographic developer applications with limited commercial scale.
4-Aminophenol sits at the top of the volume ranking, with 2-aminophenol climbing the fastest as Chinese dye manufacturers upgrade effluent treatment systems.
Application:
Margin structures across application verticals separate pharmaceutical-grade producers from commodity chemical suppliers, with carbon-accounted supply chains capturing premium positioning in regulated European procurement.
- Pharmaceuticals:Paracetamol API synthesis consumes the dominant value share, with chronic disease prevalence sustaining intermediate demand across US, European, and Indian manufacturing bases. REACH registration dossiers and USP specification alignment now function as competitive moats excluding unqualified suppliers.
- Dyes:Azo coupling reactions for textile colorants drive steady offtake, though azo-free preferences in EU Green Deal procurement are compressing traditional demand channels. Taixing Yangzi Pharm Chemical anchors regional supply to Yangtze River Delta dye houses.
- Photographic Chemicals:Silver halide developer applications face structural decline as digital imaging displaces commercial film processing, with residual demand limited to specialty archival and motion picture segments.
- Agrochemicals:Pesticide intermediate applications leverage aminophenol amino and hydroxyl reactivity for herbicide synthesis, with Brazilian ANVISA localization policies incentivizing regional capacity investment.
Pharmaceuticals maintains the dominant value position, while agrochemicals gains share fastest as Latin American import substitution accelerates.
Form:
Handling characteristics and dissolution kinetics determine form selection, with continuous flow hydrogenation technologies enabling on-site liquid production that bypasses traditional solid-form logistics.
- Powder:Fine particulate form maximizes surface area for rapid dissolution in batch pharmaceutical synthesis, with particle size distribution specifications tightening under multinational pharmacopeia alignment pressures.
- Crystals:Defined lattice structure supports reproducible melting behavior and extended shelf stability, preferred by European analytical reagent suppliers and quality-critical API producers.
- Granules:Intermediate particle size reduces dust exposure during handling while maintaining acceptable dissolution rates for agrochemical formulation plants.
- Liquid:Aqueous or solvent-based solutions enable direct feed into continuous flow reactors, with Indian and German contract manufacturers piloting modular skid-mounted systems to reduce solvent inventory.
Powder remains the volume leader, with liquid form expanding most quickly as process intensification technologies modularize capital deployment.
End User:
Procurement authority fragmentation separates sustainability, quality, and cost functions across customer organizations, with specification-driven purchasing displacing price-only tendering among large API manufacturers.
- Chemical Manufacturers:Merchant intermediate producers serving downstream formulation plants face compressed margins from nitrobenzene feedstock volatility, with integrated nitrobenzene-to-aminophenol operations sustaining cost discipline.
- Pharmaceutical Companies:Analgesic API producers maintain parallel qualification tracks for carbon-intensity, pharmacopeia grade, and security-of-supply metrics, consolidating supplier lists to those with complete SCIP database entries.
- Research Institutions:Analytical-grade and isomerically pure materials support method development and reference standard preparation, with modest volumes but premium pricing tolerance.
- Educational Organizations:Teaching laboratory consumption of basic organic intermediates represents stable but price-sensitive demand with limited specification complexity.
Pharmaceutical companies occupy the top volume position, with chemical manufacturers gaining fastest as API localization mandates concentrate intermediate demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale aminophenol synthesis first achieved commercial scale in German dye houses during the late nineteenth century, establishing Rhineland chemical parks as the historical foundation for aromatic amine chemistry. Contemporary production geography reflects this legacy while integrating new capacity clusters responding to API localization mandates and carbon-accounted procurement standards.
China
Taixing Yangzi Pharm Chemical anchors supply to Yangtze River Delta dye manufacturers upgrading effluent systems under MEE compliance deadlines. The country's dual carbon goals pressure fine chemical parks to document Scope 3 reductions for European pharmaceutical buyers. Shandong Peninsula clusters concentrate nitrobenzene reduction capacity serving both domestic paracetamol API producers and export markets.
India
Domestic pharmaceutical contract manufacturers absorb expanding volumes of 4-aminophenol under PLI scheme incentives for API production. CDSCO registration alignment with USP and EP specifications extends qualification timelines for new supply sources. Gujarat and Maharashtra chemical corridors concentrate hydrogenation capacity serving export-oriented analgesic manufacturers.
Germany
REACH registration dossier updates and EU Green Deal procurement criteria enforce stricter carbon-footprint verification across chemical supply chains. BASF Ludwigshafen and Leverkusen chemical parks maintain pharmaceutical-grade hydrogenation expertise for European generics producers. Continuous flow reactor pilots in Baden-Württemberg reduce solvent inventory for mid-scale API manufacturers.
United States
EPA oversight of phenol derivative emissions shapes manufacturing site selection and wastewater treatment capital allocation for domestic producers. Wego Chemical Group leverages North American distribution networks to serve contract manufacturers facing compliance deadlines. Gulf Coast petrochemical corridors provide feedstock proximity for integrated nitrobenzene-to-aminophenol operations.
Brazil
ANVISA localization policies incentivize regional aminophenol capacity to serve Latin American API manufacturing import substitution. São Paulo state chemical parks attract investment from multinational pharmaceutical intermediates suppliers. Minas Gerais agrochemical formulators drive niche demand for 3-aminophenol derivatives in herbicide synthesis.
Aminophenol Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across a structurally tiered vendor base. Integrated nitrobenzene-to-aminophenol operators sustain cost discipline through captive reduction capacity, while merchant traders navigate feedstock volatility through geographic arbitrage. Three archetypes dominate: integrated chemical conglomerates with backward control over nitrobenzene supply, specialized pharmaceutical intermediate producers with pharmacopeia-grade hydrogenation assets, and regional distributors with logistics networks spanning multiple regulatory jurisdictions. Competitive moves concentrate on M&A for hydrogenation expertise and strategic partnerships for carbon-accounted supply chain certification.
Among Asia-Pacific-based producers, Taixing Yangzi Pharm Chemical Co., Ltd. and Anhui Bayi Chemical Industry Co. Ltd. exemplify the integrated manufacturing archetype with established positions in aromatic amine chemistry. Wego Chemical Group occupies the distribution-focused tier, leveraging North American logistics infrastructure to serve contract manufacturers navigating multinational pharmacopeia alignment pressures. These three entities collectively represent the geographic and functional span of competitive positioning in intermediate supply chains.
| Leading Market Players |
|---|
| Wego Chemical Group |
| Loba Chemie |
| Taixing Yangzi Pharm Chemical Co., Ltd. |
| CDH Fine Chemicals |
| Anhui Bayi Chemical Industry Co. Ltd. |
| Parchem |
| Glentham Life Sciences Ltd. |
| Liaoning Shixing Pharmaceutical & Chemical Co., Ltd. |
| Ascent Chemicals |
| Others |
Value Network & Pricing Analysis
Pharmaceutical contract manufacturers under India's PLI scheme anchor aminophenol procurement volume, compressing spot-market liquidity and reinforcing contract-based long-term offtake as the dominant pricing mechanism. This buyer concentration enables integrated producers to capture premiums through pharmacopeia-grade certification while squeezing merchant traders on feedstock volatility.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, technical-grade, and commodity-grade levels stratifies aminophenol markets by certification intensity and purity specification. Price differentiation hinges on USP/EP alignment and carbon-accounted supply chain documentation, with REACH-registered producers commanding substantial premia over unqualified competitors. Cost compression in technical-grade tiers is intensifying because Chinese MEE effluent compliance is raising baseline production costs. Generic API manufacturers in India exhibit the highest price sensitivity, while European innovator pharmaceutical companies prioritize security-of-supply metrics over unit cost.
Supply Chain Analysis
Specialized hydrogenation engineering talent scarcity in Taixing and Shandong chemical parks constrains workforce scalability for nitrobenzene reduction operations. Supply concentrates in China, India, and Germany, with nitrobenzene feedstock, palladium catalysts, and pharmaceutical-grade hydrogen constituting critical input dependencies. Single-source vulnerability around Indian paracetamol API manufacturers creates systemic exposure to PLI policy discontinuities. Distribution runs through qualified supplier lists maintained by European pharmaceutical procurement committees, with spot-market liquidity diminishing as specification-driven purchasing displaces traditional tendering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Chinese manufacturing scale and Indian API localization incentives, with the PLI scheme's cost differentials against European production creating relocation pressure.
For Market Incumbents: Cement backward integration into nitrobenzene reduction capacity to buffer margin erosion from feedstock volatility. Defend qualified supplier status by accelerating SCIP database completion ahead of REACH dossier deadlines. Continuous flow hydrogenation expertise represents the critical capability gap limiting workforce scalability for mid-scale entrants. For New Entrants and Emerging Players: Brazilian agrochemical formulators present an underserved buyer archetype with ANVISA localization mandates creating procurement windows for regional capacity. Target São Paulo state chemical parks with modular continuous flow skids that bypass billion-dollar integrated site requirements. Carbon-accounted supply chain certification offers the most penetrable differentiation vector against established Chinese merchant producers. For Investors and Strategic Acquirers: Specialty pharmaceutical intermediate producers with pharmacopeia-grade hydrogenation assets are the most active acquirer in this space, consolidating fragmented technical capabilities across European and Indian targets. The viable holding period extends through the PLI scheme's full operationalization, with workforce scalability in high-pressure catalytic reduction serving as the binding constraint on capacity expansion. Watch for CDSCO registration alignment delays as the inflection signal for Indian supply reliability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrobenzene | Captive reduction capacity insulates margins from feedstock volatility at Taixing and Shandong sites. |
| Continuous Flow Reactor Deployment | Modular skid-mounted systems enable mid-scale entry into REACH-regulated European supply chains. |
| Carbon-Accounted Supply Chain Certification | EU Green Deal procurement criteria reward verified Scope 3 reductions with premium positioning. |
| PLI Scheme Qualification | Indian API localization incentives concentrate intermediate demand among domestic contract manufacturers. |
| SCIP Database Completion | European pharmaceutical buyers consolidate qualified supplier lists to complete REACH traceability entries. |
Research Methodology
Bottom-up pharmaceutical procurement modeling reconciled against top-down hydrogenation capacity tracking forms the analytical core of this study. Primary interviews with plant managers at nitrobenzene reduction facilities, procurement leads at Indian contract manufacturers, distribution channel partners serving European generics producers, and technical R&D directors at hydrogenation technology suppliers generated demand-side intelligence. Secondary validation drew from CDSCO registration databases, ECHA REACH dossier filings, SEC 10-K disclosures by listed chemical conglomerates, and Indian customs trade data for 4-aminophenol intermediates.
Historical trendline analysis of patent cliff cycles and API manufacturing relocations informed the projection framework across the analysis window. Segmentation modeling incorporated isomer type, application vertical, pharmacopeia grade tier, and regional production hub dimensions. CAGRs were derived from elasticity-adjusted demand curves for paracetamol precursor consumption and nitrobenzene feedstock cost trajectories.
Underlying measurement precision varies by segment; pharmaceutical-grade specifications carry tighter precision than commodity dye intermediates due to qualification protocol documentation. Forecasts reflect assumptions about PLI scheme continuity, REACH compliance deadline adherence, and nitrobenzene price stability. Material deviation in MEE enforcement intensity or CDSCO-USP alignment timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Nonylphenol Market
Organic Chemicals
Acetaldehyde Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
Chlorinated Methane Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
Benzethonium Chloride Market
Organic Chemicals
N-Pentane Market
Organic Chemicals
Acetic Acid Market
Organic Chemicals
Phenolic Board Market
Organic Chemicals
Ethyl Levulinate Market
Organic Chemicals
Organic Coating Market
Organic Chemicals
2,6-Dichloro Aniline Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
Organic Polysulfide Market